
 South America Feed Acidifiers Market | 2026-2036
South America Feed Acidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Acidifiers Market Analytics
Consolidation among Brazilian poultry integrators is recalibrating procurement leverage across the South America Feed Acidifiers Market. Cargill, Incorporated leverages its integrated grain-to-protein supply chain to anchor acidifier volumes in São Paulo state processing corridors. Kemin Industries competes through specialized buffered acid formulations tailored to tropical humidity conditions. DSM-Firmenich sustains R&D intensity in next-generation acidifier-synbiotic combinations for antibiotic-free broiler programs.
Feed acidifiers comprise organic acids, inorganic acids, salts, and natural blends added to animal diets to reduce gastric pH, inhibit pathogenic bacterial proliferation, and improve nutrient digestibility, typically dosed at 0.5 to 3.0 kilograms per metric ton of feed depending on species sensitivity and target pathogen profile. Organic acids dominate value capture due to established efficacy against Salmonella and E. coli in poultry, while natural blends represent the fastest-expanding margin pool as Brazilian exporters chase EU-aligned antibiotic-free certification. The aquaculture segment trails in absolute volume but commands premium pricing as Chilean salmon farmers adopt acidified diets to manage Vibrio resistance under strict export standards.
ANVISA governs feed additive registration and residue monitoring in Brazil, while Argentina's SENASA administers import protocols and manufacturing facility audits that determine which acidifier suppliers access the Mercosur trade bloc. The EU Green Deal's deforestation-free supply chain requirements indirectly pressure South American livestock exporters to document acidifier inputs as part of comprehensive farm-to-fork traceability systems. Stakeholders must monitor how forthcoming Mercosur-EU trade negotiations reshape regulatory equivalence for feed safety certifications.
Market Dynamics
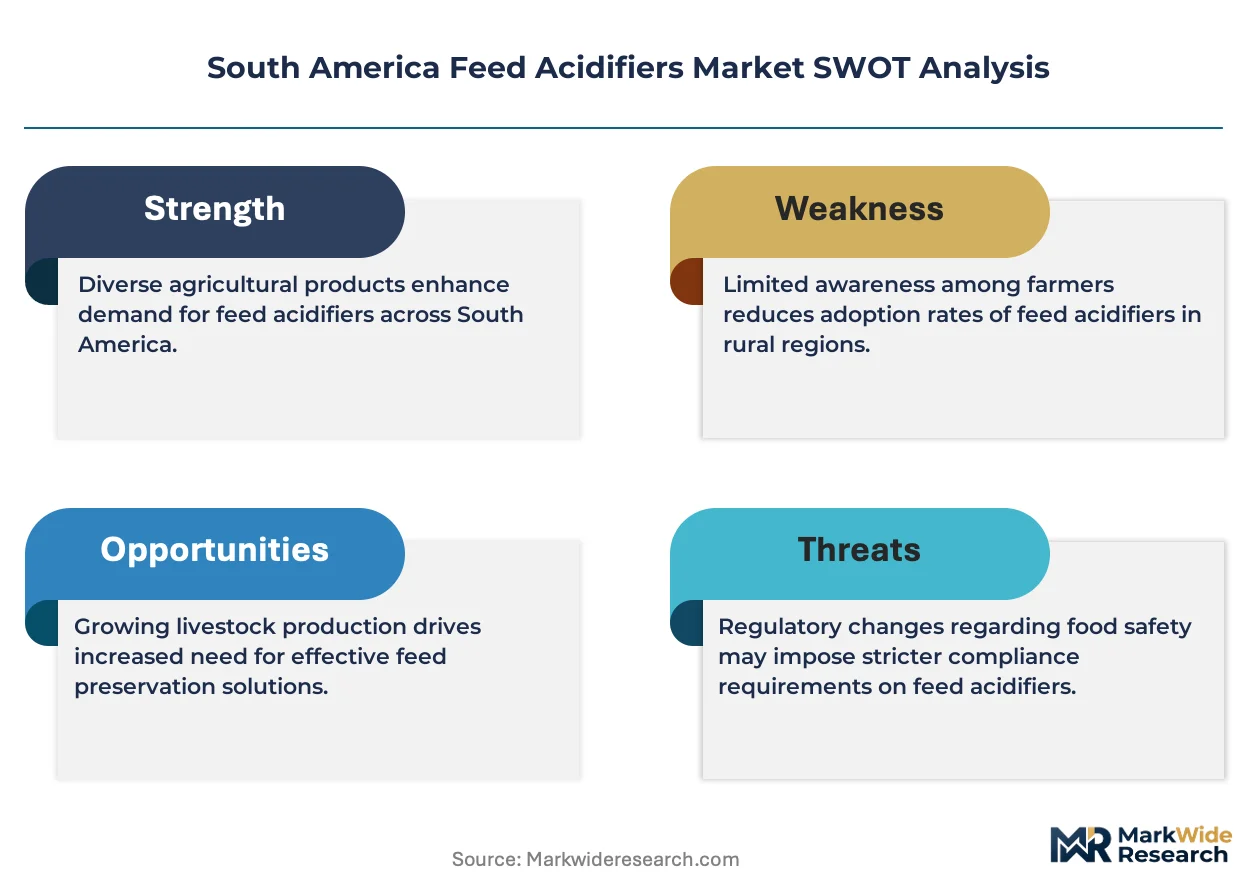
ANVISA's phased restrictions on antibiotic growth promoters have forced Brazilian poultry integrators to restructure feed formulation protocols, accelerating acidifier adoption across São Paulo and Paraná processing corridors. This regulatory pivot concentrates procurement leverage among vertically integrated protein exporters seeking EU market access.
Growth Catalysts
- EU Green Deal traceability mandates:Brazilian exporters must document acidifier inputs for deforestation-free certification, pulling premium-formulation demand from integrated producers in Mato Grosso do Sul feedlots.
- Salmonella control protocols:SENASA's tightened residue monitoring in Argentina's Pampas grain belt drives organic acid deployment in layer operations supplying Mercosur markets.
- Buffered acid technology:Tropical humidity formulations reduce degradation losses during storage, improving dose consistency for coastal Brazilian aquaculture facilities.
Market Restraints
- Propionic acid price volatility:Feedstock fluctuations in petrochemical supply chains compress margin buffers for formulators serving mid-tier cooperatives.
- Import dependency for citric acid:Concentrated Asian sourcing creates foreign exchange exposure for Argentine compound feed mills.
- Formulation complexity limits:Acidifier-synbiotic interactions require specialized nutritionist expertise scarce outside São Paulo technical centers.
Strategic Opportunities
- Chilean salmon aquaculture:Vibrio management protocols under strict export standards command premium pricing for acidified functional feeds in Los Lagos region.
- ANVISA fast-track registration:Streamlined approval pathways for natural acid blends reward early movers with 18-month exclusivity windows.
- Direct-to-farm digital channels:E-procurement platforms bypass traditional distributor markups for mid-scale swine operations in Santa Catarina.
Industry Challenges
- Technical service capacity gaps:Field nutritionist shortages delay on-farm acidifier calibration for antibiotic-free transition programs.
- Multi-certificate compliance burdens:Concurrent ANVISA, SENASA, and EU equivalence audits strain quality assurance resources at border processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Acidifiers Market |
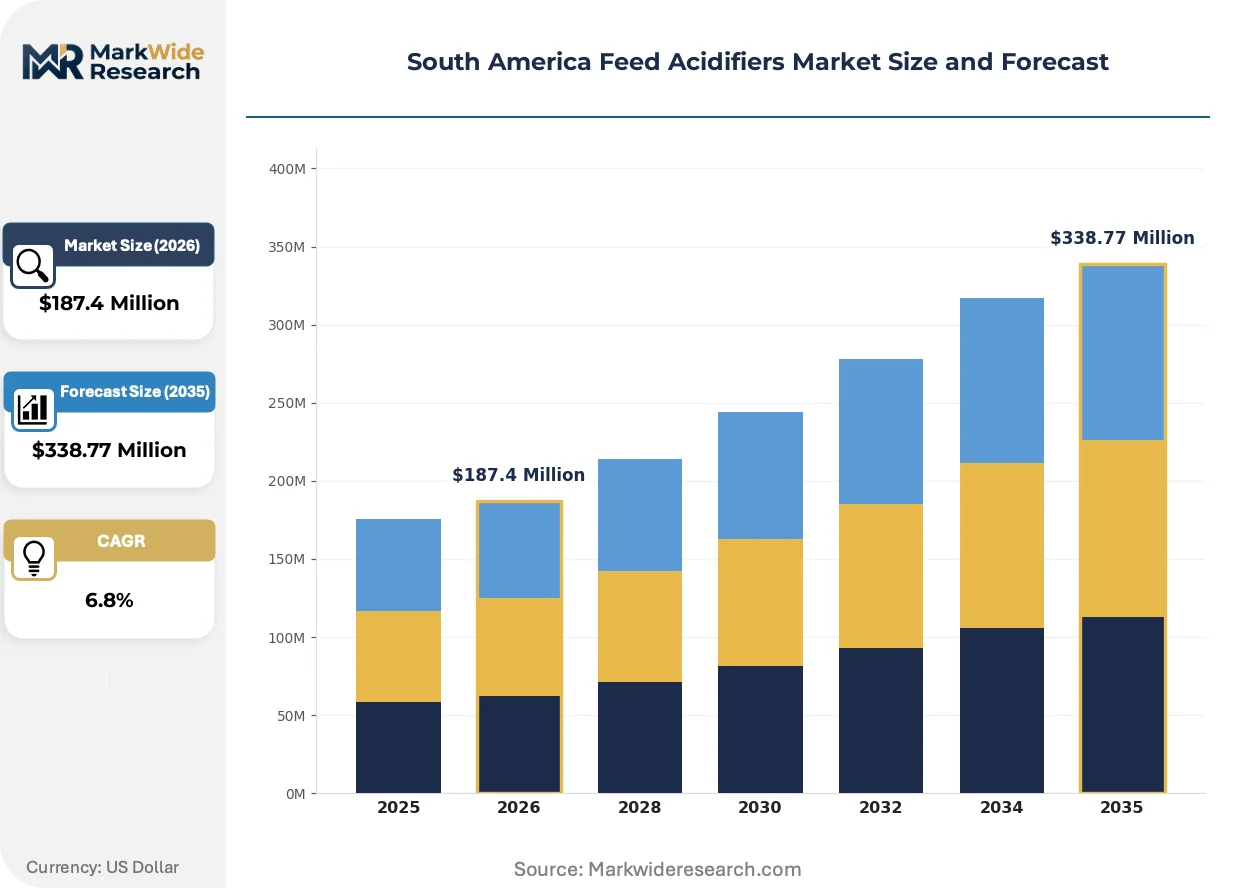
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acids, Inorganic Acids, Salts, Natural Blend Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Spray-dried Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, DSM-Firmenich, Cargill, Incorporated, Kemin Industries, Adisseo, Brenntag SE, Novus International, Perstorp Holding AB, Pancosma, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Acidifiers Market Evolving Landscape
Formulation science and regulatory alignment are compressing product lifecycles across South American feed acidifier markets. Suppliers now compete on bioavailability optimization rather than commodity acid volumes.
Encapsulated organic acid blends with sustained-release coatings are overtaking standard powdered formulations in Brazilian broiler operations. Integrators in Paraná and Rio Grande do Sul deploy these technologies to maintain gastric pH stability through tropical heat stress periods. The shift is compressing margins for unformulated acid traders while rewarding patent-protected delivery system developers.
ANVISA's forthcoming residue monitoring expansion will tighten maximum permitted levels for acidifier metabolites in exported poultry. Processing facilities in São Paulo state are pre-emptively upgrading laboratory capabilities to meet anticipated protocol harmonization with EU reference laboratories. This regulatory anticipation is accelerating capital deployment in certified analytical infrastructure ahead of formal mandate publication.
Large integrators now specify acidifier performance guarantees tied to feed conversion outcomes rather than ingredient inclusion rates. Contracts in Argentina's grain belt increasingly bundle acidifier supply with technical advisory services, displacing spot-market purchasing at cooperative feed mills. This outcome-based model concentrates supplier relationships among three to four full-service formulators with dedicated veterinary teams.
South America Feed Acidifiers Market Segmentation
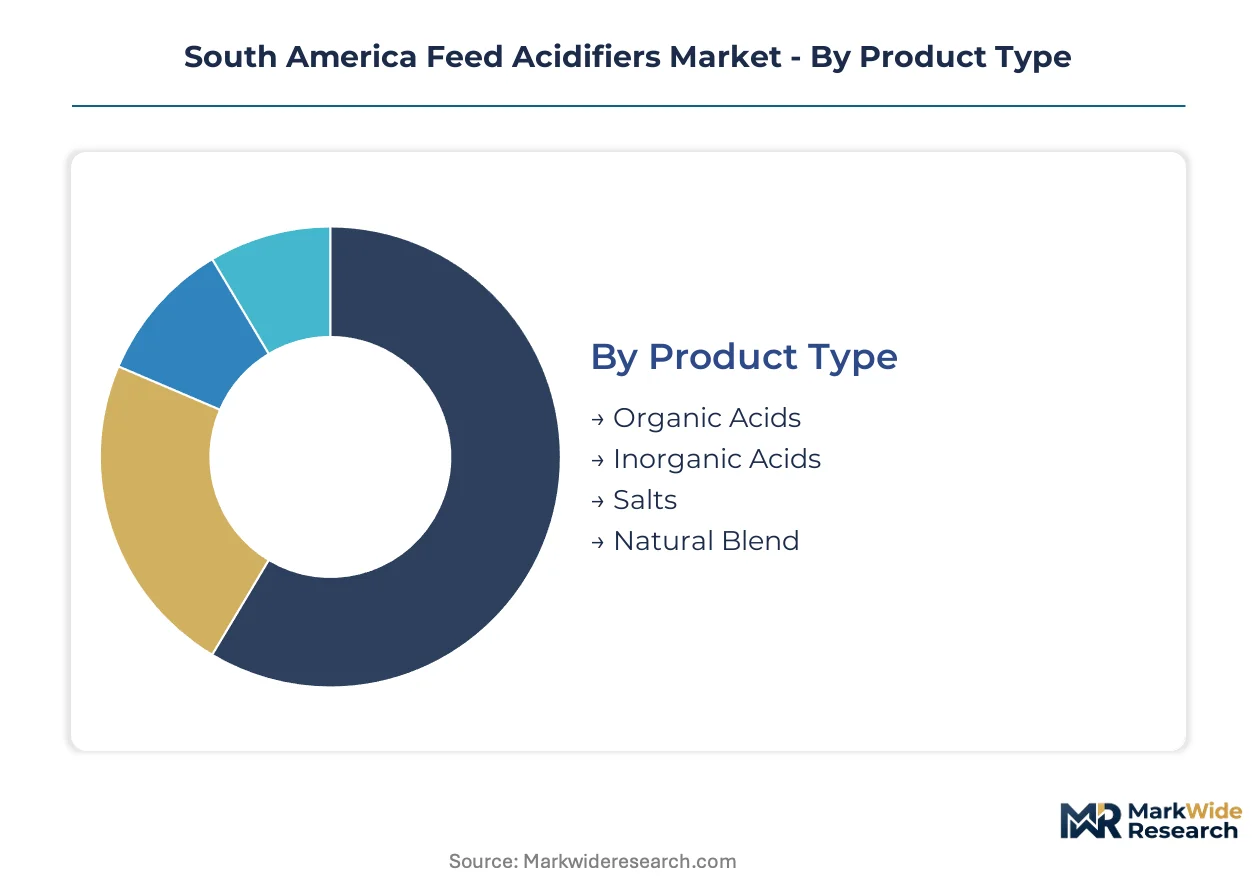
Feed acidifier procurement patterns across South America diverge sharply between commodity-driven volume plays and precision-formulation premium tiers. Understanding how integrators, cooperatives, and aquaculture operators navigate these splits reveals where margin capture concentrates and where suppliers must invest technical service capacity.
Product Type:
Customization intensity varies from standardized commodity acids to proprietary buffered blends requiring formulation expertise and tropical stability engineering.
- Organic Acids:Formic, propionic, and citric acids constitute the foundational acidifier class, typically blended at 0.5-2.0 kg per metric ton for Salmonella inhibition in Brazilian broiler operations. Demand concentrates among São Paulo and Paraná poultry integrators supplying EU export markets under ANVISA's antibiotic-free transition mandates.
- Natural Blend:Synergistic combinations of organic acids with essential oils and medium-chain fatty acids command formulation premiums for antibiotic-free certification compliance. Argentine exporters in the Pampas grain belt drive fastest adoption as SENASA tightens residue protocols for Mercosur-EU trade alignment.
- Inorganic Acids:Phosphoric and hydrochloric acids serve cost-sensitive ruminant feed applications where gastric pH modulation takes priority over pathogen inhibition.
- Salts:Calcium formate and sodium propionate offer handling safety advantages for cooperatives lacking specialized mixing infrastructure.
Most installed capacity flows through Organic Acids. Expansion is steepest in Natural Blend.
Animal Type:
Species-specific physiology and export market exposure create divergent acidifier performance requirements and pricing tolerance bands.
- Poultry:Broiler and layer operations dominate absolute volume, with gastric pH management critical for feed conversion efficiency in high-density Brazilian production systems. Southern feedlot corridors from Mato Grosso do Sul to Rio Grande do Sul anchor procurement concentration.
- Aquaculture:Chilean salmon farmers in the Los Lagos region deploy acidified functional feeds for Vibrio resistance management under strict EU and US export standards, commanding premium pricing despite smaller volume.
- Swine:Post-weaning diarrhea control drives acidifier inclusion in nursery diets across Santa Catarina's integrated pork production belt.
- Ruminants:Beef feedlot operations in Argentina's Pampas utilize acidifiers primarily for mold inhibition in high-moisture grain rations rather than digestive optimization.
Volume leadership sits with Poultry. Pricing power concentrates in Aquaculture.
Form:
Physical delivery systems determine storage stability, dosing precision, and field handling requirements across South America's climatic extremes.
- Powder:Standard free-flowing formulations serve cost-optimized feed mills with climate-controlled storage, though tropical humidity degradation limits coastal Brazilian adoption.
- Liquid:Pumpable acid solutions enable automated dosing integration at large integrator facilities, with buffered variants reducing corrosion risks in Paraná processing corridors.
- Granular:Coated particles minimize dust exposure and improve flowability for cooperatives with basic mixing equipment.
- Spray-dried:Encapsulated microspheres with sustained-release properties protect acid potency through heat stress periods, gaining traction among Rio Grande do Sul broiler operations.
Procurement volume clusters in Powder. Technology migration favors Spray-dried.
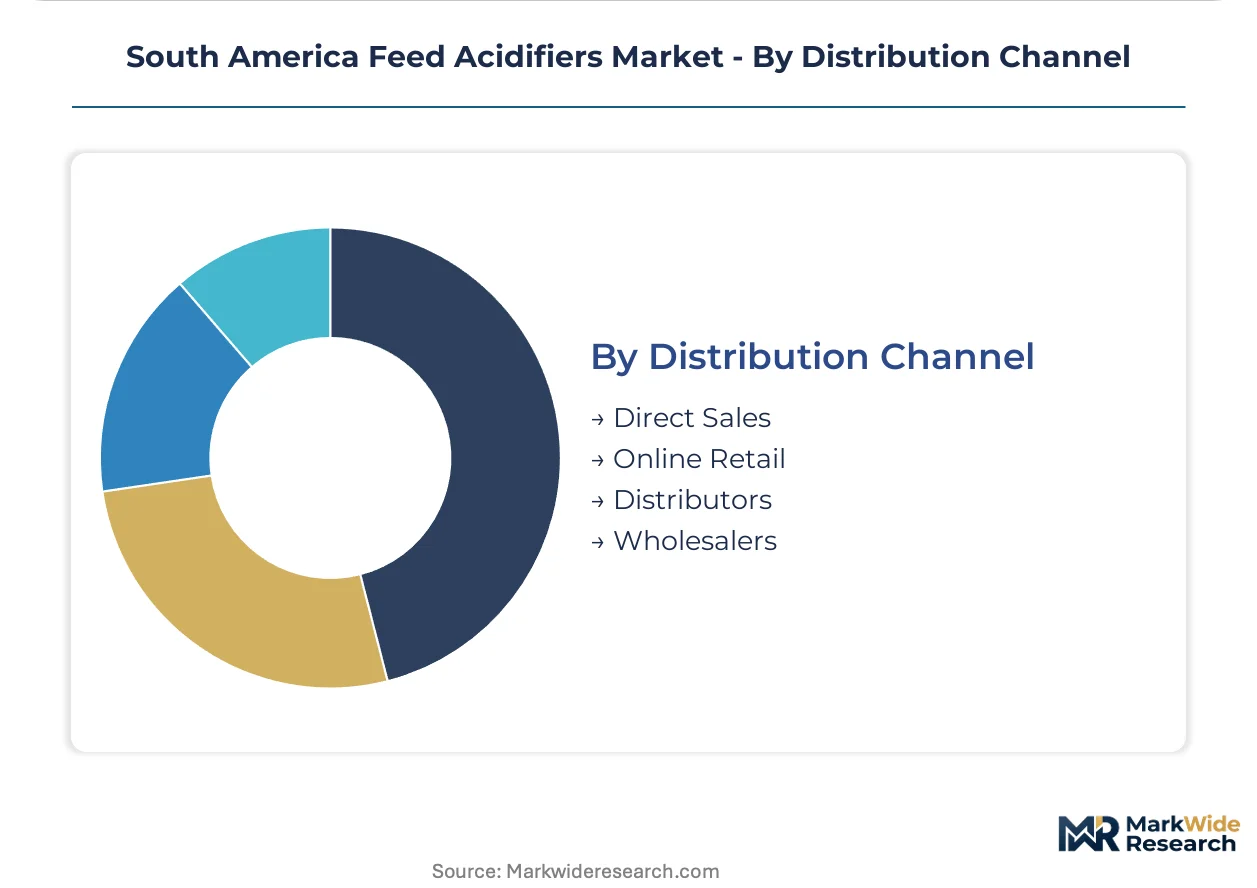
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and the digitization frontier in agricultural input procurement.
- Distributors:Regional feed additive specialists dominate mid-tier cooperative access, bundling acidifier supply with on-farm technical support in Argentina's grain belt.
- Direct Sales:Vertically integrated protein exporters negotiate volume contracts with guaranteed feed conversion outcomes, bypassing distributor markups.
- Online Retail:E-procurement platforms emerge for standardized acidifier products at Santa Catarina swine operations with in-house nutritionist capacity.
- Wholesalers:Commodity acid traders serve smallholder segments with minimal formulation requirements.
Transaction volume runs through Distributors. Margin capture shifts toward Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands substantially greater feed acidifier volumes than Argentina, yet both countries face converging regulatory pressure from ANVISA and SENASA to eliminate antibiotic growth promoters. Chile and Colombia occupy smaller but higher-margin positions, while Peru's emerging poultry sector trails in formal acidifier adoption.
Brazil
Poultry integrators in São Paulo and Paraná states drive acidifier procurement as ANVISA tightens antibiotic-free transition timelines. The southern feedlot corridor from Mato Grosso do Sul to Rio Grande do Sul concentrates demand for buffered acid formulations engineered to tropical humidity conditions. São Paulo state processing facilities are upgrading laboratory infrastructure to meet anticipated residue monitoring harmonization with EU reference standards.
Argentina
SENASA's intensified Salmonella control protocols in the Pampas grain belt accelerate organic acid deployment across layer operations supplying Mercosur markets. Argentine exporters chase EU-aligned antibiotic-free certification, pulling premium-formulation demand from vertically integrated protein producers in Buenos Aires and Córdoba provinces. The Rosario grain hub anchors compound feed manufacturing where citric acid import dependency creates foreign exchange exposure.
Chile
Salmon aquaculture operations in the Los Lagos region command premium pricing for acidified functional feeds targeting Vibrio resistance under strict EU and US export standards. Chile's national fishery service enforces residue protocols that exceed regional baselines, concentrating procurement among full-service formulators with dedicated veterinary technical teams. Puerto Montt processing clusters integrate acidifier dosing into automated feed manufacturing lines.
Colombia
Colombia's poultry sector expansion in Cundinamarca and Valle del Cauca generates mid-tier acidifier demand from cooperatives lacking specialized mixing infrastructure. The national agricultural institute promotes gradual antibiotic reduction, though enforcement lags Brazilian and Argentine timelines. Bogotá-based feed mills represent the primary distribution channel entry point for multinational acidifier suppliers.
Peru
Peru's informal poultry sector in La Libertad and Ica regions relies on commodity acid traders rather than formulated blends, constraining value capture for premium suppliers. The national sanitary agency's feed additive registration framework remains under development, creating regulatory uncertainty for imported acidifier products. Lima metropolitan area feed manufacturing concentrates import logistics for citric and propionic acid supply chains.
South America Feed Acidifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The market structure concentrates leverage among vertically integrated grain-to-protein conglomerates that negotiate volume contracts with guaranteed feed conversion outcomes. Three strategic archetypes dominate: multinational chemical conglomerates with captive acid production, regional formulators with tropical stability engineering capabilities, and aquaculture-focused specialists commanding premium positioning. Competitive moves center on backward integration into organic acid manufacturing and technology licensing for sustained-release coating systems.
Among European-based chemical conglomerates, BASF SE and DSM-Firmenich occupy positions representing scale-driven supply security and R&D-intensive formulation science respectively. Kemin Industries exemplifies the regional specialist archetype with buffered acid capabilities. Cargill, Incorporated anchors the integrated supply chain tier through captive grain origination and protein processing control. These four companies illustrate how competitive positioning stratifies across commodity volume, technical service depth, and outcome-based contracting models.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| Cargill, Incorporated |
| Kemin Industries |
| Adisseo |
| Brenntag SE |
| Novus International |
| Perstorp Holding AB |
| Pancosma |
| Others |
Value Network & Pricing Analysis
Vertically integrated Brazilian poultry exporters concentrate procurement leverage across São Paulo and Paraná processing corridors, anchoring contract-based long-term offtake pricing with guaranteed feed conversion outcomes. This buyer archetype dominance compresses spot-market margins for commodity acid traders while rewarding full-service formulators with dedicated veterinary technical teams.
Pricing Analysis
Capacity additions in Brazilian coastal states are reshaping price floors for buffered acid formulations engineered to tropical humidity conditions. Three-tier pricing structure across premium, standard, and economy levels separates encapsulated microsphere delivery systems from powdered commodity acids and unformulated bulk supply. Price differentiation hinges on EU-aligned antibiotic-free certification grade and bundled technical advisory services. Cost compression in mid-tier cooperative supply is intensifying because propionic acid feedstock volatility erodes margin buffers. Smallholder segments in Peru's informal poultry sector exhibit highest price sensitivity, while Chilean salmon aquaculture operators demonstrate lowest sensitivity due to strict export compliance requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from Argentine compound feed mills and Brazilian integrators force redundancy across citric acid and propionic acid supply channels. Manufacturing concentration centers on Brazil, Argentina, and select Asian production hubs for feedstock acids. Raw material dependencies rest on petrochemical-derived propionic acid, citrus-processing citric acid, and mineral-sourced phosphoric acid. Single-source vulnerability persists for citric acid given concentrated Asian sourcing and foreign exchange exposure at Rosario grain hub procurement desks. Distribution runs through regional feed additive specialists bundling acidifier supply with on-farm technical support, though direct sales contracts gain share among vertically integrated protein exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's phased antibiotic growth promoter restrictions compound demand acceleration across Brazilian poultry corridors, transforming feed acidifiers from optional additives into mandatory formulation components for EU market access.
For Market Incumbents: Deploy backward integration into organic acid manufacturing to secure captive supply of propionic and citric acid feedstocks against Asian import dependency. Deepen technical service capacity in Rio Grande do Sul and Santa Catarina to defend against regional formulators with tropical stability engineering capabilities. Capture ANVISA fast-track registration windows for natural acid blends to establish exclusivity moats before competitor filings. For New Entrants and Emerging Players: E-procurement platforms represent the most penetrable channel route for standardized acidifier products at mid-scale Santa Catarina swine operations with in-house nutritionist capacity. Target Peru's informal poultry sector in La Libertad and Ica regions with commodity acid offerings before regulatory formalization raises compliance barriers. Pursue outcome-based contracting models bundling acidifier supply with performance guarantees rather than ingredient inclusion rates. For Investors and Strategic Acquirers: Multinational chemical conglomerates with captive acid production are the most active acquirer in this space, seeking regional formulators with tropical stability engineering capabilities and ANVISA registration portfolios. Acquisition target archetypes include buffered acid specialists with humidity-resistant coating technologies and established SENASA audit relationships. Monitor Mercosur-EU trade negotiation progress as the critical inflection signal for regulatory equivalence harmonization and premium-formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acid Manufacturing | Captive propionic acid supply shields Brazilian formulators from petrochemical feedstock volatility and Asian import dependency. |
| Encapsulated Microsphere Technology Licensing | Sustained-release coating patents command premium positioning in Rio Grande do Sul broiler operations facing tropical heat stress. |
| ANVISA Fast-Track Registration Pursuit | Eighteen-month exclusivity windows for natural acid blends reward early movers with temporary competitive moats. |
| Technical Service Capacity Expansion | Field nutritionist deployment in Paraná and Santa Catarina addresses antibiotic-free transition program calibration delays. |
| Direct-to-Farm Digital Channel Development | E-procurement platforms bypass distributor markups for standardized products at mid-scale operations with in-house expertise. |
Research Methodology
Multiple input streams — structured interviews with feed formulation directors, regulatory affairs specialists at ANVISA and SENASA, and procurement leads at vertically integrated protein exporters — were reconciled against secondary validation from customs trade databases, SEC filings of multinational chemical conglomerates, and compound feed manufacturing capacity registries. Bottom-up and top-down triangulation cross-checked volume estimates from acidifier inclusion rate assumptions against production data from São Paulo and Paraná processing facilities.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, animal species physiology, physical delivery form, and distribution channel structure. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory milestone impacts. Forecast inputs incorporated ANVISA registration pipeline velocity and SENASA residue protocol tightening schedules without year-specific anchoring.
The model assumes a particular technology adoption path; alternative pathways for encapsulated sustained-release coating systems would alter the outlook if unformulated acid traders accelerate price competition. Deviation in Mercosur-EU trade negotiation outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Agriculture Micronutrients Market