
 Liquid Paperboard Market | 2026-2036
Liquid Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Paperboard Market Outlook
Subscription-based packaging-as-a-service models for aseptic filling lines is expanding the addressable revenue pool beyond substrate sales alone. Tetra Pak International S.A. leverages its integrated processing-and-packaging ecosystem to lock in long-term customer contracts. Stora Enso Oyj anchors its competitive position through captive pulp supply and renewable material science investments across Nordic mills. SIG Combibloc Group AG differentiates via standardized, lightweight carton geometries that reduce freight costs for beverage brands.
Liquid paperboard consists of multi-ply fiber substrates, typically incorporating polyethylene or aluminum barrier layers, engineered to contain liquids without leakage or flavor degradation. The material is thermoformed and sealed into cartons using roll-fed or blank-fed processes, serving as the primary packaging medium for shelf-stable beverages, broths, and liquid dairy. Coated liquid paperboard commands the dominant volume share due to its cost-performance balance in high-speed filling operations, while laminated grades capture expanding margin pools in premium functional beverage segments. Within end-use applications, food and beverage packaging absorbs the majority of substrate tonnage, though healthcare liquid formats for oral nutritional supplements represent a faster-growing demand pocket with stricter sterility requirements.
The EU's Packaging and Packaging Waste Regulation and the FDA's food-contact substance notification program jointly shape substrate compliance costs and regional market access conditions for liquid paperboard suppliers. China's SAMR enforces GB standards for composite food-contact materials, creating divergent testing and certification burdens for multinational converters operating across jurisdictions. Stakeholders must monitor how extended producer responsibility frameworks evolve in the EU and whether chemical recycling pathways for polyethylene-aluminum barrier layers achieve technical scale.
Market Dynamics
Aseptic carton adoption in Southeast Asia's dairy and plant-based beverage sectors is compressing demand cycles for liquid paperboard converters, forcing capacity reallocation toward barrier-grade substrates that meet tightening food-contact specifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating substrate lightweighting investments across Nordic and German converter networks.
- Indonesia ready-to-drink tea sector:Local bottlers are tripling aseptic line installations, pulling coated liquid paperboard volumes toward Java-based filling clusters.
- Aluminum-barrier lamination:Premium functional beverage brands are specifying higher-barrier grades for extended shelf-life claims in ambient distribution.
Market Restraints
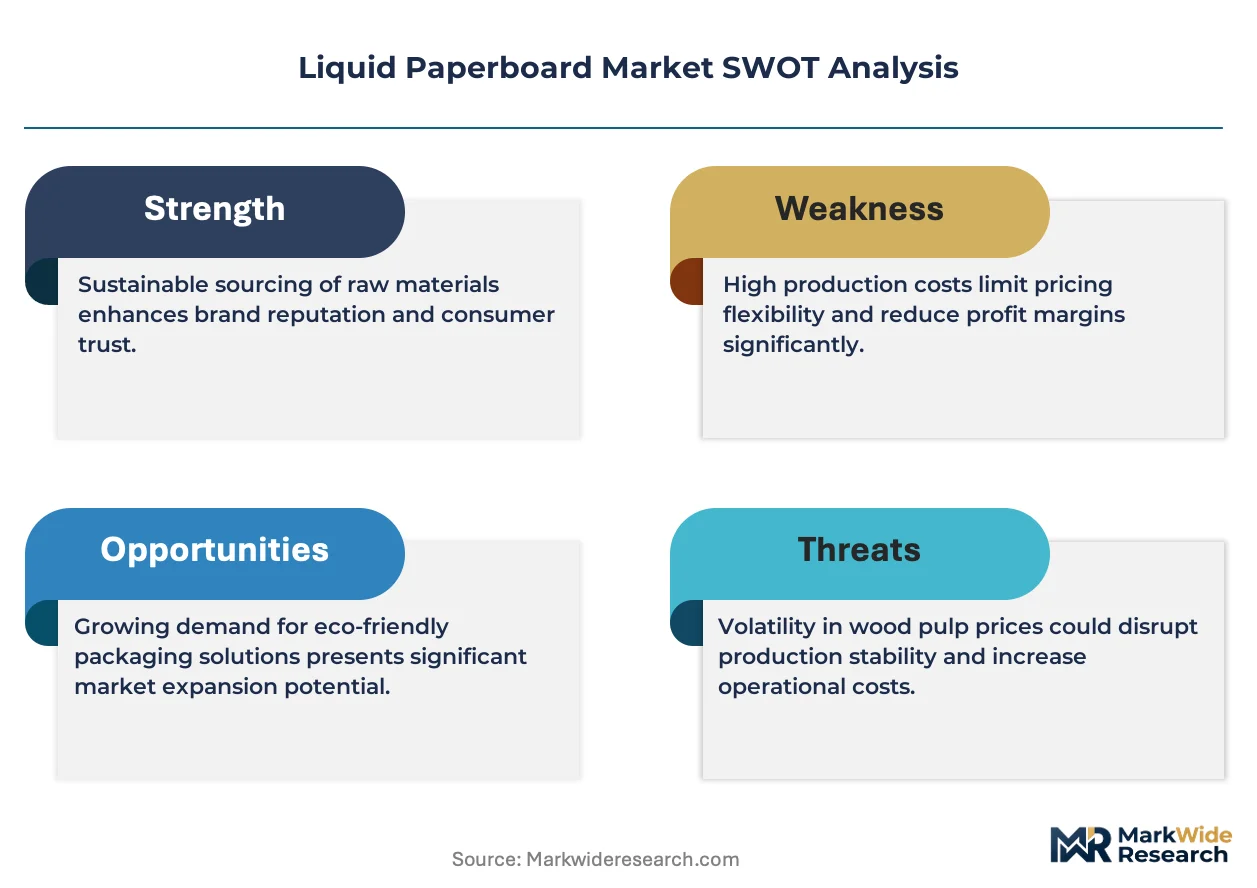
- Pulp cost volatility:Nordic softwood pulp price swings compress converter margins on standard-grade coated board.
- China GB standards divergence:SAMR's composite material testing protocols create dual-certification burdens for multinational suppliers.
- Polyethylene-aluminate recycling gap:Chemical recycling pathways for multi-layer barrier structures remain pre-commercial, limiting circularity claims.
Strategic Opportunities
- India oral nutritional supplements:Healthcare liquid formats with sterility requirements represent underpenetrated demand with premium pricing power.
- EU Green Deal packaging targets:Renewable material mandates create preferential market access for fiber-based barrier solutions.
- Digital print integration:Variable-data carton decoration enables regional SKU proliferation without plate-change downtime.
Industry Challenges
- Aseptic line engineering talent:Shortage of technicians capable of commissioning and maintaining high-speed filling equipment extends project timelines.
- Dual-carbon compliance documentation:China's MEE emission tracking requirements demand new data infrastructure across supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Paperboard Market |
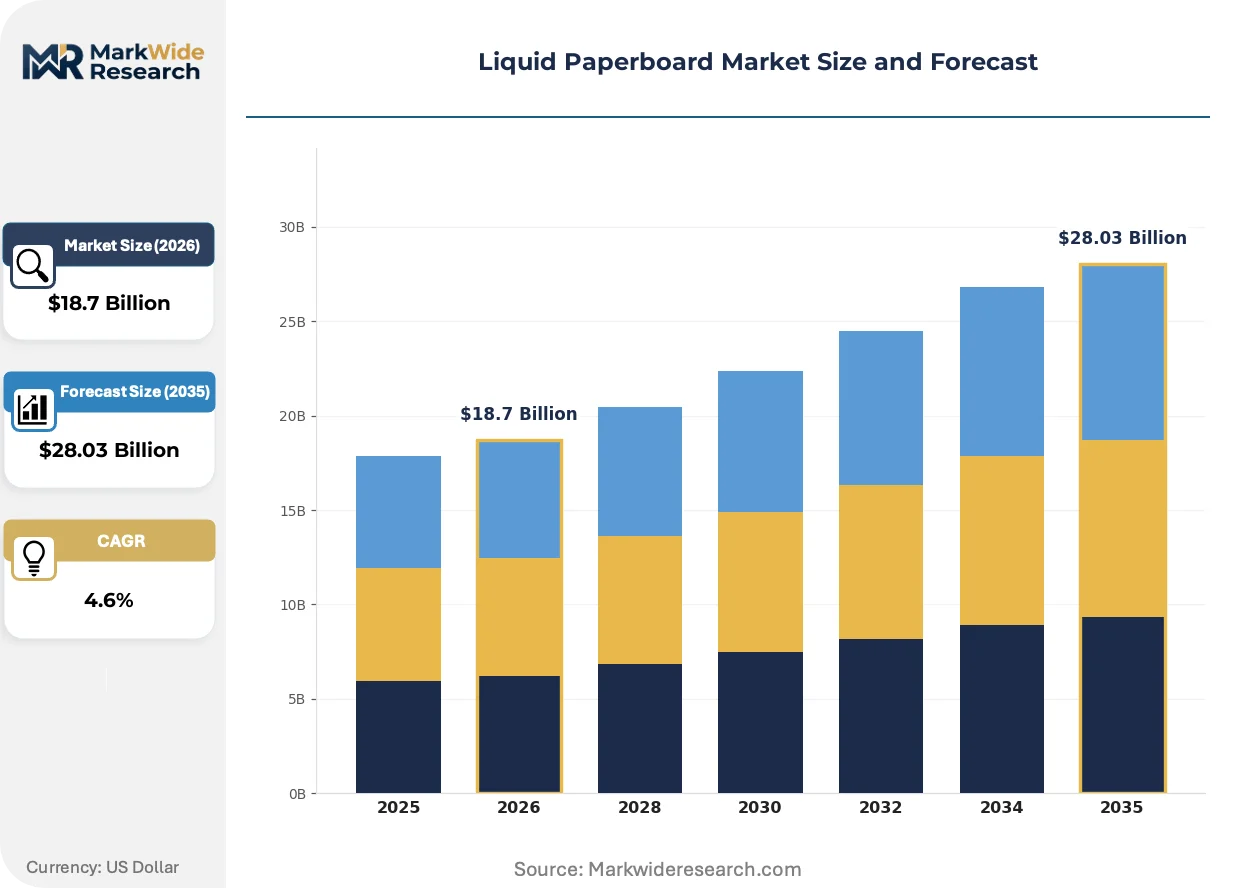
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Laminated, Recycled End Use Industry: Food & Beverage, Healthcare, Personal Care, Household Packaging Type: Cartons, Containers, Tetra Paks, Packs Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Tetra Pak International S.A., Stora Enso Oyj, SIG Combibloc Group AG, Elopak AS, WestRock Company, Nippon Paper Industries Co. Ltd., Greatview Aseptic Packaging Co. Ltd., Graphic Packaging International, Billerud AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Paperboard Market Strategic Shifts
Barrier-layer engineering and filling-line integration are converging to redefine liquid paperboard value capture, shifting competitive advantage from substrate commodity supply toward system-level performance guarantees.
Plant-fiber barrier coatings are expanding into aluminum-free carton architectures. European dairy brands are piloting these substrates for chilled distribution. The technology is expanding into premium-positioned organic milk segments where metal-free claims command shelf-space premiums.
China's GB standards for food-contact composite materials are tightening substrate migration limits. Converter networks must retest legacy polyethylene formulations against revised SAMR protocols. Dairy exporters to China face extended certification timelines that compress order-to-delivery windows.
Beverage brands are consolidating aseptic filling contracts around packaging-as-a-service models. Subscription-based line access replaces capital-heavy equipment purchases among mid-sized Southeast Asian bottlers. Indonesia and Vietnam show the fastest contract restructuring toward operational-expense-based procurement structures.
Liquid Paperboard Market Segmentation
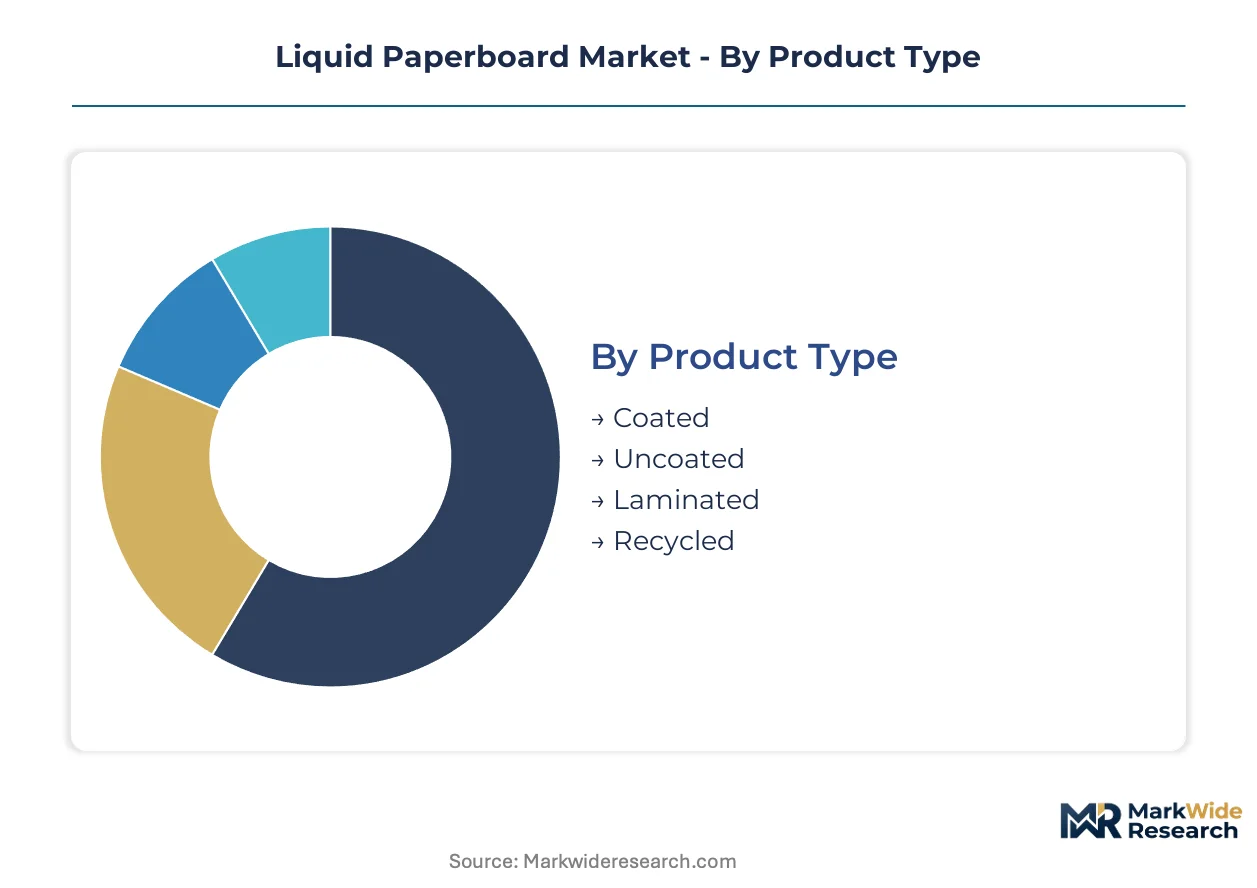
Liquid paperboard segmentation reflects divergent technical requirements across barrier performance, sterility standards, and filling-line compatibility. Converter margins vary substantially by substrate complexity and end-use certification burden.
Product Type:
Buyers differentiate primarily by barrier specification and filling-speed compatibility, with premium applications demanding multi-layer lamination while commodity volumes run on simpler coated grades.
- Coated:Polyethylene-extruded fiber substrates balance moisture resistance with heat-seal efficiency for high-speed aseptic lines. Dairy and ready-to-drink tea bottlers across Indonesia specify coated grades for ambient distribution. Volume sits with coated; growth tilts toward laminated.
- Laminated:Aluminum-interlayer constructions deliver oxygen and light barriers for extended shelf-life claims. Premium functional beverage brands in European organic segments specify these for metal-free positioning. Laminated substrates command pricing premiums tied to certification complexity.
- Uncoated:Raw fiber boards serve chilled distribution chains with shorter shelf-life requirements. Limited penetration outside refrigerated dairy.
- Recycled:Post-consumer fiber content rising under EU Green Deal packaging targets. Migration testing protocols constrain food-contact deployment.
Coated grades absorb standard-volume dairy and beverage applications; laminated variants climb fastest on premium functional beverage expansion.
End Use Industry:
Application-driven segmentation tracks regulatory intensity, with healthcare and food-contact categories facing divergent compliance architectures.
- Food & Beverage:Aseptic carton demand concentrates in Southeast Asian dairy and plant-based beverage sectors. China's SAMR enforces GB standards for composite food-contact materials that extend certification timelines for exporters.
- Healthcare:Oral nutritional supplements require sterility-assured substrates with migration-tested barrier layers. India's healthcare liquid formats show underpenetrated demand with premium pricing power.
- Personal Care:Cosmetic liquid packaging favors lightweight carton geometries for freight cost reduction.
- Household:Cleaning product containers prioritize chemical resistance over oxygen barriers.
Food and beverage dominates tonnage; healthcare shows steepest expansion trajectory on sterility requirement premiums.
Packaging Type:
Geometry selection hinges on filling-line capital investment and distribution channel shelf-space constraints.
- Cartons:Roll-fed and blank-fed forming processes dominate ambient beverage distribution. Standardized geometries reduce converter tooling costs.
- Tetra Paks:Proprietary aseptic systems lock in long-term substrate supply contracts through integrated processing-and-packaging ecosystems.
- Containers:Rigid formats for household and personal care segments prioritize stackability.
- Packs:Flexible multi-pack configurations serve retail club-channel volumes.
Carton volumes lead; Tetra Pak-integrated formats expand most quickly in Southeast Asian contract restructuring.
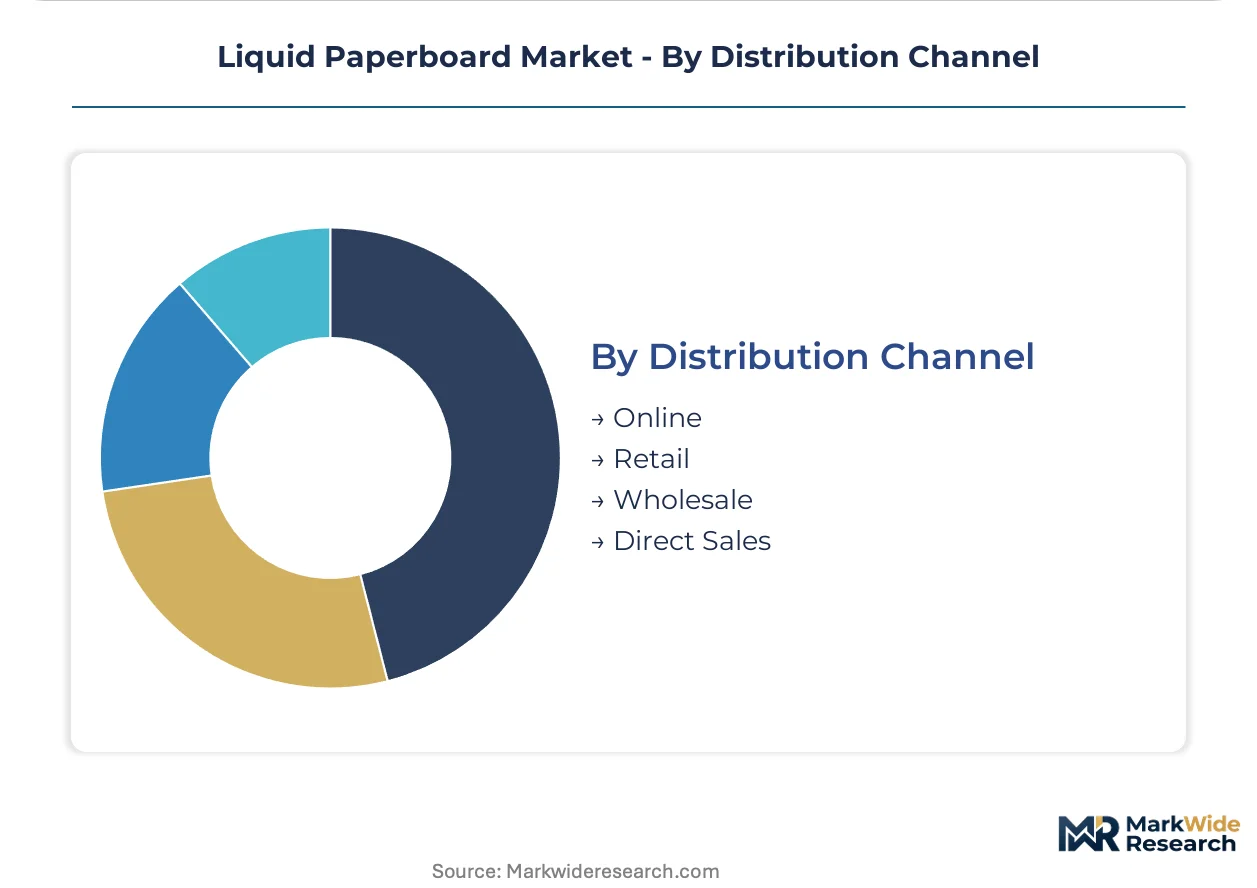
Distribution Channel:
Channel segmentation reflects procurement scale and technical service intensity requirements.
- Direct Sales:Packaging-as-a-service models for aseptic filling lines concentrate in Indonesia and Vietnam, replacing capital-heavy equipment purchases with subscription-based line access.
- Wholesale:Converter networks supply standardized coated grades to mid-sized bottlers through distributor inventories.
- Retail:Smaller beverage brands procure pre-formed cartons through packaging distributors.
- Online:Digital procurement platforms emerging for specification-grade substrate sampling.
Direct sales capture long-term contract value; wholesale moves standard-grade volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Nordic and North American pulp regions, while consumption tilts toward Southeast Asian filling operations. This geographic split shapes freight economics and converter investment patterns.
China
GB standards from SAMR tighten migration limits on polyethylene barrier layers. Dairy exporters face extended certification timelines that compress order-to-delivery windows. Shanghai and Guangdong filling clusters absorb coated liquid paperboard volumes for ready-to-drink tea distribution.
Indonesia
Local bottlers triple aseptic line installations for ready-to-drink tea and plant-based beverages. MEE emission tracking requirements demand new data infrastructure across supplier networks. Java-based filling clusters pull coated substrate volumes toward Jakarta and Surabaya industrial corridors.
Germany
EU Packaging and Packaging Waste Regulation mandates accelerate substrate lightweighting investments. Extended producer responsibility frameworks reshape converter network economics. Bavarian and North Rhine-Westphalia mill regions supply barrier-grade substrates to central European dairy brands.
United States
FDA food-contact substance notification programs shape regional market access conditions for imported substrates. Healthcare liquid formats for oral nutritional supplements drive premium-grade demand. Wisconsin and Georgia filling corridors concentrate aseptic carton conversion capacity.
India
FSSAI enforcement of composite food-contact standards extends certification burdens for multinational converters. Oral nutritional supplements in healthcare liquid formats show underpenetrated demand with premium pricing power. Maharashtra and Gujarat bottling clusters expand aseptic line capacity for ambient dairy distribution.
Liquid Paperboard Market Competitive Environment
Top-tier vendors anchor integrated processing-and-packaging ecosystems, while mid-tier converters compete on standardized substrate geometries and regional freight optimization. The vendor base stratifies around captive pulp supply, barrier-layer engineering capabilities, and aseptic line service integration. Three archetypes dominate: Nordic pulp-integrated multinationals, Asian filling-line specialists, and North American packaging conglomerates with diversified fiber portfolios. Competitive moves concentrate on backward integration into pulp supply and subscription-based packaging-as-a-service contract structures.
Among the pulp-integrated tier, Tetra Pak International S.A. and Stora Enso Oyj occupy positions defined by captive raw material access and renewable material science investments. SIG Combibloc Group AG exemplifies the standardized-geometry specialist archetype, with lightweight carton designs that reduce freight costs for beverage brands. These three entities represent distinct competitive vectors: ecosystem lock-in, upstream resource control, and operational-efficiency-focused product platforms.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Stora Enso Oyj |
| SIG Combibloc Group AG |
| Elopak AS |
| WestRock Company |
| Nippon Paper Industries Co. Ltd. |
| Greatview Aseptic Packaging Co. Ltd. |
| Graphic Packaging International |
| Billerud AB |
| Others |
Value Chain & Pricing Dynamics
Nordic softwood pulp contracts cascade through three pricing tiers before reaching Indonesian bottlers, with captive pulp supply anchoring premium positions and spot-market exposure pressuring mid-tier converters serving Java-based filling clusters.
Pricing Analysis
Margin tightening in standard-grade coated board reflects pulp cost volatility and dual-certification burdens under China's SAMR protocols. Three-tier pricing structure across premium, standard, and economy levels separates aluminum-barrier laminated substrates from polyethylene-coated grades and uncoated chilled-distribution alternatives. Certification complexity under EU Packaging and Packaging Waste Regulation commands premium positioning, while wholesale procurement of standard coated volumes shows highest price sensitivity among mid-sized Southeast Asian bottlers.
Supply Chain Analysis
Certification gating under FDA food-contact substance notifications, EU EFSA migration limits, and China's GB standards fragments supplier eligibility across export corridors. Raw material supply draws from Swedish and Finnish pulp mills, German barrier-film extrusion facilities, and Indonesian converting operations. Single-source vulnerability concentrates in Nordic softwood pulp streams. Distribution runs through direct packaging-as-a-service contracts in Jakarta and Surabaya, supplemented by wholesale converter networks serving smaller bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-fiber barrier coatings are displacing aluminum-interlayer constructions in European organic dairy segments, compressing legacy laminated substrate margins while opening premium positioning for metal-free claims.
For Market Incumbents: Deploy captive pulp supply leverage to lock in long-term aseptic line contracts before plant-fiber barrier coatings achieve technical scale. Backward integration into renewable material science investments across Nordic mills defends margin position against SIG Combibloc's standardized-geometry freight optimization. Tetra Pak's integrated processing-and-packaging ecosystem presents the dominant competitive threat to standalone substrate suppliers.
For New Entrants and Emerging Players: Launch via packaging-as-a-service models targeting Indonesia's ready-to-drink tea bottlers tripling aseptic line installations. India's oral nutritional supplements segment offers underpenetrated healthcare demand with sterility-assured premium pricing. Digital print integration for variable-data carton decoration enables regional SKU proliferation without plate-change capital burden.
For Investors and Strategic Acquirers: Distressed-cycle entries favor pulp-integrated converters with FDA and SAMR dual-certification infrastructure in Germany and the United States. Long-term viability hinges on chemical recycling pathway maturation for polyethylene-aluminum barrier layers. Watch EU Green Deal renewable material mandate enforcement as inflection signal for fiber-based barrier solution preferential access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic softwood access insulates margin from spot price volatility. |
| Packaging-as-a-Service Contract Restructuring | Subscription-based line access locks Indonesian bottlers into long-term substrate commitments. |
| Plant-Fiber Barrier Coating Scale-Up | Metal-free claims command shelf-space premiums in European organic dairy segments. |
| Dual-Certification Infrastructure Investment | FDA-SAMR parallel compliance enables uninterrupted China dairy export corridors. |
| Chemical Recycling Pathway Development | Polyethylene-aluminum circularity unlocks EU extended producer responsibility compliance. |
Study Parameters
Document review covered trade customs data, SEC filings from packaging conglomerates, EU EFSA migration limit documentation, and SAMR GB standard protocols, complemented by interviews with aseptic line engineers at Indonesian bottling clusters, procurement directors at Nordic pulp-integrated multinationals, and regulatory affairs leads navigating FDA food-contact substance notifications. Primary fieldwork across converter networks in Germany, India, and Vietnam was cross-referenced against secondary validation from FAO dairy trade statistics and IEA pulp production databases. Bottom-up substrate volume modeling was triangulated with top-down end-use consumption estimates.
Historical capacity utilization patterns were cross-referenced against expert panel inputs from barrier-layer R&D directors and filling-line commissioning specialists. Segmentation dimensions modeled include barrier specification tier, end-use industry regulatory intensity, filling-line speed compatibility, and geographic certification cluster. CAGRs were derived from slope-intercept trajectory fitting across the projection horizon, incorporating pulp price elasticity coefficients and aseptic line installation rates as industry-specific forecast inputs.
Pulp cost volatility, regulatory timeline extensions under China's SAMR retesting protocols, and chemical recycling pathway commercialization delays are the dominant revision risks across the analysis window. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Aramid Paper Market
Paper Products
Filtration Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Metallized Paper Market
Paper Products
Leatheroid Paper Market
Paper Products
Global Direct Thermal Ticket Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
GCC Stone Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Europe Coated Paper Market
Paper Products
Overlay Paper Market
Paper Products
Uncoated White Top Testliner Market