
 Wood-Based Panel Market | 2026-2036
Wood-Based Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Wood-Based Panel Market Intelligence
E0 and E1 emission-grade certification is reorganizing procurement priorities across residential and commercial construction channels. West Fraser Timber Co. Ltd. leverages its integrated softwood timber position to control fiber supply for oriented strand board mills across the southern United States. Kronospan Holding Limited anchors European capacity through continuous press investments in Germany and Poland. Georgia-Pacific LLC competes on scale in the particle board segment with multi-regional distribution density.
Wood-based panels are engineered sheet materials manufactured from wood fibers, particles, strands, or veneers bonded under heat and pressure with synthetic resins, typically achieving densities between 500 kg/m³ and 800 kg/m³ depending on product class. These panels substitute solid lumber in structural and decorative applications where dimensional stability, uniform strength, and cost efficiency matter. Medium Density Fiberboard and Particle Board dominate volume production for furniture and interior fit-outs, while Oriented Strand Board captures structural sheathing demand in North American light-frame construction. Plywood retains premium positioning in marine-grade and concrete-forming specifications where delamination resistance commands margin premiums over commodity substitutes.
The EPA Toxic Substances Control Act Title VI regulates formaldehyde emissions from composite wood products sold in the United States, compelling resin reformulation and third-party certification. The EU Timber Regulation and Ecodesign Directive enforce chain-of-custody documentation and restrict hazardous substance content in panels placed on European markets. Stakeholders must monitor evolving bio-based binder technologies and regional carbon-accounting frameworks as these factors increasingly determine product qualification and long-term contract eligibility.
Market Dynamics
The Wood-Based Panel Market pivots on formaldehyde emission regulations that are forcing resin reformulation across all major producing regions. EPA Title VI in the United States and the EU Timber Regulation are compressing margins for non-compliant manufacturers while rewarding certified producers with contract eligibility.
Growth Catalysts
- Light-frame construction codes:North American building standards are expanding structural applications for oriented strand board in multi-story residential projects, displacing plywood in shear wall specifications.
- EU Ecodesign Directive:Chain-of-custody documentation requirements are locking in demand for FSC-certified panels among European furniture exporters serving contract interiors.
- Bio-based binder R&D:Laboratory-scale lignin and tannin adhesives are approaching commercial viability, promising emission-free alternatives to urea-formaldehyde resins.
Market Restraints
- Resin cost volatility:Methanol and urea feedstock prices track natural gas benchmarks, exposing panel margins to energy market swings without pass-through mechanisms in long-term supply contracts.
- Softwood fiber concentration:Southern United States timberland ownership concentrates among REITs and institutional investors, limiting mill-site flexibility for new oriented strand board capacity.
- Concrete and steel substitution:Mass timber construction faces code acceptance gaps in seismic zones, restricting cross-laminated timber penetration in high-rise commercial buildings.
Strategic Opportunities
- India furniture manufacturing:The country's PLI scheme for wood products is attracting panel investments to serve domestic consumption and Middle East export demand.
- Retrofit building stock:European energy renovation mandates are creating specification channels for pre-finished medium-density fiberboard in interior insulation systems.
- Digital fabrication convergence:CNC routing and parametric design software are enabling mass-customized furniture production from standard panel dimensions.
Industry Challenges
- Resin chemist talent scarcity:Formulation expertise for low-emission binders concentrates among aging specialists at German and Austrian research institutes.
- Continuous press capex intensity:Single-line investments exceed 150 million euros, freezing out mid-scale producers from capacity expansion.
- CARB-to-EPA certification overlap:Dual testing requirements for California and federal markets extend product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood-Based Panel Market |
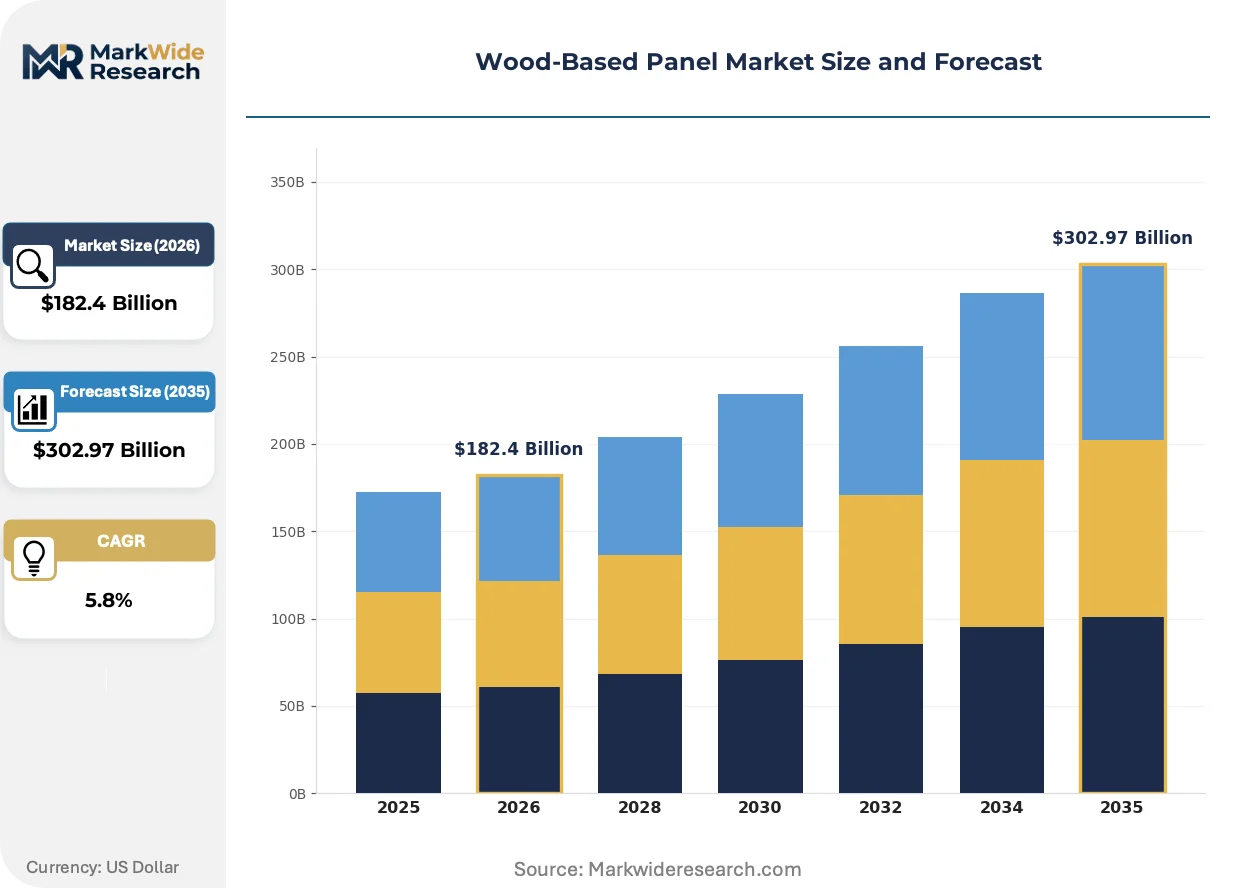
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $302.97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Medium Density Fiberboard, Oriented Strand Board, Particle Board End User: Furniture Manufacturers, Construction Industry, Automotive, Packaging Thickness: Thin Panels, Medium Panels, Thick Panels, Heavy-Duty Panels Application: Interior Design, Flooring, Wall Panels, Cabinetry |
| Companies Covered | West Fraser Timber Co. Ltd., Sonae Arauco SGPS, S.A., Kronospan Holding Limited, Kastamonu Entegre Ağaç Sanayi ve Ticaret A.Ş., Celulosa Arauco y Constitución S.A., Georgia-Pacific LLC, EGGER Holzwerkstoffe GmbH, Duratex S.A., Weyerhaeuser Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood-Based Panel Market Strategic Shifts & Innovations
Bio-based chemistry and digital manufacturing are compressing the traditional panel-to-product value chain. These forces are reconfiguring where margin accumulates and which capabilities determine competitive survival.
Continuous press technology is miniaturizing. These machines consolidate forming, pressing, and cooling into single automated lines, reducing labor content per cubic meter by two-thirds. European equipment suppliers are retrofitting mid-scale Asian mills with compact 2.4-meter-wide presses. The technology is miniaturizing capital barriers, enabling distributed production closer to urban furniture clusters.
REACH Annex XVII restrictions on formaldehyde are tightening testing protocols for imported panels. The European Chemicals Agency now requires third-party verification of emission claims at point of entry. German kitchen manufacturers are demanding E0-grade certification as a condition of supplier qualification, filtering out commodity exporters from Baltic states.
Specification behavior is fragmenting across project types. Large residential developers are consolidating panel procurement through direct mill contracts, bypassing distribution layers. Custom furniture workshops are sourcing cut-to-size blanks through online platforms that aggregate regional capacity. The shift is most visible in Poland and Czech Republic, where CNC-equipped job shops now represent thirty percent of particle board offtake.
Wood-Based Panel Market Segmentation
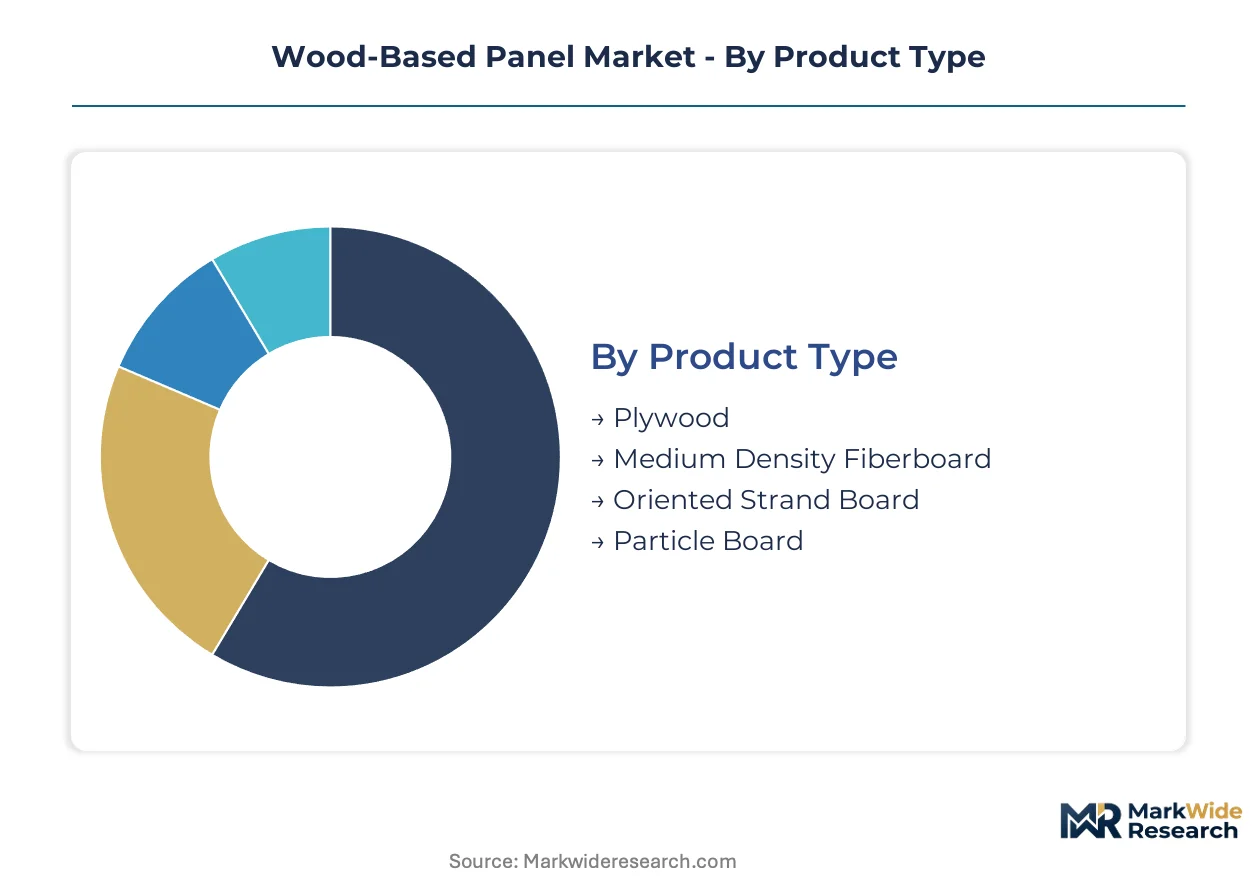
Segmentation in wood-based panels determines resin formulation, press configuration, and distribution channel selection. Product type and end-user concentration dictate margin structure and capital intensity across manufacturing footprints.
Product Type:
Channel flow splits between bulk commodity distribution for structural grades and specification-driven direct supply for certified decorative panels.
- Plywood:Cross-laminated veneer construction delivers delamination resistance for concrete forming and marine applications. Japanese construction standards and US West Coast multi-family developers concentrate specification demand for structural grades certified under APA standards.
- Medium Density Fiberboard:Homogeneous wood fiber mat formed under continuous press delivers surface uniformity for thermofoil lamination. German kitchen manufacturers and Polish furniture exporters drive E0-grade procurement through direct mill contracts bypassing distribution layers.
- Oriented Strand Board:Flaked softwood strands aligned in cross-directional layers substitute plywood in North American shear wall applications.
- Particle Board:Chipped wood particles bonded with urea-formaldehyde resin serve low-cost furniture cores and interior fit-outs.
Plywood dominates installed base in premium structural applications. Medium Density Fiberboard is where expansion concentrates as furniture manufacturers consolidate procurement around emission-certified supply.
End User:
Customer type determines order size, certification requirements, and technical service intensity.
- Furniture Manufacturers:Specification of E0 and E1 emission grades for export markets demands chain-of-custody documentation and third-party certification. Vietnamese and Polish producers now represent the primary volume absorption for particle board and MDF blanks.
- Construction Industry:Structural sheathing demand for light-frame residential and commercial buildings drives OSB volume. US southern states building codes and Canadian multi-story wood construction standards are expanding application scope beyond single-family housing.
- Automotive:Lightweight panel cores for interior trim and load floors require density optimization and thermoformability.
- Packaging:Crating and pallet applications absorb lower-grade particle board and plywood offcuts.
Construction Industry commands the largest volume share. Furniture Manufacturers represent the steepest expansion trajectory as export-driven certification requirements filter supplier bases.
Thickness:
Press configuration and raw fiber consumption scale directly with panel thickness, segmenting production economics.
- Thin Panels:Sub-9mm fiberboard and plywood serve laminate flooring substrates and decorative overlay applications. Chinese flooring exporters concentrate demand for 6-8mm HDF cores.
- Medium Panels:12-18mm range captures standard furniture construction and interior wall systems. European pre-finished panel distributors stock this thickness band most heavily.
- Thick Panels:22-38mm structural panels and high-density fiberboard support work surfaces and load-bearing furniture frames.
- Heavy-Duty Panels:40mm-plus construction-grade plywood and specialty OSB serve industrial flooring and concrete forming where repeated reuse justifies premium pricing.
Medium Panels dominate current production capacity. Thin Panels are gaining share fastest as flooring manufacturers optimize material efficiency.
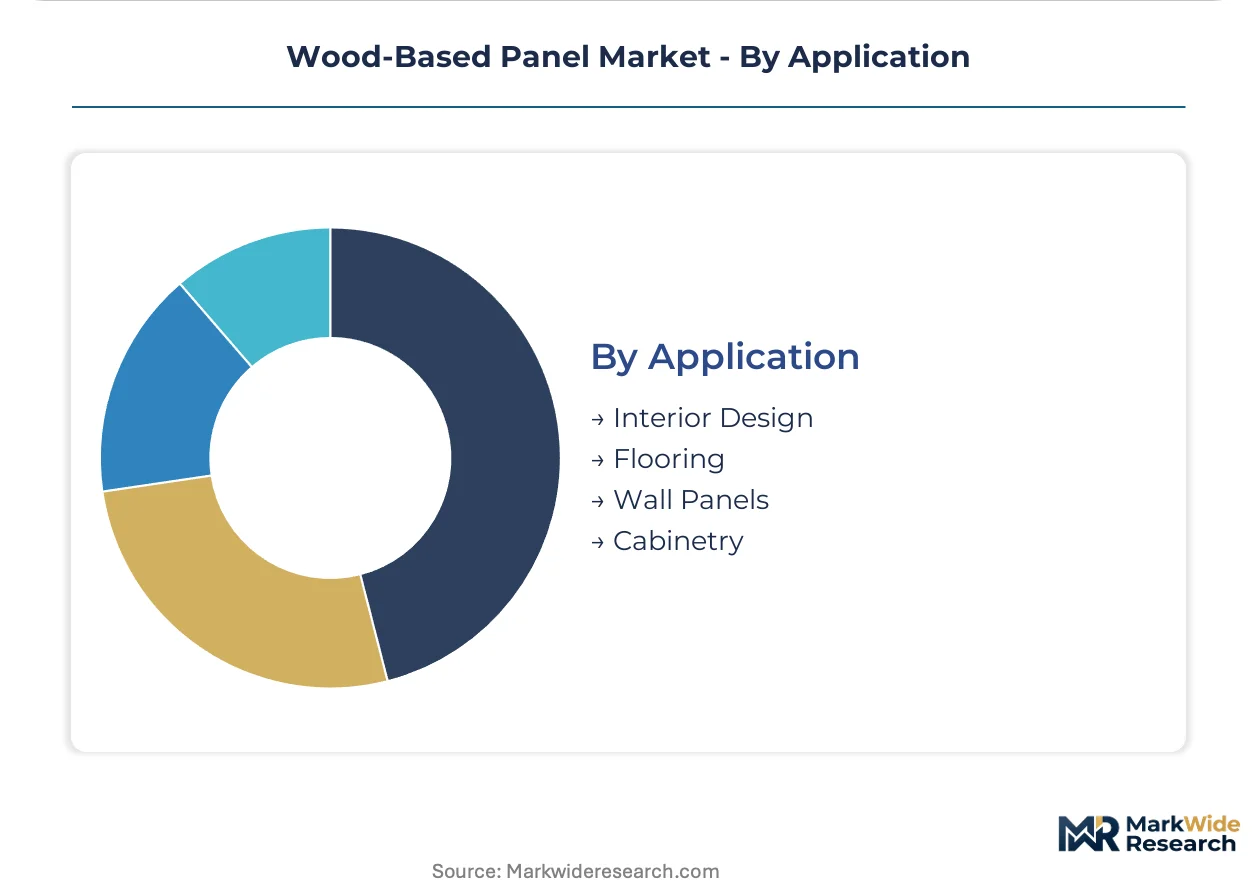
Application:
End-use specification determines surface quality, emission certification, and finishing requirements.
- Interior Design:Decorative veneered and melamine-faced panels for wall cladding and ceiling systems. UAE hospitality projects and German office fit-out contractors drive demand for FSC-certified and fire-rated grades.
- Flooring:High-density fiberboard substrates for laminate and engineered wood flooring. Chinese and German flooring producers concentrate procurement through long-term supply agreements.
- Wall Panels:Structural sheathing and decorative interior panels for residential and commercial buildings.
- Cabinetry:Moisture-resistant MDF and plywood grades for kitchen and bath applications requiring dimensional stability.
Interior Design commands premium pricing tiers. Flooring is where volume expansion concentrates as global laminate flooring production shifts toward Asian manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Softwood fiber supply chains concentrate among institutional timberland owners across the southern United States, while finished panel demand disperses toward furniture manufacturing clusters in Poland, Vietnam, and Mexico. This geographic split between raw material control and value-added consumption defines competitive positioning across regions. Regulatory divergence on formaldehyde emissions and chain-of-custody documentation creates compliance friction for exporters serving multiple markets.
United States
Light-frame residential construction codes in Texas and the Carolinas are expanding oriented strand board specifications for multi-story shear wall applications. The EPA Toxic Substances Control Act Title VI mandates third-party certification for composite wood products sold across state lines. Southern yellow pine plantations around Augusta, Georgia and Alexandria, Louisiana supply fiber to the continent's densest concentration of OSB press capacity.
Germany
German kitchen manufacturers in Bielefeld and Paderborn are consolidating procurement around E0-grade medium-density fiberboard with full chain-of-custody documentation. The EU Ecodesign Directive and REACH Annex XVII restrictions on formaldehyde tighten testing protocols for imported panels at point of entry. The Egger and Kronospan mill complexes in Bavaria and Thuringia anchor European continuous press technology leadership.
China
Laminate flooring exporters in Changzhou and Henglin are absorbing rising volumes of 6-8mm high-density fiberboard substrates for Middle East and European shipments. The country's national standards regulator enforces GB/T formaldehyde emission classifications that partially align with CARB Phase II thresholds. Yangtze River Delta panel producers are retrofitting compact continuous presses to serve dispersed urban furniture clusters.
Brazil
Furniture exporters in Bento Gonçalves and São Bento do Sul concentrate demand for medium-density fiberboard and plywood grades certified for North American and European retail channels. ANVISA maintains cosmetic-grade resin standards that diverge from structural panel regulations enforced by the national construction regulator. Eucalyptus plantation supply around Três Lagoas in Mato Grosso do Sul underpins cost-competitive fiberboard integration.
Poland
Export-oriented furniture manufacturers in Poznań and Ostrów Wielkopolski are driving specification of FSC-certified particle board and pre-finished MDF through direct mill contracts. The EU Timber Regulation enforcement has eliminated non-compliant Baltic suppliers from German kitchen industry supplier lists. CNC-equipped job shops in Lower Silesia now represent a significant share of regional particle board offtake through cut-to-size blank platforms.
Wood-Based Panel Market Key Industry Players
Concentration sits with integrated softwood timber owners and continuous press technology leaders across North America and Europe. The market structure divides between scale-driven commodity producers serving structural construction channels and specification-focused specialists capturing furniture industry certification premiums. Three archetypes dominate: timberland-integrated OSB manufacturers, European continuous press technology licensors, and Asian distributed-production fabricators. Competitive moves center on backward integration into plantation fiber supply and technology licensing partnerships for compact press retrofits.
Among North American timberland-integrated producers, West Fraser Timber Co. Ltd. and Weyerhaeuser Company occupy positions defined by captive softwood fiber access. European technology and scale leadership clusters around Kronospan Holding Limited, which exemplifies the continuous press investment archetype across German and Polish manufacturing footprints. Georgia-Pacific LLC represents the multi-regional commodity scale model with distribution density across particle board segments.
| Leading Market Players |
|---|
| West Fraser Timber Co. Ltd. |
| Sonae Arauco SGPS, S.A. |
| Kronospan Holding Limited |
| Kastamonu Entegre Ağaç Sanayi ve Ticaret A.Ş. |
| Celulosa Arauco y Constitución S.A. |
| Georgia-Pacific LLC |
| EGGER Holzwerkstoffe GmbH |
| Duratex S.A. |
| Weyerhaeuser Company |
| Others |
Cost & Logistics Intelligence
EPA Title VI certification gates both mill qualification and price differentiation simultaneously, separating E0-grade premium panels from commodity particle board in procurement contracts across North American furniture and construction channels.
Pricing Analysis
EPA Title VI dictates the pricing tier structure across the United States market, creating three-tier pricing stratification across E0-certified premium, E1-compliant standard, and non-certified economy grades. Price differentiation rests on certification level and volume scale, with German kitchen manufacturers paying substantial premiums for chain-of-custody documentation. Cost compression in the economy tier is intensifying because resin feedstock prices track volatile natural gas benchmarks. Custom furniture workshops represent the most price-sensitive buyers, while large residential developers consolidating direct mill contracts show least sensitivity.
Supply Chain Analysis
Inventory cycles for softwood fiber extend eighteen to twenty-four months from plantation thinning to mill delivery, compressing responsiveness to demand spikes in structural panel markets. Supply concentrates in the United States, Germany, and China, with southern yellow pine plantations around Augusta and Alexandria feeding North American OSB capacity. Raw material dependencies center on methanol, urea, and formaldehyde resin formulations. Single-source vulnerability sits with institutional timberland REITs controlling fiber access across the southern United States. Distribution runs through direct mill contracts for certified grades and regional distribution networks for commodity particle board.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood-based panel market is accelerating through a regulatory inflection as bio-based binder technologies approach commercial viability, promising to displace urea-formaldehyde formulations and restructure competitive economics across all producing regions.
For Market Incumbents: Secure captive fiber supply through plantation lease extensions or acquisition in the southern United States, where institutional timberland ownership concentrates. Accelerate E0-grade certification investments to defend margin position against Baltic commodity exporters facing EU Timber Regulation exclusion. Prioritize continuous press technology licensing partnerships in Asia to capture distributed production growth without direct capital deployment. For New Entrants and Emerging Players: Cut-to-size blank aggregation platforms for CNC-equipped job shops represent an underserved service layer where incumbents under-serve with standard bulk distribution. Target Poland and Czech Republic furniture clusters with digital fabrication integration, offering parametric design-to-delivery services. Penetrate through online procurement platforms that bypass traditional distribution layers and capture specification data for direct mill relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact continuous press retrofits, enabling mid-scale distributed production economics previously frozen out by 150-million-euro line investments. Long-term viability over the next decade favors technology licensors and certified-grade specialists over pure commodity volume players. Watch lignin adhesive commercialization timelines as the critical signal for resin chemistry disruption and incumbent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Fiber Supply | Captive softwood access locks in OSB mill economics against REIT pricing power. |
| E0-Grade Certification Investment | German kitchen manufacturer qualification requirements filter out non-compliant Baltic competitors. |
| Compact Continuous Press Licensing | European equipment suppliers enable Asian distributed production closer to urban furniture clusters. |
| Bio-Based Binder R&D Partnership | Lignin adhesive commercialization promises emission-free alternatives to formaldehyde resins. |
| Direct Mill Contract Consolidation | Large residential developers bypass distribution layers to secure certified panel supply chains. |
Research Approach
Operator-level perspectives from mill operations directors, resin formulation chemists, furniture procurement managers, and timberland investment officers anchored the qualitative base for this analysis. Primary interviews across these stakeholder roles combined with secondary validation from EPA compliance filings, EU Ecodesign Directive implementation reports, FSC chain-of-custody databases, and customs trade flow records. Bottom-up capacity assessments and top-down demand modeling triangulated volume and value estimates across the projection horizon.
Sensitivity analysis tested forecast robustness against resin feedstock price volatility, regulatory enforcement intensity variations, and bio-based binder adoption curve assumptions. Segmentation modeling captured product type, end-user concentration, thickness band, and application-specific demand patterns. CAGRs derived from installed base expansion rates, replacement demand cycles, and penetration assumptions for emerging applications such as mass timber construction. Forecast inputs incorporated continuous press deployment schedules and plantation fiber supply maturity profiles.
Forecasts assume regulatory continuity in EPA Title VI enforcement and EU Timber Regulation implementation; material policy shifts would require re-modeling. Outputs reflect assumptions about certification adoption rates, bio-based technology maturation timelines, and construction code evolution for engineered wood products. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Fluff Pulp Market
Paper Products
Pharma Grade Paper Market
Paper Products
North America Coated Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Paper Pigment Market
Paper Products
Paper Products Market
Paper Products
Metallized Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Paperboard Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Printing and Writing Papers Market
Paper Products
Solid Bleached Board Market
Paper Products
Digital Printing Paper Market
Paper Products
Paper Goods Market
Paper Products
BPA Free Thermal Paper Market