
 Europe Neuromorphic Chip Market | 2026-2036
Europe Neuromorphic Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Neuromorphic Chip Market Foresight
Advanced mixed-signal integration is rotating the Europe neuromorphic chip market toward higher-specification tiers. Innatera Nanosystems B.V. leverages its Delft spin-out pedigree to dominate ultra-low-power sensory processing for edge devices. GrAI Matter Labs anchors European production of brain-inspired accelerators with time-domain processing architectures. Intel Corporation competes through its Loihi research platform, sustaining deep ties to continental university labs.
Neuromorphic chips emulate biological neural networks through spiking architectures, typically operating at sub-milliwatt power budgets with event-driven computation rather than clocked matrix operations. Their primary purpose is enabling real-time inference in battery-constrained or thermally limited environments where conventional von Neumann architectures prove inefficient. Processors and accelerators together capture the dominant value share, with accelerators representing the fastest-expanding category as automotive and robotics OEMs demand dedicated inference engines. Mixed-signal technology leads in deployed European designs, while hybrid architectures are gaining traction for applications requiring both precise analog sensing and robust digital programmability.
EMA guidelines on AI-enabled medical devices and the EU AI Act's risk-based classification system shape product validation pathways for healthcare-bound neuromorphic silicon. CE marking requirements under the MDR and emerging cybersecurity standards for connected edge devices further constrain market access, favoring vendors with established European regulatory capabilities. Stakeholders must monitor how the European Chips Act's designated pilot lines allocate fabrication capacity between digital and analog process nodes, as this will determine which neuromorphic architectures achieve commercially viable European manufacturing scale.
Market Dynamics
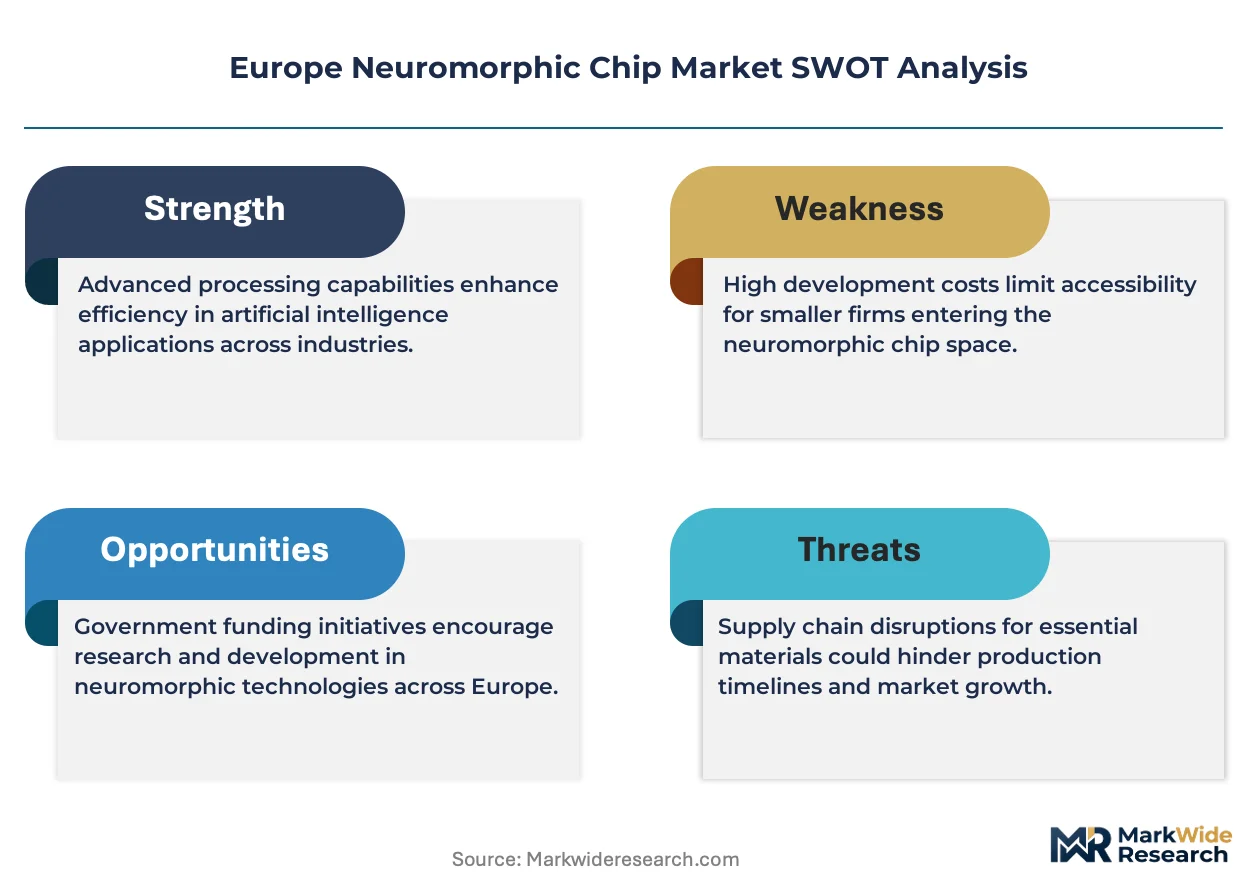
The European Chips Act's pilot line allocation decisions are compressing commercialization timelines for neuromorphic architectures, forcing vendors to secure analog-capable foundry partnerships before digital-node subsidies dominate capacity planning.
Growth Catalysts
- EU AI Act risk classification:Medical device manufacturers accelerate neuromorphic validation for Class IIa/IIb edge diagnostics to preempt MDR-IVDR convergence requirements.
- Automotive edge-computing:German and French OEMs mandate sub-10mW inference for cabin-monitoring and predictive maintenance sensors.
- Spiking neural network maturity:Event-driven computation frameworks from TU Delft and TU Dresden reduce training overhead for time-series workloads.
Market Restraints
- Analog process node scarcity:European foundry capacity at 22nm and above concentrates in legacy CMOS, constraining mixed-signal neuromorphic tape-outs.
- CE marking timeline friction:MDR notified body backlogs extend hardware-software co-validation for implantable neuromorphic interfaces to 18-24 months.
- Conventional MCU substitution:ARM Cortex-M55 with Helium vector extensions satisfies sub-dollar price points for simple sensory fusion tasks.
Strategic Opportunities
- Netherlands sensory-processing clusters:Eindhoven-Delft-Twente corridor offers packaged pilot-line access through High Tech Campus partnerships.
- CSRD supply-chain disclosure:Sustainability reporting mandates favor neuromorphic vendors with EU-based fabrication and sub-milliwatt carbon footprints.
- Photonic-neuromorphic convergence:IMEC's silicon photonics platform enables optical spike encoding for LIDAR and spectroscopy edge devices.
Industry Challenges
- Spiking network toolchain gaps:Sparse coding expertise concentrates in academic labs, limiting industrial-scale deployment teams.
- Hardware-software co-certification:EMA guidelines on adaptive AI require continuous validation protocols that stretch quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Neuromorphic Chip Market |
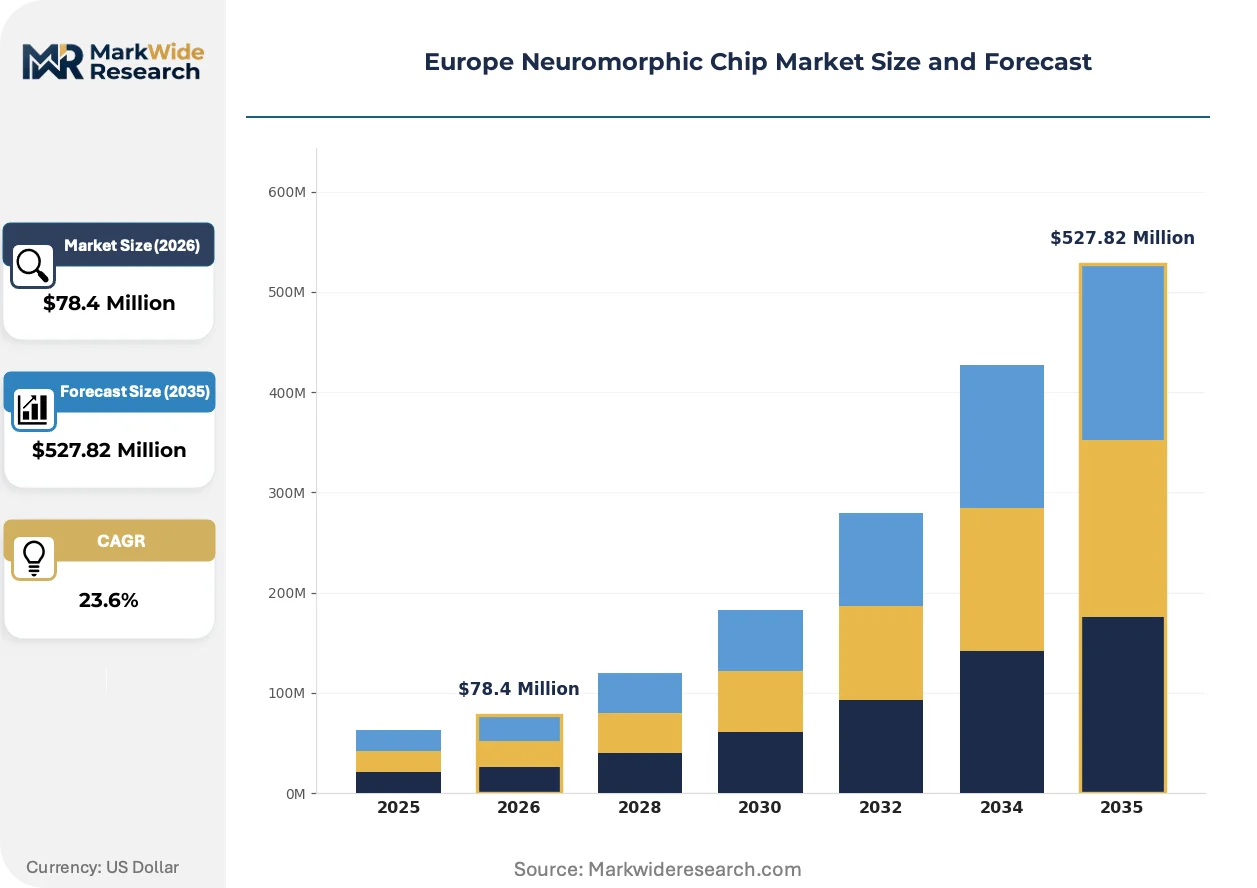
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $527.82 Million |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Accelerators, Controllers, Memory Units Technology: Analog, Digital, Mixed-Signal, Hybrid End User: Automotive, Healthcare, Robotics, Telecommunications Application: Image Processing, Natural Language Processing, Pattern Recognition, Signal Processing |
| Companies Covered | Innatera Nanosystems B.V., GrAI Matter Labs, SynSense AG, Prophesee, BrainChip Holdings Ltd., Intel Corporation, IBM Corporation, Qualcomm Technologies, Inc., General Vision, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Neuromorphic Chip Market Shifts & Advancements
Time-domain analog computing is displacing synchronous digital architectures across European edge-AI deployments, compressing power-performance envelopes while complicating standardization efforts.
Memristive crossbar arrays are displacing SRAM-based synaptic storage in training-inference hybrid chips. Fraunhofer IPMS and CEA-Leti prototype 130nm integrated ferroelectric devices for automotive temperature ranges. Bosch and Continental evaluate these for thermally constrained engine-bay placements where flash retention fails.
The EU AI Act's conformity assessment procedures are forcing neuromorphic medical device developers toward notified-body pre-submission pathways. EMA guidance on adaptive learning systems requires locked algorithmic boundaries or continuous monitoring infrastructure. French and German startups prioritize MDR Class IIa certification over broader functional scope to accelerate time-to-revenue.
Automotive tier-one procurement teams now mandate open-source spiking network compilers as a condition of RFQ participation. Continental and Valeo exclude vendors with proprietary toolchain lock-in from long-term supply agreements. This behavioral shift concentrates software investment in SynSense and open-source initiatives like sPyNNaker rather than vertically integrated stacks.
Europe Neuromorphic Chip Market Segmentation
Neuromorphic chip segmentation reveals divergent margin structures across the European supply base. Product type and technology choices determine foundry access and regulatory burden, while end-user concentration in German automotive clusters shapes volume allocation.
Product Type:
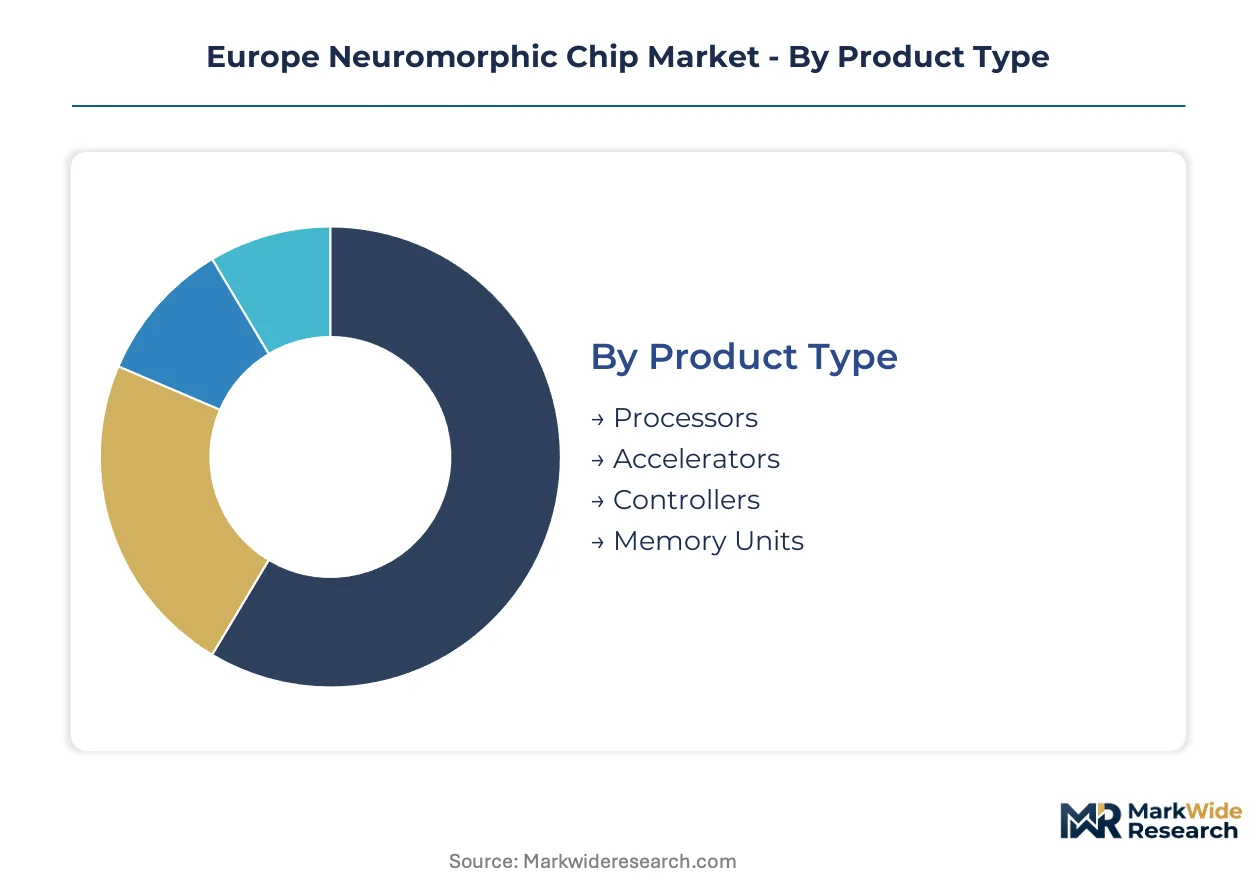
Margin pools concentrate in accelerators and processors, where automotive OEMs pay premiums for sub-10mW inference engines.
- Processors:Full-system-on-chip designs integrate spiking neural network cores with sensor interfaces for closed-loop edge autonomy. German Tier-1 suppliers source these for cabin-monitoring systems requiring CE-marked medical-grade reliability under MDR.
- Accelerators:Dedicated inference engines offload pattern recognition from host MCUs in battery-constrained robotics. French automotive suppliers dominate procurement, driven by EU AI Act risk-classification deadlines for Class IIa edge diagnostics.
- Controllers:Event-driven motor control for precision robotics.
- Memory Units:Ferroelectric and memristive synaptic storage arrays.
The dominant share belongs to processors, while accelerators are closing the gap fastest.
Technology:
Cost tiers separate legacy digital implementations from premium mixed-signal designs requiring analog-capable European foundry access.
- Mixed-Signal:Combines precise analog sensing front-ends with digital programmability for adaptive threshold calibration. Netherlands-based High Tech Campus partnerships provide packaged pilot-line access, concentrating Dutch design activity.
- Analog:Pure time-domain computation achieves sub-milliwatt event-driven processing without ADC overhead. Supply concentrates in TU Delft spin-outs serving ultra-low-power sensory edge devices.
- Digital:Synchronous CMOS implementations sacrificing efficiency for toolchain maturity.
- Hybrid:Photonic-electronic convergence for LIDAR signal conditioning.
Mixed-signal architectures command the installed base, with analog designs expanding most quickly in medical implant applications.
End User:
Application maturity varies sharply, with automotive procurement cycles running 36-48 months versus 18-24 months for healthcare validation.
- Automotive:Edge inference for predictive maintenance and occupant monitoring. German OEMs mandate open-source spiking network compilers, excluding vendors with proprietary toolchain lock-in from Continental and Valeo supply agreements.
- Healthcare:Implantable and wearable diagnostic devices requiring MDR Class IIa/IIb certification. EMA guidelines on adaptive AI force locked algorithmic boundaries or continuous monitoring infrastructure, stretching quality assurance budgets.
- Robotics:Battery-constrained mobile manipulation platforms.
- Telecommunications:Baseband signal processing for spectral efficiency.
Automotive claims the dominant share, though healthcare is gaining share fastest on regulatory preemption strategies.
Application:
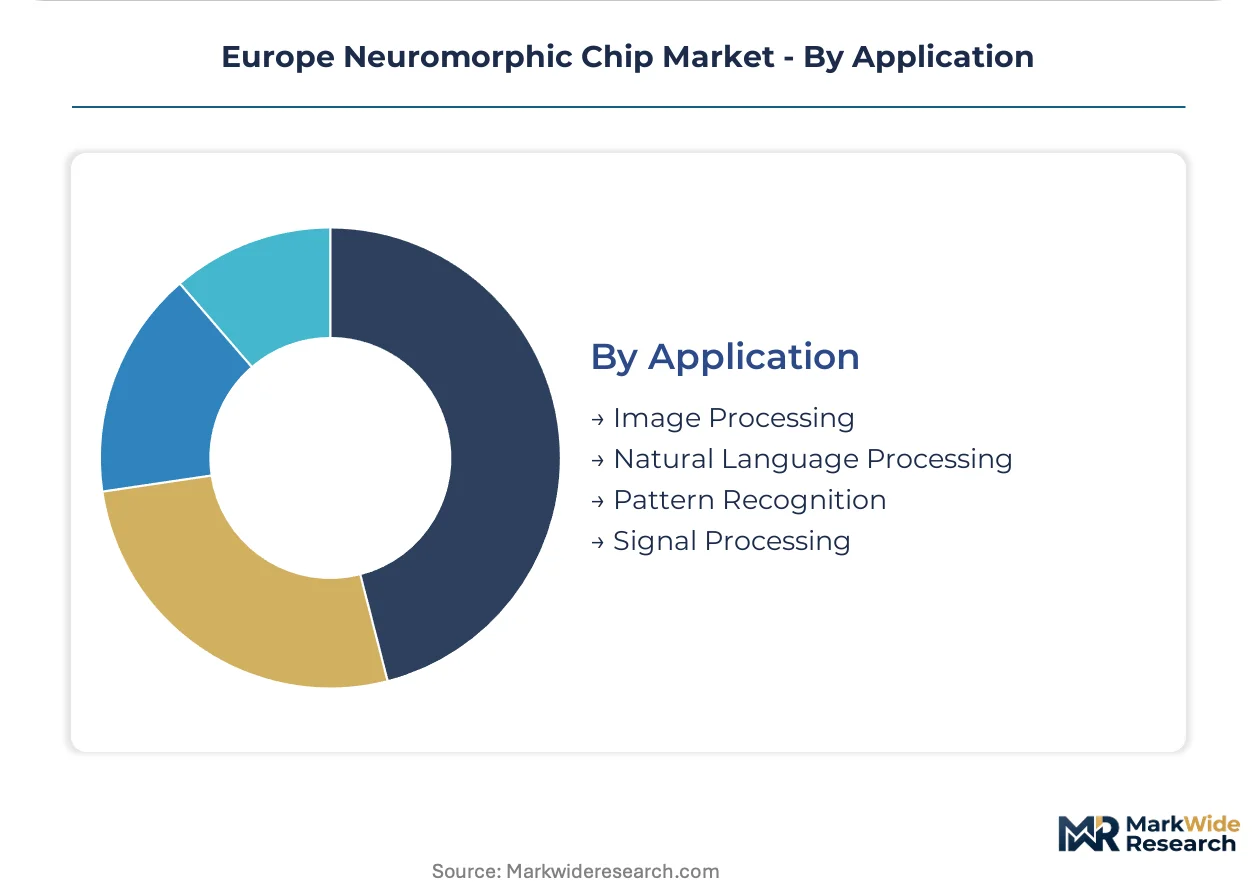
Customer type splits between high-volume image processing contracts and specialized natural language processing for industrial human-machine interfaces.
- Image Processing:Event-based vision for automotive ADAS and robotics navigation. IMEC's silicon photonics platform enables optical spike encoding, accelerating Dutch and Belgian design activity for LIDAR edge devices.
- Pattern Recognition:Time-series anomaly detection for predictive maintenance.
- Signal Processing:Spectral analysis for telecommunications and spectroscopy.
- Natural Language Processing:Sparse coding for voice command interfaces in industrial settings.
Image processing holds the dominant share, while pattern recognition shows the steepest expansion trajectory on automotive predictive maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European neuromorphic chip fabrication capacity concentrates in analog-capable foundries across the Netherlands, Germany, and France, where TU Delft spin-outs and Fraunhofer institutes anchor design-to-silicon pipelines. National procurement strategies under the European Chips Act are diverting pilot-line subsidies toward mixed-signal process nodes, compressing commercialization timelines for event-driven architectures.
Germany
Automotive OEM procurement drives demand for sub-10mW inference engines in cabin-monitoring and predictive maintenance sensors. KBA safety standards and EU AI Act risk classifications mandate MDR-aligned validation pathways for edge-diagnostic deployments. Munich-Stuttgart corridor hosts Continental and Valeo engineering centers that exclude vendors with proprietary spiking network toolchains from long-term supply agreements.
Netherlands
Eindhoven-Delft-Twente corridor offers packaged pilot-line access through High Tech Campus partnerships, concentrating ultra-low-power sensory processing design activity. CSRD supply-chain disclosure requirements favor vendors with EU-based fabrication and sub-milliwatt carbon footprints. IMEC's Leuven-adjacent silicon photonics platform enables optical spike encoding for LIDAR edge devices, accelerating Dutch and Belgian collaborative development.
France
ANSM and CNIL oversight shapes adaptive AI medical device validation, forcing locked algorithmic boundaries or continuous monitoring infrastructure for implantable interfaces. Paris-Saclay and Grenoble clusters host CEA-Leti prototyping of 130nm ferroelectric memristive devices for automotive temperature ranges. Startups prioritize MDR Class IIa certification over broader functional scope to accelerate time-to-revenue under EMA guideline pressure.
United Kingdom
Spiking neural network toolchain development concentrates in Cambridge and Bristol robotics clusters serving battery-constrained mobile manipulation platforms. MHRA convergence with MDR-IVDR frameworks extends hardware-software co-validation timelines for adaptive AI medical devices. sPyNNaker open-source initiatives attract automotive tier-one procurement teams mandating compiler transparency as an RFQ condition.
Switzerland
Swissmedic certification requirements for implantable neuromorphic interfaces favor vendors with established European regulatory capabilities and locked algorithmic architectures. Zurich-EPFL corridor specializes in precision robotics and wearable diagnostic applications requiring sub-milliwatt event-driven computation. Federal procurement guidelines prioritize CE-marked components with demonstrable MDR compliance for healthcare-bound silicon.
Europe Neuromorphic Chip Market Competitive Landscape
Concentration sits with university spin-outs and research-platform incumbents rather than scaled semiconductor majors, creating a bifurcated structure where Delft-derived startups compete against Intel's Loihi ecosystem for design wins. Three archetypes dominate: ultra-low-power sensory specialists leveraging mixed-signal analog expertise; time-domain accelerator vendors serving automotive inference workloads; and research-platform providers sustaining continental university lab partnerships. Competitive moves center on open-source toolchain development to satisfy Continental and Valeo procurement mandates, and analog-capable foundry partnership formation ahead of European Chips Act pilot-line allocation decisions.
Within the university-spin-out tier, Innatera Nanosystems B.V. and GrAI Matter Labs exemplify the Delft-to-commercial pipeline for event-driven sensory processing. Among research-platform anchors, Intel Corporation occupies a position sustaining deep ties to continental university labs through its Loihi ecosystem. SynSense AG represents the accelerator-specialist archetype serving automotive and robotics OEMs with dedicated inference engines. These named entities illustrate how geographic proximity to TU Delft, Fraunhofer IPMS, and CEA-Leti institutes shapes competitive positioning without constituting exhaustive market coverage.
| Leading Market Players |
|---|
| Innatera Nanosystems B.V. |
| GrAI Matter Labs |
| SynSense AG |
| Prophesee |
| BrainChip Holdings Ltd. |
| Intel Corporation |
| IBM Corporation |
| Qualcomm Technologies, Inc. |
| General Vision, Inc. |
| Others |
Supply & Pricing Matrix
Twenty-two-month lead times for analog-capable foundry slots at 22nm and above compress negotiation leverage for mixed-signal neuromorphic vendors, concentrating pricing power with European pilot-line operators under the European Chips Act and forcing fabless designers toward premium contract structures.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across medical-grade and automotive-grade neuromorphic silicon, separating MDR Class IIa-certified devices from uncertified commercial variants. Three-tier pricing stratifies across premium certified, standard industrial, and economy evaluation units, with CE marking and open-source toolchain compliance as the primary differentiation drivers. Cost compression in economy tiers intensifies because ARM Cortex-M55 with Helium extensions satisfies sub-dollar sensory fusion, though automotive OEMs remain least price-sensitive due to mandate-driven procurement for sub-10mW inference engines.
Supply Chain Analysis
The Netherlands and Germany anchor mixed-signal design-to-silicon pipelines, with Belgium feeding photonic-neuromorphic convergence through IMEC's platform. Wafer fabrication draws from legacy CMOS capacity at 22nm and above, with ferroelectric memristive arrays sourced from CEA-Leti prototyping lines. Single-source vulnerability concentrates in analog-capable European foundry access, where pilot-line allocation decisions under the European Chips Act determine which architectures achieve commercial scale. Distribution runs through Tier 1 automotive suppliers and medical device OEMs with established notified-body relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuromorphic silicon incumbents face substitution pressure from conventional MCU vendors embedding vector extensions, requiring defensive positioning around analog-capable foundry access and regulatory certification moats.
For Market Incumbents: Shield market position by securing European Chips Act pilot-line allocations before digital-node subsidies dominate capacity planning, and deepen MDR Class IIa certification investments to exclude ARM-based substitutes from medical edge-diagnostic procurement. Open-source spiking network compiler development serves as the critical lever to maintain Continental and Valeo supply agreement eligibility. For New Entrants and Emerging Players: Toolchain-as-a-service gaps in sparse coding deployment represent the most penetrable entry vector, as industrial-scale spiking network expertise concentrates in TU Delft and TU Dresden academic labs. Target Netherlands-based sensory processing clusters through High Tech Campus partnership structures, with CSRD-aligned carbon footprint disclosure as the differentiated go-to-market anchor for sustainability-mandated procurement teams. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU AI Act and MDR-IVDR convergence timelines compress validation moats around early-certified architectures. Acquisition targets should display analog-capable foundry partnerships and locked-algorithmic medical device pipelines. The signal to watch is European Chips Act pilot-line allocation announcements for mixed-signal process nodes.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Source Toolchain Development | Continental and Valeo procurement mandates now exclude vendors with proprietary compiler lock-in from RFQ participation. |
| MDR Class IIa Certification Pathway | EMA guidelines on adaptive AI force locked algorithmic boundaries, stretching quality assurance budgets but accelerating time-to-revenue. |
| Analog-Capable Foundry Partnership | European Chips Act pilot-line allocation decisions determine which neuromorphic architectures achieve commercially viable manufacturing scale. |
| Photonic-Neuromorphic Convergence | IMEC's silicon photonics platform enables optical spike encoding for LIDAR edge devices, accelerating Dutch and Belgian collaborative development. |
| CSRD Supply-Chain Disclosure Alignment | Sustainability reporting mandates favor vendors with EU-based fabrication and sub-milliwatt carbon footprints in procurement evaluations. |
Research Methodology
The analysis maps mixed-signal processors, analog time-domain accelerators, and photonic-neuromorphic hybrids, each validated through semiconductor design leads at TU Delft spin-outs, automotive Tier 1 procurement officers, and regulatory affairs specialists navigating EMA and notified-body pathways. Primary interviews with Fraunhofer IPMS and CEA-Leti research directors combined with secondary validation against SEC filings from Intel and Qualcomm, European Chips Act policy documents, and MDR notified-body backlog disclosures. Bottom-up shipment estimates and top-down European semiconductor consumption patterns were triangulated to anchor volume assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by product type, technology architecture, end-user industry, and regional regulatory cluster. CAGRs were derived from analog foundry capacity expansion schedules and automotive OEM platform rollout timelines, with EU AI Act risk-classification deadlines and MDR-IVDR convergence frameworks serving as key forecast inputs.
Forecasts assume regulatory continuity in EU AI Act implementation and MDR notified-body capacity; material policy shifts or extended CE marking backlogs would require re-modeling. Technology risk factors include memristive device yield maturation and spiking network toolchain standardization. Recalibration cycles align with material shifts in European Chips Act pilot-line allocations and EMA adaptive AI guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Thailand Data Center Processor Market