
 Global Biosimulation Market | 2026-2036
Global Biosimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biosimulation Market Foresight
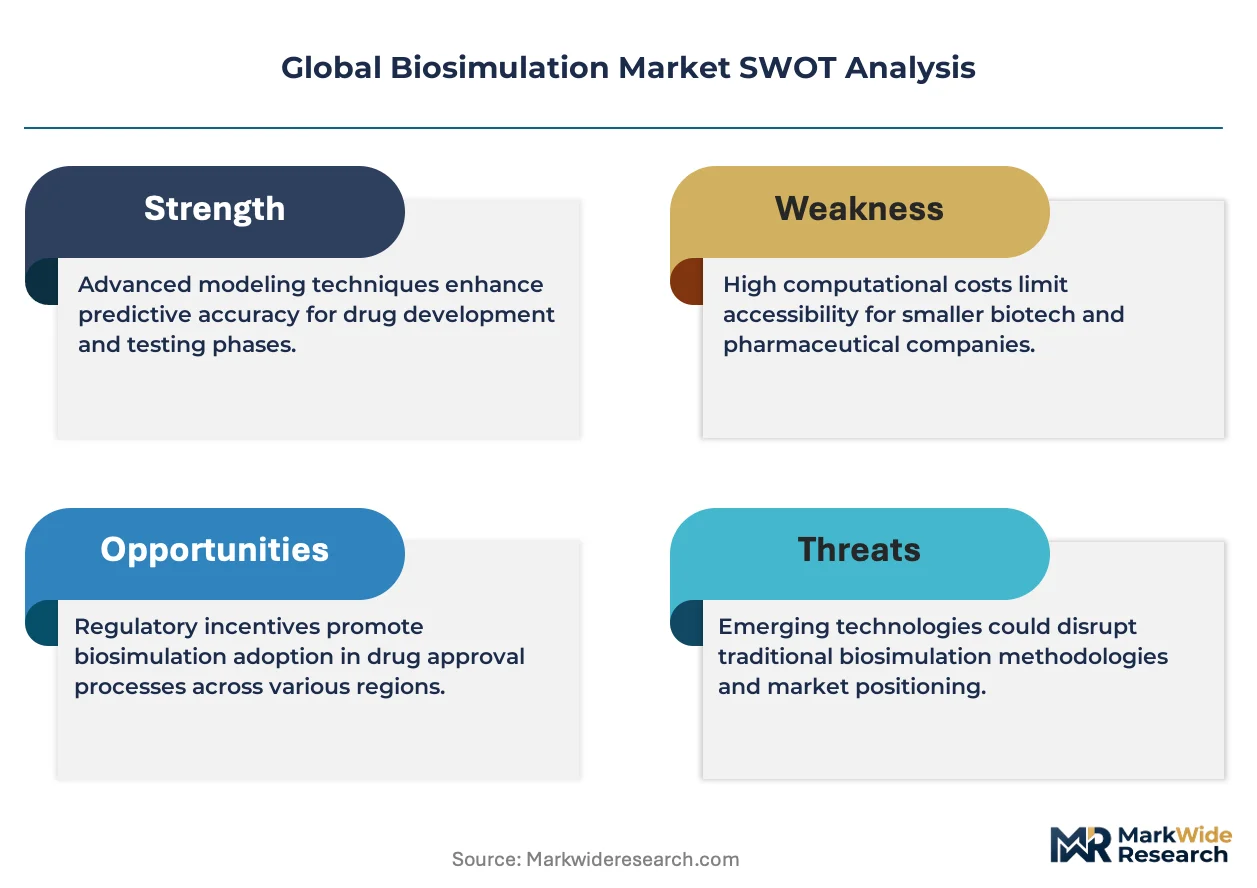
The gap between premium mechanistic modeling suites and commodity statistical tools is hardening. Certara dominates regulatory-grade pharmacokinetic platforms with deep FDA submission track records. Schrödinger anchors physics-based molecular simulation for discovery-stage clients. Dassault Systèmes extends its BIOVIA footprint through enterprise deployment scale.
Biosimulation employs computational models to replicate biological system behavior, integrating differential equations, agent-based methods, and Monte Carlo simulations to predict drug absorption, distribution, metabolism, excretion, and toxicity outcomes. Pharmacokinetic models command the largest revenue share due to mandatory regulatory submission requirements, while physiological models represent the fastest-expanding category as organ-on-chip data feeds higher-fidelity multi-scale simulations. Cloud-based deployment gains traction among mid-tier biotechnology firms seeking elastic compute access without capital-intensive infrastructure.
FDA's model-informed drug development framework and EMA's qualification opinion pathway shape validation standards and commercial access for platform vendors. ISO 9001 and 21 CFR Part 11 compliance requirements filter out smaller software providers from regulated pharmaceutical procurement cycles. Stakeholders must monitor evolving qualification pathways for novel AI-augmented simulation methodologies.
Market Dynamics
Pharmaceutical sponsors now embed computational modeling into Phase I protocols to compress clinical timelines and preempt costly late-stage failures, tightening vendor qualification standards across the supply base.
Growth Catalysts
- Model-Informed Drug Development:FDA's MIDD framework mandates quantitative justification for dosing decisions, forcing sponsors to procure validated simulation platforms for every New Drug Application.
- Physiological Modeling:Organ-on-chip data streams from Emulate and Mimetas enable higher-fidelity multi-scale simulations that predict toxicity before animal studies commence.
- Cloud Elasticity:Mid-tier biotechnology firms in Boston and Basel access GPU clusters on-demand, eliminating capital-intensive server procurement cycles.
Market Restraints
- Validation Burden:ISO 9001 and 21 CFR Part 11 compliance requirements filter smaller software providers from regulated pharmaceutical procurement cycles.
- Skill Concentration:Qualified pharmacometricians cluster in Cambridge, Massachusetts and Basel, creating talent scarcity for distributed deployment.
- Legacy Integration Friction:Enterprise LIMS and CTMS systems require custom API bridges to accept simulation outputs, extending implementation timelines.
Strategic Opportunities
- AI-Augmented Methodologies:Machine learning surrogate models trained on physics-based simulations accelerate parameter exploration beyond traditional Monte Carlo limits.
- Japanese Regulatory Streamlining:PMDA's Sakigake designation pathway rewards sponsors employing advanced modeling, creating preferential market access for qualified vendors.
- Cell Therapy Modeling:CAR-T pharmacokinetics require novel physiologically-based models that incumbent platforms do not adequately address.
Industry Challenges
- Cross-Functional Talent Scarcity:Professionals combining systems biology expertise with software engineering credentials command premium compensation, constraining platform development teams.
- Qualification Timeline Compression:EMA's qualification opinion pathway requires 18-24 month validation studies that delay revenue recognition for novel methodologies.
- Interoperability Standards:Proprietary data formats between Certara, Schrödinger, and Dassault Systèmes platforms force sponsors into redundant model reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biosimulation Market |
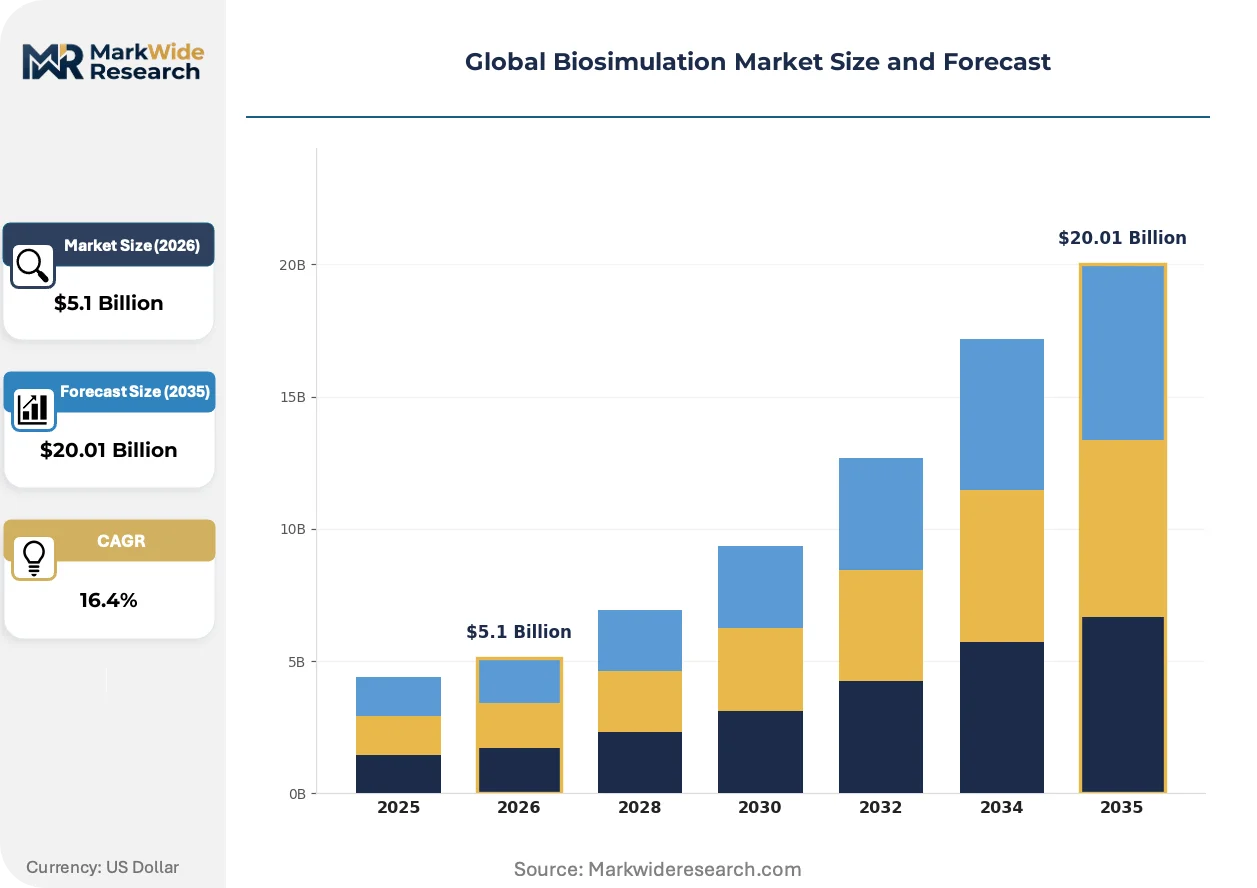
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $20.01 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacokinetic Models, Physiological Models, Mechanistic Models, Statistical Models Application: Drug Development, Disease Modeling, Toxicology Testing, Personalized Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Academic Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service |
| Companies Covered | Simulations Plus, Genedata, Certara, Advanced Chemistry Development, Physiomics, Dassault Systèmes, Rosa & Co. LLC, Chemical Computing Group, Schrödinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biosimulation Market Shifts & Advancements
Computational biology platforms are absorbing artificial intelligence capabilities while regulators construct qualification frameworks for non-traditional evidence generation.
Physics-based molecular simulation is converging with generative AI architectures to enable de novo protein design. Biopharma discovery teams in South San Francisco and Cambridge deploy these hybrid workflows to compress hit-to-lead timelines from months to weeks. The structural consequence is a bifurcation between premium mechanistic suites and commodity statistical tools.
EMA's qualification opinion pathway for novel methodologies now accepts biosimulation as primary evidence for certain bioequivalence decisions. This regulatory evolution permits generic sponsors to substitute virtual trials for clinical studies in specific therapeutic categories. Oral solid dosage forms with linear pharmacokinetics represent the initial segment benefiting from this shift.
Biotechnology procurement teams increasingly unbundle software licensing from professional services, demanding API-first platforms that integrate with existing data science stacks. This pattern disrupts traditional enterprise sales models predicated on multi-year bundled contracts. The behavior is most pronounced among Series B and C funded firms in Boston and San Francisco seeking operational flexibility.
Global Biosimulation Market Segmentation
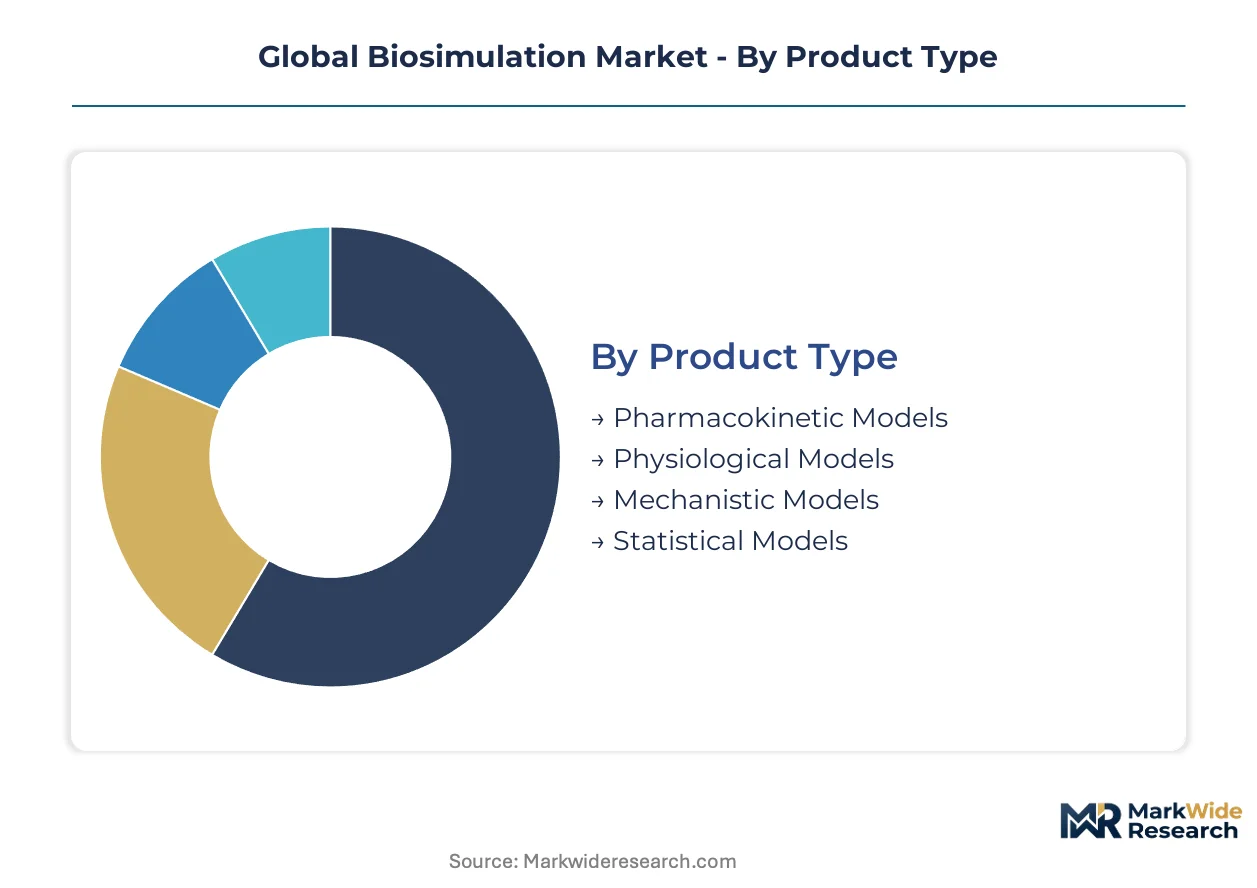
Biosimulation vendors structure product portfolios around regulatory submission pathways, with certification requirements determining pricing tiers and customer eligibility. Segmentation reveals how FDA and EMA validation standards fragment the addressable market across deployment modes and end-user sophistication levels.
Product Type:
Pharmacokinetic models carry mandatory FDA submission requirements under the MIDD framework, while physiological and mechanistic variants face evolving qualification timelines at EMA.
- Pharmacokinetic Models:Differential equation systems predicting drug absorption, distribution, metabolism, and excretion profiles. Pharmaceutical sponsors in Boston and Basel embed these into Phase I protocols to justify dosing decisions for New Drug Applications.
- Physiological Models:Multi-scale simulations integrating organ-level dynamics with systemic circulation. Organ-on-chip data from Emulate and Mimetas feeds higher-fidelity toxicity predictions before animal studies commence, driving fastest category expansion.
- Mechanistic Models:Pathway-specific reconstructions of molecular interactions governing therapeutic response.
- Statistical Models:Population pharmacometric approaches for variability quantification in clinical trial design.
Leading the category by volume: Pharmacokinetic Models. Growing fastest: Physiological Models.
Application:
Drug development commands premium pricing due to mandatory regulatory validation, while disease modeling and toxicology testing operate under lighter compliance burdens.
- Drug Development:End-to-end computational support from target validation through Phase III design. Sponsors in South San Francisco deploy physics-based molecular simulation to compress hit-to-lead timelines.
- Personalized Medicine:Patient-specific pharmacokinetic predictions enabling precision dosing. Academic medical centers in Cambridge, Massachusetts integrate genomic covariates into physiologically-based models for oncology applications.
- Disease Modeling:Computational reconstruction of pathophysiology for target identification and mechanism validation.
- Toxicology Testing:In silico safety assessment substituting for animal studies in early-stage screening.
Dominant by revenue: Drug Development. Steepest expansion trajectory: Personalized Medicine.
End User:
Procurement authority concentrates in pharmaceutical companies with dedicated pharmacometrics departments, while biotechnology firms favor flexible cloud arrangements.
- Pharmaceutical Companies:Enterprise-scale deployments with ISO 9001 and 21 CFR Part 11 compliance requirements. Major sponsors maintain captive simulation groups in Basel, Boston, and New Jersey.
- Biotechnology Firms:Series B and C funded companies in San Francisco and Cambridge seeking API-first platforms. These customers unbundle software licensing from professional services, demanding integration with existing data science stacks.
- Research Institutes:Non-commercial applications with lighter validation requirements.
- Academic Institutions:Training and methodological research with educational pricing tiers.
Highest absolute spend: Pharmaceutical Companies. Fastest-growing customer base: Biotechnology Firms.
Deployment:
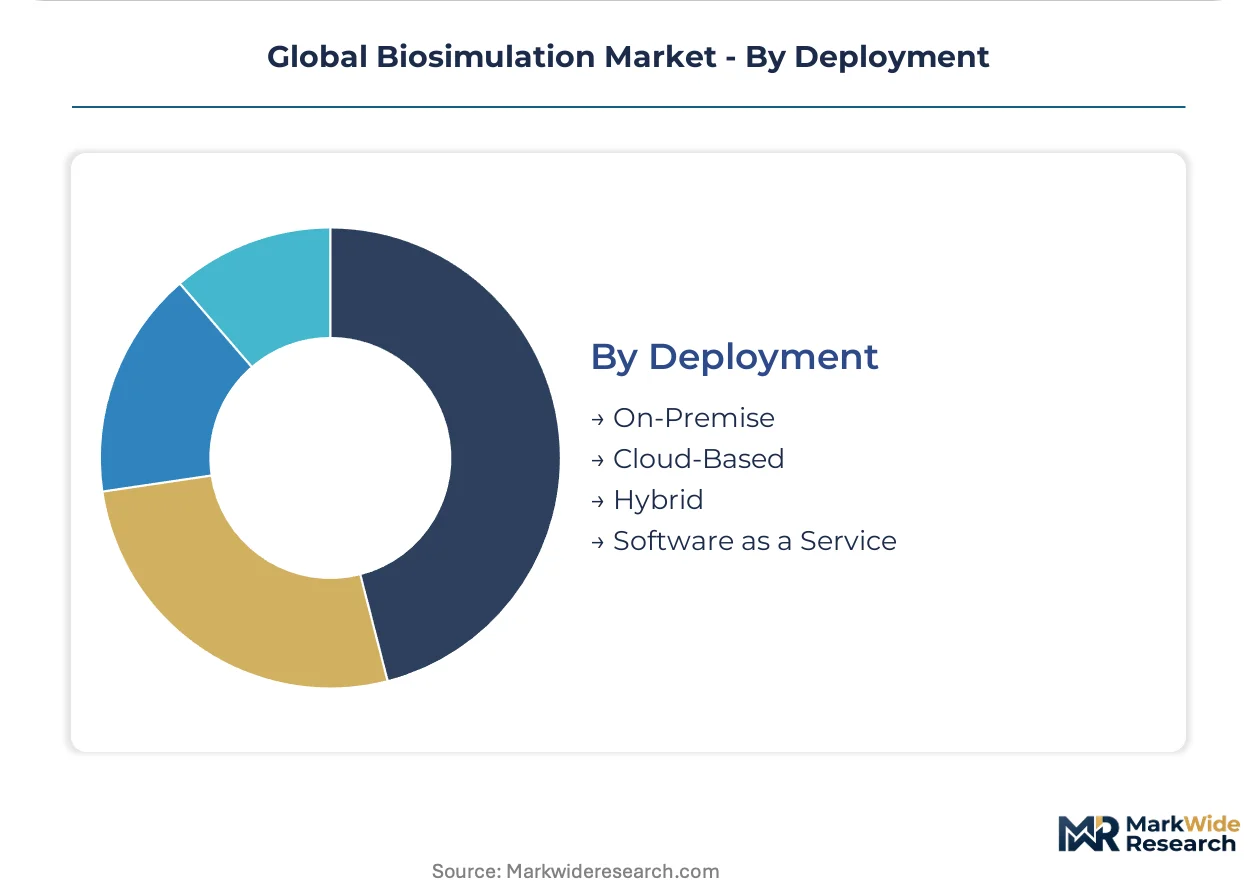
Cloud elasticity attracts mid-tier customers without capital-intensive infrastructure, while on-premise deployments satisfy stringent data sovereignty requirements.
- Cloud-Based:GPU cluster access on-demand eliminating server procurement cycles. Mid-tier biotechnology firms in Boston and Basel favor this model for parameter exploration beyond traditional Monte Carlo limits.
- Software as a Service:Subscription pricing with automatic updates and regulatory compliance maintenance. Japanese sponsors leveraging PMDA's Sakigake designation pathway prefer validated SaaS environments.
- On-Premise:Air-gapped installations for sponsors with heightened intellectual property protection requirements.
- Hybrid:Mixed architectures separating sensitive model development from scalable execution environments.
Widest current adoption: Cloud-Based. Gaining share fastest: Software as a Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors global biosimulation demand through dense concentrations of pharmaceutical sponsors and contract research organizations. The metropolitan area hosts specialized pharmacometrics talent pools that smaller markets cannot replicate. This geographic pattern repeats across three additional countries with distinct regulatory and industrial configurations.
United States
FDA's Model-Informed Drug Development framework mandates quantitative dosing justifications for every New Drug Application. South San Francisco and Cambridge biotechnology clusters deploy physics-based molecular simulation to compress hit-to-lead timelines from months to weeks. Cloud-based GPU access eliminates capital-intensive server procurement for Series B and C funded firms in these metros.
Switzerland
Basel concentrates pharmaceutical sponsors with dedicated pharmacometrics departments and captive simulation groups. Swissmedic maintains alignment with EMA qualification opinion pathways while offering streamlined local validation procedures. Roche and Novartis headquarters anchor enterprise-scale deployments with ISO 9001 and 21 CFR Part 11 compliance requirements.
Germany
Munich and Heidelberg biotechnology corridors drive physiological modeling adoption for organ-on-chip data integration. BfArM and PEI regulators coordinate with EMA on novel methodology qualification timelines. Fraunhofer Institutes supply academic partnerships that feed commercial platform development with systems biology expertise.
Japan
PMDA's Sakigake designation pathway rewards sponsors employing advanced modeling with preferential review timelines. Tokyo and Osaka pharmaceutical sponsors favor validated Software-as-a-Service environments for regulatory submission confidence. METI funding programs support domestic platform vendors competing against established Western providers.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined qualification opinions for biosimulation methodologies. Cambridge and London academic medical centers integrate genomic covariates into physiologically-based models for oncology applications. Cell and gene therapy startups in Stevenage cluster demand novel CAR-T pharmacokinetic models that incumbent platforms inadequately address.
Global Biosimulation Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light specialized consultancies for pharmaceutical procurement budgets. The vendor base concentrates around three tiers: regulatory-grade suite providers with deep FDA submission track records, physics-based molecular simulation specialists serving discovery-stage clients, and emerging cloud-native entrants unbundling software from professional services. Strategic moves center on API-first platform architectures and qualification pathway navigation for novel AI-augmented methodologies.
Within the regulatory-grade tier, Certara and Dassault Systèmes exemplify established providers with enterprise deployment scale. Schrödinger occupies a position among physics-based specialists anchoring discovery-stage workflows. Genedata represents the European contingent with bioinformatics platform integration capabilities. These archetypes illustrate how validation burden and compliance requirements filter market participation toward incumbents with documented regulatory submission histories.
| Leading Market Players |
|---|
| Simulations Plus |
| Genedata |
| Certara |
| Advanced Chemistry Development |
| Physiomics |
| Dassault Systèmes |
| Rosa & Co. LLC |
| Chemical Computing Group |
| Schrödinger |
| Others |
Supply & Pricing Matrix
The regulatory-grade platform commodity software split manifests in divergent pricing architectures and supply chain configurations across the biosimulation vendor base. Pharmaceutical sponsors in Basel and Boston pay subscription premiums for FDA-validated suites while mid-tier biotechnology firms access elastic cloud compute through API-first arrangements.
Pricing Analysis
Value-based pricing anchors on regulatory submission confidence rather than raw computational throughput. Three-tier pricing structure across premium regulatory-grade, standard enterprise, and economy cloud-access tiers separates Certara's submission-track record from Dassault Systèmes' deployment scale from emerging SaaS entrants. Price differentiation rests on ISO 9001 certification status and 21 CFR Part 11 compliance depth. Cost compression in the standard tier intensifies as biotechnology procurement teams unbundle software licensing from professional services. Series B and C funded firms in San Francisco exhibit highest price sensitivity; Basel-based pharmaceutical sponsors with captive pharmacometrics groups show lowest.
Supply Chain Analysis
Dual-sourcing requirements for regulatory validation force pharmaceutical sponsors to qualify multiple platform providers despite concentrated vendor landscapes. Software development concentrates in the United States, Switzerland, and Germany where pharmacometrician talent pools cluster. Raw material dependencies include GPU compute infrastructure from NVIDIA and cloud hosting services from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability runs through qualified pharmacometrician scarcity in Cambridge and Basel. Distribution runs through direct enterprise sales for regulatory-grade suites and self-serve API portals for cloud-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure mounts as ISO 9001 and 21 CFR Part 11 compliance requirements filter smaller software providers from regulated pharmaceutical procurement cycles.
For Market Incumbents: Lock in regulatory submission track records through accelerated EMA qualification opinion pathway navigation for AI-augmented methodologies. Deepen captive pharmacometrician talent pools in Basel and Boston to constrain competitor access. Cloud-native entrants with API-first architectures threaten traditional bundled contract models; vertical integration into organ-on-chip data partnerships with Emulate and Mimetas creates proprietary physiological model training advantages. For New Entrants and Emerging Players: Enter via cell therapy modeling white space where CAR-T pharmacokinetics demand novel physiologically-based models incumbent platforms inadequately address. Japanese sponsors leveraging PMDA's Sakigake designation pathway represent the most penetrable geography due to preferential review timeline rewards for advanced modeling adoption. Go-to-market through validated SaaS environments with automatic regulatory compliance maintenance rather than on-premise installation complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by pharmaceutical sponsors seeking captive simulation capabilities and platform consolidation plays by Dassault Systèmes or Certara extending regulatory-grade footprints. Long-term viability favors vendors with documented FDA submission histories and EMA qualification opinions already secured. Watch EMA's evolving stance on AI-augmented methodology qualification as the critical inflection signal; accelerated acceptance would shift competitive positioning toward machine learning-native entrants.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Opinion Pathway Navigation | Secures 18-24 month regulatory validation timelines for novel AI-augmented simulation methodologies. |
| API-First Platform Architecture Development | Enables biotechnology procurement teams to unbundle software licensing from professional services contracts. |
| Organ-on-Chip Data Partnership | Feeds higher-fidelity physiological models with Emulate and Mimetas toxicity prediction streams. |
| Cloud Elasticity Infrastructure Investment | Eliminates capital-intensive server procurement cycles for Series B and C funded Boston firms. |
| Pharmacometrician Talent Captive Acquisition | Concentrates scarce Cambridge and Basel systems biology expertise within platform development teams. |
Research Methodology
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads, pharmacometricians, and biotechnology procurement officers underwrites the qualitative findings. Secondary validation draws from FDA MIDD framework guidance documents, EMA qualification opinion pathway records, ClinicalTrials.gov protocol registrations, and ISO 9001 certification databases. Bottom-up segmentation modeling triangulates against top-down market sizing approaches.
Rate-of-change decomposition separates volume expansion from value capture across pharmacokinetic, physiological, mechanistic, and statistical model categories. Segmentation dimensions include product type, application across drug development and personalized medicine, end-user sophistication from pharmaceutical companies to biotechnology firms, and deployment mode from cloud-based to on-premise. CAGRs derive from regression analysis against regulatory submission volume trends and pharmaceutical R&D expenditure patterns. Forecast inputs incorporate PMDA Sakigake designation pathway adoption rates and organ-on-chip data integration velocity.
Revisions become necessary when EMA accelerates or delays AI-augmented methodology qualification timelines, when FDA expands MIDD framework mandatory requirements, or when pharmacometrician talent scarcity intensifies beyond current Cambridge and Basel concentrations. Deviation in regulatory acceptance of virtual trials for bioequivalence decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Fluoro Enzymatic Assays Market