
 America Airport Passenger Screening Systems Market | 2026-2036
America Airport Passenger Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
America Airport Passenger Screening Systems Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over software updates and spare parts distribution. Smiths Detection leverages its installed base of explosives detection systems to sustain recurring maintenance contracts across major US hubs. L3Harris Technologies anchors its position through deep integration with TSA procurement channels, while Rapiscan Systems competes aggressively on price for international airport contracts in Mexico and Brazil.
America airport passenger screening systems encompass millimeter wave scanners, X-ray machines, explosives detection systems, and biometric screening solutions designed to detect contraband, weapons, and unauthorized items on passengers using electromagnetic radiation, computed tomography, or facial recognition algorithms operating at throughputs exceeding 400 passengers per hour. These systems serve the primary commercial purpose of maintaining aviation security while minimizing boarding delays at high-volume terminals. Millimeter wave scanners and biometric screening solutions command expanding share as airports prioritize touchless passenger flow, while explosives detection systems represent the most mature margin pool with replacement cycles driven by TSA certification renewals. The technology dimension shows artificial intelligence and 3D imaging gaining fastest traction as security agencies demand lower false-alarm rates and automated threat recognition.
The Transportation Security Administration sets operational requirements that directly shape equipment specifications and deployment timelines across US airports, while Brazil's ANVISA and Mexico's aviation security directorate enforce parallel certification standards that vendors must satisfy for market access. FAA coordination with DHS on emerging unmanned aerial system threats is expanding the scope of passenger screening to include integrated perimeter-to-gate security architectures. Stakeholders must weigh the capital intensity of full checkpoint modernization against modular upgrades that preserve existing infrastructure while accommodating next-generation biometric and AI-driven detection protocols.
Market Dynamics
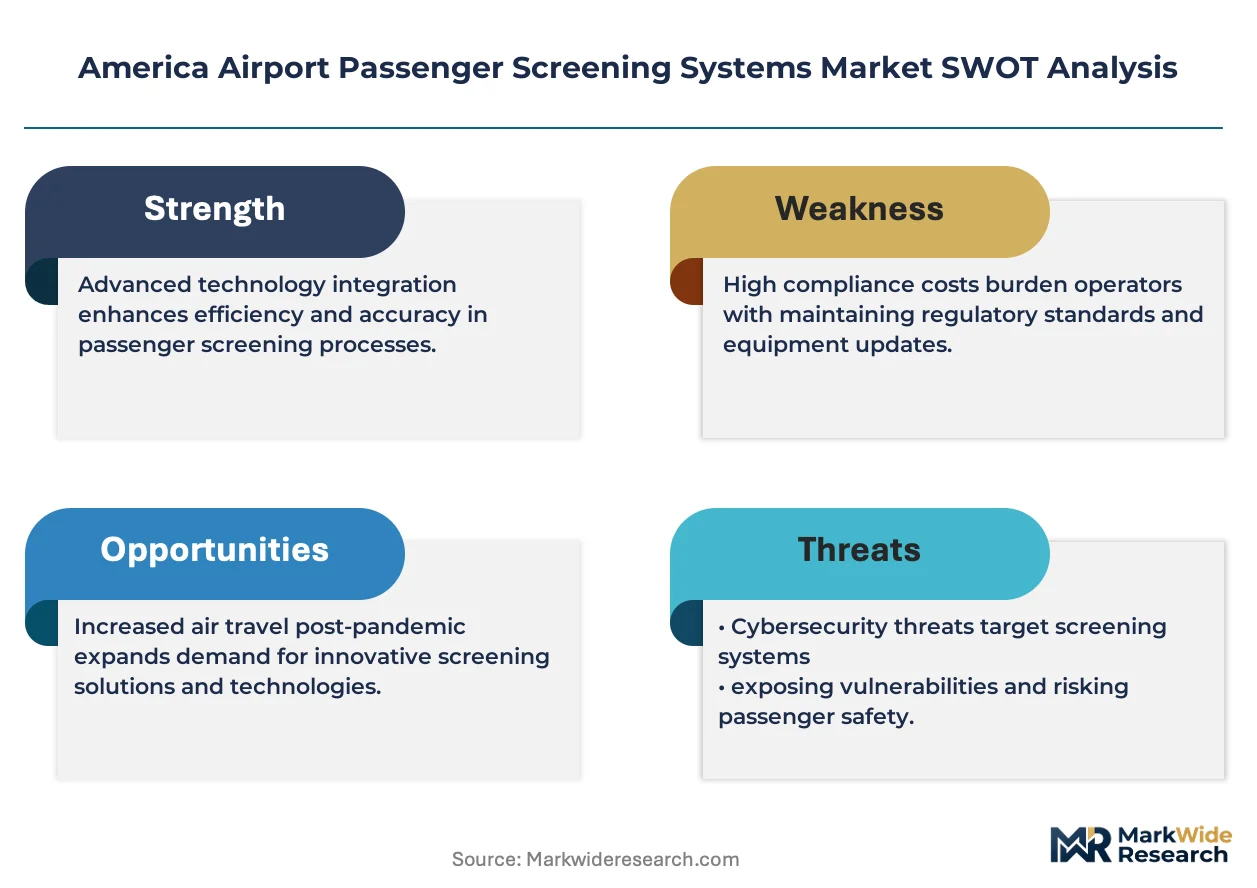
The Transportation Security Administration's mandate for AI-enabled threat detection is compressing replacement cycles for legacy X-ray systems at major US hub airports. Equipment procurement now hinges on certification timelines rather than depreciation schedules.
Growth Catalysts
- Biometric Integration Mandates:The FAA's coordination with DHS on touchless passenger flow protocols is accelerating millimeter wave scanner deployments at Atlanta, Chicago, and Dallas terminals.
- ANVISA Certification Alignment:Brazil's pharmaceutical and security regulator is harmonizing explosives detection standards with TSA protocols, opening procurement pathways for integrated screening platforms.
- Millimeter Wave Throughput Gains:Electromagnetic scanning technology now processes over 400 passengers per hour, reducing boarding delays that cost airlines slot allocations at congested hubs.
Market Restraints
- Software Update Monopolization:Original equipment manufacturers are tightening control over firmware distribution, locking airports into single-source maintenance contracts with limited price negotiation leverage.
- Legacy Infrastructure Sunk Costs:Full checkpoint modernization requires capital outlays that conflict with municipal bond financing constraints at mid-tier US airports.
- CT Detector Component Concentration:Computed tomography sensor supply chains concentrate in East Asian manufacturing clusters, exposing procurement timelines to geopolitical shipping disruptions.
Strategic Opportunities
- Mexico Hub Modernization:Mexico City's aviation security directorate is issuing tenders for integrated perimeter-to-gate architectures that US vendors can capture through TSA-certified equipment transfer.
- 3D Imaging Convergence:The fusion of computed tomography with facial recognition algorithms creates new product categories for automated baggage-passenger linkage screening.
- IRA-Aligned Energy Efficiency:US airport authorities can access federal infrastructure incentives by specifying low-power millimeter wave systems that reduce terminal electrical load.
Industry Challenges
- AI Model Training Data Access:Threat recognition algorithms require classified image libraries that TSA controls, creating bottlenecks for vendors seeking certification for new detection categories.
- Interoperability with 1990s-Era Infrastructure:Modern biometric screening solutions must interface with baggage handling systems and gate control networks built on obsolete communication protocols.
- Specialized Technician Scarcity:Electromagnetic scanner calibration and CT system maintenance demand personnel with dual expertise in RF engineering and aviation security protocols that training pipelines have not scaled to match deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Airport Passenger Screening Systems Market |
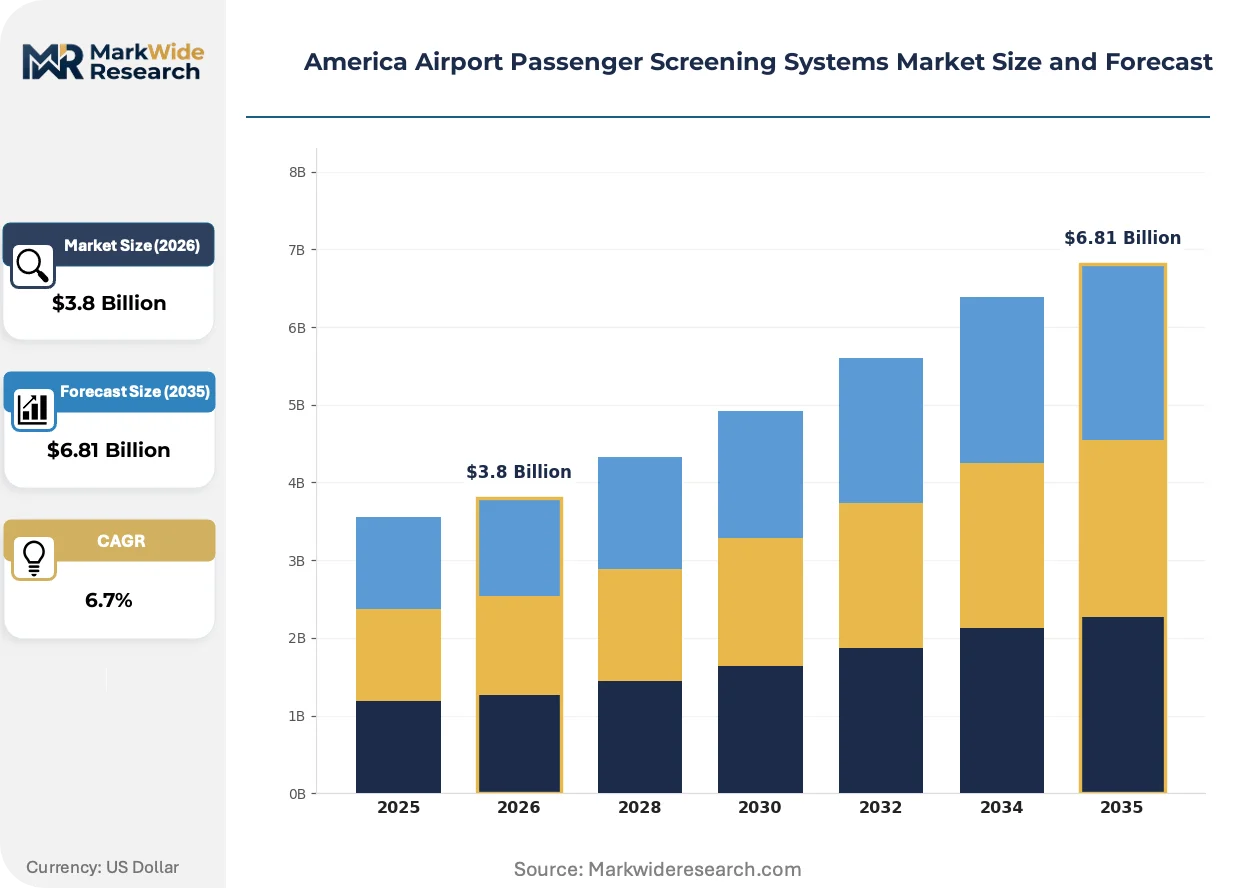
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Millimeter Wave Scanners, X-Ray Machines, Explosives Detection Systems, Biometric Screening Solutions Technology: Optical Sensors, Artificial Intelligence, Machine Learning, 3D Imaging End User: Airports, Government Agencies, Security Firms, Airlines Installation: Fixed Systems, Portable Systems, Mobile Units, Integrated Solutions |
| Companies Covered | Smiths Detection, L3Harris Technologies, Rapiscan Systems, Leidos, Analogic Corporation, Thales Group, Nuctech Company, Kromek Group, Cognitec Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Airport Passenger Screening Systems Market Strategic Shifts
Passenger screening technology is bifurcating between high-throughput automation for major hubs and modular retrofit kits for secondary airports. This divergence is reshaping vendor R&D allocation and certification strategies.
Millimeter wave body scanners are hybridizing with biometric identity verification to create single-step passenger processing lanes. Delta and American Airlines are piloting these integrated checkpoints at Dallas-Fort Worth and Atlanta Hartsfield-Jackson. The technology is hybridizing passenger flow architecture, compressing the physical footprint required for security zones while raising throughput ceilings beyond 600 passengers per hour.
The Transportation Security Administration's evolving checkpoint standards now mandate lower false-alarm rates for explosives trace detection, forcing recertification of installed base systems. Equipment vendors must resubmit validation data under tightened protocols. Mid-tier US airports with limited technical staff are outsourcing compliance documentation to specialized service firms, creating a secondary market around regulatory navigation.
Airport authorities are unbundling maintenance contracts from initial equipment purchases, treating software updates and spare parts as separately negotiable spend categories. This procurement fragmentation disadvantages smaller vendors lacking nationwide service networks. The shift is most visible in California and Texas, where port authorities have consolidated screening equipment buying across multiple municipal airports to extract volume-based service pricing.
America Airport Passenger Screening Systems Market Segmentation
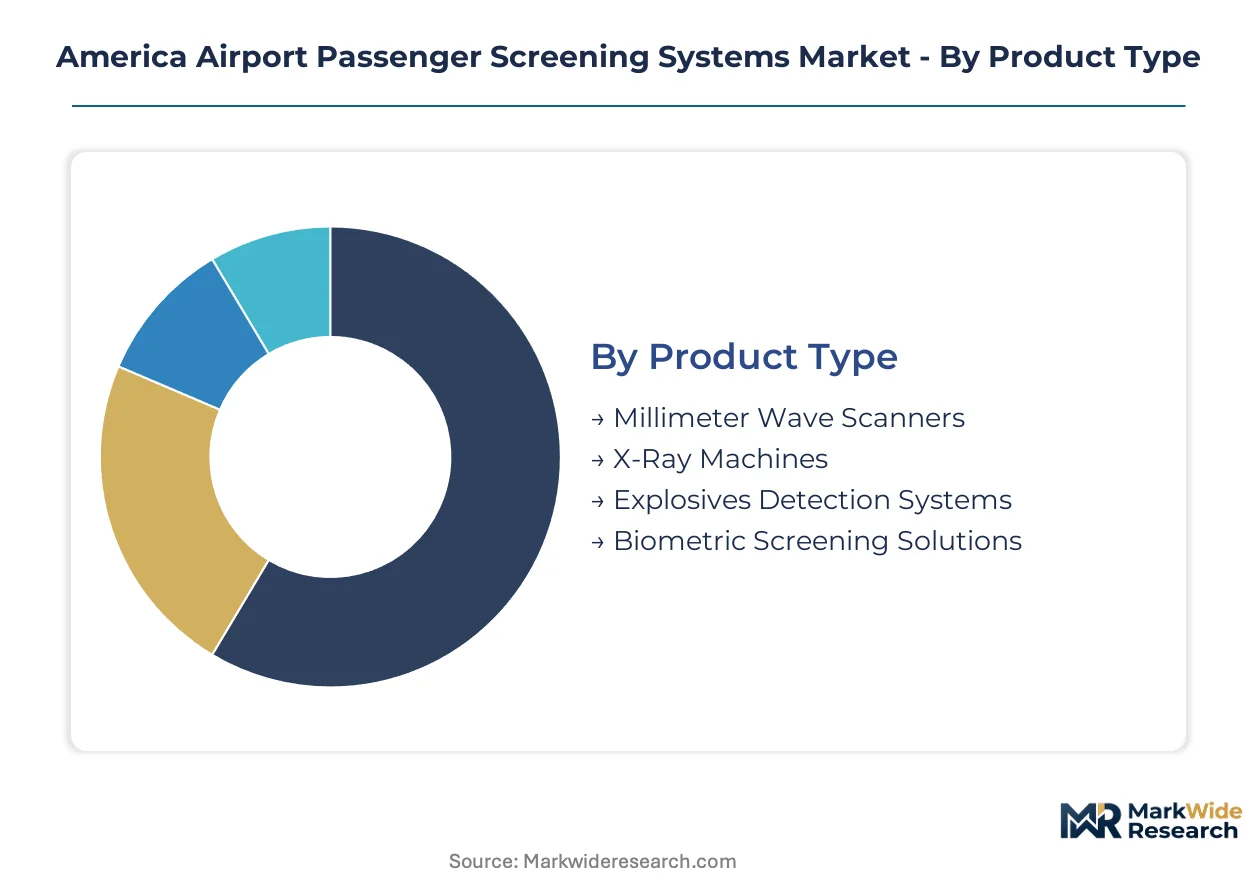
Segmentation in the America airport passenger screening systems market reveals distinct procurement patterns across product categories, with after-sales service intensity varying sharply between legacy hardware and AI-enabled platforms. Understanding these divisions helps vendors align R&D investment with replacement cycle timing and certification requirements.
Product Type:
After-sales service intensity runs highest on explosives detection systems, where TSA certification renewals demand continuous calibration support and firmware validation.
- Millimeter Wave Scanners:Electromagnetic body scanners operating at 24-30 GHz frequencies detect concealed objects beneath clothing without physical pat-downs. Demand concentrates at Atlanta, Chicago, and Dallas hubs where passenger throughput exceeds 400 per hour and boarding delay penalties threaten slot allocations. These systems require less frequent recertification than explosives detection but demand specialized RF technician networks.
- X-Ray Machines:Legacy baggage and body scanning systems using ionizing radiation for contraband detection. Replacement cycles compress as TSA mandates AI-enabled threat detection, forcing early retirement of analog systems at major US terminals before full depreciation.
- Explosives Detection Systems:Trace and bulk detection platforms for luggage and cargo screening with the most intensive service requirements.
- Biometric Screening Solutions:Facial recognition and iris scanning systems for touchless passenger flow.
Explosives Detection Systems holds the largest share; momentum sits with Millimeter Wave Scanners.
Technology:
Cost tier separation distinguishes premium AI-enabled platforms from commodity optical sensor deployments at secondary airports.
- Artificial Intelligence:Deep learning algorithms for automated threat recognition in baggage and passenger screening. Demand concentrates at TSA-regulated US hubs where false-alarm reduction mandates drive procurement specifications; classified training data access creates vendor bottlenecks.
- 3D Imaging:Computed tomography and volumetric reconstruction for layered baggage analysis. Brazil's ANVISA harmonization with TSA protocols opens procurement pathways at São Paulo and Rio de Janeiro terminals for integrated screening platforms.
- Machine Learning:Pattern recognition systems that improve detection accuracy through operational data feedback.
- Optical Sensors:Camera-based detection systems for document verification and behavioral screening.
Artificial Intelligence commands premium pricing; 3D Imaging is climbing the fastest.
End User:
Application context varies from sovereign security mandates to commercial efficiency pressures across buyer categories.
- Airports:Municipal and port authority operators of checkpoint infrastructure at commercial terminals. Procurement concentrates in Texas and California where consolidated buying across multiple municipal airports extracts volume-based service pricing.
- Government Agencies:TSA and parallel Latin American aviation security directorates setting certification standards.
- Security Firms:Private contractors operating auxiliary screening at cargo terminals and executive aviation facilities.
- Airlines:Delta and American Airlines piloting integrated biometric-millimeter wave lanes at Dallas-Fort Worth and Atlanta.
Airports hold the largest share; momentum sits with Government Agencies.
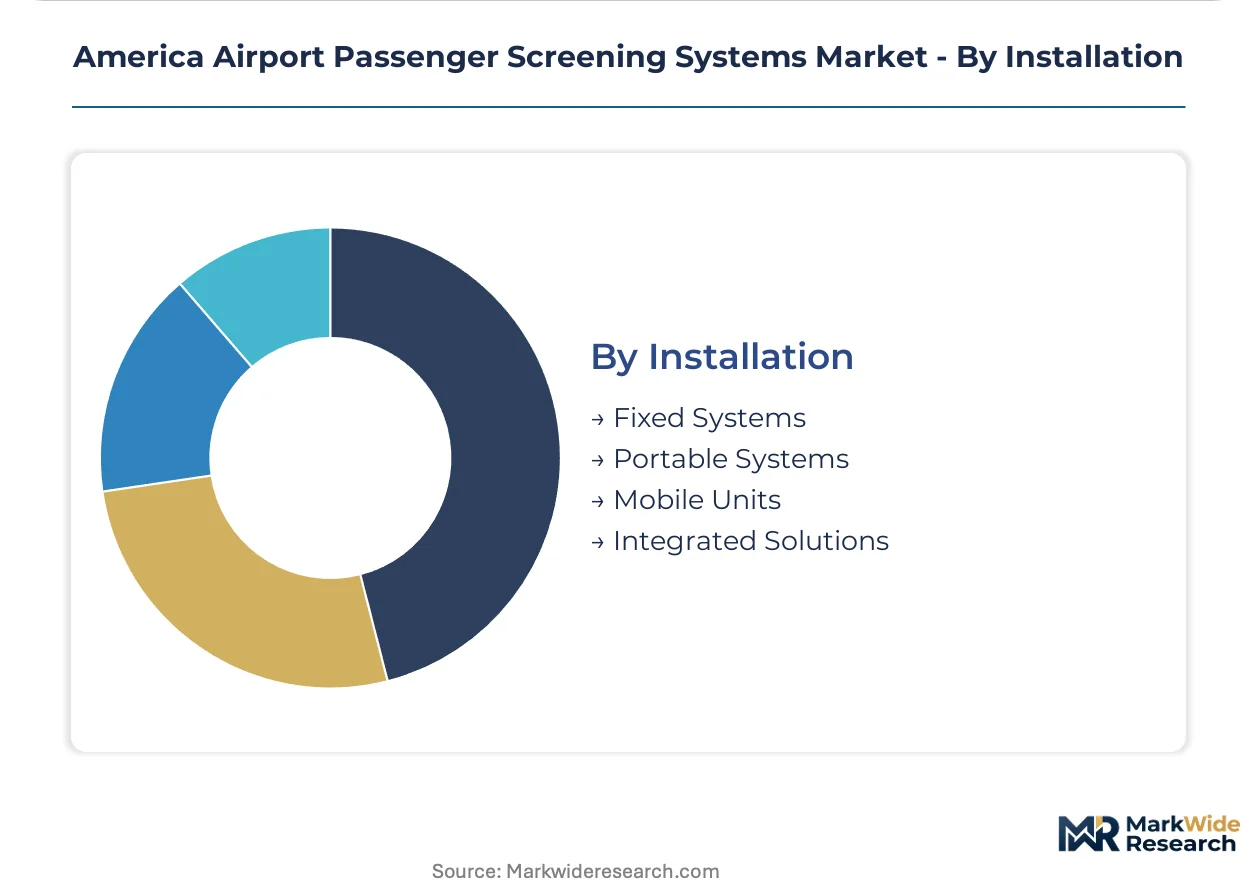
Installation:
Volume deployment patterns favor fixed systems at major hubs while mobile units serve seasonal and emergency requirements.
- Fixed Systems:Permanent checkpoint installations with hardwired power and data integration. Demand concentrates at US hub airports where full modernization conflicts with municipal bond financing constraints.
- Integrated Solutions:Perimeter-to-gate security architectures combining passenger, baggage, and access screening. Mexico City's aviation security directorate is issuing tenders for these architectures that US vendors can capture through TSA-certified equipment transfer.
- Portable Systems:Relocatable screening units for temporary checkpoints and construction disruptions.
- Mobile Units:Vehicle-mounted screening for remote terminals and special events.
Fixed Systems holds the largest share; Integrated Solutions is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Americas. US hub airports absorb premium pricing for TSA-certified AI-enabled systems, while Brazilian and Mexican operators negotiate aggressively on total cost of ownership.
United States
The FAA coordinates with DHS on touchless passenger flow protocols at Atlanta Hartsfield-Jackson, Chicago O'Hare, and Dallas-Fort Worth. TSA checkpoint standards mandate AI-enabled threat detection, compressing replacement cycles for legacy X-ray systems. California and Texas port authorities consolidate screening equipment buying across municipal airports to extract volume-based service pricing.
Brazil
ANVISA harmonizes explosives detection standards with TSA protocols, opening procurement pathways at São Paulo and Rio de Janeiro terminals. The aviation security directorate favors integrated screening platforms that reduce passenger processing bottlenecks. Mid-tier airports in Minas Gerais and Paraná delay modernization due to municipal financing constraints.
Mexico
Mexico City's aviation security directorate issues tenders for perimeter-to-gate security architectures. The country's national aviation regulator requires TSA-certified equipment transfer for vendor eligibility. Northern border state airports prioritize throughput gains to maintain slot allocations with US carriers.
Canada
Transport Canada aligns checkpoint standards with evolving FAA protocols, driving millimeter wave scanner adoption at Toronto Pearson and Vancouver International. The national transportation regulator emphasizes interoperability with US preclearance facilities. Prairie province airports defer full modernization, opting for modular retrofit kits.
America Airport Passenger Screening Systems Market Competitive Environment
Defense-electronics conglomerates and specialized security-technology firms split the market between integrated platform provision and point-solution specialization. The vendor base concentrates around TSA procurement channel access and ANVISA certification capabilities. Three archetypes dominate: systems integrators with federal agency relationships, component specialists with sensor technology depth, and emerging challengers competing on total cost of ownership. Competitive moves center on certification timeline acceleration and aftermarket service contract capture.
Among US-based systems integrators, L3Harris Technologies and Leidos occupy positions anchored in federal procurement channels. Smiths Detection exemplifies the explosives-detection specialist archetype with sustained recurring maintenance relationships. Rapiscan Systems represents aggressive pricing competition for Latin American airport contracts.
| Leading Market Players |
|---|
| Smiths Detection |
| L3Harris Technologies |
| Rapiscan Systems |
| Leidos |
| Analogic Corporation |
| Thales Group |
| Nuctech Company |
| Kromek Group |
| Cognitec Systems |
| Others |
Value Chain & Pricing Dynamics
East Asian manufacturing clusters for CT detector components anchor downstream pricing power for US airport authorities, with sensor supply bottlenecks translating directly into extended procurement timelines and inflated total cost of ownership for integrated screening platforms.
Pricing Analysis
After-sales service revenue tiers—spanning firmware subscriptions, spare parts distribution, and extended calibration contracts—drive lifetime value capture for original equipment manufacturers. Three-tier pricing structure across premium AI-enabled platforms, standard millimeter wave systems, and economy-grade X-ray retrofits differentiates vendor positioning. Cost compression in the mid-tier segment intensifies because municipal bond financing constraints at secondary US airports limit capital availability for full checkpoint modernization. Government agencies exhibit the least price sensitivity due to sovereign security mandates, while mid-tier municipal airports negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Contract manufacturing concentration for millimeter wave RF modules and CT sensor arrays rests with specialized electronics manufacturing services in Taiwan, South Korea, and Japan. Critical input dependencies include gallium arsenide semiconductors, precision electromagnetic shielding components, and high-purity detector crystals. Single-source vulnerability for CT detector subassemblies exposes procurement timelines to geopolitical shipping disruptions. Distribution runs through TSA-certified equipment integrators with established federal procurement channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of technicians combining RF engineering expertise with aviation security certification creates a structural bottleneck that shapes competitive positioning across vendor tiers.
For Market Incumbents: Insulate recurring revenue streams by tightening firmware distribution control and expanding captive spare parts networks. Consolidate service contract capture through nationwide technician training pipelines that address the specialized RF engineering scarcity. Certification investment in ANVISA-aligned protocols defends against emerging challengers competing on price for Latin American airport tenders. For New Entrants and Emerging Players: Mid-tier municipal airports in Texas and California with consolidated procurement authority represent the most penetrable entry point for modular retrofit solutions. Secondary airports in Brazil's Minas Gerais and Paraná states offer white-space opportunity given deferred modernization timelines. A go-to-market angle anchored on IRA-aligned energy efficiency specifications unlocks federal infrastructure incentive access. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-electronics conglomerates seeking to divest non-core security technology divisions. Long-term viability hinges on TSA procurement channel relationships and AI model training data access privileges. Watch ANVISA-TSA certification harmonization progress as the inflection indicator for Latin American market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI Model Certification Investment | TSA validation for automated threat recognition algorithms secures procurement eligibility at Atlanta, Chicago, and Dallas hubs. |
| Perimeter-to-Gate Integration | Mexico City aviation security tenders reward vendors with TSA-certified equipment transfer capabilities. |
| Technician Training Pipeline Expansion | Dual RF engineering and aviation security expertise addresses the specialized calibration scarcity constraining deployment rates. |
| ANVISA Certification Alignment | Brazilian regulatory harmonization opens integrated screening platform procurement at São Paulo and Rio de Janeiro terminals. |
| IRA-Aligned Energy Efficiency Specification | Low-power millimeter wave systems qualify US airports for federal infrastructure incentives under terminal electrical load reduction criteria. |
Study Parameters
Initial hypotheses were tested against primary input from TSA procurement officers, airport authority infrastructure directors, RF engineering specialists, and explosives detection system maintenance technicians and refined through secondary validation against FAA coordination protocols, ANVISA regulatory filings, TSA checkpoint standard documentation, and municipal bond financing disclosures. Bottom-up equipment deployment tracking across US hub airports triangulates with top-down market sizing derived from federal procurement database analysis.
Demand-supply-balance framing anchors the analytical framework across the analysis window, with segmentation modeled across product type, technology tier, end-user category, and installation architecture. CAGRs derive from replacement cycle compression analysis and certification timeline acceleration patterns. Industry-specific forecast inputs include TSA AI-enablement mandate implementation velocity and ANVISA-TSA protocol harmonization progress.
Practitioners should monitor TSA certification backlog expansion, CT detector component shipping disruption indicators, and municipal bond issuance volatility for early signals of forecast revision triggers. Quarterly review of ANVISA regulatory alignment milestones and federal infrastructure incentive allocation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Air Data Systems Market
Aerospace & Defense
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Aerospace & Defense
Defense Aircraft Material Market
Aerospace & Defense
Aircraft Maintenance Market
Aerospace & Defense
GCC Drones Market
Aerospace & Defense
Military Marine Vessel Engines Market
Aerospace & Defense
Military Radar Systems Market
Aerospace & Defense
Military Aircraft Maintenance, Repair and Overhaul Market
Aerospace & Defense
Satellite Sensor Market
Aerospace & Defense
Aircraft Weight Scale Market
Aerospace & Defense
Airborne Radars Market
Aerospace & Defense
Aircraft Ejection Seats Market
Aerospace & Defense
Frame Alignment Systems Market
Aerospace & Defense
Europe Small Satellite Market
Aerospace & Defense
Asia-Pacific Drone Light Shows Market
Aerospace & Defense
Global Aircraft Design and Engineering Market