
 Turbine Air Filtration Market | 2026-2036
Turbine Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Air Filtration Market Analytics
China is fragmenting as domestic filter manufacturers scale capacity for power sector contracts. Donaldson Company Inc. leverages its North American distribution network to sustain aftermarket revenue. MANN+HUMMEL GmbH anchors European supply through specialized heavy-duty intake systems. Camfil AB competes on filtration efficiency ratings for aerospace turbine applications.
Turbine air filtration encompasses intake systems designed to remove particulate, moisture, and chemical contaminants from combustion air streams, with filter media typically rated for MERV 11-16 efficiency and pressure differentials monitored at 0.5-4.0 inches water gauge to prevent compressor fouling and maintain thermal efficiency. Pre-filters dominate volume shipments across power generation installations where coarse particulate loads necessitate frequent replacement cycles. HEPA filters command premium positioning in aerospace applications where sub-micron particle retention protects precision turbine components from erosion and deposit formation.
EPA Clean Air Act standards and OSHA ventilation requirements shape product specifications for U.S. industrial installations, while REACH compliance in Europe restricts certain chemical binders in filter media manufacturing. China's GB standards and MEE environmental enforcement drive localization of supply chains for domestic power projects. Stakeholders must monitor evolving particulate emissions thresholds and filter disposal regulations as sustainability criteria penetrate procurement decisions.
Market Dynamics
Gas turbine operators face intensifying pressure to maintain compressor efficiency amid rising ambient particulate loads and tightening EPA emissions thresholds, forcing accelerated replacement cycles for intake filtration systems.
Growth Catalysts
- EPA Clean Air Act enforcement:Utility-scale power generators in the United States must upgrade intake systems to meet particulate emissions standards, driving systematic filter replacement programs.
- Combined cycle plant expansion:New gas turbine installations across the United States require high-efficiency MERV-rated pre-filtration and final-stage HEPA configurations.
- Filter media innovation:Nanofiber composite layers improve sub-micron retention while reducing pressure drop penalties, extending operational intervals between compressor washes.
Market Restraints
- Glass microfiber supply concentration:Filter media production depends on specialized borosilicate fiber supply chains concentrated in Germany and Japan, exposing manufacturers to input volatility.
- Technical limitation in high-humidity environments:Current hydrophobic coatings degrade below 85% relative humidity, restricting filter deployment in coastal Southeast Asian installations.
- REACH chemical binder restrictions:ECHA regulations limit formaldehyde-based adhesives in European-manufactured pleated media, forcing reformulation investments.
Strategic Opportunities
- India power sector modernization:NTPC and state electricity boards are tendering for F-class and H-class gas turbine intake upgrades, creating demand for heavy-duty self-cleaning systems.
- OSHA indoor air quality mandates:Workplace ventilation rules for industrial turbine halls create ancillary demand for secondary filtration and monitoring equipment.
- Predictive maintenance convergence:Integration of differential pressure sensors with SCADA analytics enables condition-based filter replacement, opening software-enabled service revenue streams.
Industry Challenges
- Specialized field technician scarcity:Installation of large-format pulse-jet cleaning systems requires certified rigging and sealing expertise that outstrips current training pipeline output.
- Legacy housing incompatibility:Retrofitting advanced v-cell and pocket configurations into 1980s-era intake plenums demands custom fabrication, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Air Filtration Market |
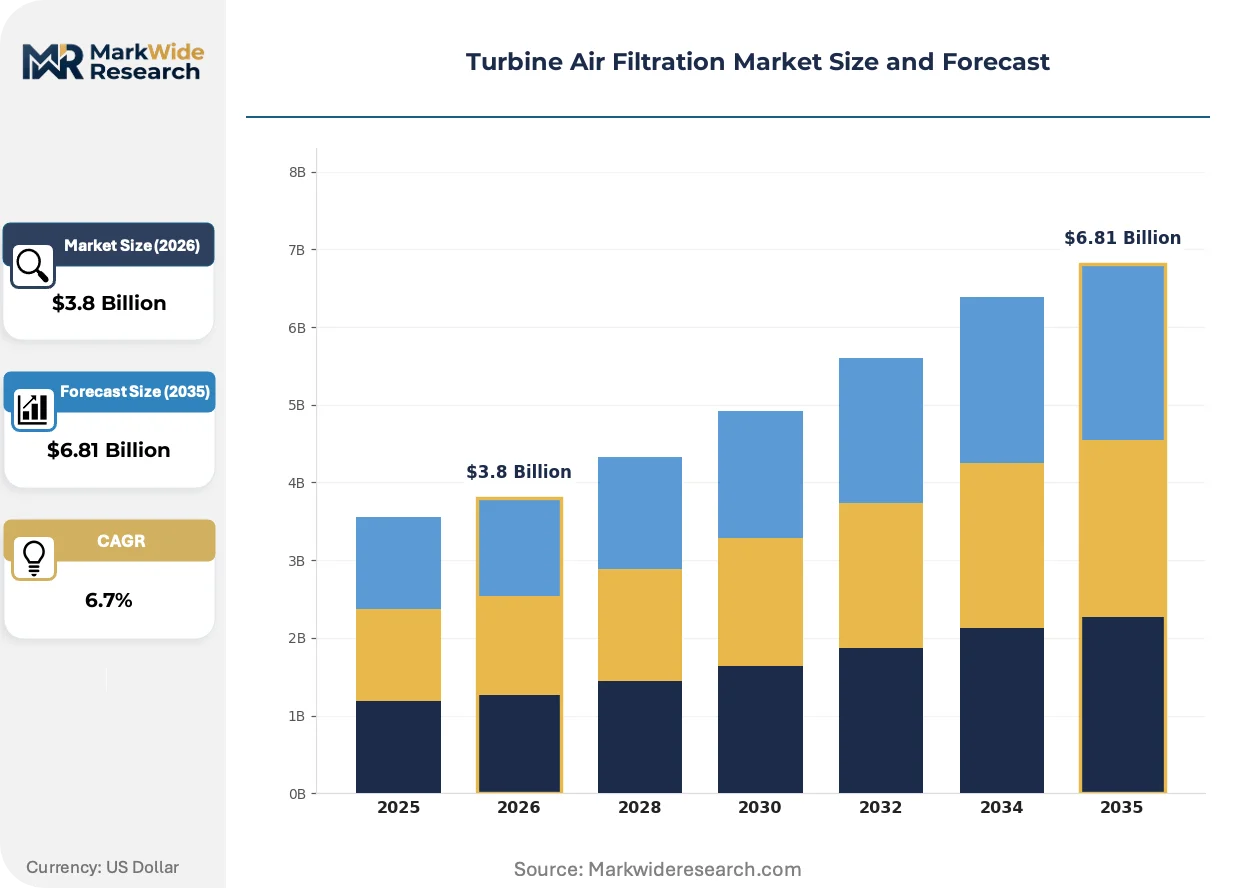
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Filters, HEPA Filters, Activated Carbon Filters, Oil Mist Filters Application: Aerospace, Power Generation, Manufacturing, Oil & Gas End User: Industrial Facilities, Aircraft Manufacturers, Energy Plants, Marine Services Technology: Electrostatic, Mechanical, Chemical, Biological |
| Companies Covered | Camfil AB, Donaldson Company Inc., MANN+HUMMEL GmbH, Graver Technologies LLC, Nordic Air Filtration A/S, Koch Filter Corporation, Purolator Air Filters, Filtration Group, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Air Filtration Market Evolving Landscape
Digital sensor integration and advanced media chemistry are compressing maintenance intervals while expanding the addressable market for high-performance filtration across aerospace and power generation verticals.
Electrospun nanofiber surface layers are virtualizing traditional depth-loading filtration by capturing sub-micron particles on the media surface rather than within the matrix, enabling pulse-jet cleaning recovery. Power generation operators in the United States are retrofitting this technology into existing pulse-clean systems to extend filter life. The technology is virtualizing the economic trade-off between filtration efficiency and pressure drop penalties that previously constrained system design.
REACH compliance deadlines for per- and polyfluoroalkyl substance restrictions are forcing European filter manufacturers to eliminate PTFE membrane laminates from high-temperature applications. Industrial gas turbine operators must validate alternative hydrophobic treatments that maintain moisture repellency without fluorinated chemistry. Aerospace turbine applications face the steepest certification burden, with EASA type approval timelines extending 18-24 months for reformulated media.
Power utilities are consolidating filter procurement through multi-year framework agreements with integrated service providers, displacing spot purchasing from distributor networks. This concentration shifts margin capture toward aftermarket service bundling and away from component manufacturing. The pattern is most pronounced among independent power producers in Texas and California, where merchant plant economics favor total cost-of-ownership contracts over capital expenditure minimization.
Turbine Air Filtration Market Segmentation
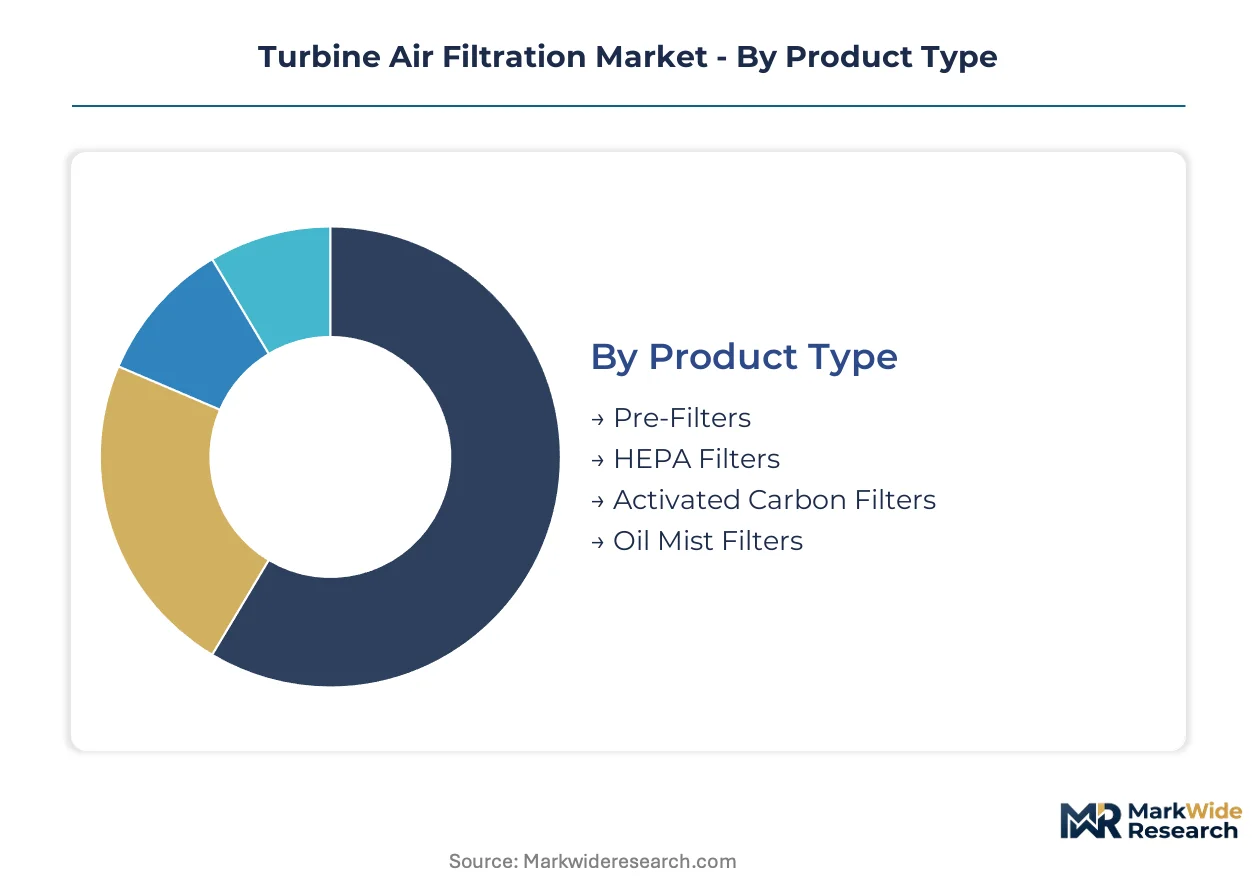
Turbine air filtration segmentation reveals stark differences in replacement economics across product tiers, with pre-filters cycling every 3-6 months against HEPA systems lasting 18-36 months. Application mix determines margin structure, as aerospace certification burdens contrast with utility-scale volume procurement.
Product Type:
Replacement cycles range from quarterly consumables to multi-year capital investments, creating divergent revenue recognition patterns across the supply base.
- Pre-Filters:Depth-loading media constructed from synthetic fibers or glass mat capture coarse particulate above 10 microns, protecting downstream stages. United States combined cycle plants drive systematic bulk procurement as compressor fouling prevention mandates accelerate changeout schedules.
- HEPA Filters:Extended-surface pleated configurations rated MERV 14-16 retain sub-micron particles through microglass or PTFE membrane media. Aerospace turbine OEMs in California and Texas concentrate specification authority, demanding EASA traceability for flight-critical applications.
- Activated Carbon Filters:Impregnated cellulose or synthetic substrates adsorb corrosive gases and hydrocarbon vapors from intake streams. Chemical plants along the Gulf Coast specify these for turbine protection against process emissions.
- Oil Mist Filters:Coalescing media separate lubricant aerosols from ventilation air in enclosed turbine halls. Manufacturing facilities in Michigan and Ohio retrofit these to meet OSHA workplace exposure limits.
Pre-filters anchor the volume base while HEPA configurations gain share at the steepest rate.
Application:
End-use concentration shapes technical requirements, with flight safety standards imposing stricter validation protocols than industrial uptime guarantees.
- Aerospace:Compact, lightweight assemblies must satisfy FAA and EASA airworthiness directives for engine intake protection. Commercial aviation MRO facilities in Georgia and Washington state consolidate procurement through OEM-approved supplier networks.
- Power Generation:Heavy-duty self-cleaning pulse-jet systems handle high dust loads in desert and coastal utility installations. Independent power producers in Texas favor total cost-of-ownership contracts over spot component purchasing.
- Manufacturing:Secondary filtration for plant ventilation supplements primary turbine intake protection. Automotive stamping plants in Kentucky and Tennessee drive demand for oil mist and particulate combination systems.
- Oil & Gas:Hydrocarbon-laden environments require explosion-rated housings and specialized sealing. Offshore platforms in the Gulf of Mexico specify stainless steel construction for salt spray resistance.
Power generation commands the installed base while aerospace applications expand most quickly.
End User:
Procurement sophistication varies sharply, with centralized utility engineering teams contrasting against fragmented industrial maintenance departments.
- Industrial Facilities:Pulp and paper mills, cement plants, and steel foundries operate aging turbine fleets requiring retrofit-compatible filtration. Pennsylvania and Alabama facilities face EPA enforcement pressure to upgrade intake systems.
- Aircraft Manufacturers:Airframe integrators specify filtration for auxiliary power units and environmental control systems. Boeing and Lockheed Martin supply chains in Washington and Texas mandate AS9100-certified component sources.
- Energy Plants:Utility and merchant generators balance capital constraints against heat rate degradation from compressor fouling. Florida municipal utilities consolidate regional procurement to extract volume discounts.
- Marine Services:Naval and commercial shipping applications demand salt spray resistance and shock-rated mounting. Norfolk and San Diego shipyards specify MIL-STD compliance for gas turbine propulsion systems.
Energy plants dominate contract value while aircraft manufacturers drive specification innovation.
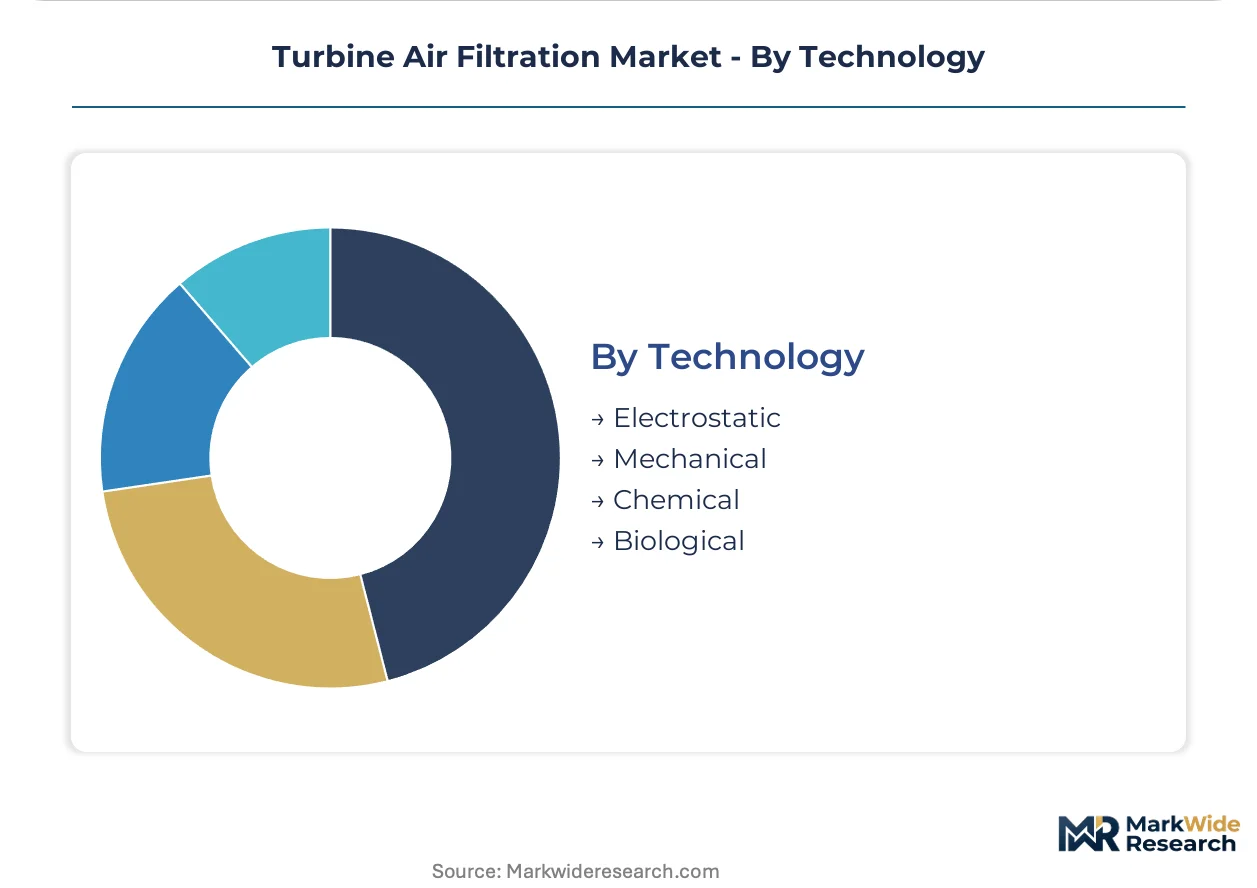
Technology:
Performance differentiation increasingly depends on media chemistry and sensor integration rather than purely mechanical designs.
- Electrostatic:Ionization chambers charge particles for enhanced collection on grounded surfaces, reducing pressure drop penalties. Data centers in Virginia and Arizona deploy these for high-efficiency cooling turbine protection.
- Mechanical:Depth and surface filtration through fibrous or membrane media remains the baseline for most installations. Nanofiber surface layers now virtualize traditional depth-loading economics in power generation retrofits.
- Chemical:Impregnated media neutralize acid gases and reactive contaminants through chemisorption. Geothermal plants in Nevada specify these for hydrogen sulfide protection.
- Biological:Bioaerosol retention systems address emerging concerns around pathogen transmission in HVAC-integrated turbine halls. Hospital cogen facilities in Massachusetts pilot these configurations.
Mechanical systems retain volume leadership while electrostatic technology climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor underwrites United States demand through combined cycle plant density, while China's West-East electricity transmission grid drives inland power station filtration procurement.
United States
Utility-scale combined cycle plants in Texas and Florida drive systematic filter replacement programs. EPA Clean Air Act enforcement mandates intake system upgrades for particulate compliance. Merchant generators in the ERCOT grid favor total cost-of-ownership contracts over spot purchasing.
China
Domestic filter manufacturers scale capacity to capture power sector contracts from state-owned utilities. MEE environmental enforcement and GB standards accelerate localization of supply chains. Yangtze River Delta industrial clusters retrofit aging gas turbine intakes with heavy-duty pulse-jet systems.
Germany
Specialized heavy-duty intake systems anchor European supply for industrial gas turbine operators. REACH chemical binder restrictions force reformulation investments in pleated media manufacturing. Bavarian precision engineering clusters develop alternative hydrophobic treatments eliminating PTFE membranes.
India
NTPC and state electricity boards tender for F-class and H-class gas turbine intake upgrades. Central Electricity Authority mandates drive procurement standardization across regional generation companies. Gujarat and Maharashtra industrial corridors pilot self-cleaning filtration for coastal humidity environments.
Saudi Arabia
Desert particulate loads necessitate high-capacity pulse-clean systems for combined cycle installations. The country's national environmental regulator enforces emissions thresholds for utility-scale plants. Eastern Province oil-gas integration projects specify stainless steel housings for hydrocarbon-laden intake streams.
Turbine Air Filtration Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in media and element manufacturing. The vendor base stratifies between multinational filtration conglomerates with full intake system capabilities and regional fabricators focused on replacement elements. Two strategic archetypes dominate: integrated service providers bundling predictive maintenance software with hardware, and nanofiber media specialists licensing surface-loading technology to downstream system builders. Competitive moves concentrate on multi-year framework agreements displacing spot purchasing, and backward integration into specialized glass microfiber supply.
Among Nordic fabricators, Nordic Air Filtration A/S exemplifies regional specialist positioning in heavy-duty pulse-jet configurations. Donaldson Company Inc. and MANN+HUMMEL GmbH anchor the multinational tier, with the former representing North American distribution-intensive aftermarket models and the latter occupying German-engineered heavy-duty system supply. Camfil AB sits within the premium efficiency vector for aerospace and precision industrial applications.
| Leading Market Players |
|---|
| Camfil AB |
| Donaldson Company Inc. |
| MANN+HUMMEL GmbH |
| Graver Technologies LLC |
| Nordic Air Filtration A/S |
| Koch Filter Corporation |
| Purolator Air Filters |
| Filtration Group |
| Pall Corporation |
| Others |
Value Network & Pricing Analysis
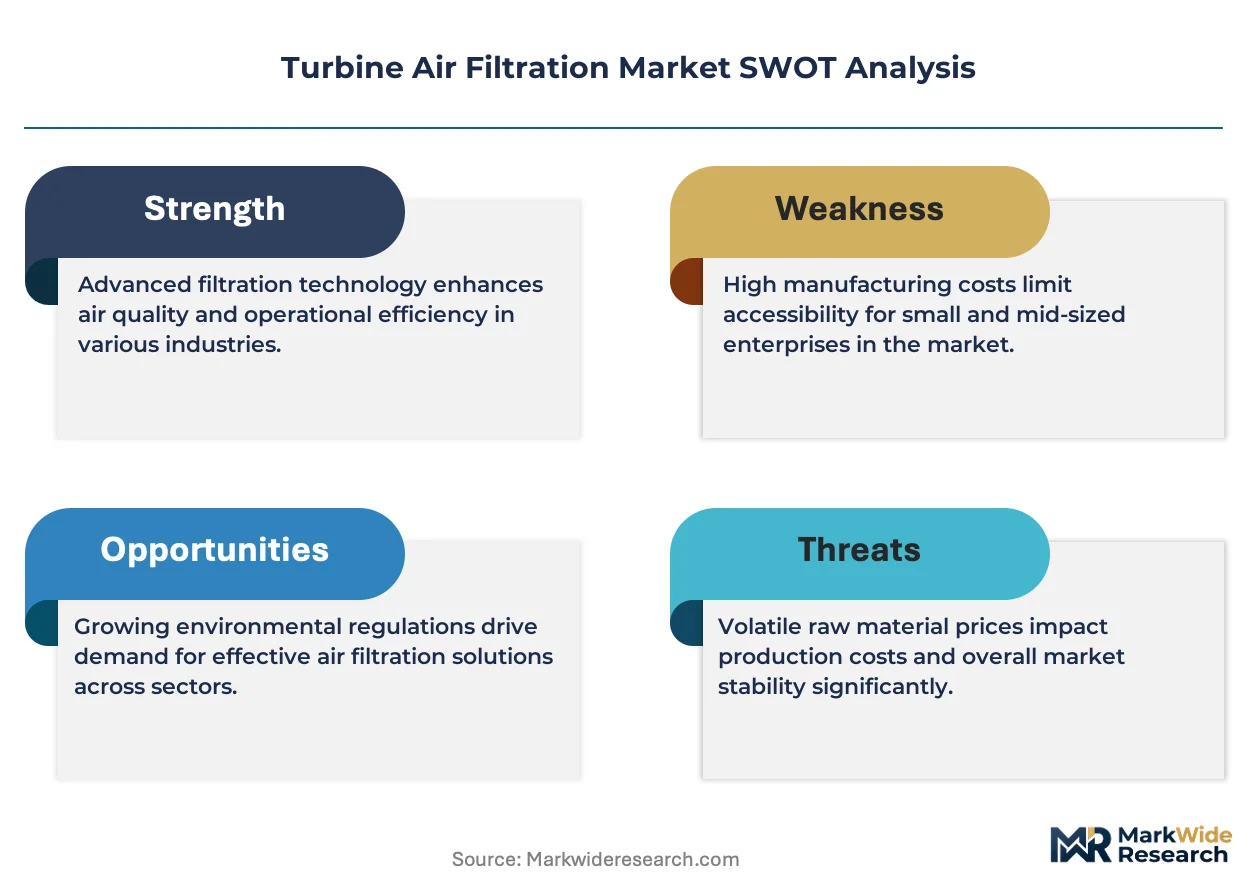
Overcapacity in Chinese filter media manufacturing is compressing spot pricing for standard-grade pleated elements while tightening margins for European suppliers still absorbing REACH reformulation costs, forcing procurement teams toward multi-year framework agreements that trade price certainty for volume commitments.
Pricing Analysis
EPA Clean Air Act dictates the pricing tier structure across United States utility installations, separating EISA-compliant premium configurations from standard MERV-rated systems and economy-grade retrofit elements. Price differentiation hinges on certification grade and after-sales service bundling, with predictive maintenance software commanding recurring revenue premiums. Cost compression in the standard tier is intensifying because domestic Chinese manufacturers are exporting surplus capacity into Southeast Asian markets. Independent power producers in Texas exhibit the highest price sensitivity, while aerospace turbine OEMs in California demonstrate minimal elasticity due to flight-critical certification requirements.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for borosilicate microfiber sourcing, with specialized glass fiber production anchored in Germany, Japan, and select United States facilities. Raw material dependencies center on borosilicate glass microfiber, synthetic nanofiber substrates, and specialized hydrophobic coating chemistries. Single-source vulnerability persists in PTFE membrane laminates as REACH deadlines eliminate European manufacturing options. Distribution runs through OEM-approved supplier networks for aerospace applications and integrated service providers for utility-scale power generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story justified by regulatory entrenchment: EPA emissions mandates and OSHA workplace rules create certification barriers that entrench incumbent positions against price-based competition.
For Market Incumbents: Harden aftermarket revenue streams by deepening predictive maintenance software integration with SCADA analytics, protecting against emerging IoT-native entrants. Secure captive supply of nanofiber composite media through backward integration or exclusive tolling arrangements with German glass fiber specialists. MANN+HUMMEL's European heavy-duty positioning offers a template for channel control through regional engineering partnerships.
For New Entrants and Emerging Players: India's coastal humidity environments present underpenetrated white space where hydrophobic coating failures among incumbent systems create specification gaps. Target NTPC tendering cycles for F-class and H-class gas turbine intake upgrades, where procurement standardization by the Central Electricity Authority lowers qualification barriers. Lead with total cost-of-ownership contracting models that displace spot purchasing from fragmented distributor networks.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle annuity play because compressor fouling physics guarantee systematic filter consumption regardless of power market cyclicality. Acquisition targets should display integrated service capabilities bundling hardware with condition-based monitoring software, not pure component manufacturing. Watch for EASA type approval timelines extending for PTFE-free media reformulations as the signal for competitive repositioning among European suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiber Media | Donaldson's North American distribution network gains margin control over specialized glass microfiber inputs. |
| Predictive Maintenance Software Launch | Differential pressure sensor integration with SCADA analytics opens recurring revenue streams for power utility contracts. |
| REACH-Compliant Hydrophobic Reformulation | Bavarian engineering clusters develop PTFE-free alternatives for European aerospace certification timelines. |
| Multi-Year Framework Agreement Expansion | Texas merchant generators consolidate procurement through integrated service providers, displacing spot distributor purchasing. |
| India Power Sector Localization | Domestic manufacturing capacity captures NTPC tendering for coastal humidity-resistant pulse-jet configurations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gas turbine maintenance directors, utility procurement officers, aerospace MRO facility managers, and filter media R&D specialists. Secondary validation drew from EPA enforcement databases, EASA type certification filings, FERC generator interconnection queues, and customs trade records for borosilicate glass fiber imports. Bottom-up unit economics for replacement cycles were triangulated against top-down power generation capacity forecasts across the analysis window.
Calibration against historical compressor fouling degradation rates and documented filter life extension from nanofiber retrofits anchored the projection framework. Segmentation modeling spanned product type tiers, application verticals, end-user procurement sophistication, and technology performance envelopes. CAGRs were derived from installed base growth, replacement intensity assumptions, and price trajectory modeling for media chemistry transitions. Industry-specific inputs included ambient particulate load variations by geography and regulatory compliance deadline schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed filter manufacturers or accelerated EASA certification for reformulated media would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market