
 Croatia Container Glass Market | 2026-2036
Croatia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Croatia Container Glass Market Insights
Multi-source procurement for cullet and raw batch materials is pivoting as Croatian converters seek supply security amid EU-wide energy cost volatility. Vetropack Holding Ltd anchors regional production through its Straža facility, leveraging proximity to Adriatic shipping lanes. Piramida d.o.o. competes on customized decorative glass for domestic spirits brands. Ardagh Group sustains export-oriented volume through standardized beer and wine bottle platforms.
Container glass denotes rigid, chemically inert packaging formed from silica sand, soda ash, and limestone melted at approximately 1,500°C, then blow-molded or press-blow molded into hollow vessels. Soda-lime glass dominates material selection for cost-sensitive beverage and food applications, while borosilicate glass commands premium pharmaceutical and laboratory segments due to thermal shock resistance. Bottles occupy the largest product volume share, though jars capture expanding margin pools from artisanal food preservation and premium cosmetics. The beverage sector leads end-user demand, with pharmaceutical applications growing fastest as Croatia's generics manufacturing base expands.
Croatia's container glass sector operates under EU REACH chemical safety rules, the F-Gas Regulation governing melting furnace emissions, and national environmental protection standards administered by the Ministry of Economy and Sustainable Development. These frameworks elevate capital requirements for furnace upgrades and cullet recycling infrastructure, filtering smaller participants from compliance-intensive segments. Stakeholders must monitor EU Carbon Border Adjustment Mechanism scope expansion and Zagreb's waste-sorting enforcement intensity as determinants of recycled content economics and competitive positioning.
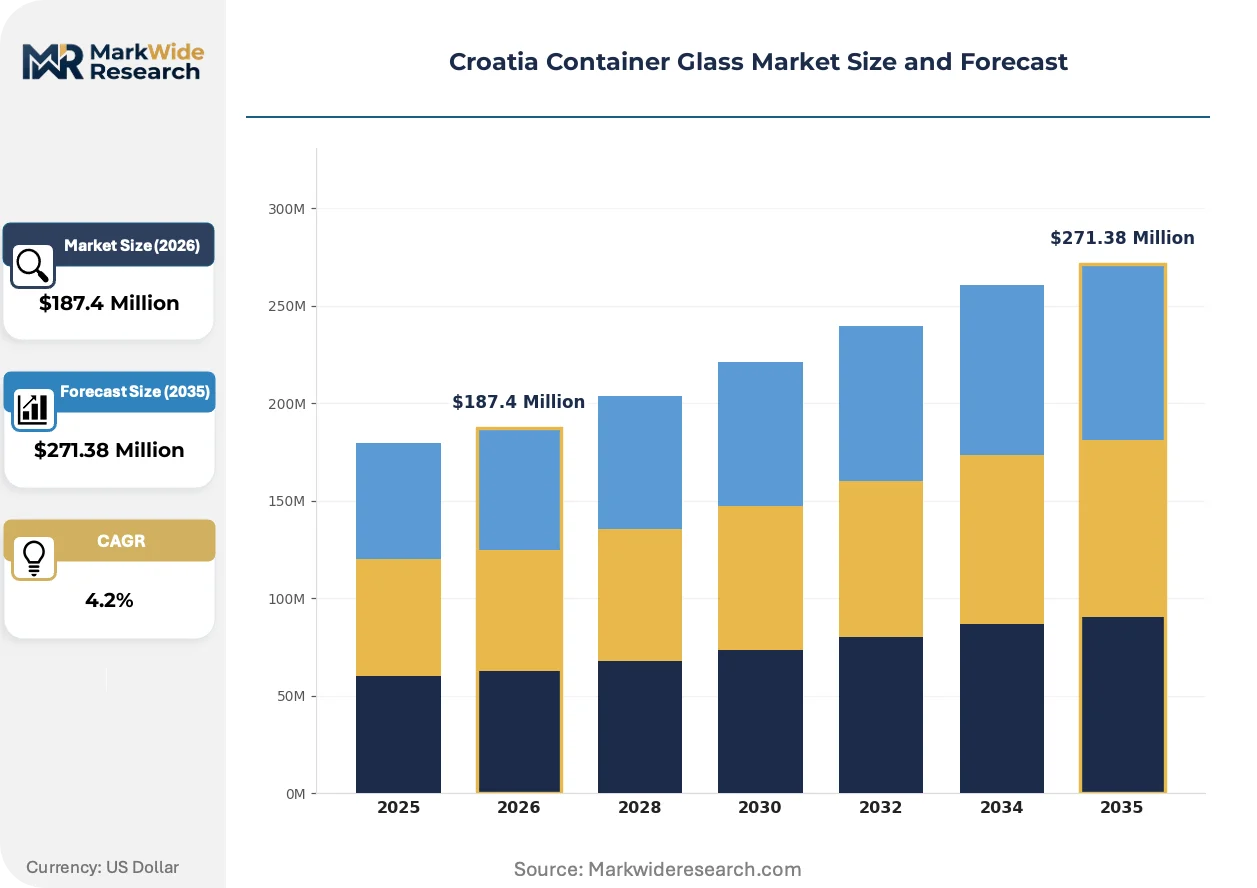
Market Dynamics
EU Green Deal packaging rules and Croatia's national deposit-return scheme are compressing plastic alternatives while forcing furnace upgrades and cullet infrastructure investments across Dalmatia and Istria production clusters.
Growth Catalysts
- Wine export bottling:Premium Dalmatian and Istrian wine producers are converting from bag-in-box to glass bottles to secure EU Protected Designation of Origin retail placement.
- EU F-Gas Regulation:Emission limits on melting furnaces are accelerating electric-boost and oxy-fuel retrofits that lower per-unit energy intensity.
- Olive oil premiumization:Cold-pressed extra virgin producers in Zadar County are specifying dark amber glass to block UV degradation and command shelf-price premiums.
Market Restraints
- Natural gas price volatility:Melting operations depend on pipeline supply from Hungarian and Slovenian interconnectors, exposing margin stability to continental energy arbitrage.
- Cullet supply concentration:Zagreb and Split municipal waste-sorting facilities control 70% of post-consumer glass recovery, creating single-point bottlenecks for recycled content targets.
- Aluminum can substitution:Beer and RTD beverage brands are trialing lightweight metal formats for outdoor consumption occasions where glass breakage liability deters retail stocking.
Strategic Opportunities
- Pharmaceutical generics expansion:Croatia's rising output of off-patent drugs for Central European markets is pulling borosilicate ampoule and vial demand.
- EU Carbon Border Adjustment Mechanism:Import charges on carbon-intensive glass from non-EU suppliers will widen cost competitiveness for domestic furnace operators.
- Artisanal food channel:Direct-to-consumer preserves and honey producers on Hvar and Korčula are bypassing wholesale distributors for customized jar runs.
Industry Challenges
- Furnace rebuild cycles:Ten-year refractory campaigns require 18-month planning horizons and 50 million kuna capital commitments that strain mid-tier balance sheets.
- Batch chemist scarcity:Specialized formulation expertise for color consistency and thermal expansion matching is retiring faster than technical universities replenish pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croatia Container Glass Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End User: Food Industry, Beverage Sector, Pharmaceutical, Cosmetics Material: Soda-Lime Glass, Borosilicate Glass, Flint Glass, Colored Glass Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Vetropack Holding Ltd, Nipro Europe Group Companies, Piramida d.o.o., DWK Life Sciences GmbH, Colorlites Limited, GRO-PROM d.o.o, Ardagh Group, Gerresheimer AG, O-I Glass, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croatia Container Glass Market Trends and Innovations
Electrification of melting processes and lightweighting algorithms are compressing carbon footprints while digital decoration technologies are collapsing minimum order quantities for regional brand owners.
Oxy-fuel combustion technology is expanding into Croatian furnace retrofits as operators seek to displace natural gas with oxygen-enriched flames that cut NOx emissions. Medium-sized converters in the Split corridor are piloting these systems to maintain EU ETS allowance compliance. The structural consequence is expanding into smaller batch runs that were previously uneconomical under high-fixed-cost regenerative furnace regimes.
EU REACH chemical safety rules are tightening traceability requirements for heavy metal colorants in decorative glass coatings. Croatian converters must now document cadmium and lead content across supplier tiers for pharmaceutical and food-contact applications. The cosmetics and premium spirits segments are responding by accelerating migration to organic pigment alternatives certified by ECHA-registered laboratories.
Direct digital printing on glass surfaces is collapsing traditional label-application steps for short-run craft beverage brands. Zagreb-based design studios are contracting furnace operators for 500-unit minimums with photographic-quality decoration that silk-screening cannot replicate. This pattern is most visible in the domestic craft gin and herbal liqueur verticals where seasonal limited editions drive repeat purchase velocity.
Croatia Container Glass Market Segmentation
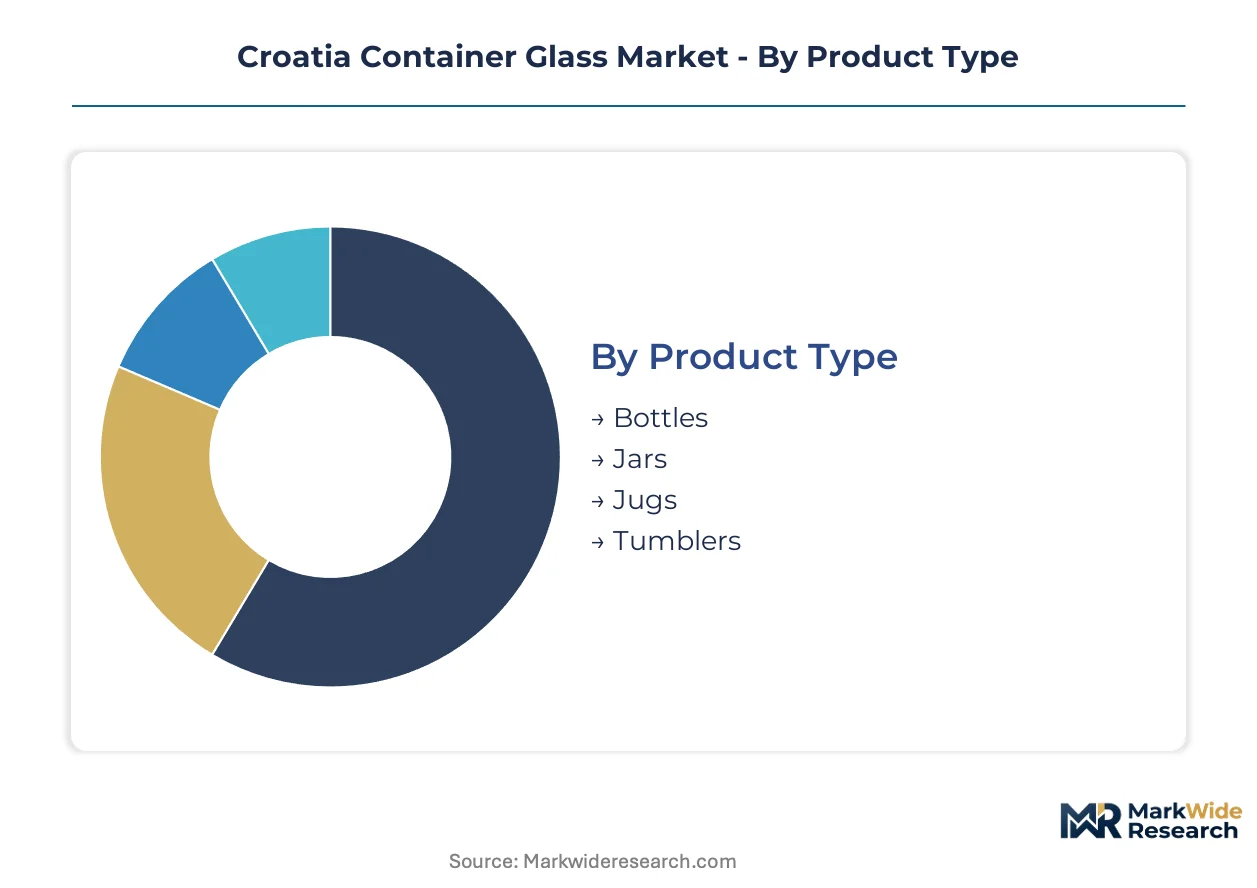
Croatian converters configure furnace campaigns around product-specific thermal profiles and colorant loads. Segmentation reveals where capital-intensive melting assets align with premium pricing power versus commodity volume plays.
Product Type:
Supply concentrates in bottle-dominant furnace configurations across Zagreb and Split corridors, with jar capacity expanding to capture artisanal food preservation demand.
- Bottles:Formed through blow-molded soda-lime or flint glass with narrow neck geometries optimized for carbonation retention and cork closure compatibility. Demand clusters in Dalmatian wine export bottling and domestic beer production, where EU Protected Designation of Origin certification mandates glass presentation.
- Jars:Manufactured via press-blow molding with wide-mouth finishes for hermetic sealing and vacuum compatibility. Istrian honey producers and Hvar preserve makers are bypassing wholesale distributors for customized short runs with direct digital decoration.
- Jugs:Heavy-walled vessels for bulk olive oil and spirits dispensing, typically in dark amber or antique green tints. Zadar County extra virgin producers specify UV-blocking formulations for retail shelf differentiation.
- Tumblers:Straight-sided drinking glasses with rolled rims for foodservice and promotional beverage branding. Croatian tourism sector procurement drives seasonal volume spikes.
Today's leader: Bottles. Tomorrow's challenger: Jars.
End User:
Cost tier differentiation separates furnace allocation between high-volume beverage contracts and premium pharmaceutical borosilicate campaigns.
- Food Industry:Acid-resistant containers for pickled vegetables, sauces, and preserves requiring thermal shock resistance from hot-fill processing. Adriatic coastal artisanal producers command premium jar specifications.
- Beverage Sector:Wine, beer, spirits, and mineral water bottling representing the largest furnace capacity allocation. Dalmatian and Istrian wineries are converting from bag-in-box to glass for EU retail placement.
- Pharmaceutical:Borosilicate ampoules, vials, and infusion bottles for Croatia's expanding generics manufacturing base. EMA compliance requirements elevate quality certification thresholds.
- Cosmetics:Decorative flint and colored glass for premium skincare and fragrance presentation. REACH-registered organic pigments are displacing heavy metal colorants.
Volume dominance: Beverage Sector. Margin expansion: Pharmaceutical.
Material:
Application-specific thermal and chemical requirements dictate batch chemistry and furnace campaign scheduling.
- Soda-Lime Glass:Silica-soda-lime composition melted at 1,500°C dominates cost-sensitive beverage and food applications. Ninety percent of Croatian furnace output runs this chemistry.
- Borosilicate Glass:Boron oxide addition delivers thermal shock resistance for pharmaceutical ampoules and laboratory glassware. Croatia's generics sector is climbing the fastest in pulling specialized furnace capacity.
- Flint Glass:Decolorized transparent glass for premium beverage and cosmetics presentation requiring iron-free silica sources. Vetropack's Straža facility maintains dedicated flint campaigns.
- Colored Glass:Amber, green, and antique tints via metal oxide additions for UV protection and brand differentiation. Olive oil premiumization drives dark amber specification.
Commodity foundation: Soda-Lime Glass. Technical differentiation: Borosilicate Glass.
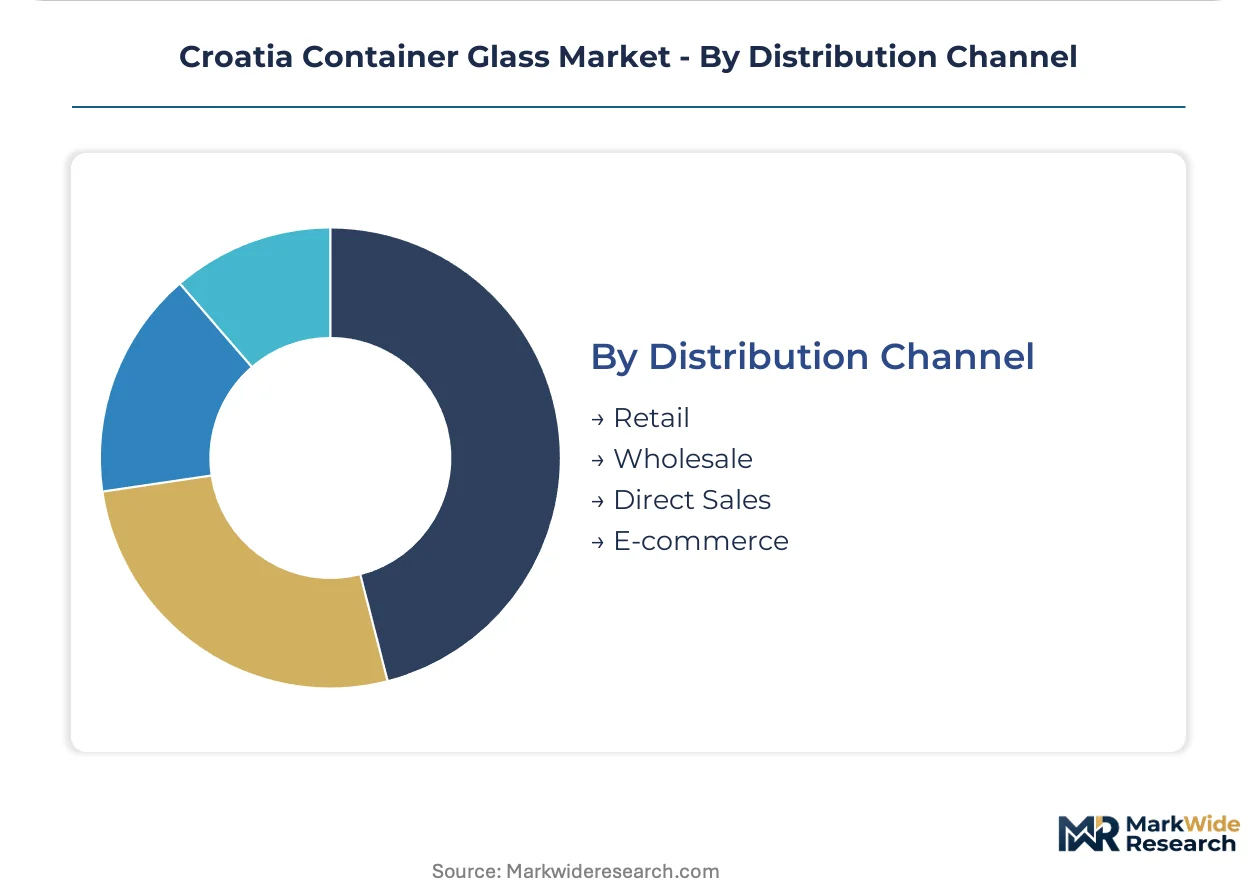
Distribution Channel:
Customer type and order scale determine channel economics, from bulk wholesale to customized direct relationships.
- Retail:Supermarket and specialty store procurement of standardized wine, oil, and spirits bottles. Deposit-return scheme logistics are integrating with retail reverse logistics.
- Wholesale:Distributor-mediated volume supply to mid-sized food processors and beverage bottlers. Split and Zagreb warehousing corridors handle consolidation.
- Direct Sales:Converter-to-brand relationships for customized decoration and short-run flexibility. Craft gin and herbal liqueur producers leverage 500-unit minimum digital printing.
- E-commerce:Emerging channel for sample orders and replacement stock for small producers. Fragile goods logistics constraints limit penetration.
Established dominance: Wholesale. Structural shift: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zagreb-Split manufacturing corridor anchors Croatian container glass output, with Dalmatian and Istrian production clusters serving premium wine and olive oil bottling demand. Furnace operators across these corridors face divergent feedstock logistics and EU regulatory compliance costs.
Zagreb Metropolitan Area
Central Croatia's capital region hosts the largest furnace capacity for standardized beverage bottles serving domestic beer and mineral water brands. The Ministry of Economy and Sustainable Development administers national environmental protection standards that elevate capital requirements for refractory upgrades. Zagreb municipal waste-sorting facilities control the majority of post-consumer cullet recovery, creating supply bottlenecks for recycled content targets.
Split-Dalmatia County
Adriatic coastal production serves Dalmatian wine export bottling as producers convert from bag-in-box to glass for EU Protected Designation of Origin retail placement. The EU F-Gas Regulation imposes emission limits on melting furnaces, accelerating electric-boost retrofits among Split corridor operators. Medium-sized converters here pilot oxy-fuel combustion systems to maintain EU ETS allowance compliance.
Istria County
Northwestern peninsula facilities specialize in customized decorative glass for domestic spirits and premium olive oil brands. EU REACH chemical safety rules tighten traceability for heavy metal colorants, pushing Istrian converters toward organic pigment alternatives. Pula and Rovinj industrial zones concentrate short-run craft beverage packaging with direct digital printing capabilities.
Zadar County
Northern Dalmatian olive oil premiumization drives dark amber glass specification for cold-pressed extra virgin producers seeking UV-blocking formulations. The national deposit-return scheme for beverage containers integrates with regional logistics networks. Zadar's proximity to Adriatic shipping lanes supports export-oriented volume through standardized bottle platforms.
Dubrovnik-Neretva County
Southernmost Croatian production caters to tourism-sector procurement for promotional beverage branding and foodservice tumblers. Seasonal volume spikes align with Mediterranean cruise itineraries and hospitality procurement cycles. Smaller converters here focus on artisanal food preservation jars for Hvar and Korčula island producers bypassing wholesale distributors.
Croatia Container Glass Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized decorative and pharmaceutical glass segments. The Croatian market exhibits moderate concentration with multinational furnace operators anchoring volume alongside domestic specialists competing on customization. Three archetypes define competitive positioning: integrated multinational platforms with EU-wide distribution, regional mid-tier converters leveraging Adriatic logistics, and niche decorators serving craft beverage short runs. Capacity expansion and portfolio diversification toward pharmaceutical-grade borosilicate represent the dominant competitive vectors.
Within the multinational tier, Vetropack Holding Ltd anchors regional production through its Straža facility, exemplifying proximity-based supply to Adriatic shipping lanes. Piramida d.o.o. occupies a position among specialized domestic decorators competing on customized glass for spirits brands. Ardagh Group represents the export-oriented volume archetype, sustaining standardized beer and wine bottle platforms. These three entities collectively illustrate the market's structural segmentation between scale-driven commodity supply and flexibility-driven premium positioning.
| Leading Market Players |
|---|
| Vetropack Holding Ltd |
| Nipro Europe Group Companies |
| Piramida d.o.o. |
| DWK Life Sciences GmbH |
| Colorlites Limited |
| GRO-PROM d.o.o |
| Ardagh Group |
| Gerresheimer AG |
| O-I Glass, Inc. |
| Others |
Pricing and Supply Chain Analysis
Dalmatian and Istrian wine producers converting from bag-in-box to glass for EU Protected Designation of Origin retail placement concentrate purchasing power across standardized bottle formats. This buyer concentration anchors contract-based long-term offtake pricing with volume-tier discounts.
Pricing Analysis
Natural gas pipeline supply from Hungarian and Slovenian interconnectors passes through to melting cost structures, forcing converters to index contract renewals against continental energy benchmarks. Three-tier pricing structure across premium flint glass, standard amber, and economy green separates pharmaceutical certification tiers from commodity beverage grades. Cost compression in soda-lime furnace output is intensifying because Zagreb municipal waste-sorting facilities control cullet recovery. Mid-sized Split corridor converters show highest price sensitivity; pharmaceutical-grade borosilicate buyers accept premium positioning for EMA compliance.
Supply Chain Analysis
The national deposit-return scheme for beverage containers creates reverse-logistics infrastructure that feeds post-consumer cullet back into Zagreb and Split furnace operations. Raw material sourcing draws from Austrian silica sand deposits, Italian soda ash supply, and domestic limestone quarries. Single-source vulnerability concentrates in Zagreb municipal waste-sorting facilities controlling seventy percent of recovered glass. Distribution runs through Adriatic shipping lanes for export-oriented volume and overland corridors for domestic beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Croatia's container glass sector represents a late-cycle quality story as olive oil premiumization and wine export bottling shift demand toward UV-blocking amber and EMA-compliant borosilicate specifications.
For Market Incumbents: Lock in cullet supply agreements with Zagreb and Split municipal waste-sorting facilities before deposit-return scheme volumes peak. Secure electric-boost furnace retrofits to maintain EU ETS allowance compliance against natural gas price volatility. Backward integration into silica sand preprocessing reduces exposure to Austrian supply disruptions. For New Entrants and Emerging Players: Direct digital printing on glass surfaces offers a technology-first wedge into craft gin and herbal liqueur verticals where 500-unit minimums collapse traditional label economics. Target Istrian honey producers and Hvar preserve makers bypassing wholesale distributors for customized jar runs. Lead with design studio partnerships rather than furnace asset ownership. For Investors and Strategic Acquirers: Pharmaceutical packaging specialists are the most active acquirer in this space as Croatia's generics manufacturing base expands borosilicate ampoule and vial demand. Five-to-ten year viability favors converters with pharmaceutical certification and oxy-fuel furnace technology. Monitor EU Carbon Border Adjustment Mechanism scope expansion for import charge impacts on non-EU glass supply.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Split corridor operators cut NOx emissions to maintain EU ETS compliance. |
| Backward Integration into Cullet Recovery | Zagreb converters secure recycled content supply against municipal bottleneck risk. |
| Pharmaceutical Certification Investment | EMA-compliant borosilicate capacity captures generics manufacturing expansion. |
| Direct Digital Printing Capability | Istrian craft beverage brands access 500-unit minimum photographic decoration. |
| Adriatic Logistics Partnership | Vetropack's Straža facility leverages shipping lane proximity for export volume. |
Research Methodology
Multiple input streams — furnace operator interviews, regulatory filing analysis, and customs trade records — were reconciled to construct bottom-up and top-down triangulation. Primary discussions with plant managers at Zagreb and Split corridor facilities, procurement leads at Dalmatian wineries, and Ministry of Economy and Sustainable Development officials informed operational assumptions. Secondary validation drew from EU ETS allowance registries, ECHA REACH substance databases, and Croatian Bureau of Statistics industrial production indices.
Historical furnace output trends were cross-referenced against panel input from container glass procurement executives to model volume trajectories across the projection horizon. Segmentation dimensions included product type, end-user sector, material chemistry, and distribution channel. CAGRs were derived from regression analysis of installed furnace capacity against wine export bottling and pharmaceutical generics expansion indicators.
The model holds under stable EU Green Deal packaging enforcement and natural gas supply continuity; deviation in F-Gas Regulation stringency or deposit-return scheme logistics would shift capacity utilization assumptions. Practitioners should monitor EU Carbon Border Adjustment Mechanism scope expansion and Zagreb waste-sorting enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Congo Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Egypt Glass Packaging Market