
 Finished Steel Products Market | 2026-2036
Finished Steel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Finished Steel Products Market Analysis
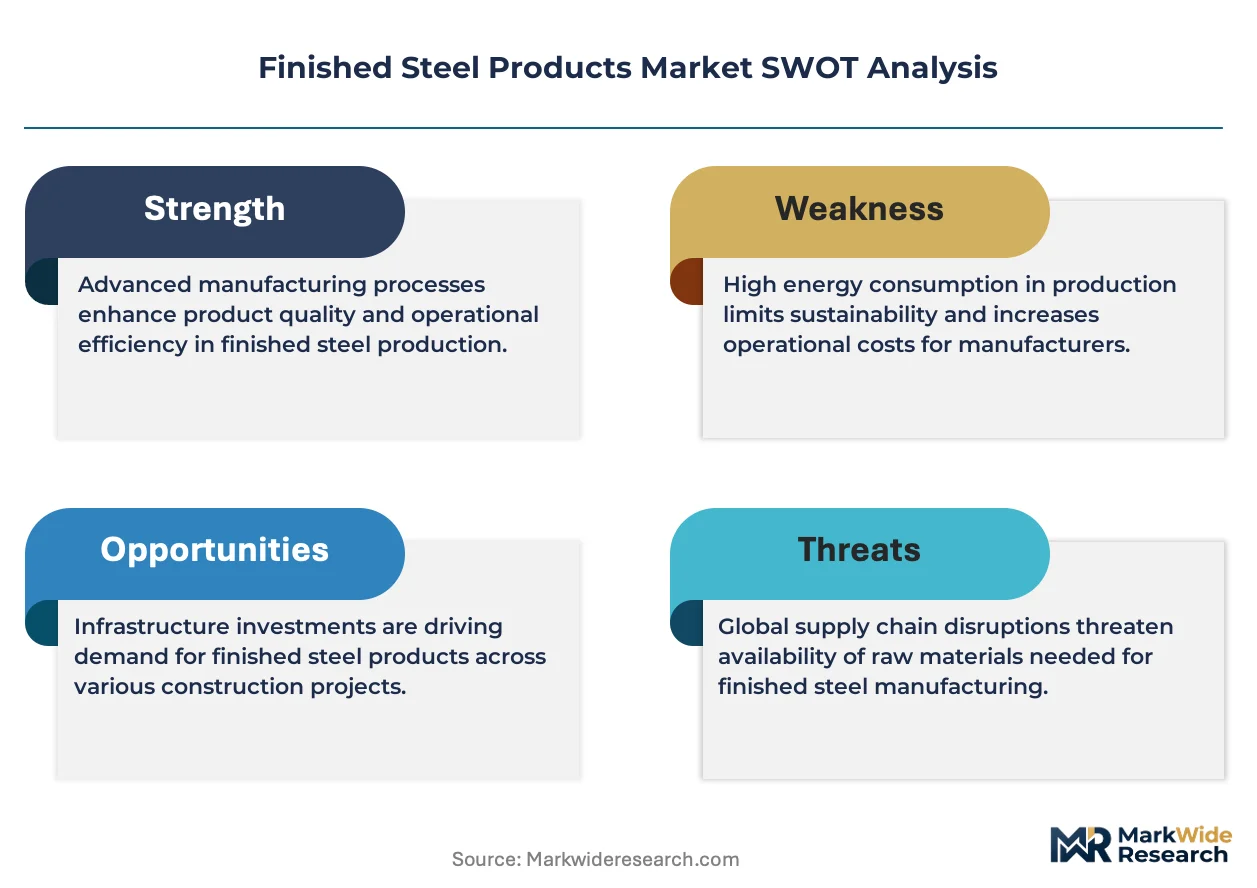
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and excluded regional mills. ArcelorMittal leverages its integrated European production network to sustain premium-grade output. Nucor Corporation anchors its position through electric arc furnace technology leadership and scrap-based circularity. China Baowu Steel Group dominates domestic volume through state-backed consolidation and coastal logistics control.
Finished steel products encompass mill output that has undergone final shaping and surface treatment, typically containing iron with controlled carbon content between 0.02% and 2.1% alongside manganese, silicon, and trace alloying elements, produced through continuous casting followed by hot or cold rolling to achieve specified dimensional tolerances and mechanical properties for load-bearing applications. Carbon steel grades command the largest volume share due to cost efficiency in construction frameworks, while stainless steel commands superior margin pools from chemical processing and medical equipment specifications. Hot rolled forms absorb the majority of tonnage through structural and automotive stampings, whereas cold rolled and galvanized variants capture value-added premiums from appliance and exposed automotive panel requirements.
China's MEE enforces dual carbon goals that cap blast furnace emissions and redirect investment toward hydrogen-based direct reduction. The EU Green Deal and F-Gas Regulation tighten embodied carbon standards for imported steel, reshaping trade flows and mill certification requirements. India's BIS mandates product conformity for structural grades under national building codes. Stakeholders must monitor which regulatory convergence between carbon border adjustments and domestic green procurement rules determines competitive access across major demand centers.
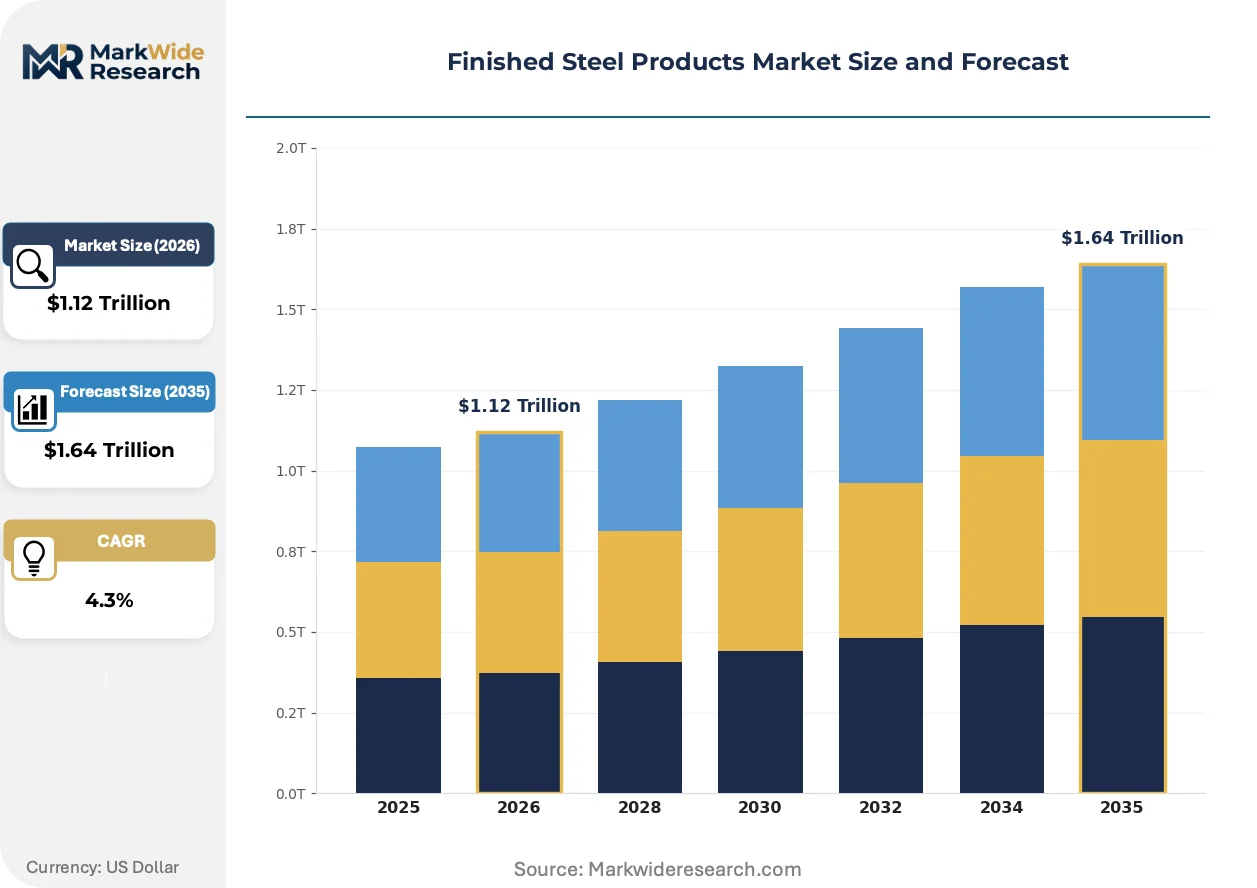
Market Dynamics
Blast furnace emission caps under China's dual carbon goals are forcing capital reallocation toward hydrogen-based direct reduction, compressing traditional integrated mill margins while elevating scrap-based electric arc furnace operators.
Growth Catalysts
- India's infrastructure buildout:National highway corridors and metro rail expansions under the National Infrastructure Pipeline absorb structural long products at scale.
- EU Green Deal embodied carbon standards:The Carbon Border Adjustment Mechanism redirects import flows toward certified low-carbon suppliers, creating premium tier access.
- Scrap-based circularity:Electric arc furnace technology advances in North American flat-rolled production, cutting Scope 3 emissions for automotive OEM procurement mandates.
Market Restraints
- Iron ore supply concentration:Australian and Brazilian seaborne ore markets expose integrated mills to freight volatility and geopolitical chokepoints.
- China's blast furnace capacity limits:MEE emission enforcement caps domestic output growth despite residual demand, forcing price-floor volatility.
- Aluminum substitution in automotive:OEM lightweighting programs displace cold-rolled advanced high-strength steel in hood and door applications.
Strategic Opportunities
- Vietnam's underpenetrated construction-grade demand:FDI manufacturing relocation and port infrastructure expansion outpace domestic mill capacity.
- Green hydrogen direct reduction:Pilot projects in Sweden and Germany converge renewable power with shaft furnace technology for near-zero primary steel.
- BIS certification arbitrage:India's mandatory IS 1786 and IS 2062 compliance creates margin capture for qualified importers against non-certified regional supply.
Industry Challenges
- Skilled furnace operator shortage:Electric arc furnace process control and hydrogen DRI commissioning outpace vocational training pipeline output.
- ISO 9001 certification timeline compression:Multi-site mill audits and documentation gaps delay qualification for EU and Middle East export tenders.
- Legacy ERP integration:Carbon accounting modules and supply chain traceability platforms conflict with installed MES architectures at decades-old integrated plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finished Steel Products Market |
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.64 Trillion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Sheets, Coils, Plates End User: Construction, Automotive, Machinery, Energy Grade: Stainless Steel, Carbon Steel, Alloy Steel, Tool Steel Form: Cold Rolled, Hot Rolled, Galvanized, Painted |
| Companies Covered | POSCO, JFE Steel, China Baowu Steel Group, HBIS Group, Nucor Corporation, ArcelorMittal, Tata Steel, Steel Dynamics, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finished Steel Products Market Emerging Trajectories
Decarbonization technology maturation is bifurcating the supplier base between hydrogen-ready assets and stranded blast furnace capacity, while regulatory convergence on embodied carbon reshapes procurement qualification criteria.
Hydrogen-based direct reduction combined with electric arc furnace finishing is displacing blast furnace-basic oxygen furnace routes in premium automotive and appliance-grade flat-rolled supply. European and Korean automakers now mandate near-zero emission steel in supplier contracts, compressing the qualified supplier pool. This displacement is fragmenting the market into certified low-carbon tier and conventional commodity tier with widening price spreads.
The EU F-Gas Regulation and Carbon Border Adjustment Mechanism impose lifecycle emission disclosure requirements on imported steel and aluminum products. Mills must now submit verified Product Carbon Footprint data to customs authorities, with non-compliant shipments facing tariff penalties. Indian and Turkish exporters are accelerating ISO 14064 certification and third-party verification to maintain European market access.
Automotive OEM procurement departments now unbundle steel supply from legacy mill-direct contracts toward toll-processing arrangements with independent service centers. Tier-1 stampers in Germany and the US Midwest increasingly source master coils through digital spot platforms, displacing annual volume commitments. This channel shift concentrates price discovery power with large fleet buyers while compressing service margins at traditional distributors.
Finished Steel Products Market Segmentation
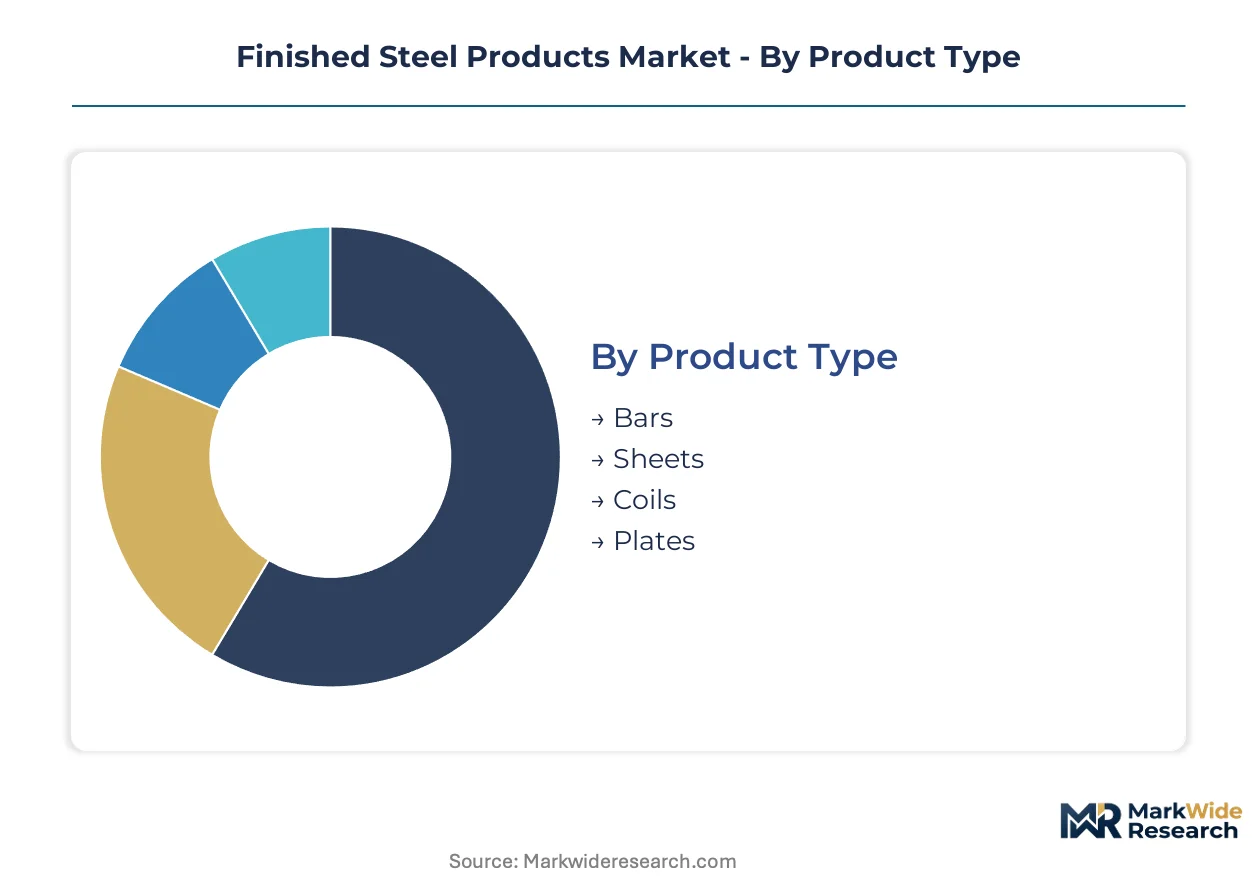
Finished steel products fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct margin structures, certification requirements, and geographic demand patterns that reshape supplier qualification criteria.
Product Type:
Domestic construction absorbs bars and plates through national infrastructure programs, while sheets and coils flow disproportionately into export-oriented manufacturing clusters.
- Sheets:Flat-rolled products under 6mm thickness serve automotive stampings and appliance panels. German and Korean OEMs now mandate near-zero emission certificates for coil supply, compressing the qualified supplier pool.
- Bars:Long products with circular, square, or hexagonal cross-sections reinforce concrete frameworks and machined components. India's National Infrastructure Pipeline consumes structural rebar at scale, outpacing domestic mill capacity.
- Coils:Continuously wound flat products enable high-speed processing at service centers and tier-1 stampers.
- Plates:Thick flat products above 6mm thickness support shipbuilding, pressure vessels, and heavy equipment fabrication.
Sheets holds the largest share; momentum sits with bars.
End User:
Cost tier separation runs deepest here, with automotive and energy commanding premium certified grades while construction absorbs commoditized tonnage.
- Construction:Structural frameworks, rebar, and piling absorb the majority of long product volume. Vietnam's port infrastructure expansion and metro rail buildout outpace domestic mill capacity, creating import dependency.
- Automotive:Advanced high-strength steel for body-in-white and chassis applications faces displacement pressure from aluminum lightweighting in hood and door panels.
- Machinery:Precision-ground shafts, gears, and tooling demand controlled dimensional tolerances and surface finish specifications.
- Energy:Line pipe, wind tower sections, and offshore platform grades require sour gas resistance and sub-zero toughness certifications.
Construction dominates volume; automotive captures the steepest margin expansion trajectory.
Grade:
Supply concentration varies sharply by metallurgical complexity, with carbon steel available from fragmented regional mills and specialty grades controlled by integrated producers.
- Carbon Steel:Iron-carbon alloys between 0.02% and 2.1% carbon content deliver cost-efficient strength for construction frameworks and general fabrication. Chinese blast furnace emission caps under MEE enforcement constrain domestic output growth despite residual demand.
- Stainless Steel:Chromium-nickel alloys with minimum 10.5% chromium content command superior margin pools from chemical processing, medical equipment, and food handling specifications.
- Alloy Steel:Controlled additions of molybdenum, vanadium, or nickel enhance hardenability and high-temperature performance for power generation and aerospace applications.
- Tool Steel:High-carbon, high-alloy grades optimized for wear resistance and dimensional stability in cutting, forming, and die-casting operations.
Carbon steel holds the largest share; stainless steel is gaining share fastest.
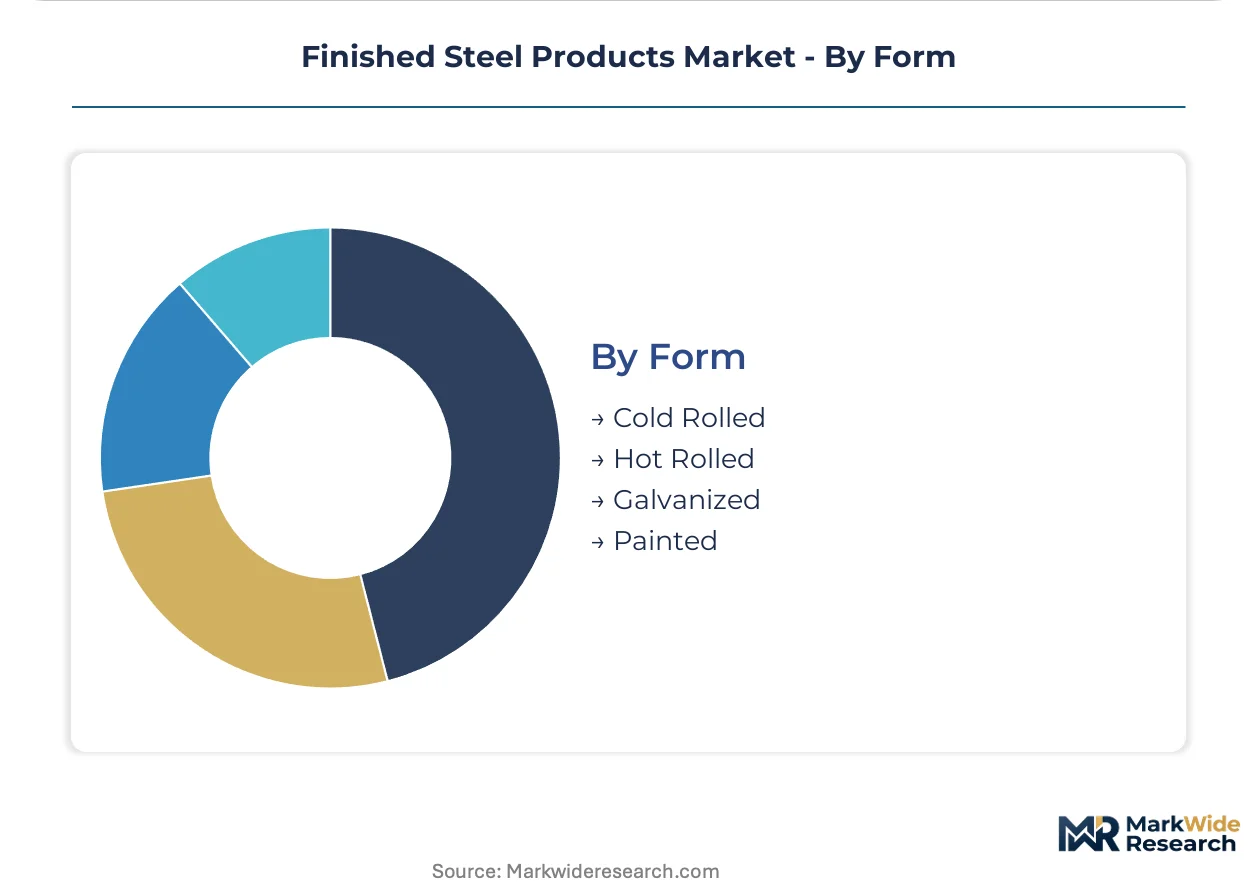
Form:
Customer type bifurcation separates hot-rolled commodity buyers from cold-rolled and coated purchasers with exacting surface quality requirements.
- Hot Rolled:Mill-finished products shaped above recrystallization temperature absorb the majority of structural and automotive stamping tonnage. Southeast Asia's construction activity drives consumption through national highway corridors and commercial development.
- Cold Rolled:Gauge-reduced and surface-finished products capture value-added premiums from exposed automotive panels and precision appliance components.
- Galvanized:Zinc-coated products provide corrosion protection for outdoor construction, HVAC ducting, and agricultural equipment.
- Painted:Pre-coated products eliminate downstream finishing steps for building cladding, appliance exteriors, and signage applications.
Hot rolled holds the largest share; cold rolled shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon border adjustments and green procurement mandates are redirecting capital flows and trade patterns across major steel-consuming economies. National infrastructure programs and emission enforcement regimes now determine competitive access more than raw material proximity.
China
MEE emission caps under dual carbon goals constrain blast furnace output growth despite residual construction and manufacturing demand. Coastal mill clusters in Jiangsu and Hebei provinces face forced capacity rationalization while hydrogen DRI pilot projects advance in Baoshan. State-backed consolidation through China Baowu Steel Group concentrates domestic volume control.
India
National Infrastructure Pipeline highway corridors and metro rail expansions absorb structural long products at volumes exceeding domestic mill capacity. BIS mandates IS 1786 and IS 2062 conformity for structural grades under national building codes, creating qualification barriers for uncertified regional supply. Odisha and Jharkhand ore belts anchor integrated production expansion.
United States
Electric arc furnace technology leadership in flat-rolled production cuts Scope 3 emissions for automotive OEM procurement mandates. EPA enforcement and state-level clean energy standards accelerate scrap-based circularity adoption. Nucor Corporation and Steel Dynamics anchor Southeastern and Midwestern mini-mill corridors with riverine scrap logistics.
Germany
EU Green Deal embodied carbon standards and Carbon Border Adjustment Mechanism redirect import flows toward certified low-carbon suppliers. Thyssenkrupp and Salzgitter pilot hydrogen-based direct reduction in Duisburg and Peine, converging renewable power with shaft furnace technology. Automotive OEM near-zero emission steel contracts compress the qualified supplier pool.
Vietnam
FDI manufacturing relocation and port infrastructure expansion outpace domestic mill capacity, creating import dependency for construction-grade tonnage. Formosa Ha Tinh Steel anchors central coast production while northern demand concentrates around Hanoi-Hai Phong industrial corridors. National highway buildout and metro construction absorb structural rebar at scale.
Finished Steel Products Market Vendor Landscape
Player mix skews toward integrated multinational producers with blast furnace-basic oxygen furnace assets and scrap-based electric arc furnace operators with regional feedstock control. Market structure bifurcates between certified low-carbon tier suppliers commanding premium automotive and appliance contracts and commodity tier mills exposed to price-floor volatility. Strategic archetypes include hydrogen-ready integrated producers, mini-mill circularity specialists, and state-backed volume consolidators. Dominant competitive moves center on emission-compliant capacity expansion and backward integration into renewable power and hydrogen supply.
Within the state-backed consolidation archetype, China Baowu Steel Group and HBIS Group exemplify volume-driven positioning through domestic merger integration and coastal logistics control. Among scrap-based circularity specialists, Nucor Corporation and Steel Dynamics occupy positions anchored by electric arc furnace technology leadership and North American flat-rolled production scale. POSCO and JFE Steel sit within the hydrogen-transition tier, representing Korean and Japanese integrated producers advancing direct reduction pilot projects to meet automotive OEM near-zero emission procurement mandates.
| Leading Market Players |
|---|
| POSCO |
| JFE Steel |
| China Baowu Steel Group |
| HBIS Group |
| Nucor Corporation |
| ArcelorMittal |
| Tata Steel |
| Steel Dynamics |
| Nippon Steel Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day order-to-delivery windows for hot-rolled coil concentrate pricing power with coastal mill clusters in China and South Korea, while inventory buffers at European service centers compress when blast furnace output tightens under MEE emission enforcement. This lead-time band ties directly to supply-chain shape: where hydrogen DRI pilot projects lag commissioning schedules, spot premiums widen for certified low-carbon grades.
Pricing Analysis
Certification level under ISO 14064 and EU CBAM compliance creates the primary spread between qualified low-carbon suppliers and conventional commodity tier mills. Three-tier pricing structure across premium certified, standard mill-direct, and economy spot-grade levels dominates contract negotiations. Pricing pressure stems from aluminum substitution in automotive lightweighting programs, compressing cold-rolled advanced high-strength steel margins. Construction-grade rebar buyers exhibit highest price sensitivity, while German and Korean automotive OEM procurement teams accept certified-grade premiums for near-zero emission supply.
Supply Chain Analysis
China and Australia anchor seaborne iron ore supply, with Brazilian volumes providing swing capacity for Atlantic basin mills. Integrated producers draw from Australian Pilbara fines, Brazilian Carajás lump, and domestic Chinese concentrates for sinter feed blending. Single-source vulnerability concentrates in Australian ore export terminals, where weather disruptions and geopolitical friction amplify freight volatility. Distribution runs through mill-direct annual contracts, digital spot platforms, and independent service centers with toll-processing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finished steel products markets cycle with infrastructure investment waves and emission policy enforcement intensity. India's National Infrastructure Pipeline and Vietnam's port expansion programs currently drive demand recovery, while China's MEE caps constrain supply response.
For Market Incumbents: Consolidate hydrogen-ready asset positions through selective DRI-EAF capacity additions in coastal European and Indian clusters. ArcelorMittal and POSCO demonstrate this path. Defend against scrap-based mini-mill encroachment by locking renewable power offtake for shaft furnace electrification. Certification investment in ISO 14064 verification preserves EU CBAM market access against Turkish and Indian export competition. For New Entrants and Emerging Players: Toll-processing service gaps at German and US Midwest tier-1 stampers offer white-space entry where legacy mill-direct contracts fragment. Target Vietnam's underpenetrated construction-grade demand, where FDI manufacturing relocation outpaces domestic Formosa Ha Tinh capacity. Digital spot platform participation enables price discovery without captive melt shop investment, lowering capital barriers versus integrated mill replication. For Investors and Strategic Acquirers: Long-term, this sits as a green-transition infrastructure play because carbon border adjustments and automotive OEM procurement mandates structurally favor certified low-carbon capacity. Acquisition targets should screen for hydrogen DRI project pipelines, renewable power integration, and existing ISO 14064 certification. The signal to watch is EU CBAM tariff implementation pace, which determines premium-tier pricing power duration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen DRI Capacity Buildout | Swedish and German pilot projects converge renewable power with shaft furnaces for near-zero primary steel output. |
| ISO 14064 Certification Acceleration | Indian and Turkish exporters secure EU CBAM compliance to maintain European market access against tariff penalties. |
| Scrap-Based Circular Expansion | Nucor and Steel Dynamics anchor North American mini-mill corridors with riverine logistics and automotive OEM contracts. |
| Digital Spot Platform Integration | Tier-1 stampers in Germany and the US Midwest displace annual volume commitments through coil procurement marketplaces. |
| Renewable Power Backward Integration | European integrated producers lock offshore wind and solar offtake to electrify DRI-EAF routes and cut Scope 2 emissions. |
Methodological Framework
Operator-level perspectives from blast furnace managers, electric arc furnace process engineers, automotive OEM procurement directors, and service center toll-processing operators anchored the qualitative base. Primary fieldwork combined with secondary validation through customs trade data, SEC 10-K filings, BIS certification registries, and EU CBAM implementation guidance. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic infrastructure spending projections.
Sensitivity analysis tested forecast outputs across blast furnace emission enforcement intensity, scrap price volatility, and hydrogen DRI commissioning delays. Segmentation dimensions modeled include product form, metallurgical grade, end-use industry, and regional regulatory cluster. CAGRs derived from installed capacity utilization trends, national infrastructure pipeline commitments, and carbon border adjustment implementation schedules.
Forecasts assume regulatory continuity in EU Green Deal, China's MEE dual carbon enforcement, and India's BIS mandatory certification regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in emission enforcement intensity, infrastructure procurement award timing, and hydrogen supply chain maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Titanium Sponge Market
Metals
Global Tantalum Market
Metals
High Carbon Bearing Steel Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Europe Aluminium Cans Market
Metals
Base Metals Market
Metals
Copper Clad Aluminum Wire Market
Metals
High Purity Lead Market
Metals
Copper Chromium Black Market
Metals
Global Brass Rods Market
Metals
North America and Europe Metal Powder Market
Metals
Aluminium Conductors Market
Metals
Global Oxygen-Free Copper Market
Metals
Global Titanium Metal Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Metal Forging Parts Market