
 Emulsifiers Market | 2026-2036
Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifiers Market Intelligence
European oleochemical producers is recalibrating capacity toward bio-based feedstocks amid tightening REACH compliance. BASF SE leverages integrated oleochemical complexes to sustain cost advantages across glycerol-derived emulsifier lines. Cargill, Incorporated anchors North American supply through backward integration into oilseed crushing and refined oil output. Kerry Group plc differentiates via application-specific formulations targeting plant-based dairy alternatives.
Emulsifiers are surface-active agents containing hydrophilic and lipophilic moieties that reduce interfacial tension between immiscible phases, typically manufactured through esterification of fatty acids with polyols or ethoxylation of natural alcohols. These compounds enable stable dispersion systems in food matrices, cosmetic creams, pharmaceutical suspensions, and coating formulations. Natural emulsifiers dominate value pools as clean-label procurement from food manufacturers tightens specification thresholds for synthetic alternatives. Synthetic emulsifiers retain volume leadership in industrial paints where cost sensitivity outweighs biodegradability preferences. Lecithin segments are capturing fastest growth in pharmaceutical applications as lipid-based drug delivery systems expand.
FDA food additive regulations and EPA chemical safety assessments shape product registration pathways and reformulation timelines in the United States. EFSA purity criteria and EU Green Deal decarbonization mandates are accelerating substitution of petrochemical-derived emulsifiers across member states. India's FSSAI additive standards and BIS quality specifications create compliance layers for import-dependent formulations. Stakeholders must monitor regulatory divergence between jurisdictions to optimize multi-plant certification strategies and avoid stranded inventory positions.
Market Dynamics
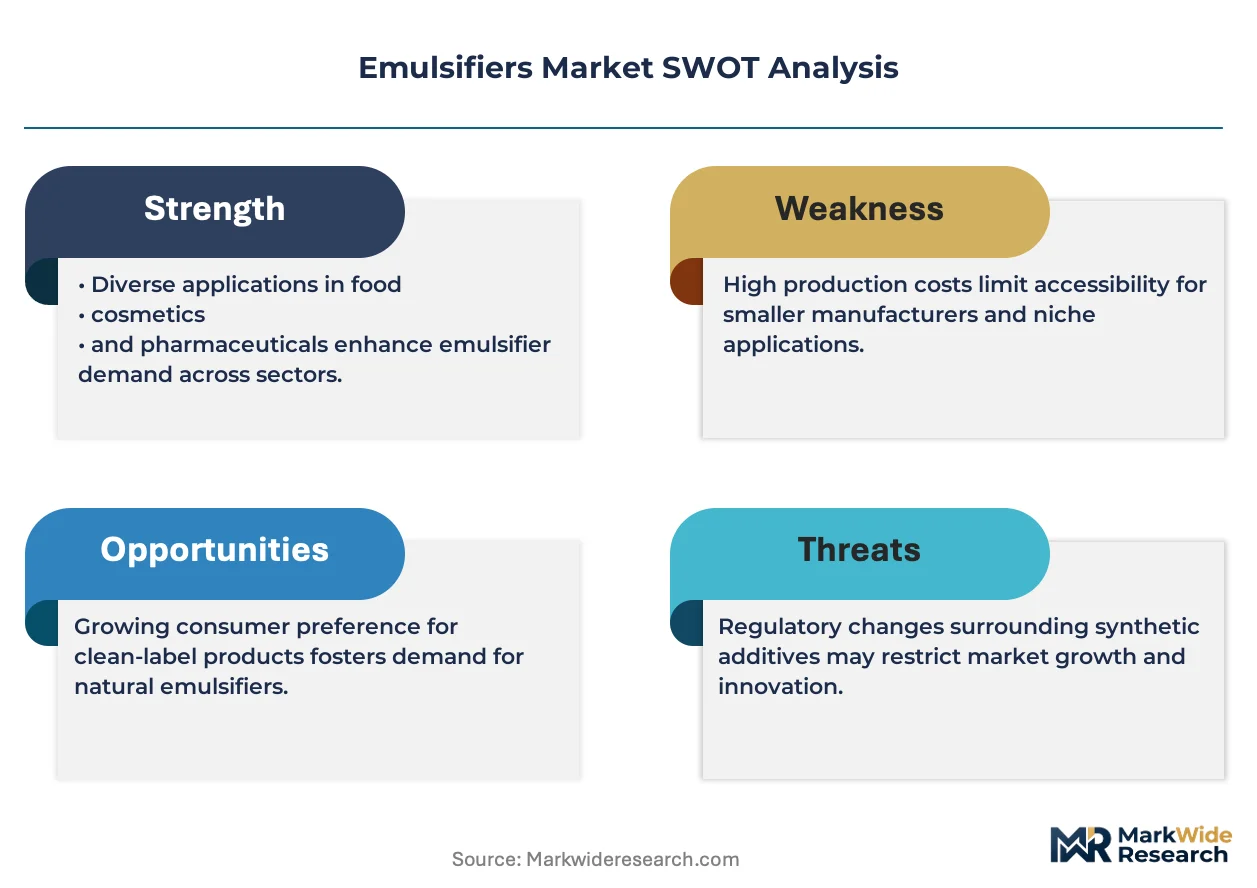
Clean-label procurement mandates from multinational food manufacturers are compressing specification windows for synthetic emulsifiers while accelerating reformulation cycles across bakery, confectionery, and plant-based dairy categories.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for processed food manufacturing is accelerating domestic emulsifier demand as contract manufacturers expand capacity for export-oriented ready-meal production.
- REACH compliance substitution:ECHA's tightening purity criteria for petrochemical-derived surfactants is forcing systematic replacement with bio-based alternatives across EU member state formulations.
- Lipid-based drug delivery:Pharmaceutical formulators are expanding lecithin procurement for nanostructured lipid carriers and self-emulsifying systems targeting bioavailability enhancement.
Market Restraints
- Palm oil price volatility:Natural emulsifier margins compress when Malaysian and Indonesian feedstock costs spike, exposing formulators to input cost cycles beyond hedging reach.
- EU Green Deal carbon accounting:Scope 3 emission disclosure requirements for imported oleochemicals are creating compliance friction for Asian suppliers serving European customers.
- Enzymatic hydrolysis limitations:Current biocatalytic routes to modified lecithins face yield constraints at commercial scale, restricting throughput for high-purity pharmaceutical grades.
Strategic Opportunities
- Sub-Saharan Africa processed food:Underpenetrated markets in Nigeria and Kenya present white space as multinational CPG brands localize production to circumvent import tariff barriers.
- Cell-cultured meat scaffolding:Emerging applications in alternative protein matrix stabilization require novel emulsifier architectures not addressed by incumbent food-grade portfolios.
- EU CSRD reporting mandates:Corporate sustainability disclosure requirements are creating preference premiums for bio-based emulsifiers with verified supply chain traceability.
Industry Challenges
- Food-grade certification timelines:Novel bio-based emulsifiers face extended FSSAI and FDA safety assessment cycles that delay commercialization by 18-36 months.
- Oleochemical process engineering talent:Specialized expertise in enzymatic esterification and membrane fractionation is concentrated among retiring cohorts in European producer facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsifiers Market |
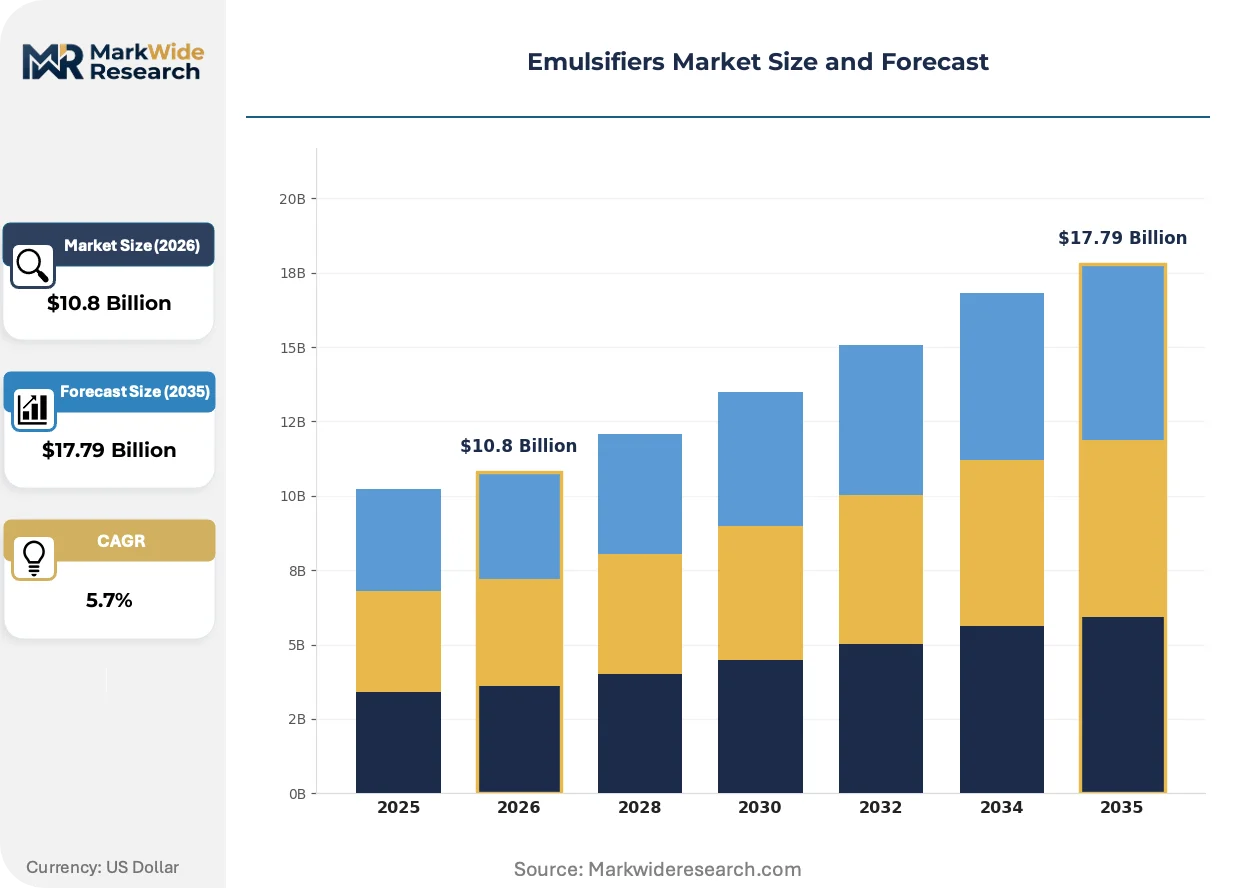
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.79 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Emulsifiers, Synthetic Emulsifiers, Semi-Synthetic Emulsifiers, Lecithin Application: Food & Beverage, Cosmetics, Pharmaceuticals, Paints Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Cosmetics Companies, Pharmaceutical Firms, Paint Producers |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, BASF SE, Evonik Industries AG, Kerry Group plc, Corbion, Stepan Company, Ingredion Incorporated, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifiers Market Strategic Shifts & Innovations
Enzymatic modification processes are displacing chemical esterification across premium emulsifier tiers, while regulatory carbon accounting and procurement digitization reshape competitive requirements simultaneously.
Enzyme-catalyzed interesterification is expanding into high-value lecithin fractions for pharmaceutical and nutraceutical applications. BASF and Cargill are scaling immobilized lipase systems to produce lysophospholipids with precise acyl chain specificity. This biocatalytic route is expanding into food emulsifier lines previously dominated by chemical processing, compressing energy intensity and enabling cleaner label claims.
REACH authorization timelines for ethoxylated surfactants are tightening substitution deadlines for industrial formulators. ECHA's 2024-2027 rolling review of non-ionic surfactants is accelerating petrochemical displacement in coatings and agrochemical emulsifiable concentrates. German and Dutch paint manufacturers are qualifying bio-based alkyl polyglucosides ahead of anticipated restriction proposals.
Direct supplier relationships are displacing distributor intermediaries in North American food emulsifier procurement. Large bakery and confectionery manufacturers are consolidating vendor bases to capture volume pricing and secure allocation during feedstock shortages. This concentration is most visible in Midwest manufacturing corridors where plant-based dairy startups negotiate backward integration into oilseed crushing.
Emulsifiers Market Segmentation
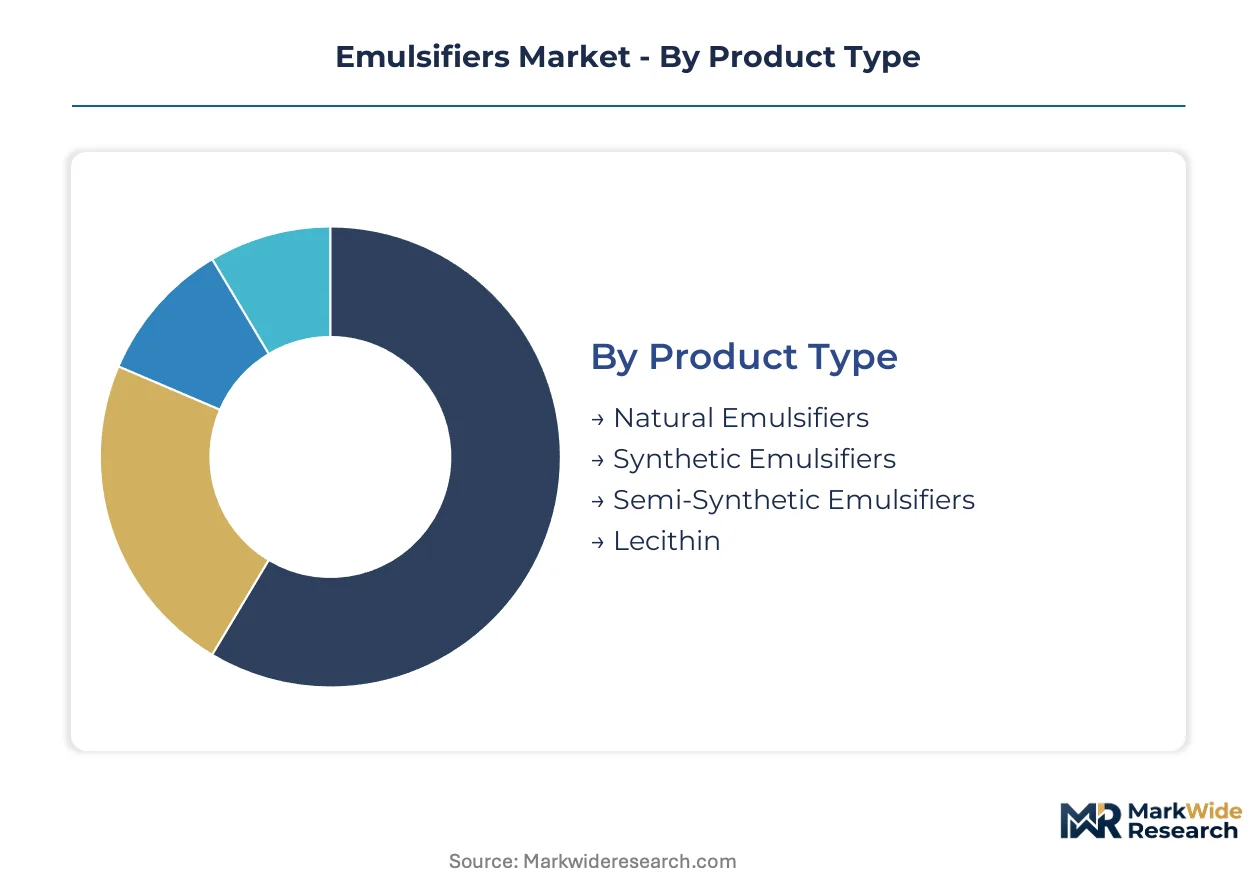
Emulsifier procurement patterns diverge sharply across product chemistry and application requirements. Formulators select emulsifier architectures based on label positioning, processing constraints, and regulatory jurisdiction rather than functional equivalence alone.
Product Type:
Replacement cycles accelerate as clean-label mandates force synthetic-to-natural transitions in food formulations.
- Natural Emulsifiers:Derived from plant gums, proteins, and phospholipid extracts. Food manufacturers in India and Germany are expanding procurement of gum arabic and saponin-based systems as FSSAI and EFSA tighten additive scrutiny.
- Synthetic Emulsifiers:Petrochemical-derived ethoxylates and sorbitan esters dominate industrial paints and cost-sensitive applications. REACH authorization pressures are compressing their viable deployment window across EU member states.
- Semi-Synthetic Emulsifiers:Chemically modified natural feedstocks bridge performance and label requirements. Modified starches and cellulose derivatives serve bakery applications where clean-label claims must coexist with freeze-thaw stability.
- Lecithin:Phospholipid fractions from soybean and sunflower sources. Pharmaceutical formulators are expanding procurement for lipid-based drug delivery systems targeting enhanced bioavailability.
Volume placements concentrate in Synthetic Emulsifiers; the faster expansion belongs to Natural Emulsifiers.
Application:
Cost tiers separate commodity emulsifiers from pharmaceutical-grade specifications.
- Food & Beverage:Bakery, confectionery, and plant-based dairy drive formulation innovation. Asia-Pacific food manufacturers are retrofitting lines for enzymatically modified lecithins to meet clean-label procurement mandates.
- Cosmetics:Skin creams and personal care products require emulsifiers with sensory and stability performance. Korean and French formulators are qualifying bio-based alkyl polyglucosides ahead of anticipated EU restriction proposals.
- Pharmaceuticals:Lecithin fractions enable nanostructured lipid carriers and self-emulsifying drug delivery systems. US and Swiss drug developers are expanding lysophospholipid procurement for bioavailability enhancement.
- Paints:Architectural and industrial coatings rely on cost-optimized ethoxylated surfactants. German and Dutch manufacturers are accelerating bio-based substitution ahead of ECHA's rolling surfactant review.
Food & Beverage captures the largest volume footprint; Pharmaceuticals is climbing the fastest.
Form:
Customer handling infrastructure dictates form selection more than functional performance.
- Powder:Free-flowing particulates suit dry-mix applications and extended shelf-life requirements. Bakery manufacturers prefer powder lecithin for flour premix integration.
- Liquid:Pumpable concentrates dominate high-throughput food processing. Fluid lecithin serves oil-in-water emulsion systems in mayonnaise and dressing production.
- Granular:Low-dust handling properties address occupational exposure concerns. Granular soy lecithin is displacing powder forms in Midwest US manufacturing corridors.
- Paste:High-viscosity semisolids suit specialized pharmaceutical and cosmetic compounding. Paste phospholipids enable precise dosing in topical formulation suites.
Volume concentrates in Liquid forms; Powder is gaining share fastest in clean-label retrofit applications.
End User:
Supply concentration varies by end-user technical sophistication and certification burden.
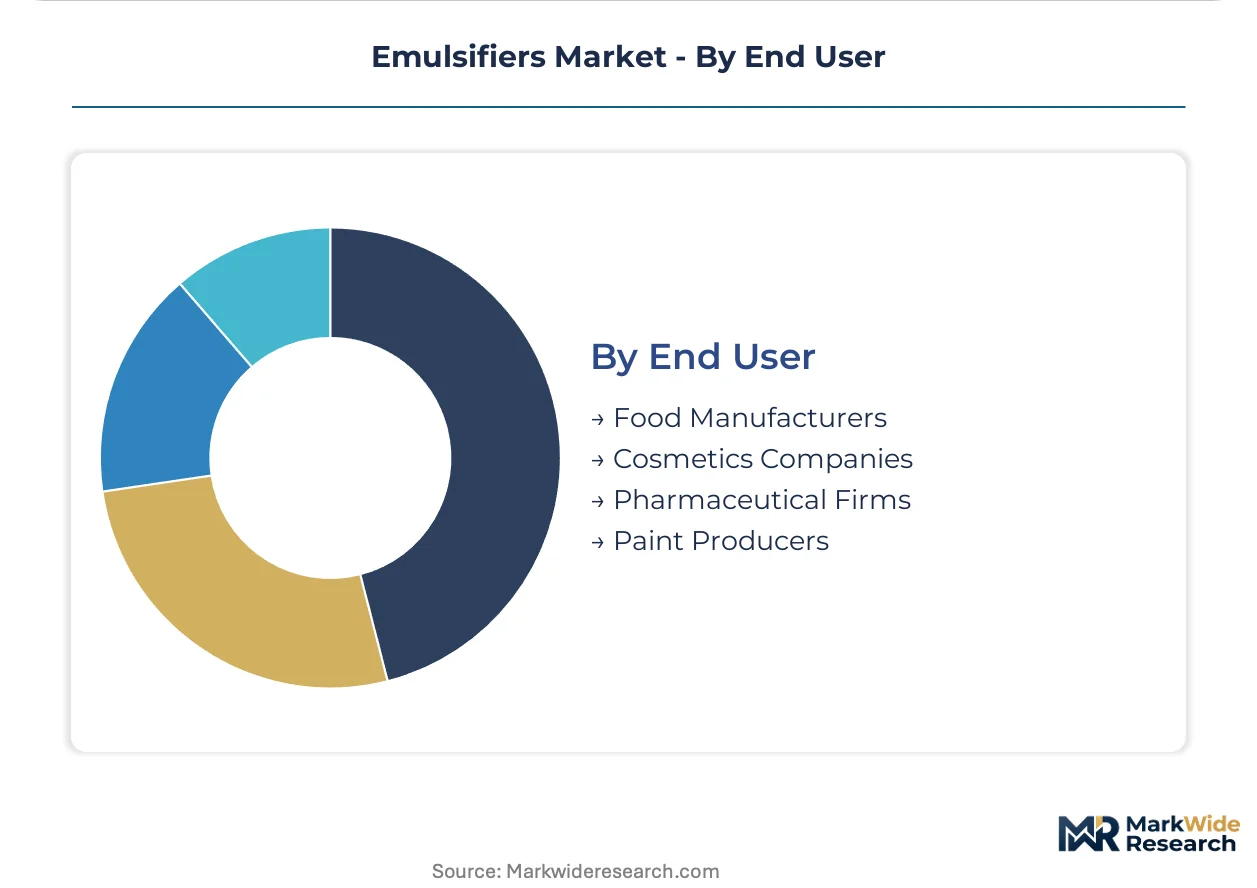
- Food Manufacturers:Multinational CPG brands and contract manufacturers drive specification tightening. Indian PLI scheme beneficiaries are expanding emulsifier consumption for export-oriented ready-meal production.
- Cosmetics Companies:Formulation houses and brand owners prioritize sensory performance and regulatory compliance. EU CSRD reporting mandates are creating preference premiums for traceable bio-based supply chains.
- Pharmaceutical Firms:Drug developers and CDMOs impose stringent purity and documentation requirements. US FDA and EMA lipid excipient monographs shape procurement qualification timelines.
- Paint Producers:Architectural and industrial coating manufacturers balance cost and performance. REACH substitution deadlines are forcing systematic reformulation across German and Benelux production bases.
Food Manufacturers represent the dominant volume segment; Pharmaceutical Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian palm oil plantations anchor feedstock supply for natural emulsifier production serving global food and pharmaceutical formulators. Regional demand patterns diverge sharply between mature regulatory jurisdictions accelerating bio-based substitution and emerging markets scaling processed food manufacturing.
United States
Midwest oilseed crushing corridors and Gulf Coast oleochemical complexes sustain domestic lecithin and modified phospholipid output. FDA food additive regulations and EPA chemical safety assessments compress registration timelines for novel bio-based entrants. Chicago and Minneapolis manufacturing belts concentrate plant-based dairy startups negotiating backward integration into regional soybean processing.
Germany
Ruhr Valley chemical parks and Hamburg oleochemical terminals anchor EU emulsifier formulation leadership. ECHA REACH authorization timelines and EU Green Deal decarbonization mandates accelerate petrochemical displacement in coatings and food applications. BASF SE leverages Ludwigshafen integrated complexes to sustain glycerol-derived emulsifier cost advantages amid tightening purity criteria.
India
Maharashtra and Gujarat food processing corridors absorb expanding emulsifier volumes under PLI scheme incentives for export-oriented ready-meal production. FSSAI additive standards and BIS quality specifications create compliance layers for import-dependent formulations. Mumbai and Ahmedabad contract manufacturers retrofit lines for enzymatically modified lecithins to meet multinational clean-label procurement mandates.
China
Yangtze River Delta chemical clusters and Shandong Peninsula oleochemical bases dominate regional synthetic and natural emulsifier output. SAMR food safety regulations and dual carbon goals reshape production economics for domestic and export markets. Shanghai and Ningbo formulators qualify bio-based alternatives ahead of anticipated restriction proposals on ethoxylated surfactants.
Brazil
São Paulo state food manufacturing belts and Paraná soybean processing hubs anchor South American emulsifier demand. ANVISA pharmaceutical excipient standards and Mercosur trade protocols shape import substitution strategies. Campinas and Curitiba industrial corridors concentrate bakery and confectionery producers expanding natural emulsifier procurement for regional CPG brand localization.
Emulsifiers Market Key Industry Players
Global majors compete with regional champions across feedstock access and formulation specialization. Market structure tilts toward consolidation at the top tier, with integrated oleochemical conglomerates commanding cost advantages through captive supply of refined oils and glycerol fractions. Three archetypes dominate: backward-integrated agribusiness conglomerates, specialty chemical houses with enzymatic process expertise, and application-focused formulation providers. Competitive intensity centers on M&A targeting regional distribution networks and strategic partnerships securing non-GMO and organic feedstock certification.
Among integrated agribusiness players, Archer Daniels Midland Company and Cargill, Incorporated exemplify the feedstock-to-formulation archetype through oilseed crushing and refined oil output. BASF SE occupies a position representing European chemical conglomerates with oleochemical complex integration. Kerry Group plc sits within the application-specific formulation tier targeting plant-based dairy alternatives and clean-label retrofit cycles.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| BASF SE |
| Evonik Industries AG |
| Kerry Group plc |
| Corbion |
| Stepan Company |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in Southeast Asian oleochemical processing anchor feedstock-to-formulation pipelines, translating plantation proximity into pricing discipline that multinational buyers struggle to replicate through spot-market sourcing alone.
Pricing Analysis
Warranty and technical service bundling separates pharmaceutical-grade lecithin contracts from unbundled commodity food-grade transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with FDA and EFSA excipient monographs commanding substantial premia over industrial paint specifications. Cost compression in synthetic ethoxylates is intensifying because REACH authorization deadlines compress viable deployment windows. Paint producers exhibit highest price sensitivity due to formulation cost thresholds, while pharmaceutical CDMOs prioritize supply security over unit economics.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for processed food manufacturing are reshaping sourcing patterns toward Maharashtra and Gujarat contract manufacturers. Malaysian and Indonesian palm oil plantations, together with Brazilian soybean crushing corridors, anchor global natural emulsifier feedstock supply. Crude vegetable oil, glycerol fractions, and phospholipid extracts constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian oleochemical complexes exposed to El Niño precipitation disruptions. Distribution runs through regional distributor networks in North America, direct supplier relationships in European food manufacturing, and integrated trading houses serving Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emulsifiers market sits in a technology-transition phase where enzymatic modification processes displace chemical esterification across premium tiers, forcing legacy chemical processors to retool or cede high-margin pharmaceutical and clean-label food segments.
For Market Incumbents: Extend enzymatic process capabilities through acquisition of specialist biocatalysis firms or licensing of immobilized lipase systems to defend against specialty chemical houses capturing pharmaceutical lecithin growth. Lock in non-GMO and organic feedstock certification through backward integration into oilseed crushing or long-term offtake agreements with certified plantation operators. Capacity concentration in Ruhr Valley and Ludwigshafen chemical parks anchors European supply security amid REACH-driven substitution cycles.
For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade lecithin and economy industrial surfactant pricing creates entry space for mid-tier bio-based alternatives targeting cosmetics and plant-based dairy applications. Sub-Saharan Africa processed food manufacturing corridors in Nigeria and Kenya offer white-space expansion as multinational CPG brands localize production to circumvent import tariff barriers. Qualify enzymatically modified lecithin formulations ahead of anticipated EFSA and FSSAI tightening to capture first-mover positioning in clean-label retrofit cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor application-specific formulation specialists with enzymatic process expertise in European chemical parks, where REACH compliance costs strain mid-tier chemical processors. Long-term viability over the coming decade hinges on securing bio-based feedstock traceability and pharmaceutical excipient certification that synthetic alternatives cannot replicate. Monitor ECHA rolling surfactant review timelines as inflection indicators for accelerated petrochemical displacement in coatings and agrochemical applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM leverage captive soybean supply to secure non-GMO lecithin certification for pharmaceutical clients. |
| Enzymatic Process Scale-Up | BASF's immobilized lipase systems enable lysophospholipid production with precise acyl chain specificity for lipid-based drug delivery. |
| Clean-Label Formulation Partnerships | Kerry Group's plant-based dairy collaborations capture reformulation cycles as multinational CPG brands retrofit portfolios. |
| Pharmaceutical Excipient Certification | Corbion's EMA and FDA lipid monograph qualifications open CDMO procurement channels for nanostructured lipid carriers. |
| Sub-Saharan Africa Distribution Buildout | Regional trading house partnerships circumvent import tariff barriers serving Nigerian and Kenyan processed food manufacturers. |
Research Approach
Trade databases, SEC 10-K filings, and ECHA REACH authorization records formed the secondary backbone, supplemented by customs data tracking oleochemical feedstock flows and ACC sector reports on surfactant production economics. Primary interviews with plant managers at European oleochemical complexes, procurement leads at downstream food manufacturers, technical R&D directors specializing in enzymatic esterification, and distribution channel partners in Asia-Pacific validated demand assumptions and pricing benchmarks. Bottom-up capacity modeling and top-down consumption estimates triangulated volume and value outputs across the analysis window.
Historical trendline analysis of emulsifier consumption patterns informed projection frameworks spanning product chemistry tiers, application requirements, and regional regulatory clusters. Segmentation dimensions modeled included natural versus synthetic versus semi-synthetic chemistry, food versus pharmaceutical versus industrial end-use, and powder versus liquid versus granular form factors. CAGRs derived from fitted growth curves incorporating PLI scheme incentive trajectories, REACH substitution deadlines, and pharmaceutical lipid delivery system expansion rates.
Inputs from ECHA rolling review timelines and FSSAI additive standard consultations were available through the study window; gaps in proprietary enzymatic process yield data introduce uncertainty bands around pharmaceutical-grade lecithin supply forecasts. Forecasts reflect assumptions regarding palm oil price volatility, EU Green Deal carbon accounting implementation, and enzymatic hydrolysis scale-up timelines that could revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Germany Food Colorants Market