
 Natural Food Additives Market | 2026-2036
Natural Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Additives Market Insights
Modular clean-label ingredient kits is restructuring how food manufacturers configure their additive procurement. Cargill, Incorporated leverages its integrated supply chain from farm to formulation to dominate plant-derived emulsifier availability. Kerry Group plc differentiates through taste-masked natural preservative systems that extend shelf life without synthetic labels. Chr. Hansen Holding A/S specializes in microbial colorants and cultures, anchoring its position in dairy and beverage applications.
Natural food additives comprise functionally active compounds extracted, fermented, or refined from plant, animal, mineral, or microbial sources, typically standardized to specific purity thresholds and declared on ingredient panels as recognizable names rather than E-numbers or chemical designations. These substances serve primarily to preserve safety, enhance sensory properties, or maintain physical stability in processed foods while satisfying clean-label procurement criteria. Colorants derived from beet anthocyanins and turmeric curcumin occupy mature margin pools in confectionery and beverage manufacturing, whereas microbial-sourced preservatives represent the fastest-expanding segment as biotechnology yields shelf-stable alternatives to benzoates and sorbates. Powder formulations lead volume across bakery and dry-mix applications, while liquid delivery systems capture premium positioning in beverage processing lines where dispersion uniformity commands technical specification.
FDA GRAS self-affirmation pathways and USDA organic certification requirements shape product development timelines and label claims for US-market suppliers. EFSA purity standards and EU Green Deal sustainable sourcing mandates restrict acceptable extraction solvents and geographic origin documentation for European commercialization. Stakeholders must monitor evolving definitions of "natural" across jurisdictions, as regulatory divergence between FDA guidance and EU case-law interpretations threatens to fragment formulation strategies and complicate cross-border product registration.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing supplier qualification timelines and forcing additive portfolios toward single-ingredient solutions that satisfy both EFSA purity standards and FDA GRAS pathways simultaneously.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Manufacturers must document geographic origin and extraction solvent profiles, accelerating demand for vertically traceable plant-derived colorants and preservatives.
- Clean-label bakery applications:Industrial bakeries in Germany and France are eliminating synthetic emulsifiers, pulling demand for lecithin and plant-based alternatives through reformulation cycles.
- Biotechnology-enabled microbial preservatives:Fermentation-derived alternatives to benzoates and sorbates are achieving shelf-life parity while bypassing consumer rejection of chemical designations.
Market Restraints
- Raw material concentration risk:Beet anthocyanin supply clusters in Ukrainian and Polish agricultural zones, exposing colorant manufacturers to geopolitical input volatility.
- REACH compliance cost structure:ECHA registration requirements for novel natural extracts impose six-figure toxicology testing burdens that freeze SME innovation pipelines.
- Functional performance gaps:Natural antioxidants demonstrate inferior oxidative stability versus synthetic TBHQ in high-fat applications, limiting penetration in frying oil and snack segments.
Strategic Opportunities
- USDA organic certification tailwinds:Dual-certified organic-natural additives command 40-60% price premiums in US retail channels as private-label organic lines expand.
- Taste-masked preservative systems:Convergence of encapsulation technology and fermentation science enables clean-label shelf extension in neutral-pH beverages previously resistant to natural preservation.
- India FSSAI regulatory harmonization:Streamlined approval pathways for GRAS-affirmed ingredients are opening formulation partnerships with domestic processed food manufacturers.
Industry Challenges
- Fermentation scale-up talent scarcity:Microbial production facilities require hybrid skill sets combining food science and bioprocess engineering that outpace current vocational training output.
- Cross-jurisdictional label claim fragmentation:Divergent FDA and EFSA interpretations of "natural" force dual formulation tracks, inflating SKU complexity and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Additives Market |
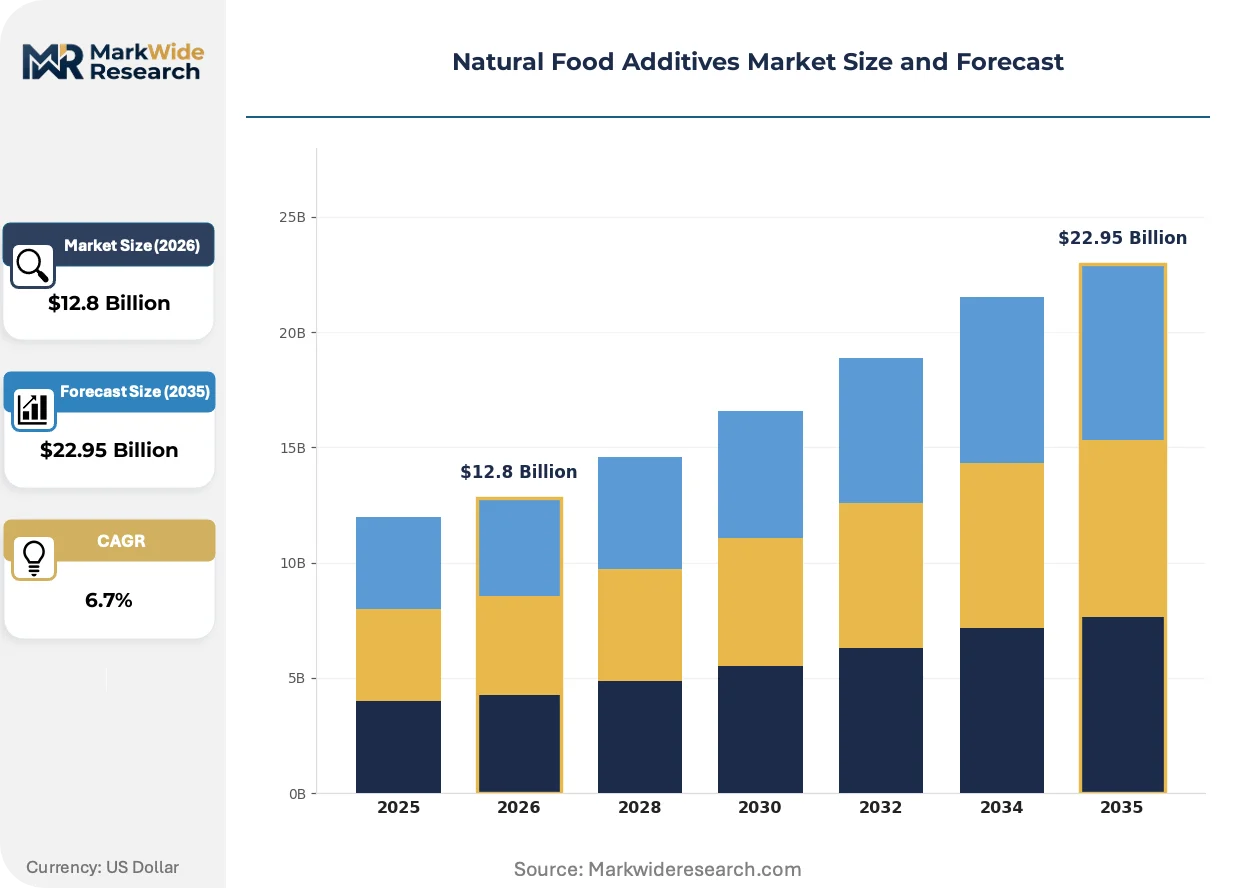
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorants, Preservatives, Emulsifiers, Flavoring Agents Source: Plant-Based, Animal-Based, Mineral-Based, Microbial Application: Beverages, Bakery Products, Dairy, Snacks Form: Powder, Liquid, Gel, Granules |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, BASF SE, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, Givaudan SA, Chr. Hansen Holding A/S, International Flavors & Fragrances, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Additives Market Trends and Innovations
Biotechnology and precision fermentation are collapsing the cost and performance gaps between natural and synthetic additives, while regulatory divergence between major markets is fragmenting formulation strategies.
Precision fermentation platforms producing high-purity natural preservatives are decentralizing production geography away from concentrated agricultural supply zones. Mid-sized ingredient houses in Denmark and the Netherlands are deploying modular bioreactor systems that bypass dependency on seasonal botanical harvests. This distributed manufacturing model is compressing lead times from 12-18 months to 8-12 weeks for custom preservative blends.
EFSA's 2023 updated guidance on extraction solvent residues is tightening permissible thresholds for ethyl acetate and hexane in plant-derived colorants. Manufacturers must revalidate existing supply chains or switch to supercritical CO2 processes, adding 15-25% to production costs. Dairy and confectionery applications in France and Italy face the steepest reformulation pressure given their reliance on legacy anthocyanin sources.
Ingredient buyers at multinational food manufacturers are consolidating supplier panels from 15-20 vendors to 5-8 strategic partners capable of delivering integrated clean-label systems. This concentration is displacing commodity spot purchasing with multi-year framework agreements that bundle R&D support, regulatory documentation, and volume guarantees. The shift is most advanced in German and Swiss headquarters of European food conglomerates.
Natural Food Additives Market Segmentation
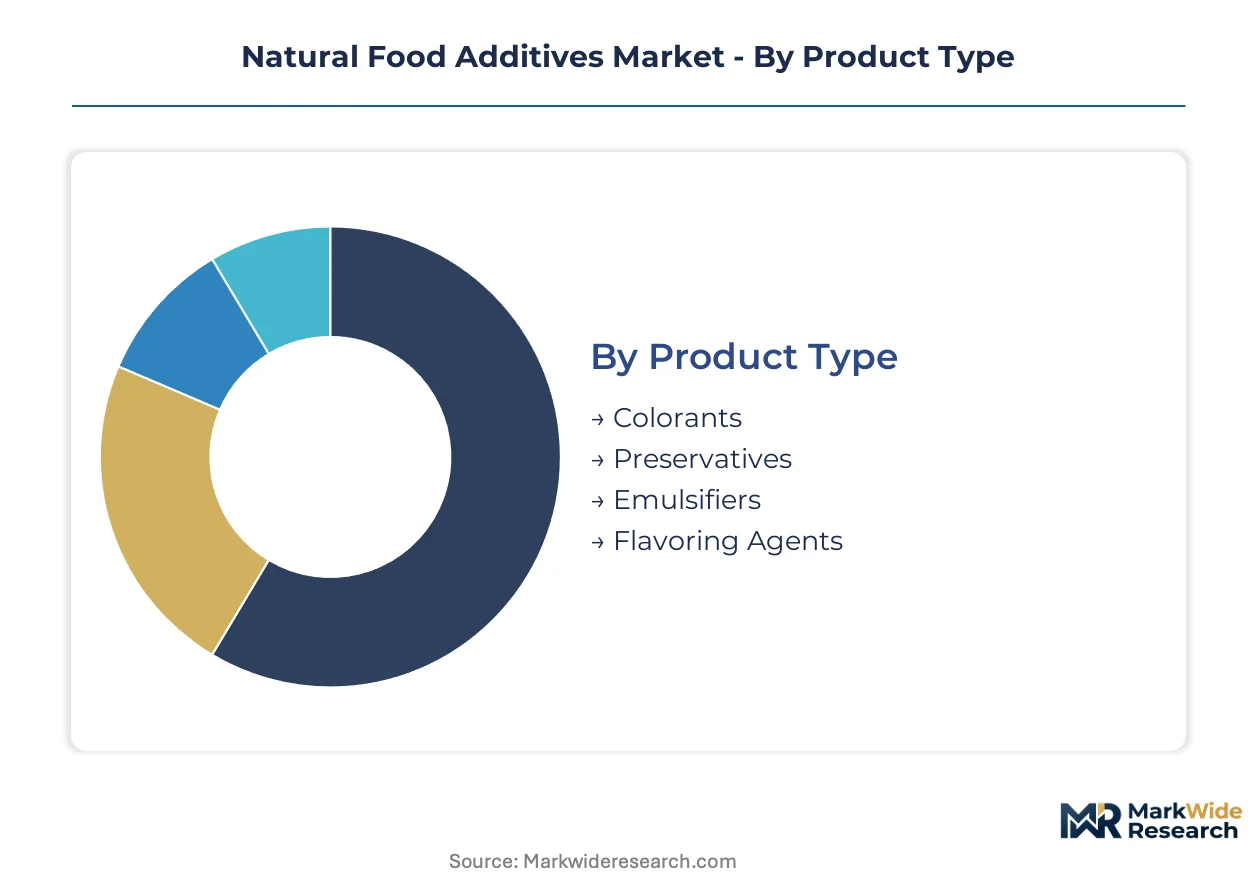
Segmentation in natural food additives reveals how regulatory certification burdens cluster around specific product categories and source types. Manufacturers configure procurement strategies around which segments demand simultaneous FDA GRAS and EFSA compliance versus single-jurisdiction pathways.
Product Type:
Colorants and preservatives carry the heaviest certification loads, requiring dual documentation for cross-Atlantic distribution, while emulsifiers and flavoring agents navigate lighter regulatory frameworks in most formulations.
- Colorants:Beet anthocyanins and turmeric curcumin dominate confectionery and beverage manufacturing. Demand concentrates in German and French dairy applications where EFSA's updated extraction solvent guidance is forcing supercritical CO2 process adoption.
- Preservatives:Fermentation-derived alternatives to benzoates and sorbates achieve shelf-life parity through biotechnology. Clean-label mandates from German retailers are accelerating reformulation cycles in neutral-pH beverages previously resistant to natural preservation.
- Emulsifiers:Plant-derived lecithin and specialty emulsifiers serve industrial bakery applications eliminating synthetic alternatives.
- Flavoring Agents:Natural extracts and essential oils enhance sensory profiles across processed food categories with streamlined regulatory pathways.
Colorants sit at the top of the volume ranking, with preservatives climbing the fastest.
Source:
Cost tiers separate source categories, with microbial fermentation commanding premium positioning against commodity botanical extraction.
- Plant-Based:Standardized extracts from beets, turmeric, and other botanicals supply mature margin pools. Ukrainian and Polish agricultural zones concentrate beet anthocyanin feedstock, exposing manufacturers to geopolitical input volatility.
- Microbial:Precision fermentation platforms decentralize production geography through modular bioreactor systems. Danish and Dutch ingredient houses compress lead times from seasonal harvest dependencies to continuous manufacturing cycles.
- Animal-Based:Marine and dairy-derived functional ingredients serve specialized applications in premium formulations.
- Mineral-Based:Purified mineral salts and natural acidulants provide cost-effective functional solutions across mass-market segments.
Plant-based sources dominate current volume, with microbial alternatives gaining share fastest through biotechnology scale-up.
Application:
Application segmentation tracks how clean-label pressure intensity varies by end-use category and retailer procurement mandates.
- Bakery Products:Industrial bakeries in Germany and France are eliminating synthetic emulsifiers, pulling demand for lecithin and plant-based alternatives through accelerated reformulation cycles mandated by retail partners.
- Beverages:Neutral-pH drinks previously resisted natural preservation due to microbial stability gaps. Convergence of encapsulation technology and fermentation science now enables clean-label shelf extension in this high-volume category.
- Dairy:Anthocyanin colorants and microbial cultures anchor positioning in yogurt and fermented milk applications facing steep EFSA reformulation pressure.
- Snacks:Natural antioxidants demonstrate inferior oxidative stability versus synthetic TBHQ in high-fat frying applications, limiting penetration despite clean-label demand.
Bakery products command the largest additive volume, with beverages expanding most quickly as preservation technology matures.
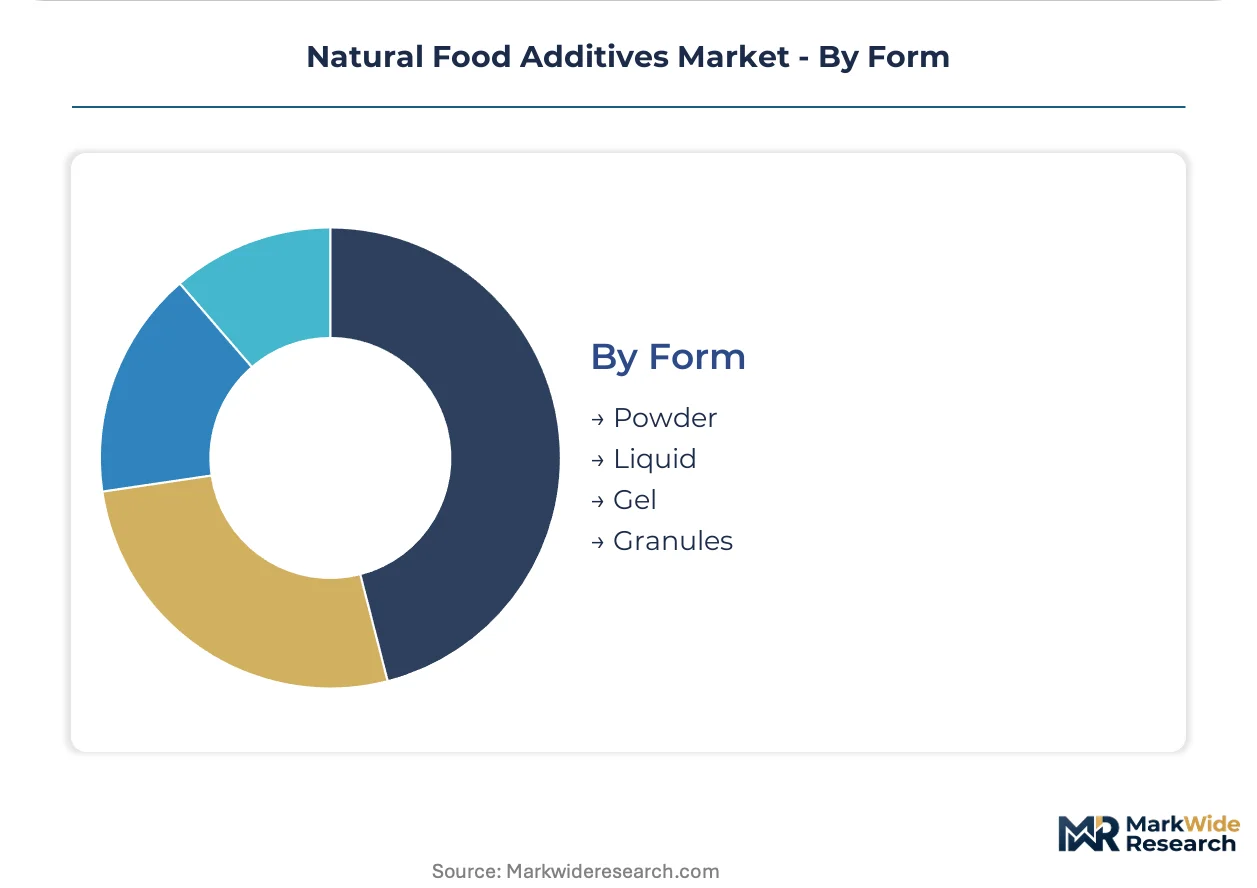
Form:
Form selection determines manufacturing integration complexity and dispersion uniformity requirements across processing lines.
- Powder:Dry-mix and bakery applications favor powder formulations for handling efficiency and storage stability. Volume leadership reflects compatibility with existing industrial infrastructure.
- Liquid:Beverage processing lines command premium positioning for liquid delivery systems where dispersion uniformity dictates technical specifications and batch consistency.
- Gel:Specialized applications in confectionery and texture-modified products leverage gel matrices for controlled release and processing tolerance.
- Granules:Intermediate form factors bridge powder handling advantages with liquid dispersion performance in select manufacturing configurations.
Powder formulations lead by volume, with liquid systems capturing the steepest value-per-kilogram trajectory in premium beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural food additives trace their industrial lineage to nineteenth-century European botanical extraction houses in France and Germany, where standardized plant-derived colorants first achieved commercial scale for confectionery and dairy applications.
Germany
Industrial bakeries in Hamburg and Frankfurt supply corridors are eliminating synthetic emulsifiers under retailer clean-label mandates. ECHA REACH compliance requirements impose six-figure toxicology testing burdens that freeze SME innovation pipelines. Ingredient manufacturers cluster around Hamburg's port infrastructure for beet anthocyanin import processing.
United States
FDA GRAS self-affirmation pathways shape product development timelines for plant-derived preservatives and colorants. USDA organic certification requirements command 40-60% price premiums in retail channels as private-label organic lines expand. Midwest agricultural zones supply commodity botanical feedstock for standardized extract production.
France
Dairy and confectionery applications in Lyon and Paris basin face steep reformulation pressure from EFSA's 2023 updated extraction solvent guidance. French industrial buyers are consolidating supplier panels from 15-20 vendors to 5-8 strategic partners. Supercritical CO2 process adoption adds 15-25% to production costs for legacy anthocyanin sources.
Denmark
Precision fermentation platforms decentralize production geography through modular bioreactor systems bypassing seasonal harvest dependencies. Danish ingredient houses compress lead times from 12-18 months to 8-12 weeks for custom preservative blends. Copenhagen's biotechnology corridor anchors microbial-sourced natural preservative development.
India
FSSAI regulatory harmonization with GRAS-affirmed ingredients opens formulation partnerships with domestic processed food manufacturers. Streamlined approval pathways accelerate market entry for fermentation-derived additives. Maharashtra and Gujarat industrial zones concentrate contract manufacturing for export-oriented natural extract processing.
Natural Food Additives Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive supply chains from farm to formulation. Three to five strategic archetypes dominate: diversified ingredient houses with fermentation capabilities, specialized microbial culture developers, and commodity extract processors with geographic sourcing advantages. Dominant competitive moves include backward integration into agricultural supply zones and multi-year framework agreements bundling R&D support with volume guarantees.
Within the integrated supply chain tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify archetypes spanning commodity origination through formulated ingredient delivery. Kerry Group plc occupies a position representing taste-masked preservative system specialization. These anchors demonstrate how scale-driven procurement consolidation favors partners capable of simultaneous FDA GRAS and EFSA compliance documentation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| BASF SE |
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Givaudan SA |
| Chr. Hansen Holding A/S |
| International Flavors & Fragrances, Inc. |
| Others |
Pricing and Supply Chain Analysis
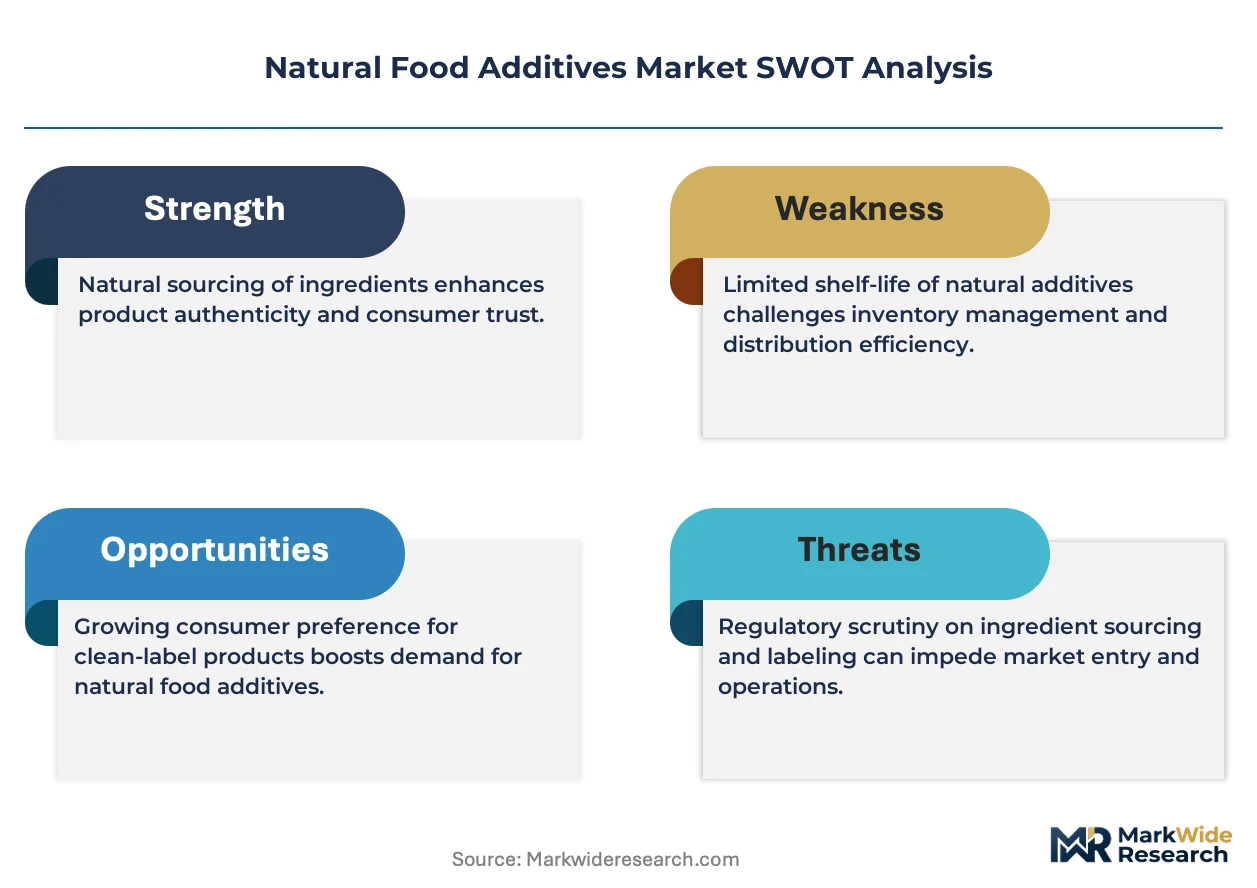
Beet anthocyanin spot prices in Ukrainian and Polish agricultural zones cascade through three distinct procurement tiers, compressing margins for commodity extract processors while fermentation-derived alternatives capture premium positioning through supply security guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates microbial fermentation batches from commodity botanical extracts and mineral-based alternatives. Certification grade under USDA organic and EFSA purity standards drives price differentiation, while volume scale discounts favor multinational food manufacturers with consolidated supplier panels. Cost compression in economy-tier botanical extracts is intensifying because REACH compliance burdens and geopolitical input volatility squeeze spot-market suppliers. Private-label organic lines in US retail channels demonstrate least price sensitivity, whereas industrial bakeries in Germany operating on reformulation timelines show highest sensitivity to lecithin and plant-based emulsifier costs.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam anchor hub-and-spoke patterns for beet anthocyanin feedstock moving from Ukrainian and Polish agricultural zones into German and French dairy processing corridors. Supply draws from concentrated botanical extraction zones in Eastern Europe, precision fermentation facilities in Denmark and the Netherlands, and Midwest agricultural regions in the United States for commodity lecithin. Single-source vulnerability in Ukrainian beet harvests exposes colorant manufacturers to geopolitical disruption. Distribution runs through integrated ingredient houses bundling R&D support with volume guarantees rather than commodity spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural food additives function as a stable compounder anchored by irreversible clean-label mandates from major European retailers that lock in reformulation demand across bakery, beverage, and dairy categories.
For Market Incumbents: Anchor defensive positioning through backward integration into beet anthocyanin agricultural zones in Poland and Ukraine to secure feedstock against geopolitical volatility, while expanding fermentation capacity in Denmark's biotechnology corridor to capture microbial preservative growth. Certification investment in simultaneous FDA GRAS and EFSA compliance documentation preserves multi-year framework agreement eligibility as supplier panels consolidate from fifteen to eight strategic partners. For New Entrants and Emerging Players: Begin with modular bioreactor deployment for custom preservative blends targeting neutral-pH beverage manufacturers in Germany and France previously resistant to natural preservation due to microbial stability gaps. White-space concentration in taste-masked natural preservative systems for clean-label shelf extension offers penetrable entry, with go-to-market leverage through partnerships with domestic processed food manufacturers in Maharashtra and Gujarat industrial zones. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation specialists combining hybrid food science and bioprocess engineering capabilities that outpace current vocational training output. Long-term viability over a five-to-ten-year window favors acquisition targets with validated microbial production platforms and existing GRAS-affirmation pathways. Watch EFSA extraction solvent guidance evolution as the inflection signal—tightened ethyl acetate and hexane thresholds forcing supercritical CO2 process adoption will accelerate consolidation among legacy anthocyanin suppliers unable to absorb fifteen-to-twenty-five percent cost increases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Supply Zones | Cargill's farm-to-formulation control secures Ukrainian beet anthocyanin against geopolitical disruption. |
| Precision Fermentation Scale-Up | Danish bioreactor deployment compresses lead times from seasonal harvest dependencies to continuous manufacturing cycles. |
| Dual Certification Investment | Simultaneous FDA GRAS and EFSA compliance documentation unlocks multi-year framework agreements with German retailers. |
| Modular Clean-Label Ingredient Kits | Integrated systems bundling colorants, preservatives, and emulsifiers displace commodity spot purchasing in bakery reformulation cycles. |
| Geographic Expansion into Indian Manufacturing | FSSAI harmonization with GRAS-affirmed ingredients accelerates market entry for fermentation-derived additives in Maharashtra. |
Research Methodology
Direct dialogue with R&D directors at multinational food manufacturers, procurement leads at German and French industrial bakeries, regulatory affairs specialists navigating EFSA and FDA pathways, and biotechnology process engineers at Danish fermentation facilities grounded qualitative insights. Secondary validation drew from EFSA guidance documents, FDA GRAS affirmation notices, EU Green Deal sustainable sourcing mandates, USDA organic certification databases, and customs records of beet anthocyanin trade flows. Bottom-up volume modeling across product type, source, application, and form segments triangulated against top-down macroeconomic drivers.
Bottom-up segment analysis tracked colorant, preservative, emulsifier, and flavoring agent volumes through application-specific demand curves in bakery, beverage, dairy, and snack categories, while top-down approaches validated aggregate market expansion against clean-label procurement intensity indices. The analytical framework incorporated regulatory compliance burden differentials, biotechnology-enabled production cost trajectories, and retailer mandate diffusion patterns across the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by EFSA and FDA pathway penetration assumptions.
Caveats apply where EFSA extraction solvent threshold revisions, Ukrainian agricultural supply disruptions, or FDA guidance reinterpretations of natural claims could materially shift the outlook. Forecasts reflect modeling assumptions about biotechnology scale-up timelines and retailer clean-label mandate enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
North America Anti-Caking Market