
 United States Food Enzymes Market | 2026-2036
United States Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Enzymes Market Intelligence
FDA GRAS self-determination is pivoting how enzyme suppliers validate novel biocatalysts for commercial food use. Novonesis Group leverages deep fermentation expertise to sustain leadership in dairy processing applications. Kerry Group plc anchors its position through integrated enzyme solutions that span bakery and beverage channels. DuPont de Nemours Inc. differentiates via biotechnology platforms that optimize enzyme performance under industrial stress conditions.
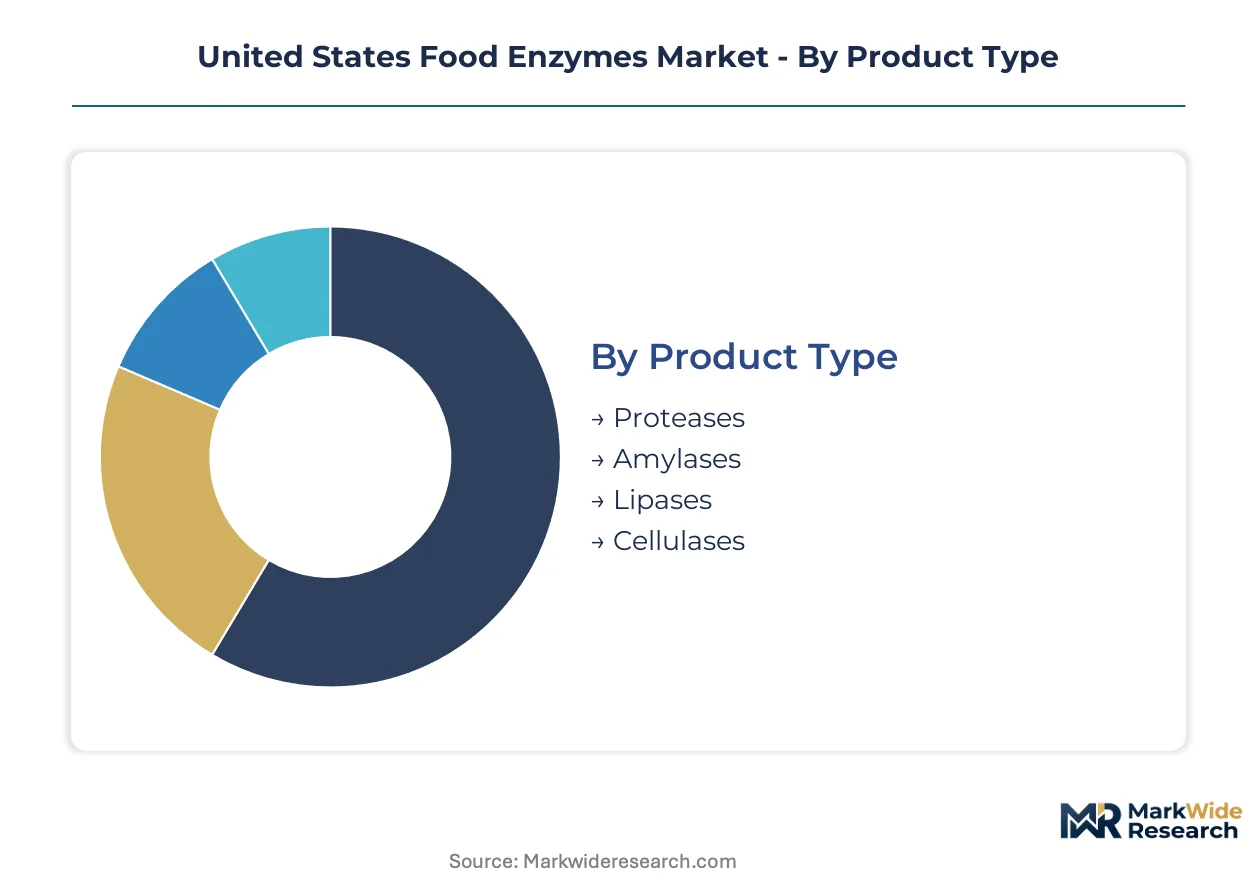
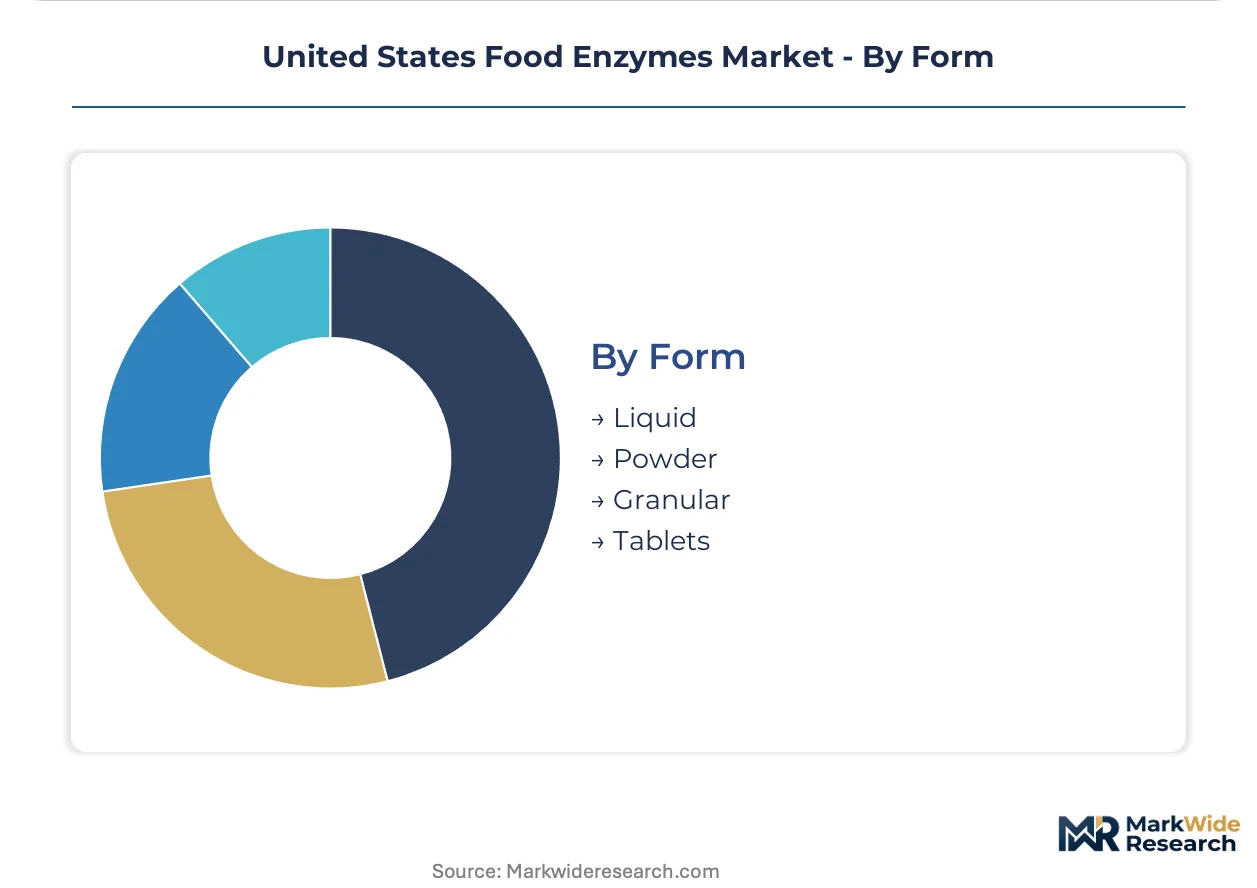
Food enzymes are protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions without being consumed in the process. Their primary commercial purpose is to enhance processing efficiency, improve product texture, extend shelf life, and enable clean-label formulations across manufactured food systems. Proteases command the largest share of product-type demand due to their versatility in dairy coagulation and protein modification. Beverage production represents the fastest-growing application segment as brewers and juice processors adopt enzymatic clarification to replace conventional filtration. Liquid formulations dominate the form category because they integrate seamlessly into continuous processing lines and reduce handling losses.
The USDA and EPA jointly influence enzyme market access through bioengineered organism oversight and industrial bioprocessing discharge standards that affect fermentation facility siting. FDA GRAS notifications and FSSC 22000 certification requirements shape product liability exposure and customer procurement criteria for domestic enzyme suppliers. Stakeholders must monitor how evolving FDA guidance on precision-fermented ingredients reclassifies certain enzyme production pathways and alters competitive licensing structures.
Market Dynamics
FDA GRAS self-determination rules are recalibrating validation timelines for novel biocatalysts while clean-label bakery demand concentrates enzyme procurement in the Midwest dairy processing belt.
Growth Catalysts
- Clean-label formulation mandates:Bakery processors across Wisconsin and Minnesota are reformulating to eliminate chemical conditioners, pulling higher volumes of amylase and xylanase enzymes into bread and pastry applications.
- EPA bioengineered organism oversight:Streamlined discharge standards for fermentation facilities are reducing siting friction for domestic enzyme production, expanding fermentation capacity in the Upper Midwest.
- Precision-fermented ingredient pathways:Evolving FDA guidance on novel production methods is reclassifying certain biocatalyst sourcing routes, altering competitive licensing structures for domestic suppliers.
Market Restraints
- Input cost volatility:Fluctuations in corn steep liquor and soybean meal prices—primary fermentation feedstocks—compress margin predictability for bulk enzyme manufacturers.
- Supply concentration risk:Specialty enzyme strains remain concentrated among a limited cohort of culture collection holders, creating bottleneck vulnerability for novel protease development.
- Technical substitution pressure:Chemical acidulants and emulsifiers retain cost advantages in mass-market baked goods, limiting enzyme penetration in price-sensitive retail segments.
Strategic Opportunities
- Underpenetrated beverage clarification:Juice processors in Florida and California represent untapped demand for enzymatic clarification systems that replace conventional filtration membranes.
- Technology convergence:Integration of CRISPR-edited production strains with continuous fermentation bioreactors is opening pathways to enzyme variants with tailored temperature stability profiles.
- Regulatory tailwind:USDA bioengineered food disclosure standards are creating preference pull for enzymes produced via non-GMO fermentation routes, rewarding suppliers with verified strain lineages.
Industry Challenges
- FSSC 22000 certification timelines:Extended audit cycles for food safety system certification are delaying customer qualification for enzyme suppliers seeking entry into multinational food manufacturer approved-vendor lists.
- Integration complexity with legacy dairy systems:Retrofitting continuous enzyme dosing into batch-based cheese vat operations requires process engineering expertise that mid-sized Wisconsin cooperatives struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Enzymes Market |
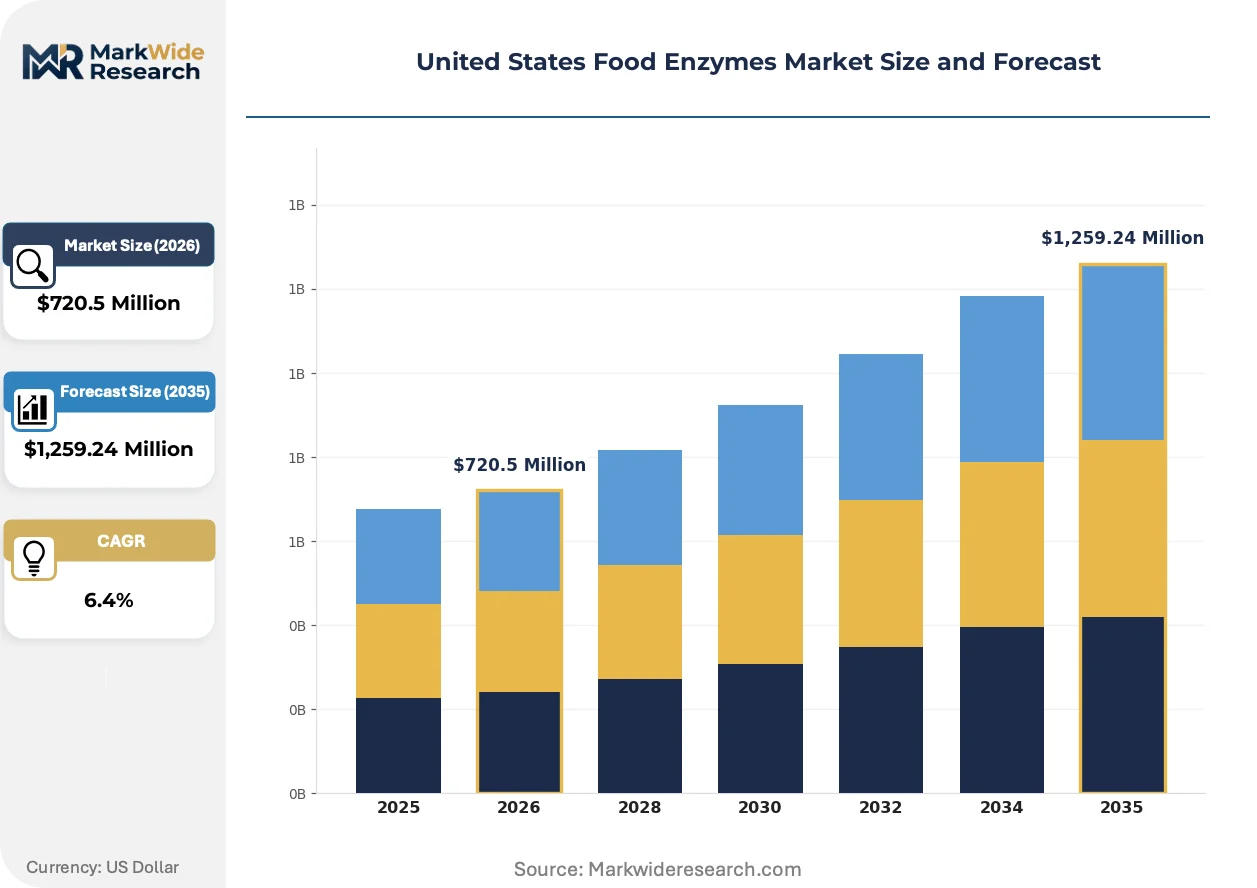
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,259.24 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy Processing, Beverage Production, Meal Replacement End User: Food Manufacturers, Beverage Companies, Confectionery Producers, Bakery Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | International Flavors & Fragrances Inc., DSM-Firmenich AG, Novonesis Group, Kerry Group plc, Associated British Foods plc, Amano Enzyme Inc., DuPont de Nemours Inc., The Archer-Daniels-Midland Company, Advanced Enzyme Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Enzymes Market Strategic Shifts & Innovations
Biotechnology platforms and regulatory guidance evolution are compressing development cycles while reshaping how enzyme performance is validated and priced in commercial food systems.
CRISPR-edited production strains are rewriting strain development economics by enabling precise knock-ins of temperature-tolerant enzyme variants. Dairy processors in Minnesota and Wisconsin are adopting these biocatalysts at accelerating pace to reduce cooling requirements during cheese production. The technology is rewriting competitive positioning by collapsing the traditional 18-24 month strain optimization timeline into 6-9 month development windows.
FDA guidance on precision-fermented ingredients is tightening disclosure requirements for enzymes derived from novel host organisms. Industrial consequence includes expanded toxicology documentation burdens for suppliers seeking GRAS self-determination. The dairy processing segment is most affected, with Wisconsin-based manufacturers accelerating internal analytical capabilities to preempt regulatory scrutiny.
Specification-driven procurement is consolidating enzyme buying among national bakery and dairy cooperatives with dedicated technical staff. Regional distributors and independent brokers are losing share to direct manufacturer relationships as buyers demand application-specific performance guarantees. The shift is most visible in the Upper Midwest, where dairy processing belt concentration enables volume-based contracting with embedded technical service support.
United States Food Enzymes Market Segmentation
Enzyme procurement patterns across the United States food manufacturing base cluster around performance specifications tied to specific processing conditions. Suppliers calibrate product portfolios to match the technical requirements of Midwest dairy cooperatives, national bakery chains, and beverage processors in Florida and California.
Product Type:
Supply concentration for high-activity protease strains tilts toward culture collection holders with validated GRAS lineages.
- Proteases:These protein-cleaving biocatalysts operate optimally between pH 4.5 and 7.0, enabling milk coagulation in cheddar production and gluten modification in bread dough. Wisconsin and Minnesota dairy processors command the largest share of food-grade protease offtake as cheese vat operations convert from animal-derived rennet to microbial alternatives. FDA GRAS self-determination requirements favor suppliers with documented strain histories, entrenching incumbent positions.
- Amylases:Starch-hydrolyzing enzymes catalyze dextrose formation in corn syrup production and control crumb structure in commercial bread. Clean-label bakery reformulation across national retail chains is pulling higher volumes of fungal and bacterial amylase variants into bread and pastry applications. Temperature stability specifications vary sharply between high-heat baking and low-temperature beverage processing.
- Lipases:Fat-modifying biocatalysts enable flavor development in aged cheese and structured lipid production.
- Cellulases:Cell wall-degrading enzymes facilitate juice extraction and improve feed digestibility in secondary food applications.
Proteases absorb the bulk of installed capacity; amylases are expanding most quickly.
Application:
Cost tier differentiation separates commodity enzyme users from processors requiring application-specific technical service.
- Baking:Enzyme systems replace chemical conditioners in clean-label bread and pastry production, with amylase-xylanase blends controlling dough rheology and shelf-life extension. National retail bakery chains in the Upper Midwest are consolidating procurement through direct manufacturer relationships with embedded technical support. Specification-driven buying favors suppliers capable of guaranteeing performance across variable flour protein content.
- Dairy Processing:Cheese production in Wisconsin and Minnesota relies on protease-coagulant combinations optimized for vat time reduction and yield improvement. Batch-based operations face integration complexity when retrofitting continuous enzyme dosing, creating demand for process engineering expertise that mid-sized cooperatives struggle to access internally. Precision-fermented enzyme variants are gaining traction for temperature tolerance advantages.
- Beverage Production:Enzymatic clarification systems replace conventional filtration membranes in juice processing, with pectinase and cellulase blends reducing turbidity without heat damage. Florida and California juice processors represent underpenetrated demand as technical adoption lags brewing industry standards.
- Meal Replacement:Protein hydrolysis for nutritional beverage applications requires protease systems with controlled peptide release profiles.
Dairy processing commands the largest enzyme volumes; beverage production is climbing the fastest.
End User:
Customer type fragmentation separates multinational food manufacturers with dedicated technical staff from regional processors dependent on distributor relationships.
- Food Manufacturers:National packaged food companies with internal R&D capabilities specify enzyme performance metrics and demand batch-to-batch consistency documentation. Direct procurement relationships with enzyme suppliers are displacing regional distributors as specification complexity increases.
- Beverage Companies:Brewing and juice processing operations prioritize enzymatic clarification efficiency and flavor preservation. Technical service requirements vary by scale, with craft brewers relying on distributor support while national brands demand direct manufacturer engagement.
- Confectionery Producers:Sugar inversion and texture modification applications require precise enzyme dosing control.
- Bakery:Commercial bread and pastry operations span independent regional bakers and national retail chains with divergent procurement sophistication.
Food manufacturers absorb the bulk of installed capacity; beverage companies are gaining share fastest.
Form:
Volume economics favor liquid formulations in continuous processing environments while powder and granular forms serve batch operations with intermittent dosing requirements.
- Liquid:Pumpable enzyme concentrates integrate seamlessly into automated dosing systems on continuous production lines, minimizing handling losses and enabling real-time flow adjustment. Dairy processors in Wisconsin and Minnesota specify liquid protease for cheese vat operations where uniform distribution accelerates coagulation kinetics.
- Powder:Dry enzyme preparations offer extended shelf stability and simplified logistics for bakeries with intermittent production schedules. Dust containment requirements and precise weighing infrastructure create operational complexity that smaller processors struggle to justify.
- Granular:Intermediate moisture formulations balance handling convenience with storage stability for mid-scale food manufacturers.
- Tablets:Unit-dose enzyme preparations serve specialized applications requiring precise single-batch addition without measurement equipment.
Liquid formulations absorb the bulk of installed capacity; powder is expanding most quickly in artisan bakery segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Opportunity Zones in Wisconsin and Minnesota accelerate fermentation facility siting through capital gains tax deferrals, concentrating enzyme production capacity in the Upper Midwest dairy processing belt.
Midwest Dairy Belt
Wisconsin and Minnesota cheese processors drive protease demand as vat operations convert from animal rennet to microbial coagulants. EPA streamlined discharge standards for bioengineered organism fermentation reduce regulatory friction for facility expansion. The Fox Valley corridor between Green Bay and Milwaukee anchors the highest concentration of food-grade enzyme manufacturing capacity.
Southeast
Florida citrus processors represent underpenetrated demand for enzymatic juice clarification systems. FDA GRAS notification requirements shape supplier qualification timelines for regional beverage manufacturers. The Orlando-Tampa corridor hosts emerging contract fermentation capacity serving flavor and fragrance applications.
Pacific Coast
California wine and juice producers adopt pectinase blends for premium product turbidity control. California Air Resources Board industrial bioprocessing emission standards influence fermentation facility design specifications. The Central Valley processing cluster between Fresno and Modesto concentrates enzymatic extraction applications for nut and fruit products.
Northeast Corridor
New York and New Jersey pharmaceutical-grade enzyme demand spills into food applications through shared fermentation infrastructure. FDA district office oversight in New Jersey shapes GRAS self-determination documentation standards for suppliers serving national accounts. The New York Metro area anchors corporate R&D functions for multinational enzyme suppliers.
Southwest
Texas corn wet milling operations consume bulk amylase for dextrose and high-fructose corn syrup production. Texas Commission on Environmental Quality industrial discharge permits affect fermentation facility water recycling requirements. The Houston Ship Channel corridor enables import logistics for specialized culture media and fermentation feedstocks.
United States Food Enzymes Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base concentrates around fermentation technology holders with validated GRAS strain lineages and integrated application service capabilities. Three archetypes dominate: global ingredient conglomerates with enzyme divisions, biotechnology platforms specializing in biocatalyst engineering, and regional fermentation houses serving dairy cooperatives. Competitive moves center on precision-fermentation capacity expansion and direct technical service relationships displacing distributor intermediaries.
Among global diversified suppliers, International Flavors & Fragrances Inc. and DSM-Firmenich AG occupy positions spanning fragrance, nutrition, and enzyme applications. Novonesis Group exemplifies the biotechnology-platform archetype with deep fermentation expertise. These three represent contrasting strategic postures: conglomerate breadth versus specialized biocatalyst depth versus integrated biotechnology platforms.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| DSM-Firmenich AG |
| Novonesis Group |
| Kerry Group plc |
| Associated British Foods plc |
| Amano Enzyme Inc. |
| DuPont de Nemours Inc. |
| The Archer-Daniels-Midland Company |
| Advanced Enzyme Technologies |
| Others |
Cost & Logistics Intelligence
Corn steep liquor price volatility cascades through fermentation economics to stratify enzyme pricing across performance tiers, with feedstock cost pass-through mechanisms concentrating margin pressure on commodity protease suppliers serving Midwest dairy cooperatives.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate spot enzyme procurement from contracted annual offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FSSC 22000-certified strains commanding substantial markups over generic alternatives. Cost compression in standard-tier amylases is intensifying because Brazilian soybean meal import disruptions feed directly into bulk fermentation economics. National bakery chains with dedicated technical staff exhibit lowest price sensitivity, while independent Wisconsin dairy cooperatives negotiate aggressively on per-kilogram protease contracts.
Supply Chain Analysis
Domestic-content mandates under USDA bioengineered disclosure standards are reshaping sourcing toward verified non-GMO strain lineages. Fermentation capacity concentrates in the United States, Denmark, and the Netherlands, with culture collection repositories in Japan and Germany anchoring specialty protease development. Raw material dependencies center on corn steep liquor from Midwest wet mills, pharmaceutical-grade yeast extract from European suppliers, and purified water systems meeting EPA discharge standards. Single-source vulnerability around thermostable strain IP held by Novonesis and DuPont creates bottleneck exposure for precision-fermented variants. Distribution runs through direct manufacturer relationships with national food manufacturers, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-edited production strains are displacing conventional mutagenesis pipelines, compressing development timelines and rewriting competitive economics for enzyme suppliers across dairy and bakery applications.
For Market Incumbents: Deploy precision-fermentation capacity expansion in the Fox Valley corridor to preempt emerging biotechnology platforms from capturing temperature-tolerant protease share. Secure backward integration into corn steep liquor supply through offtake agreements with Minnesota wet mill operators, insulating margin structures from feedstock volatility. Defensive patent thickets around CRISPR-edited strain lineages must thicken before FDA guidance tightens disclosure requirements for novel host organisms. For New Entrants and Emerging Players: Launch via contract fermentation services targeting Florida citrus processors seeking enzymatic clarification alternatives to conventional filtration. White-space concentration in beverage applications offers lower competitive density than saturated Midwest dairy procurement, with technical service gaps at mid-scale juice operations creating entry footholds. Direct technical relationships with California Central Valley nut processors bypass entrenched distributor networks. For Investors and Strategic Acquirers: The window for entry favors biotechnology platforms with validated GRAS strain lineages and embedded dairy industry relationships. Long-term viability hinges on regulatory navigation capabilities as FDA precision-fermentation guidance evolves. Acquisition target archetype: regional fermentation houses with Wisconsin cooperative contracts and pending FSSC 22000 certification. Signal to watch: EPA discharge standard modifications that alter Upper Midwest facility siting economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Capacity Expansion | CRISPR-edited strain deployment accelerates temperature-tolerant protease commercialization timelines. |
| Backward Integration into Feedstock Supply | Corn steep liquor offtake agreements insulate margin structures from commodity volatility. |
| Direct Technical Service Relationships | Embedded dairy process engineering displaces distributor intermediaries in Wisconsin cooperative procurement. |
| FSSC 22000 Certification Investment | Food safety system credentials unlock multinational manufacturer approved-vendor qualification. |
| Non-GMO Strain Lineage Verification | USDA bioengineered disclosure standards create preference pull for verified fermentation routes. |
Research Approach
Document review covered FDA GRAS notification filings, EPA industrial discharge permit databases, and FSSC 22000 certification registries, complemented by interviews with fermentation facility operations directors, dairy cooperative procurement managers, bakery chain technical directors, and enzyme supplier regulatory affairs leads. Secondary validation drew from USDA National Agricultural Statistics Service feedstock reports, SEC 10-K disclosures from diversified ingredient suppliers, and American Association of Cereal Chemists technical bulletins. Bottom-up enzyme volume estimates from individual facility capacities triangulated against top-down food manufacturer consumption surveys.
Historical capacity utilization patterns cross-referenced against panel input from plant engineering consultants anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application processing condition, end-user technical sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for technology adoption S-cycles and substitution elasticity between enzymatic and chemical processing alternatives. Forecast inputs incorporated EPA discharge standard modification probabilities and FDA precision-fermentation guidance evolution scenarios.
Feedstock price volatility, regulatory reclassification of novel production pathways, and certification audit timeline extensions are the dominant revision risks to installed capacity and pricing assumptions. Forecasts reflect documented strain development pipelines and disclosed facility expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Film Forming Starches Market