
 Twin Pouch Packaging Market | 2026-2036
Twin Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Twin Pouch Packaging Market Analytics
The EU Packaging and Packaging Waste Regulation is recalibrating how European food brands specify multi-compartment flexible formats, pushing converters toward mono-material and recyclable substrate roadmaps. Amcor Limited leverages its global film supply network to anchor sustainable pouch development across three continents. Sealed Air Corporation differentiates through proprietary barrier technologies that extend shelf life for sensitive ingredients in separated chambers. Bemis Company, Inc. specializes in high-speed form-fill-seal integration for twin-chamber medical and nutritional applications.
Twin pouch packaging denotes a flexible format incorporating two distinct sealed compartments within a single outer structure, typically fabricated from coextruded polyethylene or polypropylene films with peelable or permanent seal interfaces between chambers. The design enables simultaneous containment of incompatible substances—such as wet and dry components, or active and inert ingredients—that require isolation until point of use. Plastic composites dominate material type segmentation due to their tunable barrier properties and thermoformability, though aluminum laminates retain margin pools in pharmaceutical oxygen-sensitive applications. Zip lock and tear notch closure types are gaining fastest in e-commerce channels where resealability and consumer convenience drive repeat purchase behavior.
FDA food contact substance notifications govern material safety for U.S. twin pouch applications, while EFSA and REACH frameworks regulate migration limits and chemical composition across European supply chains. The EU Green Deal's packaging recyclability targets are forcing substrate redesigns that eliminate multi-material laminations in favor of detectable mono-polymer structures. Stakeholders must monitor how forthcoming extended producer responsibility schemes alter cost allocation between brand owners, converters, and resin suppliers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate redesigns across the twin pouch value chain, eliminating multi-material laminations in favor of detectable mono-polymer structures that satisfy mechanical recycling streams.
Growth Catalysts
- Portion-controlled meal formats:Food and beverage brands in North America are accelerating adoption of twin pouch designs that separate wet and dry components until point of consumption, driving equipment upgrades at flexible packaging converters.
- REACH migration limits:ECHA frameworks governing chemical composition and substance migration are standardizing material specifications, reducing formulation variability and enabling scale economies for compliant substrate suppliers.
- Precision filling clusters:Equipment manufacturers concentrated around Düsseldorf and Hamburg are developing high-speed form-fill-seal systems purpose-built for twin-chamber medical and nutritional applications.
Market Restraints
- Aluminum laminate dependency:Pharmaceutical oxygen-sensitive applications retain margin pools in aluminum laminates, which face mechanical recycling incompatibility under EU Green Deal targets and require costly substrate transitions.
- Resin supply concentration:Coextruded polyethylene and polypropylene film supply chains concentrate among petrochemical complexes in Germany and the Netherlands, exposing converters to feedstock volatility and force majeure risk.
- Extended producer responsibility friction:Forthcoming EPR schemes are recalibrating cost allocation between brand owners and converters without clear precedent, creating contracting uncertainty for multi-year equipment investments.
Strategic Opportunities
- E-commerce resealability demand:Zip lock and tear notch closure types are gaining fastest in direct-to-consumer channels, where repeat purchase behavior correlates with unboxing convenience and portion control features.
- Mono-material detectability:EU Green Deal recyclability targets are creating first-mover advantage for converters developing near-infrared detectable single-polymer structures that sort cleanly in municipal recycling streams.
- Active-ingredient isolation:Nutraceutical and probiotic applications requiring separated chambers for live cultures and stabilizers represent underpenetrated white space beyond established food and pharmaceutical verticals.
Industry Challenges
- Peelable seal engineering:Achieving consistent burst strength and hermetic integrity across permanent and peelable seal interfaces requires polymer science expertise that concentrates among a narrow supplier base.
- Legacy equipment retrofit:Converters operating standard form-fill-seal lines face capital intensity challenges when retooling for twin-chamber formats with differential fill volumes and synchronized sealing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twin Pouch Packaging Market |
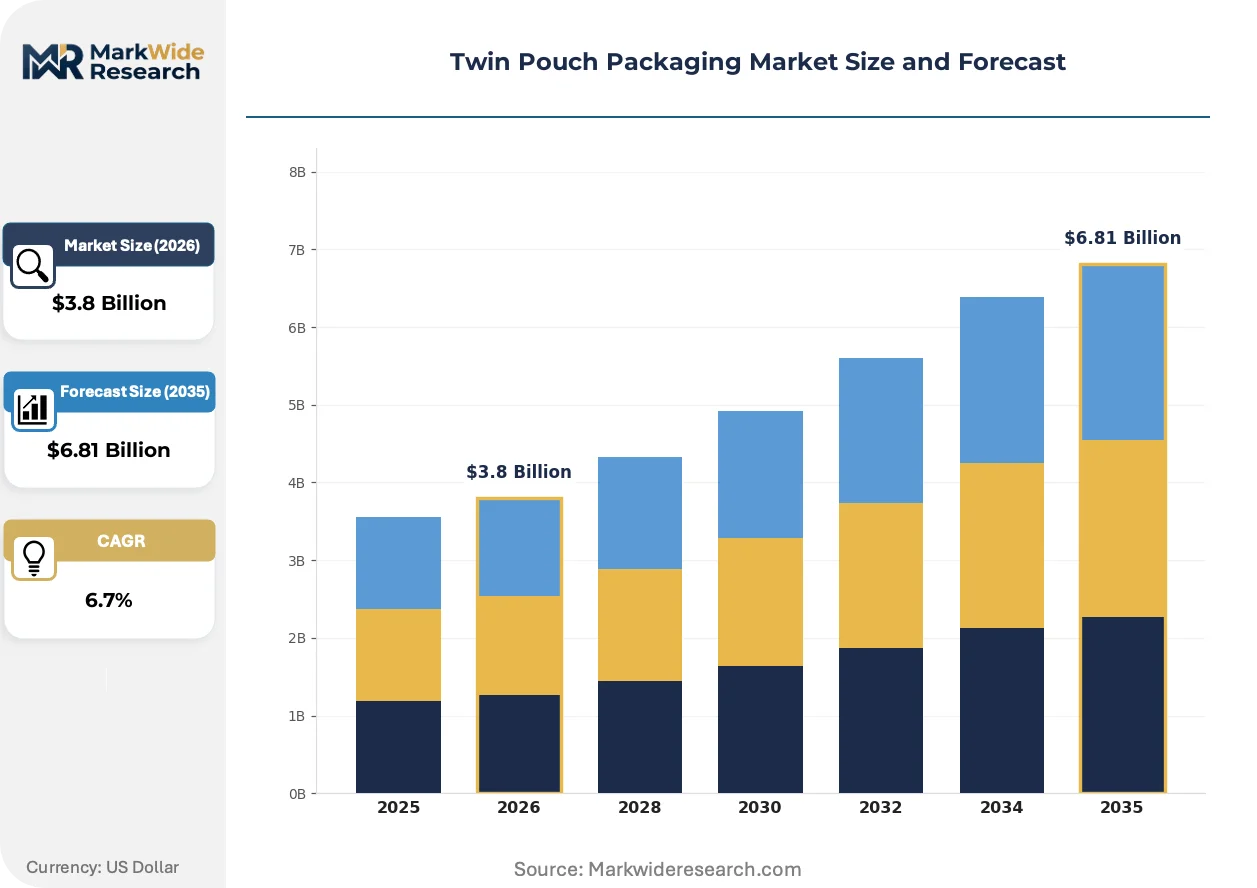
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Paper, Composites Closure Type: Zip Lock, Screw Cap, Tear Notch, Press-to-Seal End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Distribution Channel: Retail, E-commerce, Direct Sales, Others |
| Companies Covered | Amcor Limited, Bemis Company, Inc., Sealed Air Corporation, Clondalkin Group Holdings B.V., Winpak Ltd., Uflex Ltd., Swiss Pac Pvt. Ltd., SN Maschinenbau GmbH, Anzu Technology LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twin Pouch Packaging Market Evolving Landscape
Active barrier technologies and mono-material substrate roadmaps are converging to redefine competitive positioning in flexible packaging, with regulatory detectability requirements now dictating R&D priority.
Laser-scored peelable seal interfaces are electrifying product development at European flexible packaging converters, enabling precise burst strength calibration for wet-dry component separation. Nutraceutical brands are piloting these interfaces for probiotic-meal-pairing formats. The technology is compressing development cycles for multi-compartment applications previously requiring custom tooling.
REACH substance restrictions are eliminating certain phthalate plasticizers and adhesive chemistries from food-contact laminates, forcing reformulation of coextruded seal layers. Converters serving German retail chains are accelerating compliance timelines ahead of enforcement windows. Medical device pouches with oxygen-sensitive chambers face the steepest substitution curves.
Direct-to-consumer subscription models are fragmenting order patterns for twin pouch formats, compressing production runs and elevating changeover frequency at form-fill-seal operations. Pet food brands in the United States are shifting volume toward e-commerce channels that reward resealable closure innovation. This channel rotation is elevating converter investments in quick-change tooling and digital print compatibility.
Twin Pouch Packaging Market Segmentation
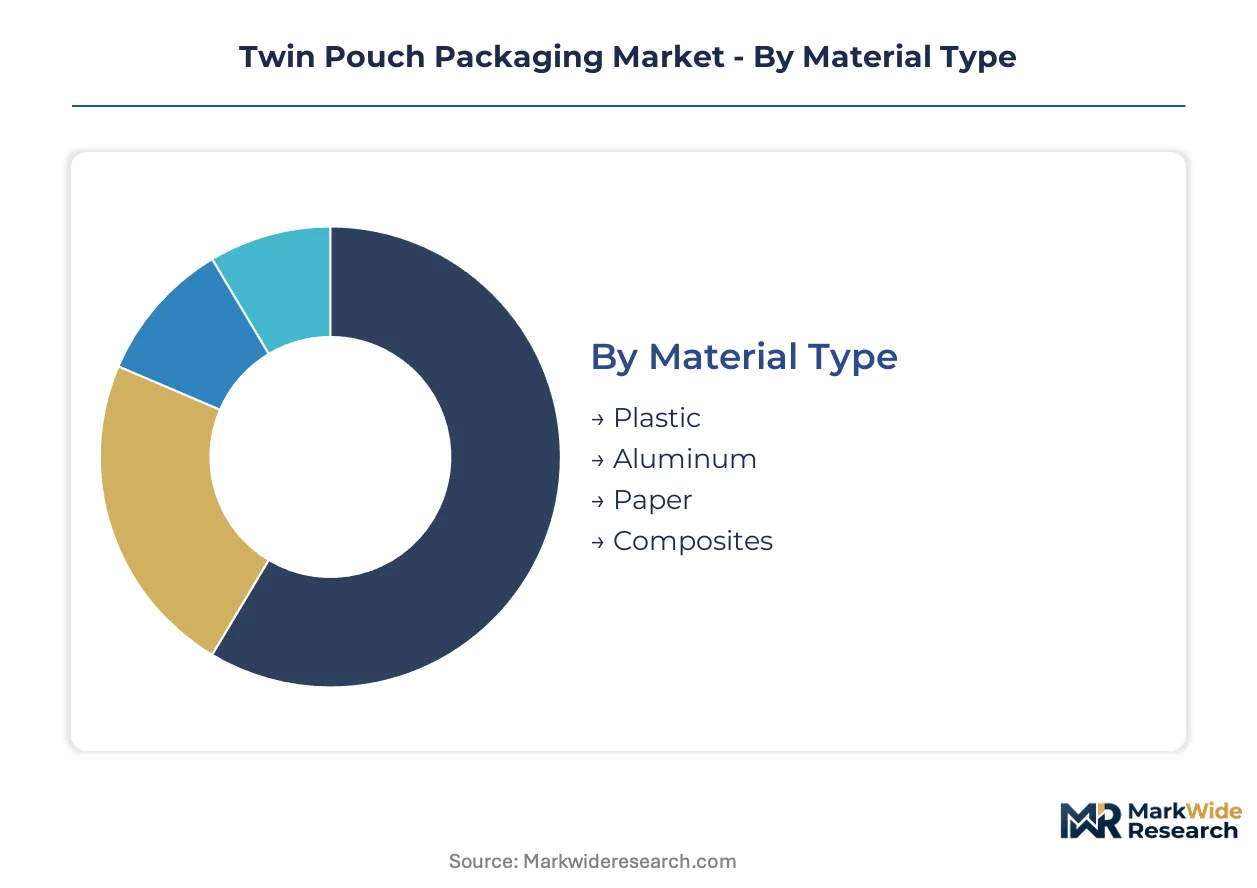
Twin pouch packaging configurations diverge sharply across material substrates and closure mechanisms, with each combination dictating capital equipment requirements, barrier performance thresholds, and regulatory compliance pathways. Converters must align production capabilities with the specific isolation demands of wet-dry, active-inert, or oxygen-sensitive product pairings.
Material Type:
Resin supply chains for coextruded films concentrate among petrochemical complexes in Germany and the Netherlands, exposing converters to feedstock volatility and specialized additive formulation dependencies.
- Plastic:Coextruded polyethylene and polypropylene films dominate commercial volumes due to tunable barrier properties and thermoformability. Food and beverage brands in Germany specify these substrates for portion-controlled meal formats requiring peelable seal interfaces between wet and dry chambers.
- Aluminum:Multi-layer laminates with aluminum foil cores retain critical oxygen and moisture barriers for pharmaceutical applications. EFSA migration limits and REACH substance restrictions are forcing costly reformulations of adhesive chemistries bonding metal to polymer layers.
- Paper:Fiber-based substrates with polymer barrier coatings serve premium cosmetic and dry goods segments where tactile differentiation commands price premiums. Swedish and Finnish pulp suppliers anchor European supply for these specialty grades.
- Composites:Hybrid structures combining plastic, metal, and fiber layers address niche performance requirements in medical device packaging. Recycling incompatibility under EU Green Deal targets is compressing addressable market scope for these formats.
Plastic absorbs the bulk of installed capacity; paper is expanding most quickly in premium personal care applications.
Closure Type:
End-use channel rotation toward direct-to-consumer distribution is elevating resealability and unboxing experience as specification criteria that override pure cost minimization.
- Zip Lock:Interlocking plastic tracks enable repeated opening and resealing for multi-serve products. Pet food brands in the United States specify these closures for e-commerce subscription formats where portion control drives repeat purchase behavior.
- Tear Notch:Laser-scored perforations provide controlled burst opening without additional hardware. Nutraceutical applications requiring precise dosing separation favor this low-cost mechanism for probiotic-meal-pairing formats.
- Screw Cap:Threaded plastic closures attach to fitments in liquid-containing chambers. Pharmaceutical syrups and reconstitution kits specify these for secure transport of active ingredients.
- Press-to-Seal:Adhesive or mechanical pressure-activated interfaces offer single-use security with simpler tooling requirements. Household cleaning product twins utilize these for cost-sensitive disposable formats.
Zip lock commands the highest equipment investment per line; tear notch is climbing the fastest as laser scoring technology compresses development cycles.
End User:
Regulatory frameworks governing chemical migration and oxygen sensitivity create divergent material qualification timelines that segment converter customer bases by compliance capability.
- Food & Beverage:Wet-dry component isolation for ready meals, baking mixes, and beverage concentrates. FDA food contact substance notifications and EFSA frameworks govern material safety with differing migration limit stringencies.
- Pharmaceuticals:Oxygen-sensitive chambers for active ingredients, reconstitution kits, and medical devices. Aluminum laminate dependency persists despite mechanical recycling incompatibility under EU Green Deal targets.
- Personal Care:Cosmetic serums, mask activators, and dual-phase formulations requiring aesthetic differentiation. Premium positioning supports paper substrate adoption and complex closure mechanisms.
- Household Products:Cleaning agent concentrates, adhesive two-part systems, and automotive chemical twins. Cost minimization dominates specification with press-to-seal and basic plastic film structures.
Food and beverage holds the deepest converter relationships; pharmaceuticals maintains the steepest expansion trajectory driven by biologic drug delivery formats.
Distribution Channel:
Channel mix fragmentation is compressing production run lengths and elevating changeover frequency at form-fill-seal operations, favoring digital print compatibility and quick-change tooling investments.
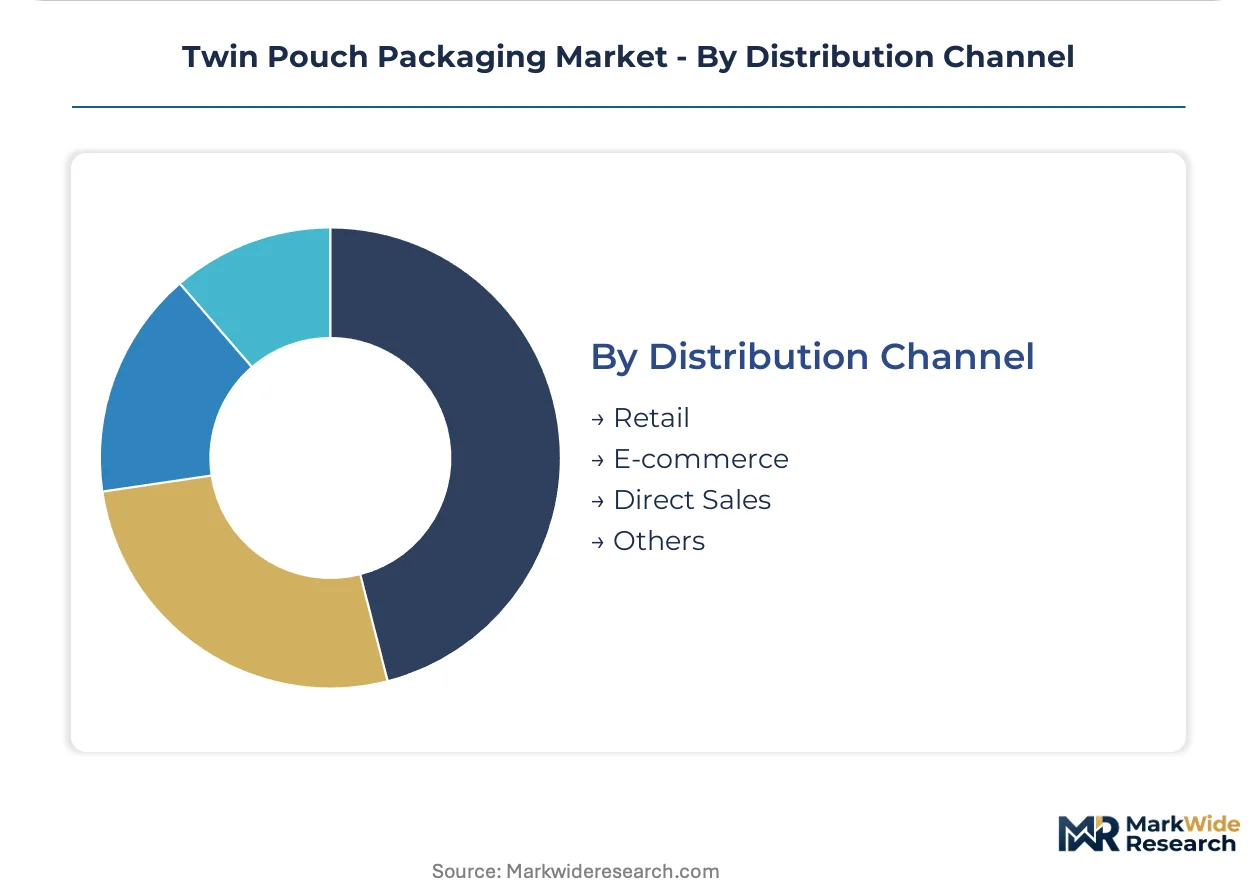
- Retail:Traditional brick-and-mortar grocery, pharmacy, and mass merchant channels. German retail chains are accelerating REACH compliance timelines ahead of enforcement windows for private label twin pouch programs.
- E-commerce:Direct-to-consumer and third-party marketplace fulfillment. Resealable closure innovation and unboxing experience specification concentrate in this channel.
- Direct Sales:Manufacturer-controlled subscription and replenishment programs. Nutraceutical and pet food verticals dominate with customized portion-controlled formats.
- Others:Institutional foodservice, healthcare procurement, and industrial supply arrangements. Volume concentration and long-term contracting characterize this fragmented residual category.
Retail retains the largest absolute volume; e-commerce is gaining share fastest as channel rotation accelerates among pet food and nutraceutical brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European twin pouch equipment manufacturing, with precision filling specialists clustering around the Rhine-Ruhr corridor to serve pharmaceutical and food-grade flexible packaging converters.
Germany
Portion-controlled meal brands specify twin-chamber formats for wet-dry component isolation, driving converter demand near Hamburg and Düsseldorf. ECHA REACH frameworks govern migration limits for coextruded seal layers, forcing adhesive reformulations ahead of enforcement windows. Equipment manufacturers in North Rhine-Westphalia deploy high-speed form-fill-seal systems purpose-built for medical nutritional applications.
United States
Pet food subscription brands accelerate zip lock closure adoption for e-commerce channels where resealability drives repeat purchase behavior. FDA food contact substance notifications govern material safety for separated-chamber designs. Flexible packaging converters in the Midwest and Southeast invest in quick-change tooling to accommodate fragmented direct-to-consumer order patterns.
China
Domestic nutraceutical brands pilot laser-scored peelable seals for probiotic-meal-pairing formats requiring precise burst strength. SAMR and GB standards regulate chemical composition in food-contact laminates. Yangtze River Delta converters develop mono-material detectable substrates compatible with municipal mechanical recycling streams.
India
Uflex Ltd. anchors domestic flexible film supply for twin-chamber snack and spice formats serving price-sensitive consumer segments. FSSAI frameworks standardize food-contact material specifications across multi-layer structures. Gujarat and Maharashtra-based converters expand form-fill-seal capacity to capture export demand from Middle East and African markets.
United Kingdom
Premium personal care brands specify paper-based twin pouches with polymer barrier coatings for tactile differentiation in cosmetic serum applications. UK REACH retains substance restrictions inherited from EU frameworks post-Brexit. Southeast England converters focus on short-run digital print compatibility for direct-sales subscription models.
Twin Pouch Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology specialization and regulatory compliance capability, with consolidated film supply networks commanding pricing power over fragmented converter operations. The vendor base stratifies into three archetypes: integrated resin-to-pouch conglomerates with global film networks, regional flexible packaging specialists with equipment integration expertise, and precision machinery fabricators concentrated in German industrial clusters. Dominant competitive moves include backward integration into resin compounding and strategic licensing of laser-scored seal interface technologies.
Among integrated packaging conglomerates, Amcor Limited and Sealed Air Corporation occupy positions spanning three continents with captive film supply networks. Bemis Company, Inc. exemplifies the North American equipment-integrated specialist archetype, while Clondalkin Group Holdings B.V. represents European converter consolidation. SN Maschinenbau GmbH anchors German precision machinery supply for high-speed twin-chamber filling systems. These named entities serve as structural anchors for understanding competitive positioning without attributing specific strategic actions or market shares to individual firms.
| Leading Market Players |
|---|
| Amcor Limited |
| Bemis Company, Inc. |
| Sealed Air Corporation |
| Clondalkin Group Holdings B.V. |
| Winpak Ltd. |
| Uflex Ltd. |
| Swiss Pac Pvt. Ltd. |
| SN Maschinenbau GmbH |
| Anzu Technology LLC |
| Others |
Value Network & Pricing Analysis
Precision polymer engineers concentrated around Düsseldorf and Hamburg command wage premiums that propagate through three-tier pricing structures separating pharmaceutical-grade from commodity food-contact substrates. Labor-cost differentials between German equipment clusters and Asian resin compounding centers widen spreads between premium mono-material detectable films and standard multi-layer laminates facing EU Green Deal obsolescence.
Pricing Analysis
Barrier-performance guarantees anchor value-based pricing for oxygen-sensitive pharmaceutical applications, with FDA and EFSA certification tiers commanding substantial premiums over standard food-contact grades. Price differentiation separates laser-scored peelable seal interfaces from basic tear-notch formats, while REACH-driven adhesive reformulations compress margins in aluminum laminate segments most exposed to substitution risk. Cost compression in commodity plastic films intensifies as Yangtze River Delta converters expand mono-polymer capacity. Household cleaning product buyers exhibit highest price sensitivity; pharmaceutical brand owners prioritize barrier reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch petrochemical complexes supplying specialized coextruded polyethylene and polypropylene resins with tuned seal-layer additives. Raw material dependencies encompass metallocene catalysts, oxygen-scavenger masterbatches, and near-infrared detectable pigment systems. Feedstock volatility tied to naphtha-cracking economics presents persistent margin risk without geographic diversification. Distribution runs through converter-direct relationships for pharmaceutical volumes, while food and beverage segments rely on regional flexible packaging distributors with form-fill-seal integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation compliance costs are forcing substrate transitions that eliminate capital-constrained converters unable to fund mono-material R&D programs.
For Market Incumbents: Anchor barrier technology leadership through captive supply of detectable mono-polymer films, defending against Asian converter encroachment via EFSA pre-certification pipelines. Backward integration into resin compounding secures additive formulation control essential for peelable seal consistency. Equipment manufacturers in North Rhine-Westphalia represent acquisition targets to lock in high-speed twin-chamber system capabilities. For New Entrants and Emerging Players: Capture nutraceutical probiotic-meal-pairing white space where laser-scored peelable seal demand outstrips qualified converter capacity. Indian and Middle Eastern export markets offer penetrable entry points given Uflex Ltd. capacity constraints and FSSAI framework standardization. Direct-to-consumer subscription channel specialization enables bypass of entrenched retail converter relationships. For Investors and Strategic Acquirers: Re-rating potential sits with European flexible packaging specialists possessing EFSA REACH compliance infrastructure given enforcement window acceleration. Long-term viability favors converters with demonstrated mono-material detectability and pharmaceutical barrier qualification. The signal to watch is extended producer responsibility scheme finalization recalibrating brand owner-converter cost allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Substrate Transition | EU Green Deal recyclability targets eliminate multi-material laminations, favoring near-infrared detectable single-polymer structures. |
| Laser-Scored Seal Interface Licensing | Proprietary burst-strength calibration technology compresses development cycles for wet-dry component separation applications. |
| Precision Filling Equipment Acquisition | High-speed form-fill-seal systems from Düsseldorf clusters anchor medical and nutritional twin-chamber production capabilities. |
| E-Commerce Resealability Certification | Zip lock and tear notch validation programs capture pet food subscription brand procurement specifications. |
| REACH Compliance Acceleration | Adhesive chemistry reformulation ahead of ECHA enforcement windows secures German retail chain supplier status. |
Research Methodology
Multi-period observation of coextruded film capacity expansions, REACH substance restriction timelines, and laser-scoring patent filings anchored the trend analysis, supplemented by interviews with flexible packaging converters, pharmaceutical brand managers, precision filling equipment engineers, and polymer resin procurement leads. Secondary validation drew from ECHA substance restriction databases, EU PPWR legislative trackers, FDA food contact substance notification records, and German mechanical engineering association production statistics. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across material type and closure mechanism categories.
Input-output matrices mapped resin feedstock availability through converter processing capacity to end-use demand across food, pharmaceutical, personal care, and household product verticals. Segmentation dimensions encompassed material substrate, closure mechanism, end-use application, and distribution channel intensity. CAGRs were derived from equipment installation rates, regulatory compliance deadline clustering, and channel shift velocity indicators including e-commerce penetration in pet food and nutraceutical segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to extended producer responsibility scheme implementation timing and mechanical recycling infrastructure buildout rates. Forecasts reflect documented assumptions regarding REACH substance substitution curves and mono-material detectability technology maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pouch Dispensing Fitment Market
Pouch
Stand Up Paper Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
Bio PE Pouches Market
Pouch
Slider Pouches Market
Pouch
Clipless Vertical Pouches Market
Pouch
Twist Wrap Packaging Market
Pouch
India Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Feminine Care Pouch Film Market
Pouch
Flexible Plastic Pouches Market
Pouch
Pouch-Bowl Packaging Market
Pouch
GCC Retort Pouches Market
Pouch
Poland Pouch Packaging Market