
 Almond Oil Market | 2026-2036
Almond Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Oil Market Analysis
Asset-light contract processing and toll-refining arrangements is narrowing the capital barrier for mid-tier entrants in almond oil extraction. Blue Diamond Growers leverages its captive California almond supply to sustain vertical integration from orchard to refined oil. AAK AB anchors European demand through its specialty fats and oils division, while Croda International Plc differentiates via pharmaceutical-grade purification capabilities.
Almond oil is a fixed oil expressed from Prunus dulcis kernels, containing approximately 70% oleic acid and 20% linoleic acid with a smoke point near 215°C for refined grades; its primary commercial purpose spans emollient delivery in cosmetics, carrier oil functionality in aromatherapy, and oxidative-stability applications in food formulations. Sweet almond oil occupies the dominant volume position due to its safety profile for dermal application, while unrefined variants command premium positioning in clean-label skincare channels. Pharmaceutical applications represent the fastest-growing application segment as nutraceutical firms seek GRAS-validated lipid excipients.
FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act and ECHA REACH registration requirements for imported botanical oils collectively elevate compliance costs for cross-border suppliers. USDA organic certification and ISO 22000 food safety management standards further segment market access by quality tier. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates and California agricultural water allocation policies that directly impact kernel supply security.
Market Dynamics
REACH compliance in Europe is tightening impurity thresholds for cosmetic-grade oils, forcing processors to upgrade purification infrastructure and reshaping competitive access across supply corridors.
Growth Catalysts
- Clean-label formulation mandates:Skincare brands in California and Mediterranean markets are expanding almond oil procurement for preservative-free emollient systems, pulling volume through certified organic channels.
- Nutraceutical excipient validation:Pharmaceutical-grade lipid demand is accelerating as GRAS-validated carriers displace synthetic alternatives in softgel and parenteral formulations.
- Water-efficient cultivar adoption:California's agricultural water allocation policies are driving orchard renovation toward drought-tolerant rootstocks, securing kernel supply density in the Central Valley processing cluster.
Market Restraints
- Kernel supply concentration:California's Central Valley and select Mediterranean corridors control over 80% of commercial almond production, exposing processors to climate-induced yield volatility and irrigation quota restrictions.
- Refining capex intensity:Pharmaceutical-grade purification requires molecular distillation and supercritical CO2 extraction equipment, creating capital barriers for mid-tier entrants lacking toll-refining partnerships.
- Botanical oil substitution:Jojoba and squalane derivatives are capturing premium skincare share where oxidative stability and skin-feel equivalence satisfy formulator requirements.
Strategic Opportunities
- EU Deforestation Regulation traceability:Early compliance with EUDR geolocation and chain-of-custody mandates will unlock preferential access to European cosmetic and food formulation channels ahead of enforcement deadlines.
- Aromatherapy channel expansion:Direct-to-practitioner distribution through certified aromatherapy schools and wellness clinics is bypassing conventional cosmetic ingredient distributors in Germany and France.
- Upcycled byproduct valorization:Cold-press cake and hull biomass streams are converging with biogas and animal feed applications, converting waste liabilities into revenue offsets for integrated processors.
Industry Challenges
- Pharmaceutical-grade certification timelines:ISO 22000 and EXCiPACT audits require 12-18 month validation cycles, delaying market entry for new refining capacity.
- Legacy ERP integration:Batch-level traceability systems for EUDR compliance must interface with existing orchard management and toll-refining platforms, creating data architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Oil Market |
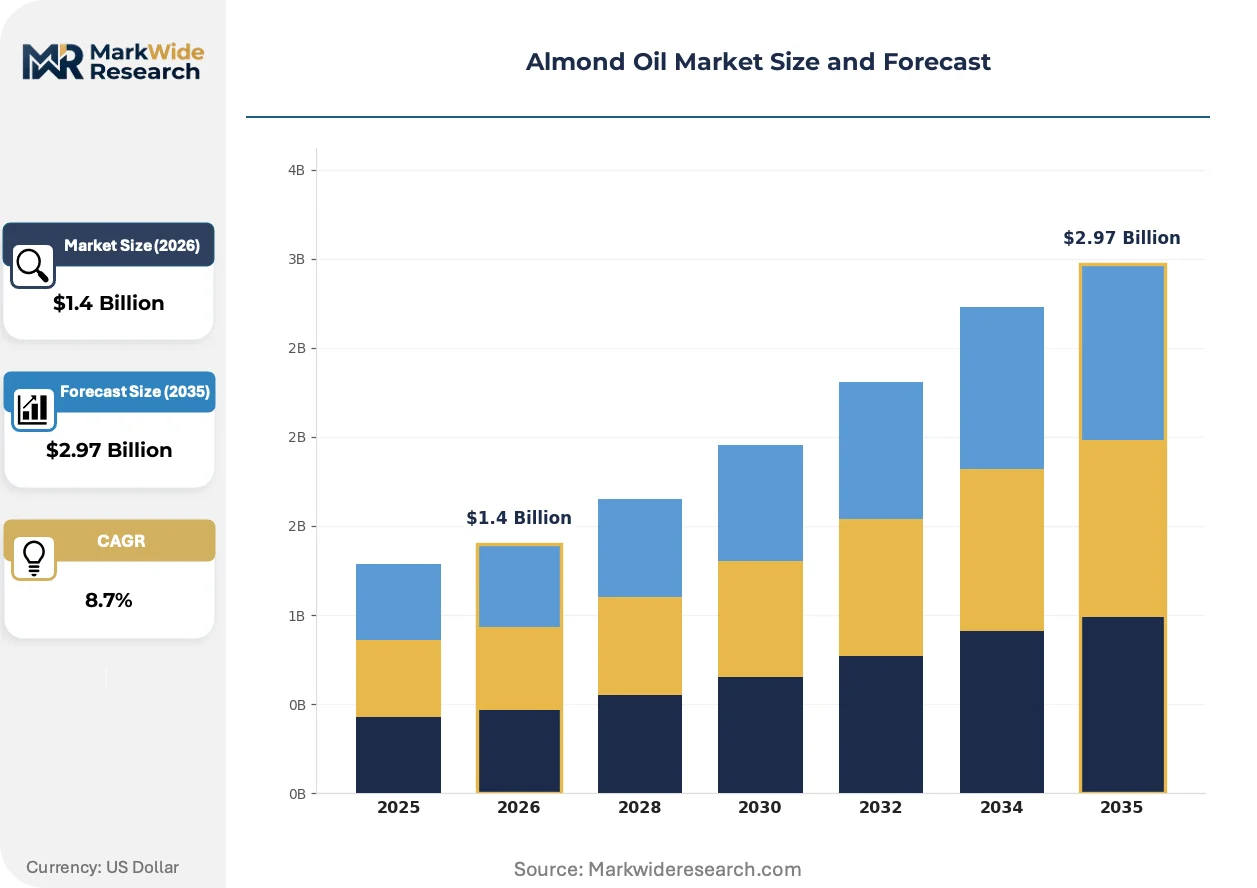
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Almond Oil, Bitter Almond Oil, Refined Almond Oil, Unrefined Almond Oil Application: Cosmetics, Culinary, Pharmaceutical, Food Additive End User: Households, Food Manufacturers, Skincare Brands, Nutraceutical Firms Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Blue Diamond Growers, Inc., Caloy Company, LP, AOS Products Private Limited, Jiangxi Baicao Pharmaceutical Co., Ltd., Proteco Oils Pty Ltd, Liberty Vegetable Oil Company, Ashwin Fine Chemicals & Pharmaceuticals, Croda International Plc, AAK AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Oil Market Emerging Trajectories
Supercritical CO2 extraction is displacing conventional solvent-based refining across premium segments, while regulatory traceability mandates and direct-procurement models are compressing traditional distribution layers.
Supercritical CO2 extraction systems operate at near-ambient temperatures, preserving heat-sensitive tocopherols and phytosterols that confer oxidative stability. Cosmetic formulators in France and Switzerland are specifying CO2-extracted grades for high-margin facial oil serums. Conventional hexane extraction is rendering obsolete for pharmaceutical and clean-label cosmetic applications where residual solvent limits under REACH and FDA guidance create compliance exposure.
EUDR geolocation requirements now mandate polygon mapping of all orchard plots supplying EU-bound almond products, with due diligence statements required from January 2025. This policy shift fragments supplier qualification workflows, forcing importers to maintain parallel traceability systems for EU and non-EU destinations. Smallholder-dependent supply corridors in Spain and Italy face the steepest compliance cost escalation relative to vertically integrated California processors.
Beauty brand procurement teams are consolidating supplier rosters around integrated processors offering certified organic, food-grade, and pharmaceutical-grade tiers from common origin documentation. This concentration is displacing fragmented spot-market purchasing through commodity brokers. The shift is most visible in German and UK markets where retailer ESG audit requirements demand single-point accountability for deforestation and labor compliance.
Almond Oil Market Segmentation
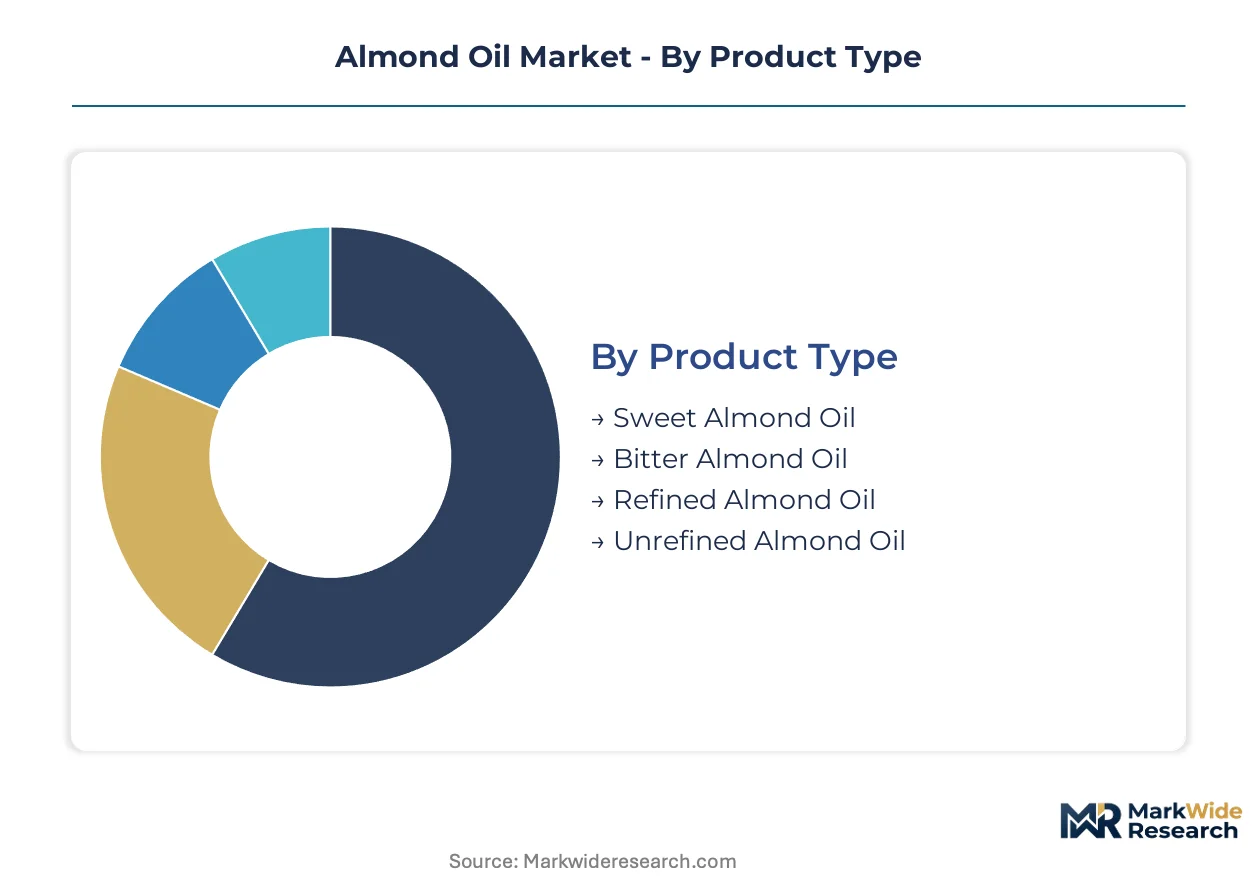
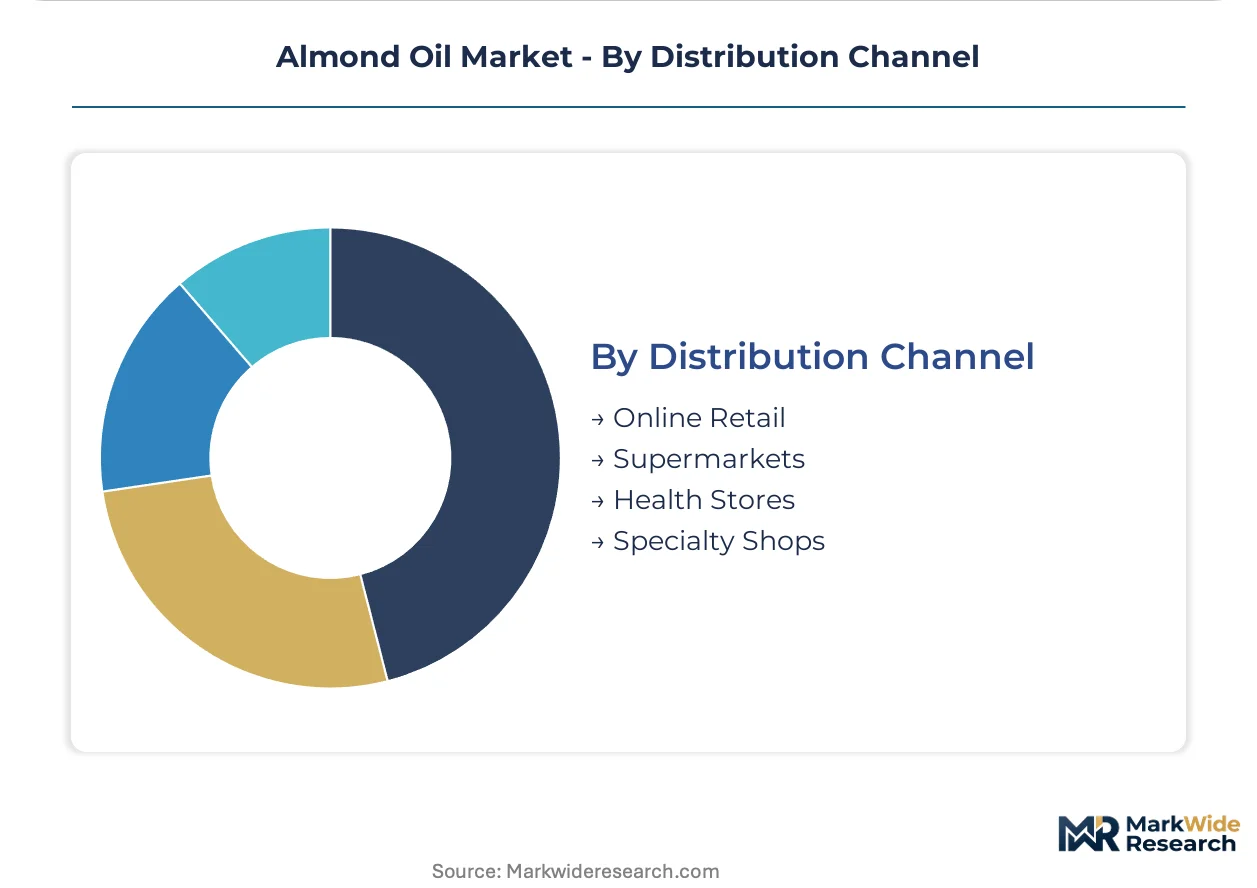
Almond oil segmentation reveals divergent margin structures and compliance burdens across grades and channels. Product type determines refining investment intensity, while application segments impose distinct regulatory validation timelines that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product grades, with pharmaceutical and cosmetic buyers demanding batch-specific certificates of analysis and traceability documentation that unrefined food-grade purchasers rarely require.
- Sweet Almond Oil:Comprising approximately 70% oleic acid and 20% linoleic acid with a smoke point near 215°C for refined grades. Demand concentrates in California's Central Valley processing cluster where skincare brands source certified organic volumes for clean-label emollient systems, constrained by drought-tolerant rootstock conversion timelines.
- Unrefined Almond Oil:Cold-pressed at temperatures below 40°C to preserve tocopherols and phytosterols. Premium positioning in French and Swiss facial serum formulations drives procurement through direct-procurement models, though shorter shelf life limits inventory holding strategies.
- Bitter Almond Oil:Derived from Prunus dulcis var. amara kernels containing amygdalin; requires denaturation or purification for safe cosmetic use. Niche aromatherapy applications in German wellness clinics.
- Refined Almond Oil:Solvent-extracted or physically refined to achieve neutral flavor and extended oxidative stability. Food manufacturers in Mediterranean corridors specify this grade for frying and baking applications.
By volume, Refined Almond Oil leads. By growth pace, Unrefined Almond Oil is ahead.
Application:
Cost tier differentiation separates commodity food additive volumes from pharmaceutical-grade excipients commanding five-fold price multiples for equivalent kernel input.
- Cosmetics:Emollient delivery and carrier oil functionality dominate formulation demand. REACH compliance in Europe tightens impurity thresholds, forcing processors to upgrade supercritical CO2 extraction infrastructure for EU-bound shipments.
- Pharmaceutical:GRAS-validated lipid excipients for softgel and parenteral formulations. ISO 22000 and EXCiPACT audits require 12-18 month validation cycles, creating certification barriers for new refining capacity.
- Culinary:Oxidative-stability applications in premium cooking oils and finishing drizzles. Mediterranean supply corridors concentrate procurement for traditional consumption patterns.
- Food Additive:Flavor carrier and texturizing agent in processed foods. Price-sensitive procurement through commodity brokers faces compression from integrated processor direct sales.
Cosmetics commands the largest revenue pool. Pharmaceutical applications are expanding most quickly.
End User:
Customer type determines order frequency and specification stringency, with nutraceutical firms placing large annual contracts against household spot purchasing through retail channels.
- Skincare Brands:Clean-label formulation mandates pull volume through certified organic channels, with EUDR geolocation requirements now mandating polygon mapping of all orchard plots.
- Nutraceutical Firms:Pharmaceutical-grade lipid demand accelerates as GRAS-validated carriers displace synthetic alternatives.
- Food Manufacturers:Bulk procurement of refined grades for formulation integration; USDA organic certification segments market access by quality tier.
- Households:Small-format retail purchasing through online and health store channels; price sensitivity highest in this segment.
Food Manufacturers move the greatest tonnage. Nutraceutical Firms show the steepest expansion trajectory.
Distribution Channel:
Supply concentration in California and Mediterranean corridors shapes channel economics, with direct-procurement models compressing traditional broker layers for large-volume buyers.
- Online Retail:Direct-to-practitioner distribution through certified aromatherapy schools bypasses conventional cosmetic ingredient distributors in Germany and France.
- Specialty Shops:Premium unrefined grades with origin documentation; ESG audit requirements from UK retailers demand single-point accountability.
- Supermarkets:Mass-market refined culinary oils; price competition intensifies with private label penetration.
- Health Stores:Organic-certified sweet almond oil for wellness consumers; inventory turnover constraints favor established brands with replenishment reliability.
Supermarkets dominate volume throughput. Online Retail channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Deforestation Regulation traceability mandates and California water allocation policies are restructuring procurement geography for almond oil, concentrating investment in compliant supply corridors.
United States
California's Central Valley processing cluster dominates kernel supply for cosmetic and pharmaceutical grades. The state's agricultural water allocation policies are accelerating orchard renovation toward drought-tolerant rootstocks. Fresno and Modesto house integrated processors offering certified organic, food-grade, and pharmaceutical-grade tiers from common origin documentation.
Germany
REACH compliance tightens impurity thresholds for cosmetic-grade oils, forcing processors to upgrade supercritical CO2 extraction infrastructure. Hamburg and Frankfurt serve as distribution hubs for EU-bound pharmaceutical excipient volumes. German nutraceutical firms place large annual contracts for GRAS-validated lipid carriers.
France
Clean-label skincare brands in Paris and Lyon are expanding procurement of cold-pressed unrefined grades for facial serum formulations. ANSM oversight of cosmetic ingredient safety elevates documentation requirements. Provence-Alpes-Côte d'Azur hosts specialty distributors serving aromatherapy practitioners directly.
India
FSSAI food safety standards and emerging CDSCO pharmaceutical excipient guidelines segment market access by quality tier. Gujarat and Rajasthan concentrate cold-press extraction capacity for domestic cosmetic and export food-grade volumes. Mumbai-based traders coordinate spot-market purchasing for price-sensitive food additive applications.
Australia
TGA pharmaceutical manufacturing standards and organic certification requirements shape export competitiveness. Victoria's almond growing regions supply kernel stock to toll-refining arrangements for Asian cosmetic brand customers. Sydney distributors manage direct-procurement relationships bypassing traditional commodity brokers.
Almond Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Vertically integrated processors with captive orchard supply dominate pharmaceutical and premium cosmetic segments. Toll-refining specialists serve mid-tier entrants lacking capital for molecular distillation equipment. Regional commodity brokers face compression as beauty brands consolidate supplier rosters. Dominant competitive moves include backward integration into kernel supply and portfolio diversification across organic, food-grade, and pharmaceutical-grade tiers.
Among integrated processors with agricultural origins, Blue Diamond Growers exemplifies the orchard-to-refined-oil archetype through its captive California supply base. AAK AB anchors European demand through specialty fats and oils capabilities, while Croda International Plc occupies a position emphasizing pharmaceutical-grade purification standards. Jiangxi Baicao Pharmaceutical Co., Ltd. and AOS Products Private Limited represent Asia-Pacific contract processing specialists serving toll-refining demand.
| Leading Market Players |
|---|
| Blue Diamond Growers, Inc. |
| Caloy Company, LP |
| AOS Products Private Limited |
| Jiangxi Baicao Pharmaceutical Co., Ltd. |
| Proteco Oils Pty Ltd |
| Liberty Vegetable Oil Company |
| Ashwin Fine Chemicals & Pharmaceuticals |
| Croda International Plc |
| AAK AB |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting California's Central Valley to Rotterdam and Hamburg transmit cost volatility from fuel surcharges and container availability directly into European landed prices, amplifying spreads between pharmaceutical-grade and commodity food-grade almond oil tiers while reinforcing procurement consolidation around integrated processors with captive supply.
Pricing Analysis
Certification level creates the primary spread across almond oil tiers, with ISO 22000 and EXCiPACT-validated pharmaceutical grades commanding substantial premiums over unrefined cosmetic and refined food-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects vertical integration depth, with Blue Diamond Growers and AAK AB capturing margin through captive kernel supply. Cost compression in commodity food-grade channels is intensifying because toll-refining partnerships are narrowing capital barriers for mid-tier entrants. Household retail purchasers exhibit highest price sensitivity, while nutraceutical firms placing large annual contracts demonstrate lowest sensitivity due to excipient validation requirements.
Supply Chain Analysis
Toll-refining specialists including AOS Products Private Limited and Jiangxi Baicao Pharmaceutical Co., Ltd. concentrate contract processing capacity for Asian cosmetic brand customers lacking molecular distillation infrastructure. Kernel supply draws from California's Central Valley, Spain's Mediterranean corridors, and Australia's Victoria region, with drought-tolerant rootstock conversion timelines constraining expansion. Supply chain risk centers on irrigation quota restrictions under California agricultural water allocation policies. Distribution runs through direct-procurement relationships that compress traditional commodity broker layers for large-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Almond oil procurement is becoming a service-attach opportunity as batch-specific certificates of analysis and EUDR geolocation documentation expand faster than base oil volumes, creating recurring-revenue layers for integrated processors with traceability infrastructure.
For Market Incumbents: Entrench pharmaceutical-grade certification advantages by accelerating EXCiPACT audit completion ahead of competitor capacity additions, while securing backward integration into drought-tolerant orchard renovation to defend against climate-induced yield volatility. Expand toll-refining partnerships to capture mid-tier entrant volume without direct capital deployment. For New Entrants and Emerging Players: Build out certified organic unrefined capacity serving French and Swiss facial serum formulators, where direct-procurement models bypass established distributor relationships. Target German aromatherapy practitioner channels through certified school partnerships as the most penetrable white-space segment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated processors with captive California supply and multi-grade certification capabilities. Long-term viability hinges on EUDR compliance infrastructure and water-rights security. Watch California agricultural water allocation policy announcements as the primary inflection signal for kernel supply cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Supply | Captive kernel access insulates processors from California irrigation quota volatility. |
| Pharmaceutical-Grade Certification Investment | EXCiPACT validation unlocks five-fold price multiples in nutraceutical excipient channels. |
| EUDR Traceability Infrastructure Deployment | Polygon mapping and chain-of-custody systems secure preferential EU market access. |
| Supercritical CO2 Extraction Capacity Addition | Near-ambient temperature processing preserves tocopherols for premium cosmetic specifications. |
| Direct-to-Practitioner Distribution Expansion | Bypassing conventional cosmetic ingredient distributors captures margin in German aromatherapy channels. |
Methodological Framework
Desk research of customs trade records, ECHA REACH registration databases, and USDA organic certification filings preceded structured interviews with almond oil procurement managers at skincare brands, toll-refining operations directors, and regulatory affairs leads at nutraceutical firms. Primary fieldwork across California's Central Valley processing cluster and Mediterranean supply corridors was cross-validated against secondary data from FDA cosmetic ingredient guidance documents and EU Deforestation Regulation implementation notices. Bottom-up kernel supply modeling and top-down end-use demand estimation were triangulated to establish volume and value baselines.
Assumptions regarding California agricultural water allocation policy stability, REACH compliance threshold evolution, and drought-tolerant rootstock adoption rates were held fixed across baseline scenarios while EUDR enforcement timing and pharmaceutical excipient validation demand were varied in sensitivity analysis. Segmentation modeling spanned product grade tier, application end-use, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves against historical kernel production data and projected cosmetic formulation demand across the analysis window.
Stress conditions across California drought severity indices, EU regulatory enforcement intensity, and jojoba oil substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including climate-induced yield volatility and botanical oil competitive displacement. Quarterly review of California State Water Resources Control Board allocation announcements and EUDR due diligence system adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
South America Nut-Based Spread Market