
 Nutmeg Market | 2026-2036
Nutmeg Market Size, Share, and Industry Trends Forecast 2026-2036
Nutmeg Market Outlook
Pharmaceutical applications for nutmeg-derived compounds is rebalancing procurement priorities among major processors. McCormick & Company sustains broad retail distribution across North American grocery channels. Olam International anchors origin sourcing through its integrated Indonesian supply operations. Spice Jungle differentiates via direct-to-consumer organic and specialty grade offerings.
Nutmeg comprises the dried seed kernel of Myristica fragrans, typically containing 25-40% fixed oil and 5-15% essential oil with myristicin as the primary aromatic constituent, used commercially as a flavoring agent, fragrance precursor, and traditional medicine ingredient. Ground nutmeg occupies the largest volume share among product types due to its convenience in industrial food processing, while nutmeg oil commands premium positioning in pharmaceutical and cosmetics applications where standardization of active compounds matters. The food and beverages application segment leads absolute consumption, though dietary supplements represents the fastest-growing channel as functional ingredient interest expands.
FDA oversight of myristicin content in dietary supplements and EPA agricultural import protocols shape product specifications for US-bound shipments. Indonesia's national food safety agency and BIS quality standards in India further define acceptable residue limits and grading classifications. Stakeholders must monitor evolving myristicin thresholds across jurisdictions to maintain formulation compliance and market access continuity.
Market Dynamics
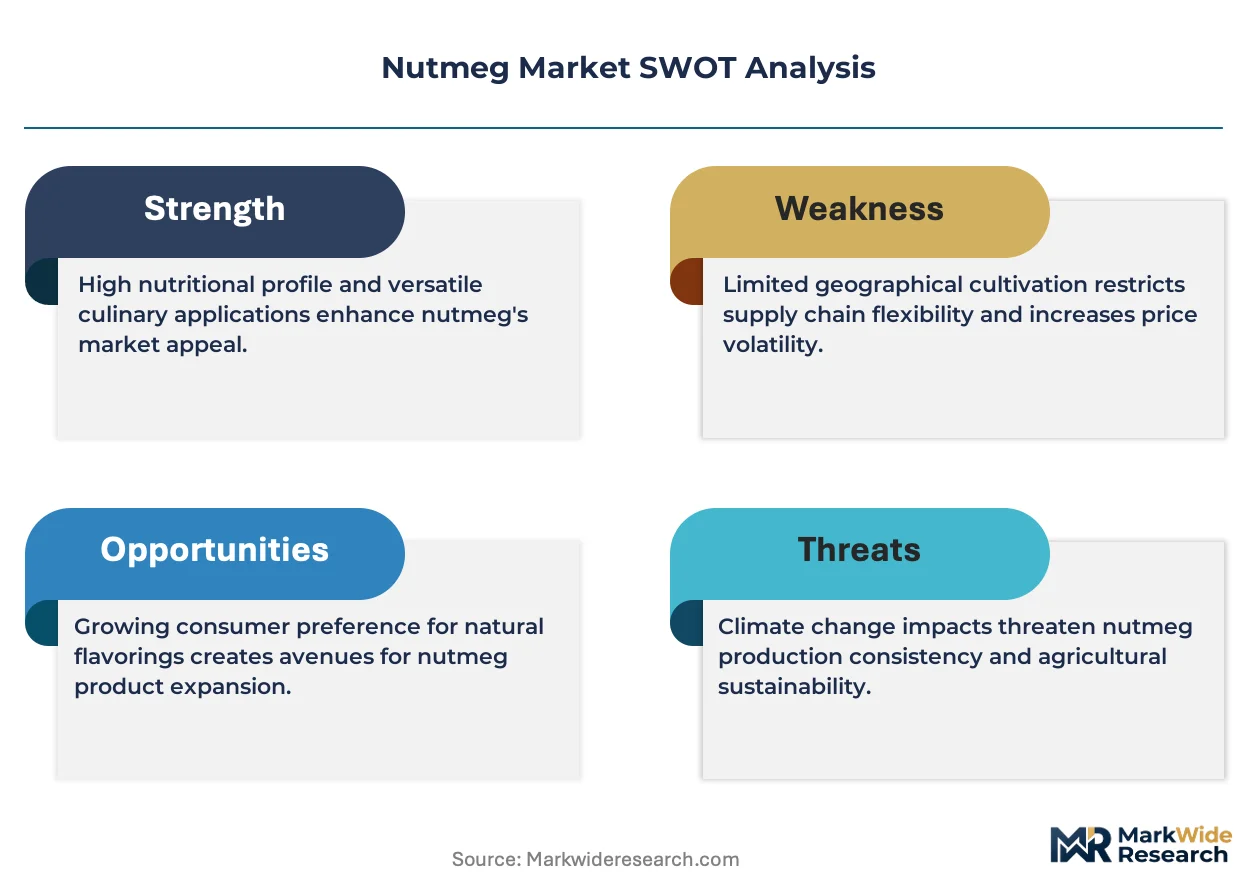
The nutmeg market's structural center of gravity tilts on Indonesia's concentrated origin supply and tightening myristicin thresholds in import jurisdictions, forcing processors to rebuild compliance infrastructure around residue testing and lot traceability.
Growth Catalysts
- Clean-label formulation mandates:Food manufacturers in North America and Europe are eliminating artificial flavorants, pulling natural nutmeg extracts into reformulated sauces, baked goods, and beverage bases.
- REACH-compliant distillation upgrades:European processors investing in closed-loop essential oil extraction are capturing pharmaceutical-grade myristicin fractions that command formulation premiums in regulated markets.
- Indonesian export infrastructure modernization:Port cold-chain investments in Ambon and Surabaya are reducing post-harvest aflatoxin exposure, expanding shelf-stable shipment windows to temperate-climate buyers.
Market Restraints
- Input cost volatility:Indonesian smallholder labor costs and sulfur-based post-harvest treatment chemicals fluctuate with fuel price swings, compressing processor margins on standard-grade ground nutmeg.
- Supply concentration risk:Over 70% of global export volume originates from Maluku and North Sulawesi provinces, exposing buyers to localized drought, pest cycles, and port congestion.
- Regulatory friction:The EU's updated Food Additives Regulation imposes descending myristicin limits that disqualify legacy oil batches, forcing inventory write-downs and reformulation costs.
Strategic Opportunities
- Underpenetrated dietary supplement channel:Functional ingredient brands in Germany and the United States are developing standardized myristicin capsules for sleep and cognitive positioning, creating pull-through for laboratory-verified extracts.
- Organic certification arbitrage:USDA Organic and EU Organic-accredited Indonesian cooperatives are capturing 40-60% price premiums over conventional grades in direct-to-consumer channels.
- Cosmetics convergence with terpene science:Fragrance houses combining nutmeg oil with synthetic biology-derived musks are opening high-margin personal care applications beyond traditional spice use.
Industry Challenges
- Analytical chemistry skill scarcity:Commercial labs capable of ISO 17025-compliant myristicin quantification are concentrated in Jakarta and Singapore, creating testing bottlenecks for regional processors.
- Certification timeline compression:FSSAI import clearance in India and FDA prior notice requirements for dietary supplement raw materials are extending order-to-delivery cycles beyond historical norms.
- Legacy traceability infrastructure:Paper-based smallholder documentation in Eastern Indonesia conflicts with blockchain-enabled buyer requirements, forcing intermediaries to absorb digitization costs.
Report Scope
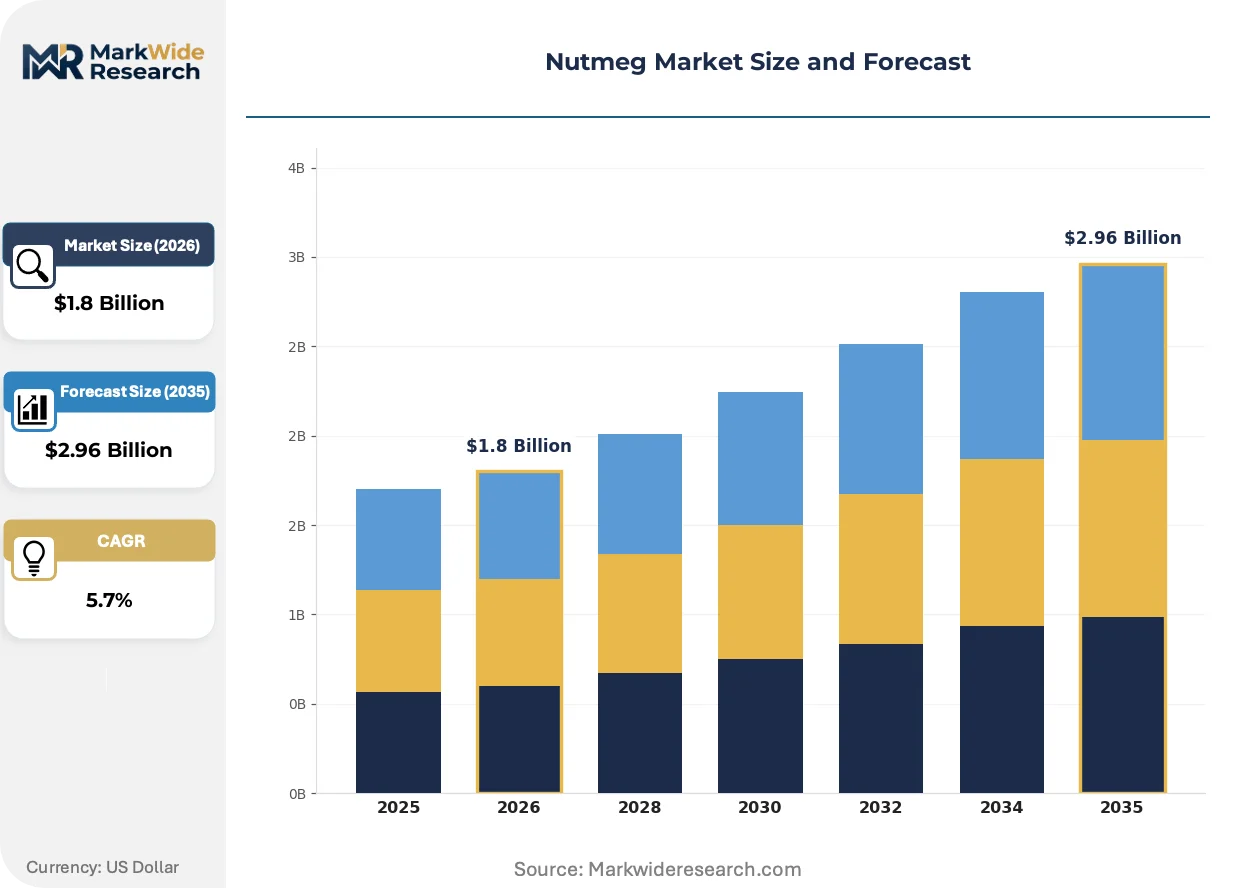
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutmeg Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Nutmeg, Ground Nutmeg, Nutmeg Oil, Nutmeg Extract Application: Food & Beverages, Pharmaceuticals, Cosmetics, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors End User: Restaurants, Food Manufacturers, Retail Consumers, Bakers |
| Companies Covered | Goya Foods, Inc., Spice Jungle, McCormick & Company, Doehler Group SE, Watkins Incorporated, Olam International, Mountain Rose Herbs, Penzeys Spices, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutmeg Market Strategic Shifts
Supercritical CO2 extraction technology and myristicin-standardized fractionation are displacing conventional steam distillation, while regulatory divergence between FDA dietary supplement guidance and EU novel food classifications is fragmenting formulation strategies across Atlantic markets.
Supercritical CO2 extraction systems operating at 300 bar and 50°C are capturing essential oil yields 15-20% above atmospheric steam methods while preserving heat-labile terpenoids. Pharmaceutical contract manufacturers in Switzerland and the United States are adopting these units for GMP-certified active pharmaceutical ingredient precursor production. This precision is rewriting the economics of myristicin isolation, compressing batch-to-batch variability from 12% to under 3% and enabling therapeutic-grade claims previously unavailable to botanical extract suppliers.
The EU's 2023 Food Additives Regulation amendment establishing maximum myristicin levels in nutmeg oil imports is forcing non-European processors to install in-house HPLC testing or surrender market access. Indonesian exporters without laboratory partnerships are redirecting volumes to Middle Eastern and Asian markets with less stringent residue frameworks. Pharmaceutical-grade oil shipments bound for European compounding pharmacies now require third-party certificates from EMA-recognized analytical laboratories, adding 8-12% landed cost premiums.
Direct-procurement contracts between North American dietary supplement brands and Indonesian organic cooperatives are displacing traditional Amsterdam and Singapore spice trading houses. These arrangements specify myristicin content ranges, aflatoxin limits, and harvest date windows that commodity brokers cannot guarantee. The shift is most visible in Utah and California, where vertically integrated supplement manufacturers are securing three-year offtake agreements to lock in organic certification continuity and price hedges against currency volatility.
Nutmeg Market Segmentation
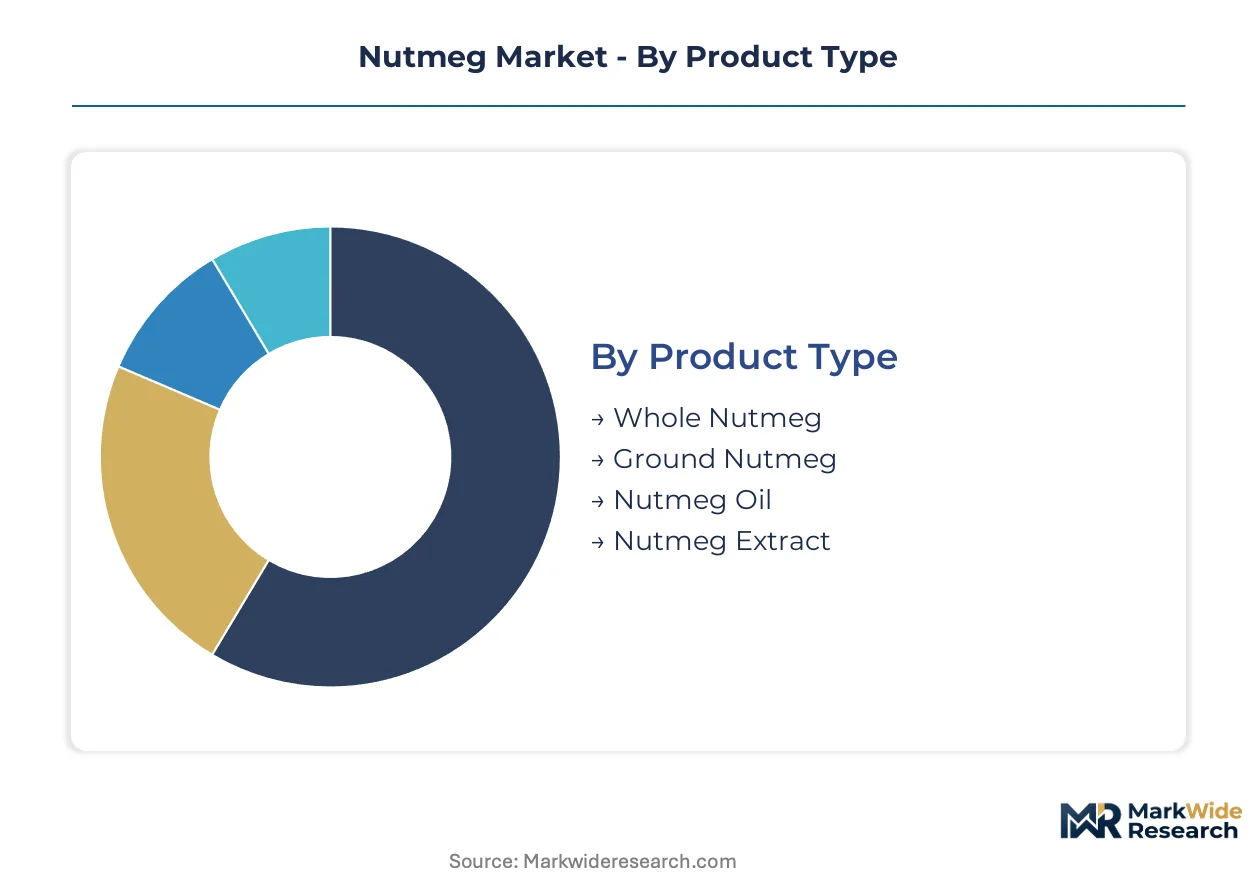
Nutmeg processors configure production lines around physical form factors and extraction depth, with capital deployment varying dramatically between simple grinding operations and supercritical CO2 systems. Segmentation clarity enables buyers to match procurement specifications with end-use compliance requirements across food, pharmaceutical, and cosmetics channels.
Product Type:
Capital intensity escalates sharply from basic post-harvest handling through precision extraction infrastructure, separating commodity processors from specialized fractionation operators.
- Whole Nutmeg:Dried seed kernels retain the fixed oil reservoir within the intact endosperm, requiring only sorting, grading, and sulfur-based surface treatment equipment. Indonesian smallholder cooperatives in Maluku and North Sulawesi dominate export volume, with EU-bound shipments facing escalating aflatoxin testing costs at Rotterdam and Hamburg entry points.
- Ground Nutmeg:Mechanical milling to 40-60 mesh particle size releases aromatic volatiles and accelerates oxidation, demanding nitrogen-flush packaging lines and moisture-controlled storage. North American industrial bakeries and sauce manufacturers absorb the largest share, though margin compression from energy-intensive grinding operations is pushing mid-tier processors toward toll-manufacturing arrangements.
- Nutmeg Oil:Steam-distilled essential oil containing 4-8% myristicin by weight serves fragrance compounding and traditional medicine formulations. Swiss and German pharmaceutical contract manufacturers are capturing premium positioning through GMP-certified distillation upgrades.
- Nutmeg Extract:Supercritical CO2 and ethanol-based concentrates standardize myristicin content for dietary supplement encapsulation. Utah and California supplement brands are locking in three-year offtake agreements with Indonesian organic cooperatives to secure laboratory-verified active compound ranges.
Ground nutmeg absorbs the bulk of installed capacity; nutmeg extract is expanding most quickly.
Application:
Formulation standards diverge sharply across end-use categories, with pharmaceutical and supplement channels imposing analytical chemistry requirements that food-grade processors rarely maintain.
- Food & Beverages:Clean-label reformulation in sauces, baked goods, and beverage bases pulls natural nutmeg extracts into industrial-scale production. FDA flavorant regulations and EU Food Additives Regulation myristicin thresholds force dual-track specification management for Atlantic-crossing suppliers.
- Pharmaceuticals:Myristicin-standardized fractions serve as active pharmaceutical ingredient precursors for neurological and antimicrobial research programs. EMA-recognized laboratory certification from Swissmedic and BfArM-compliant German processors creates qualification bottlenecks for origin-country exporters.
- Cosmetics:Fragrance houses combine nutmeg terpenoids with synthetic biology-derived musks for personal care positioning. REACH-compliant European formulators are capturing margin premiums through documented supply chain sustainability credentials.
- Dietary Supplements:Standardized myristicin capsules targeting sleep and cognitive positioning are climbing the fastest among application channels. FSSAI import clearance in India and FDA prior notice requirements are extending order-to-delivery cycles beyond historical norms.
Food and beverages commands absolute volume; dietary supplements is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and certification continuity, with direct procurement contracts displacing traditional trading house intermediaries in premium segments.
- Online Retail:Direct-to-consumer platforms enable organic and specialty grade positioning with 40-60% price premiums over conventional grades. Spice Jungle and comparable specialty operators are building USDA Organic and EU Organic-accredited supply relationships that commodity brokers cannot replicate.
- Supermarkets:Mass-market retail distribution requires McCormick-scale brand recognition and broad grocery channel penetration. North American shelf placement demands compliance with retailer-specific residue documentation and packaging sustainability mandates.
- Specialty Stores:Ethnic grocery and gourmet food retailers serve diaspora communities and premium home cooking segments. Amsterdam and Singapore trading houses historically dominated this channel, though Indonesian cooperative direct sales are eroding their position.
- Distributors:Industrial ingredient brokers manage volume aggregation for food manufacturers and pharmaceutical compounders. Blockchain-enabled traceability requirements from major buyers are forcing digitization investments that paper-based smallholder documentation cannot satisfy.
Supermarkets and distributors handle the majority of volume flow; online retail is climbing fastest.
End User:
User sophistication around myristicin content and residue documentation varies enormously, from industrial-scale specification compliance to household convenience purchasing.
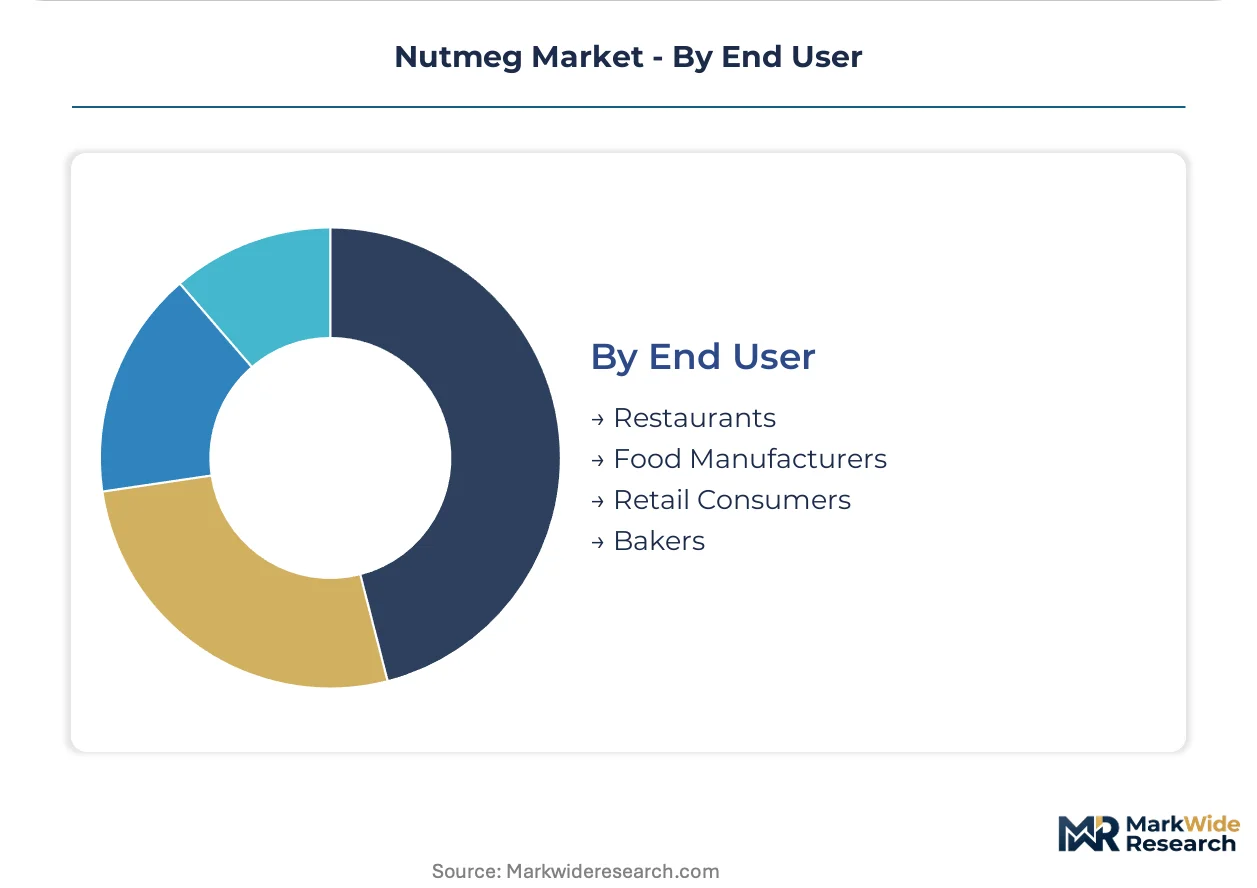
- Restaurants:Commercial kitchen demand concentrates in whole and coarse-ground formats for sauce and dessert finishing. Indonesian supply concentration creates vulnerability to port congestion at Surabaya and Ambon during peak harvest windows.
- Food Manufacturers:Industrial-scale procurement specifies aflatoxin limits, mesh size, and myristicin content ranges that smallholder aggregators struggle to guarantee. Direct-procurement contracts with organic cooperatives are displacing traditional spice trading houses for premium formulations.
- Retail Consumers:Supermarket and online purchasing decisions hinge on organic certification, packaging convenience, and brand recognition. Price sensitivity in this segment is compressing margins for standard-grade ground nutmeg processors.
- Bakers:Artisan and industrial baking operations require consistent volatile oil content for flavor profile stability. Ground nutmeg occupies the dominant format due to dispensing convenience, though oxidation-sensitive operations are shifting toward nitrogen-flush packaging specifications.
Food manufacturers absorb the bulk of procurement volume; dietary supplement channel end users are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Maluku Islands special economic zone status for spice processing concentrates origin supply infrastructure, drawing downstream investment into Ambon and Surabaya port facilities that handle over 70 percent of global export volume.
Indonesia
Maluku and North Sulawesi smallholder cooperatives supply whole nutmeg to European compounders seeking REACH-compliant distillation inputs. The national food safety agency enforces aflatoxin testing protocols that redirect non-compliant batches to Middle Eastern markets. Surabaya's cold-chain port investments reduce post-harvest spoilage for pharmaceutical-grade oil shipments bound for Swissmedic-certified processors.
United States
Utah and California dietary supplement manufacturers lock in three-year offtake agreements with Indonesian organic cooperatives for myristicin-standardized extracts. FDA prior notice requirements for botanical raw materials extend order-to-delivery cycles beyond historical norms. McCormick & Company sustains broad retail distribution across grocery channels requiring retailer-specific residue documentation.
Germany
Fragrance houses in Hamburg combine nutmeg terpenoids with synthetic biology-derived musks for personal care formulations. BfArM compliance mandates for pharmaceutical-grade extracts create qualification bottlenecks for origin-country exporters. REACH-compliant closed-loop distillation systems capture premium positioning in regulated European markets.
India
FSSAI import clearance protocols for spice raw materials compress margins on standard-grade ground nutmeg shipments. Mumbai and Kochi trading houses historically dominated regional volume aggregation. BIS quality standards define acceptable residue limits that disqualify legacy oil batches from European re-export channels.
Switzerland
Swissmedic-certified pharmaceutical contract manufacturers adopt supercritical CO2 extraction systems for GMP-certified active pharmaceutical ingredient precursor production. Basel and Zurich clusters specialize in myristicin fractionation for neurological research programs. EMA-recognized laboratory certification requirements add landed cost premiums for third-party analytical verification.
Nutmeg Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with retail grocery concentration favoring scale players while pharmaceutical and supplement channels reward laboratory-verified sourcing relationships. The vendor base organizes around three strategic archetypes: origin-integrated agricultural conglomerates, North American brand houses with broad retail penetration, and direct-to-consumer organic specialists capturing certification premiums. Competitive moves center on backward integration into Indonesian cooperative partnerships and capacity expansion in supercritical extraction infrastructure for pharmaceutical-grade output.
Within the origin-integrated tier, Olam International exemplifies agricultural supply chain control through Indonesian operations, while McCormick & Company anchors mass-market retail positioning across North American grocery channels. Spice Jungle occupies the specialty direct-to-consumer vector with organic and premium grade offerings. These three players represent divergent scale and certification strategies rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Goya Foods, Inc. |
| Spice Jungle |
| McCormick & Company |
| Doehler Group SE |
| Watkins Incorporated |
| Olam International |
| Mountain Rose Herbs |
| Penzeys Spices |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Indonesian analytical chemistry specialists concentrated in Jakarta and Singapore drive labor-cost differentials that widen pricing-tier spreads between laboratory-verified extracts and commodity-grade ground nutmeg. Smallholder cooperatives in Maluku absorb lower wage structures than Swiss pharmaceutical contract manufacturers, translating into 40-60% price premiums for certification-intensive grades.
Pricing Analysis
Short lead-time premiums command substantial markups as Utah and California dietary supplement manufacturers pay up for three-year offtake agreements with locked-in myristicin ranges. Spot inventory discounts widen when Indonesian port congestion at Surabaya and Ambon extends delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical extracts from nitrogen-flush packaged ground nutmeg and sulfur-treated whole seeds. Cost compression in standard-grade ground nutmeg intensifies because energy-intensive grinding operations face fuel price volatility. Food manufacturers exhibit highest price sensitivity due to volume procurement and substitution options, while pharmaceutical compounders accept premium positioning for documented active compound standardization.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg serve as quality-control gates for EU-bound shipments, while Singapore and Dubai hubs handle Middle Eastern and Asian re-exports. Raw material flows draw from Indonesian Maluku and North Sulawesi provinces, with secondary sourcing from Grenada and Sri Lanka for specialty organic grades. Sulfur-based post-harvest treatments, nitrogen-flush packaging materials, and HPLC testing reagents constitute critical input dependencies. Single-source vulnerability concentrates in Eastern Indonesian smallholder networks where drought and pest cycles disrupt harvest windows. Distribution runs through Amsterdam and Singapore trading houses for commodity volumes, though direct-procurement contracts are displacing traditional intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutmeg market functions as a cost-of-compliance story where the EU's Food Additives Regulation myristicin thresholds erect barrier-to-entry moats favoring laboratory-capable processors over commodity traders.
For Market Incumbents: Deepen backward integration into Indonesian organic cooperatives to secure certification continuity and price hedges against currency volatility. Add supercritical CO2 capacity in Swissmedic-certified facilities to capture pharmaceutical-grade premium positioning as REACH-compliant distillation upgrades displace legacy steam methods. Defend against emerging direct-to-consumer specialists by locking in three-year offtake agreements with North American supplement brands.
For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer entry wedges into premium food manufacturer supply chains where paper-based smallholder documentation creates compliance bottlenecks. Target dietary supplement encapsulation in Germany and the United States as the most penetrable segment given functional ingredient interest expansion. Pursue USDA Organic and EU Organic accreditation arbitrage through direct-procurement relationships with Eastern Indonesian cooperatives, bypassing Amsterdam trading house markups.
For Investors and Strategic Acquirers: Re-rating potential sits with Swiss and German pharmaceutical contract manufacturers given EMA-recognized laboratory certification requirements that add landed cost premiums and widen margin capture. Long-term viability over a multi-year horizon favors processors with captive supercritical extraction infrastructure and GMP-certified active pharmaceutical ingredient precursor capabilities. Monitor FSSAI import clearance timeline compression in India as an inflection indicator for regulatory friction spreading to other Asian jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indonesian Cooperatives | Captures organic certification premiums and locks in myristicin-standardized supply for pharmaceutical extract production. |
| Supercritical CO2 Capacity Expansion | Enables GMP-certified active pharmaceutical ingredient precursor output for Swissmedic-compliant neurological research programs. |
| Blockchain Traceability Implementation | Satisfies major buyer documentation requirements that paper-based smallholder records cannot support. |
| Direct-to-Consumer Channel Launch | Captures 40-60% price premiums through USDA Organic and EU Organic-accredited specialty grade positioning. |
| REACH-Compliant Distillation Upgrade | Qualifies for European pharmaceutical compounding pharmacy shipments requiring EMA-recognized laboratory certification. |
Study Parameters
Document review covered EU Food Additives Regulation amendments, FDA dietary supplement guidance, and Indonesian national food safety agency protocols, complemented by interviews with spice trading house procurement directors, pharmaceutical contract manufacturing executives, and organic cooperative agronomists. Secondary validation drew from customs and trade data, BIS quality standards documentation, and SEC filings from publicly traded flavor and fragrance houses. Bottom-up volume modeling triangulated against top-down market sizing from processor capacity assessments.
Segmentation outputs reflect product type, application channel, and distribution model dimensions across the projection horizon. CAGRs were derived from historical trade flow analysis and forward-looking procurement contract disclosures. Forecast inputs incorporated myristicin threshold regulatory trajectories, supercritical extraction technology adoption curves, and organic certification expansion rates among Indonesian smallholder networks.
Several conditions sit outside the modeled scope, including abrupt climatic events in Eastern Indonesia, unilateral regulatory threshold revisions by major import jurisdictions, and synthetic biology-derived flavorant substitution breakthroughs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market