
 Almond Products Market | 2026-2036
Almond Products Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Products Market Analysis
Precision roasting and cold-press extraction is reconfiguring how almond processors preserve volatile flavor compounds and extend shelf stability without chemical additives. Blue Diamond Growers leverages its cooperative structure to dominate bulk ingredient supply to North American food manufacturers. The Wonderful Company sustains vertical control from orchards through retail branding, anchoring premium positioning in almond milk and snack categories. Olam International operates a globally distributed sourcing network that navigates seasonal harvest variability across multiple growing regions.
Almond products encompass derivatives of Prunus dulcis kernels processed through blanching, grinding, pressing, or milling into butter, milk, flour, and oil formats with protein contents ranging from 6% in milk to 25% in flour and lipid profiles exceeding 50% in cold-pressed oil, serving functional roles in plant-based nutrition, gluten-free formulation, and clean-label food systems. Almond milk leads product type volume due to its entrenched position in refrigerated beverage cases, while almond flour captures expanding demand from gluten-free bakery applications where fat content and moisture retention prove critical to performance. Within applications, beverages and snacks concentrate margin pools as branded finished goods command price premiums over commodity almond ingredients sold to food manufacturers.
FDA food labeling requirements and USDA organic certification standards shape product claims and market access for almond-based goods sold in the United States, while the EU Green Deal's Farm to Fork strategy pressures imported nut suppliers to document sustainable water use and reduced pesticide residues. California's State Water Resources Control Board imposes groundwater sustainability obligations that directly constrain orchard expansion and elevate compliance costs for growers supplying the bulk of domestic almond output. Stakeholders must monitor how evolving sustainability disclosure rules in the European Union and United States alter procurement criteria for multinational food manufacturers sourcing almond derivatives.
Market Dynamics
California's Sustainable Groundwater Management Act is forcing orchard operators to retire marginal acreage and consolidate water rights, concentrating supply control among capitalized growers while elevating raw nut input costs for downstream processors.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:European food manufacturers face mandatory sustainability disclosure requirements for imported nuts, creating certified-supply premiums for growers documenting reduced pesticide use and water efficiency.
- Precision roasting systems:Thermal profiling technology preserves volatile flavor compounds in nut butter and milk applications, extending clean-label shelf stability without potassium sorbate or synthetic antioxidants.
- Gluten-free bakery expansion:Almond flour captures formulation share from rice and tapioca alternatives where fat content and moisture retention improve crumb structure in artisan bread and pastry segments.
Market Restraints
- Groundwater scarcity:California's State Water Resources Control Board sustainability obligations constrain San Joaquin Valley orchard expansion and elevate compliance costs for growers supplying domestic bulk ingredient demand.
- Oat milk substitution:Oatly and private-label oat beverage brands capture refrigerated case space with lower water footprints and price points, compressing almond milk volume growth in North American retail channels.
- Single-origin supply risk:Eighty percent of global almond output originates from California's Central Valley, exposing processors to climate-induced harvest variability and trade policy disruptions.
Strategic Opportunities
- India FSSAI plant-based labeling clarity:India's food safety regulator is drafting standards for nut-based beverages, opening formal retail channels currently restricted by ambiguous dairy-alternative classification.
- Upcycled almond meal:Oil extraction byproduct streams convert into high-fiber protein ingredients for pet food and aquafeed applications, monetizing waste streams currently sold for cattle feed at commodity prices.
- Direct-to-consumer subscription models:Specialty roasters and small-batch butter producers bypass distributor markups through ecommerce portals, capturing margin pools traditionally allocated to retail slotting fees.
Industry Challenges
- Organic certification timelines:USDA organic transition periods require three years of documented synthetic input abstention, delaying premium pricing access for growers converting conventional orchards.
- Cross-contamination protocols:Peanut-free and tree-nut-segregated production lines demand dedicated processing equipment and sanitation validation, elevating capital intensity for contract manufacturers serving allergen-sensitive brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Products Market |
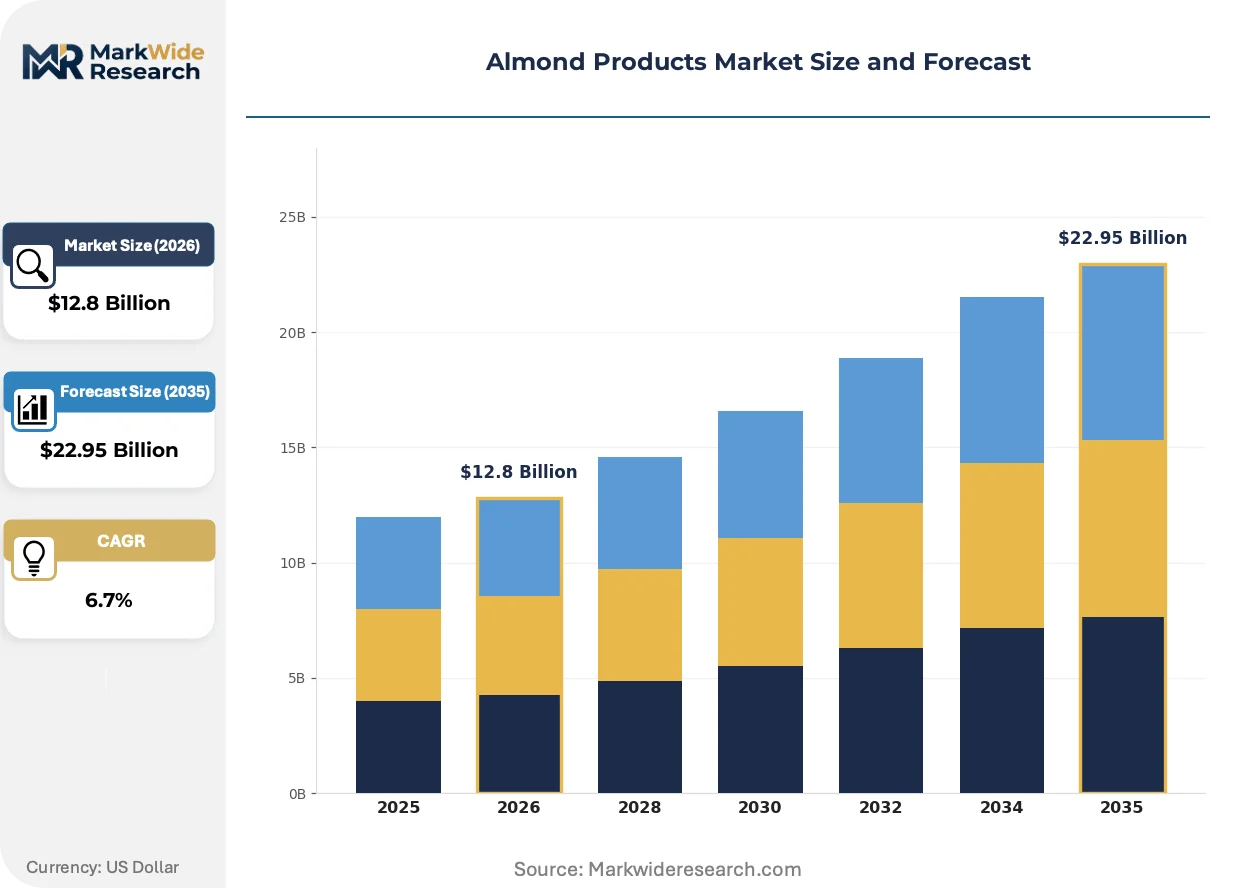
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Butter, Almond Milk, Almond Flour, Almond Oil Application: Beverages, Snacks, Bakery, Confectionery End User: Households, Food Manufacturers, Restaurants, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Blue Diamond Growers, The Wonderful Company, Archer Daniels Midland Company, Olam International, Borges Agricultural & Industrial Nuts, Treehouse California Almonds, John B. Sanfilippo & Son, Royal Nut Company, Barry Callebaut Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Products Market Emerging Trajectories
Digital traceability infrastructure and thermal processing advances are compressing quality variability while regulatory disclosure mandates reshape procurement criteria across plant-based supply chains.
Hyperspectral sorting technology is virtualizing defect detection in raw kernel processing. Blue Diamond Growers and Olam International deploy near-infrared systems to identify concealed mold and insect damage before roasting, reducing batch rejection rates and enabling real-time premium-grade segregation. This capability is virtualizing commodity-adjacent pricing tiers into discrete quality-certified contracts.
The EU Green Deal's deforestation-free supply chain regulation requires nut importers to document geolocation coordinates for production plots entering the European Union. Food manufacturers sourcing almond derivatives must implement satellite-verified traceability systems by enforcement deadlines, with mid-sized ingredient suppliers facing compliance cost burdens that favor scaled operators with existing sustainability infrastructure.
Retail buyers are consolidating supplier relationships around vertically integrated processors offering certified organic and conventional streams from common orchards. This procurement concentration displaces fragmented spot-market purchasing, with Costco and Whole Foods Market requiring single-source accountability for ESG claims previously assembled from multiple commodity handlers.
Almond Products Market Segmentation
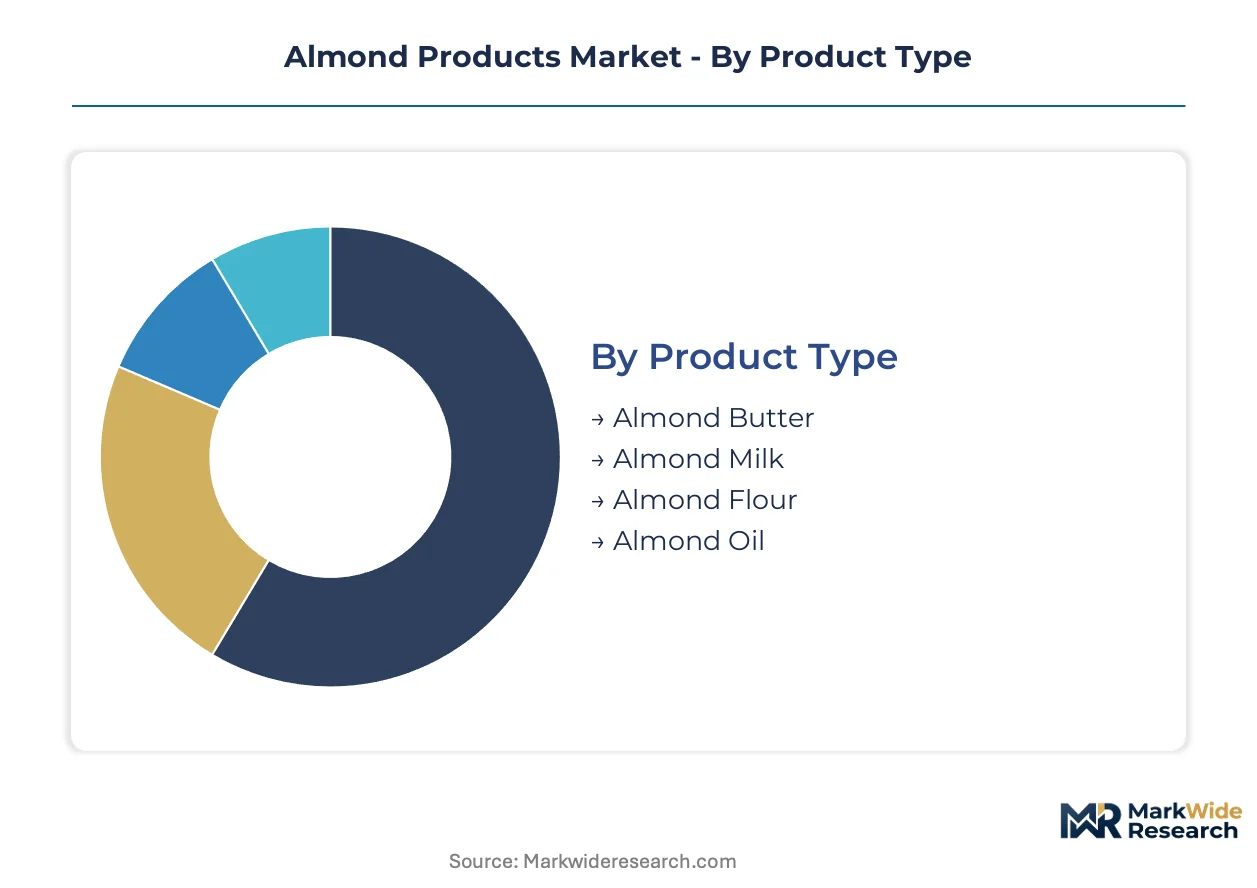
Almond derivatives serve divergent functional roles across beverage formulation, clean-label snacking, gluten-free baking, and nutritional supplementation. Segmentation reveals how protein content, fat profiles, and processing intensity determine margin capture and channel access for processors.
Product Type:
Each format commands distinct price positioning based on processing complexity and shelf stability requirements.
- Almond Milk:Refrigerated and shelf-stable liquid formulations contain 6-8% almond content with emulsifier systems stabilizing fat dispersion. Household purchases in the United States dominate refrigerated case turnover, though oat milk substitution is compressing volume expansion in North American retail channels.
- Almond Butter:Roasted kernel grinding yields spreads with 25% protein and 50% lipid content, with cold-press variants preserving volatile flavor compounds. Precision thermal profiling systems enable clean-label shelf stability without potassium sorbate, supporting premium positioning in natural food channels.
- Almond Flour:Blanched kernel milling produces gluten-free bakery ingredients with fat content and moisture retention properties superior to rice or tapioca alternatives. Artisan bread and pastry segments are capturing expanding formulation share where crumb structure performance justifies ingredient cost premiums.
- Almond Oil:Cold-pressed extraction delivers lipid profiles exceeding 50% monounsaturated content for cosmetic and culinary applications. Nutraceutical buyers concentrate demand for unrefined grades with preserved tocopherol content.
The dominant share belongs to Almond Milk, while Almond Flour is closing the gap fastest.
Application:
Margin pools concentrate where branded finished goods command price premiums over commodity ingredient sales.
- Beverages:Plant-based milk alternatives anchor refrigerated dairy cases with entrenched consumer recognition. California-based processors supply bulk concentrate to North American co-packers facing private-label price compression.
- Snacks:Roasted kernels, bars, and coated products capture branded margin pools through clean-label positioning. The Wonderful Company and Blue Diamond Growers dominate retail shelf allocation through vertical orchard-to-shelf control.
- Bakery:Almond flour and paste incorporation addresses gluten-free and paleo formulation trends. Fat content performance in moisture retention justifies premium pricing over commodity wheat alternatives.
- Confectionery:Marzipan, praline, and chocolate inclusion applications demand specific particle size distributions. European manufacturers source California-origin paste under EU Green Deal sustainability documentation requirements.
Beverages retain volume leadership, though Snacks applications are expanding most quickly through premium branded positioning.
End User:
Procurement scale and specification rigor separate mass-market from specialty demand segments.
- Households:Retail package sizes from 8 to 64 ounces drive supermarket and online channel turnover. United States consumer spending patterns concentrate in almond-based snack and milk categories.
- Food Manufacturers:Bulk ingredient procurement for CPG formulation demands consistent lot-to-lot quality and allergen segregation protocols. Blue Diamond Growers leverages cooperative scale to dominate North American supply contracts.
- Restaurants:Foodservice distributors supply kernels, milks, and butters for menu incorporation in plant-forward concepts. Almond milk procurement scales with dairy-alternative beverage program expansion.
- Nutraceuticals:Protein isolate and oil extraction byproducts serve supplement and functional food applications. Upcycled almond meal from oil processing converts into high-fiber ingredients for specialized nutrition products.
Food Manufacturers command the largest volume share, while Nutraceuticals is gaining share fastest through protein concentrate demand.
Distribution Channel:
Channel selection determines margin retention and brand control for processors of varying scale.
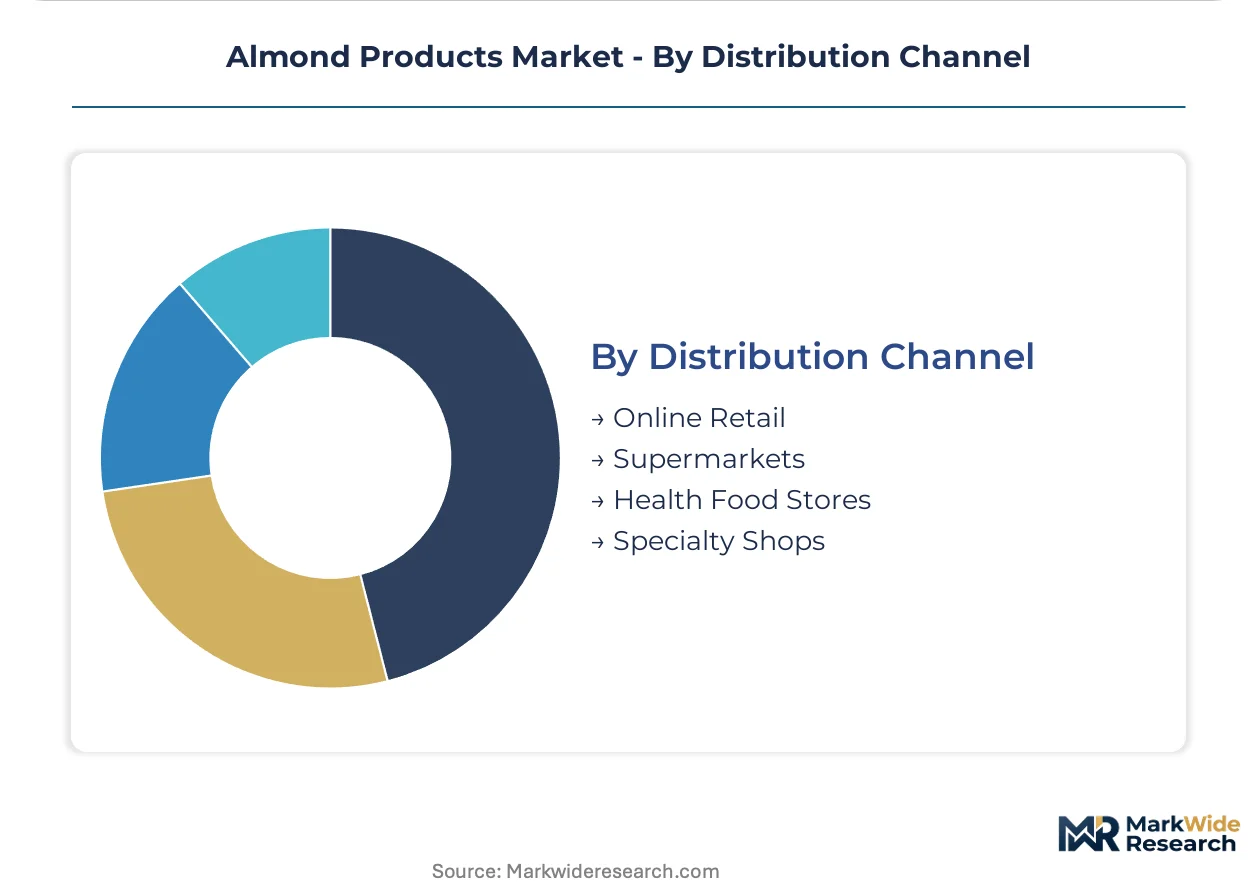
- Online Retail:Direct-to-consumer subscription models enable specialty roasters and small-batch producers to bypass distributor markups. Ecommerce portals capture margin pools traditionally allocated to retail slotting fees.
- Supermarkets:Refrigerated case placement requires trade promotion spending and shelf-stable supply chain infrastructure. Costco and Whole Foods Market consolidate supplier relationships around vertically integrated processors with single-source ESG accountability.
- Health Food Stores:Natural channel buyers prioritize organic certification and clean-label claims. USDA organic transition timelines constrain supply availability for three-year conversion orchards.
- Specialty Shops:Gourmet retailers and ethnic grocers stock imported and artisanal grades with origin storytelling. European importers demand satellite-verified geolocation documentation under EU deforestation-free supply chain regulations.
Supermarkets maintain dominant shelf presence, though Online Retail is climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California ships bulk almond kernels to European confectionery houses and Asian beverage manufacturers, while Australian and Spanish orchards capture premium-grade contracts demanding satellite-verified sustainability documentation.
United States
Household snack and milk purchases concentrate spending in California's Central Valley processing corridors. The State Water Resources Control Board imposes groundwater sustainability obligations that constrain San Joaquin Valley orchard expansion. Fresno and Modesto host cooperative processing facilities supplying North American food manufacturers with bulk butter and flour ingredients.
Germany
Marzipan and chocolate inclusion applications drive paste demand from European confectionery headquarters. The EU Green Deal's deforestation-free supply chain regulation mandates geolocation documentation for imported kernels entering Hamburg and Rotterdam ports. Bavarian ingredient distributors consolidate procurement around vertically integrated California suppliers offering certified organic streams.
India
Festive gifting traditions and health-conscious urban households expand kernel consumption in Mumbai and Delhi metropolitan markets. FSSAI plant-based beverage labeling standards under draft review would open formal retail channels for almond milk currently restricted by ambiguous dairy-alternative classification. Gujarat processing hubs import California bulk nuts for re-export to Middle Eastern markets.
Australia
Premium-grade kernel exports serve Asian markets demanding pesticide-residue documentation and water-efficiency certification. The country's national agricultural regulator enforces strict biosecurity protocols governing orchard establishment and varietal importation. Riverina and Sunraysia growing regions concentrate irrigation-dependent cultivation supplying Singapore and Japanese buyers.
Spain
Traditional Mediterranean cultivation supports organic and single-origin positioning in European specialty channels. EU Farm to Fork strategy disclosure requirements pressure growers in Catalonia and Andalusia to document reduced pesticide applications and sustainable water management. Valencia processors supply continental confectioners seeking shorter supply chains than California alternatives.
Almond Products Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Cooperative structures dominate bulk ingredient contracts to North American food manufacturers, while vertically integrated orchard-to-retail operators anchor premium branded positioning. Three archetypes define competitive positioning: cooperative giants with processing scale, integrated agribusinesses with captive supply, and specialist roasters with direct-to-consumer reach. Capacity consolidation and sustainability certification investments represent the dominant competitive moves reshaping procurement relationships.
Within the cooperative processing tier, Blue Diamond Growers and Olam International occupy positions exemplifying scale-driven supply consolidation. The Wonderful Company anchors vertically integrated premium positioning across orchard ownership through retail branding. Specialist differentiation emerges from John B. Sanfilippo & Son representing mid-tier diversified nut processors balancing commodity and branded product streams.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| The Wonderful Company |
| Archer Daniels Midland Company |
| Olam International |
| Borges Agricultural & Industrial Nuts |
| Treehouse California Almonds |
| John B. Sanfilippo & Son |
| Royal Nut Company |
| Barry Callebaut Group |
| Others |
Supply Flow & Price Mechanics
California's groundwater sustainability obligations under the State Water Resources Control Board create a regulatory chokepoint that simultaneously widens pricing spreads between certified-organic and conventional grades while compressing supply chain tiers toward vertically integrated handlers with water rights consolidation.
Pricing Analysis
Precision thermal profiling technology gaps separate current-gen cold-press extraction systems from legacy roasting equipment, with processors deploying near-infrared sorting commanding 15-20% premiums over commodity handlers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USDA organic and EU Green Deal-compliant streams capturing margin premiums. Cost compression in standard-grade almond milk is intensifying because oat beverage substitution erodes refrigerated case pricing power. Private-label buyers at mass retailers exhibit highest price sensitivity, while European confectioners sourcing marzipan paste demonstrate lowest sensitivity due to sustainability documentation requirements.
Supply Chain Analysis
Extended payment terms from multinational food manufacturers to California cooperative processors now stretch 60-90 days, with supply-chain finance facilities emerging as working capital bridges for mid-tier handlers. Geographic supply concentration centers on the United States, Spain, and Australia, with California's Central Valley anchoring 80% of global kernel output. Raw material dependencies rest on groundwater access, bee pollination services, and potassium-based fertilizer inputs. Single-source vulnerability from climate-induced harvest variability in the San Joaquin Valley threatens processor inventory planning. Distribution runs through cooperative bulk handlers to North American food manufacturers, with direct-to-consumer subscription models bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based beverage penetration in Indian metropolitan markets signals early-cycle expansion, with FSSAI regulatory clarity poised to unlock formal retail channels previously restricted by ambiguous dairy-alternative classification.
For Market Incumbents: Insulate margin pools by deepening backward integration into water-rights-consolidated orchards and deploying hyperspectral sorting technology to virtualize quality-certified pricing tiers. Oat milk substitution in North American refrigerated cases demands precision roasting investments that preserve clean-label shelf stability without synthetic preservatives. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting specialty roasters and small-batch butter producers, capturing margin pools traditionally allocated to retail slotting fees. India's draft FSSAI plant-based labeling standards represent the most penetrable geography, with formal retail channel access enabling branded almond milk positioning ahead of multinational incumbent expansion. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with existing sustainability infrastructure and satellite-verified traceability systems. Long-term viability over a multi-year window hinges on water rights security and EU Green Deal compliance capability. The signal to watch is California State Water Resources Control Board enforcement actions accelerating orchard retirement and cooperative consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Investment | EU Green Deal deforestation-free documentation requirements favor handlers with satellite-verified geolocation systems. |
| Precision Processing Technology Deployment | Near-infrared sorting and thermal profiling enable quality-tier virtualization and clean-label shelf stability. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass distributor markups and capture margin pools from retail slotting fees. |
| Water Rights Consolidation | California's Sustainable Groundwater Management Act rewards capitalized growers with orchard expansion capacity. |
| Upcycled Byproduct Monetization | Oil extraction waste streams convert to high-fiber protein ingredients for pet food and aquafeed applications. |
Methodological Framework
Cross-validation between primary interviews with almond processors, cooperative executives, and food manufacturer procurement leads and secondary validation through USDA organic certification databases, FDA food labeling guidance, and EU Green Deal regulatory filings anchors the qualitative findings. Orchard operators, sustainability compliance officers at vertically integrated handlers, and category buyers at mass retailers provided operational perspective. Bottom-up volume modeling from processor capacity and top-down demand triangulation from retail channel audits ensured convergence.
Calibration against historical price spreads between organic and conventional grades and documented water cost escalations in California's Central Valley shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application category, end-user scale, and distribution channel, with certification tier and geographic supply origin as industry-specific stratifiers. CAGRs derived from trend extrapolation of almond milk volume displacement by oat alternatives and gluten-free bakery formulation shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed water-rights consolidators or rapid FSSAI regulatory finalization in India would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
China Almond Market