
 Tree Nut Allergy Market | 2026-2036
Tree Nut Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Tree Nut Allergy Market Analytics
Allergist and pediatric immunologist staffing is rotating toward biologic therapy administration and oral immunotherapy protocols, expanding treatable patient populations. Aimmune Therapeutics leverages its peanut allergy platform expertise to anchor adjacent tree nut programs. DBV Technologies competes through epicutaneous delivery systems that reduce systemic reaction risk. Sanofi sustains a diversified immunology pipeline spanning biologics and small molecules.
Tree nut allergy comprises hypersensitivity reactions to proteins in almonds, cashews, walnuts, pecans, pistachios, hazelnuts, and macadamias, triggered by IgE-mediated immune responses that can progress from urticaria to anaphylaxis. Diagnostic thresholds and component-resolved IgE testing enable precise phenotyping for clinical intervention. Families represent the dominant end user segment, with purchasing decisions driven by allergen-free labeling reliability and school accommodation requirements. Healthcare institutions command premium pricing for epinephrine auto-injector procurement and immunotherapy administration, while specialty stores capture margin pools through curated allergen-free product assortments.
FDA breakthrough therapy and fast track programs compress development timelines for desensitization biologics, while EMA orphan drug incentives stimulate European trial investment. The EU Food Information for Consumers Regulation mandates bold allergen labeling, reshaping packaged food formulation and cross-contamination protocols. Stakeholders must monitor oral immunotherapy durability data and payer coverage determinations for emerging biologics.
Market Dynamics
Pediatric allergist workforce expansion in North America is unlocking clinical trial capacity for biologic desensitization therapies, compressing development timelines and expanding treatable patient populations.
Growth Catalysts
- FDA breakthrough therapy designation:The FDA breakthrough pathway accelerates biologics development for tree nut desensitization by enabling rolling review and priority regulatory engagement.
- Component-resolved IgE testing:Diagnostic laboratories are deploying molecular allergen profiling to enable precise phenotyping and stratified intervention protocols.
- EU orphan drug incentives:EMA orphan designation stimulates European trial investment through protocol assistance, fee reductions, and market exclusivity provisions.
Market Restraints
- Specialized allergist scarcity:Concentrated pediatric immunologist supply in urban academic centers limits rural and suburban patient access to oral immunotherapy administration.
- Biologics manufacturing complexity:Cold chain requirements and biosimilar competition pressure margins for injectable desensitization products.
- Cross-contamination protocols:EU Food Information for Consumers Regulation mandates bold allergen labeling that increases packaged food reformulation costs for manufacturers.
Strategic Opportunities
- School-based accommodation mandates:District-level epinephrine stocking requirements and individualized education plans create institutional procurement channels for auto-injector suppliers.
- Epicutaneous delivery convergence:Patch-based immunotherapy platforms combined with wearable monitoring devices enable home-administered desensitization with reduced anaphylaxis risk.
- Specialty retail curation:Allergen-free product assortments in dedicated brick-and-mortar and direct-to-consumer channels capture margin pools from label-reliant family purchasers.
Industry Challenges
- Pediatric immunotherapy administration training:Clinical staff require specialized certification in oral immunotherapy protocols and anaphylaxis response, constraining site activation for trials.
- Oral immunotherapy durability uncertainty:Long-term maintenance dosing requirements and relapse rates complicate payer coverage determinations for emerging biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tree Nut Allergy Market |
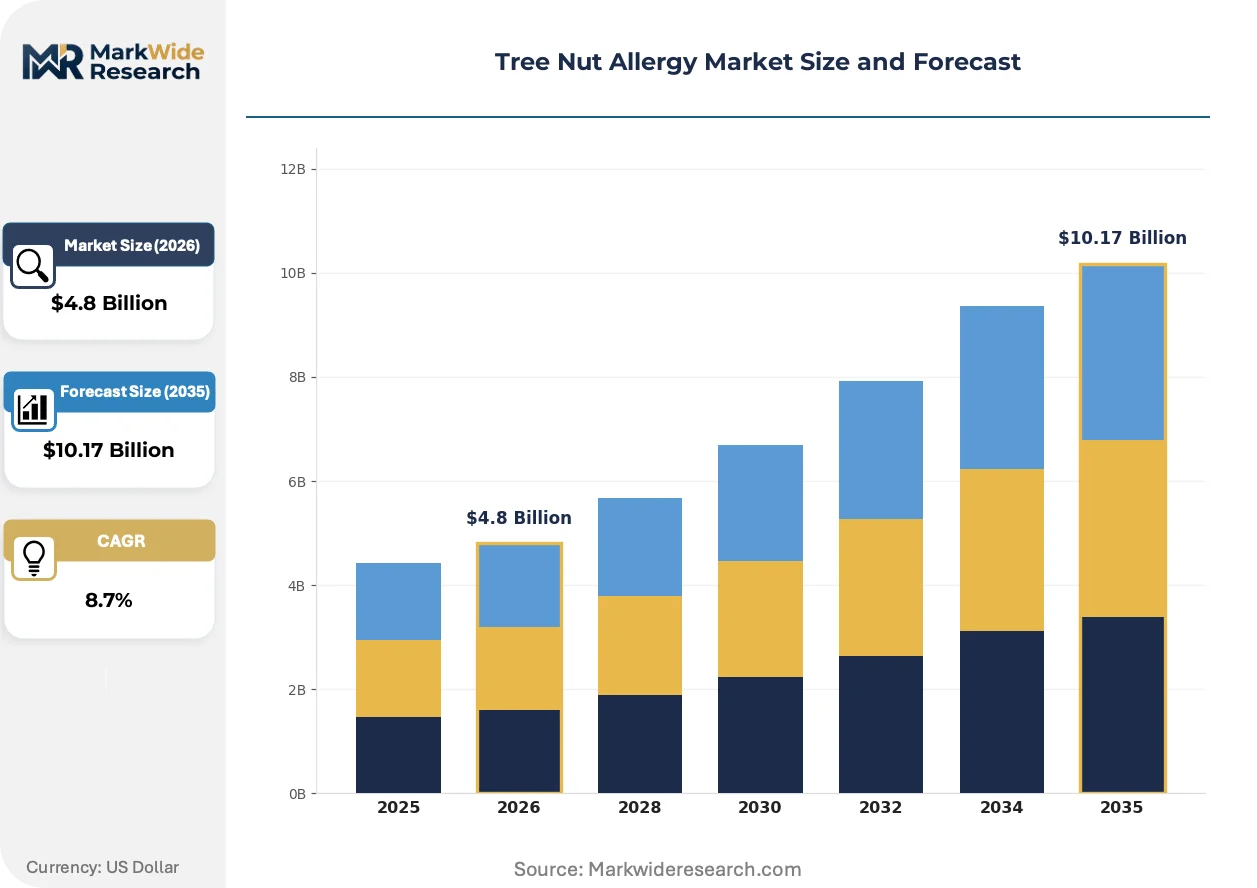
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Baked Goods, Sauces, Dairy Alternatives End User: Families, Schools, Healthcare Institutions, Restaurants Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores Ingredient Form: Whole Nuts, Nut Butters, Flours, Extracts |
| Companies Covered | Aravax, Sanofi, Aimmune Therapeutics, Immunomic Therapeutics, ALK-Abello, DBV Technologies, Novartis, Prota Therapeutics, Allergy Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tree Nut Allergy Market Evolving Landscape
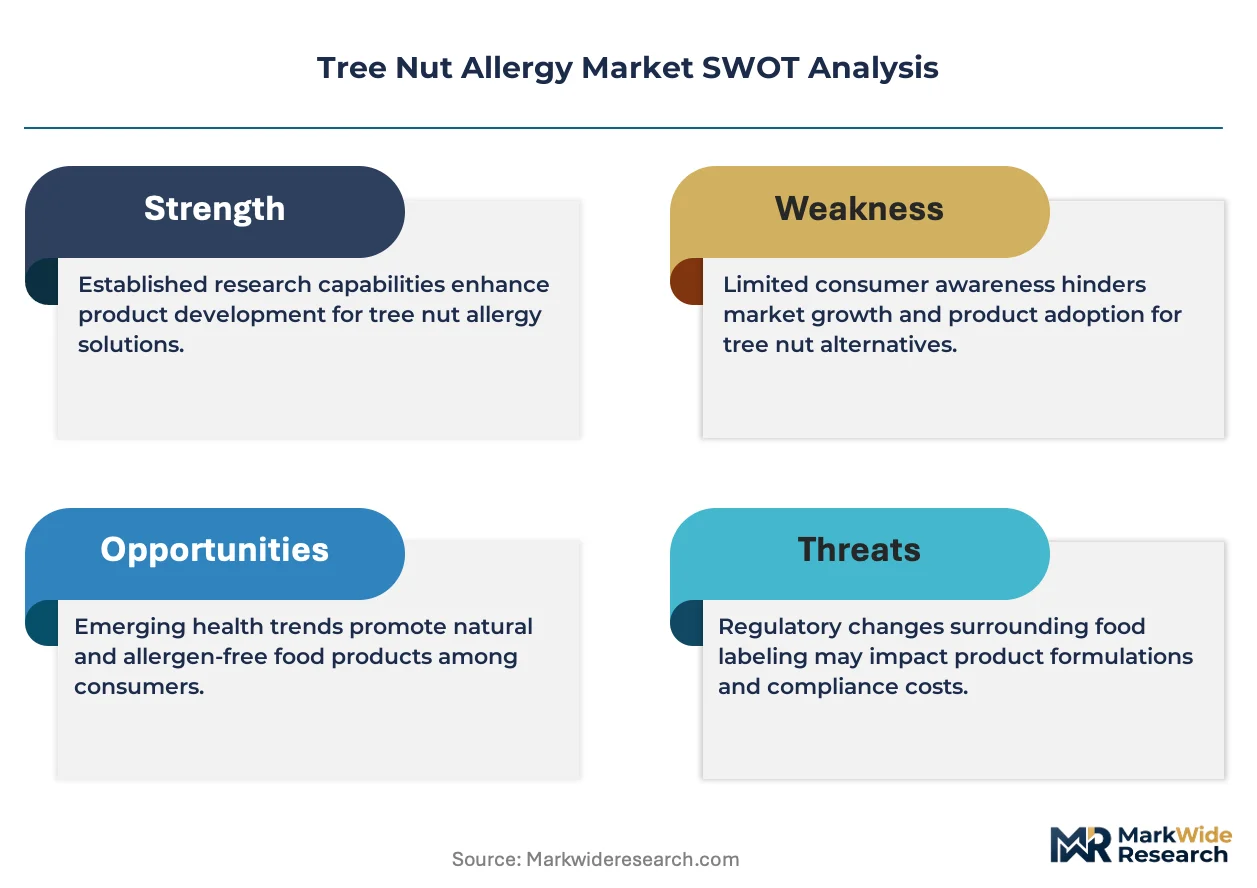
Biologic delivery modalities and diagnostic precision tools are reshaping competitive positioning in tree nut allergy management, while regulatory pathways compress development timelines and reimbursement frameworks evolve.
Epicutaneous immunotherapy patches are bifurcating the desensitization landscape by enabling gradual allergen exposure through intact skin without systemic absorption. Pediatric allergy practices are adopting patch protocols for multi-nut sensitization, particularly for patients with anxiety around oral challenges. This delivery shift is compressing the addressable market for injectable biologics in mild-to-moderate phenotypes while expanding total treatable population through lower-threshold entry.
EMA orphan drug designation paired with FDA breakthrough therapy pathways is compressing regulatory review timelines for novel biologics. Dual-track development strategies now prioritize European trial sites to leverage centralized EMA assessment and mutual recognition procedures. Biologics developers are responding by front-loading EU clinical investment and aligning manufacturing standards with MDR quality system requirements.
Family purchasing decisions now center on third-party certification reliability rather than manufacturer claims alone. Allergen-free specialty stores and subscription direct-to-consumer channels are displacing conventional retail for high-risk product categories. This channel rotation is most pronounced in the United States, where diagnostic penetration and school accommodation requirements drive premium label-seeking behavior.
Tree Nut Allergy Market Segmentation
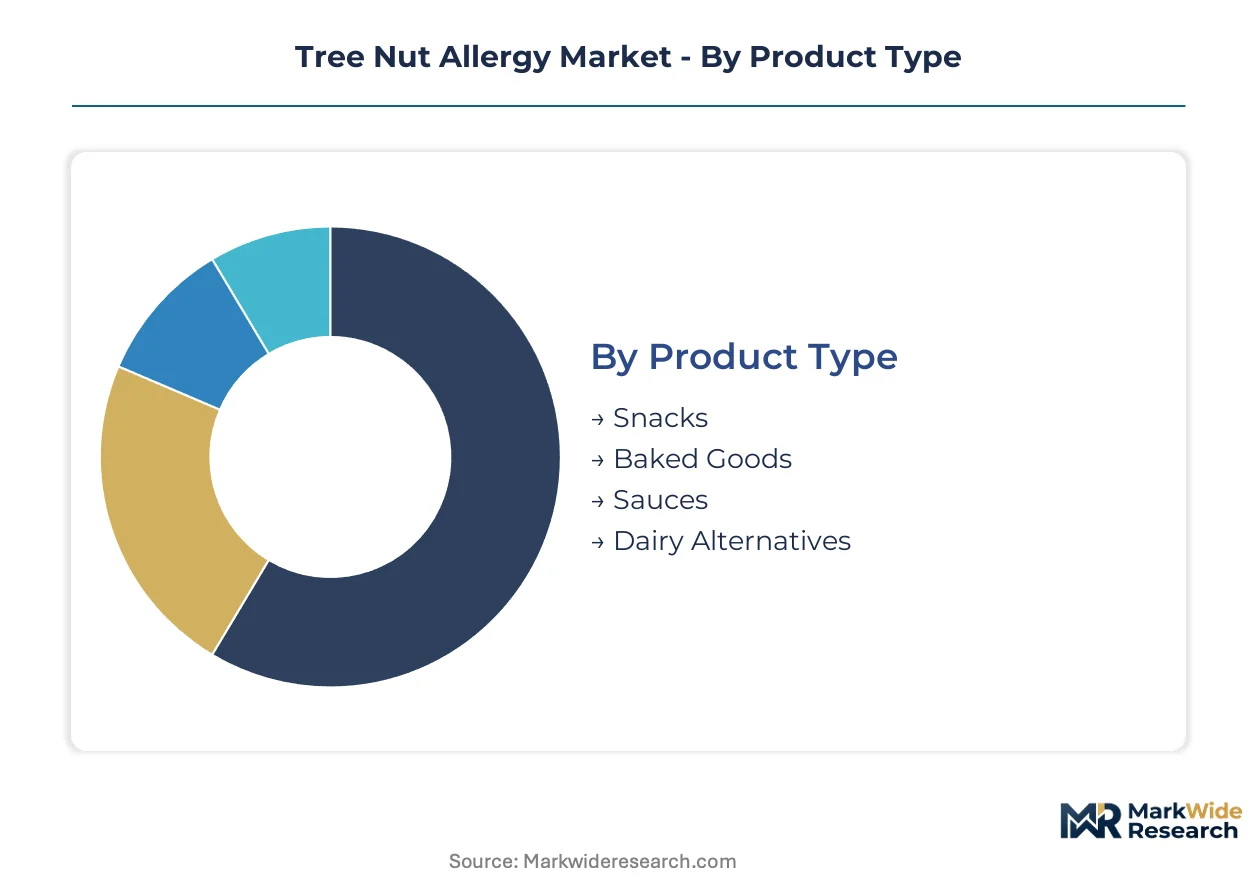
Tree nut allergy market segmentation reveals distinct procurement patterns across consumer-facing and institutional channels. Product form and distribution access determine pricing power and brand loyalty in this label-sensitive category.
Product Type:
Domestic consumption concentrates in shelf-stable formats, while export-oriented manufacturers prioritize ambient-stable baked goods for cross-border retail placement.
- Snacks:Packaged bars, trail mixes, and roasted nut products carry the highest allergen-labeling scrutiny. United States families drive premium pricing for third-party certified snack lines, particularly for school lunchbox compliance.
- Baked Goods:Cookies, pastries, and bread mixes require dedicated production lines to prevent cross-contamination. European Union manufacturers absorb reformulation costs under EFSA labeling mandates, compressing margins for mid-tier producers.
- Sauces:Pesto, nut-based dressings, and cooking sauces.
- Dairy Alternatives:Almond milk, cashew cream, and nut-based yogurts.
Snacks commands the established base. The steepest expansion runs through Baked Goods.
End User:
Cost tiering separates family discretionary purchases from institutional procurement with mandated safety protocols and volume contracting.
- Families:Primary decision-makers seeking allergen-free household staples. Label reliability and school accommodation documentation determine brand selection, with direct-to-consumer subscription channels capturing high lifetime value in the United States.
- Schools:District-level epinephrine stocking requirements and individualized education plans create institutional procurement channels. USDA school nutrition guidelines intersect with FDA food allergen labeling to shape vendor qualification.
- Healthcare Institutions:Hospitals and clinics managing acute allergic reactions.
- Restaurants:Foodservice operators implementing allergen-aware kitchen protocols.
Families commands the established base. Healthcare Institutions shows the steepest expansion trajectory through clinical trial site activation and biologic administration.
Distribution Channel:
Volume concentration favors mass retail, while margin accretion concentrates in curated specialty channels with certification authority.
- Supermarkets:Dominant volume channel with dedicated allergen-free aisle placement. Kroger, Whole Foods, and Safeway parent companies negotiate slotting fees for certified product lines, squeezing regional brand economics.
- Online Stores:Amazon and Thrive Market capture subscription-driven replenishment. Direct-to-consumer brands bypass retail margin stacking, though cold-chain shipping constraints limit fresh-format penetration.
- Specialty Stores:Allergen-free boutiques and natural products retailers.
- Convenience Stores:Limited allergen-free SKU availability in grab-and-go formats.
Supermarkets commands the established base. Online Stores gains share fastest through subscription retention and personalized recommendation engines.
Ingredient Form:
Supply concentration in tree nut processing clusters—California almonds, Vietnam cashews—determines input cost volatility across downstream forms.
- Whole Nuts:Raw and roasted intact kernels for snacking and ingredient use. California almond growers supply the dominant share of United States whole nut demand, with water allocation policies from the State Water Resources Control Board affecting crop yields and pricing.
- Nut Butters:Ground paste formats for spreads and baking applications. Jif and Skippy parent companies compete with artisanal brands on grinding texture and oil separation control, with organic certification commanding 40-60% price premiums.
- Flours:Finely milled nut meals for gluten-free baking.
- Extracts:Concentrated flavoring agents for beverage and confectionery use.
Whole Nuts commands the established base. Nut Butters climbs the fastest through snacking occasion expansion and clean-label formulation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States concentrates biologic therapy demand through pediatric allergist networks and school accommodation mandates. European markets prioritize diagnostic precision and labeling compliance over therapeutic intervention.
United States
Pediatric allergist workforce expansion and FDA breakthrough therapy designation drive clinical trial density. The Food Allergy Safety, Treatment, Education, and Research Act mandates epinephrine availability in schools and public venues. Boston and New York Metro anchor the highest concentration of oral immunotherapy administration sites.
Germany
Component-resolved IgE testing adoption and EMA orphan drug incentives shape biologics investment. The Federal Institute for Drugs and Medical Devices enforces MDR-aligned quality standards for allergen immunotherapy products. Munich and Berlin cluster diagnostic laboratory capacity and university hospital trial networks.
United Kingdom
NHS England commissioning frameworks determine reimbursement for novel desensitization therapies. The Medicines and Healthcare products Regulatory Agency operates post-Brexit alongside EMA mutual recognition procedures. London and Cambridge concentrate biotech R&D and early-phase clinical infrastructure.
France
ANSM regulatory pathways and hospital pharmacy procurement centralization influence market access. The French National Agency for Food, Environmental and Occupational Health Safety enforces allergen labeling beyond EU baseline requirements. Paris and Lyon host the dominant share of pediatric immunology referral centers.
Australia
TGA provisional approval pathways accelerate biologic registration for severe allergic indications. The Australian Commission on Safety and Quality in Health Care mandates standardized anaphylaxis protocols in schools and childcare. Melbourne and Sydney concentrate specialist allergist practices and clinical research organizations.
Tree Nut Allergy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the tree nut allergy market. Large-cap pharmaceutical developers leverage diversified immunology pipelines and established regulatory affairs infrastructure to compress approval timelines. Mid-cap biotech specialists concentrate on single-modality platforms—epicutaneous delivery, oral immunotherapy, or recombinant protein engineering. Competitive moves center on portfolio expansion into adjacent allergen indications and geographic licensing partnerships that access EMA centralized procedures.
Within the platform-specialist tier, Aimmune Therapeutics and DBV Technologies exemplify divergent therapeutic modalities. Aimmune anchors oral immunotherapy development through peanut allergy platform extension into tree nut programs. DBV Technologies occupies a position in epicutaneous delivery systems that reduce systemic exposure risk. Sanofi represents the integrated pharmaceutical archetype with cross-immunology pipeline diversification spanning biologics and small molecules.
| Leading Market Players |
|---|
| Aravax |
| Sanofi |
| Aimmune Therapeutics |
| Immunomic Therapeutics |
| ALK-Abello |
| DBV Technologies |
| Novartis |
| Prota Therapeutics |
| Allergy Therapeutics |
| Others |
Value Network & Pricing Analysis
Almond flour substitution into gluten-free baked goods simultaneously redraws procurement geography toward California Central Valley growers and compresses premium pricing tiers as commodity nut meal competes with legacy specialty ingredients.
Pricing Analysis
Long-term offtake contracts between major snack manufacturers and California almond cooperatives dominate procurement, locking in volume commitments that insulate against spot price volatility while compressing margins for mid-tier processors lacking scale. Price differentiation hinges on third-party certification tier—organic and allergen-free audit standards command 40-60% premiums over conventional grades—and geographic delivery cost to East Coast distribution centers. Pricing pressure stems from biosimilar competition in injectable desensitization products and cold chain logistics inflation. School district procurement offices exhibit highest price sensitivity through competitive bidding mandates, while direct-to-consumer subscription channels show lowest sensitivity due to label-reliant family loyalty.
Supply Chain Analysis
Inventory lead times for tree nut processors stretch 8-14 weeks during harvest windows, forcing downstream manufacturers to carry buffer stocks through Q3-Q4 demand surges. Raw material sourcing concentrates in California almonds, Vietnam cashews, and Turkey hazelnuts, with each node exposed to distinct climate and trade policy risks. Manufacturing draws from whole nut crushing, solvent extraction for protein isolates, and precision grinding for flour grades. Single-source vulnerability in Vietnam cashew shelling operations creates chokepoint exposure for premium snack lines. Distribution runs through temperature-controlled regional distribution centers serving mass retail, with direct-to-consumer cold-chain shipping emerging as a parallel channel for fresh-format alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through pediatric allergist network consolidation and health system procurement centralization, shifting negotiation leverage toward institutional purchasers with volume contracting authority.
For Market Incumbents: Fortify oral immunotherapy platform durability through extended maintenance dosing data packages that secure payer coverage determinations against emerging epicutaneous competitors. Deepen backward integration into allergen-free manufacturing facilities to capture margin pools currently lost to third-party co-packers subject to FDA food safety audit costs. Lock in exclusive supply agreements with California almond cooperatives before new entrant offtake competition intensifies. For New Entrants and Emerging Players: Anchor in school-based accommodation mandates as the most penetrable institutional channel, where district-level epinephrine stocking requirements create procurement entry points absent entrenched supplier relationships. Target suburban and rural pediatric practices underserved by oral immunotherapy-certified allergists, leveraging telemedicine protocols to extend geographic reach. Pursue direct-to-consumer subscription models with personalized dosing support to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward platform-specialist biotechs with FDA breakthrough therapy designation and adjacent allergen pipeline optionality rather than single-product candidates. Long-term viability favors developers with demonstrated European trial site activation and EMA centralized procedure familiarity. Watch oral immunotherapy durability data readouts as the critical inflection signal for payer coverage expansion and addressable market re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pediatric allergist workforce expansion unlocks site activation capacity for biologic desensitization studies. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for novel immunotherapy platforms. |
| Manufacturing Scale-Up | Cold chain infrastructure investment secures distribution capacity for injectable biologic products. |
| Pipeline Diversification | Peanut allergy platform extension into tree nut programs leverages established safety databases. |
| Strategic Partnership | European trial site networks access EMA centralized assessment and mutual recognition procedures. |
Research Methodology
The analysis maps biologic therapy development, diagnostic testing services, allergen-free food manufacturing, and institutional procurement channels, each validated through pediatric allergists, regulatory affairs specialists at FDA and EMA, formulary directors at major payers, and school district procurement officers. Primary interview data triangulates against FDA breakthrough therapy designation filings, EMA orphan drug applications, ClinicalTrials.gov protocol registries, and USDA school nutrition program purchasing records. Bottom-up patient population sizing and top-down market value reconciliation anchor volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions include product form, end user archetype, distribution channel, and ingredient processing grade. CAGRs derive from patient population growth, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate allergist workforce expansion rates, FDA review timeline distributions, and payer coverage determination probabilities.
Material uncertainties—regulatory approval delays, oral immunotherapy durability failures, and biosimilar entry timing—sit outside the modeled envelope. Forecasts reflect documented assumptions about patient adherence, clinician adoption curves, and reimbursement policy continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
South America Nut-Based Spread Market