
 Carob Extract Market | 2026-2036
Carob Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Carob Extract Market Insights
The EU Green Deal is hardening sustainability requirements across European food supply chains, directly elevating carob extract's standing as a cocoa alternative with lower water intensity. Cargill, Incorporated leverages its grain and oilseed logistics backbone to secure Mediterranean carob bean supply at scale. Australian Carobs anchors Southern Hemisphere production through orchard consolidation in South Australia and Victoria. DuPont de Nemours competes on texture-system formulations that integrate carob gum into reduced-sugar bakery applications.
Carob extract comprises soluble fibers, polyphenols, and galactomannan hydrocolloids recovered from Ceratonia siliqua pods through aqueous extraction and spray-drying, serving primarily as a cocoa replacer, stabilizer, and prebiotic feedstock in formulated goods. Powder formats dominate volume due to extended shelf stability and ease of dry-blending into bakery and confectionery bases, while liquid extracts capture premium positioning in beverage fortification where rapid dispersion matters. Nutraceutical applications represent the fastest-expanding demand pool as dietary supplement producers seek clean-label prebiotic and antioxidant positioning.
EFSA novel food assessments and EU organic certification frameworks govern ingredient legitimacy and label claims across member states, with REACH compliance additionally constraining extraction solvent profiles. The US FDA GRAS status for carob bean gum under 21 CFR 184.1343 enables cross-Atlantic formulation continuity for multinational food manufacturers. Stakeholders must monitor evolving prebiotic health claim substantiation pathways in both jurisdictions to anticipate which product positioning will sustain premium pricing.
Market Dynamics
Clean-label procurement mandates from EU food manufacturers are compressing formulation windows, forcing rapid substitution of synthetic stabilizers with Mediterranean-sourced carob derivatives that satisfy EFSA novel food pathways and REACH solvent compliance.
Growth Catalysts
- EU Green Deal sustainability benchmarks:Hardening procurement criteria across German, French, and Spanish food manufacturing clusters elevate carob extract's water-efficient profile against cocoa and synthetic alternatives.
- Prebiotic supplement positioning:Dietary supplement producers in nutraceutical channels exploit carob's soluble fiber and polyphenol content for clean-label antioxidant and gut-health claims.
- Spray-drying technology maturation:Aqueous extraction and spray-drying process refinements in Mediterranean sourcing hubs improve powder format shelf stability and dry-blending compatibility for bakery applications.
Market Restraints
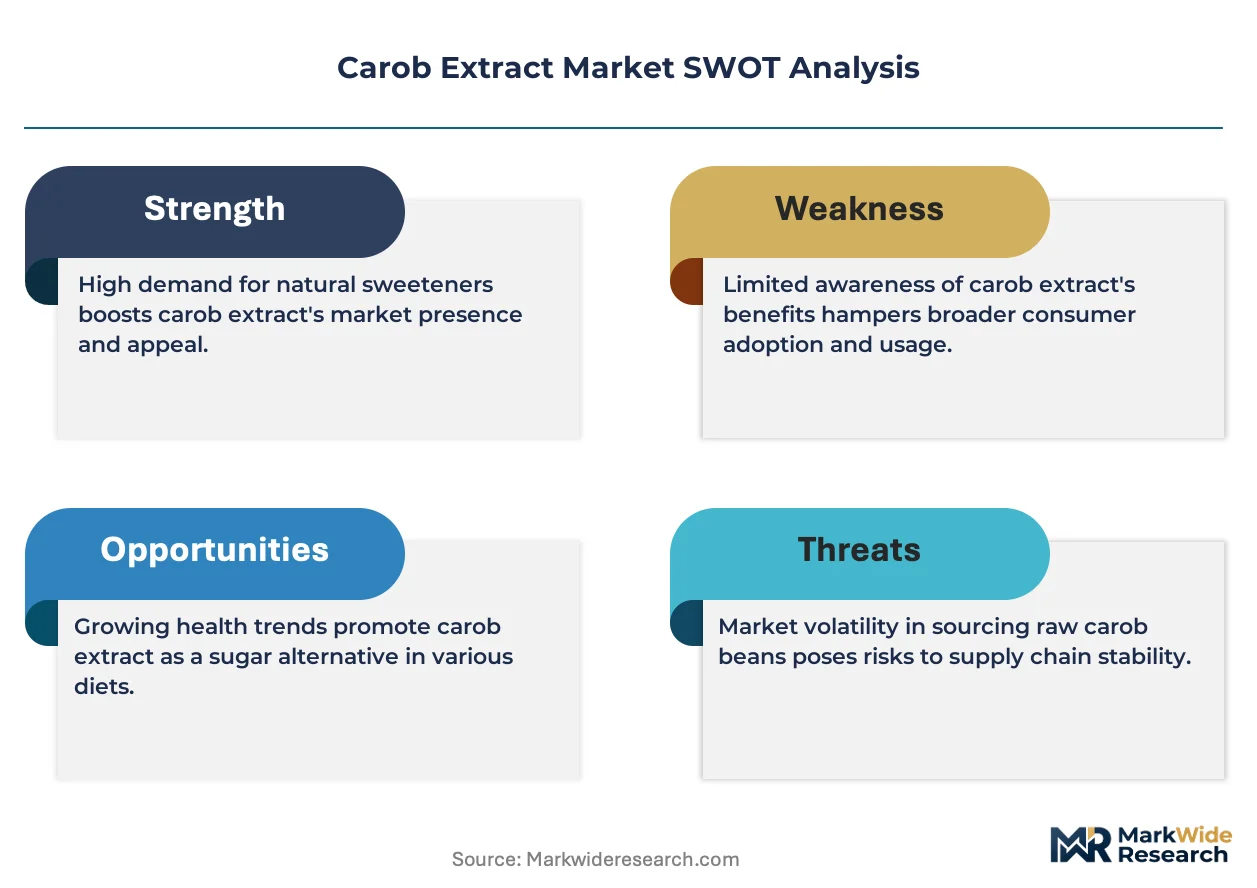
- Carob bean supply concentration:Mediterranean orchard dependency—principally Spain, Portugal, and Italy—exposes processors to climate volatility and single-region harvest risk.
- EFSA novel food assessment timelines:Extended regulatory review periods for new extraction methods and solvent profiles delay product launch schedules and tie up R&D capital.
- Cocoa price volatility spillover:When cocoa futures drop below threshold levels, confectionery manufacturers revert to conventional formulations, eroding carob's cost-competitive positioning.
Strategic Opportunities
- Southern Hemisphere production expansion:Australian orchard consolidation in South Australia and Victoria offers counter-seasonal supply security and reduced Mediterranean climate dependency.
- Beverage fortification liquid formats:Premium positioning in functional drinks and ready-to-mix beverages exploits rapid dispersion properties absent in powder alternatives.
- US FDA GRAS pathway leverage:Cross-Atlantic formulation continuity under 21 CFR 184.1343 enables multinational manufacturers to standardize recipes across EU and North American production facilities.
Industry Challenges
- Prebiotic health claim substantiation:Evolving EFSA and FDA evidentiary standards for gut-microbiome benefits require costly clinical trials and extended documentation timelines.
- Galactomannan extraction capex intensity:Specialized aqueous extraction infrastructure and solvent recovery systems demand significant upfront capital deployment relative to commodity hydrocolloid alternatives.
- Organic certification compliance:EU organic framework adherence across multi-tier Mediterranean supplier networks complicates traceability and audit documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carob Extract Market |
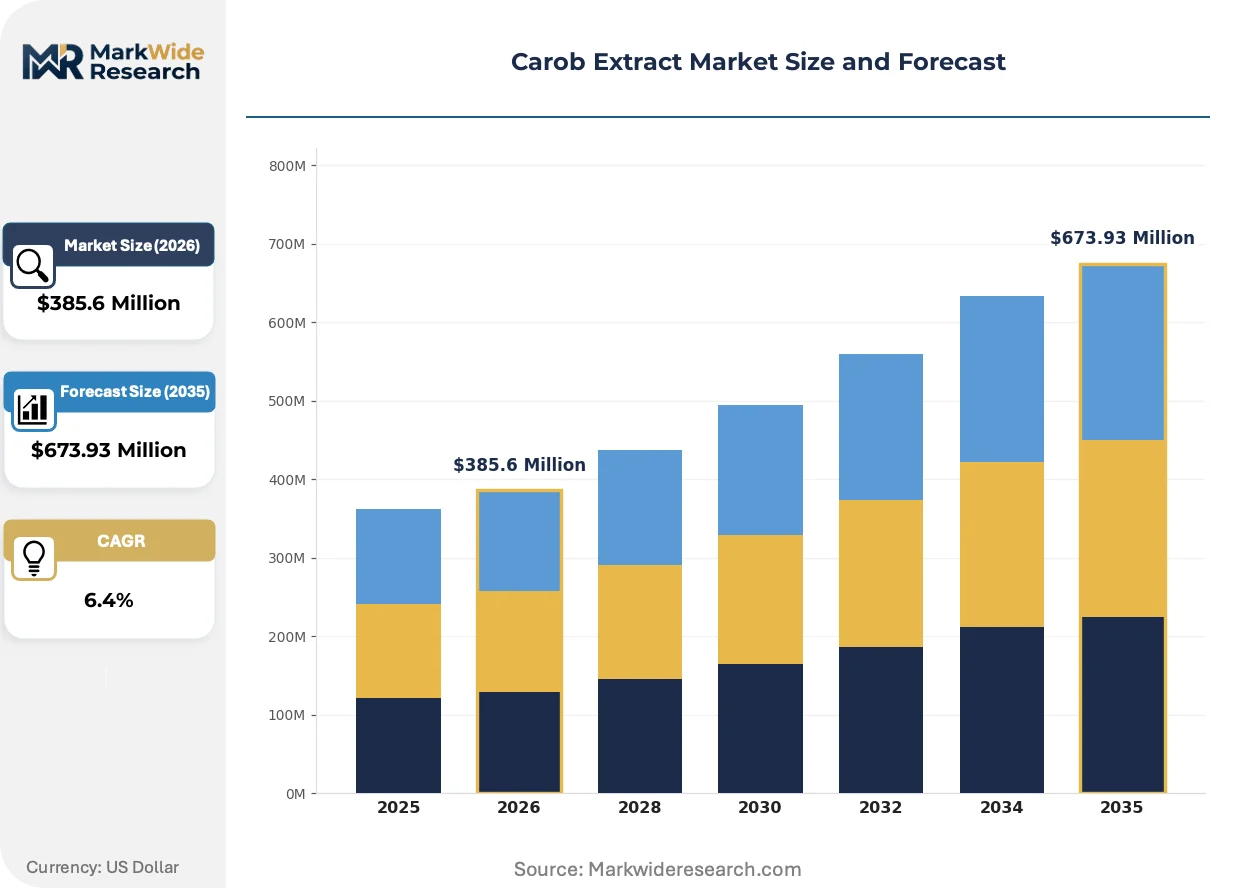
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Extracts Application: Food & Beverage, Nutraceuticals, Cosmetics, Animal Feed End User: Food Manufacturers, Dietary Supplement Producers, Personal Care Brands, Livestock Feed Suppliers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Cargill, Incorporated, Tate & Lyle, Carob S.A., AEP Colloids, Altrafine Gums, Australian Carobs, DuPont de Nemours, Savvy Foods, Stavros Parpis Foods Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carob Extract Market Trends and Innovations
Formulation science and procurement protocols are converging to reposition carob extract from commodity cocoa substitute to functional ingredient with differentiated health claims and supply chain credentials.
Enzymatic modification of carob galactomannans is expanding into reduced-sugar bakery texture systems where hydrocolloid functionality replaces both fat and sugar in clean-label applications. European industrial bakeries and contract manufacturers are accelerating adoption ahead of 2025 reformulation deadlines. This enzymatic processing is expanding into premium positioning territory previously occupied by chemically modified starches and synthetic emulsifiers.
REACH compliance constraints on extraction solvents are tightening permissible chemical profiles for hydrocolloid recovery operations across EU member states. Manufacturers must retire legacy solvent systems and validate aqueous alternatives through ECHA registration dossiers. Spanish and Portuguese processors face the steepest retooling requirements given their concentration of legacy extraction infrastructure.
Direct contracting between food manufacturers and Mediterranean orchard cooperatives is displacing spot-market bean purchasing and multi-layer trader networks. German and French confectionery multinationals now specify origin and harvest batch in procurement agreements. This relationship compression is most visible in organic-certified supply chains where traceability commands premium positioning.
Carob Extract Market Segmentation
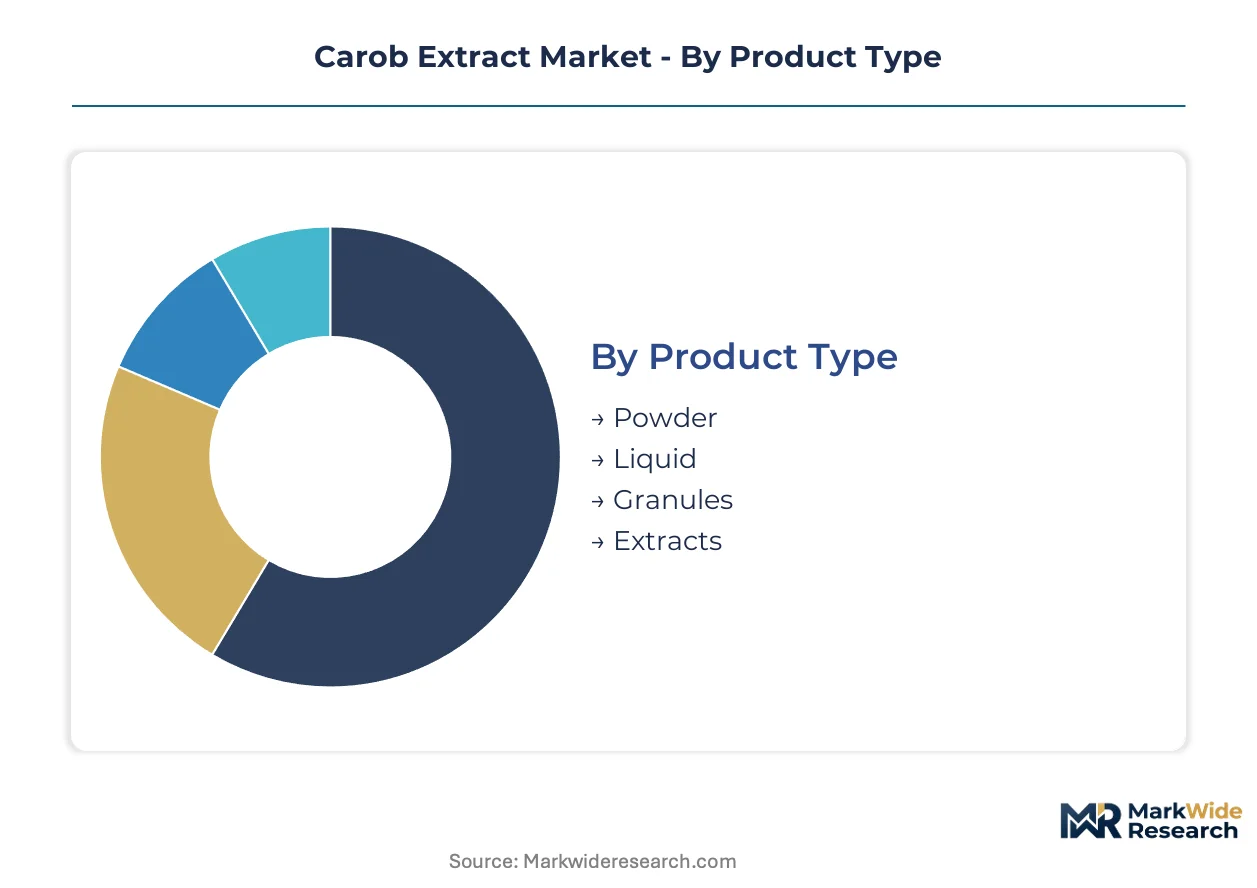
Carob extract's commercial trajectory hinges on format versatility across powder, liquid, and solid states, each commanding distinct procurement economics and shelf-life profiles. Application fragmentation between food manufacturing and nutraceutical channels creates divergent specification requirements that reshape supplier R&D priorities. Distribution pathway selection directly determines margin capture, with direct-to-manufacturer contracts yielding superior unit economics against retail intermediation.
Product Type:
Powder formats dominate volume throughput across Mediterranean processing clusters, while liquid extracts command premium positioning in beverage fortification where rapid dispersion properties justify higher procurement costs.
- Powder:Spray-dried aqueous extracts with extended shelf stability and superior dry-blending compatibility anchor bakery and confectionery formulation. German and Spanish industrial bakeries specify powder grades for clean-label cocoa replacement in reduced-sugar applications.
- Liquid:Aqueous concentrates optimized for rapid dispersion in functional beverages and ready-to-mix drink bases. Nutraceutical producers in France and Italy leverage liquid formats for prebiotic shot positioning where bioactive preservation matters.
- Granules:Intermediate moisture formats bridging powder flowability and liquid solubility for specialty confectionery inclusions.
- Extracts:Standardized polyphenol and galactomannan concentrates serving pharmaceutical-grade specifications in dietary supplement capsules.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Food and beverage channels absorb the majority of Mediterranean-sourced supply, though nutraceutical applications are climbing the fastest as EFSA prebiotic claim pathways mature.
- Food & Beverage:Cocoa replacement in chocolate confectionery, clean-label stabilizers in reduced-sugar bakery, and natural sweetening systems in dairy alternatives. EU Green Deal procurement mandates from French and German manufacturers accelerate substitution away from synthetic hydrocolloids.
- Nutraceuticals:Prebiotic fiber supplements and antioxidant capsules exploiting soluble polyphenol content for gut-microbiome positioning. REACH-compliant extraction methods from Portuguese processors enable novel food dossier preparation.
- Cosmetics:Emollient and humectant applications in natural personal care formulations targeting antioxidant skin protection claims.
- Animal Feed:Palatability enhancers and digestive health promoters in premium livestock and pet nutrition rations.
Food & Beverage holds current volume primacy. Nutraceuticals present the steepest expansion trajectory.
End User:
Procurement scale and specification stringency separate multinational food manufacturers from mid-tier dietary supplement producers, with contract manufacturers occupying a hybrid position on volume and customization.
- Food Manufacturers:Large-scale confectionery and bakery producers with direct Mediterranean orchard contracting and EFSA novel food compliance requirements.
- Dietary Supplement Producers:Mid-scale capsule and powder blenders prioritizing organic certification and prebiotic claim substantiation documentation.
- Personal Care Brands:Natural cosmetics formulators seeking clean-label emollients with antioxidant marketing positioning.
- Livestock Feed Suppliers:Agricultural nutrition companies integrating carob pulp byproducts into ruminant and monogastric feed formulations.
Food Manufacturers dictate current procurement volumes. Dietary Supplement Producers are gaining negotiating leverage through claim differentiation.
Distribution Channel:
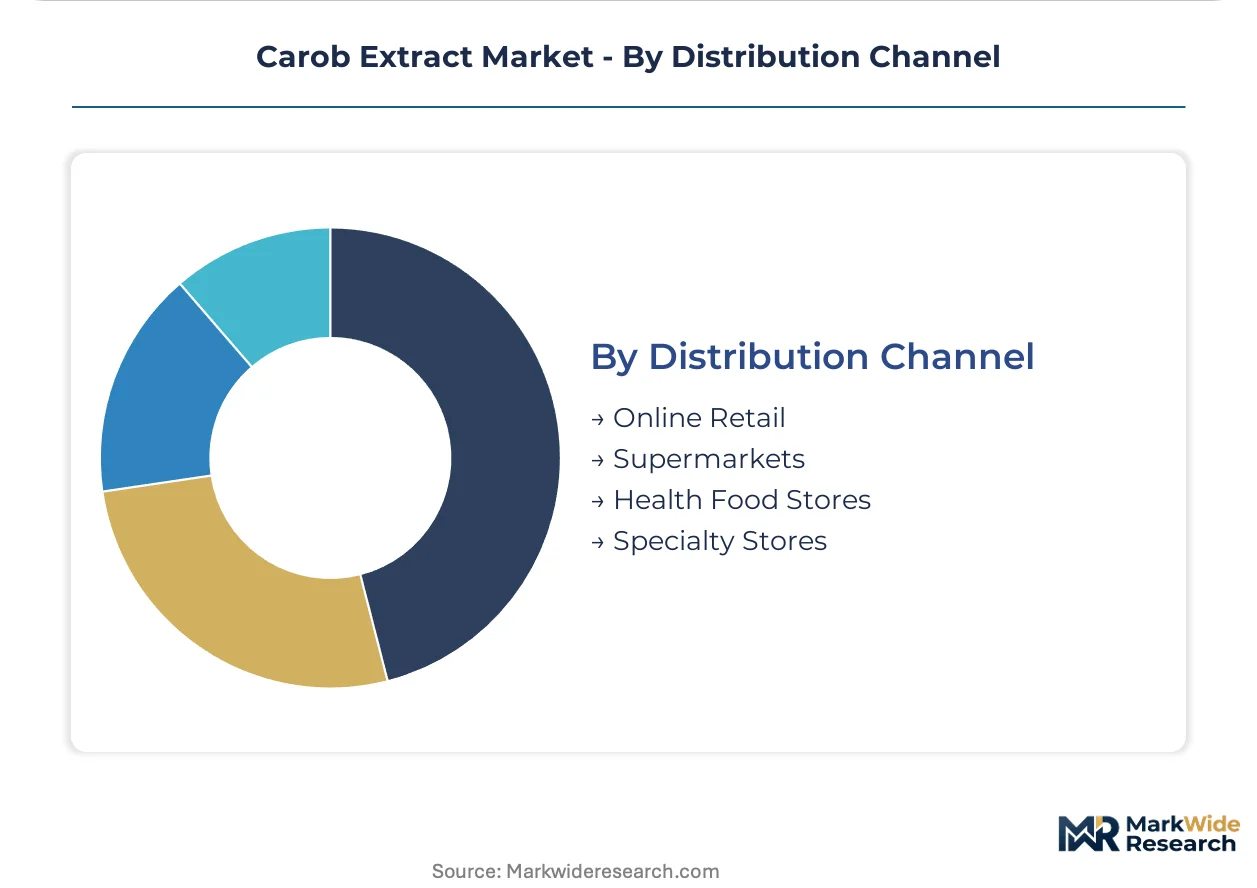
Channel selection determines traceability depth and margin retention, with direct manufacturer relationships displacing multi-layer trader networks in organic-certified supply chains.
- Online Retail:E-commerce platforms serving small-scale nutraceutical and cosmetic ingredient buyers with certificate-of-analysis documentation.
- Supermarkets:Mass-market retail for consumer-packaged carob powder and beverage products with standard shelf placement.
- Health Food Stores:Specialty retail channels emphasizing organic certification and Mediterranean origin storytelling for premium positioning.
- Specialty Stores:Professional ingredient suppliers and food service distributors catering to artisan bakery and craft confectionery segments.
Direct contracting dominates at-scale procurement. Online Retail is capturing incremental share among emerging brand entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carob cultivation originated in the eastern Mediterranean, with Spain, Portugal, and Italy establishing the first commercial orchards during the 19th century. Modern processing infrastructure now clusters around these historical growing regions, while Australian plantings provide Southern Hemisphere counter-seasonal supply security.
Spain
Andalusian cooperatives supply the majority of EU organic-certified carob beans to German confectionery manufacturers. EU Green Deal procurement mandates from Madrid accelerate orchard renovation subsidies. Valencia hosts the densest concentration of aqueous extraction facilities serving French industrial bakery chains.
Italy
Sicilian and Apulian growers dominate pharmaceutical-grade galactomannan production for nutraceutical capsule manufacturers. EFSA novel food dossier preparation consumes significant regulatory bandwidth in Rome. Emilia-Romagna's ingredient distributors maintain direct contracting relationships with Dutch dietary supplement blenders.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia specify carob powder for clean-label cocoa replacement in reduced-sugar formulations. REACH compliance auditing of Mediterranean suppliers occurs through Hamburg-based chemical regulatory consultancies. Berlin-headquartered food multinationals negotiate origin-traceable procurement agreements with Spanish orchard cooperatives.
France
Paris-region nutraceutical producers leverage liquid carob extracts for prebiotic shot positioning in functional beverage channels. ANSM oversight of novel food claims shapes formulation documentation requirements. Provence-Alpes-Côte d'Azur maintains limited domestic orchard acreage, relying on Portuguese bean imports for regional processing.
Australia
South Australian and Victorian orchard consolidation delivers counter-seasonal supply security to Asian-Pacific nutraceutical manufacturers. TGA prebiotic health claim pathways influence extraction method documentation standards. Melbourne-based ingredient traders coordinate containerized shipments to US West Coast dietary supplement producers under FDA GRAS continuity frameworks.
Carob Extract Market Competitive Landscape
Capital-heavy Mediterranean processors compete with asset-light formulation specialists across distinct value chain segments. The market structure concentrates upstream extraction capacity among Spanish and Portuguese operators with legacy aqueous infrastructure, while downstream blending and claim substantiation fragments across German, French, and Australian specialists. Three archetypes dominate: orchard-integrated processors controlling bean supply, toll manufacturers offering REACH-compliant extraction services, and nutraceutical-positioned brands investing in clinical trial documentation. Consolidation pressures manifest through direct contracting displacement of trader networks, and enzymatic modification capability acquisition for reduced-sugar texture systems.
Within the orchard-integrated tier, Australian Carobs anchors Southern Hemisphere production archetypes through consolidated South Australian and Victorian holdings. Cargill, Incorporated represents multinational agricultural commodity traders leveraging grain and oilseed logistics networks for Mediterranean bean procurement at scale. DuPont de Nemours occupies the specialty chemicals positioning, exemplifying hydrocolloid formulators integrating carob gum into texture-system applications. These three entities collectively illustrate the competitive spectrum from raw material control through functional ingredient formulation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle |
| Carob S.A. |
| AEP Colloids |
| Altrafine Gums |
| Australian Carobs |
| DuPont de Nemours |
| Savvy Foods |
| Stavros Parpis Foods Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive orchard integration across Mediterranean cooperatives anchors both supply security and premium pricing power for organic-certified carob extract, compressing trader margins while elevating direct-contractor returns.
Pricing Analysis
Three-tier pricing structure across organic premium, conventional standard, and feed-grade economy levels separates pharmaceutical-grade galactomannan concentrates from industrial bakery powders and pulp byproducts. Price differentiation hinges on EU organic certification tier and EFSA novel food dossier completion status, with REACH-compliant aqueous extraction commanding substantial premiums. Cost compression in conventional powder grades is intensifying as Spanish processors retool legacy solvent infrastructure. Dietary supplement producers exhibit highest price sensitivity due to clinical trial documentation burdens, while German industrial bakeries prioritize supply continuity over unit cost.
Supply Chain Analysis
Seasonal labor availability in Andalusian and Sicilian harvesting regions constrains peak-season processing throughput and shapes orchard consolidation economics. Raw material supply draws from Spanish, Portuguese, and Italian carob bean harvests, with South Australian counter-seasonal plantings reducing single-region dependency. Single-source vulnerability persists for pharmaceutical-grade galactomannan extraction, where Sicilian and Apulian processors hold specialized aqueous infrastructure. Distribution runs through direct manufacturer contracts displacing multi-layer trader networks, particularly in organic-certified channels where traceability documentation commands premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in carob extract hinges on enzymatic modification technology maturation, which collapses production costs for reduced-sugar texture systems while opening premium bakery positioning.
For Market Incumbents: Extend EFSA novel food dossier capabilities ahead of competitor filings, securing claim exclusivity windows for prebiotic positioning. Deepen backward integration into Australian orchard assets to neutralize Mediterranean climate volatility. Cargill-scale logistics networks and DuPont formulation science represent defendable moats against emerging toll manufacturers. For New Entrants and Emerging Players: Enzymatic galactomannan modification expertise offers entry into reduced-sugar bakery texture systems where incumbent chemical portfolios lag clean-label requirements. White-space concentration in US West Coast dietary supplement manufacturing under FDA GRAS frameworks presents lower regulatory barrier entry than EU novel food pathways. Direct-to-manufacturer liquid extract positioning in functional beverages bypasses powder-format volume competition. For Investors and Strategic Acquirers: Roll-up economics work for Mediterranean toll processors because ECHA REACH compliance costs are driving consolidation among sub-scale Spanish and Portuguese extraction facilities. Orchard-integrated processors with novel food dossier capabilities offer superior long-term viability through claim substantiation assets. The signal to watch is EFSA prebiotic health claim authorization timelines, which would trigger rapid premium-tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Consolidation | Australian counter-seasonal plantings reduce Mediterranean climate dependency for multinational manufacturers. |
| Enzymatic Modification Investment | Clean-label texture systems replace synthetic emulsifiers in EU industrial bakery reformulation deadlines. |
| EFSA Novel Food Dossier Filing | Prebiotic claim substantiation opens premium nutraceutical positioning ahead of competitor regulatory approval. |
| REACH-Compliant Extraction Retooling | Aqueous solvent systems satisfy ECHA registration requirements for continued EU market access. |
| Direct Manufacturer Contracting | Origin-traceable procurement agreements displace trader networks and capture organic certification premiums. |
Research Methodology
Coverage spans Mediterranean sourcing clusters, Australian production regions, and North American formulation centers, with primary inputs from each. Orchard cooperative managers, extraction facility technical directors, German and French industrial bakery procurement leads, and Portuguese REACH compliance consultants provided ground-level operational data. Secondary validation drew from EFSA novel food register entries, ECHA REACH registration dossiers, EU organic certification databases, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across powder, liquid, and granule format segments.
Granularity extends to product type, application channel, and end-user procurement tier throughout the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit trends, with cross-validation against EFSA regulatory timeline assumptions and EU Green Deal procurement mandate implementation rates. Industry-specific inputs included Mediterranean orchard yield variability patterns and spray-drying capacity expansion announcements.
The model holds under stable EFSA novel food assessment timelines and continued EU Green Deal procurement enforcement; deviation in regulatory authorization delays or cocoa price collapse below substitution thresholds would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Macadamia Butter Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Fruit Kernel Products Market