
 Flax Seed Meal Market | 2026-2036
Flax Seed Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Flax Seed Meal Market Foresight
Organic certification tiers is redrawing competitive boundaries in flax seed meal procurement. Richardson International Limited leverages its Canadian prairie sourcing network to sustain premium organic volumes. Archer Daniels Midland anchors North American supply through its grain handling infrastructure. Cargill Incorporated controls downstream access by integrating oil extraction with meal processing operations.
Flax seed meal is the ground residue of flaxseed after oil extraction, typically containing 30-40% protein and 25-35% dietary fiber by weight, used primarily as a functional ingredient in human nutrition and animal feed formulations. The organic product type commands premium positioning as clean-label procurement tightens across food manufacturers. Nutritional supplements application leads value contribution as dietary supplement companies seek standardized lignan content. Bakery products application competes on volume scale but faces margin compression from commodity pricing dynamics.
USDA organic standards and FDA food facility registration requirements shape ingredient verification protocols for domestic suppliers. Health Canada and the Canadian Food Inspection Agency regulate cross-border meal shipments through mycotoxin limits and GMO documentation. EFSA novel food evaluations in Europe create entry barriers for unproven processing variants. Stakeholders must monitor evolving allergen labeling mandates and omega-3 stability claims enforcement as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
Clean-label procurement mandates from dietary supplement manufacturers are restructuring flax seed meal sourcing priorities, forcing suppliers to validate organic provenance and alpha-linolenic acid stability through documented chain-of-custody systems.
Growth Catalysts
- USDA Organic Certification:Food manufacturers in the United States now require certified organic defatted meal with guaranteed lignan content, pulling premium volumes from Canadian prairie processors who maintain dual-certified facilities.
- Omega-3 Fortification Demand:Nutritional supplement formulators seek standardized alpha-linolenic acid concentrations, creating specification-driven contracts that reward processors with in-house testing laboratories.
- Domestic Processing Infrastructure:United States-based oil extraction facilities are expanding captive meal production capacity to secure supply for functional food manufacturers facing import documentation delays.
Market Restraints
- Input Cost Volatility:Flaxseed commodity prices fluctuate with Canadian prairie weather patterns, compressing processor margins when oil extraction yields drop below target recovery rates.
- Supply Concentration Risk:Premium organic flaxseed production concentrates in Saskatchewan and Manitoba, exposing buyers to single-region crop failure and mycotoxin contamination events.
- Substitution Threat:Chia seed meal and algae-derived omega-3 ingredients capture share in premium supplement formulations where price sensitivity remains low.
Strategic Opportunities
- Underpenetrated Bakery Segment:Artisan bread manufacturers in Germany and France represent untapped volume potential for fiber-fortified formulations using defatted flax meal as a wheat flour extender.
- Regulatory Tailwind:Health Canada's updated dietary fiber health claims framework creates pathway for lignan-specific marketing in functional food applications.
- Direct-to-Manufacturer Distribution:Bypassing traditional ingredient distributors through integrated e-procurement platforms reduces lead times for mid-scale supplement compounders.
Industry Challenges
- Certification Timeline Compression:USDA organic recertification audits now require 18-month documentation windows, straining processors who source from multi-year crop rotations.
- Omega-3 Stability Expertise Gap:Formulation chemists with specialized knowledge of alpha-linolenic acid oxidation prevention command premium salaries, constraining R&D expansion at emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flax Seed Meal Market |
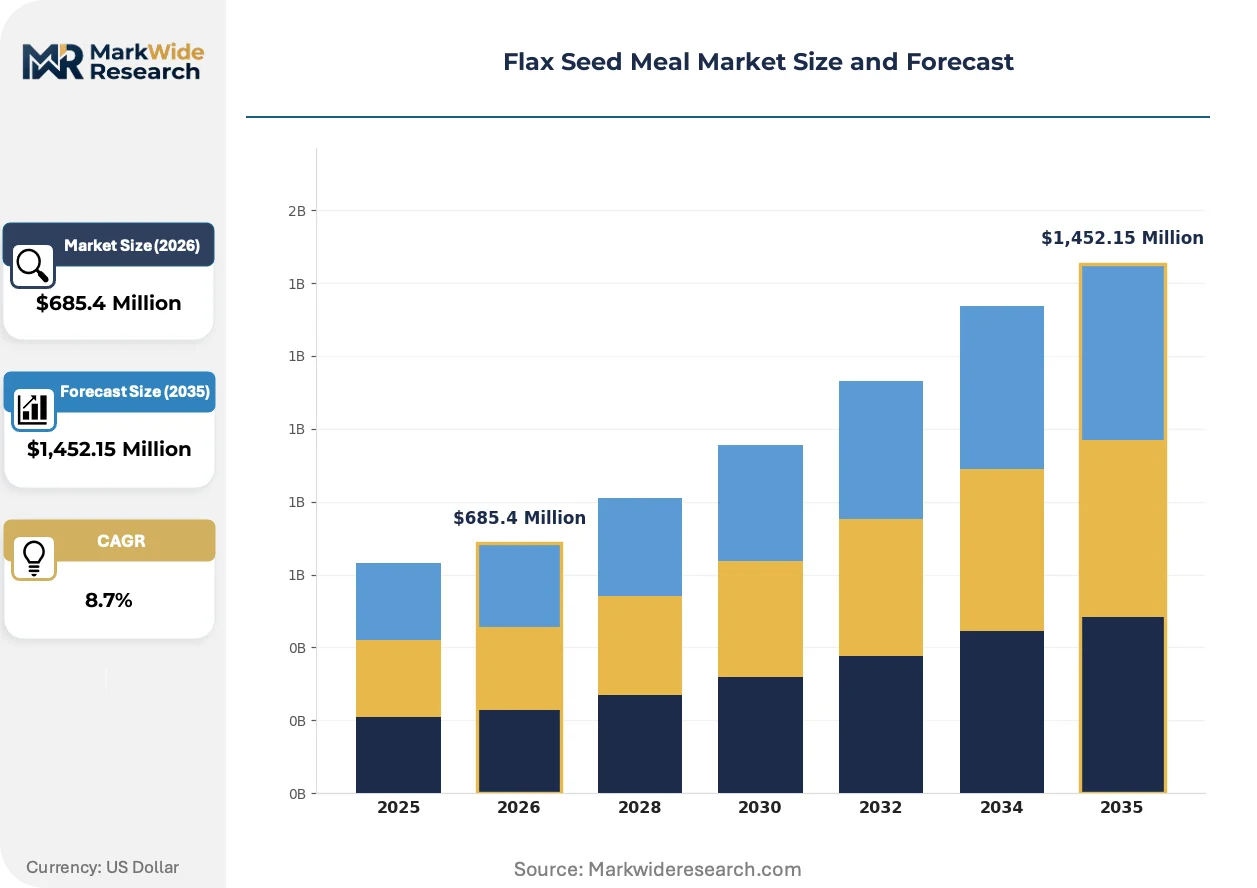
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Powdered, Defatted, Whole, Milled Application: Bakery Products, Nutritional Supplements, Animal Feed, Cosmetics, Pharmaceuticals, Beverages End User: Food Manufacturers, Dietary Supplement Companies, Pet Food Producers, Personal Care Firms Packaging Type: Plastic Bags, Paper Bags, Bulk Containers, Foil Packs |
| Companies Covered | Richardson International Limited, Glanbia Nutritionals Inc., Archer Daniels Midland, CanMar Grain Products Ltd., Grain Millers Inc., Cargill Incorporated, Bioriginal Food & Science Corp., AgMotion Inc., TA Foods Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flax Seed Meal Market Shifts & Advancements
Processing technology advances and regulatory documentation requirements are converging to reshape how flax seed meal quality is verified and monetized across the value chain.
Cold-press oil extraction with inline nitrogen blanketing is miniaturizing from industrial-scale installations to modular 500-kilogram batch systems. Regional organic processors in Minnesota and North Dakota are adopting these compact units to offer toll processing services for smallholder flaxseed cooperatives. This distributed processing model is compressing transportation costs and enabling farm-gate organic certification that was previously uneconomical.
EFSA's novel food evaluation pathway for enzymatically modified flax protein isolates is creating compliance complexity for European market entry. Supplement manufacturers targeting EU distribution must submit comprehensive toxicology dossiers that extend product launch timelines by 24-36 months. German and Dutch formulators are responding by prioritizing minimally processed whole meal ingredients that fall outside novel food scope.
Long-term offtake agreements with fixed alpha-linolenic acid specifications are displacing spot market purchasing among top-ten dietary supplement brands. This contract consolidation concentrates volume with processors who maintain certified laboratories and multi-year organic supply contracts. The shift is most visible in United States contract manufacturing organizations, who now bundle ingredient sourcing with formulation services to lock in margin.
Flax Seed Meal Market Segmentation
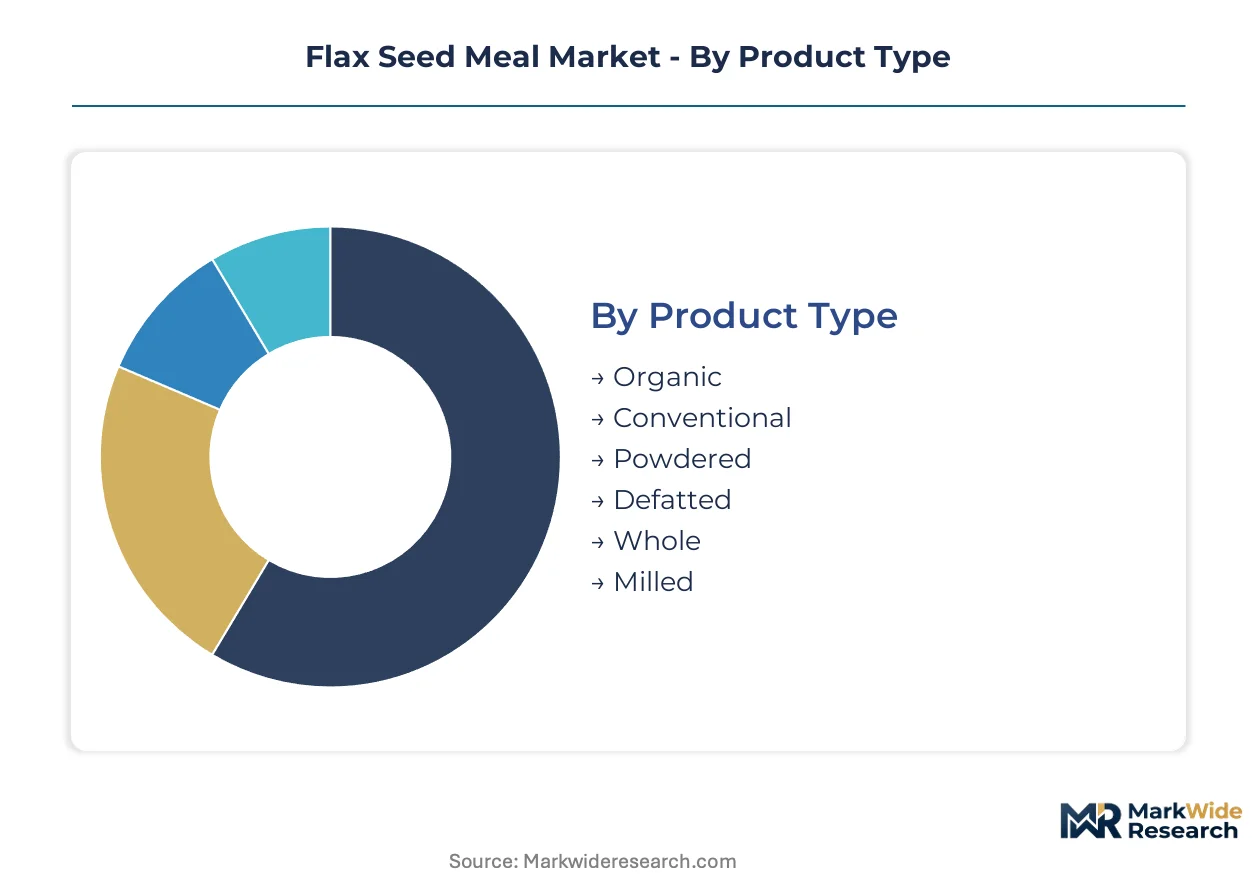
Flax seed meal segmentation reveals divergent margin structures across certification tiers and processing intensities. Product type and application splits expose where premium extraction commands pricing power versus commodity volume plays.
Product Type:
Margin pools concentrate in certified organic and defatted segments where specification-driven contracts reward provenance documentation.
- Organic:USDA-certified organic meal carries 30-40% protein content and guaranteed lignan specifications. Dietary supplement companies in the United States now mandate certified organic defatted meal with validated chain-of-custody documentation, pulling premium volumes from Saskatchewan and Manitoba processors.
- Defatted:Oil-extracted residue with standardized alpha-linolenic acid content serves functional food manufacturers seeking omega-3 fortification without lipid instability. Domestic United States oil extraction facilities are expanding captive defatted meal capacity to bypass import documentation delays.
- Conventional:Non-certified commodity meal competes on volume scale for animal feed and industrial applications.
- Powdered:Fine-milled particle size distribution targets beverage and cosmetic formulators requiring dispersibility.
- Whole:Unprocessed seed meal retains full oil content for artisan bakery applications demanding moisture retention.
- Milled:Coarse grind specifications serve pet food producers seeking fiber fortification at lower price points.
Defatted holds installed capacity. Organic is rotating up the share rankings.
Application:
Volume concentration sits with bakery and feed, while value extraction concentrates in supplement and pharmaceutical tiers.
- Nutritional Supplements:Standardized lignan and alpha-linolenic acid content drives specification-driven procurement. United States contract manufacturing organizations now bundle organic flax meal sourcing with formulation services to secure multi-year offtake agreements.
- Bakery Products:Fiber-fortified formulations use defatted meal as wheat flour extender in artisan bread production. German and French manufacturers represent expanding volume potential as clean-label fiber claims tighten across European Union labeling requirements.
- Animal Feed:Protein and fiber content supports ruminant and poultry nutrition formulations.
- Cosmetics:Lignan antioxidant properties drive demand in natural personal care formulations.
- Pharmaceuticals:Clinical-grade specifications for enterolactone precursor applications require GMP-compliant processing.
- Beverages:Powdered meal integration into smoothie and functional drink bases demands ultra-fine milling and suspension stability.
Nutritional Supplements capture value density. Bakery Products anchor volume throughput.
End User:
Procurement sophistication varies sharply across customer types, with dietary supplement firms demanding laboratory certification that food manufacturers often waive.
- Dietary Supplement Companies:These buyers enforce fixed alpha-linolenic acid specifications and 18-month organic documentation windows. Top-ten brands are consolidating volume with processors maintaining certified laboratories and multi-year organic supply contracts.
- Food Manufacturers:Functional food producers seek domestically processed defatted meal with guaranteed omega-3 content for clean-label positioning.
- Pet Food Producers:Fiber and protein specifications drive procurement for premium companion animal formulations.
- Personal Care Firms:Cosmetic-grade lignan extracts require contaminant testing beyond food-grade standards.
Dietary Supplement Companies dictate specification intensity. Food Manufacturers provide volume baseload.
Packaging Type:
Packaging selection tracks customer scale and shelf-life requirements, with bulk formats dominating industrial procurement.
- Bulk Containers:Tote and drum formats serve high-volume food manufacturers with just-in-line delivery systems. United States-based oil extraction facilities favor bulk handling to minimize labor and packaging material costs in captive meal production.
- Foil Packs:Oxygen-barrier pouches preserve alpha-linolenic acid stability for premium supplement brands. Nitrogen-flushed foil packaging extends shelf life for organic meal distributed through direct-to-manufacturer e-procurement channels.
- Plastic Bags:Standard polyethylene formats serve conventional grade commodity shipments.
- Paper Bags:Kraft multi-wall constructions target sustainability-positioned artisan bakery and pet food segments.
Bulk Containers dominate tonnage movement. Foil Packs are climbing the fastest as stability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie provinces generate the bulk of organic flaxseed supply, yet downstream processing capacity clusters in United States grain corridors where dietary supplement manufacturers enforce specification-driven procurement.
United States
Functional food manufacturers in Minnesota and North Dakota are expanding captive defatted meal production to bypass import documentation delays. FDA food facility registration requirements and USDA organic certification standards shape verification protocols for domestic suppliers. Minneapolis-St. Paul processors are installing modular cold-press systems to serve smallholder flaxseed cooperatives with toll processing services.
Canada
Saskatchewan and Manitoba prairie growers supply premium organic volumes to cross-border supplement compounders. Health Canada and the Canadian Food Inspection Agency regulate meal shipments through mycotoxin limits and GMO documentation requirements. Winnipeg-based processors maintain dual-certified facilities to satisfy United States organic procurement mandates.
Germany
Artisan bread manufacturers in Bavaria and Baden-Württemberg represent expanding volume potential for fiber-fortified formulations. EFSA novel food evaluations create compliance complexity for enzymatically modified flax protein isolates, extending launch timelines. Cologne and Hamburg formulators are prioritizing minimally processed whole meal ingredients that fall outside novel food scope.
France
Clean-label bakery producers in Île-de-France and Auvergne-Rhône-Alpes are tightening fiber claim requirements under EU labeling standards. ANSM and national food safety authorities enforce contaminant testing beyond baseline food-grade specifications. Lyon-based ingredient distributors are building direct-to-manufacturer e-procurement channels to reduce lead times for mid-scale compounders.
Netherlands
Rotterdam and Amsterdam serve as consolidation points for flax meal distribution into German and French manufacturing clusters. REACH and EU Green Deal sustainability frameworks are reshaping documentation requirements for cross-border ingredient shipments. Eindhoven region logistics providers are specializing in nitrogen-flushed bulk handling to preserve alpha-linolenic acid stability during transshipment.
Flax Seed Meal Market Competitive Landscape
Concentration sits with integrated grain handlers and specialized oil extraction operators who control both upstream supply and downstream meal processing. The vendor base separates into three functional tiers: multinational agribusiness conglomerates with captive crushing capacity, regional organic processors with dual-certification infrastructure, and toll-processing specialists serving smallholder cooperatives. Dominant competitive moves include backward integration into organic flaxseed contracting and capacity expansion of in-house testing laboratories to secure multi-year offtake agreements.
Among North American integrated handlers, Richardson International Limited and Archer Daniels Midland exemplify the grain infrastructure archetype with prairie sourcing networks and cross-border distribution capabilities. Cargill Incorporated occupies a position representing oil extraction integration, where downstream meal processing ties directly to crushing operations. CanMar Grain Products Ltd. and Grain Millers Inc. sit within the specialized processor tier, serving specification-intensive dietary supplement manufacturers with certified organic volumes.
| Leading Market Players |
|---|
| Richardson International Limited |
| Glanbia Nutritionals Inc. |
| Archer Daniels Midland |
| CanMar Grain Products Ltd. |
| Grain Millers Inc. |
| Cargill Incorporated |
| Bioriginal Food & Science Corp. |
| AgMotion Inc. |
| TA Foods Ltd. |
| Others |
Supply & Pricing Matrix
USDA organic certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where documented chain-of-custody commands substantial premiums over conventional grades while excluding uncertified prairie processors from premium buyer pools.
Pricing Analysis
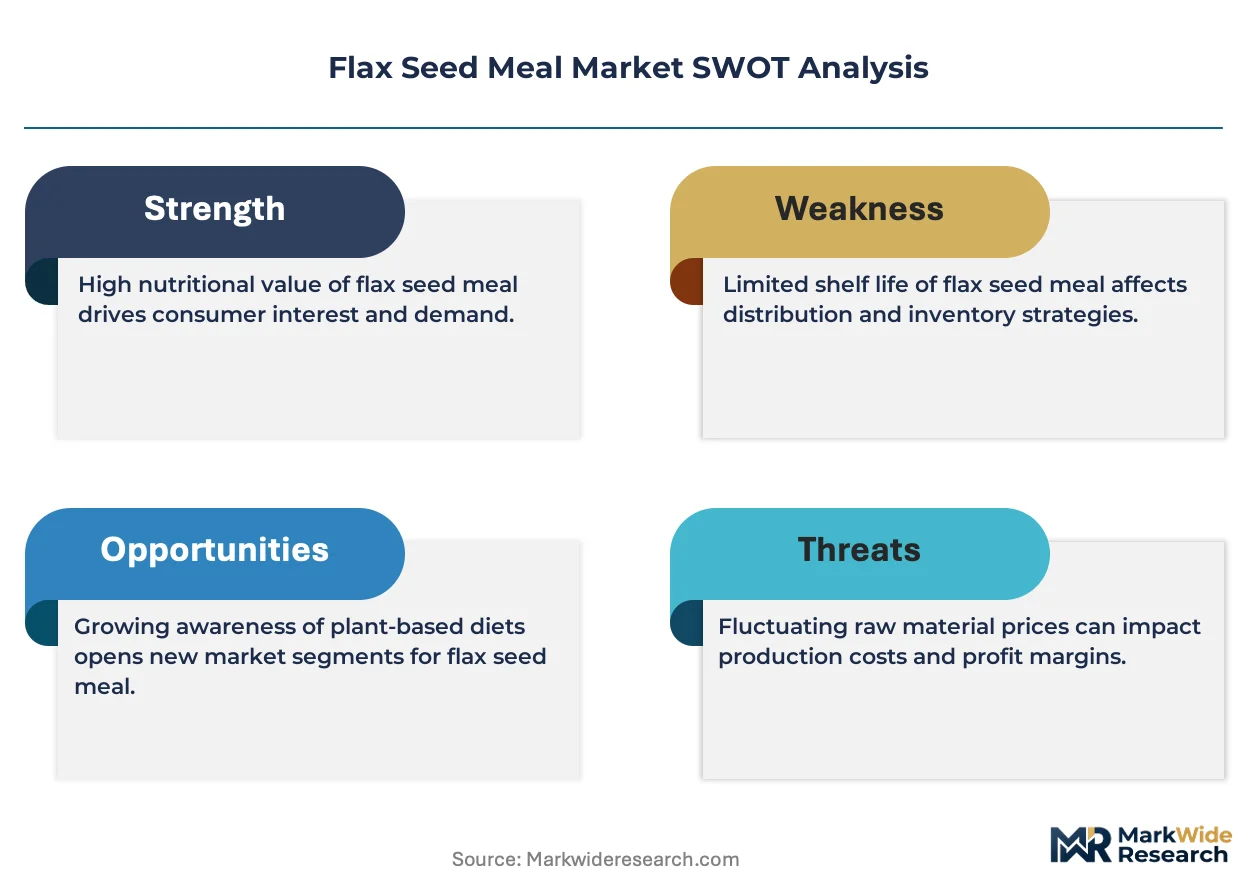
USDA organic standards dictate the pricing tier structure across the flax seed meal market, separating certified organic defatted meal from conventional commodity grades. Three-tier pricing stratifies across premium organic-lignan-specified, standard defatted-omega-3-verified, and economy conventional-feed-grade levels. Price differentiation rests on certification grade and alpha-linolenic acid testing infrastructure. Cost compression in the conventional tier is intensifying because chia seed meal and algae omega-3 alternatives capture share in price-insensitive supplement formulations. Dietary supplement companies show least price sensitivity; animal feed compounders exhibit highest sensitivity.
Supply Chain Analysis
Inventory cycles compress to 6-8 weeks for organic-certified meal as buyers enforce just-in-line delivery to preserve alpha-linolenic acid stability. Geographic supply concentrates in Canada, specifically Saskatchewan and Manitoba prairie provinces, with secondary processing clusters in Minnesota and North Dakota. Raw material dependencies center on flaxseed commodity availability, nitrogen blanketing equipment for oxidation prevention, and certified laboratory testing capacity. Single-region crop failure in the Canadian prairies represents the dominant supply chain risk. Distribution runs through integrated grain handlers with captive oil extraction and direct-to-manufacturer e-procurement channels for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as flaxseed commodity prices normalize following prairie weather disruptions and organic certification backlogs clear through recertification cycles.
For Market Incumbents: Fortify backward integration into organic flaxseed contracting with Saskatchewan and Manitoba grower cooperatives to secure multi-year supply against substitution threats from chia and algae omega-3 ingredients. Expand in-house testing laboratory capacity in Minnesota and North Dakota to capture specification-driven contract consolidation among top-ten dietary supplement brands. For New Entrants and Emerging Players: Lead with toll processing services for smallholder organic flaxseed cooperatives using modular cold-press nitrogen blanketing systems, targeting the underpenetrated artisan bakery segment in Germany and France. Prioritize direct-to-manufacturer e-procurement platforms to bypass traditional ingredient distributors and compress lead times for mid-scale European compounders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular processing equipment as 500-kilogram batch systems displace industrial-scale installations. Over the 5-10 year window, target acquisition of regional organic processors with dual USDA-Health Canada certification infrastructure and established relationships with prairie grower cooperatives. Watch for inflection signals in Health Canada dietary fiber health claims enforcement that would unlock lignan-specific marketing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Contracting | Secures prairie flaxseed supply against Canadian weather volatility and substitution threats. |
| Modular Cold-Press Capacity Expansion | Enables toll processing for smallholder cooperatives in Minnesota and North Dakota. |
| Dual-Certification Infrastructure Investment | Unlocks cross-border access to USDA and Health Canada regulated buyer pools. |
| In-House Testing Laboratory Buildout | Captures specification-driven contracts from top-ten dietary supplement brands. |
| Direct-to-Manufacturer E-Procurement Platform | Reduces lead times for German and French mid-scale compounders. |
Research Methodology
A spread of perspectives from organic certification auditors, oil extraction facility managers, dietary supplement procurement leads, and prairie grower cooperative representatives converged on the working assumptions underlying supply and demand modeling. Primary fieldwork combined structured interviews with secondary validation through USDA organic certification databases, Health Canada mycotoxin compliance records, FDA food facility registration filings, and EFSA novel food evaluation dossiers. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand aggregation from end-use application segments.
Segmentation dimensions modeled include product type tier, application intensity, certification grade, and geographic processing cluster across the projection horizon. CAGRs were derived from trend extrapolation of specification-driven contract growth and substitution elasticity estimates. Industry-specific forecast inputs incorporated alpha-linolenic acid stability degradation curves and organic certification audit timeline compression effects.
The analysis sits within stated boundaries; outcomes outside sustained organic premium retention or EFSA regulatory pathway clarity would require recalibration. Forecasts reflect documented assumptions regarding prairie crop yields, nitrogen blanketing technology adoption rates, and lignan standardization enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Soy Nut Market