
 Dry Roasted Almonds Snack Market | 2026-2036
Dry Roasted Almonds Snack Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Roasted Almonds Snack Market Foresight
Specialty shops is narrowing as a standalone channel as supermarkets and online retailers consolidate snack purchasing into fewer trips. Blue Diamond Growers leverages its cooperative structure to control supply from California orchards through branded retail. Wonderful Pistachios & Almonds sustains massive billboard and sports marketing spend that anchors consumer mindshare in the premium nut set. Planters competes through heritage brand recognition and ubiquitous placement across conventional grocery formats.
Dry roasted almonds are tree nuts subjected to dry heat treatment without oil immersion, typically reaching internal temperatures of 130°C to 160°C to develop Maillard browning while preserving lipid stability and crunch texture; the process yields shelf-stable, portable protein sources for on-the-go consumption. Flavored varieties dominate volume as chili-lime, smokehouse, and honey-roasted profiles command price premiums over base salted lines. Organic almonds represent the fastest-growing product type as supply chain traceability and pesticide-free claims attract health food store buyers. Resealable packs capture expanding margin pools by reducing staleness-driven waste and encouraging repeat purchase behavior.
The FDA mandates allergen labeling for tree nuts under FALCPA, while USDA organic certification governs premium positioning in the segment. California's Almond Board enforces pasteurization requirements that shape processing infrastructure investments and out-of-state market access protocols. Stakeholders must monitor water allocation rulings in the Central Valley and evolving EU maximum residue limits for aflatoxin as determinants of export viability and roasting facility siting decisions.
Market Dynamics
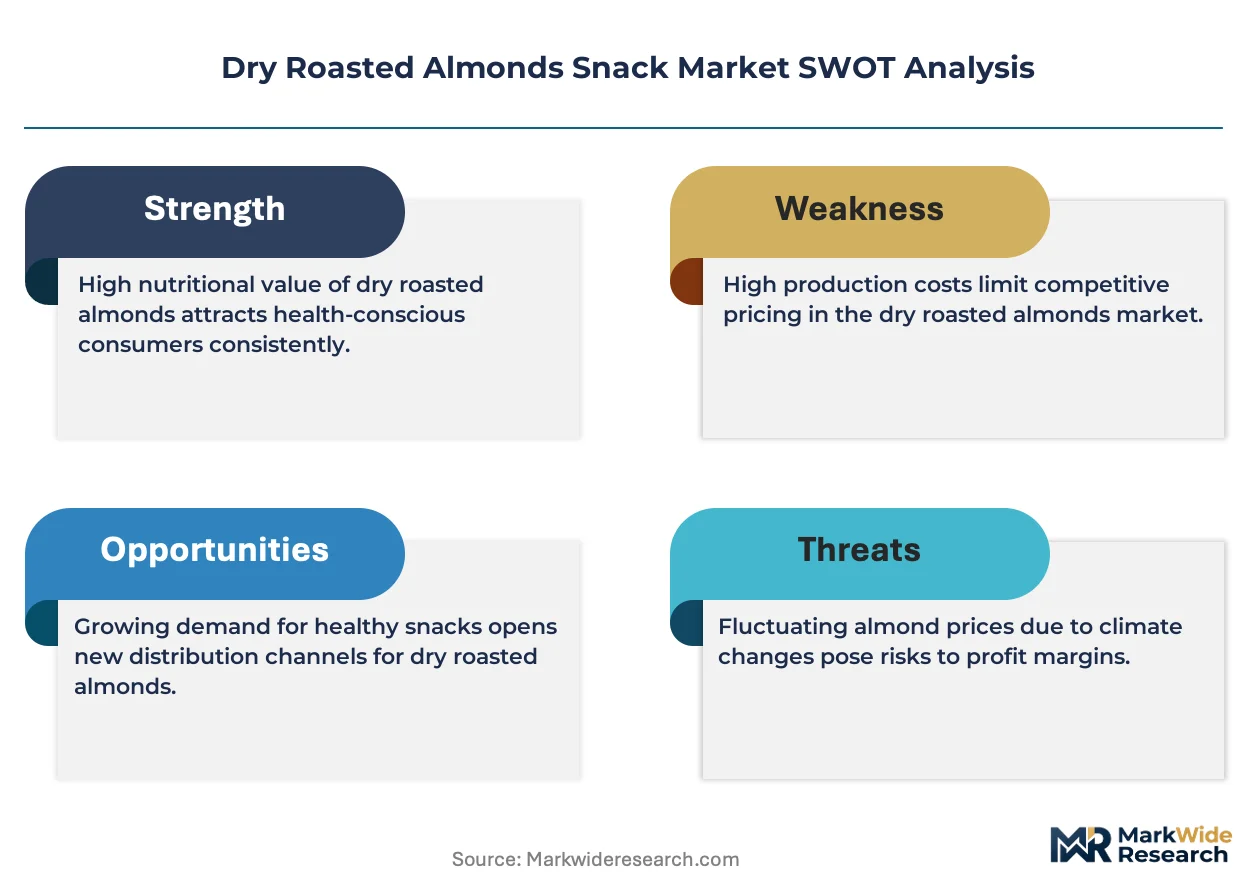
California's Central Valley water allocation rulings are compressing raw almond supply reliability while pasteurization mandates from the Almond Board of California reshape capital deployment across roasting infrastructure.
Growth Catalysts
- Protein-forward snacking:Health enthusiasts are displacing conventional chips and crackers with portable tree nut options that deliver clean-label macronutrient density without processing additives.
- USDA organic certification:Pesticide-free supply chain traceability commands shelf-space premiums in health food channels and attracts buyers willing to absorb higher per-unit costs.
- Clean-label roasting technologies:Hot-air and infrared systems reduce acrylamide formation while preserving Maillard browning, enabling brands to market reduced-sodium formulations without flavor compromise.
Market Restraints
- Input cost volatility:Bee colony rental fees for orchard pollination and Central Valley irrigation water pricing swing unpredictably, compressing processor margins during drought cycles.
- Supply concentration risk:California's monopoly on domestic raw almond requirements creates single-point vulnerability to heat dome events, frost damage, and shipping port congestion at Oakland and Long Beach.
- Regulatory friction:EU maximum residue limits for aflatoxin impose batch-testing burdens and rejection risks that deter small-roaster export ambition and favor scaled testing infrastructure.
Strategic Opportunities
- Underpenetrated convenience channels:Vending machine and micro-market installations in corporate campuses and healthcare facilities remain underserved by premium nut brands relative to candy and chip incumbents.
- Regulatory tailwind:FDA modernization of healthy claim definitions under the Nutrition Innovation Strategy creates pathway for roasted almonds to carry explicit heart-health messaging previously restricted to raw forms.
- Technology convergence:Blockchain-enabled lot tracking combined with smartphone-accessible provenance data is digitizing consumer trust verification and commanding price premiums in direct-to-subscription channels.
Industry Challenges
- Skill gap in thermal process engineering:Roasting facilities struggle to hire operators capable of calibrating multi-zone hot-air systems for consistent moisture reduction without lipid oxidation.
- Capex intensity for pasteurization compliance:PPO treatment chambers or steam pasteurization lines require seven-figure facility investments that strain mid-tier processors seeking Almond Board certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Roasted Almonds Snack Market |
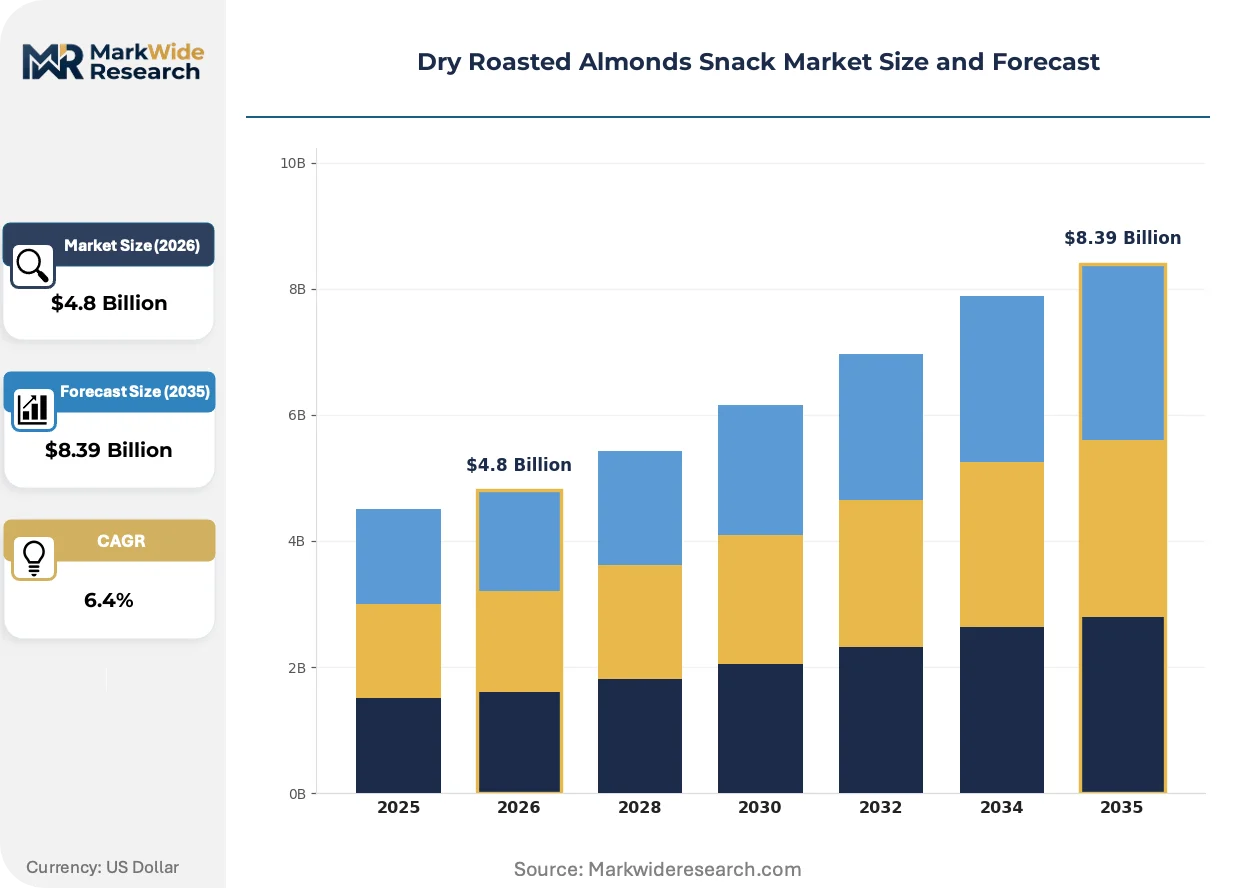
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unsalted, Salted, Organic Packaging Type: Bag, Jar, Bulk, Resealable Pack Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Shops End User: Health Enthusiasts, Diabetics, General Consumers, Fitness Buffs |
| Companies Covered | Blue Diamond Growers, Wonderful Pistachios & Almonds, Planters, Mariani Nut Company, Sahale Snacks, Olam International, The Hershey Company, Treehouse Almonds, Bergin Fruit and Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Roasted Almonds Snack Market Shifts & Advancements
Flavor innovation and packaging functionality are converging with traceability demands to redefine what constitutes premium positioning in tree nut snacking.
Infrared roasting control systems is digitizing temperature profiling across belt ovens, enabling real-time moisture and color feedback loops. Mid-sized processors in the Texas Triangle are retrofitting legacy gas-fired lines with sensor arrays. This compression of process variance is reducing reject rates and extending shelf-life claims from nine to fourteen months.
EU Green Deal Farm-to-Fork strategy is tightening maximum residue limits for pesticide metabolites in imported tree nuts. Roasting facilities serving European distributors are consolidating supplier relationships to California orchards with documented integrated pest management protocols. Organic-certified processors with existing EU equivalency arrangements are capturing expanded allocation from buyers seeking regulatory pre-clearance.
Resealable pack formats are displacing single-serve pillow packs in club and e-commerce channels. Health-conscious households in the Pacific Northwest and Northeast corridor are gravitating toward multi-serve pouches with zip-lock closures that reduce perceived waste. This shift is compressing unit economics for brands reliant on convenience-store velocity and forcing packaging line reconfiguration investments.
Dry Roasted Almonds Snack Market Segmentation
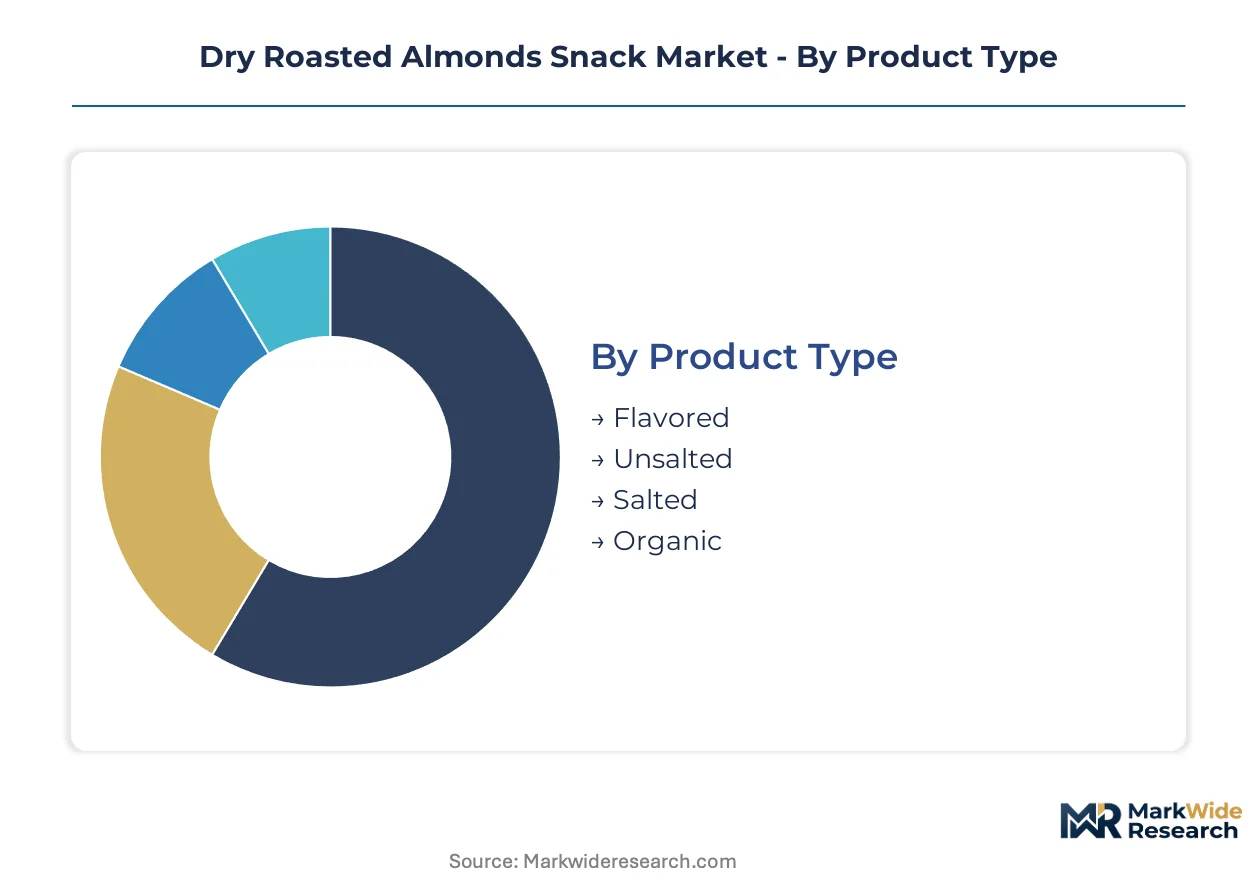
Segmentation in dry roasted almonds reveals divergent velocity profiles across consumption occasions, with impulse formats cycling faster than pantry staples and wellness-positioned lines commanding premium shelf resets. Understanding these turnover rhythms shapes inventory deployment and promotional cadence for processors and retailers alike.
Product Type:
Flavored varieties turn inventory fastest through convenience channels, while organic SKUs sit longer in specialty retail awaiting discerning buyers.
- Flavored:Chili-lime, smokehouse, and honey-roasted profiles undergo Maillard browning with added seasoning layers that accelerate palate fatigue and repeat purchase frequency. Convenience stores in Texas and Florida rotate these SKUs weekly to capture novelty-seeking snackers.
- Organic:USDA-certified pesticide-free almonds require documented supply chain traceability from California orchards with integrated pest management protocols. Health food stores in the Pacific Northwest and Northeast corridor absorb extended holding periods for these premium-positioned lines.
- Salted:Classic formulations anchor conventional grocery velocity through heritage brand recognition.
- Unsalted:Reduced-sodium positioning targets cardiac-conscious households and medical dietary prescriptions.
Flavored dominates installed base. Organic is where expansion concentrates.
Packaging Type:
Cost tier stratification separates single-serve convenience formats from bulk value positioning, with mid-tier resealable packs capturing margin expansion.
- Resealable Pack:Zip-lock pouch formats with multi-serve configurations reduce perceived waste and extend consumption windows across household snacking occasions. Club retailers and e-commerce channels favor these formats for their shipping durability and pantry storage appeal.
- Bulk:Food-service and ingredient-channel buyers in commercial bakeries and confectionery operations purchase unpackaged roasted almonds by weight for further processing into granola bars and chocolate confections.
- Bag:Standard pillow packs dominate traditional grocery impulse placement with lower unit economics.
- Jar:Rigid containers target pantry-stocking households seeking extended shelf stability.
Bag formats dominate installed base. Resealable pack is where expansion concentrates.
Distribution Channel:
Volume concentration varies sharply by geography, with consolidated retail power in California and fragmented specialty access in secondary markets.
- Supermarkets:Kroger, Safeway, and Albertsons banners control mainstream almond snack placement through category management protocols that favor scaled suppliers with promotional fund depth. These chains execute quarterly planogram resets that determine brand survival.
- Online Retailers:Amazon and Thrive Market subscription models enable direct-to-consumer velocity with blockchain-enabled provenance verification commanding price premiums. Digital channels bypass traditional slotting fee barriers for emerging organic brands.
- Health Food Stores:Sprouts and independent natural grocers maintain curated SKU counts with stringent clean-label requirements.
- Specialty Shops:Gourmet nut roasters and farmers market vendors serve regional taste preferences with small-batch production.
Supermarkets dominate installed base. Online retailers are where expansion concentrates.
End User:
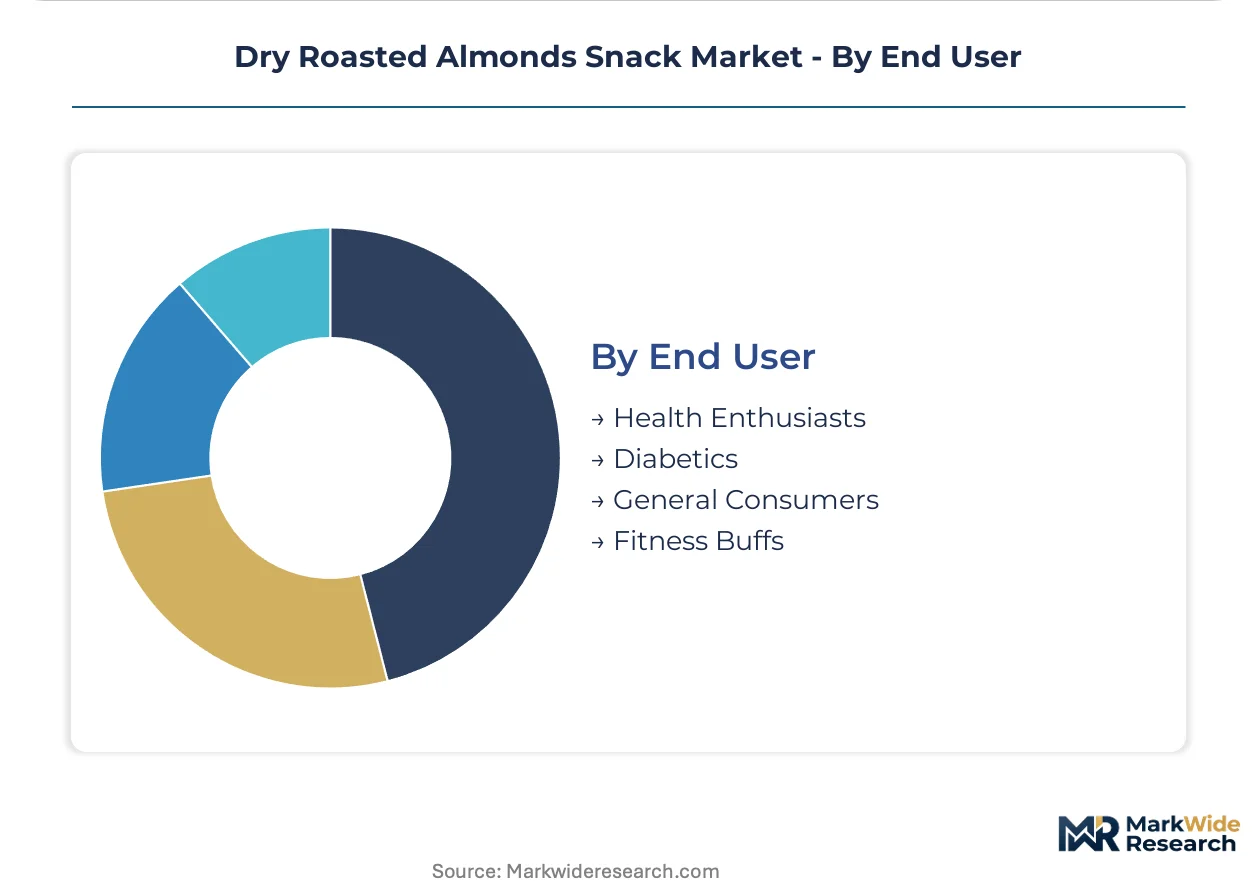
Customer type segmentation aligns protein-forward positioning with distinct lifestyle cohorts, from performance optimization to chronic condition management.
- Health Enthusiasts:Protein-forward snacking advocates displacing conventional chips with clean-label macronutrient density drive the steepest expansion trajectory in this category. These consumers absorb premium pricing for organic certification and reduced-sodium formulations.
- Fitness Buffs:Post-workout recovery protocols favor portable 1-ounce portion packs with measured protein content for gym bag and locker room consumption. Sports nutrition retailers stock these formats adjacent to protein powders.
- Diabetics:Low-glycemic index positioning with explicit carbohydrate disclosure targets blood glucose management protocols.
- General Consumers:Price-sensitive households purchase almonds as interchangeable salty snacks without wellness attribution.
General consumers dominate installed base. Health enthusiasts are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland and Long Beach container terminals anchor California's export corridor for processed almond products, while Union Pacific rail links connect Central Valley roasting facilities to Midwest distribution hubs.
United States
California's Central Valley supplies nearly all domestic raw almond requirements, with health-conscious households in the Pacific Northwest and Northeast corridor absorbing premium organic lines. The FDA mandates allergen labeling under FALCPA, while USDA organic certification governs shelf-space premiums in health food channels. Roasting clusters concentrate in Modesto and Fresno, where pasteurization-compliant facilities serve both retail and food-service buyers.
Germany
EU Green Deal Farm-to-Fork strategy is tightening maximum residue limits for pesticide metabolites in imported tree nuts, redirecting procurement toward California orchards with documented integrated pest management protocols. EFSA aflatoxin standards impose batch-testing burdens that favor scaled processors with dedicated laboratory infrastructure. Hamburg and Rotterdam serve as consolidation points for organic-certified shipments entering continental distribution networks.
United Kingdom
Post-Brexit border inspection protocols for tree nut imports have lengthened clearance times at Dover and Felixstowe, compressing shelf-life windows for small-batch roasters. The Food Standards Agency maintains alignment with EU aflatoxin thresholds while negotiating bilateral equivalence arrangements with California suppliers. London and Southeast England anchor demand for premium resealable pack formats through club retail and subscription e-commerce channels.
Japan
METI food labeling standards require explicit allergen disclosure and country-of-origin documentation for roasted nut imports, favoring suppliers with blockchain-enabled lot tracking. Consumer preference for low-sodium formulations aligns with domestic hypertension prevention campaigns. Yokohama and Osaka distribution centers handle the majority of California almond shipments entering the Japanese market.
Australia
Biosecurity import permits from the Department of Agriculture mandate heat treatment verification for California almond shipments to prevent pest introduction. Domestic almond production in South Australia and Victoria competes with imported roasted products on traceability claims. Sydney and Melbourne retail channels show expanding velocity for organic-certified lines targeting fitness-oriented consumer segments.
Dry Roasted Almonds Snack Market Competitive Landscape
On the supply side, the industry is consolidating around cooperative structures and integrated orchard-to-retail operations that control raw material flow through branded channels. Three strategic archetypes dominate: vertically integrated agricultural cooperatives with captive California acreage, diversified snack conglomerates leveraging heritage brand recognition, and specialty organic processors emphasizing supply chain transparency. Competitive moves center on pasteurization infrastructure investment to meet Almond Board certification requirements and packaging line reconfiguration to capture resealable format demand.
Among cooperative-structured operators, Blue Diamond Growers and Wonderful Pistachios & Almonds exemplify the orchard-control archetype, with the former representing centralized agricultural cooperative governance and the latter exemplifying integrated brand marketing investment. Planters occupies a position within the heritage-brand tier, anchoring conventional grocery placement through decades of consumer recognition. These three entities collectively represent the spectrum from upstream supply control to downstream brand equity leverage that defines competitive positioning in tree nut snacking.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Wonderful Pistachios & Almonds |
| Planters |
| Mariani Nut Company |
| Sahale Snacks |
| Olam International |
| The Hershey Company |
| Treehouse Almonds |
| Bergin Fruit and Nut Company |
| Others |
Supply & Pricing Matrix
California water allocation rulings function as a dual chokepoint that simultaneously widens organic-to-conventional price spreads and forces roasting facility consolidation toward pasteurization-compliant infrastructure. This regulatory risk vector compresses mid-tier processor margins while rewarding scaled operators with captive Central Valley orchard relationships.
Pricing Analysis
Volume-discount tiering structures separate bulk food-service contracts from premium direct-to-consumer subscriptions. Three-tier pricing stratifies across organic-certified premium, conventional branded standard, and private-label economy levels. Price differentiation rests on USDA organic certification and resealable pack functionality as primary drivers. Pricing pressure intensifies in the standard tier as drought-driven raw almond costs transmit downstream. Health enthusiasts demonstrate lowest price sensitivity, while general consumers exhibit highest elasticity.
Supply Chain Analysis
Supplier-financing arrangements including extended payment terms for California orchard pollination services and equipment leasing for pasteurization infrastructure shape working capital requirements. Raw material sourcing draws from California's Central Valley, with secondary dependencies on Australian and Spanish orchards for organic varietals. Bee colony rental fees, irrigation water pricing, and PPO treatment chemicals constitute critical input dependencies. Single-source vulnerability to California heat dome events represents the dominant structural risk. Distribution runs through Union Pacific rail links to Midwest hubs and Port of Oakland container terminals for European and Asian export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance verification is transforming dry roasted almonds into a platform economy where subscription-direct brands capture margin pools previously absorbed by retail slotting fees. Interoperability between smartphone-accessible lot tracking and health-app nutritional logging creates new data-layer value.
For Market Incumbents: Pre-empt private-label erosion by consolidating organic-certified orchard acreage through cooperative governance expansion. Accelerate resealable pack line reconfiguration to capture club retail velocity before mid-tier processors achieve Almond Board pasteurization compliance. Channel control through quarterly planogram reset negotiation remains the critical defensive lever against emerging direct-to-subscription competitors.
For New Entrants and Emerging Players: Corporate campus vending and healthcare facility micro-markets represent the most penetrable white-space entry points, underserved by premium nut brands relative to candy and chip incumbents. Pacific Northwest health food store buyers seeking reduced-sodium formulations offer secondary access. A go-to-market angle anchored on blockchain-verified Central Valley provenance commands subscription pricing premiums without slotting fee burdens.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors organic-certified processors with existing EU equivalency arrangements and pasteurization-compliant infrastructure. Long-term viability hinges on water security positioning within California's Central Valley groundwater sustainability districts. The signal to watch is Almond Board enforcement of enhanced pasteurization standards that would accelerate mid-tier processor exit.
| Strategic Initiative | Industry Significance |
|---|---|
| Pasteurization Infrastructure Investment | Almond Board certification requirements favor scaled processors with seven-figure facility commitments. |
| Resealable Pack Line Reconfiguration | Zip-lock pouch formats capture club retail and e-commerce margin pools from legacy pillow packs. |
| Organic Certification Expansion | USDA pesticide-free traceability commands shelf-space premiums in Sprouts and Thrive Market channels. |
| Blockchain Provenance Integration | Smartphone-accessible lot tracking digitizes consumer trust verification for subscription-direct models. |
| EU Equivalency Arrangement Securing | EFSA aflatoxin pre-clearance enables organic shipment allocation to Hamburg and Rotterdam distributors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with roasting facility operators, almond orchard managers, and health food store category buyers; and secondary validation through USDA organic certification databases, FDA FALCPA guidance documents, Almond Board pasteurization compliance records, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down value projections derived from trade flow analysis.
Forecast inputs incorporated product type segmentation across flavored, organic, salted, and unsalted lines; packaging format differentiation between resealable, bulk, bag, and jar configurations; and end-user cohorts spanning health enthusiasts, fitness buffs, diabetics, and general consumers. CAGRs were computed through iterative reconciliation of historical velocity patterns with projected protein-forward snacking displacement rates and clean-label roasting technology adoption curves. Water allocation rulings and EU maximum residue limit evolution served as scenario-weighting variables.
Practitioners should monitor Central Valley groundwater sustainability enforcement and EU Green Deal Farm-to-Fork pesticide metabolite tightening for early signals of supply cost inflection. Forecasts reflect assumptions regarding drought cycle duration and Almond Board regulatory posture. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Almond Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Australia Fox Nuts Market