
 Seed Butter Market | 2026-2036
Seed Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Butter Market Analytics
Parents of children with nut allergies is collapsing as the dominant buyer archetype while food service procurement teams gain share in institutional and commercial channels. SunButter LLC dominates branded sunflower butter distribution across North American retail shelves. Meridian Foods Limited leverages organic certification and clean-label positioning to anchor premium shelf space in European grocers. The Hain Celestial Group extends its natural foods portfolio into seed-based spreads through established retail relationships.
Seed butter denotes a spreadable paste produced by grinding oilseeds such as sunflower, pumpkin, or sesame seeds into a butter-like consistency, typically containing 50-60% fat content and requiring stabilization to prevent oil separation. Manufacturers employ stone milling or high-shear processing to achieve target particle sizes below 20 microns for smooth mouthfeel. Sunflower seed butter leads product type segments due to neutral flavor compatibility with childhood nutrition programs. Pouch packaging represents the fastest-growing format as on-the-go snacking applications expand among health enthusiasts. Baking applications command margin concentration through bulk ingredient contracts with commercial bakeries seeking allergen-free alternatives.
FDA enforces Food Allergen Labeling and Consumer Protection Act requirements that position seed butters as explicitly nut-free substitutes in school and childcare settings. USDA National School Lunch Program standards influence procurement specifications for sunflower butter as a protein component in meal planning. Stakeholders must monitor evolving state-level school nutrition mandates and clean-label certification standards to anticipate formulation and sourcing requirements.
Market Dynamics
School nutrition procurement mandates are compressing formulation timelines as sunflower seed butter displaces peanut butter in federally subsidized meal programs, forcing manufacturers to reconfigure stabilization systems for institutional-scale production runs.
Growth Catalysts
- USDA National School Lunch Program standards:Federal procurement specifications now explicitly permit sunflower seed butter as a protein alternative in K-12 cafeterias, creating institutional demand corridors that bypass retail velocity constraints.
- Stone milling technology:Traditional low-temperature grinding preserves heat-sensitive micronutrients while achieving sub-20-micron particle distribution, enabling clean-label positioning without synthetic stabilizers.
- Childcare facility concentration:Nut-free policies at daycare centers and summer camps in the United States have normalized bulk purchasing of seed butter as a standard inventory item rather than specialty allergen substitute.
Market Restraints
- Sunflower seed oil price volatility:Crude sunflower oil futures on the Black Sea exchange directly compress seed butter margins when Ukrainian export routes face disruption.
- Single-origin supply concentration:Premium organic sunflower seed processing clusters in Eastern European crushing facilities, exposing buyers to regional logistics bottlenecks and currency fluctuation.
- Sesame allergen labeling expansion:FDA's 2023 addition of sesame to major allergen lists complicates multi-seed butter formulations and triggers reformulation costs for existing SKUs.
Strategic Opportunities
- Pouch packaging for food service:Single-serve 1.15-ounce squeeze pouches penetrate airline catering and hospital meal kits where portion control and contamination prevention override cost sensitivity.
- Clean-label certification convergence:Dual pursuit of USDA Organic and Non-GMO Project verification opens shelf placement in natural grocery chains that command price premiums over conventional retail.
- Commercial bakery ingredient contracts:Bulk sunflower butter replaces almond paste in cookie and energy bar manufacturing lines seeking to eliminate tree nut cross-contamination protocols.
Industry Challenges
- Oil separation stabilization expertise:Food science talent capable of optimizing palm oil versus sunflower lecithin emulsifier ratios remains concentrated at legacy peanut butter manufacturers with limited seed-specific experience.
- State-level nutrition mandate fragmentation:California's stricter school sodium thresholds versus Texas flexibility forces multi-state distributors to maintain parallel SKU portfolios with divergent sodium specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Butter Market |
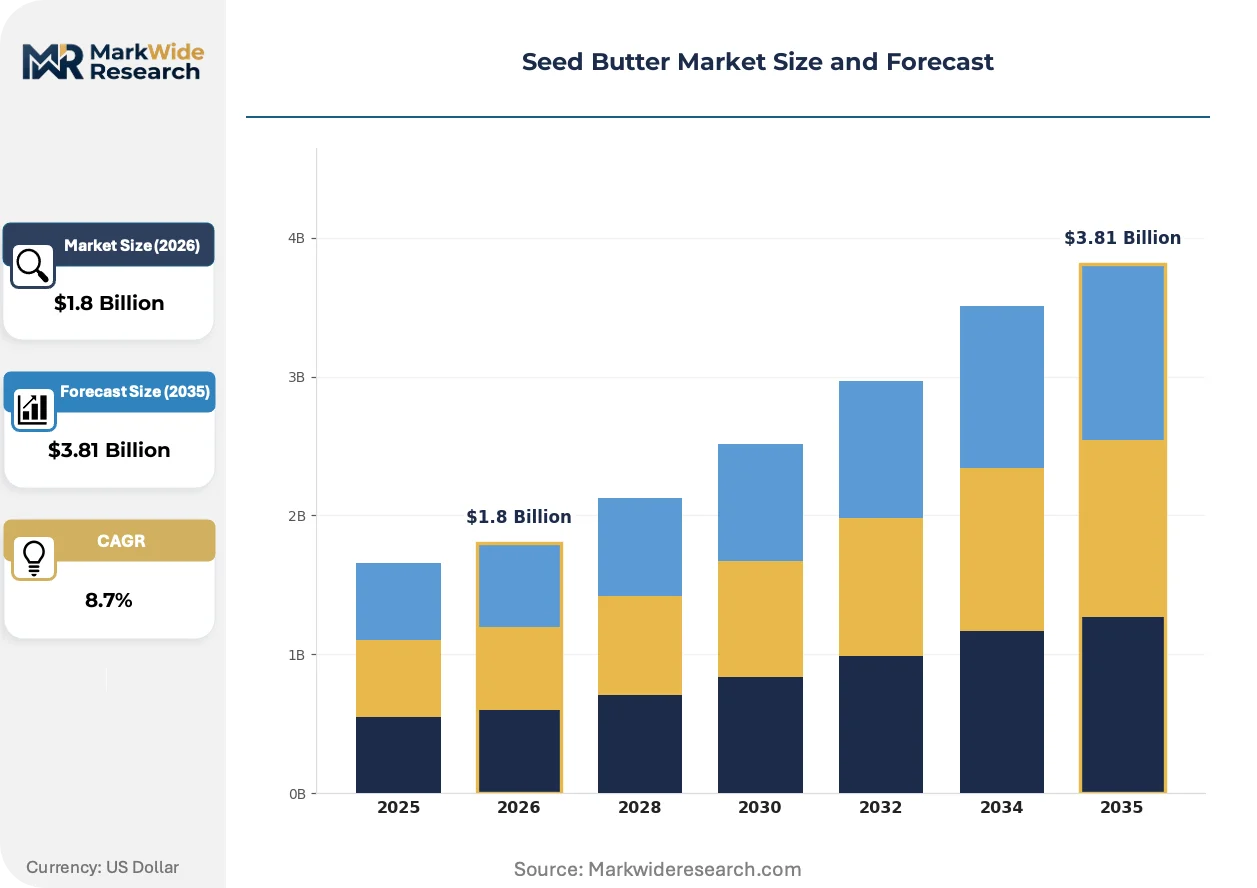
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower, Pumpkin, Sesame, Flaxseed End User: Households, Food Service, Retailers, Health Enthusiasts Packaging Type: Tubs, Jars, Pouches, Sachets Application: Baking, Spreading, Cooking, Snacking |
| Companies Covered | Meridian Foods Limited, SunButter LLC, Wells Made, Windy City Organics, 88 Acres The Seed, JAGRMA, Once Again Nut Butter Collective, Bliss Nut Butters, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Butter Market Evolving Landscape
Processing technology divergence and packaging format experimentation are compressing traditional category boundaries as seed butter migrates from spreadable condiment to functional ingredient across multiple food manufacturing verticals.
High-shear colloid milling is fragmenting the equipment supply base as mid-cap processors abandon traditional stone mills for continuous-flow systems capable of 500-kilogram hourly throughput. Commercial bakeries and co-manufacturers are adopting these systems to integrate seed butter directly into dough mixing lines without pre-tempering. The shift is compressing artisan positioning as a premium differentiator and forcing traditional stone-mill operators to defend craft credentials through transparent sourcing storytelling.
FDA enforcement of the Food Allergen Labeling and Consumer Protection Act is tightening disclosure requirements for facilities that process both tree nuts and seeds on shared equipment. Manufacturers must now validate cleaning protocols through allergen-specific ELISA testing or segregate production entirely. The regulatory pressure is accelerating capital deployment into dedicated seed-only processing facilities, particularly among suppliers targeting school district contracts where liability exposure concentrates.
On-the-go snacking behavior is displacing traditional jar purchasing as younger consumers reject refrigerator-dependent storage and communal spread contamination. Pouch formats with tear-notches and direct-squeeze nozzles are capturing gym bag and desk drawer occasions previously served by protein bars. The channel rotation is most visible in United States coastal metropolitan markets where convenience store penetration of natural products outpaces conventional grocery velocity.
Seed Butter Market Segmentation
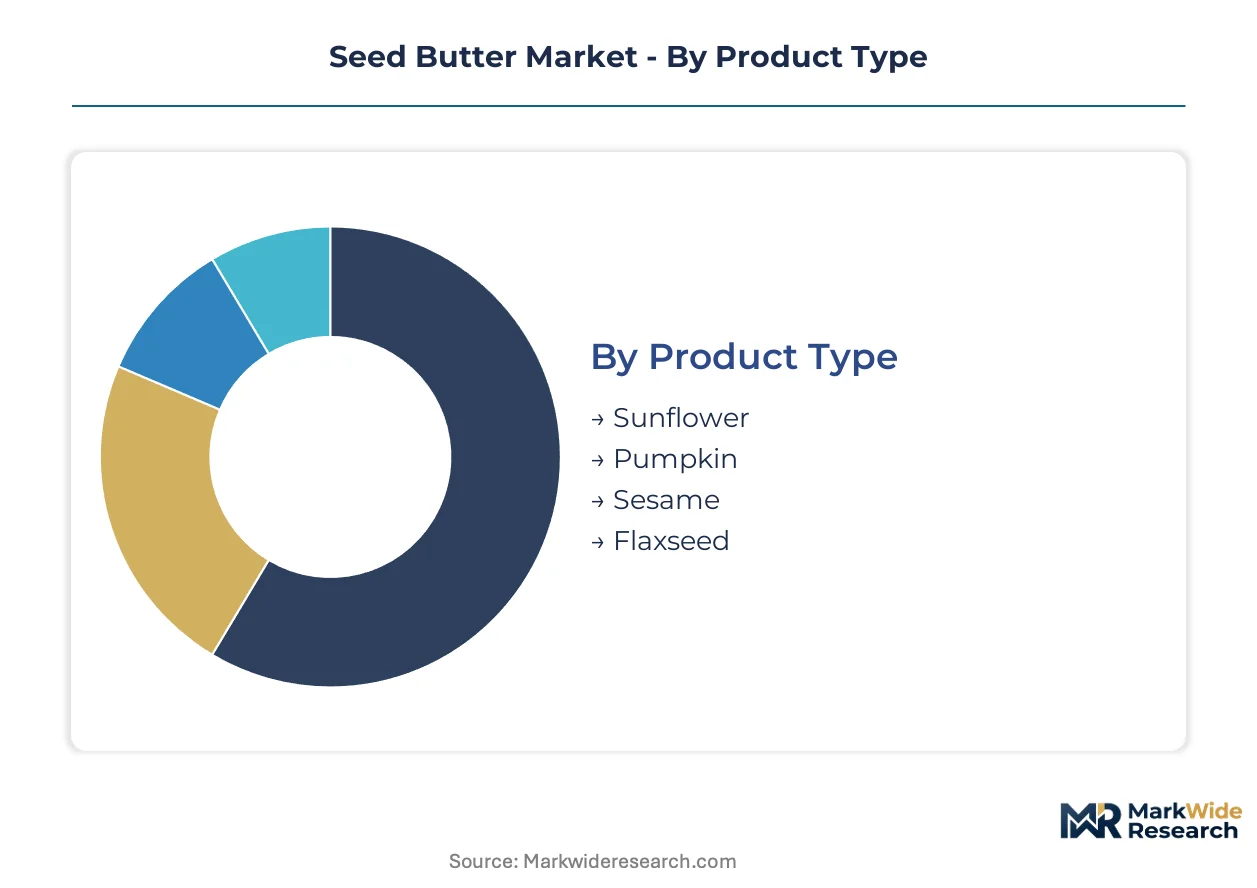
Segmentation in seed butter reveals how formulation specifications, channel requirements, and consumption occasions fragment manufacturing priorities. Distinct margin pools attach to institutional procurement versus premium retail positioning, forcing parallel production strategies.
Product Type:
Margin concentration aligns with flavor neutrality and allergen policy compatibility, not commodity input costs.
- Sunflower:Neutral flavor profile and pale coloration enable seamless substitution in childhood nutrition programs. USDA school lunch procurement specifications explicitly designate sunflower butter as the preferred peanut alternative, locking in institutional volume commitments. FDA allergen labeling exemptions for sunflower relative to sesame strengthen its position in multi-allergen facilities.
- Pumpkin:Distinctive orange hue and roasted seed notes command premium positioning in natural grocery channels. European organic certification clusters concentrate crushing capacity in Austria and Slovenia, exposing buyers to Black Sea logistics volatility.
- Sesame:Traditional tahini applications in Middle Eastern and Mediterranean cuisines sustain ethnic grocery distribution. FDA's 2023 major allergen reclassification triggers reformulation costs and dedicated line requirements.
- Flaxseed:Omega-3 fatty acid content targets functional nutrition positioning among aging demographics. Heat-sensitive lignin compounds require nitrogen-flush packaging and refrigerated distribution.
Sunflower holds installed capacity. Pumpkin is rotating up the share rankings.
End User:
Volume scale concentrates in contract-driven channels where specification compliance overrides brand premium.
- Households:Jar purchasing persists among families with diagnosed nut allergies seeking refrigerator-stable pantry staples. Clean-label certification premiums concentrate in coastal metropolitan markets with higher natural products penetration.
- Food Service:Bulk tub formats with pump dispensers dominate K-12 cafeteria lines and summer camp feeding operations. USDA commodity processing specifications mandate specific viscosity ranges for automated portioning equipment.
- Retailers:Private-label programs at natural grocery chains demand dual organic and Non-GMO Project verification as table stakes. Slotting fee structures favor established sunflower butter suppliers with proven velocity history.
- Health Enthusiasts:Pouch format adoption concentrates in gym and workplace snacking occasions. Protein content claims and portability drive repurchase rates above traditional spread applications.
Food Service commands contract volume. Health Enthusiasts are climbing the fastest.
Packaging Type:
Format selection directly determines distribution channel access and shelf-life engineering requirements.
- Tubs:Institutional-scale formats with resealable lids serve food service portioning and commercial bakery ingredient staging. HDPE construction withstands freezer-to-thaw cycling in bulk storage environments.
- Jars:Traditional glass and PET formats retain dominance in conventional grocery peanut butter aisle placement. Oil separation visibility through transparent walls necessitates consumer education on natural stabilization.
- Pouches:Flexible laminate structures with direct-squeeze nozzles capture on-the-go snacking and airline catering applications. Oxygen barrier layers extend ambient shelf life without synthetic preservatives.
- Sachets:Single-serve pillow packs penetrate hotel breakfast buffets and hospital meal kits where cross-contamination protocols prohibit communal containers. Unit economics favor high-volume contract manufacturing.
Jars hold installed capacity. Pouches are rotating up the share rankings.
Application:
Functional ingredient use in manufacturing verticals expands addressable market beyond condiment occasions.
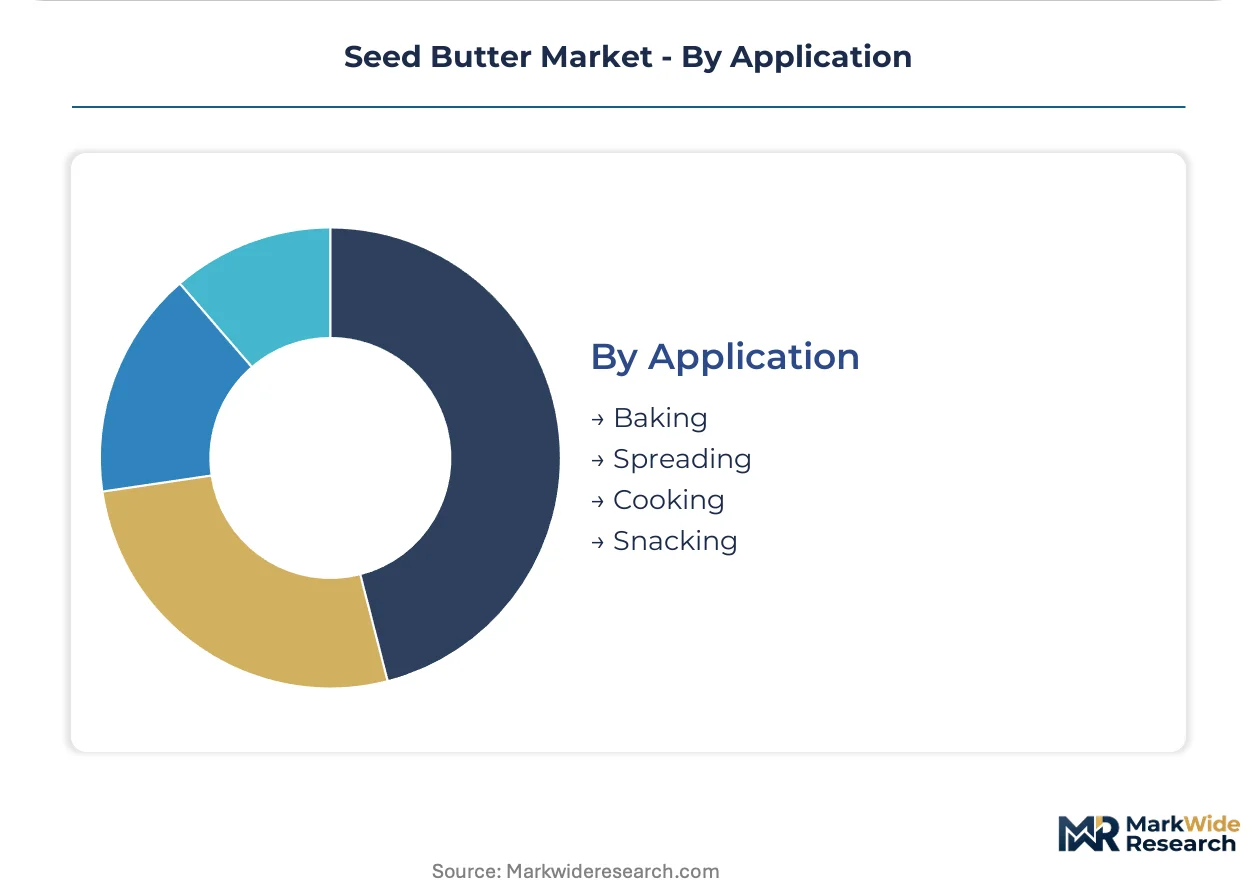
- Baking:Sunflower butter replaces almond paste in cookie, muffin, and energy bar formulations seeking tree nut elimination. Commercial bakeries specify particle size below 20 microns for seamless dough integration without pre-tempering.
- Spreading:Traditional bread and cracker applications sustain baseline consumption in household and food service channels. Texture engineering balances spreadability at refrigeration temperature with shelf stability.
- Cooking:Sauce and dressing formulations leverage seed butter emulsification properties in Asian and African cuisine adaptations. Heat tolerance limitations constrain high-temperature frying applications.
- Snacking:Protein-dip pairings with vegetable sticks and fruit slices drive pouch format growth. Portion-controlled packaging aligns with workplace wellness program procurement criteria.
Spreading holds installed capacity. Baking is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parents of children with nut allergies and food service procurement teams concentrate demand in distinct geographies, with institutional buyers clustering in jurisdictions with strict school nutrition mandates and allergen labeling enforcement.
United States
USDA National School Lunch Program specifications explicitly designate sunflower seed butter as the preferred peanut alternative in K-12 cafeterias, driving bulk procurement contracts. FDA's Food Allergen Labeling and Consumer Protection Act enforcement tightens disclosure requirements for shared equipment facilities. Minneapolis-based SunButter LLC anchors branded distribution across North American retail shelves.
Germany
Clean-label certification premiums concentrate in metropolitan markets with higher natural products penetration. EFSA guidance on novel food ingredients influences formulation approvals for emerging seed varieties. Bavaria-based organic processors leverage stone milling credentials to defend shelf placement against high-shear competitors.
United Kingdom
Meridian Foods Limited leverages organic certification to anchor premium positioning in European grocers. Food Standards Agency allergen labeling requirements align with EU frameworks while retaining national enforcement discretion. London metropolitan natural grocery chains command dual USDA Organic and Non-GMO Project verification as table stakes.
Canada
Health Canada and PMRA coordinate allergen labeling with FDA approaches, facilitating cross-border product standardization. Childcare facility nut-free policies normalize bulk purchasing in Ontario and British Columbia population corridors. Prairie province sunflower crushing capacity supplies ingredient inputs to North American manufacturers.
France
ANSM and DGCCRF enforce strict clean-label standards that favor traditional processing methods over synthetic stabilization. Mediterranean cuisine traditions sustain sesame butter distribution through ethnic grocery channels. Île-de-France metropolitan health enthusiasts drive pouch format adoption for workplace snacking occasions.
Seed Butter Market Competitive Landscape
Player mix skews toward mid-cap specialists with dedicated seed processing capabilities rather than diversified food conglomerates. Market structure exhibits moderate consolidation around branded sunflower butter distribution in North America, with fragmentation in organic and specialty seed variants. Strategic archetypes include institutional contract suppliers, clean-label premium positioned operators, and private-label co-manufacturers. Competitive moves center on dedicated facility construction for allergen segregation and dual certification pursuit for natural grocery access.
Within the institutional contract tier, SunButter LLC and The Hain Celestial Group occupy positions anchored by established retail relationships and natural foods portfolio extension. Meridian Foods Limited exemplifies the clean-label premium archetype through organic certification concentration. Among specialty seed butter operators, 88 Acres The Seed and Once Again Nut Butter Collective represent the artisan-positioned segment. These named entities serve as reference points for understanding how geographic origin and company structure correlate with strategic positioning across the category.
| Leading Market Players |
|---|
| Meridian Foods Limited |
| SunButter LLC |
| Wells Made |
| Windy City Organics |
| 88 Acres The Seed |
| JAGRMA |
| Once Again Nut Butter Collective |
| Bliss Nut Butters |
| The Hain Celestial Group |
| Others |
Value Network & Pricing Analysis
Sunflower seed butter's displacement of peanut butter in USDA-subsidized meal programs simultaneously redraws procurement geography toward Black Sea crushing corridors and compresses margin structures through commodity-linked input costs. Manufacturers face pricing power erosion when Ukrainian export routes face disruption, yet institutional volume commitments provide demand anchors that stabilize contract pricing against retail volatility.
Pricing Analysis
Stone-milling versus high-shear processing equipment generations create a pricing gap where traditional low-temperature systems command 15-25% premiums for clean-label positioning. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies by certification grade and volume scale. Cost compression in the economy tier intensifies because Black Sea sunflower oil futures directly feed seed butter input costs. Food service procurement teams exhibit lowest price sensitivity due to specification compliance mandates, while household jar purchasers show highest elasticity to shelf-price fluctuations.
Supply Chain Analysis
Port congestion at Constanța and Odesa trade lanes elevates inbound logistics costs for European organic seed processors dependent on Eastern European crushing capacity. Supply concentrates in Ukraine, Russia, and Argentina for raw sunflower seed inputs, with premium organic clusters in Austria and Slovenia. The chain draws from single-origin sunflower seed dependencies, palm oil stabilizer inputs, and flexible packaging laminate suppliers. Single-source vulnerability to Black Sea logistics chokepoints threatens margin stability. Distribution runs through institutional food service distributors, natural grocery retail networks, and direct-to-manufacturer bulk ingredient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed butter sits at an early-cycle expansion story where school nutrition procurement mandates normalize bulk purchasing as standard inventory rather than specialty substitute. USDA National School Lunch Program adoption curves provide visible penetration tailwinds across institutional channels.
For Market Incumbents: Consolidate through dedicated seed-only processing facility construction that segregates production from tree nut cross-contamination liability. Acquire stone-milling capabilities in Eastern European organic clusters to secure premium supply anchors against Black Sea logistics volatility. Vertical integration into Ukrainian sunflower seed crushing buffers margin compression from crude oil futures exposure. For New Entrants and Emerging Players: Differentiate on pouch format innovation targeting health enthusiast snacking occasions in coastal metropolitan markets where convenience store natural product penetration outpaces conventional grocery velocity. Target commercial bakery ingredient contracts as the most penetrable application segment, replacing almond paste in cookie and energy bar manufacturing lines. Pursue dual USDA Organic and Non-GMO Project verification as table stakes for natural grocery shelf placement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with dedicated seed processing capabilities over diversified food conglomerates. Long-term viability centers on institutional contract suppliers with proven school district relationships and clean-label premium operators with transparent sourcing storytelling. Watch state-level nutrition mandate fragmentation as the inflection indicator—California's stricter sodium thresholds versus Texas flexibility signals where parallel SKU portfolios become competitive moats or cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Seed-Only Facility Construction | FDA allergen segregation requirements accelerate capital deployment for school contract eligibility. |
| Dual Certification Pursuit | USDA Organic and Non-GMO Project verification opens natural grocery chains commanding price premiums. |
| Pouch Format Line Investment | Oxygen barrier laminate structures capture gym bag and desk drawer snacking occasions. |
| Commercial Bakery Ingredient Contracts | Bulk sunflower butter replaces almond paste in manufacturing lines eliminating cross-contamination protocols. |
| Stone Milling Capacity Acquisition | Traditional low-temperature grinding preserves micronutrients for clean-label positioning without synthetic stabilizers. |
Research Methodology
A spread of perspectives from food service procurement directors, clean-label brand managers, stone mill equipment operators, and organic certification auditors converged on the working assumptions driving this analysis. Primary interviews with school nutrition coordinators and commercial bakery R&D heads combined with secondary validation from USDA commodity procurement databases, FDA allergen labeling enforcement records, and Black Sea sunflower oil futures exchanges. Bottom-up volume modeling triangulated against top-down category spend estimates anchored the forecast framework.
Segmentation dimensions modeled include seed type, end-user channel, packaging format, and application across the projection horizon. CAGRs derived from historical velocity patterns in institutional procurement and retail scanner data, adjusted for state-level nutrition mandate adoption curves. Industry-specific inputs encompassed school district contract award timelines, stone mill versus high-shear equipment capacity utilization, and clean-label certification penetration rates in natural grocery channels.
Material uncertainties — Black Sea logistics disruption, FDA enforcement intensity on shared equipment facilities, and state-level sodium threshold divergence — sit outside the modeled envelope. Forecasts reflect assumptions about continued USDA National School Lunch Program sunflower butter designation and stable organic certification premiums. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Almond Protein Market