
 Self-Sealing Tire Market | 2026-2036
Self-Sealing Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sealing Tire Market Analysis
Multi-source sealant-compound procurement is broadening as tire makers reduce dependence on single specialty-chemical suppliers. Continental AG leverages captive polymer research facilities to control viscosity-grade development for its ContiSeal line. Michelin anchors European supply through integrated elastomer blending operations in Clermont-Ferrand. Bridgestone competes via geographic diversification of sealant-layer production across Japan and North American plants.
A self-sealing tire incorporates an inner lining of viscoelastic polymer compound, typically 3-5 millimeters thick, that flows into puncture channels under internal pressure to maintain inflation without external repair. The technology serves commercial and consumer applications where mobility continuation outweighs the cost premium over conventional tires. Passenger Cars occupies the largest volume position due to OEM fitment on premium electric-vehicle platforms, while Fleet Operators generates the fastest value expansion as total-cost-of-ownership calculations favor downtime reduction. Prevention Technology leads the technology split because pre-integrated sealant layers avoid the weight and balance compromises of aftermarket add-on systems.
EPA fuel-economy standards and NHTSA tire-safety ratings in the United States shape OEM specification requirements, compelling sealant-layer integration that preserves rolling-resistance targets. The EU Green Deal's extended producer-responsibility provisions and REACH chemical-compliance protocols constrain sealant-formulation choices for European manufacturers. Stakeholders must monitor evolving battery-electric-vehicle weight specifications, as heavier platforms intensify load-index demands that interact directly with sealant-layer durability thresholds.
Market Dynamics
Commercial fleet operators are forcing sealant-layer integration into OEM specification sheets as total-cost-of-ownership models now weight downtime costs above upfront tire premiums, compressing traditional replacement cycles and elevating factory-fit sealant systems over aftermarket alternatives.
Growth Catalysts
- EU Green Deal tire-labeling mandates:Rolling-resistance thresholds for passenger-car OEM fitment are accelerating demand for low-drag sealant formulations that maintain efficiency ratings without sacrificing puncture protection.
- Electric-vehicle platform weight premiums:Heavier battery architectures are intensifying load-index requirements that sealant layers must satisfy, pulling next-generation compounds into premium vehicle segments.
- Fleet operator uptime prioritization:Logistics contracts with penalty clauses for delivery delays are embedding sealant-specified tires into standard procurement terms for commercial vehicle pools.
Market Restraints
- Specialty-polymer supply concentration:High-viscosity sealant base stocks concentrate among a narrow tier of European and Japanese chemical processors, creating input vulnerability during feedstock disruptions.
- REACH chemical-compliance friction:ECHA substance restrictions on certain plasticizers and adhesion promoters are forcing reformulation cycles that extend development timelines for European-market products.
- Aftermarket plug-kit substitution:Low-cost external repair solutions retain cost-sensitive consumer segments, particularly in markets with limited roadside-service infrastructure.
Strategic Opportunities
- Underpenetrated commercial-motorcycle segments:Two-wheel delivery fleets in Southeast Asian urban corridors represent untapped volume for lightweight sealant-layer adaptations.
- Autonomous-vehicle redundancy requirements:Self-driving truck specifications are anticipated to mandate dual puncture-mitigation systems, creating specification pull for integrated sealant technology.
- Extended producer-responsibility incentives:EU circular-economy packaging for tire recycling is creating preferential treatment for sealant-integrated tires in end-of-life processing contracts.
Industry Challenges
- Compound rheology talent scarcity:Formulation chemists with simultaneous expertise in tire elastomer processing and sealant viscosity-grade calibration remain concentrated among a handful of research clusters.
- OEM homologation timeline compression:Accelerated vehicle-development cycles are squeezing sealant-layer validation protocols, forcing suppliers to parallel-track testing phases that previously ran sequentially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sealing Tire Market |
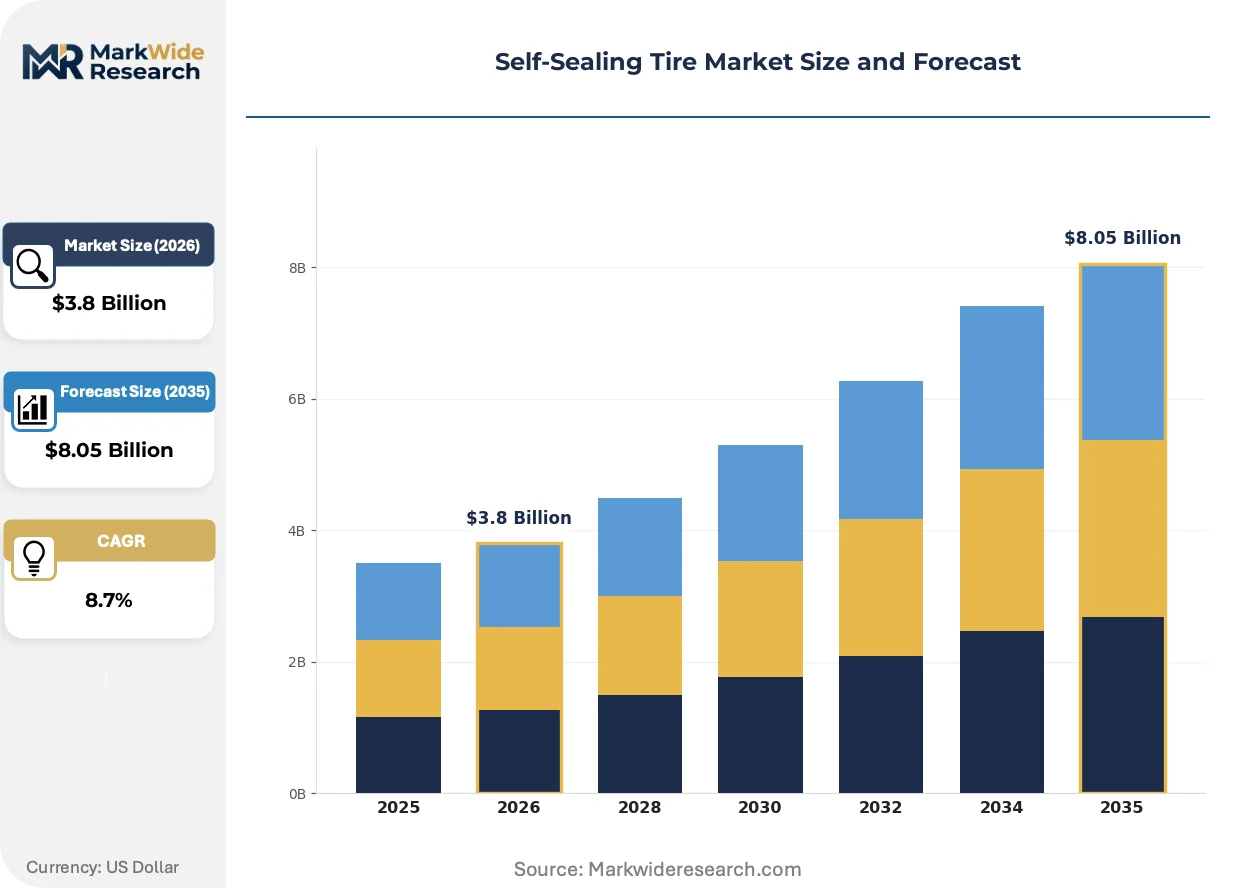
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Light Trucks, Heavy Trucks, Motorcycles Technology: Prevention Technology, Repair Technology, Adaptive Technology, Inflation Technology End User: OEMs, Fleet Operators, Retail Customers, Aftermarket Providers Distribution Channel: Online Retail, Specialty Stores, Tire Dealers, Direct Sales |
| Companies Covered | Continental AG, Hankook Tire & Technology Co., Ltd., Michelin, Kumho Tire Co., Inc., Yokohama Rubber Company, Bridgestone Corporation, Pirelli & C. S.p.A., Toyo Tire Corporation, Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sealing Tire Market Emerging Trajectories
Material science advances and regulatory efficiency mandates are converging to redefine how sealant functionality is engineered into tire architectures, shifting competitive advantage toward suppliers who control both compound formulation and layer-integration processes.
Biobased sealant polymers derived from guayule rubber and dandelion-root latex are integrating into premium tire lines as manufacturers respond to EU-origin requirements and Scope 3 emissions accounting. Passenger-car OEMs in Germany and France are adopting these compounds fastest, with sealant-layer suppliers capturing carbon-credit benefits that offset formulation cost premiums. The technology is integrating sustainability credentials into specification battles where rolling-resistance and puncture-resistance were previously the sole purchase criteria.
NHTSA tire-safety ratings and EPA fuel-economy standards are tightening in parallel, forcing sealant-layer designers to optimize for dual performance vectors that previously traded off against each other. The regulatory compression is eliminating margin for standalone efficiency or safety solutions, favoring integrated architectures that satisfy both frameworks simultaneously. Commercial fleet specifications in the United States are responding fastest, with sealant-integrated tires capturing share in Class 3-8 vehicle segments.
Direct procurement relationships between large fleet operators and tire manufacturers are displacing traditional distribution intermediaries, with sealant-layer customization becoming a negotiation lever in volume contracts. Fleet engineering departments are specifying compound viscosity grades and layer thicknesses previously reserved for OEM development programs. This channel compression is most visible in German and Dutch logistics corridors, where integrated operators are consolidating tire spend across thousands of vehicles.
Self-Sealing Tire Market Segmentation
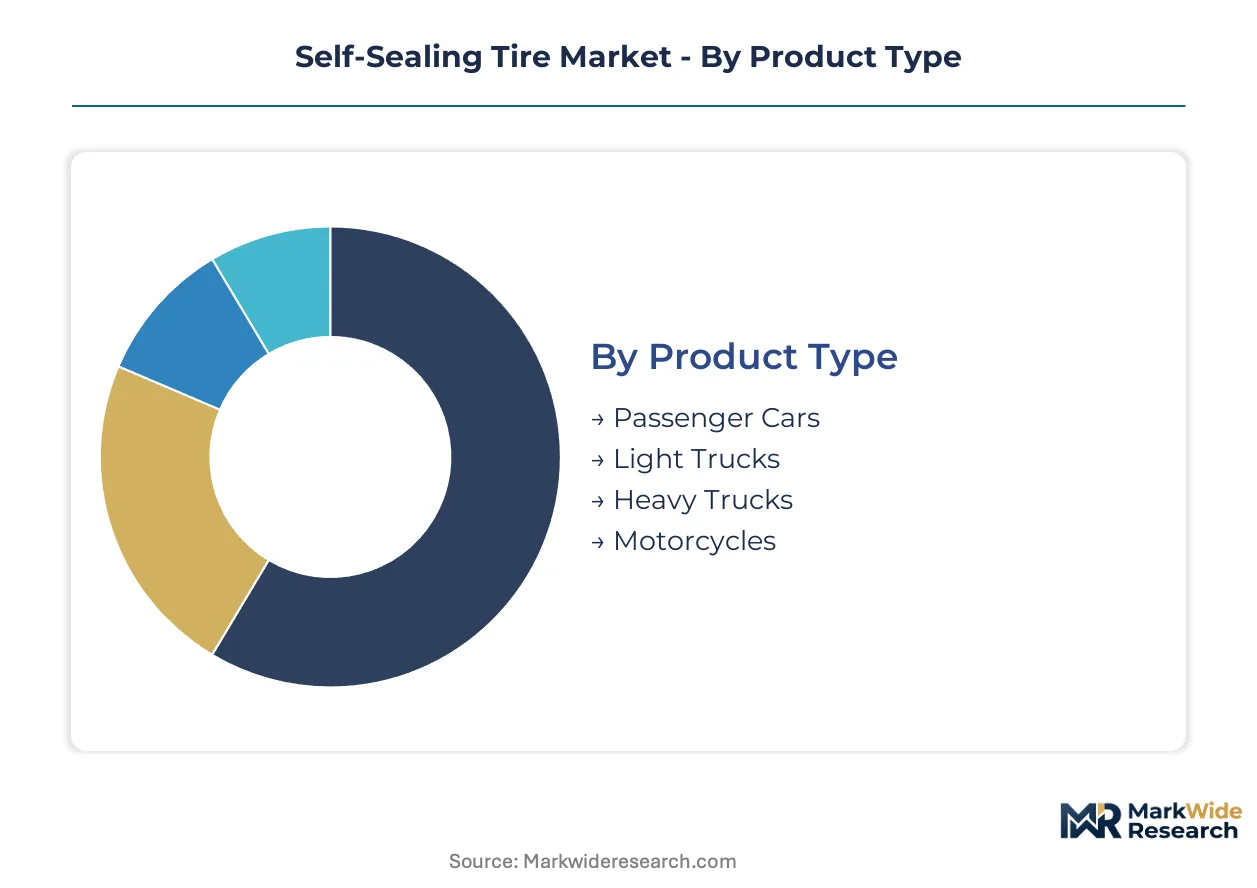
Segmentation in self-sealing tires reveals how specification requirements diverge across mobility platforms, with OEM integration timelines and fleet uptime economics driving radically different compound performance priorities. Understanding these divides exposes where formulation R&D investments concentrate versus where channel economics dominate purchasing decisions.
Product Type:
Purchase decisions here hinge on load-index requirements and downtime cost exposure, with heavier platforms demanding thicker sealant layers that trade off rolling efficiency.
- Passenger Cars:OEM fitment on premium electric-vehicle platforms specifies 3-4 millimeter sealant layers balancing puncture protection with range preservation. German and French manufacturers lead factory integration, driven by EU tire-labeling efficiency mandates.
- Light Trucks:Commercial delivery fleets in urban corridors specify these for mixed-route durability where curb-impact punctures dominate failure modes. Last-mile logistics operators in the Netherlands prioritize this segment for reduced roadside assistance dependency.
- Heavy Trucks:Long-haul operators accept weight premiums for sealant layers that eliminate tire-related roadside stops across transcontinental routes.
- Motorcycles:Two-wheel delivery fleets in Southeast Asian urban markets represent emerging demand for lightweight sealant adaptations.
Passenger Cars leads on scale; Fleet Operators drives specification pull in Light Trucks and Heavy Trucks.
Technology:
Technology selection reflects a maturity gradient, with integrated factory solutions commanding premium positioning against aftermarket alternatives that sacrifice performance for retrofit accessibility.
- Prevention Technology:Pre-integrated viscoelastic polymer layers applied during tire manufacture eliminate balance and weight compromises of add-on systems. OEMs in Germany and the United States specify this exclusively for new vehicle platforms.
- Repair Technology:Post-puncture sealant injection systems serve cost-sensitive aftermarket segments where mobility continuation outweighs factory integration benefits.
- Adaptive Technology:Smart sealant formulations responding to pressure differentials remain in validation phases with autonomous-vehicle developers.
- Inflation Technology:Pressure-maintenance systems with auxiliary sealant backup serve specialized military and emergency vehicle applications.
Prevention Technology dominates current revenue; Adaptive Technology holds steepest expansion trajectory contingent on autonomous-vehicle homologation timelines.
End User:
Procurement authority concentration determines whether sealant specifications emerge from engineering departments or fleet financial controllers.
- OEMs:Vehicle manufacturers integrate sealant layers during platform development, with NHTSA safety ratings and EPA fuel-economy standards dictating rolling-resistance thresholds. German premium OEMs specify proprietary viscosity grades through direct compound development partnerships.
- Fleet Operators:Logistics companies with penalty-clause contracts embed sealant specifications into standard procurement terms, compressing replacement cycles toward factory-fit systems. Dutch and German integrated operators consolidate tire spend across thousands of vehicles.
- Retail Customers:Individual purchasers respond to warranty length and roadside-assistance bundling rather than technical sealant specifications.
- Aftermarket Providers:Independent installers compete on installation speed and price, rarely influencing compound formulation decisions.
Fleet Operators commands fastest value expansion; OEMs anchors technology development investment.
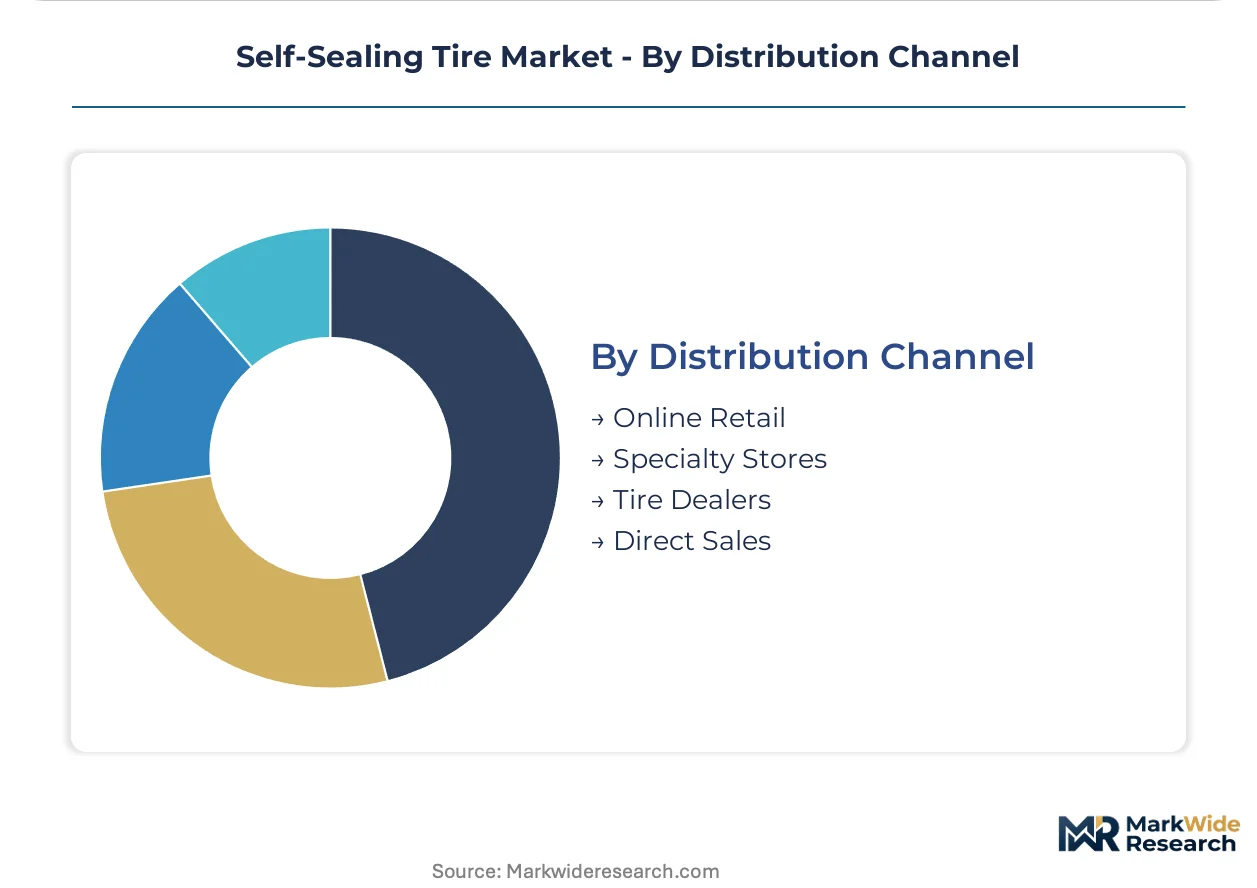
Distribution Channel:
Channel selection reflects customer technical sophistication and urgency requirements, with specification-heavy buyers bypassing intermediaries entirely.
- Online Retail:E-commerce platforms capture price-sensitive replacement demand where standardized specifications suffice. German consumers lead European online tire purchasing penetration.
- Specialty Stores:Performance-focused retailers advise on sealant-layer compatibility with specific vehicle platforms and driving profiles.
- Tire Dealers:Independent dealer networks handle bulk of replacement volume, with installation service bundling outweighing product differentiation.
- Direct Sales:Large fleet operators negotiate customized viscosity grades and layer thicknesses directly with manufacturers, displacing traditional distribution tiers.
Tire Dealers retains volume leadership; Direct Sales gains share fastest as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling sealant-layer production toward jurisdictions with REACH-equivalent chemical frameworks but lower operational overhead, while OEM contract concentration keeps R&D anchored in premium manufacturing clusters. Tier-1 suppliers now operate dual-track sourcing: formulation development in high-compliance zones, volume manufacturing in cost-optimized locations.
Germany
Fleet operator consolidation across the Dutch-German logistics corridor is driving specification pull for heavy-truck sealant systems. KBA type-approval requirements for rolling-resistance labeling enforce strict efficiency thresholds on OEM fitments. Continental AG anchors production in Hanover, where captive polymer research facilities supply both domestic vehicle contracts and export channels into France and the Benelux.
United States
Class 3-8 commercial fleet operators are embedding sealant specifications into procurement terms with penalty clauses for tire-related downtime. NHTSA tire-safety ratings and EPA fuel-economy standards operate in parallel, forcing sealant-layer designs that satisfy dual performance vectors. Manufacturing concentration in the Southeast serves both domestic OEM contracts and cross-border supply into Mexican assembly plants.
Japan
Domestic OEMs specify proprietary viscosity grades for electric-vehicle platforms, pulling advanced sealant formulations into premium passenger-car segments. METI energy-efficiency guidelines for automotive components create preferential treatment for low-rolling-resistance tire systems. Yokohama and Tokyo-based research clusters coordinate compound development with synthetic rubber suppliers in the Chubu industrial belt.
China
Battery-electric-vehicle weight premiums are intensifying load-index requirements that sealant layers must satisfy for domestic OEM platforms. MIIT new-energy vehicle certification protocols incorporate tire efficiency metrics that favor integrated sealant architectures. Production gravity concentrates in the Yangtze River Delta, where tire manufacturers serve both local EV brands and export assembly operations.
South Korea
Hankook Tire anchors sealant-layer development in Daejeon-Sejong, with formulation R&D tied to domestic OEM electric-vehicle programs. MFDS chemical-substance management frameworks constrain plasticizer selection for sealant compounds, extending reformulation timelines. The Busan-Ulsan manufacturing corridor supplies both Korean vehicle exports and aftermarket replacement demand across Southeast Asian markets.
Self-Sealing Tire Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aftermarket repair-technology niches and regional private-label contracts. The vendor base concentrates among integrated tire manufacturers with captive polymer blending capabilities, while specialty-chemical suppliers compete for sealant-base-stock contracts. Three archetypes dominate: vertically integrated multinationals controlling formulation-to-distribution pipelines; regional tire makers licensing sealant-layer technology from compound specialists; and chemical processors supplying viscosity-grade base stocks to multiple tire brands. Competitive moves center on backward integration into sealant-polymer production and direct procurement relationships with large fleet operators that displace traditional distribution tiers.
Among the integrated multinationals, Continental AG exemplifies the captive-research archetype through in-house polymer facilities, while Michelin occupies a position emphasizing European supply-chain control. Bridgestone represents geographic diversification of manufacturing footprint across multiple regulatory jurisdictions. These three anchor the premium-tier competitive vector where formulation expertise and OEM homologation timelines constitute primary barriers.
| Leading Market Players |
|---|
| Continental AG |
| Hankook Tire & Technology Co., Ltd. |
| Michelin |
| Kumho Tire Co., Inc. |
| Yokohama Rubber Company |
| Bridgestone Corporation |
| Pirelli & C. S.p.A. |
| Toyo Tire Corporation |
| Goodyear Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with simultaneous expertise in tire elastomer processing and sealant viscosity-grade calibration concentrate in the Chubu industrial belt and Clermont-Ferrand research clusters, where labor-cost differentials between Japanese and French technical centers widen pricing-tier spreads between premium OEM-specified compounds and standard fleet-grade alternatives.
Pricing Analysis
Distributor margin compression in European aftermarket channels is forcing tire manufacturers toward direct fleet contracts that eliminate intermediary markups. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified viscosity grades from fleet-negotiated volumes and price-sensitive retail replacement demand. Pricing pressure stems from REACH reformulation cycles extending European development timelines while Asian manufacturers capture standard-tier volume with faster homologation pathways. Retail customers exhibit highest price sensitivity, while integrated fleet operators with penalty-clause contracts accept premium positioning for uptime guarantees.
Supply Chain Analysis
High-viscosity sealant base stocks rest on a narrow tier of European and Japanese chemical processors in Germany, Japan, and Belgium, creating concentrated dependency for tire manufacturers lacking captive polymer facilities. Synthetic rubber feedstocks, specialty plasticizers, and adhesion promoters constitute critical input categories where ECHA substance restrictions constrain formulation flexibility. Single-source vulnerability in butadiene-derived polymer supply chains exposes producers to petrochemical feedstock disruption during refinery maintenance cycles. Distribution runs through direct procurement relationships with large fleet operators that displace traditional tire dealer intermediaries in German and Dutch logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH-equivalent chemical compliance in Western Europe imposes formulation cost premiums that Southeast Asian manufacturing jurisdictions avoid through less restrictive substance management frameworks.
For Market Incumbents: Cement captive control over sealant-polymer production through backward integration into viscosity-grade base stock manufacturing, eliminating dependency on concentrated Japanese and European chemical processors. Defend specification authority in German premium OEM channels by accelerating homologation timelines that outpace emerging Asian compound suppliers seeking European market entry. For New Entrants and Emerging Players: Begin with lightweight sealant-layer adaptations for two-wheel delivery fleets in Vietnamese and Indonesian urban corridors, where underpenetrated commercial-motorcycle segments lack established supplier relationships. Capture white-space volume through direct procurement pitches to Southeast Asian logistics operators before integrated multinationals localize production for these platforms. For Investors and Strategic Acquirers: Specialty chemical processors with tire-industry formulation expertise are the most active acquirer in this space, consolidating viscosity-grade development capabilities that OEMs increasingly require for platform-specific sealant integration. Long-term viability hinges on positioning against autonomous-vehicle homologation timelines where dual puncture-mitigation specifications will reshape competitive tiers. Watch for fleet operator consolidation announcements in the Dutch-German corridor as volume-concentration inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive viscosity-grade development eliminates dependency on concentrated Japanese and European chemical processors. |
| Direct Fleet Procurement Relationships | Large logistics operators in Germany and the Netherlands now negotiate customized sealant specifications directly with manufacturers. |
| Biobased Sealant Polymer Development | Guayule rubber and dandelion-root latex formulations capture EU-origin carbon credits for German and French OEM platforms. |
| REACH Compliance Reformulation Investment | ECHA substance restrictions on plasticizers force development timeline extensions that favor producers with captive research facilities. |
| Autonomous-Vehicle Homologation Partnerships | Self-driving truck specifications anticipated to mandate dual puncture-mitigation systems creating specification pull for integrated sealant technology. |
Methodological Framework
Bottom-up fleet operator and OEM procurement modeling reconciled against top-down sealant-layer production capacity tracking forms the analytical core of this study. Primary interviews with tire platform engineers, fleet procurement directors, specialty chemical R&D leads, and aftermarket distribution managers combined with secondary validation from KBA type-approval databases, EPA fuel-economy certification filings, ECHA substance restriction registers, and customs trade data for synthetic rubber feedstocks. Triangulation between demand-side contract analysis and supply-side manufacturing footprint mapping ensures cross-verification of volume and value estimates.
Historical trendline analysis of sealant-layer integration rates across passenger-car, light-truck, and heavy-truck platforms informs the projection framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, sealant technology type, end-user procurement authority, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to penetration-rate assumptions, with specific inputs for electric-vehicle weight-premium effects on load-index requirements and EU tire-labeling efficiency mandate compliance thresholds across the analysis window.
Several conditions sit outside the modeled scope, including potential REACH substance list expansions, autonomous-vehicle regulatory acceleration or delays, and feedstock disruption events in butadiene supply chains. Forecasts reflect assumptions about continued fleet operator consolidation and OEM platform development cycle stability. A small set of named triggers warrants ongoing watch: ECHA plasticizer restriction amendments, NHTSA tire-safety rating recalibrations, and battery-electric-vehicle platform weight specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Automotive Racing Slicks Tire Market