
 Ground Support Equipment Tires Market | 2026-2036
Ground Support Equipment Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Support Equipment Tires Market Analytics
The capital-intensity gap between integrated tire manufacturers and regional assemblers is collapsing as automated curing and testing investments become table stakes. Michelin leverages captive rubber compounding facilities across three continents to sustain margin structure. Trelleborg AB specializes in solid tire formulations for pushback tractors, anchoring its position in high-cycle airport applications. Titan International competes through aftermarket distribution density, controlling replacement channels at regional hubs.
Ground support equipment tires are heavy-duty pneumatic or non-pneumatic structures engineered for aircraft tugs, baggage loaders, and jet bridges, typically rated for loads exceeding 15,000 kg and speeds below 40 km/h. Radial tires dominate commercial aviation procurement due to heat dissipation and retreadability, while solid tires capture maintenance-intensive military and cargo handling segments where puncture elimination justifies premium pricing. Foam-filled tires occupy a narrowing niche in legacy equipment retrofit programs. Airlines and ground handling companies represent the primary end-user demand pool, with military procurement subject to distinct durability specifications.
The U.S. FAA mandates tire pressure monitoring and tread-depth thresholds for all GSE operating on commercial ramps, while EU REACH restrictions on aromatic oils in rubber compounding force reformulation investments. China's GB standards for industrial tires, administered by SAMR, impose load-rating certifications that condition market access. Stakeholders must monitor regulatory divergence between FAA durability protocols and emerging EU Ecodesign requirements for material traceability.
Market Dynamics
Automated tire curing systems are collapsing the capital barrier between integrated manufacturers and regional assemblers, redistributing competitive advantage toward production flexibility rather than scale alone.
Growth Catalysts
- EU REACH aromatic oil restrictions:Reformulation mandates are accelerating bio-based rubber compound adoption, creating first-mover advantages for suppliers with captive R&D facilities.
- Air cargo volume expansion:Ground handling companies at Dubai International and Singapore Changi are expanding tire replacement cycles to match 24/7 cargo throughput requirements.
- Solid tire technology maturation:Non-pneumatic formulations now match radial heat dissipation profiles for pushback tractors, opening military procurement segments previously closed to solid constructions.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to weather-driven input cost swings exceeding 30% annually.
- FAA tire pressure monitoring mandates:Retrofit requirements for legacy GSE fleets impose certification costs that freeze replacement demand at smaller regional airports.
- Retreadability limitations in solid tires:Non-pneumatic constructions cannot extend service life through recap processes, forcing full replacement purchases that compress maintenance budgets.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals at Navi Mumbai and Jewar are specifying 10-year tire lifecycle contracts, locking in supplier relationships before competition intensifies.
- RFID-enabled tire tracking:Embedded sensors meeting FAA data logging requirements are creating recurring revenue streams through predictive maintenance subscriptions.
- China GB standard alignment:SAMR load-rating certifications for industrial tires are conditioning market access, favoring early entrants with established testing partnerships.
Industry Challenges
- Compounder talent scarcity:Formulation chemists with aromatic-free rubber expertise command 40% salary premiums, constraining R&D expansion at mid-tier manufacturers.
- Multi-jurisdiction certification lag:Simultaneous FAA, EASA, and CAAC approval timelines extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Support Equipment Tires Market |
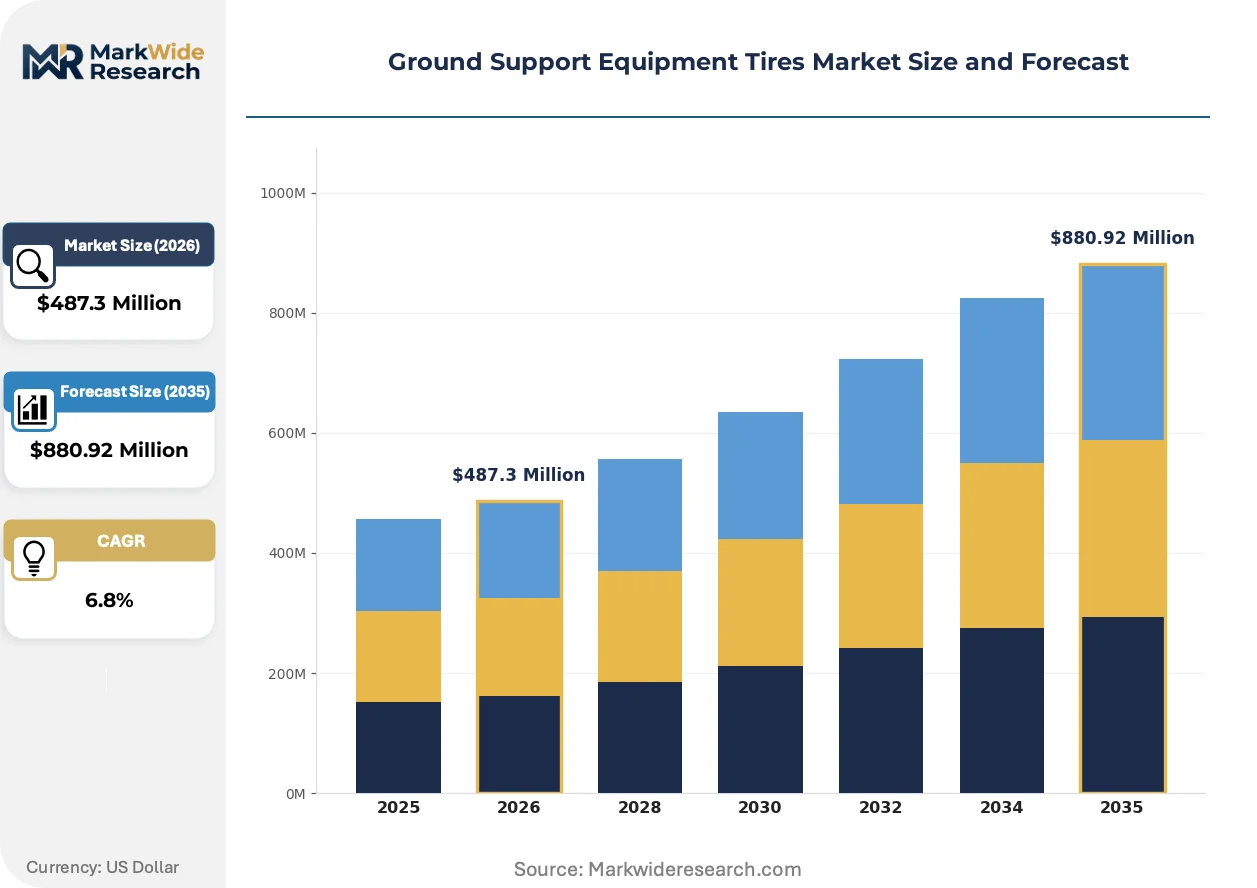
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Solid Tires, Foam-Filled Tires Application: Airports, Cargo Handling, Aircraft Maintenance, Ground Services End User: Airlines, Ground Handling Companies, Military, Cargo Service Providers Material: Rubber, Synthetic Compounds, Metal, Others |
| Companies Covered | Michelin, Continental AG, Trelleborg AB, Bridgestone Corporation, The Goodyear Tire and Rubber Company, Yokohama Rubber Company, Balkrishna Industries Limited, Titan International, MAXAM Tire International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Support Equipment Tires Market Evolving Landscape
Digital tire monitoring systems are converging with predictive maintenance platforms, transforming GSE tires from commodity consumables into data-generating assets that anchor long-term service contracts.
Advanced silica-silane coupling agents are displacing carbon black as the primary reinforcing filler in radial GSE compounds. Major ground handling operators at Heathrow and Frankfurt airports are specifying these formulations for high-cycle baggage tractor fleets. The shift is compressing retread intervals by 15% while extending casing life, forcing compounders to restructure pricing around total cost of ownership metrics rather than upfront unit cost.
EU Ecodesign requirements for material traceability are mandating blockchain-linked supply chain documentation for rubber sourcing. Tire manufacturers serving European airports must now certify plantation origin and processing facility compliance. The regulation most impacts suppliers to Amsterdam Schiphol and Paris Charles de Gaulle, where procurement departments have embedded traceability scoring into vendor scorecards ahead of formal deadlines.
Ground handling companies are consolidating tire purchasing through integrated fleet management contracts that bundle installation, pressure monitoring, and replacement scheduling. This model is displacing spot procurement through regional distributors at major hub airports. The transition is most advanced in the United States, where American Airlines and Delta Air Lines have centralized GSE tire specification authority at their Atlanta and Dallas operational headquarters.
Ground Support Equipment Tires Market Segmentation
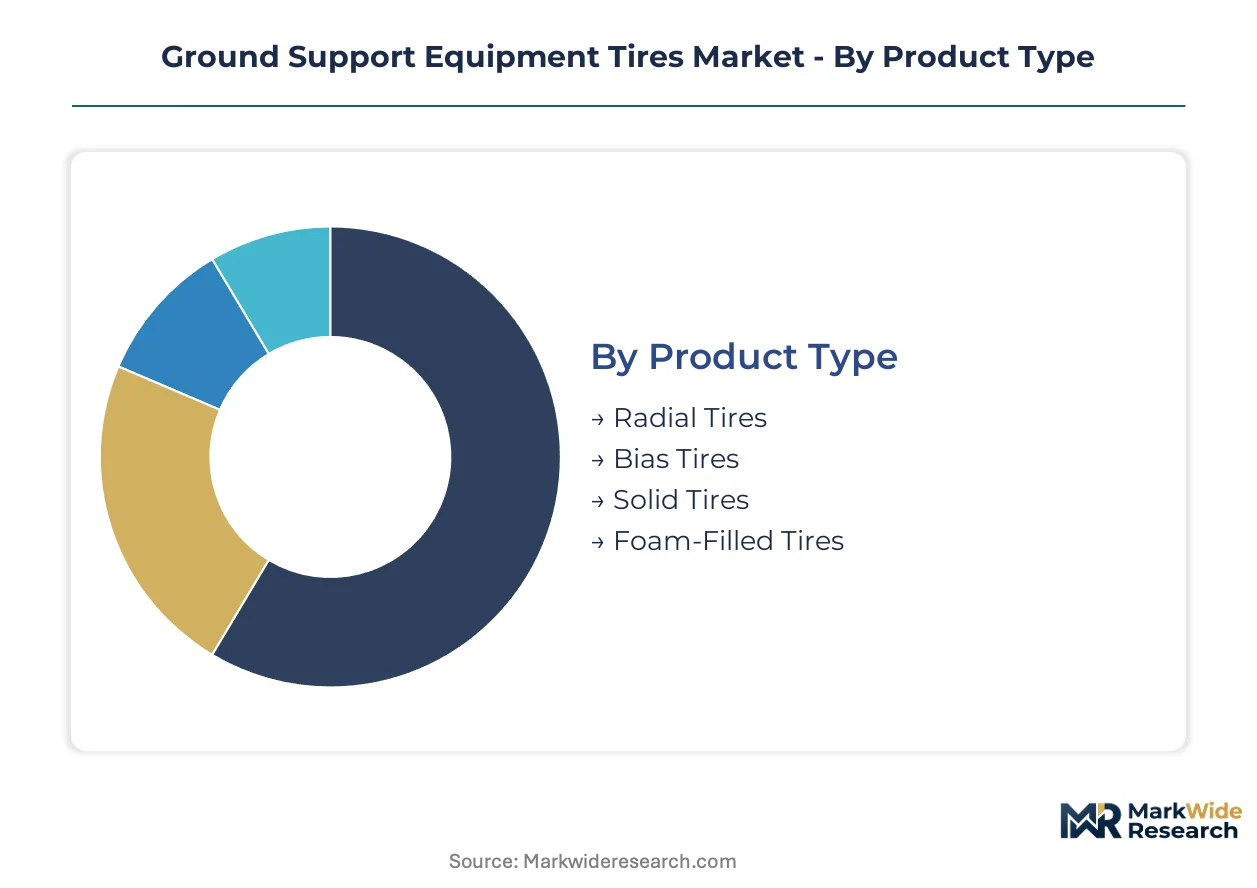
Segmentation in the Ground Support Equipment Tires Market reveals how regulatory mandates and operational intensity reshape procurement priorities across tire constructions and user categories. Understanding these divisions exposes where specification authority concentrates and which material innovations command premium positioning.
Product Type:
FAA tire pressure monitoring mandates and EU REACH aromatic oil restrictions create divergent compliance burdens across pneumatic and non-pneumatic constructions, forcing distinct reformulation strategies.
- Radial Tires:Steel-belted radial constructions with optimized heat dissipation profiles dominate commercial aviation procurement for high-speed baggage tractors and pushback equipment. Demand concentrates at Heathrow, Frankfurt, and Singapore Changi where retreadability programs extend casing life across 24/7 operations. Heat management specifications from the FAA and EASA favor these constructions for continuous-duty applications.
- Solid Tires:Non-pneumatic rubber compounds eliminate puncture risk entirely, anchoring military and heavy cargo segments where downtime carries operational penalties. Dubai International and Memphis cargo hubs specify solid constructions for container loaders handling maximum rated loads. Recent formulation advances now match radial heat dissipation, opening previously restricted procurement categories.
- Bias Tires:Cross-ply nylon constructions serve legacy equipment fleets at regional airports with lower duty cycles and reduced speed requirements.
- Foam-Filled Tires:Polyurethane-injected pneumatic casings occupy narrowing retrofit niches where full solid conversion costs exceed operational budgets.
Radial tires handle the majority of throughput; solid tires are expanding most quickly on share as heat-dissipation formulations mature.
Application:
Operational tempo and surface exposure intensity separate specification tiers, with 24/7 cargo environments demanding distinct durability certifications from intermittent maintenance operations.
- Cargo Handling:High-cycle container loaders and dollies at Memphis, Louisville, and Leipzig hubs require reinforced sidewall constructions rated for continuous loading. Ground handling companies here negotiate lifecycle contracts tied to guaranteed uptime metrics. The segment absorbs premium solid tire volumes where puncture elimination justifies unit cost premiums.
- Airports:Passenger terminal GSE including jet bridges and passenger stairs operate on defined schedules with predictable replacement windows. Procurement at Atlanta, Dallas-Fort Worth, and Denver International centralizes through airline operational headquarters, consolidating specification authority away from regional distributors.
- Aircraft Maintenance:Hangar-based tugs and maintenance platforms operate at lower speeds with reduced load variability, permitting bias tire specifications in cost-sensitive operations.
- Ground Services:De-icing trucks and utility vehicles face seasonal demand spikes and chemical exposure, requiring specialized compound formulations.
Cargo handling commands the steepest expansion trajectory; airports retain the largest installed base requiring replacement.
End User:
Procurement centralization and specification authority vary sharply, with airline fleet management departments increasingly dictating terms across ground handling subcontractors.
- Ground Handling Companies:Swissport, dnata, and Menzies Aviation operate under performance-based contracts that penalize equipment downtime, driving specification toward solid tire and premium radial categories. These entities consolidate purchasing through integrated fleet management agreements bundling installation, monitoring, and replacement scheduling.
- Airlines:American Airlines, Delta Air Lines, and Lufthansa Group have centralized GSE tire authority at operational headquarters, displacing spot procurement through regional distributors. Their specification power extends through subcontractor agreements, reshaping competitive dynamics for tire suppliers.
- Military:Durability specifications from the U.S. Department of Defense and NATO procurement offices emphasize puncture resistance and field repairability over retread economics.
- Cargo Service Providers:FedEx, UPS, and DHL ground operations specify independently, often prioritizing total cost of ownership metrics over upfront unit pricing.
Ground handling companies absorb the highest volume; airlines are gaining specification authority fastest.
Material:
EU REACH restrictions on aromatic oils and emerging blockchain traceability mandates are restructuring compound supply chains and reformulation investments.
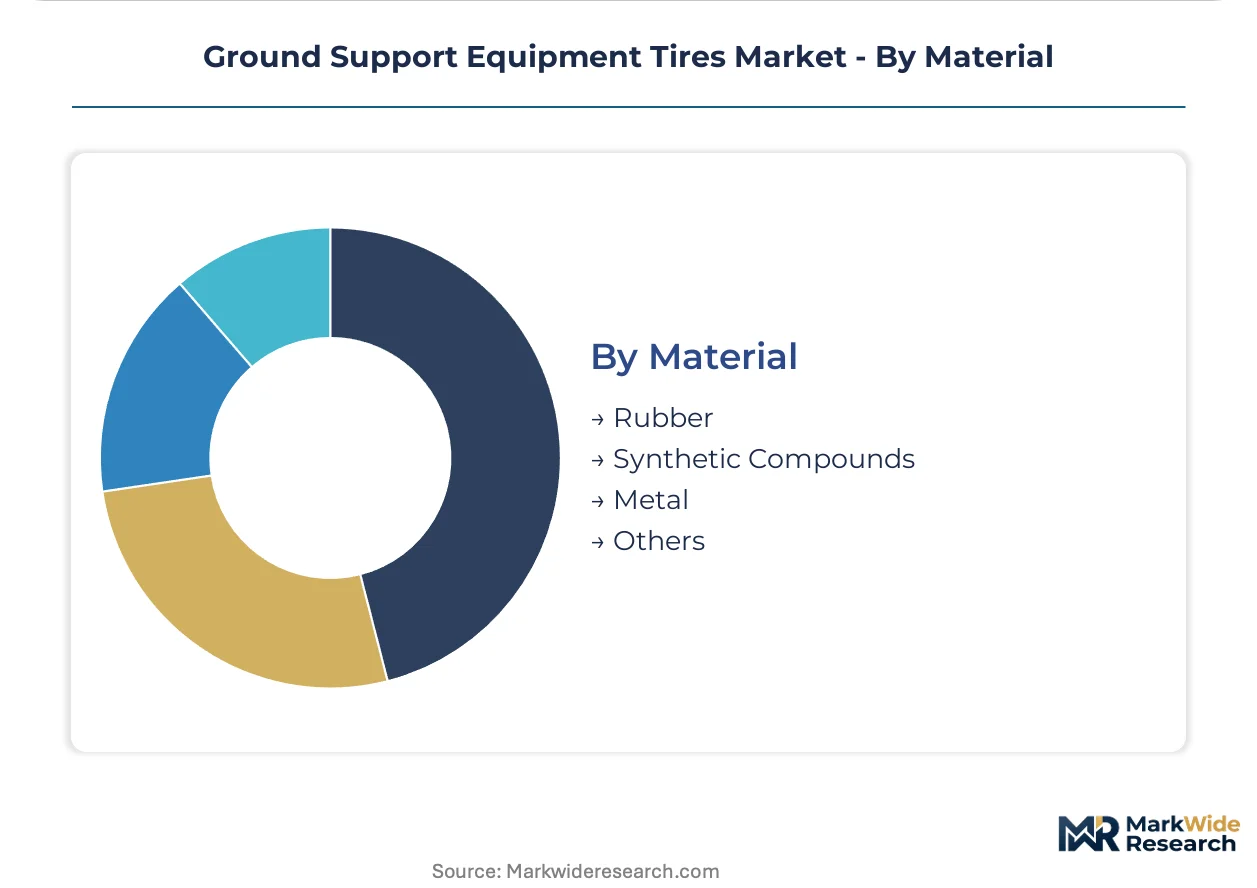
- Rubber:Natural rubber from Thai and Indonesian plantations remains the primary elastomer base, now subject to EU Ecodesign documentation requirements for plantation origin certification. Compounders with captive sourcing partnerships command margin advantages as traceability scoring enters vendor evaluations at Amsterdam Schiphol and Paris Charles de Gaulle.
- Synthetic Compounds:Advanced silica-silane coupling agents displace carbon black reinforcing fillers at Heathrow and Frankfurt, compressing retread intervals while extending casing life. Bio-based alternatives to aromatic oil plasticizers are accelerating under REACH compliance timelines.
- Metal:Steel bead wires and belt plies provide structural integrity for radial constructions, with sourcing concentrated among integrated tire manufacturers.
- Others:Aramid fiber reinforcements and specialized curing agents serve niche high-load applications.
Rubber maintains foundational volume; synthetic compounds are climbing fastest as reformulation investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground handling operators in India and Southeast Asia exhibit acute price sensitivity, squeezing margins on standard radial constructions, while cargo hubs in Germany and the UAE absorb premium solid tire pricing without volume elasticity.
United States
FAA tire pressure monitoring mandates and tread-depth thresholds reshape procurement at Atlanta Hartsfield-Jackson and Dallas-Fort Worth, where American Airlines and Delta Air Lines have centralized specification authority. The FAA mandates retrofit certification costs that freeze replacement demand at smaller regional airports. Memphis and Louisville cargo hubs drive premium solid tire volumes for FedEx and UPS ground operations.
Germany
EU REACH aromatic oil restrictions force compound reformulation investments at Frankfurt and Munich airports, where Lufthansa Group procurement departments specify advanced silica-silane radial constructions. The ECHA compliance timeline accelerates bio-based rubber adoption among suppliers serving Berlin Brandenburg. Trelleborg AB anchors solid tire supply relationships at Leipzig cargo hub through integrated fleet management contracts.
China
SAMR GB standards for industrial tires impose load-rating certifications that condition market access for radial and solid constructions. Beijing Capital and Shanghai Pudong airport infrastructure investment continues at pace, concentrating demand among state-owned ground handling entities. The dual carbon goals pressure compounders toward traceable natural rubber sourcing from Hainan and Yunnan plantations.
India
Airport privatization at Navi Mumbai and Jewar specifies decade-long tire lifecycle contracts, locking supplier relationships before competition intensifies. The BIS industrial tire standards create certification bottlenecks for imported radial constructions. Ground handling companies at Delhi Indira Gandhi International negotiate performance-based contracts penalizing equipment downtime, favoring solid tire specifications.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International cargo expansion drives 24/7 tire replacement cycles matching air freight throughput requirements. The country's national aviation regulator enforces durability specifications aligned with EASA frameworks. Dnata operations consolidate purchasing through bundled installation, pressure monitoring, and replacement scheduling agreements at Al Maktoum cargo hub.
Ground Support Equipment Tires Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive rubber compounding facilities and automated curing systems now table stakes rather than differentiators. The capital-intensity gap between integrated manufacturers and regional assemblers has collapsed, redistributing competitive advantage toward production flexibility and regulatory compliance speed. Two strategic archetypes dominate: integrated compounders with multi-continent sourcing control, and application specialists anchoring high-cycle airport segments. Competitive moves concentrate on backward integration into traceable natural rubber supply chains and predictive maintenance platform partnerships.
Within the integrated compounder tier, Michelin and Continental AG represent archetypes of multi-continent production footprint and captive R&D facility deployment. Trelleborg AB occupies a specialist position exemplifying solid tire formulation focus for pushback tractor applications. These three anchors demonstrate how competitive positioning now depends on regulatory compliance speed—REACH reformulation, FAA certification timelines, and SAMR load-rating partnerships—rather than scale economies alone.
| Leading Market Players |
|---|
| Michelin |
| Continental AG |
| Trelleborg AB |
| Bridgestone Corporation |
| The Goodyear Tire and Rubber Company |
| Yokohama Rubber Company |
| Balkrishna Industries Limited |
| Titan International |
| MAXAM Tire International Ltd. |
| Others |
Value Network & Pricing Analysis
Automated curing system investments exceeding $5 million per line have collapsed minimum efficient scale thresholds, concentrating supply among compounders with multi-continent rubber sourcing control while compressing price floors for regional assemblers lacking captive plantation partnerships.
Pricing Analysis
After-sales service bundling drives lifetime value, with integrated fleet management contracts at Atlanta and Dallas-Fort Worth capturing installation, pressure monitoring, and predictive maintenance subscriptions. Three-tier pricing structure across premium certified-radial, standard retreadable-bias, and economy solid constructions differentiates on REACH compliance speed and FAA certification status. Cost compression in standard radial tiers intensifies as Indian airport privatization squeezes margin structures. Ground handling companies at Dubai International show lowest price sensitivity, absorbing premium solid tire pricing for guaranteed uptime metrics.
Supply Chain Analysis
Strategic stockpiling of natural rubber dominates compounder behavior, with 90-day inventory buffers insulating against Thai and Indonesian weather-driven supply interruptions. Thailand, Indonesia, and Vietnam anchor raw elastomer sourcing, while steel bead wire draws from Chinese and German metallurgical specialists. Single-source vulnerability in aromatic-free plasticizer formulations—now mandated under EU REACH—threatens reformulation timelines. Distribution runs through integrated fleet management contracts at major hub airports, displacing spot procurement through regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with aromatic-free rubber expertise command 40% salary premiums, constraining R&D expansion and consolidating competitive advantage among compounders with established training pipelines and university partnerships.
For Market Incumbents: Secure captive rubber sourcing partnerships across Thai and Indonesian plantations before EU Ecodesign traceability mandates harden procurement requirements. Accelerate SAMR load-rating certification pipelines in China to preempt competitor entry at Beijing Capital and Shanghai Pudong. Defend against automated curing system diffusion by embedding RFID-enabled tire tracking into long-term service contracts.
For New Entrants and Emerging Players: Predictive maintenance platform integration represents a service-layer gap where incumbents under-serve regional airports with legacy GSE fleets. Target India airport privatization wave at Navi Mumbai and Jewar with decade-long lifecycle contract proposals. Enter through bio-based rubber compound specialization, leveraging REACH reformulation timelines to establish first-mover positioning.
For Investors and Strategic Acquirers: Regional compounders with established SAMR testing partnerships and aromatic-free formulation capabilities present acquisition target archetypes with embedded regulatory compliance speed. Long-term viability hinges on backward integration into traceable natural rubber supply chains and predictive maintenance platform partnerships. Watch for FAA certification timeline compression as inflection indicator—accelerated approvals signal competitive repositioning opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Traceable Rubber Sourcing | EU Ecodesign mandates at Amsterdam Schiphol and Paris Charles de Gaulle require plantation-origin certification. |
| RFID-Enabled Predictive Maintenance Platform | FAA data logging requirements create recurring revenue streams through subscription-based tire monitoring. |
| SAMR Load-Rating Certification Partnership | China GB standards condition market access for radial and solid constructions at state-owned ground handling entities. |
| Aromatic-Free Compound Reformulation | EU REACH restrictions accelerate bio-based plasticizer adoption, creating first-mover advantages for compliant suppliers. |
| Integrated Fleet Management Contract Consolidation | American Airlines and Delta Air Lines centralize specification authority, displacing regional distributor channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with ground handling fleet managers at Swissport and dnata, airline GSE procurement directors at American Airlines and Lufthansa Group, tire compounder R&D heads, and aftermarket service channel partners providing operational perspective. Secondary validation drew from FAA airworthiness directives, ECHA REACH substance restrictions, SAMR GB standard filings, customs trade data for natural rubber imports, and SEC 10-K disclosures from integrated tire manufacturers. Bottom-up demand modeling across tire construction types, application intensities, and end-user procurement structures triangulated against top-down macroeconomic indicators for aviation activity.
Across the analysis window, volume and value outputs reflect segment-level modeling across radial, solid, bias, and foam-filled constructions; cargo handling, airport, maintenance, and ground service applications; and ground handling company, airline, military, and cargo service provider end-user categories. CAGRs were derived from elasticity-adjusted replacement cycle analysis incorporating air cargo throughput growth and regulatory mandate compliance timelines. Forecast inputs included airport infrastructure investment pipelines, military procurement specifications, and REACH reformulation adoption curves.
Forecasts assume regulatory continuity in FAA, ECHA, and SAMR regimes; material policy shifts would require re-modeling. Natural rubber price volatility exceeding historical bands, multi-jurisdiction certification timeline extensions, or compounding talent scarcity acceleration represent specific revision triggers. Revision becomes warranted when aromatic-free formulation adoption crosses 60% threshold among EU-serving suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Connected Tire Market