
 Global Bead Wire (Tyre Bead Wire) Market | 2026-2036
Global Bead Wire (Tyre Bead Wire) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bead Wire (Tyre Bead Wire) Market Analysis
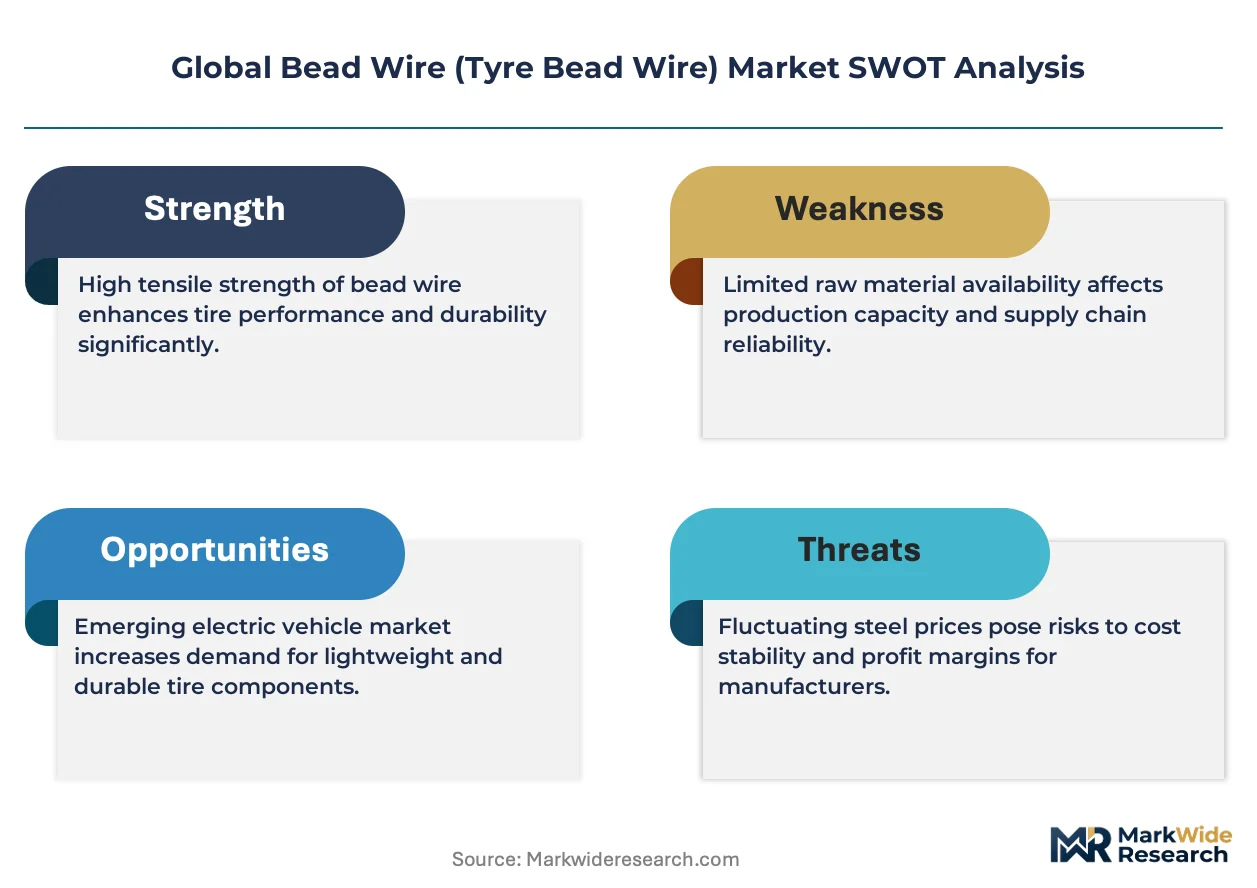
The EU Green Deal is decoupling low-carbon bead wire from commodity pricing, raising compliance costs for non-integrated producers. Bekaert leverages its European melt-shop network to sustain premium positioning in high-strength grades. Hyosung anchors Asian supply through captive steelmaking in South Korea. WireCo WorldGroup competes on North American proximity to tire OEMs.
Bead wire is a high-tensile steel filament, typically 0.78–2.0 mm in diameter, brass- or copper-coated to ensure rubber adhesion, wound into annular rings that seat tires securely on wheel rims. Steel wire dominates volume due to its fatigue resistance under cyclic inflation loads, while brass coated wire commands margin pools from OEM tire manufacturers seeking superior bonding in run-flat constructions. The grade dimension shows high-strength alloys outpacing low-carbon alternatives as vehicle weight ratings rise.
REACH in Europe, EPA emissions rules in the United States, and China's GB standards on steel product carbon intensity are each tightening material disclosure and process efficiency requirements for bead wire suppliers. India's BIS certification mandates now cover imported tire reinforcement inputs, reshaping market access for regional mills. Stakeholders must monitor how carbon border adjustments redefine cost structures for coated wire crossing into the European Union.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are decoupling low-carbon bead wire from commodity steel pricing, forcing procurement officers to weight compliance premiums alongside tensile specifications.
Growth Catalysts
- Electric vehicle platforms:OEM tire manufacturers are expanding procurement of high-strength steel bead wire to accommodate heavier battery-electric vehicle weight ratings and sustained high-torque loads.
- REACH disclosure mandates:European tire producers now require full material provenance documentation, pulling volume toward suppliers with integrated melt-shop-to-coating traceability.
- India's BIS certification expansion:Mandatory certification for imported tire reinforcement inputs is redirecting regional demand toward domestic South Asian mills with certified coating lines.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when ferrous scrap benchmarks spike, compressing bead wire pricing flexibility.
- Chinese supply concentration:Over half of global brass-coated wire capacity sits within three coastal provinces, creating single-point vulnerability to port congestion or power rationing.
- Aramid fiber substitution in aerospace:Run-flat military and aviation tires increasingly specify composite bead reinforcements above 2.0 mm diameter thresholds.
Strategic Opportunities
- Vietnam tire manufacturing corridor:Greenfield radial tire plants near Haiphong lack captive wire supply, opening slots for toll-coating joint ventures with European technology licensors.
- EU carbon border adjustment mechanism:CBAM phase-in creates first-mover advantage for bead wire producers with verified sub-1.5 tCO2e/tonne melt-shop emissions.
- Digital twin integration:Convergence of AI-driven fatigue modeling with real-time draw-bench sensors enables predictive grade certification, collapsing R&D cycle times.
Industry Challenges
- Metallurgical talent scarcity:Specialized wire-drawing engineers with brass-bath chemistry expertise are retiring faster than vocational programs in Germany and Japan can replace them.
- Dual certification timelines:Simultaneous pursuit of IATF 16949 automotive quality and ISO 14064 carbon accounting stretches mid-cap mills across 18-24 month approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bead Wire (Tyre Bead Wire) Market |
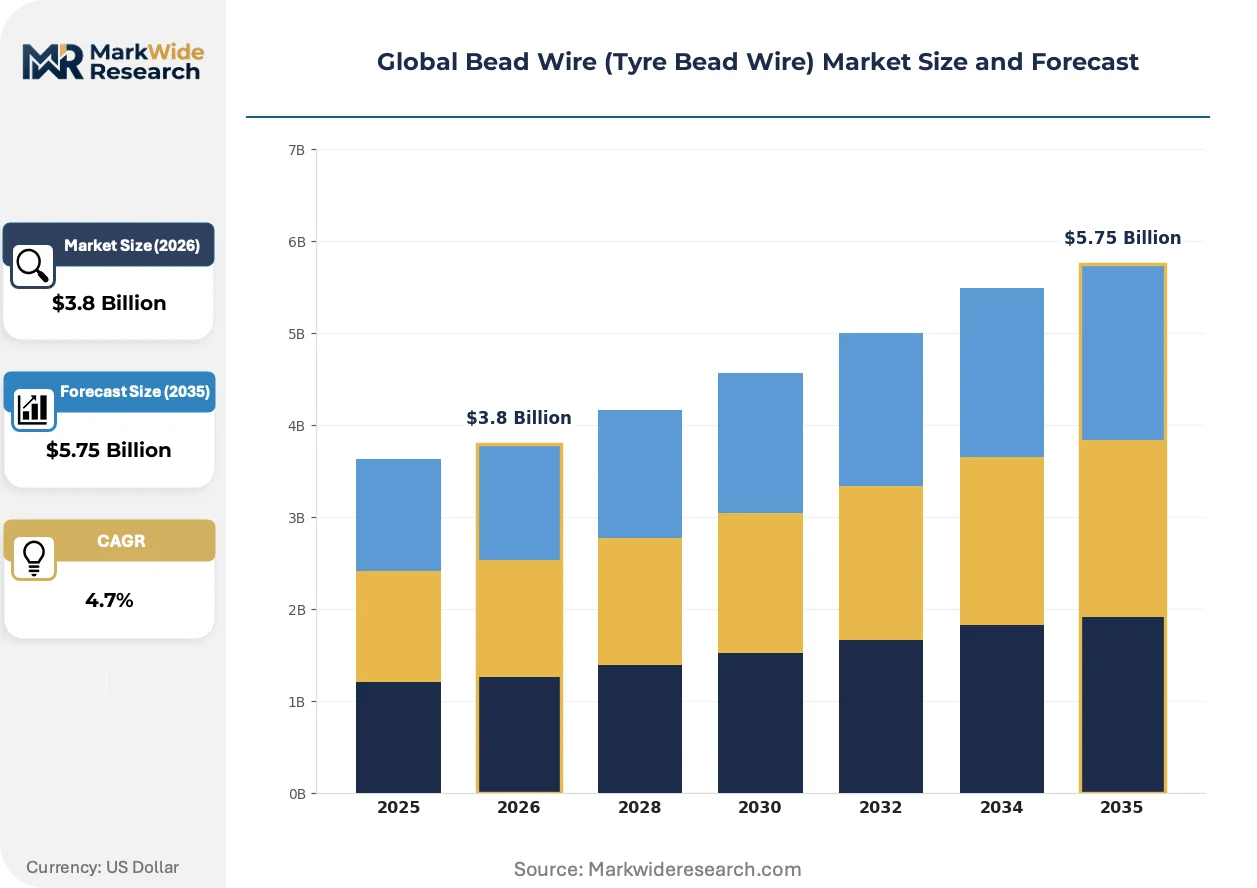
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wire, Brass Coated Wire, Copper Coated Wire, Galvanized Wire Manufacturing Stage: Raw Material, Intermediate Product, Finished Product, Recycled Material End User: OEMs, Aftermarket Providers, Tire Manufacturers, Retreaders Grade: High Strength, Low Carbon, Medium Carbon, Specialty Alloy |
| Companies Covered | HBT Rubber Industrial Co., Ltd, WireCo WorldGroup, Bekaert, Jiangsu Xingda Steel Tyre Cord Co., Ltd, Hyosung, Kiswire, SNTAI Industrial Group Ltd, Aarti Steels Limited, Rajratan Global Wire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bead Wire (Tyre Bead Wire) Market Emerging Trajectories
Active reshaping in bead wire markets centers on material science breakthroughs, regulatory disclosure architectures, and procurement model compression. These forces are rewriting supplier qualification protocols.
Ultra-high-strength microalloyed grades reaching 2,000 MPa tensile strength are electrifying OEM specification sheets for electric vehicle and commercial truck platforms. Tier-one tire manufacturers in Germany and South Korea are fast-tracking validation of these alloys for 22-inch and larger rim diameters. The technology is electrifying competitive positioning by collapsing the historical trade-off between fatigue resistance and weight reduction.
REACH Article 33 disclosure obligations now mandate Substances of Very High Concern reporting through the full tire supply chain. European tire producers are rejecting bead wire lots lacking SCIP database registration, forcing coating houses to requalify brass-bath chemistries. Small-batch South Asian exporters without ECHA-compliant documentation are losing tender access to Continental and Michelin procurement portals.
Consolidated procurement through tire OEM central engineering offices is displacing decentralized plant-level buying. Regional tire factories in China and India now route bead wire specifications through headquarters technical committees, compressing approved vendor lists. This concentration is most visible in Shandong province, where three radial tire megaplants have merged qualified supplier pools from twelve to four mills since 2023.
Global Bead Wire (Tyre Bead Wire) Market Segmentation
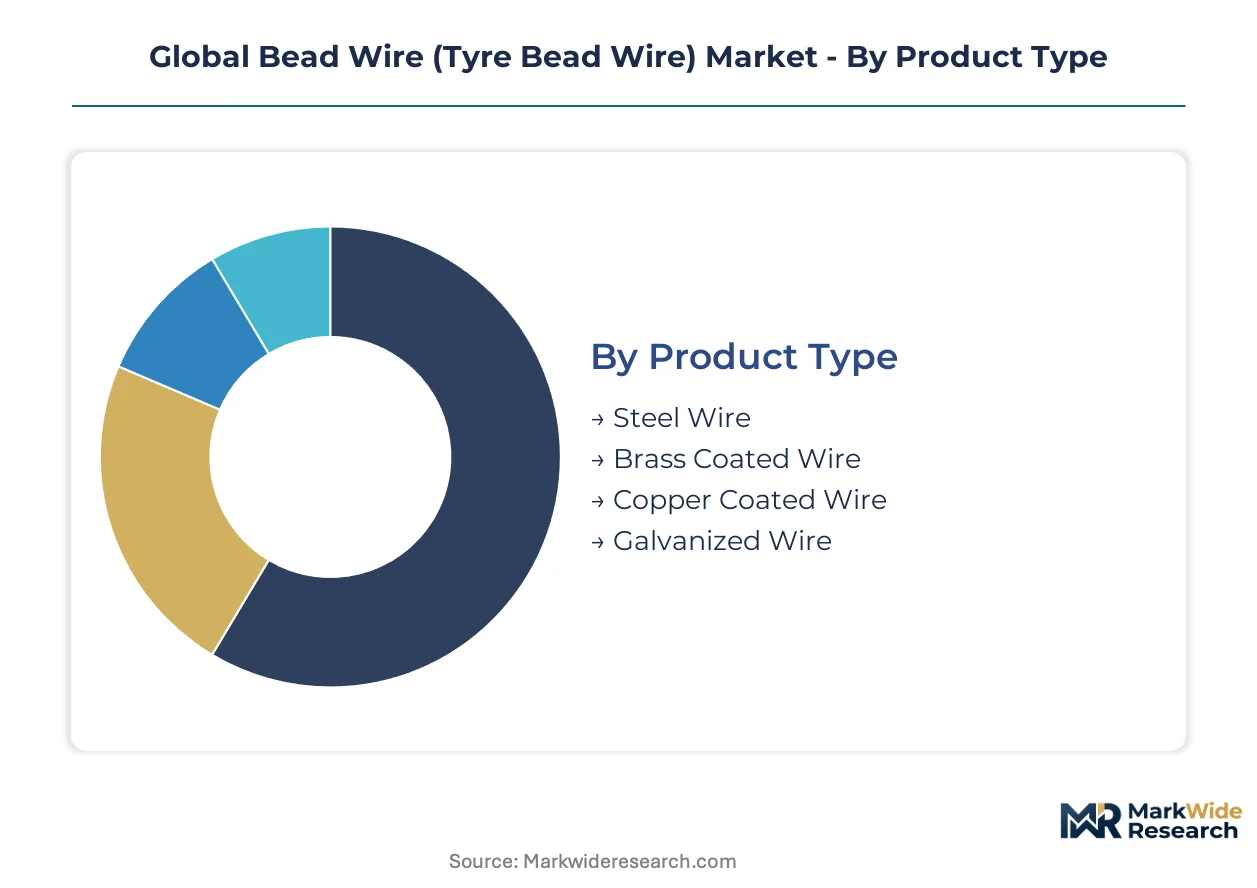
Bead wire segmentation maps directly to capital deployment decisions across steelmaking, coating infrastructure, and certification pathways. Tire OEM procurement committees weight grade specifications and coating chemistry more heavily than commodity wire attributes when qualifying suppliers.
Product Type:
Capital intensity peaks with coated wire variants demanding integrated melt-shop-to-bath control, while commodity steel wire tolerates toll-drawn sourcing models.
- Steel Wire:High-tensile carbon steel filaments drawn to 0.78–2.0 mm diameters dominate volume in commercial truck and passenger tire platforms. Demand concentrates in China and India where radial tire production clusters around integrated steel-rubber supply corridors, constrained by scrap price volatility affecting electric arc furnace operators.
- Brass Coated Wire:Copper-zinc alloy baths deposited onto steel substrates ensure rubber adhesion under cyclic inflation loads. OEM tire manufacturers in Germany and South Korea specify this grade for run-flat and electric vehicle tire constructions, pulling volume toward suppliers with REACH-compliant SCIP database registration.
- Copper Coated Wire:Single-metal deposition offers intermediate bonding performance for economy-tier radial tires.
- Galvanized Wire:Zinc-layer protection serves niche agricultural and off-road tire segments with lower adhesion requirements.
Most installed capacity flows through Steel Wire. Expansion is steepest in Brass Coated Wire.
Manufacturing Stage:
Margin capture shifts downstream from raw material trading toward finished product certification, rewarding mills with in-house drawing and coating lines.
- Raw Material:Ferrous scrap and hot-rolled rod feedstock procurement commands working capital intensity but thin conversion margins. Suppliers in Shandong province and South Korea leverage captive steelmaking to buffer scrap price spikes.
- Intermediate Product:Patenting, pickling, and initial drawing stages require continuous annealing furnaces. Mills near Haiphong, Vietnam lack this installed base, opening toll-processing slots for European technology licensors.
- Finished Product:Final draw, brass coating, and spooling operations carry the highest value-add, with IATF 16949 certification mandatory for OEM tire supply.
- Recycled Material:Reclaimed bead wire from end-of-life tires feeds secondary steelmaking, constrained by rubber contamination separation costs.
Finished Product commands the pricing premium. Recycled Material trails in capacity expansion.
End User:
Procurement authority is centralizing toward headquarters technical committees, compressing approved vendor lists regardless of regional plant location.
- OEMs:Automotive manufacturers specify bead wire indirectly through tire supplier contracts, prioritizing high-strength grades for electric vehicle weight ratings.
- Aftermarket Providers:Independent distributors serve replacement tire channels with standard-grade inventory, price-sensitive to steel commodity movements.
- Tire Manufacturers:Continental, Michelin, and Bridgestone central engineering offices now route specifications through procurement portals, rejecting lots lacking full material provenance documentation.
- Retreaders:Tire remanufacturing operations consume lower-specification wire for casing reinforcement, concentrated in North American and European commercial vehicle fleets.
Tire Manufacturers absorb the dominant volume share. Aftermarket Providers are gaining share fastest in emerging radial tire markets.
Grade:
Specification divergence between high-strength alloys and commodity carbon grades is widening as vehicle weight ratings and fatigue performance thresholds escalate.
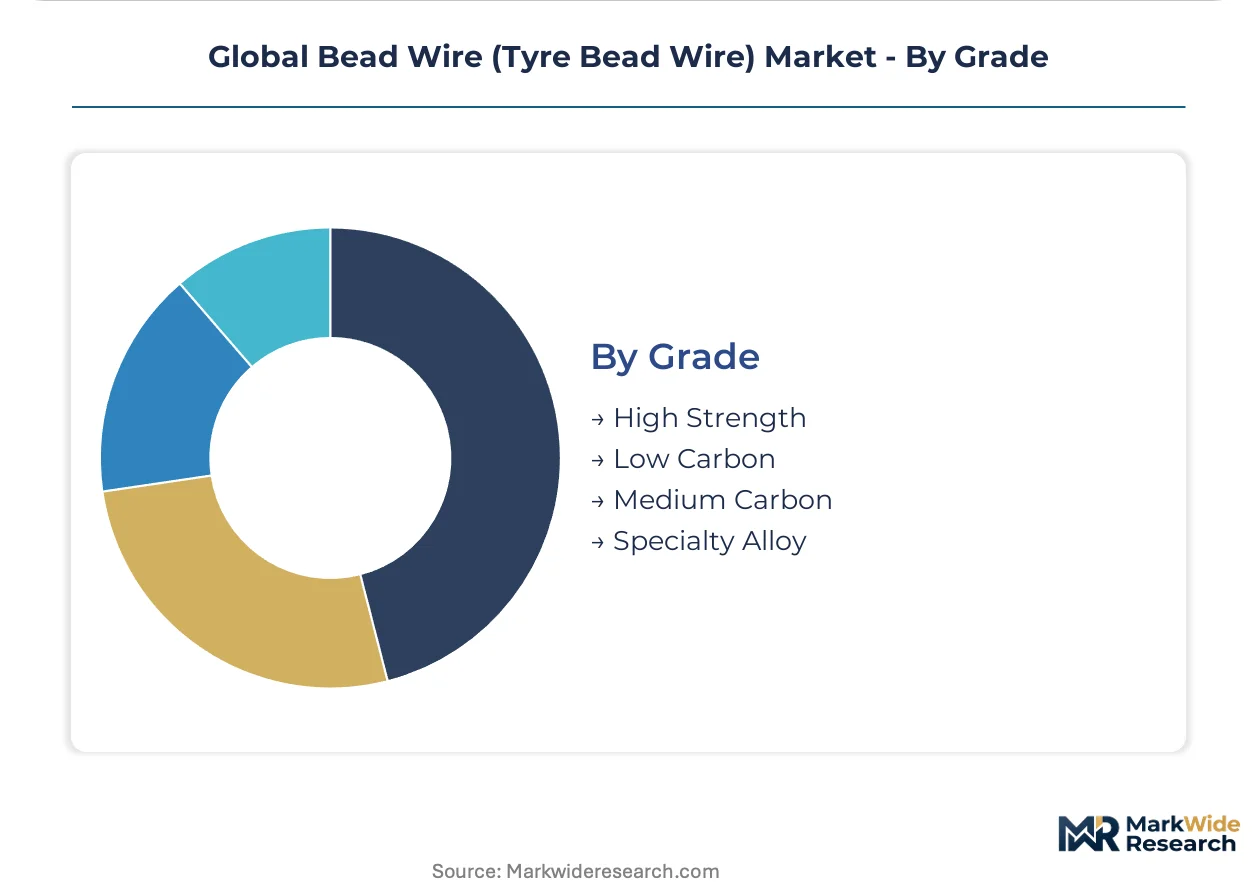
- High Strength:Microalloyed grades reaching 2,000 MPa tensile strength address electric vehicle and commercial truck platforms with 22-inch and larger rim diameters. Validation programs at German and South Korean OEMs are collapsing the historical fatigue-versus-weight trade-off.
- Low Carbon:Standard ductility grades serve economy passenger tires and retreading applications where cost minimization overrides performance margins.
- Medium Carbon:Intermediate strength-to-cost positioning captures mid-tier original equipment specifications.
- Specialty Alloy:Custom chemistries for aerospace and military run-flat tires face aramid fiber substitution above 2.0 mm diameter thresholds.
High Strength commands the investment focus. Specialty Alloy remains the smallest addressable niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized wire-drawing engineers with brass-bath chemistry expertise concentrate in Germany, Japan, and South Korea, anchoring the highest-value bead wire production corridors worldwide.
China
Radial tire megaplants in Shandong province consume over half of global brass-coated wire capacity, consolidating procurement through three coastal manufacturing clusters. GB standards on steel product carbon intensity now mandate material disclosure for all automotive inputs. Qingdao and Weihai host integrated steel-rubber supply corridors where tire OEMs centralize vendor qualification.
Germany
Continental and Michelin engineering offices in Hanover and Karlsruhe route bead wire specifications through centralized procurement portals. REACH Article 33 disclosure obligations force coating houses to requalify brass-bath chemistries for SCIP database registration. The Ruhr Valley melt-shop network sustains premium positioning for high-strength grades serving electric vehicle platforms.
India
BIS certification mandates now cover all imported tire reinforcement inputs, redirecting demand toward domestic South Asian mills with certified coating lines. Radial tire production clusters around Chennai and Pune are expanding procurement of high-strength alloys for commercial vehicle weight ratings. The PLI scheme for automotive components incentivizes backward integration into captive steelmaking.
South Korea
Hyosung anchors Asian supply through captive steelmaking facilities serving OEM tire manufacturers in Gyeonggi province. MFDS-aligned material provenance documentation supports export qualification for European markets facing EU Green Deal embodied carbon thresholds. Busan-Ulsan industrial complexes concentrate drawing and coating operations for run-flat tire constructions.
United States
EPA emissions rules tighten process efficiency requirements for bead wire suppliers serving tire OEMs in the Southeast manufacturing corridor. WireCo WorldGroup leverages North American proximity to radial tire plants in South Carolina and Tennessee. Detroit-based automotive manufacturers specify bead wire indirectly through tire supplier contracts prioritizing fatigue resistance under high-torque electric vehicle loads.
Global Bead Wire (Tyre Bead Wire) Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the bead wire value chain, creating a tiered structure where scale advantages clash with coating chemistry expertise. The market consolidates around integrated melt-shop-to-coating operations capable of REACH-compliant documentation. Three archetypes dominate: European steel majors with premium-grade positioning, Asian conglomerates with captive raw material access, and regional toll-coating specialists serving emerging tire corridors. Capacity expansion and strategic technology licensing represent the dominant competitive moves as mills race to certify ultra-high-strength microalloyed grades.
Among Belgian-based diversified steel groups, Bekaert exemplifies the premium-tier archetype through its European melt-shop network. Hyosung and Kiswire anchor the Asian conglomerate tier with South Korean captive steelmaking operations. WireCo WorldGroup occupies a position within the North American proximity-focused segment. These three represent distinct strategic postures: Bekaert leverages compliance infrastructure for EU Green Deal thresholds, Hyosung and Kiswire exploit integrated cost positions, and WireCo WorldGroup competes on logistics proximity to tire OEMs.
| Leading Market Players |
|---|
| HBT Rubber Industrial Co., Ltd |
| WireCo WorldGroup |
| Bekaert |
| Jiangsu Xingda Steel Tyre Cord Co., Ltd |
| Hyosung |
| Kiswire |
| SNTAI Industrial Group Ltd |
| Aarti Steels Limited |
| Rajratan Global Wire |
| Others |
Supply Flow & Price Mechanics
REACH Article 33 disclosure obligations in Europe are forcing coating houses to requalify brass-bath chemistries for SCIP database registration, compelling supply chains to absorb compliance premiums or lose OEM tire manufacturer access. This procurement filter concentrates volume toward integrated melt-shop-to-coating operations capable of documented traceability, compressing margins for toll-dependent mills.
Pricing Analysis
Coated wire services split between bundled certification-inclusive offerings and unbundled commodity supply. Pricing stratifies across premium, standard, and economy tiers based on IATF 16949 automotive quality certification and verified sub-1.5 tCO2e/tonne emissions documentation. Cost compression in standard grades is intensifying because scrap steel price volatility squeezes electric arc furnace operators. Aftermarket distributors serving replacement tire channels exhibit highest price sensitivity, while OEM tire manufacturers prioritize fatigue performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Shandong province, Gyeonggi province, and the Ruhr Valley anchor hub-and-spoke patterns feeding radial tire megaplants. Geographic supply concentrates in China, South Korea, and Germany where integrated steel-rubber corridors cluster. Raw material feeds draw from ferrous scrap benchmarks, hot-rolled rod feedstock, and copper-zinc alloy baths for brass coating. Single-source vulnerability to port congestion in three coastal Chinese provinces constitutes the dominant structural risk. Distribution runs through tire OEM central engineering offices that compress approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bead wire market functions as a regulatory compounder where EU Green Deal embodied carbon thresholds continuously ratchet compliance costs upward, embedding structural demand for documented low-carbon grades.
For Market Incumbents: Hedge against aramid fiber substitution in aerospace run-flat applications above 2.0 mm diameter thresholds by accelerating validation of ultra-high-strength microalloyed grades reaching 2,000 MPa tensile strength. Prioritize backward integration into captive steelmaking to buffer scrap price volatility and sustain REACH-compliant SCIP database registration. Defend premium positioning through Ruhr Valley and South Korean melt-shop network investments. For New Entrants and Emerging Players: India's BIS certification expansion opens a window for domestic South Asian mills with certified coating lines to capture redirected import replacement demand. Target toll-coating joint ventures near Haiphong, Vietnam where greenfield radial tire plants lack captive wire supply. Pursue European technology licensing agreements as the primary go-to-market angle to secure brass-bath chemistry expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing IATF 16949 certification and verified low-carbon melt-shop emissions. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than commodity scale. Watch for EU carbon border adjustment mechanism phase-in as the inflection indicator separating first-mover certified producers from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Steelmaking | Buffers scrap price volatility and secures REACH-compliant material provenance for OEM tire supply. |
| Ultra-High-Strength Grade Validation | Addresses electric vehicle weight ratings and commercial truck 22-inch rim specifications at German OEMs. |
| Toll-Coating Joint Venture in Vietnam | Captures unmet demand from greenfield radial tire plants near Haiphong lacking integrated wire supply. |
| SCIP Database Registration Investment | Enables continued access to Continental and Michelin procurement portals under REACH Article 33. |
| Digital Twin Integration for Predictive Certification | Collapses R&D cycle times through AI-driven fatigue modeling converging with real-time draw-bench sensors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tire manufacturer procurement directors, steel mill technical directors, coating house operations managers, and automotive OEM platform engineers with secondary validation. Sources included customs and trade data, SEC filings from diversified steel groups, BIS certification registries, and ECHA SCIP database disclosures. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated for coherence.
Segment-weighting approaches distributed volume and value across product type, manufacturing stage, end user, and grade dimensions over the projection horizon. CAGRs were derived from elasticity modeling against vehicle production forecasts and tire OEM procurement patterns. Industry-specific inputs incorporated electric vehicle platform weight ratings, radial tire megaplant capacity expansion pipelines, and scrap steel price volatility indices.
Revisions become necessary when EU carbon border adjustment mechanism implementation timelines accelerate, when Chinese power rationing disrupts coastal province coating operations, or when aramid fiber substitution thresholds shift in aerospace specifications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market