
 Green Supplement Market | 2026-2036
Green Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Green Supplement Market Foresight
Plant-based protein isolates is recalibrating cost structures across green supplement portfolios as manufacturers reformulate away from dairy-derived bases. NOW Foods leverages its vertically integrated manufacturing network to control raw spirulina quality from cultivation through bottling. Herbalife Nutrition Ltd. anchors its green product line through direct-selling channels that sustain higher margin capture than mass retail. Athletic Greens differentiates via subscription-based distribution that locks in recurring revenue per customer cohort.
Green supplements encompass concentrated formulations of algae, cereal grasses, and leafy botanicals standardized for chlorophyll, antioxidant, and micronutrient density, primarily consumed to fill dietary gaps in vegetable intake and support detoxification pathways. Powdered formats dominate volume sales due to lower per-serving cost and flexible dosing, while gummy formulations capture the fastest expansion as taste-sensitive consumers reject earthy flavor profiles. Organic ingredient sourcing commands premium shelf positioning and tighter supply relationships, whereas conventional sourcing competes on price in private-label channels.
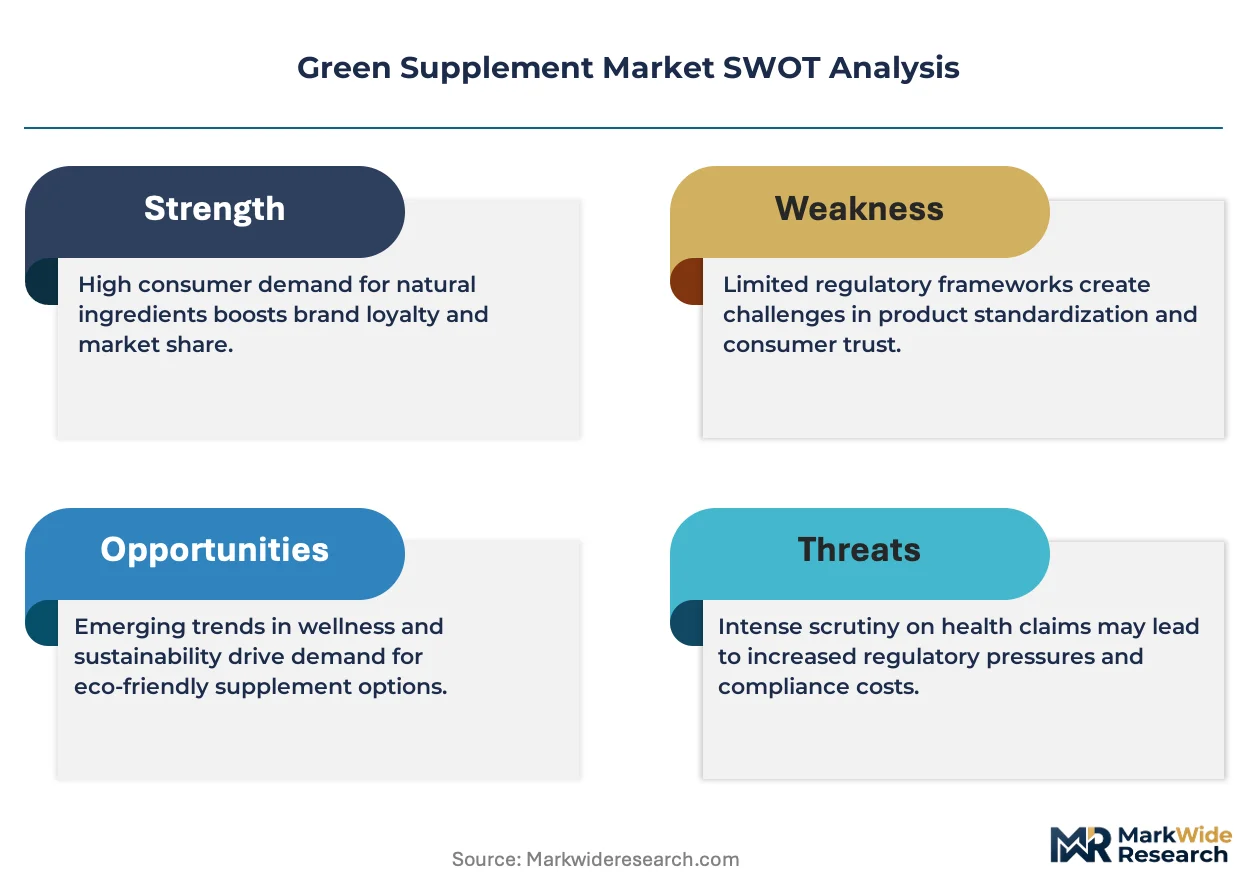
The FDA oversees supplement labeling and Good Manufacturing Practice compliance, while the USDA administers organic certification standards that gate premium market access; together these frameworks elevate compliance costs for new entrants but protect incumbent positions. The EU EFSA health claims process restricts marketing language around detoxification benefits, forcing companies to invest in clinical substantiation. Stakeholders must monitor evolving novel food designations for emerging algae strains and adapt formulation pipelines accordingly.
Market Dynamics
Plant-based protein isolates are forcing wholesale reformulation across green supplement portfolios as manufacturers abandon dairy-derived bases to capture flexitarian consumers and meet clean-label expectations from specialty retailers.
Growth Catalysts
- EU Novel Food Regulation:The streamlined approval pathway for algae-derived ingredients accelerates time-to-market for spirulina and chlorella variants, reducing regulatory friction for new botanical entrants seeking premium positioning.
- Sports nutrition channel expansion:Specialty retailers now merchandise green powders alongside traditional protein supplements, exposing concentrated botanicals to high-frequency gym and athletic consumers with established supplement routines.
- Organic certification premiums:Germany's consumer willingness to pay for USDA- and EU-organic certified green powders tightens supply relationships and gates private-label competitors from premium shelf placement.
Market Restraints
- Algae cultivation input volatility:Spirulina and chlorella production depends on controlled-temperature pond systems vulnerable to energy price swings and climate stress, compressing margin stability for non-integrated processors.
- Supply concentration in East Asian pond operations:A limited number of large-scale algae farms in China and Taiwan control raw spirulina availability, creating bottleneck risk for Western bottlers without captive cultivation.
- EFSA health claim restrictions:The European regulator's strict substantiation requirements for detoxification marketing language force costly clinical trials, elevating compliance burdens for mid-tier entrants.
Strategic Opportunities
- Gummy format white space:Taste-sensitive consumers rejecting earthy powder profiles create expansion room for palatable gummy formulations, particularly among younger demographics in North American direct-to-consumer channels.
- Subscription distribution models:Recurring revenue platforms lock in per-cohort lifetime value and reduce customer acquisition cost volatility compared to mass retail churn.
- Dual carbon goals alignment:China's national emissions targets incentivize low-carbon algae cultivation investments, positioning domestic producers for preferential procurement from sustainability-focused multinational brands.
Industry Challenges
- Clinical substantiation skill scarcity:EFSA-compliant detoxification claims require specialized toxicology and nutrition science expertise that mid-size formulators struggle to retain in-house.
- Legacy ERP integration with traceability systems:Organic certification demands lot-level ingredient tracking that conflicts with older manufacturing execution software, forcing costly middleware deployments.
- Algae strain IP licensing complexity:Proprietary spirulina and chlorella variants carry germplasm access restrictions that delay formulation pipelines and inflate royalty structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Supplement Market |
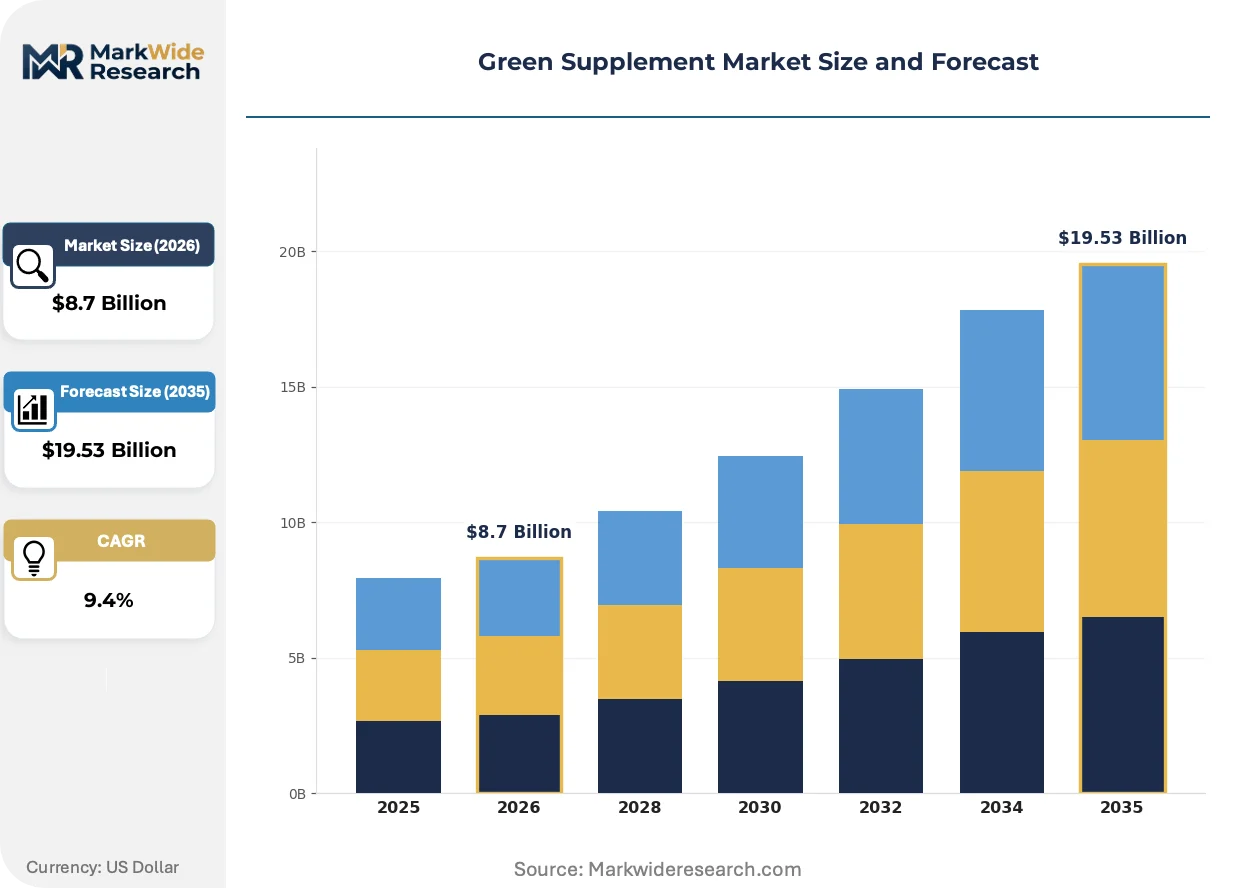
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Nutritional Yeast, Spirulina, Chlorella Form: Powder, Capsule, Liquid, Gummy End User: Athletes, Health Enthusiasts, Vegans, Seniors Ingredient Source: Organic, Non-GMO, Wildcrafted, Conventional |
| Companies Covered | Amway Corporation, Herbalife Nutrition Ltd., GNC Holdings Inc., NOW Foods, Athletic Greens, Amazing Grass, Organifi, Vibrant Health, Puritan's Pride, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Supplement Market Shifts & Advancements
Cellular agriculture and precision fermentation are reshaping how concentrated botanicals achieve micronutrient density, compressing traditional cultivation timelines while raising new regulatory classification questions for novel food authorities.
Lipid encapsulation technology is expanding into green supplement manufacturing, shielding chlorophyll and antioxidant compounds from oxidation during shelf storage. Premium powder brands in Germany and California are adopting microencapsulation to extend best-by windows without synthetic preservatives. This innovation is expanding into mass-market private-label channels as equipment costs decline and co-manufacturers build captive capabilities.
The EU EFSA health claims process is tightening marketing vocabulary around detoxification benefits, forcing companies to invest in randomized controlled trials for substantiation. This regulatory friction most heavily impacts mid-tier European brands that previously relied on traditional use claims. German and French market entrants are responding by pivoting toward immune support and micronutrient gap-filling positioning with stronger clinical precedent.
Athletic consumers are consolidating purchases through subscription platforms that bundle green powders with protein and hydration products, displacing single-SKU retail experimentation. This behavioral shift concentrates demand among digitally native brands with direct fulfillment infrastructure. The pattern is most visible in North American urban markets where gym membership and supplement subscription overlap exceeds fifty percent.
Green Supplement Market Segmentation
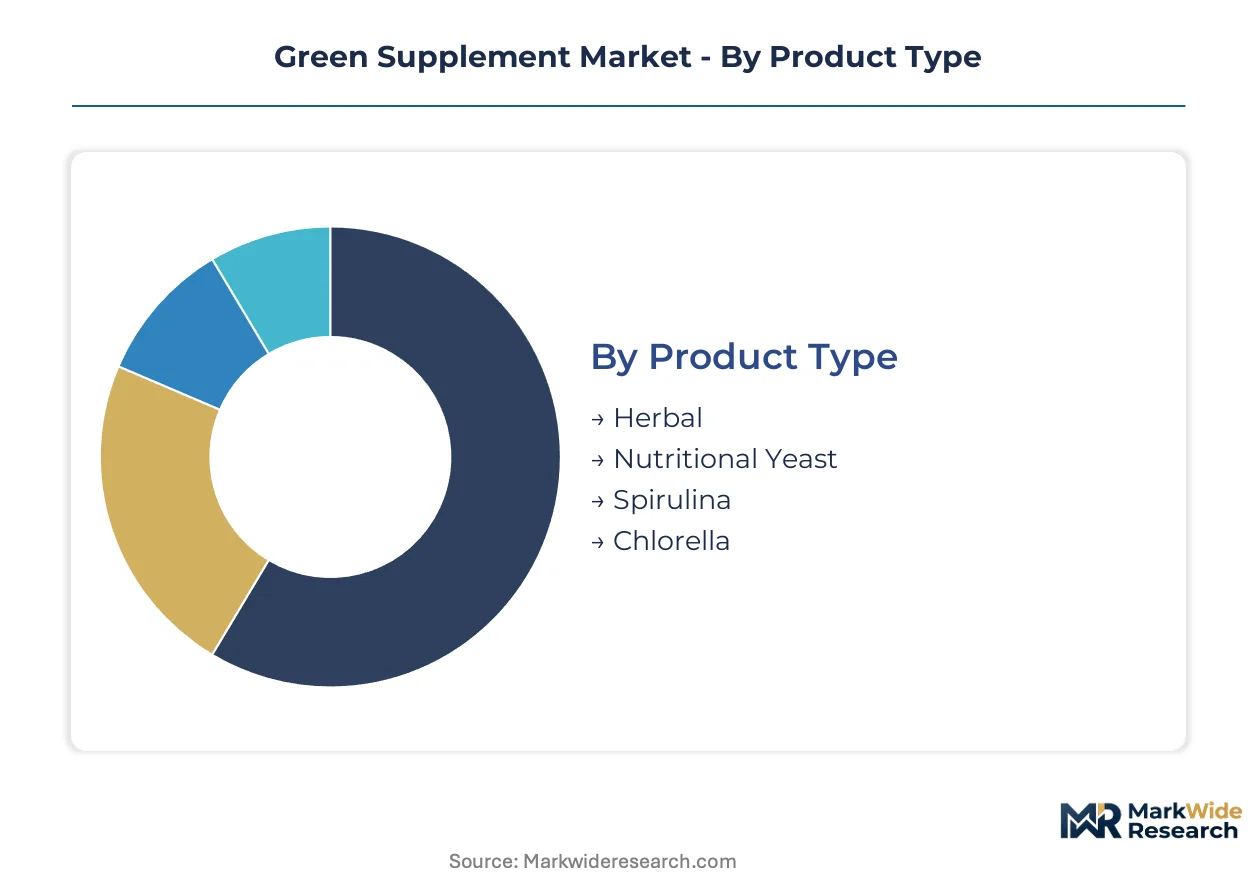
Segmentation in green supplements reveals divergent capital requirements and margin profiles across product architectures. Powdered spirulina demands heavy pond infrastructure investment while gummy formats require specialized encapsulation equipment. Understanding these structural differences clarifies where new entrants face barriers versus white-space opportunities.
Product Type:
Spirulina and chlorella cultivation systems require the steepest upfront capital commitment due to climate-controlled pond infrastructure and continuous harvesting technology.
- Spirulina:Cyanobacteria biomass cultivated in open or closed photobioreactor systems, standardized for phycocyanin and protein content. German specialty retailers command premium shelf placement for organic-certified variants, though energy-intensive temperature control compresses margins during price volatility.
- Chlorella:Single-celled green algae requiring cell-wall disruption processing to unlock nutrient bioavailability. Japanese and Taiwanese pond operations dominate raw supply, forcing Western brands into long-term offtake agreements or captive cultivation investments.
- Herbal:Concentrated extracts from wheatgrass, barley grass, and moringa leaf, typically spray-dried for powder formulations. Supply relationships with certified organic farms in California and Bavaria determine quality tier access.
- Nutritional Yeast:Inactive Saccharomyces cerevisiae fortified with B-vitamins, appealing to vegan consumers seeking cheese-alternative flavor profiles. Precision fermentation infrastructure in North American and European facilities supports scalable production.
Spirulina absorbs the bulk of installed capacity; chlorella is expanding most quickly as clinical substantiation for detoxification positioning strengthens.
Form:
Format selection directly determines manufacturing asset requirements and per-unit economics, with powder lines requiring blending equipment and gummy production demanding starch molding or depositing systems.
- Powder:Bulk dry blends offering flexible dosing and lowest per-serving cost structure. Athletic consumers in US urban markets consolidate purchases through subscription bundles combining green powders with protein isolates.
- Gummy:Palatable gelatin or pectin-based delivery masking earthy algae flavors with fruit extracts. Direct-to-consumer channels in North America capture younger demographics rejecting traditional powder formats.
- Capsule:Pre-measured gelatin or vegetable cellulose shells enabling precise dosing and portability. German pharmacies and US specialty retailers favor this format for senior consumers seeking convenience.
- Liquid:Ready-to-drink concentrates or shots with shorter shelf life requiring cold-chain logistics. Premium positioning in California and New York wellness boutiques supports higher price points despite distribution complexity.
Powder commands the largest production footprint; gummy formats gain share fastest among taste-sensitive consumer cohorts.
End User:
Customer archetypes diverge sharply in purchase frequency, channel preference, and willingness to pay for certification premiums.
- Athletes:High-frequency consumers integrating green supplements into peri-workout nutrition stacks. Sports nutrition specialty retailers in the US and Germany now merchandise algae powders alongside traditional protein products.
- Health Enthusiasts:Broad wellness-focused buyers prioritizing organic certification and clean-label ingredient transparency. Subscription platforms lock in recurring revenue from this cohort through bundled product offerings.
- Vegans:Dietary-restricted consumers seeking B12, iron, and complete protein from non-animal sources. Nutritional yeast and spirulina serve as cornerstone ingredients in plant-based nutrition protocols.
- Seniors:Age-demographic prioritizing ease of consumption and digestive tolerability. Capsule and liquid formats dominate this segment due to swallowing convenience and reduced fiber load.
Health enthusiasts generate the steadiest recurring demand; athletes show the steepest expansion trajectory as sports nutrition channels broaden green supplement exposure.
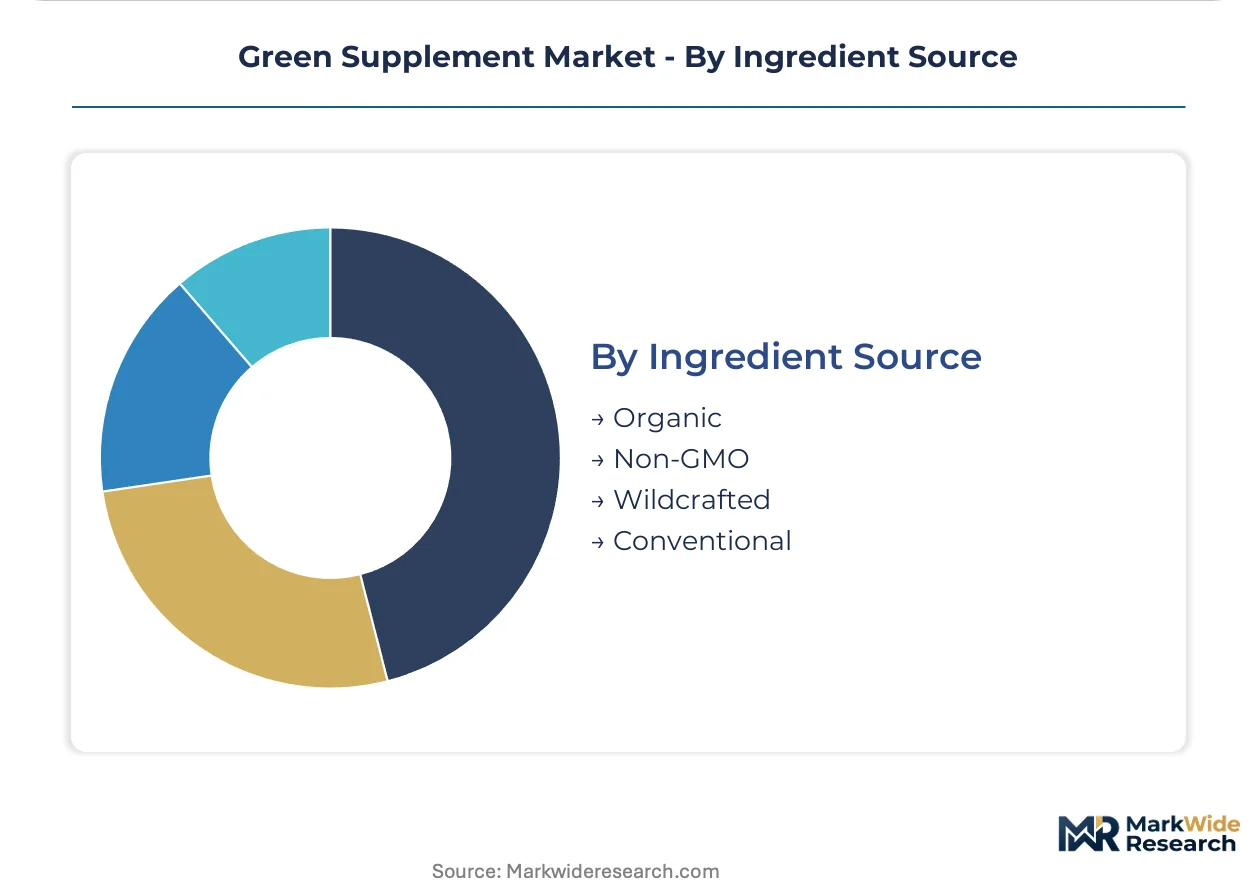
Ingredient Source:
Sourcing tier determines regulatory pathway complexity, certification cost burden, and access to premium retail placement.
- Organic:USDA or EU-organic certified cultivation prohibiting synthetic pesticides and fertilizers. German consumers demonstrate the strongest willingness-to-pay premium, gating private-label competitors from premium shelf positioning.
- Non-GMO:Identity-preserved supply chains verified through third-party testing. US retailers and direct-to-consumer brands leverage this positioning to capture consumers avoiding genetically modified organisms without full organic price premiums.
- Wildcrafted:Hand-harvested botanicals from non-cultivated sources, typically seaweeds and forest botanicals. Limited scalability and harvest seasonality constrain volume expansion despite premium positioning.
- Conventional:Standard agricultural or pond-cultivated sourcing without certification premiums. Private-label channels and price-sensitive mass retail in emerging markets rely on this tier for competitive entry points.
Organic sourcing claims the majority of premium manufacturing capacity; non-GMO verification is climbing fastest as a middle-tier positioning strategy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer willingness to pay for organic-certified green powders concentrates in Germany, while North American direct-to-consumer channels drive subscription model adoption. Regulatory frameworks in the EU and US shape ingredient approval timelines and marketing vocabulary.
Germany
Specialty retailers in Munich and Hamburg command premium shelf placement for USDA- and EU-organic certified spirulina powders. EFSA health claim restrictions force brands to invest in randomized controlled trials for substantiation. The Bavarian organic farming corridor supplies wheatgrass and barley grass to domestic formulators.
United States
Athletic consumers in Los Angeles and New York consolidate purchases through subscription platforms bundling green powders with protein isolates. FDA labeling requirements and USDA organic certification standards elevate compliance costs for new entrants. California's precision fermentation facilities support nutritional yeast production for vegan nutrition protocols.
China
Large-scale spirulina pond operations in Yunnan and Guangdong provinces control raw biomass availability for Western bottlers. National dual carbon goals incentivize low-carbon algae cultivation investments. Shanghai-based co-manufacturers build captive microencapsulation capabilities for lipid encapsulation technology.
Japan
Chlorella cell-wall disruption processing expertise concentrates in Kyushu and Okinawa, where Taiwanese and domestic pond operations supply raw algae. METI guidelines influence novel food designation timelines for emerging strains. Tokyo direct-to-consumer brands pioneer gummy format development for taste-sensitive demographics.
United Kingdom
London wellness boutiques drive premium liquid shot positioning despite cold-chain distribution complexity. FSA compliance with EU-retained EFSA standards restricts detoxification marketing language. Manchester and Birmingham specialty retailers expand sports nutrition sections to include algae powders alongside traditional supplements.
Green Supplement Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers reformulate around plant-based protein isolates and experiment with palatable gummy formats. The vendor base spans vertically integrated cultivators, direct-selling specialists, and digitally native subscription platforms. Three archetypes define competitive positioning: captive cultivation operators controlling raw spirulina quality from pond to bottling; direct-selling networks sustaining higher margin capture than mass retail; and subscription-first brands locking in recurring revenue per customer cohort. M&A activity targets algae strain IP and precision fermentation capabilities, while strategic partnerships with East Asian pond operators secure raw biomass offtake.
Among US-based formulators, NOW Foods exemplifies captive supply chain control through in-house spirulina cultivation, while Athletic Greens occupies a position within the subscription-native tier. Herbalife Nutrition Ltd. represents the direct-selling archetype with its network-driven distribution model. These three anchors illustrate how competitive advantage flows from upstream control, recurring revenue mechanics, or channel-specific margin structures rather than interchangeable product positioning.
| Leading Market Players |
|---|
| Amway Corporation |
| Herbalife Nutrition Ltd. |
| GNC Holdings Inc. |
| NOW Foods |
| Athletic Greens |
| Amazing Grass |
| Organifi |
| Vibrant Health |
| Puritan's Pride, Inc. |
| Others |
Supply & Pricing Matrix
China's dual carbon goals and the EU Green Deal's sustainability mandates gate qualified supply and premium-tier pricing access, as algae cultivators in Yunnan and certified organic farms in Bavaria face divergent compliance cost structures that stratify raw material access and shelf positioning economics.
Pricing Analysis
The volume-vs-margin split separates mass-market private-label powders from subscription-native and direct-selling channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and captive cultivation status. Price differentiation hinges on USDA and EU-organic seals that command shelf placement in German specialty retail. Cost compression in conventional spirulina sourcing is intensifying because energy price volatility strains non-integrated pond operators. Mass retail buyers in emerging markets show highest price sensitivity; health enthusiasts in North America and Germany demonstrate lowest sensitivity when organic certification is present.
Supply Chain Analysis
Workforce availability in precision fermentation facilities across California and Shanghai shapes downstream capacity expansion for nutritional yeast and encapsulated formats. Raw spirulina biomass concentrates in China, Taiwan, and Japan, while organic wheatgrass and barley grass sourcing draws from California and Bavaria. Phycocyanin extraction equipment and cell-wall disruption technology for chlorella rest on specialized engineering talent pools in Kyushu and Okinawa. Single-source vulnerability runs through East Asian pond operations controlling Western bottler offtake. Distribution runs through three channels: direct-to-consumer subscription platforms, specialty sports nutrition retailers, and pharmacy chains in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Novel Food Regulation creates a compliance moat that rewards clinical substantiation investment and punishes traditional-use claim reliance, elevating capital requirements for market entry while protecting incumbent positions.
For Market Incumbents: Anchor market position through captive spirulina cultivation investments in climate-stable geographies and microencapsulation capability builds that extend best-by windows without synthetic preservatives. Defend against direct-to-native subscription brands by locking athletic consumers into bundled protein-and-greens offerings. Prioritize EFSA-compliant immune support positioning over detoxification claims to reduce regulatory friction.
For New Entrants and Emerging Players: The EU Novel Food Regulation in Europe opens a window for algae strain IP licensing plays that bypass lengthy novel food designation timelines. Target gummy format white space in North American direct-to-consumer channels where taste-sensitive younger demographics reject earthy powder profiles. Pursue white-label manufacturing partnerships with Shanghai-based co-manufacturers building captive lipid encapsulation capabilities.
For Investors and Strategic Acquirers: M&A activity targeting precision fermentation infrastructure is the leading indicator that cellular agriculture capabilities are consolidating toward platform-scale players. Frame long-term viability around subscription revenue retention and organic certification asset ownership rather than single-SKU retail exposure. Target acquisition candidates with captive pond operations or clinical trial pipelines for EFSA substantiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Algae Cultivation Investment | Backward integration into Yunnan pond operations insulates margin stability from energy price volatility. |
| EFSA-Compliant Clinical Trial Program | Randomized controlled trials unlock immune support marketing vocabulary in German and French markets. |
| Gummy Format Manufacturing Scale-Up | Starch molding capacity in North American facilities captures taste-sensitive younger consumer cohorts. |
| Subscription Platform Technology Build | Recurring revenue infrastructure reduces customer acquisition cost volatility versus mass retail churn. |
| Organic Certification Asset Acquisition | USDA and EU-organic supply relationships gate premium shelf placement in Munich and Hamburg retailers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning supplement brand formulators, specialty retail category buyers, algae cultivation facility managers, and regulatory affairs consultants specializing in novel food submissions. Bottom-up volume modeling triangulated against top-down market sizing from EU organic certification databases and USDA National Organic Program producer listings.
Data-stream reconciliation across shipment volumes, certification registry counts, and channel sell-through metrics informed the analytical framework. Segmentation dimensions modeled include product architecture, ingredient source tier, format type, end-user archetype, and regional regulatory cluster. CAGRs derived from fitted trend lines applied to historical certification growth and channel penetration curves, with cross-validation against sports nutrition retail audit data and direct-to-consumer subscription platform disclosures.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation and cellular agriculture would alter the outlook for traditional pond-cultivated spirulina economics. Forecasts reflect assumptions regarding EFSA enforcement consistency, energy price stabilization, and organic certification demand elasticity. Material deviation in novel food approval timelines or East Asian biomass export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Maternity Vitamins and Supplements Market