
 Food Grade Beta-Alanine Market | 2026-2036
Food Grade Beta-Alanine Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Beta-Alanine Market Insights
Buyer concentration among nutraceutical companies is consolidating as mid-size supplement brands merge procurement functions and negotiate long-term supply agreements. Natural Alternatives International leverages its patented sustained-release technology to lock in premium sports nutrition contracts. Anhui Huaheng Biotechnology anchors Asian supply chains through integrated fermentation capacity. Merck KGaA competes on pharmaceutical-grade purity standards that extend into food-grade beta-alanine applications.
Food grade beta-alanine is a non-essential amino acid produced via microbial fermentation or chemical synthesis, typically specified at minimum 98.5% purity with strict limits on heavy metals and microbial contaminants; it functions primarily as a carnosine precursor to buffer muscle pH during high-intensity exercise. Powder formulations dominate bulk ingredient shipments to contract manufacturers, while capsules capture higher margins in direct-to-consumer channels. Performance enhancement applications lead absolute volume, though cognitive function positioning in nootropic stacks is expanding fastest among specialty formulators.
FDA food additive regulations and EFSA novel food assessments shape market access timelines for new beta-alanine suppliers entering North American and European markets. FSSAI in India and China's SAMR enforce parallel purity standards that determine import eligibility for cross-border ingredient trade. Stakeholders must monitor evolving sports nutrition claim restrictions in major jurisdictions to anticipate reformulation requirements and channel strategy adjustments.
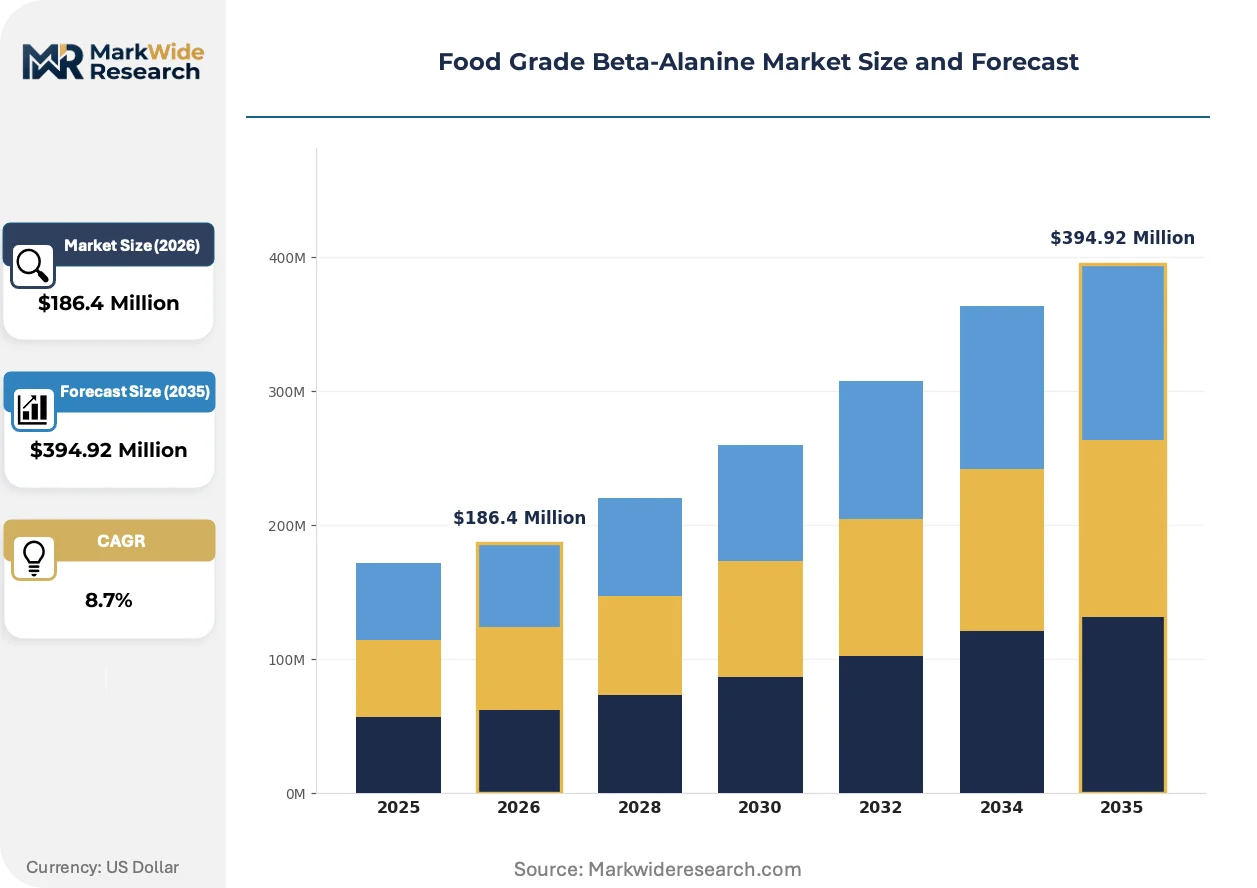
Market Dynamics
Sports nutrition procurement consolidation is compressing supplier margins and forcing fermentation-scale investments as mid-tier brands aggregate volume commitments and demand multi-year purity guarantees.
Growth Catalysts
- EFSA novel food assessments:Clean-label certification pathways in Europe are accelerating premium-grade beta-alanine qualification for functional beverage applications.
- Carnosine precursor positioning:Pre-workout supplement formulators are expanding beta-alanine inclusion rates to differentiate pH-buffering claims in crowded sports nutrition shelves.
- United States functional beverage sector:Ready-to-drink performance drinks command sustained-release powder volumes that outpace capsule growth in absolute tonnage.
Market Restraints
- Corn-derived feedstock volatility:Fermentation input costs fluctuate with agricultural commodity cycles, squeezing integrated Chinese producers.
- Heavy metal contamination thresholds:FDA food additive regulations enforce stricter lead and arsenic limits than chemical synthesis routes reliably achieve.
- Sustained-release patent estates:Proprietary delivery technology licensing creates barriers for generic powder suppliers seeking sports nutrition contracts.
Strategic Opportunities
- Nootropic stack positioning:Cognitive function claims in specialty formulator channels represent underdeveloped demand outside traditional sports nutrition.
- FSSAI import pathway optimization:India's evolving amino acid additive standards create first-mover advantages for suppliers achieving dual FDA-FSSAI certification.
- Direct-to-consumer capsule formats:Branded ingredient partnerships with subscription wellness platforms bypass contract manufacturer margin compression.
Industry Challenges
- Pharmaceutical-grade crossover talent:Food-grade producers struggle to recruit analytical chemists capable of executing USP heavy metal validation protocols.
- SAMR registration timelines:China's novel food ingredient approval processes extend market access delays beyond fermentation capacity lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Beta-Alanine Market |
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $394.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquids End User: Fitness Enthusiasts, Athletes, Dietary Supplements, Nutraceutical Companies Application: Muscle Recovery, Performance Enhancement, Weight Management, Cognitive Function Distribution Channel: Online Retail, Specialty Stores, Pharmacy Chains, Direct Sales |
| Companies Covered | Natural Alternatives International, Anhui Huaheng Biotechnology, NOW Foods, Merck KGaA, Zibo Haolong Biotechnology, Wuhan Microsen Technology, ALLMAX Nutrition, Shandong Yangcheng Biotech, NutraBlend Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Beta-Alanine Market Trends and Innovations
Sustained-release delivery technologies are fragmenting competitive advantage away from commodity purity metrics toward pharmacokinetic performance claims in pre-workout formulations.
Microencapsulation via lipid-matrix coating is absorbing market preference among sports nutrition formulators seeking reduced paresthesia onset without dose reduction. Tier-one contract manufacturers in the United States are specifying coated beta-alanine for 40% of new pre-workout launches. This absorption of delivery-technology premiums is compressing margins for uncoated powder suppliers locked into bulk ingredient contracts.
EFSA's evolving position on amino acid novel food assessments is tightening purity documentation requirements for European market entry. Suppliers must now submit batch-level heavy metal certificates exceeding baseline food additive standards. Sports nutrition brands exporting into Germany and France are reformulating around certified-beta-alanine-only supply chains to preempt border rejection risks.
Buyer concentration among merged mid-size supplement brands is consolidating procurement decisions into centralized sourcing committees. Direct supplier relationships are displacing distributor intermediaries for volumes exceeding 50 metric tons annually. This pattern is most visible in United States coastal clusters where functional beverage startups aggregate demand through shared manufacturing facilities.
Food Grade Beta-Alanine Market Segmentation
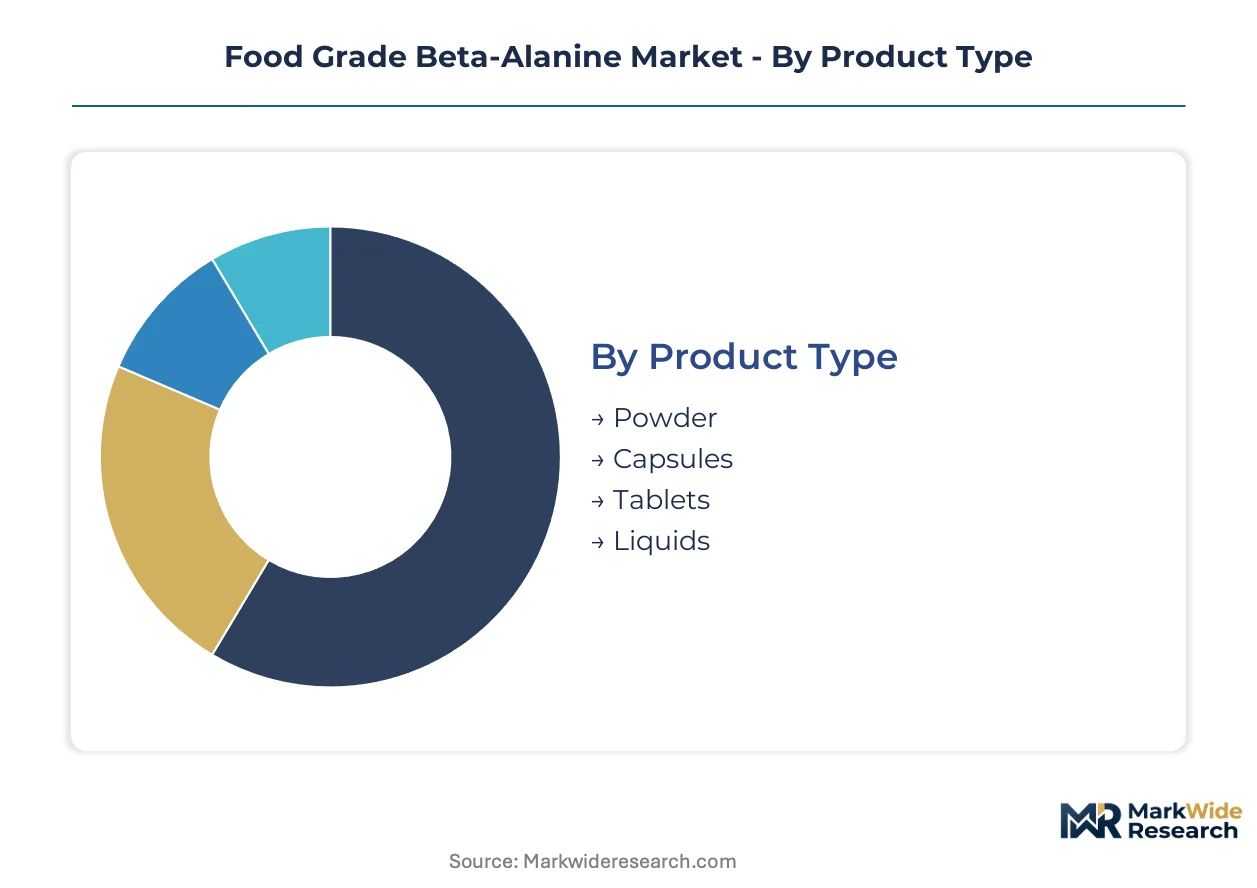
Food grade beta-alanine procurement patterns diverge sharply between bulk powder commodity contracts and value-added delivery formats. Segment boundaries determine margin capture, with sustained-release technologies commanding premium positioning against standard powder specifications.
Product Type:
Powder formulations dominate absolute volume shipments while coated and encapsulated variants extract pricing premiums through pharmacokinetic differentiation.
- Powder:Standard crystalline beta-alanine at minimum 98.5% purity ships in bulk to contract manufacturers and sports nutrition blenders. United States functional beverage producers aggregate multi-ton procurement through shared manufacturing facilities in coastal clusters.
- Capsules:Hard-shell gelatin and vegetable cellulose formats target direct-to-consumer subscription channels with precise dosing convenience. Specialty formulators in nootropic stacks specify capsules for cognitive function positioning outside traditional sports nutrition.
- Tablets:Compressed formulations with binding agents suit pharmacy chain distribution requiring shelf-stable unit dosing. European retailers under EFSA novel food assessments favor tablet formats for clean-label certification compliance.
- Liquids:Ready-to-drink suspensions and concentrated drops serve functional beverage innovation pipelines seeking rapid absorption claims. Limited thermal stability constrains widespread adoption beyond niche pre-workout shot applications.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquids.
End User:
Procurement authority concentrates in institutional buyers while individual consumption patterns fragment across performance-oriented demographics.
- Nutraceutical Companies:Integrated formulation houses negotiate multi-year supply agreements with purity guarantees exceeding 99%. Merged mid-size supplement brands centralize sourcing committees and displace distributor intermediaries for volumes above 50 metric tons annually.
- Athletes:Elite and professional competitors drive specification of pharmaceutical-grade crossover standards with USP heavy metal validation protocols. Olympic training facilities and collegiate athletic programs command certified-beta-alanine-only supply chains.
- Fitness Enthusiasts:Recreational gym-goers and CrossFit participants sustain mass-market powder consumption through e-commerce subscription models. Social media influencer partnerships accelerate trial conversion in this segment.
- Dietary Supplements:Broad wellness positioning targets aging populations seeking carnosine precursor benefits for cellular health claims. Formulation rates remain below sports nutrition applications due to paresthesia tolerance limitations.
Volume leadership belongs to Nutraceutical Companies. Margin expansion concentrates in Athletes.
Application:
Performance claims anchor commercial demand while emerging therapeutic positioning reshapes R&D allocation.
- Performance Enhancement:Pre-workout pH buffering formulations specify beta-alanine inclusion rates of 3.2g per serving for saturation dosing. Tier-one United States contract manufacturers now require coated variants for 40% of new launches to reduce paresthesia onset.
- Muscle Recovery:Post-exercise carnosine synthesis support targets endurance athletes with repeat-dose protocols. Clinical validation gaps constrain premium pricing relative to established performance enhancement claims.
- Cognitive Function:Nootropic stack integration represents the segment climbing fastest among specialty formulators seeking differentiation from saturated sports nutrition shelves. SAMR registration timelines in China delay market access for cognitive positioning claims.
- Weight Management:Thermogenic and appetite modulation applications remain speculative with limited mechanistic evidence. Formulator interest concentrates in combination products rather than standalone beta-alanine positioning.
Established deployment centers on Performance Enhancement. Experimental deployment concentrates in Cognitive Function.
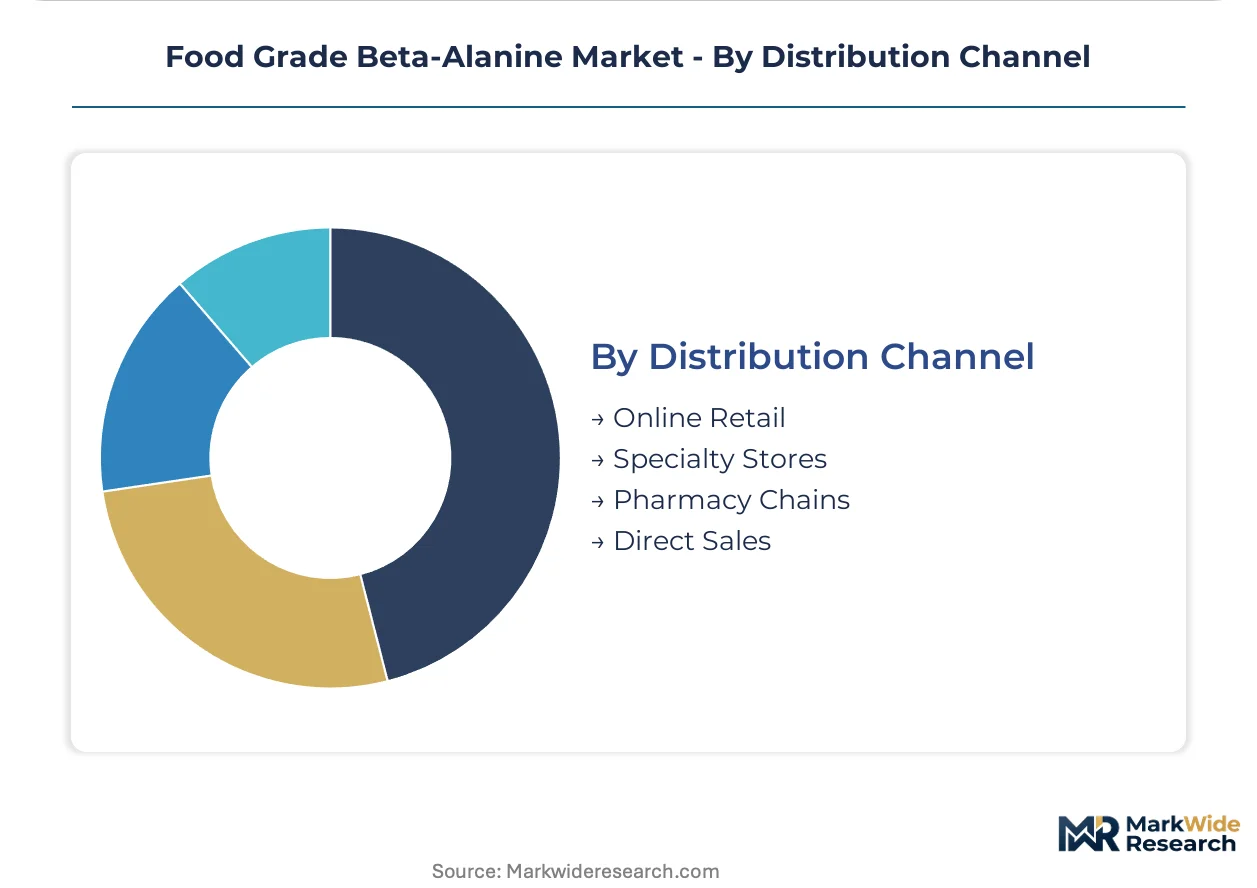
Distribution Channel:
Channel strategy determines margin capture with direct relationships compressing intermediary costs.
- Online Retail:Amazon, direct-to-consumer brand sites, and subscription wellness platforms aggregate fragmented individual demand. Branded ingredient partnerships bypass contract manufacturer margin compression through vertical channel control.
- Specialty Stores:GNC, Vitamin Shoppe, and independent supplement retailers provide tactile evaluation for sustained-release format differentiation. Staff training investments correlate with coated beta-alanine attachment rates.
- Pharmacy Chains:CVS, Walgreens, and Rite Aid shelf placement requires FDA food additive regulation compliance documentation exceeding baseline standards. Unit-dose packaging specifications add cost burden relative to bulk formats.
- Direct Sales:Multi-level marketing networks and practitioner-exclusive lines serve personalized protocol markets with higher per-unit economics. Recruitment and retention costs offset margin advantages in this channel.
Scale concentration sits with Online Retail. Relationship-dependent deployment concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-growing regions in the United States Midwest anchor feedstock supply for fermentation-based beta-alanine production. Manufacturing clusters concentrate near these agricultural inputs and adjacent to functional beverage formulators.
United States
Functional beverage startups in California and New York coastal clusters aggregate multi-ton procurement through shared contract manufacturing facilities. FDA food additive regulations enforce stricter heavy metal thresholds than competing jurisdictions, favoring suppliers with USP-grade analytical capabilities. Tier-one contract manufacturers now specify coated beta-alanine for 40% of new pre-workout launches to reduce paresthesia onset.
China
Integrated fermentation capacity in Shandong and Anhui provinces supplies global powder volumes through microbial production routes. SAMR novel food ingredient approvals extend market access timelines beyond fermentation capacity lead times, delaying cognitive function positioning claims. Zibo and Wuhan biotech clusters compete on scale economies while navigating agricultural commodity input volatility.
Germany
EFSA novel food assessments in the European Union tighten purity documentation requirements for amino acid additives entering German and French markets. Sports nutrition brands headquartered in Bavaria and North Rhine-Westphalia reformulate around certified-beta-alanine-only supply chains to preempt border rejection risks. Clean-label certification pathways accelerate premium-grade qualification for functional beverage applications.
India
FSSAI evolving amino acid additive standards create first-mover advantages for suppliers achieving dual FDA-FSSAI certification. Nutraceutical contract manufacturers in Maharashtra and Gujarat centralize procurement decisions as merged mid-size supplement brands aggregate volume commitments. Import pathway optimization remains critical for cross-border ingredient trade eligibility.
Japan
PMDA pharmaceutical-grade standards extend into food-grade applications, demanding analytical chemists capable of executing heavy metal validation protocols. METI industrial policy supports precision fermentation investments in the Kanto and Kansai regions. Domestic formulators prioritize sustained-release delivery technologies for aging population wellness positioning.
Food Grade Beta-Alanine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cognitive function and nootropic stack differentiation outside traditional sports nutrition. The vendor base stratifies across fermentation specialists, chemical synthesis operators, and delivery-technology licensors. Three archetypes dominate: integrated Chinese fermenters with captive agricultural inputs, European pharmaceutical-grade crossovers leveraging analytical superiority, and patented sustained-release technology holders extracting premium positioning. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as procurement consolidation compresses commodity margins.
Within the technology-licensing tier, Natural Alternatives International exemplifies premium positioning through proprietary sustained-release patents that lock in sports nutrition contracts. Anhui Huaheng Biotechnology and Shandong Yangcheng Biotech represent the integrated Chinese fermentation archetype, anchoring Asian supply chains through microbial production scale. Merck KGaA occupies the pharmaceutical-grade crossover position, extending analytical chemist capabilities from drug applications into food-grade purity validation protocols.
| Leading Market Players |
|---|
| Natural Alternatives International |
| Anhui Huaheng Biotechnology |
| NOW Foods |
| Merck KGaA |
| Zibo Haolong Biotechnology |
| Wuhan Microsen Technology |
| ALLMAX Nutrition |
| Shandong Yangcheng Biotech |
| NutraBlend Foods |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement among merged mid-size supplement brands is forcing fermentation-scale investments and multi-year purity guarantees that compress commodity margins while elevating premium-tier pricing power for patented delivery technologies.
Pricing Analysis
Multi-year purity guarantees bundled with batch-level heavy metal certificates anchor premium pricing for suppliers serving FDA-regulated United States functional beverage producers, while uncoated powder contracts trade on spot-market volatility without service attachments. Three-tier pricing structure across sustained-release premium, certified-standard, and uncoated-economy levels reflects pharmacokinetic differentiation and regulatory documentation burden. Pricing pressure stems from corn-derived feedstock volatility squeezing integrated Chinese fermenters. Nutraceutical companies with centralized sourcing committees above 50 metric tons annually exhibit lowest price sensitivity; individual fitness enthusiasts through e-commerce subscriptions show highest elasticity.
Supply Chain Analysis
Regional distribution centers in United States coastal clusters operate hub-and-spoke patterns feeding shared contract manufacturing facilities, while bulk powder shipments from Shandong and Anhui provinces in China bypass intermediaries for volumes exceeding 50 metric tons. Corn feedstock from United States Midwest agricultural regions and glucose substrates from Chinese grain processing centers constitute primary fermentation inputs. Single-source vulnerability concentrates in Shandong fermentation capacity serving global powder demand. Distribution runs through direct supplier relationships displacing distributor intermediaries for institutional nutraceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as players pursue captive fermentation capacity to secure agricultural input control and defend margin position against procurement consolidation.
For Market Incumbents: Anticipate sustained-release patent estate challenges from emerging microencapsulation specialists by deepening analytical chemist recruitment for USP heavy metal validation protocols. Anchor capacity expansion in United States Midwest corn-growing regions to tighten feedstock cost control against Chinese fermenter price competition.
For New Entrants and Emerging Players: Direct-to-consumer subscription wellness platforms offer the most penetrable route for bypassing contract manufacturer margin compression and establishing branded ingredient recognition. Target cognitive function positioning in nootropic stacks outside saturated sports nutrition shelves, leveraging FSSAI dual-certification pathways for Indian market entry ahead of SAMR-registered competitors.
For Investors and Strategic Acquirers: The window for entry favors integrated fermentation specialists with captive agricultural inputs and analytical-grade certification capabilities. Watch for sustained-release technology licensing deal flow as inflection indicator of delivery-format commoditization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Feedstock | Captive agricultural supply from United States Midwest regions insulates fermentation margins against commodity volatility cycles. |
| Microencapsulation Technology Licensing | Lipid-matrix coating patents extract premium positioning from tier-one United States contract manufacturers specifying reduced paresthesia formats. |
| Dual FDA-FSSAI Certification Investment | First-mover qualification under India's evolving amino acid additive standards unlocks cross-border import eligibility ahead of competitors. |
| Direct-to-Consumer Channel Launch | Subscription wellness platform partnerships bypass consolidated nutraceutical procurement committees and preserve margin capture. |
| Analytical Chemist Capability Buildout | USP-grade heavy metal validation protocols satisfy FDA food additive thresholds exceeding baseline chemical synthesis achievement. |
Research Methodology
Independent corroboration across primary interviews with sports nutrition formulators, contract manufacturing procurement leads, fermentation plant managers, and regulatory affairs specialists, combined with secondary validation through FDA food additive filings, EFSA novel food assessment databases, FSSAI notification records, and SAMR registration timelines, underwrites the qualitative findings. Bottom-up volume triangulation against top-down value estimates ensures cross-verification.
Rate-of-change decomposition across the analysis window segments growth by product type, end user archetype, application claim, and distribution channel, with CAGRs derived from regression against historical procurement patterns and forward-looking purity standard trajectories. Fermentation capacity expansion schedules and sustained-release technology adoption curves inform projection boundaries.
The model holds under stable agricultural commodity input costs and regulatory assessment timelines; deviation in corn price volatility or SAMR approval delays would shift capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Effervescent Product Market