
 Global Ashwagandha Extract Market | 2026-2036
Global Ashwagandha Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ashwagandha Extract Market Analysis
India is reshaping upstream supply dynamics through expanded cultivation in Madhya Pradesh and Rajasthan. Ixoreal Biomed leverages KSM-66 branded extract technology to sustain premium positioning in sports nutrition. Sabinsa Corporation anchors botanical extraction expertise across multiple adaptogen categories. Himalaya Wellness Company competes through integrated Ayurvedic heritage and pharmacy channel control.
Ashwagandha extract comprises bioactive withanolides, primarily withaferin A and withanolide D, standardized typically to 2.5–5% concentration through solvent or supercritical CO2 extraction for use in dietary supplements and functional foods. Powder formulations dominate volume throughput due to blending flexibility in finished products, while liquid extracts command higher margins in clinical and wellness-center channels. Stress relief applications lead consumer pull, with sleep aid and cognitive function segments showing faster trajectory in e-commerce direct-to-consumer flows.
FDA New Dietary Ingredient notifications, EFSA novel food assessments, and India's FSSAI quality standards collectively determine market access timelines and label claim permissibility across major demand centers. The EU Green Deal's botanical sustainability criteria are beginning to filter into procurement specifications for European supplement brands. Stakeholders must monitor evolving pharmacovigilance requirements as adaptogen categories attract heightened regulatory scrutiny.
Market Dynamics
Standardization of withanolide content through supercritical CO2 extraction is compressing batch-to-batch variability and forcing solvent-based processors to upgrade equipment or exit contract manufacturing.
Growth Catalysts
- Sports nutrition embedding:Pre-workout and recovery formulations now incorporate adaptogenic extracts as performance claims shift from stimulant-driven to stress-modulation positioning.
- FDA NDI pathway maturation:The notification framework for New Dietary Ingredients has created predictable entry timelines for extract suppliers targeting US direct-to-consumer channels.
- India cultivation expansion:Madhya Pradesh and Rajasthan field acreage is extending raw material availability beyond traditional Karnataka and Andhra Pradesh clusters.
Market Restraints
- Withanolide assay volatility:Root age, soil chemistry, and harvest timing create 15-40% bioactive variance, forcing processors to over-purchase raw material to hit label claims.
- Single-origin concentration:Over 70% of cultivated supply originates from Indian subcontinent contract farms, exposing buyers to monsoon failure and export documentation friction.
- Pharmacovigilance escalation:EMA's emerging adaptogen surveillance framework is extending safety dossier requirements and delaying novel food approvals for non-traditional delivery formats.
Strategic Opportunities
- Brazil regulatory opening:ANVISA's simplified botanical registration pathway for traditional medicines is creating first-mover positioning for extractors establishing local analytical partnerships.
- Personalized nutrition convergence:DNA-based stress-response profiling paired with adaptogen dosing algorithms is virtualizing product selection in telehealth subscription models.
- EU Green Deal procurement filters:Sustainability certification requirements are favoring extractors with verified organic cultivation and carbon-accounted processing infrastructure.
Industry Challenges
- Phytochemical standardization expertise gap:Analytical chemists capable of validating withaferin A versus withanolide D ratios in complex matrices command 40% salary premiums over general HPLC technicians.
- Dual certification burden:Simultaneous pursuit of USP dietary supplement verification and EFSA novel food status requires parallel toxicology studies, stretching R&D budgets across incompatible dossier formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ashwagandha Extract Market |
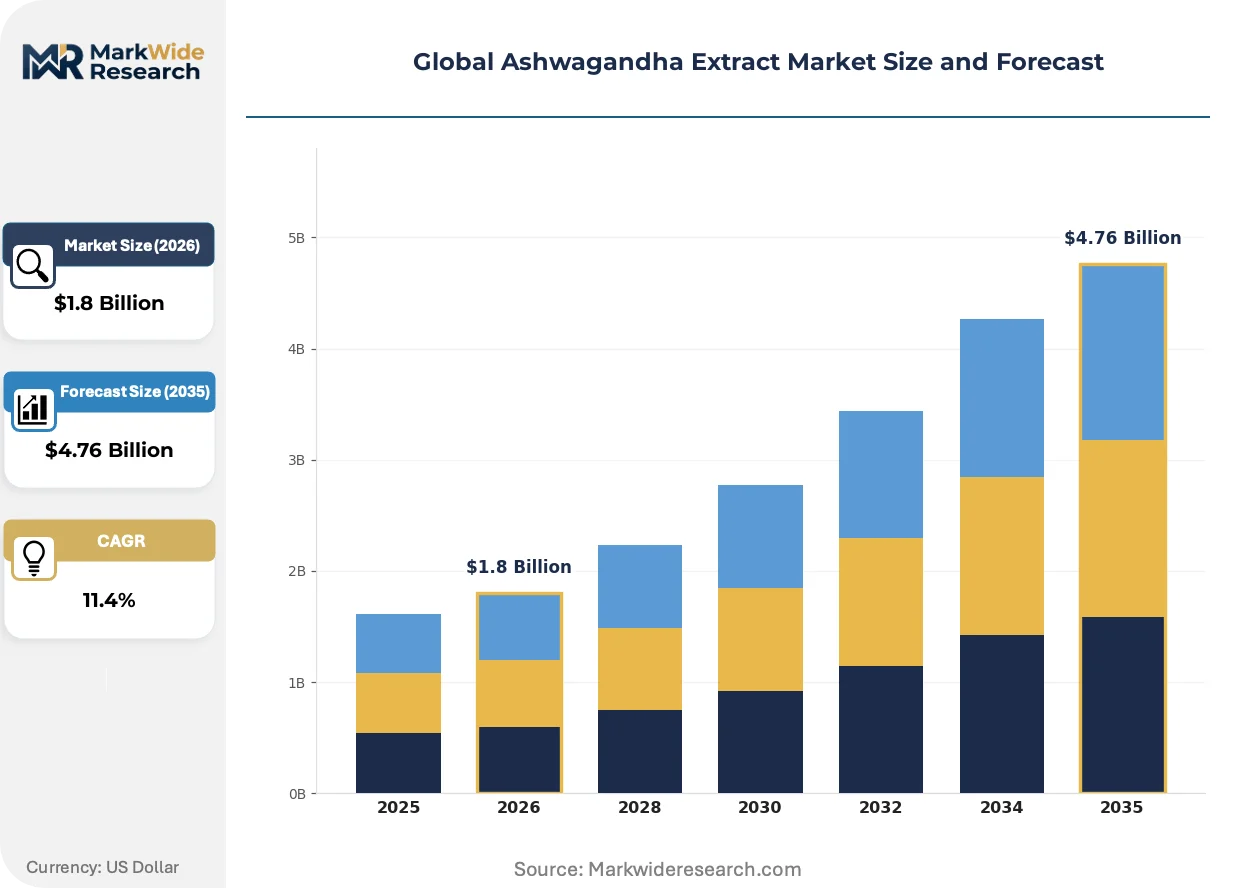
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tinctures, Liquid Extracts End User: Fitness Enthusiasts, Herbal Supplement Users, Wellness Centers, Pharmacies Application: Stress Relief, Sleep Aid, Cognitive Function, Immune Support Distribution Channel: Online Retail, Health Stores, Supermarkets, Direct Selling |
| Companies Covered | Ixoreal Biomed Inc., Natreon Inc., Arjuna Natural Pvt. Ltd., Sabinsa Corporation, Himalaya Wellness Company, Dabur India Ltd., Patanjali Ayurved Limited, Organic India Pvt. Ltd., Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ashwagandha Extract Market Emerging Trajectories
Extraction technology and regulatory science are converging to compress product development cycles while fragmenting quality tiers based on analytical rigor rather than origin branding alone.
Supercritical CO2 extraction with ethanol co-solvent modification is virtualizing the separation of withanolide fractions previously requiring sequential solvent partitioning. Sports nutrition contract manufacturers in Germany and California are adopting these systems to reduce residual solvent testing failures. The technology is compressing time-to-certificate-of-analysis from 14 days to 72 hours for premium-positioned extracts.
EFSA's novel food assessment backlog is forcing European brands to reformulate around existing ingredient approvals rather than pioneer new delivery formats. The industrial consequence is a freeze in gummy and beverage innovation while capsules and tablets dominate shelf space. German pharmacy chains are responding by private-labeling Indian-manufactured extracts with established safety dossiers rather than funding proprietary approval pathways.
Subscription-based direct-to-consumer models are displacing retail pharmacy as the primary volume channel for stress-relief positioning. Wellness platforms in the United States and United Kingdom are bundling ashwagandha with biometric tracking devices, shifting purchase decisions from ingredient sourcing transparency to perceived efficacy correlation. This behavioral pivot is most visible among urban millennials in London and New York metropolitan zones where telehealth integration drives 60-day auto-replenishment rates above 45%.
Global Ashwagandha Extract Market Segmentation
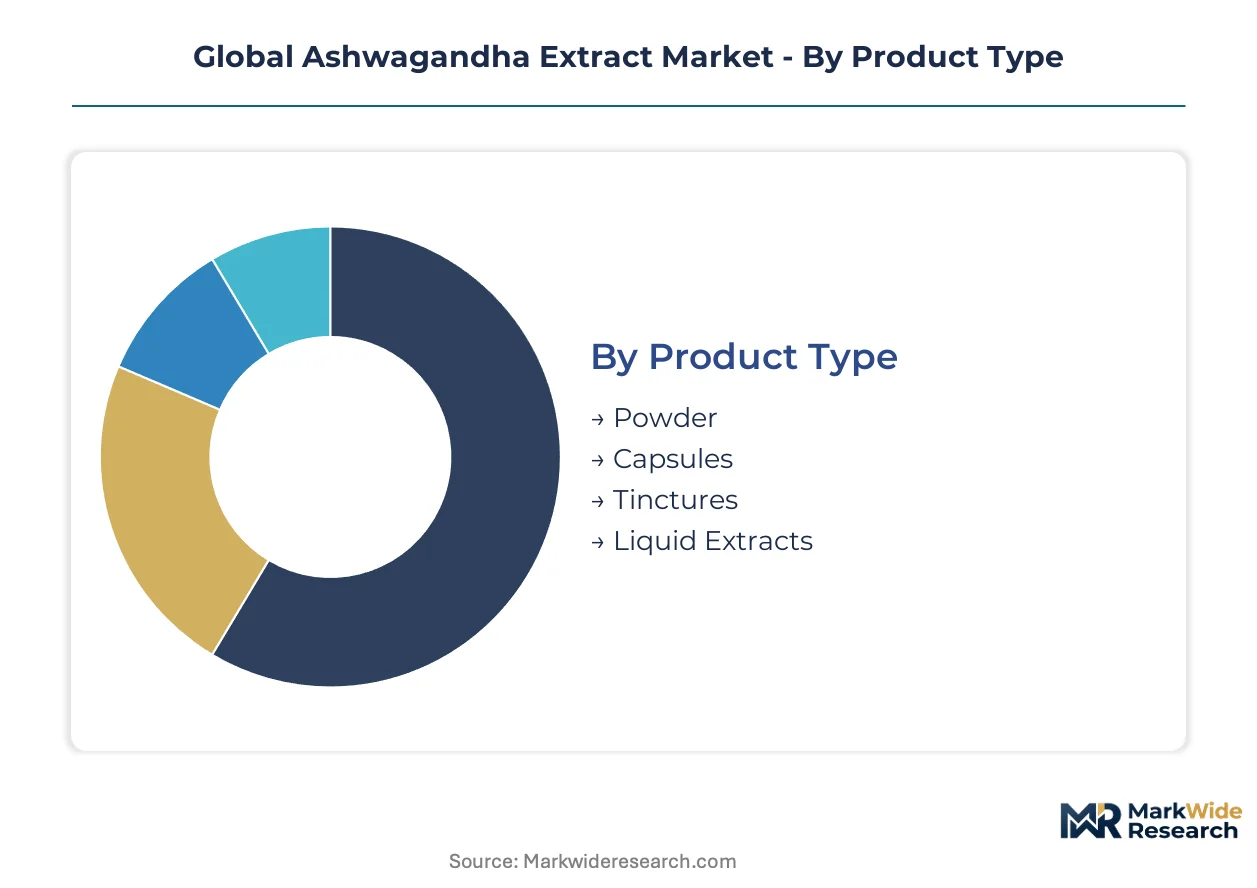
Ashwagandha extract markets fragment across four distinct dimensions. Product form determines manufacturing complexity and margin structure. End-user identity shapes channel selection and dosing format preferences. Application positioning drives regulatory pathway requirements and label claim permissibility.
Product Type:
Powder formulations turn inventory fastest through bulk ingredient trading, while liquid extracts sit longest in quality assurance queues awaiting withanolide assay certification.
- Powder:Standardized to 2.5-5% withanolide content through solvent or supercritical CO2 extraction. Sports nutrition contract manufacturers in Germany and California blend this into pre-workout matrices, with batch-to-batch variability compressing as CO2 systems displace legacy solvent infrastructure.
- Capsules:Encapsulated powder or standardized extract in gelatin or vegetable shells. Direct-to-consumer subscription platforms in the United States and United Kingdom favor this format for telehealth bundle integration, where 60-day auto-replenishment rates exceed 45% among urban millennials.
- Tinctures:Alcohol-based liquid preparations with extended shelf stability. Wellness centers in London metropolitan zones stock these for personalized dosing protocols.
- Liquid Extracts:Glycerin or aqueous solutions with rapid absorption profiles. Clinical channels command premium positioning here, though EFSA novel food assessment backlogs freeze beverage innovation.
Powder dominates installed base. Liquid extracts are where expansion concentrates.
End User:
Cost tier stratification separates mass-market accessibility from premium clinical positioning, with subscription economics displacing traditional pharmacy margin structures.
- Fitness Enthusiasts:Pre-workout and recovery formulation demand concentrates here. Ixoreal Biomed's KSM-66 branded extract technology anchors premium positioning in this segment through sports nutrition embedding.
- Herbal Supplement Users:Traditional Ayurvedic consumers seeking root-to-extract traceability. India's FSSAI quality standards and US FDA NDI notifications shape their purchase confidence.
- Wellness Centers:Clinical and spa channels requiring certificate-of-analysis documentation. Supercritical CO2 extraction compresses their time-to-COA from 14 days to 72 hours.
- Pharmacies:German pharmacy chains now private-label Indian-manufactured extracts with established safety dossiers rather than funding proprietary EFSA approval pathways.
Herbal supplement users anchor volume throughput. Fitness enthusiasts are climbing the fastest.
Application:
Volume concentration varies sharply by claim permissibility, with stress relief holding broadest regulatory acceptance while cognitive function faces steepest pharmacovigilance escalation.
- Stress Relief:The foundational positioning with widest label claim acceptance across FDA, EFSA, and India's FSSAI frameworks. E-commerce direct-to-consumer flows concentrate here.
- Sleep Aid:Faster trajectory in subscription models paired with biometric tracking devices. Telehealth integration in New York and London metropolitan zones drives format innovation.
- Cognitive Function:EMA's emerging adaptogen surveillance framework extends safety dossier requirements. Novel food approvals for non-traditional delivery formats face delays.
- Immune Support:Post-pandemic residual demand with tighter evidentiary thresholds. European brands reformulate around existing ingredient approvals rather than pioneer new formats.
Stress relief commands installed base. Sleep aid is gaining share fastest.
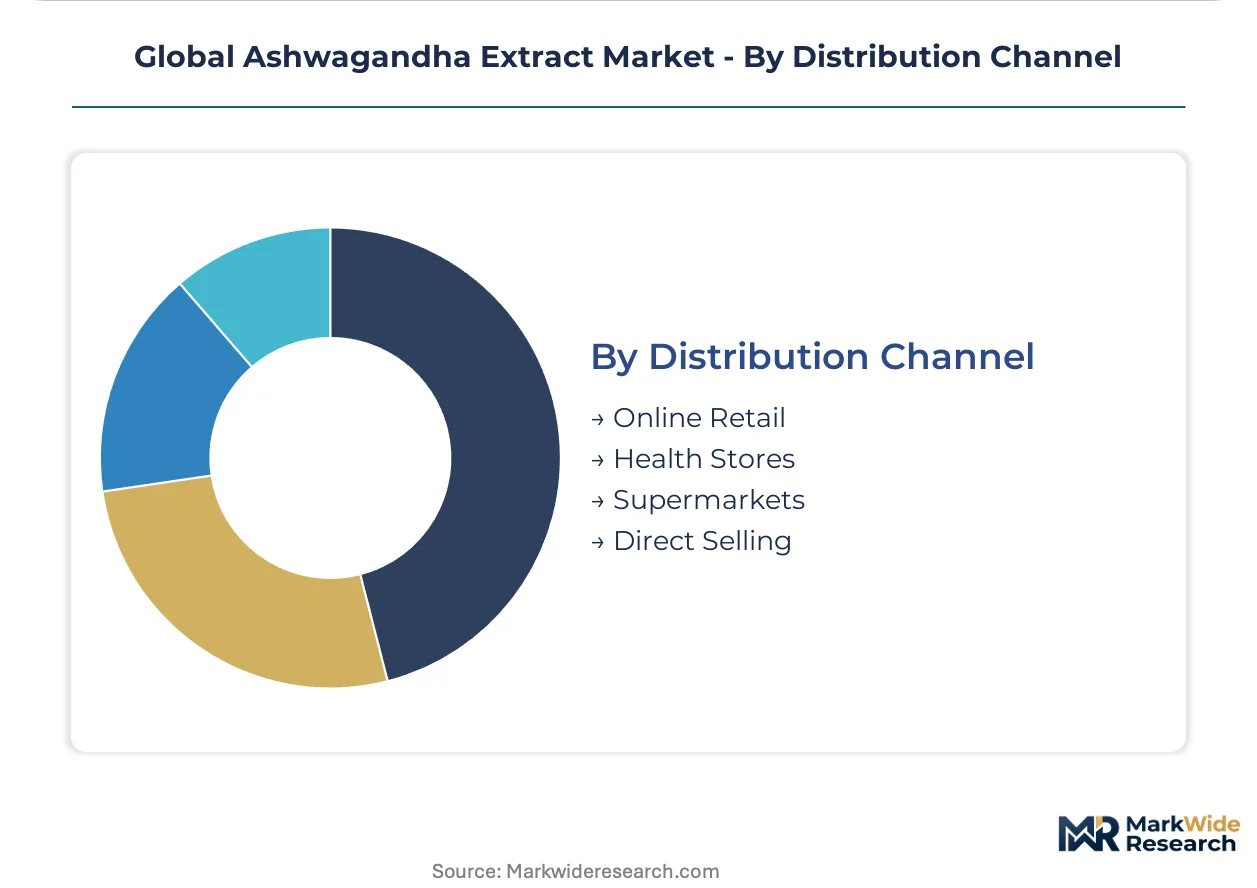
Distribution Channel:
Customer type migration from retail pharmacy to platform-mediated subscription is restructuring margin capture and working capital requirements.
- Online Retail:Primary volume channel for stress-relief positioning. Wellness platforms bundle ashwagandha with biometric tracking devices, shifting purchase decisions from sourcing transparency to perceived efficacy correlation.
- Health Stores:Specialty retailers with trained staff explaining withaferin A versus withanolide D differentiation. Staff expertise commands 40% salary premiums over general supplement retail.
- Supermarkets:Mass-market penetration with standardization to lowest common denominator specifications. Powder sachets dominate this channel.
- Direct Selling:Multi-level marketing with Ayurvedic heritage storytelling. Himalaya Wellness Company competes here through integrated pharmacy channel control.
Online retail dominates installed base. Health stores are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's New Dietary Ingredient notification pathway anchors United States market access, while EFSA novel food assessments and India's FSSAI standards shape procurement timelines across other major demand centers. Regulatory divergence is fragmenting product development cycles by geography.
United States
Direct-to-consumer subscription platforms concentrate volume throughput in New York and Los Angeles metropolitan zones. FDA NDI notifications create predictable entry timelines for extract suppliers targeting wellness platforms. California-based sports nutrition contract manufacturers are adopting supercritical CO2 extraction systems to compress certificate-of-analysis turnaround.
Germany
German pharmacy chains now private-label Indian-manufactured extracts with established safety dossiers rather than funding proprietary EFSA approval pathways. EMA's emerging adaptogen surveillance framework extends safety dossier requirements for novel delivery formats. Berlin and Munich wellness centers command premium positioning for liquid extract formulations.
India
Madhya Pradesh and Rajasthan field acreage is extending raw material availability beyond traditional Karnataka and Andhra Pradesh cultivation clusters. FSSAI quality standards determine export documentation friction for contract farms. Hyderabad and Bengaluru processing facilities anchor supercritical CO2 extraction capacity expansion.
United Kingdom
London metropolitan zones drive 60-day auto-replenishment rates above 45% through telehealth-integrated subscription models. EFSA novel food assessment backlogs freeze gummy and beverage innovation while capsules dominate shelf space. Manchester health stores command 40% salary premiums for staff explaining withaferin A versus withanolide D differentiation.
Brazil
ANVISA's simplified botanical registration pathway for traditional medicines is creating first-mover positioning for extractors establishing local analytical partnerships. São Paulo wellness platforms are bundling ashwagandha with biometric tracking devices. Rio de Janeiro pharmacy chains are adopting Indian-manufactured extracts with verified organic cultivation certification.
Global Ashwagandha Extract Market Vendor Landscape
Branded-technology specialists and integrated Ayurvedic heritage players split the market between premium sports nutrition positioning and pharmacy channel control. The vendor base concentrates around extraction technology differentiation and regulatory dossier depth rather than raw material scale alone. Three archetypes dominate: KSM-66 type branded extract licensors, vertically integrated wellness companies with pharmacy networks, and contract manufacturers with supercritical CO2 infrastructure. Competitive moves center on EFSA novel food dossier accumulation and ANVISA registration partnerships.
Among India-based integrated players, Ixoreal Biomed Inc., Himalaya Wellness Company, and Dabur India Ltd. exemplify divergent positioning strategies. Ixoreal Biomed occupies the branded-technology tier through KSM-66 extract licensing. Himalaya Wellness Company anchors pharmacy channel control through integrated Ayurvedic heritage and retail network density. Dabur India Ltd. sits within the mass-market accessibility tier leveraging established distribution infrastructure across domestic and export markets.
| Leading Market Players |
|---|
| Ixoreal Biomed Inc. |
| Natreon Inc. |
| Arjuna Natural Pvt. Ltd. |
| Sabinsa Corporation |
| Himalaya Wellness Company |
| Dabur India Ltd. |
| Patanjali Ayurved Limited |
| Organic India Pvt. Ltd. |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
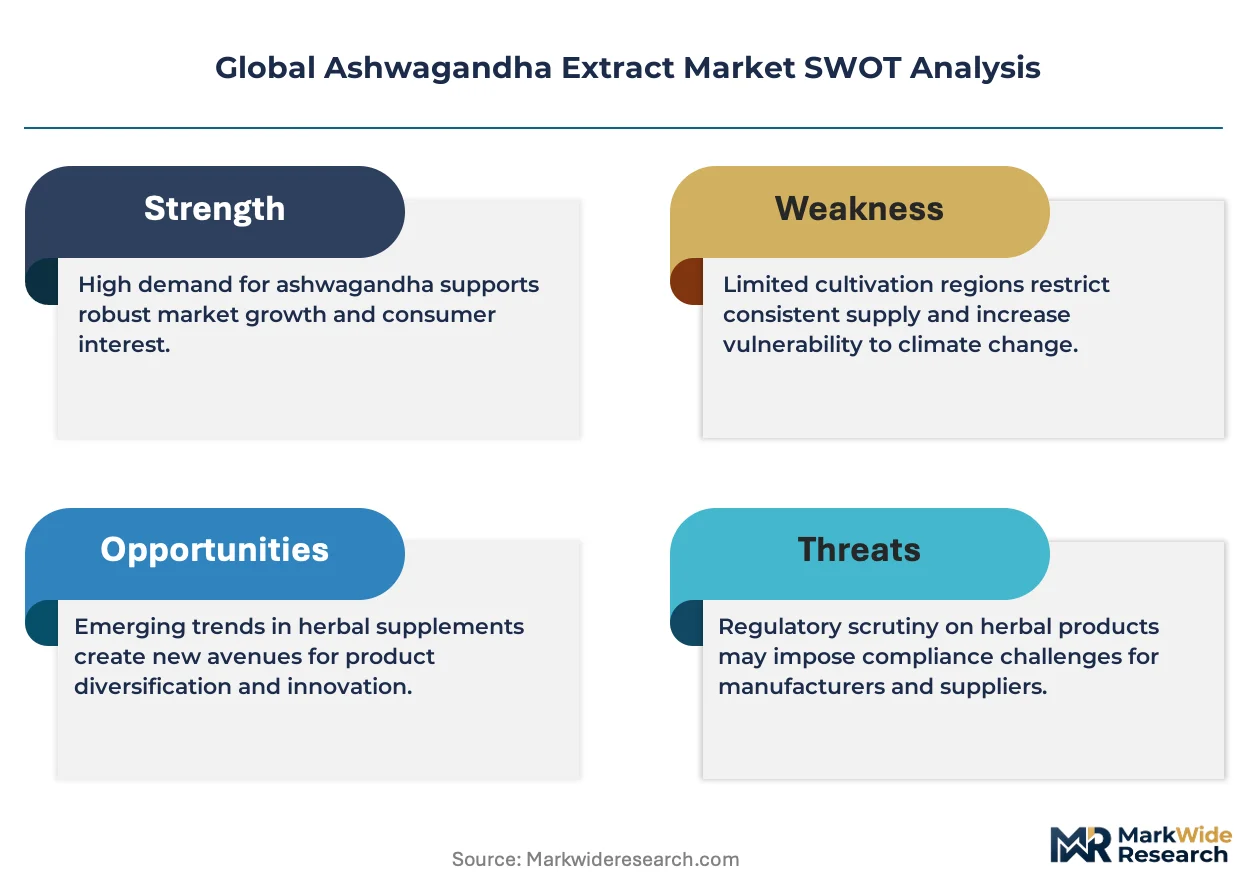
Single-origin concentration in Indian subcontinent cultivation exposes pricing power to monsoon failure and export documentation friction, compressing margin spreads between premium supercritical CO2 extracts and solvent-based commodity grades while forcing buyers to over-purchase raw material to hit label claims. This geographic chokepoint simultaneously widens tier differentials and reshapes procurement toward verified organic certification and carbon-accounted processing infrastructure.
Pricing Analysis
Geographic price spreads separate German wellness-center premiums from Indian contract-farm commodity baselines by factors reflecting certification depth and extraction technology. Three-tier pricing structure across premium, standard, and economy levels stratifies by withanolide assay precision, organic cultivation verification, and supercritical CO2 versus solvent processing. Pricing pressure stems from EFSA novel food assessment backlogs freezing gummy and beverage innovation while capsule formats commoditize. Fitness enthusiasts through sports nutrition channels show least price sensitivity; mass-market supermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock from Madhya Pradesh and Rajasthan field acreage extends beyond traditional Karnataka and Andhra Pradesh clusters, though over 70% of cultivated supply remains Indian subcontinent dependent. Root age, soil chemistry, and harvest timing create bioactive variance forcing processors to over-purchase raw material. Distribution runs through direct-to-consumer subscription platforms displacing retail pharmacy, with Berlin and Los Angeles metropolitan zones anchoring premium liquid extract demand. Single-source vulnerability concentrates around monsoon-dependent field operations and FSSAI export documentation friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction maturation constitutes a technological inflection compressing certificate-of-analysis turnaround from 14 days to 72 hours, enabling premium positioning that disrupts legacy solvent-based processors.
For Market Incumbents: Entrench analytical chemist capabilities validating withaferin A versus withanolide D ratios, as 40% salary premiums for this expertise create scarcity barriers against commodity competitors. Accumulate EFSA novel food dossiers for capsule and tablet formats while gummy innovation remains frozen. Backward integration into Madhya Pradesh organic cultivation secures raw material priority access against monsoon volatility. For New Entrants and Emerging Players: Establish a beachhead in Brazilian wellness platforms through ANVISA's simplified botanical registration pathway for traditional medicines, where first-mover positioning awaits extractors with local analytical partnerships. Target London and New York metropolitan telehealth subscription models bundling ashwagandha with biometric tracking devices. Lead with DNA-based stress-response profiling paired with adaptogen dosing algorithms as virtualized product selection differentiator. For Investors and Strategic Acquirers: FDA NDI notification pathway maturation reshapes the acquisition landscape toward extract suppliers with predictable US entry timelines and established safety dossiers. Five-to-ten year viability favors branded-technology specialists with KSM-66 type extract licensing over undifferentiated commodity processors. Signal to watch: EMA adaptogen surveillance framework implementation extending safety dossier requirements and accelerating consolidation around dossier-rich incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Compresses batch-to-batch variability and displaces legacy solvent infrastructure in California and German contract manufacturing. |
| EFSA Novel Food Dossier Accumulation | Freezes out gummy and beverage competitors while capsule formats dominate German pharmacy private-label sourcing. |
| ANVISA Registration Partnership | Creates first-mover positioning in São Paulo wellness platforms through Brazil's simplified botanical pathway. |
| Telehealth Subscription Integration | Drives 60-day auto-replenishment rates above 45% among urban millennials in London and New York zones. |
| Organic Cultivation Certification | Meets EU Green Deal procurement filters favoring carbon-accounted processing infrastructure for European supplement brands. |
Methodological Framework
A standing panel of extraction technology directors, sports nutrition formulation scientists, regulatory affairs specialists at FDA and EFSA, and pharmacy chain procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA New Dietary Ingredient notification databases, EFSA novel food assessment registers, India's FSSAI quality standard filings, and customs trade documentation for ashwagandha root and extract shipments. Bottom-up cultivation acreage modeling triangulated against top-down supplement manufacturer demand surveys.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product form, end-user identity, application positioning, and distribution channel migration. CAGRs derived from weighted average of historical trajectory and technology diffusion curves for supercritical CO2 adoption. Industry-specific inputs included withanolide assay standardization rates and subscription platform auto-replenishment velocity by metropolitan zone.
Sensitivities concentrate around EMA adaptogen surveillance framework implementation timing, Indian monsoon failure frequency, and FDA NDI notification backlog fluctuations. Cross-checking against ANVISA registration throughput and German pharmacy private-label sourcing shifts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Global Nutraceuticals Product Market