
 DHA Oil Supplement Market | 2026-2036
DHA Oil Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
DHA Oil Supplement Market Outlook
EU EFSA health claim authorizations for maternal DHA intake is hardening quality benchmarks across the European supply base. DSM leverages captive algal fermentation capacity to sustain premium positioning in vegan DHA oils. BASF SE anchors industrial-scale fish-oil refining through its omega-3 technology platform. Aker BioMarine ASA competes via Antarctic krill traceability, differentiating its marine phospholipid DHA from standard ethyl ester alternatives.
DHA oil supplement denotes docosahexaenoic acid delivered in concentrated triglyceride, ethyl ester, or phospholipid forms, typically standardized to 200-600 mg DHA per serving unit through molecular distillation or enzymatic concentration. The ingredient serves primary commercial purpose in cognitive development, cardiovascular maintenance, and prenatal neural tissue formation. Natural product type leads volume share due to sustained consumer preference for marine-origin oils, while vegan DHA from Schizochytrium algae records the fastest expansion as plant-based dietary patterns reshape purchasing. Softgel delivery mode dominates pharmacy and mass-market channels for oxidation protection and dose precision.
EMA pharmaceutical guidelines and EU Novel Food catalog entries govern DHA oil purity thresholds and new source approvals across member states. FDA GRAS notifications and EPA fisheries sustainability rules shape US import eligibility and raw material traceability requirements. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade DHA specifications as classification decisions determine channel access and margin architecture.
Market Dynamics
EU EFSA health claim authorizations for maternal DHA intake are hardening quality benchmarks across the European supply base, forcing ingredient manufacturers to upgrade purity thresholds and documentation protocols to maintain channel access.
Growth Catalysts
- EFSA maternal health claim framework:Validated prenatal neural development benefits drive prescription-grade DHA adoption through pharmacy channels in Germany, France, and Italy.
- Algal fermentation technology:Vegan DHA from Schizochytrium algae expands addressable demand among plant-based dietary adherents and allergen-sensitive consumers.
- Heidelberg-Kiel manufacturing cluster:Pharmaceutical-grade DHA concentration in southern and northern Germany anchors regional supply security for EU pharmaceutical buyers.
Market Restraints
- Wild-catch fish oil volatility:Peruvian anchovy quota fluctuations and El Niño events destabilize marine triglyceride feedstock pricing.
- Antarctic krill supply concentration:Aker BioMarine's dominant krill harvesting position creates single-source dependency for phospholipid DHA variants.
- Novel Food catalog entry delays:EU approval timelines for new algal strains extend 18-24 months, blocking rapid product line extensions.
Strategic Opportunities
- Pediatric cognitive development applications:School-age children represent an underpenetrated segment beyond prenatal and infant nutrition.
- Direct-to-consumer subscription channels:Recurring revenue models bypass pharmacy margin compression and build consumer lifetime value.
- EU Green Deal bioeconomy incentives:Fermentation-based algal DHA qualifies for sustainable biotechnology funding and preferential procurement.
Industry Challenges
- Pharmacopeial-grade certification complexity:USP and EP monograph compliance requires dedicated analytical chemistry capabilities and extended stability testing.
- Oxidation protection engineering:Softgel encapsulation and nitrogen blanketing demand specialized equipment investments to prevent rancidity.
- Cross-border regulatory divergence:FDA GRAS notification requirements differ materially from EMA pharmaceutical guidelines, complicating multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DHA Oil Supplement Market |
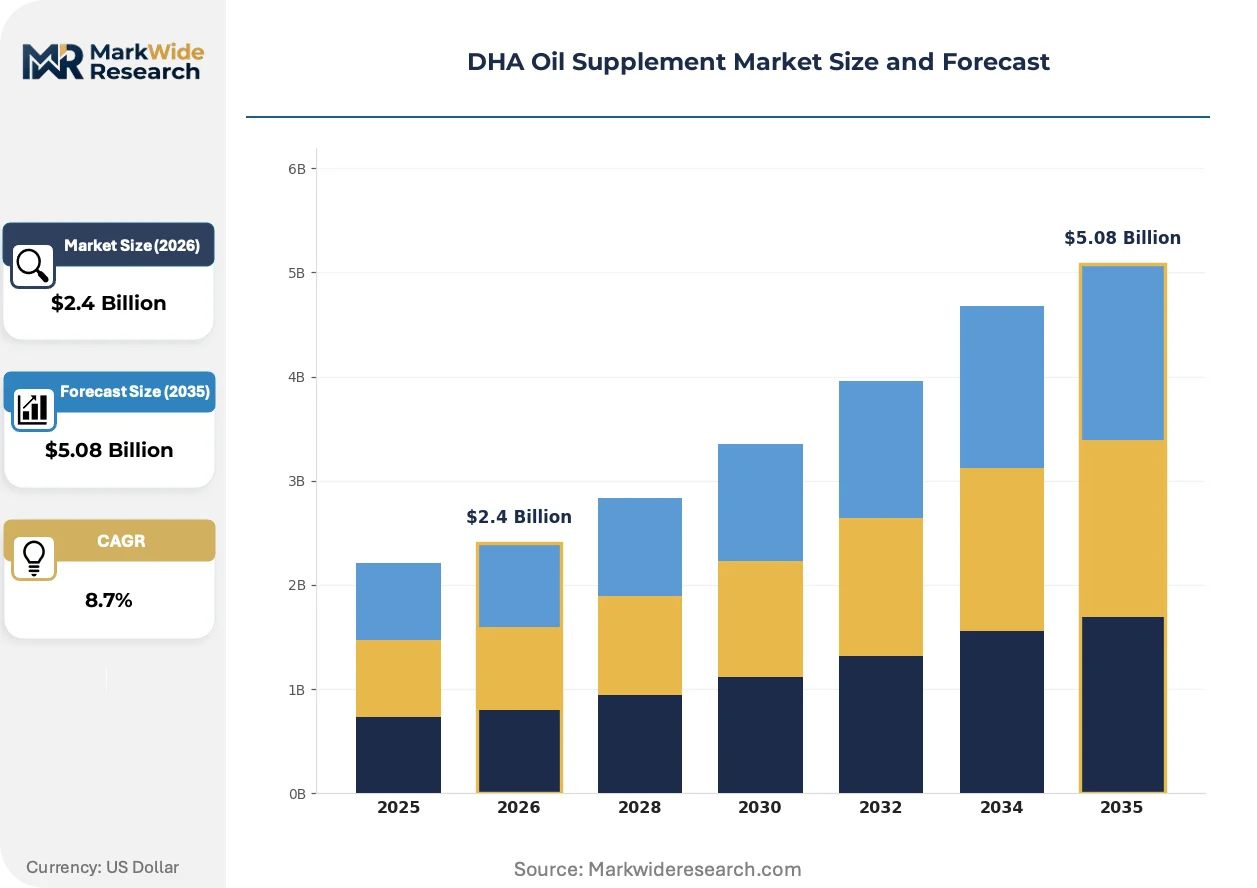
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Vegan, Fortified End User: Fitness Enthusiasts, Pregnant Women, Children, Elderly Delivery Mode: Capsules, Liquid, Softgels, Gummies Packaging Type: Bottles, Sachets, Blister Packs, Jars |
| Companies Covered | BASF SE, DSM, Croda International Plc, KD Pharma Group, Corbion, Aker BioMarine ASA, Clover Corporation, Omega Protein Corporation, Cellana Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DHA Oil Supplement Market Strategic Shifts
Fermentation-based production methods and regulatory harmonization efforts are restructuring how DHA oils are sourced, certified, and delivered to end-users across consumer health channels.
Enzymatic concentration technology is rewriting the economics of high-purity DHA extraction. This process selectively enriches docosahexaenoic acid content without thermal degradation of triglyceride structures. Premium supplement brands in Germany and the Netherlands are adopting enzymatic methods to support EFSA-compliant health claim substantiation. The shift is compressing reliance on molecular distillation and enabling cleaner label positioning.
EMA pharmaceutical guidelines governing DHA oil purity thresholds are tightening heavy metal and oxidation parameter limits across EU member states. Manufacturers must now demonstrate batch-level compliance with EP monograph specifications to access pharmacy distribution. German and French contract manufacturers are responding by installing in-house HPLC and GC-MS analytical capabilities rather than outsourcing testing.
Certification-driven purchasing behavior is reshaping procurement patterns among institutional buyers. Hospital formulary committees and maternal health clinics now require third-party sustainability verification alongside pharmacopeial documentation. This dual-credential requirement favors suppliers with Marine Stewardship Council or Friend of the Sea chain-of-custody certification, particularly in Nordic markets where public procurement rules embed environmental criteria.
DHA Oil Supplement Market Segmentation
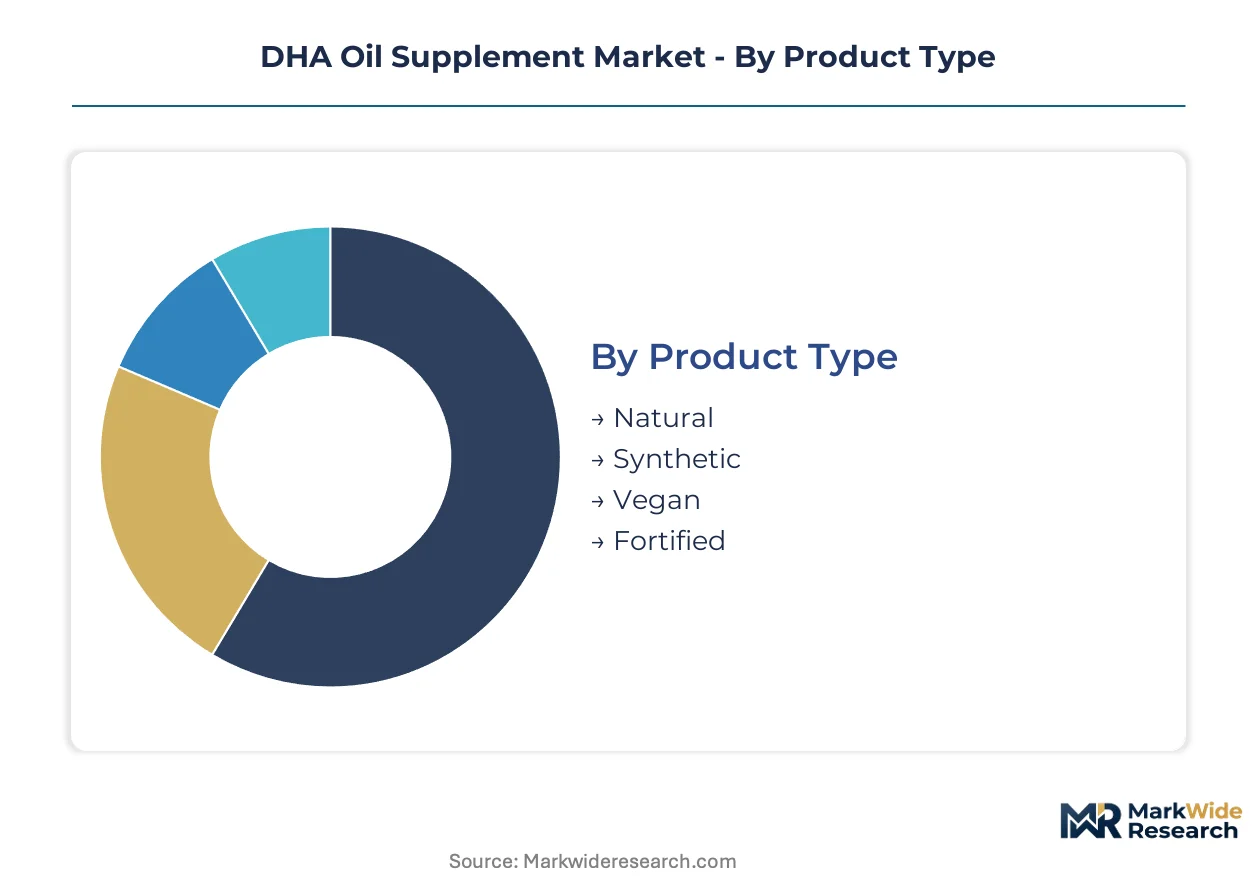
DHA oil supplement segmentation reveals how supply chain configuration and end-use requirements fragment manufacturing priorities. Product origin, delivery format, and target physiology each impose distinct purity thresholds and packaging investments that reshape competitive positioning across value tiers.
Product Type:
Supply concentration in marine-derived feedstocks anchors manufacturing economics, while algal fermentation capacity is redrawing sourcing geography.
- Natural:Marine-origin triglyceride concentrates standardized to 200-600 mg DHA per serving through molecular distillation. Demand concentrates in German pharmacy channels where EFSA maternal health claim compliance requires full traceability documentation. Peruvian anchovy and Antarctic krill fisheries dominate raw material procurement.
- Vegan:Schizochytrium algae fermentation yields phospholipid-bound DHA without marine allergens. German and Dutch brands are adopting enzymatic concentration methods to support premium positioning among plant-based dietary adherents. EU Green Deal bioeconomy incentives accelerate capacity expansion.
- Synthetic:Laboratory-synthesized ethyl ester forms serve industrial-scale fortification applications.
- Fortified:DHA-enriched carrier oils blended into functional food matrices.
Natural absorbs the bulk of installed capacity; Vegan is expanding most quickly.
End User:
Physiological life-stage requirements segment formulation complexity and channel access, with prenatal applications commanding strictest pharmacopeial certification.
- Pregnant Women:Prescription-grade DHA at 200-300 mg daily doses for neural tube development support. EFSA health claim authorizations validate prenatal benefits across Germany, France, and Italy, driving pharmacy-dispensed adoption. Heidelberg-Kiel manufacturing clusters anchor EU supply security.
- Children:School-age cognitive development represents underpenetrated demand beyond infant nutrition. Direct-to-consumer subscription models bypass pharmacy margin compression for this segment.
- Fitness Enthusiasts:Recovery and anti-inflammatory positioning drives sports nutrition channel placement.
- Elderly:Cardiovascular maintenance and cognitive preservation applications target geriatric care protocols.
Pregnant Women commands premium pricing tiers; Children offers steepest expansion trajectory for new entrants.
Delivery Mode:
Packaging technology investments separate pharmacy-grade oxidation protection from mass-market convenience formats.
- Softgels:Gelatin or plant-based shells with nitrogen blanketing prevent oxidative rancidity. German contract manufacturers have installed in-house HPLC and GC-MS capabilities to demonstrate EP monograph compliance batch-by-batch.
- Capsules:Two-piece hard shells accommodate powder or oil fill for dose flexibility. Demand concentrates in multipack retail formats where cost-per-unit sensitivity shapes purchasing.
- Liquid:Dropper bottles serve pediatric and elderly populations with swallowing difficulties.
- Gummies:Confectionery-format delivery expands palatability for children but requires stability engineering for DHA incorporation.
Softgels dominate pharmacy and mass-market channels; Gummies are climbing the fastest as palatability engineering improves.
Packaging Type:
Unit-dose versus bulk presentation aligns with consumption setting and regulatory documentation requirements.
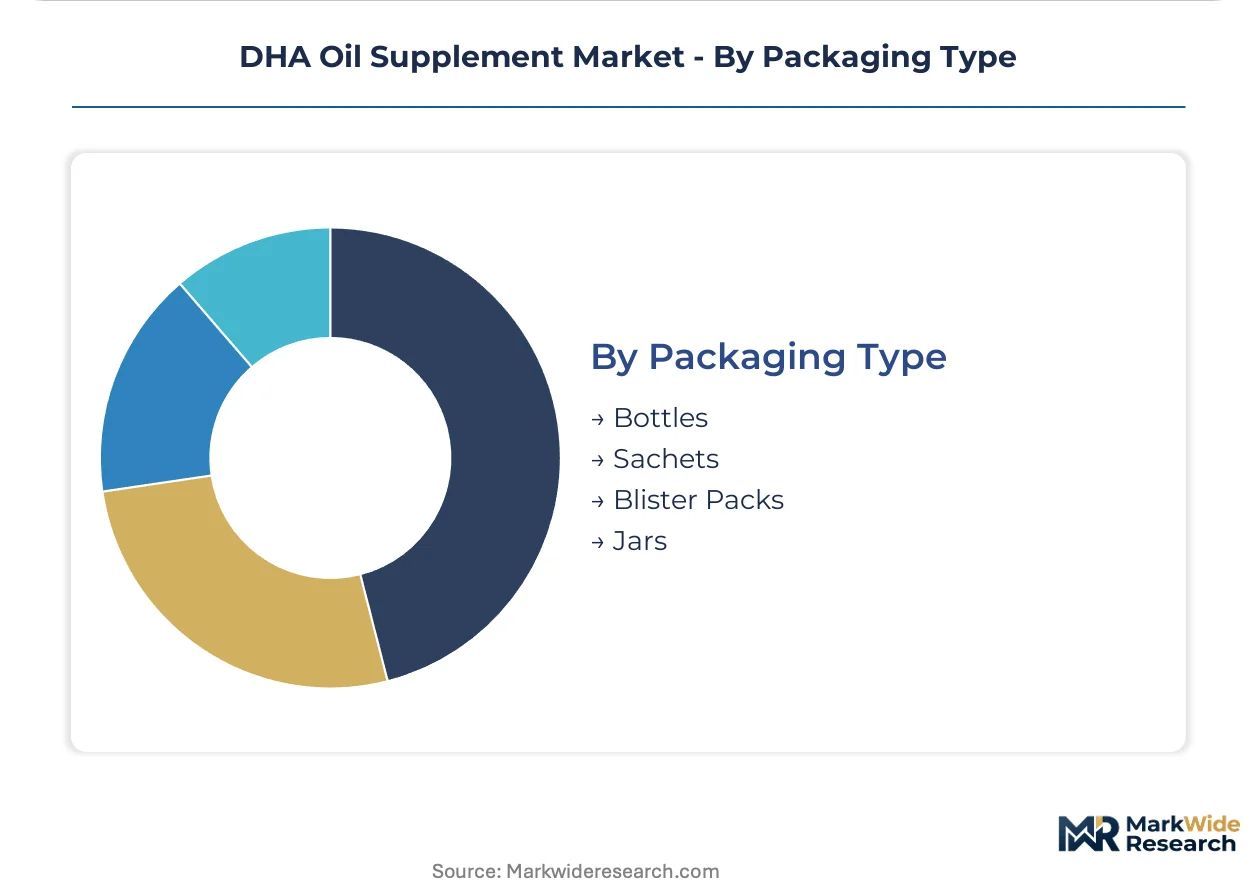
- Bottles:Amber glass or opaque plastic containers with desiccant inserts protect bulk softgel inventory. Hospital formulary committees require third-party sustainability verification alongside pharmacopeial documentation for procurement approval.
- Blister Packs:Individual cavity sealing extends shelf life for pharmacy-dispensed prescription products. German maternal health clinics favor this format for dose adherence tracking.
- Sachets:Single-serve foil pouches serve travel and trial-size applications.
- Jars:Wide-mouth containers accommodate gummy and liquid formats.
Bottles absorb the bulk of installed capacity; Blister Packs are gaining share fastest as prescription-channel documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of pharmaceutical-grade DHA concentrates in Germany and the Netherlands outpaces domestic consumption, creating export dependency to pharmacy channels across Southern Europe and North America. Consumption gravity sits with maternal health protocols in France, Italy, and the United States where EFSA and FDA frameworks validate prenatal dosing claims. This geographic split between manufacturing concentration and demand absorption shapes regional trade flows and regulatory compliance investments.
Germany
Heidelberg and Kiel host the densest clusters of pharmaceutical-grade DHA concentration capacity in Europe. EMA pharmaceutical guidelines enforce EP monograph compliance for pharmacy channel access, driving contract manufacturers to install in-house HPLC and GC-MS analytical capabilities. The Heidelberg-Kiel corridor supplies prescription-grade softgels to maternal health clinics across France, Italy, and Benelux markets.
United States
FDA GRAS notifications and EPA fisheries sustainability rules govern import eligibility for marine-origin DHA oils. Direct-to-consumer subscription channels bypass pharmacy margin compression for pediatric and fitness segments. California and New Jersey distribution hubs handle bulk softgel inventory for mass-market retail placement.
France
ANSM oversight of nutritional supplements intersects with EFSA maternal health claim recognition to elevate quality benchmarks for pharmacy-dispensed products. Hospital formulary committees in Paris and Lyon require third-party sustainability verification alongside pharmacopeial documentation. French maternal health clinics favor blister-pack formats for dose adherence tracking.
Netherlands
DSM leverages captive algal fermentation capacity near Rotterdam to serve vegan DHA demand across Northern Europe. EU Green Deal bioeconomy incentives accelerate capacity expansion for Schizochytrium-derived oils. Dutch brands adopt enzymatic concentration methods to support premium positioning among plant-based dietary adherents.
China
NMPA novel food approvals and GB standards govern DHA oil import and domestic manufacturing. Dual carbon goals under MEE oversight favor fermentation-based algal production over marine extraction. Yangtze River Delta pharmaceutical formulators source concentrated triglycerides for pediatric nutrition applications.
DHA Oil Supplement Market Competitive Environment
The competitive structure tilts toward integrated ingredient suppliers with captive fermentation or marine extraction assets. BASF SE and DSM anchor industrial-scale positions through technology platforms spanning fish-oil refining and algal fermentation. Three archetypes dominate: multinational chemical conglomerates with omega-3 divisions, specialized marine biotechnology firms with Antarctic krill traceability, and contract manufacturers serving pharmacy channel compliance requirements. Capacity expansion and enzymatic concentration technology licensing represent the dominant competitive moves as purity thresholds harden across EMA and FDA jurisdictions.
Within the multinational chemical tier, BASF SE and DSM exemplify integrated supply control through captive raw material sourcing. Aker BioMarine ASA occupies a distinct position as a marine biotechnology specialist with Antarctic harvesting operations. KD Pharma Group and Croda International Plc sit within the contract manufacturing and lipid technology tier, serving brands requiring pharmacopeial-grade certification. These named entities represent the competitive spectrum from industrial-scale refining to specialized marine traceability, with positioning determined by raw material access and regulatory documentation depth rather than product differentiation alone.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Croda International Plc |
| KD Pharma Group |
| Corbion |
| Aker BioMarine ASA |
| Clover Corporation |
| Omega Protein Corporation |
| Cellana Inc. |
| Others |
Value Chain & Pricing Dynamics
Pharmacy channel procurement committees in Germany and France concentrate purchasing power for prescription-grade DHA, anchoring a contract-based pricing structure that rewards pharmacopeial certification depth over volume scale.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects EMA-mandated EP monograph compliance investments and in-house analytical chemistry capability buildouts. Three-tier pricing structure across premium, standard, and economy levels separates prescription pharmacy products from mass-market softgels and bulk fortification oils. Cost-down pressure on economy-grade fish oil concentrates accelerates because Peruvian anchovy quota volatility destabilizes feedstock economics. Direct-to-consumer subscription buyers show lowest price sensitivity; institutional formulary committees exhibit highest.
Supply Chain Analysis
Marine triglyceride feedstock rests on Peruvian anchovy fisheries, Antarctic krill harvesting operations, and North Atlantic fish oil refining capacity. Schizochytrium algae fermentation draws from Rotterdam-based bioreactor clusters and Heidelberg-Kiel pharmaceutical concentration infrastructure. Single-source dependency for phospholipid-bound DHA creates structural vulnerability given Aker BioMarine's dominant Antarctic harvesting position. Distribution runs through German pharmacy wholesalers for prescription products and California-New Jersey mass-market hubs for retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity expansion timelines outpace demand growth for vegan DHA, propping pricing power for incumbent algal suppliers through mid-decade.
For Market Incumbents: Extend analytical chemistry capabilities to demonstrate batch-level EP monograph compliance without third-party outsourcing. Deepen captive Schizochytrium fermentation capacity near Rotterdam to defend against novel algal strain entrants awaiting EU Novel Food catalog approval. Prioritize nitrogen blanketing and oxidation protection engineering investments to prevent rancidity-related quality failures. For New Entrants and Emerging Players: The gap between premium prescription-grade pricing and economy mass-market tiers offers entry space for mid-certification products targeting direct-to-consumer pediatric subscriptions. School-age cognitive development applications remain underpenetrated relative to prenatal segments. Pursue enzymatic concentration technology licensing to bypass molecular distillation capital requirements. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with installed pharmacopeial-grade softgel capacity and existing EMA documentation protocols. Long-term viability hinges on dual-source raw material strategies spanning marine and algal origins. Watch EU Green Deal bioeconomy incentive disbursement velocity as inflection indicator for algal DHA capacity expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Concentration Technology Licensing | Enables cleaner label positioning and EFSA-compliant health claim substantiation for German brands. |
| Captive Algal Fermentation Capacity Expansion | DSM's Rotterdam bioreactor investments anchor vegan DHA supply security for EU plant-based demand. |
| In-House Analytical Chemistry Capability Buildout | German contract manufacturers install HPLC and GC-MS to demonstrate EP monograph compliance batch-by-batch. |
| Direct-to-Consumer Subscription Channel Launch | Recurring revenue models bypass pharmacy margin compression and build consumer lifetime value. |
| Marine Stewardship Council Certification Investment | Nordic hospital formulary committees require third-party sustainability verification alongside pharmacopeial documentation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across pharmaceutical formulators, maternal health clinic procurement managers, contract manufacturing executives, and algal biotechnology R&D directors. EMA pharmaceutical guidelines, FDA GRAS notifications, EU Novel Food catalog entries, and EPA fisheries sustainability rules provided regulatory boundary conditions. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Granularity-level modeling operated at product type, end user physiology, delivery mode, and packaging format dimensions across the analysis window. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions calibrated to pharmacy channel pricing structures. Forecast inputs incorporated fermentation capacity expansion timelines, EU Green Deal bioeconomy incentive disbursement schedules, and Peruvian anchovy quota allocation patterns.
Underlying measurement precision varies by segment; prescription-grade pharmaceutical products carry tighter precision than mass-market economy tiers due to documented channel flows. Forecasts reflect assumptions about regulatory approval timelines for novel algal strains and marine fishery sustainability certification persistence. A small set of triggers—Novel Food catalog entry delays, El Niño event severity, and pharmacopeial monograph revision cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Global Algal DHA and ARA Market