
 Japan Protein Market | 2026-2036
Japan Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Protein Market Foresight
Precision fermentation and enzymatic hydrolysis is tilting Japanese protein manufacturing toward higher bioavailability and cleaner label profiles. Ajinomoto Co., Inc. leverages its amino acid science heritage to dominate specialty protein ingredients for clinical nutrition. Fuji Oil Holdings Inc. anchors plant protein supply chains through its soy and pea protein extraction capabilities. Maruha Nichiro Corporation competes in marine-derived protein segments with its fish protein concentrate operations.
Japan protein encompasses amino acid chains derived from animal, plant, and microbial sources, typically processed through isolation, concentration, or hydrolysis to achieve protein content exceeding 80% in isolate form, serving nutritional fortification and muscle protein synthesis applications. Whey protein and soy protein lead volume consumption due to established supply infrastructure and cost efficiency, while pea protein represents the fastest-growing category as food manufacturers seek allergen-free alternatives. The application split reveals nutritional supplements commanding premium margins, whereas food and beverage integration is expanding through functional ingredient positioning in conventional retail channels.
METI enforces food labeling standards that mandate protein content accuracy and allergen disclosure, directly influencing formulation decisions and package claim strategies. PMDA oversight of Foods with Function Claims creates a regulated pathway for protein products bearing specific health benefits, tightening clinical evidence requirements. JIS standards govern industrial protein quality benchmarks for non-food applications including cosmetics and biomaterials. Stakeholders must monitor evolving FFC claim criteria and fermentation-derived novel protein approvals as regulatory clarity will determine which production technologies achieve commercial scale.
Market Dynamics
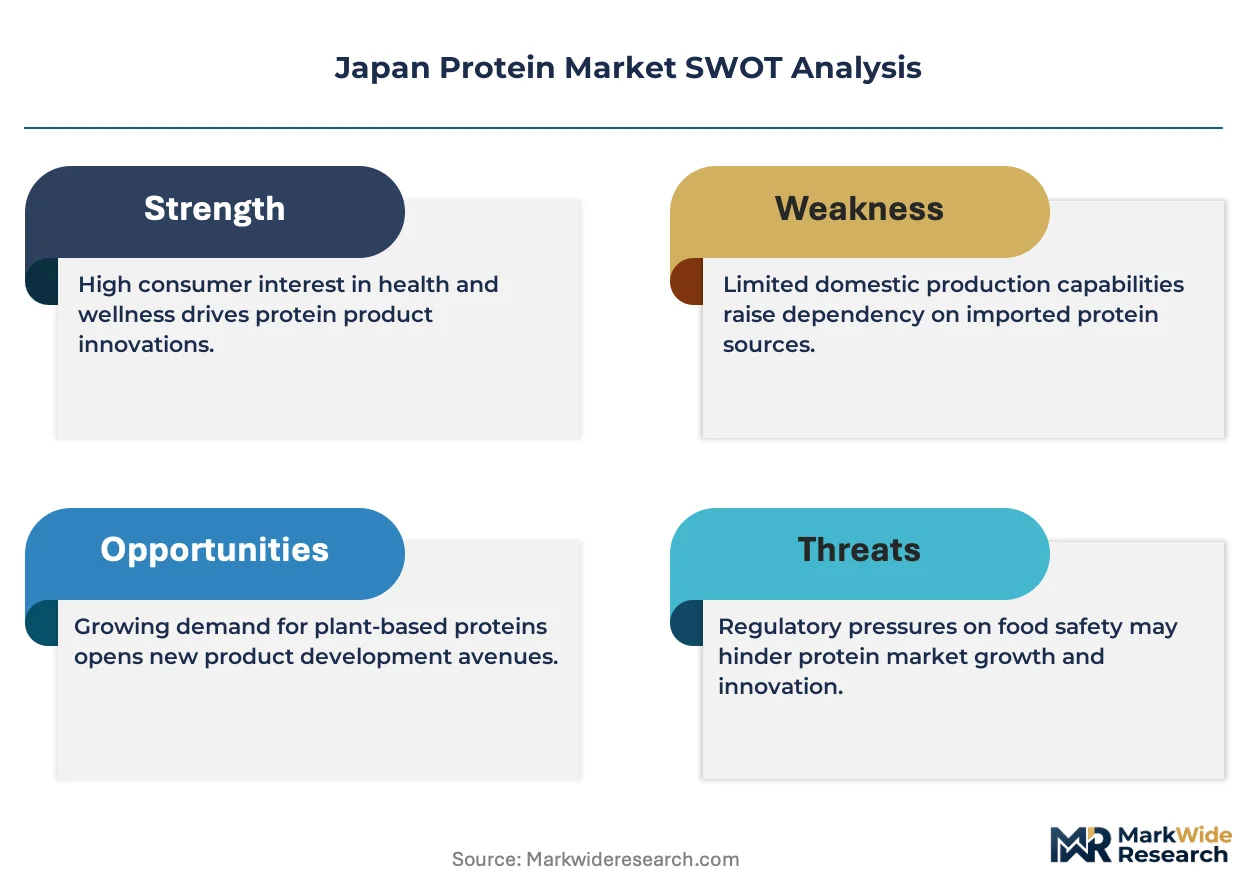
Precision fermentation infrastructure is reshaping Japanese protein manufacturing economics, compressing production timelines for novel ingredients while METI's labeling revisions force reformulation investments across conventional portfolios.
Growth Catalysts
- Foods with Function Claims pathway:PMDA's FFC framework permits protein products bearing specific muscle maintenance claims, creating a regulated premium channel for clinically substantiated formulations.
- Kanto retail density:Tokyo's concentration of premium fitness clubs and specialty nutrition outlets accelerates product trial velocity for new protein formats.
- Enzymatic hydrolysis adoption:Domestic manufacturers deploy advanced hydrolysis to achieve higher bioavailability scores, differentiating isolate products in clinical nutrition segments.
Market Restraints
- Import dependency for whey feedstock:Domestic dairy protein production remains insufficient, exposing formulators to ocean freight volatility and currency fluctuation from Australian and North American suppliers.
- Allergen labeling stringency:METI's mandatory soy and dairy allergen disclosure compresses formulation flexibility for multi-source protein blends in conventional retail.
- Fermentation scale-up capex:Precision fermentation facilities require specialized bioreactor infrastructure that domestic chemical engineering contractors have limited experience constructing.
Strategic Opportunities
- Kansai underpenetration:Osaka and Kyoto metropolitan areas show lower per-capita sports nutrition consumption than Kanto, presenting whitespace for regional distribution partnerships.
- Marine protein valorization:Fish processing byproduct streams from coastal prefectures offer untapped raw material for collagen and fish protein concentrate production.
- Convenience store channel expansion:Lawson and 7-Eleven Japan are expanding chilled functional beverage sets, creating shelf access for ready-to-drink protein formats beyond specialty retail.
Industry Challenges
- Fermentation bioprocess talent scarcity:Japanese universities produce limited graduates with combined food science and industrial microbiology training, constraining novel protein R&D pipelines.
- FFC evidentiary burden:PMDA requires controlled human studies for functional claims, extending product development timelines and demanding clinical research capabilities few ingredient suppliers possess.
- Legacy equipment retrofit costs:Soy protein isolate facilities built for commodity applications require substantial capital to achieve pharmaceutical-grade cleanliness standards for clinical nutrition supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Protein Market |
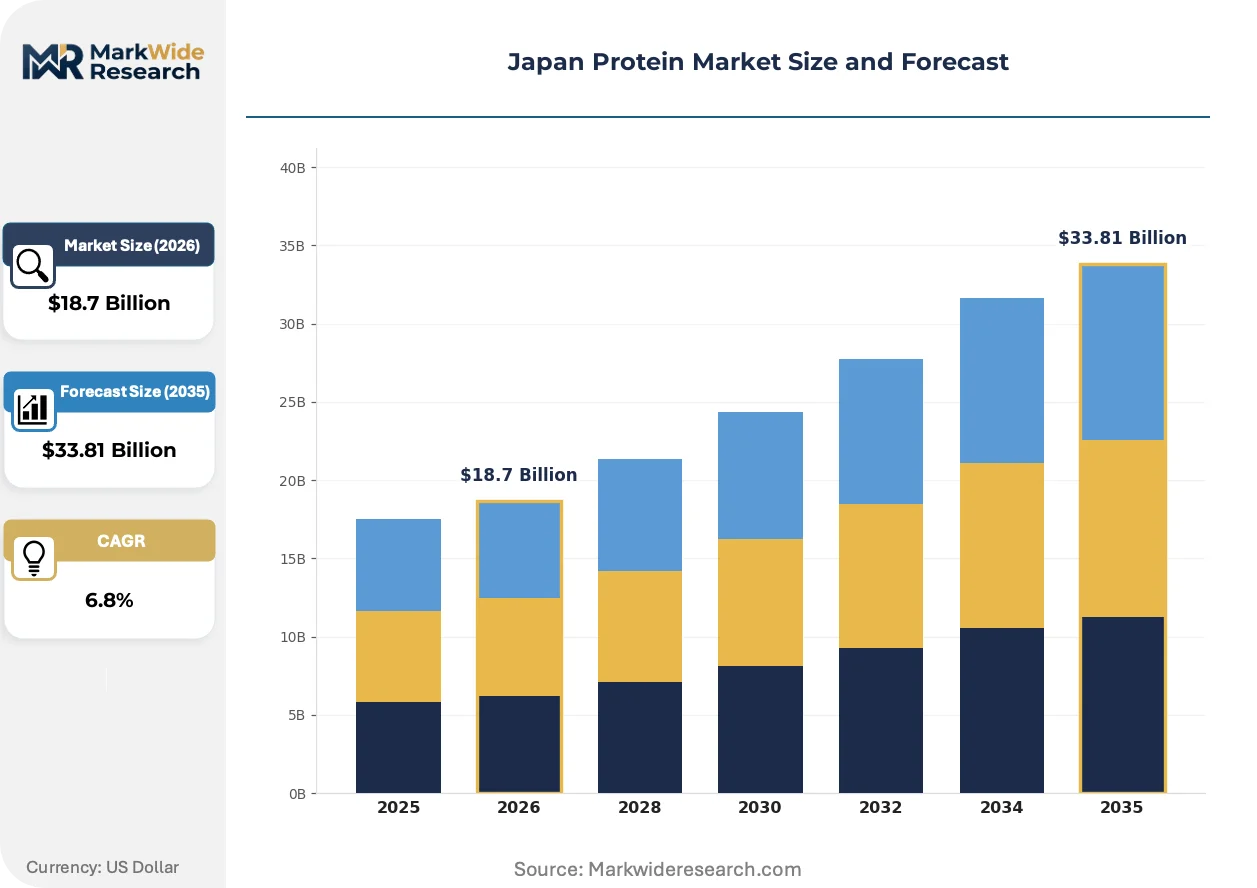
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Form: Powder, Bars, Ready-to-Drink, Capsules End User: Fitness Enthusiasts, Athletes, Health-Conscious Consumers, Dietary Supplement Users Application: Nutritional Supplements, Food & Beverage, Sports Nutrition, Clinical Nutrition |
| Companies Covered | Fuji Oil Holdings Inc., Maruha Nichiro Corporation, Ajinomoto Co., Inc., Kewpie Corporation, Otsuka Pharmaceutical Co., Ltd., Meiji Holdings Co., Ltd., Nippon Protein Co., Ltd., Nagasta Co., Ltd., Morinaga Milk Industry Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Protein Market Shifts & Advancements
Biomanufacturing automation and regulatory claim pathways are compressing product development cycles while shifting competitive advantage toward vertically integrated producers with clinical research capabilities.
Smart bioreactor control systems are digitizing precision fermentation operations across Japanese contract manufacturing facilities. Specialty ingredient producers deploy real-time metabolite monitoring to optimize protein yield curves. This capability is digitizing quality control documentation for PMDA submission packages, shortening novel protein approval timelines.
METI's revised Food Labeling Standards mandate protein content verification through standardized analytical methods, tightening permissible variance thresholds. Manufacturers must invest in HPLC and Dumas nitrogen testing infrastructure to maintain compliance. The regulation most affects imported protein blends, forcing foreign suppliers to establish Japanese analytical certification partnerships.
Fitness enthusiasts increasingly source protein through subscription direct-to-consumer channels rather than conventional retail. Specialty e-commerce platforms displace drugstore and supermarket purchases for repeat buyers. This pattern concentrates in Tokyo and Osaka metropolitan areas where delivery logistics enable same-day fulfillment of temperature-sensitive formulations.
Japan Protein Market Segmentation
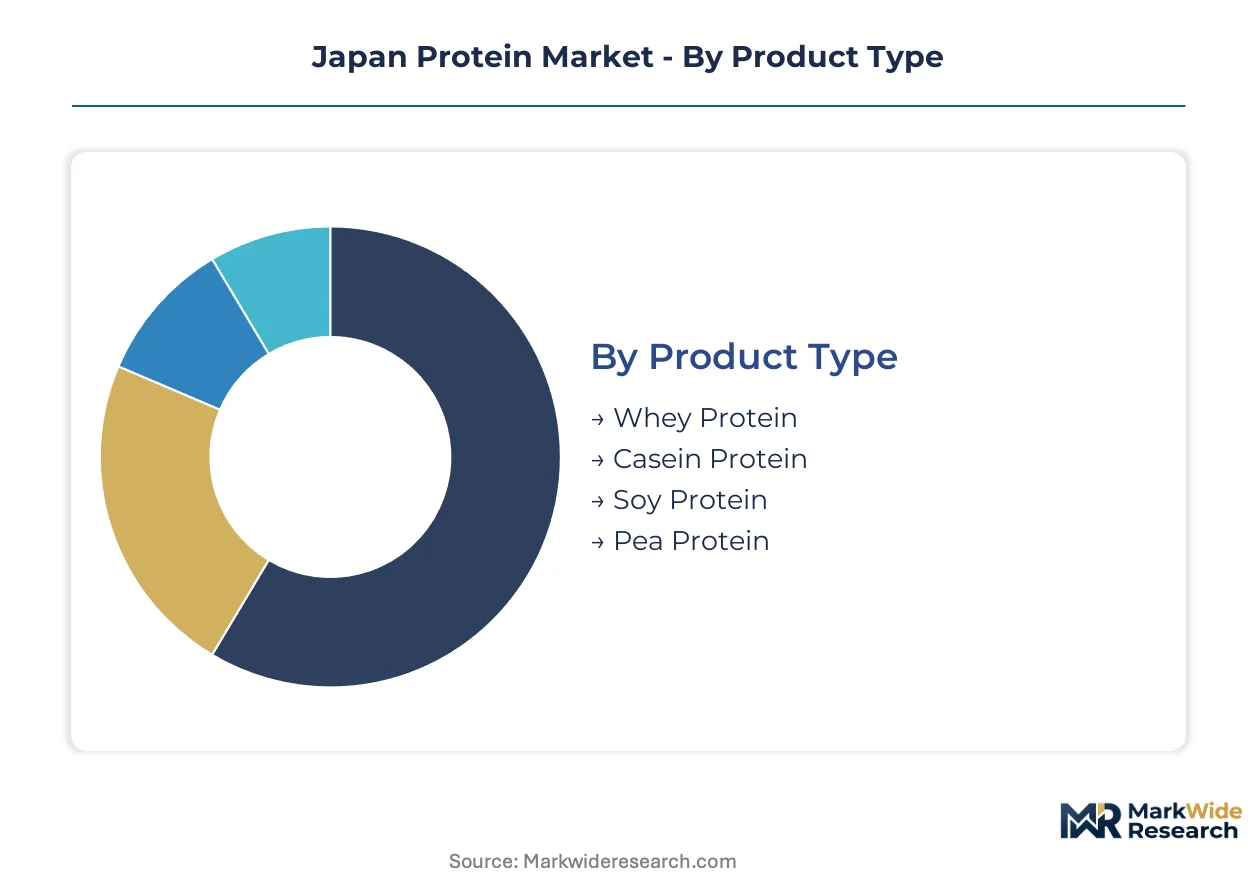
Japan's protein market fragments across four distinct dimensions that determine formulation requirements, channel access, and regulatory pathways. Each segmentation axis carries implications for METI labeling compliance, PMDA Foods with Function Claims eligibility, and manufacturing infrastructure investment.
Product Type:
The use-case spectrum spans rapid-absorption formulations for post-workout recovery through sustained-release matrices for overnight muscle maintenance.
- Whey Protein:Concentrates and isolates derived from cheese production byproducts deliver complete amino acid profiles with rapid gastric emptying. Demand concentrates in Kanto-region fitness clubs and specialty e-commerce channels where consumers prioritize leucine content for muscle protein synthesis.
- Soy Protein:Isolates and concentrates extracted from defatted soybean flakes provide cost-efficient amino acid fortification. Kansai metropolitan areas show persistent soy protein adoption in conventional retail, though METI allergen labeling mandates constrain multi-source blend formulation flexibility.
- Casein Protein:Micellar structures from milk curd coagulation enable slow amino acid release over 6-8 hour windows.
- Pea Protein:Hypoallergenic isolates from yellow pea fractionation are gaining traction among dietary supplement users seeking dairy-free and soy-free alternatives.
Established volume favors whey protein; emerging adoption favors pea protein.
Form:
Consumption occasions and portability requirements segment manufacturing investment across ambient-stable and cold-chain-dependent formats.
- Powder:Bulk canisters and single-serve sachets dominate home consumption and gym-bag portability. Tokyo's dense specialty retail infrastructure supports powder trial through in-store sampling programs.
- Ready-to-Drink:UHT-processed beverages in aseptic packaging command premium shelf positioning in Lawson and 7-Eleven chilled sets. Osaka metropolitan underpenetration presents whitespace for RTD distribution partnerships.
- Bars:Extruded and cold-pressed formats combine protein with carbohydrate matrices for meal replacement occasions.
- Capsules:Hard-shell and soft-gel delivery systems target clinical nutrition segments requiring precise dosing.
Powder formats capture household pantry penetration; RTD formats are climbing the fastest in convenience channel expansion.
End User:
Performance goals and health literacy levels determine product positioning from clinical-grade formulations to mass-market accessibility.
- Fitness Enthusiasts:Recreational exercisers with moderate protein knowledge drive volume through subscription direct-to-consumer platforms concentrated in Tokyo and Osaka.
- Athletes:Competitive and professional performers demand batch-tested formulations with anti-doping certification. PMDA FFC pathway products with muscle maintenance claims concentrate demand in this segment despite evidentiary burden requirements.
- Health-Conscious Consumers:General wellness seekers prioritize clean label positioning and allergen-free sourcing.
- Dietary Supplement Users:Existing supplement regimen adherents exhibit cross-category purchasing behavior.
Athletes anchor premium pricing tiers; fitness enthusiasts show steepest expansion trajectory in subscription channel migration.
Application:
Regulatory classification and margin structure diverge sharply between Foods with Function Claims pathways and conventional food ingredient supply.
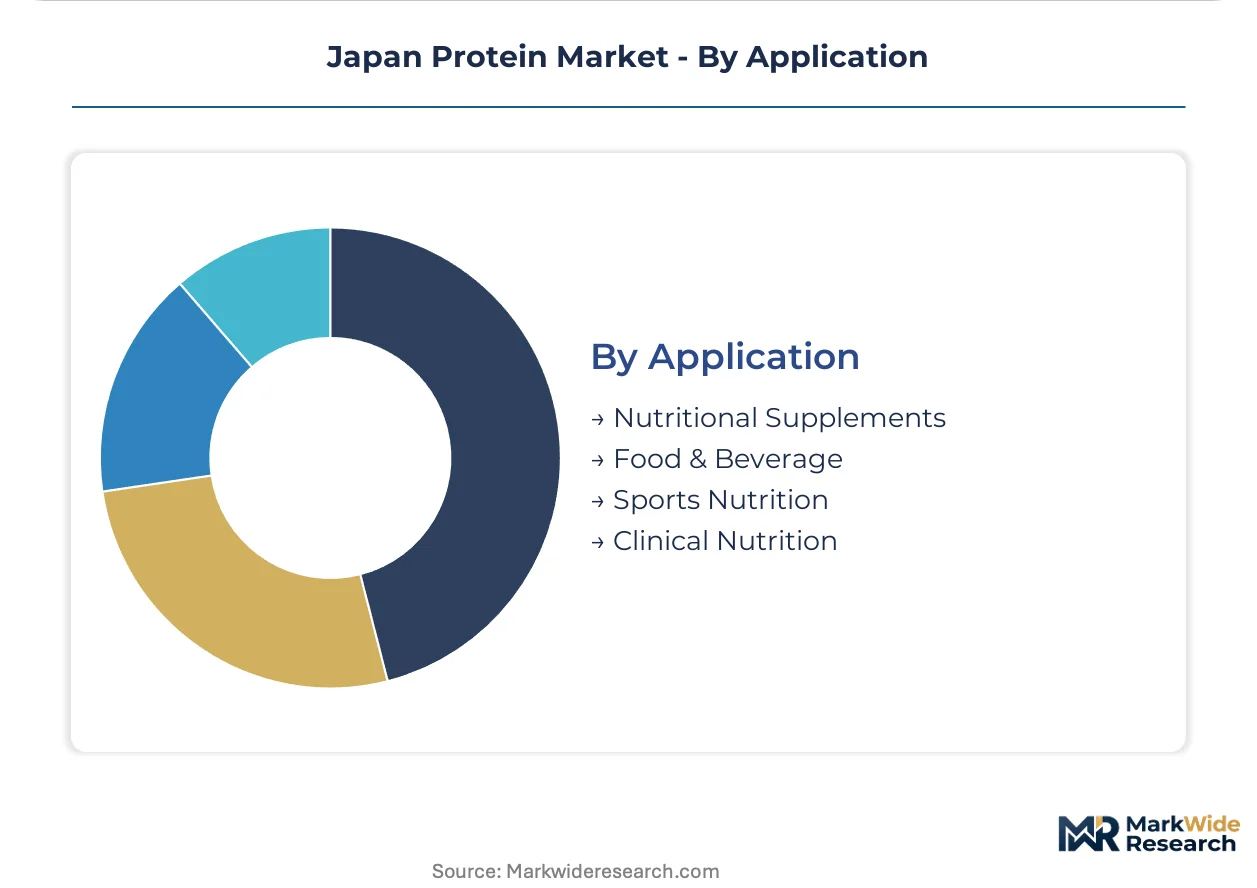
- Sports Nutrition:Pre-workout, intra-workout, and recovery formulations targeting muscle protein synthesis and glycogen replenishment. Kanto-region specialty retail density accelerates product velocity for novel formats.
- Clinical Nutrition:Medical-grade formulations for sarcopenia prevention and post-surgical recovery require pharmaceutical-grade manufacturing infrastructure. Ajinomoto's amino acid science heritage dominates this high-margin, low-volume segment.
- Nutritional Supplements:General wellness positioning through drugstore and mass-market channels.
- Food & Beverage:Functional ingredient integration into conventional products including fortified beverages and baked goods.
Sports nutrition captures recreational fitness expenditure; clinical nutrition exhibits highest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian and North American dairy exporters supply whey protein feedstock to Japanese formulators, while domestic soy processing concentrates in coastal industrial zones. Regional protein consumption patterns diverge sharply between metropolitan fitness corridors and conventional retail channels.
Kanto/Tokyo
Tokyo's dense network of premium fitness clubs and specialty nutrition outlets accelerates product trial velocity for novel protein formats. METI's Food Labeling Standards enforcement is tightest in this region due to proximity to regulatory headquarters. Chiba and Kanagawa prefectures host soy protein isolate facilities serving both food and clinical nutrition applications.
Kansai/Osaka
Osaka and Kyoto metropolitan areas show lower per-capita sports nutrition consumption than Kanto, presenting whitespace for regional distribution partnerships. PMDA's Foods with Function Claims review process operates from Osaka headquarters, influencing local formulation strategies. Hyogo prefecture maintains traditional soy processing infrastructure now retrofitting for higher-value isolate production.
Chubu/Nagoya
Nagoya's automotive manufacturing heritage supports precision engineering capabilities migrating into bioreactor construction for fermentation-derived proteins. Aichi prefecture's chemical industry cluster provides contract manufacturing infrastructure for enzymatic hydrolysis operations. Local universities produce food science graduates with limited industrial microbiology cross-training.
Kyushu
Fukuoka's startup ecosystem incubates alternative protein ventures leveraging regional agricultural byproducts. Nagasaki and Kagoshima coastal prefectures generate fish processing waste streams suitable for marine protein concentrate extraction. METI regional bureaus here administer subsidies for novel food technology commercialization.
Hokkaido
Hokkaido's dairy farming base supplies limited domestic whey feedstock, though volumes remain insufficient for national demand. Sapporo's food science research institutes collaborate with marine biotechnology startups on cold-water protein extraction methods. The prefecture's distance from major consumption centers elevates logistics costs for finished product distribution.
Japan Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's protein market, creating a tiered structure where scale advantages clash with formulation expertise. The vendor base clusters around three archetypes: diversified food conglomerates with amino acid science heritage, mid-cap soy and marine protein processors, and pharmaceutical-grade clinical nutrition specialists. Competitive moves concentrate on enzymatic hydrolysis capability acquisition and PMDA Foods with Function Claims pathway navigation.
Within the diversified conglomerate tier, Ajinomoto Co., Inc. and Fuji Oil Holdings Inc. exemplify players leveraging legacy ingredient expertise toward higher-margin specialty applications. Ajinomoto's amino acid science heritage positions it within clinical nutrition supply chains, while Fuji Oil's oilseed processing infrastructure anchors plant protein extraction capabilities. Maruha Nichiro Corporation occupies a distinct position among marine-derived protein specialists, with coastal processing assets supporting fish protein concentrate operations. These three players represent the dominant competitive vectors: amino acid technology, oilseed fractionation, and marine biomass valorization.
| Leading Market Players |
|---|
| Fuji Oil Holdings Inc. |
| Maruha Nichiro Corporation |
| Ajinomoto Co., Inc. |
| Kewpie Corporation |
| Otsuka Pharmaceutical Co., Ltd. |
| Meiji Holdings Co., Ltd. |
| Nippon Protein Co., Ltd. |
| Nagasta Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ocean freight volatility from Australian and North American dairy suppliers compresses margin spreads across whey protein tiers while forcing Japanese formulators to diversify feedstock sourcing toward domestic soy and marine alternatives. This dependency structure creates pricing power concentration among importers with long-term offtake contracts, while METI labeling compliance costs add fixed overhead that disproportionately burdens economy-tier producers.
Pricing Analysis
The technology-generation pricing gap separates enzymatic hydrolysis isolates commanding premium positioning from commodity-grade concentrates and next-generation precision fermentation proteins awaiting PMDA approval. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with pharmaceutical-grade clinical nutrition products capturing widest spreads. Pricing pressure stems from currency fluctuation on imported whey feedstock, compressing margins for standard-tier blenders without captive soy processing. Health-conscious consumers in Tokyo's specialty channels show lowest price sensitivity, while Kansai conventional retail buyers drive hardest bargain negotiations.
Supply Chain Analysis
Export-control regime limitations on bioreactor technology transfers from Germany and Switzerland constrain domestic precision fermentation scale-up, forcing Japanese manufacturers to source equipment through licensed Asian intermediaries. Geographic supply concentration centers on Australia and North America for whey protein, China for pea protein isolate feedstock, and domestic coastal prefectures for marine-derived inputs. Raw material dependencies include defatted soybean flakes, cheese production byproducts, and fish processing waste streams. Single-source vulnerability runs through ocean freight lanes connecting Australian dairy processors to Kanto-region ports. Distribution runs through specialty nutrition retailers in Tokyo, drugstore chains in Osaka, and expanding convenience store chilled sets nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's protein market functions as a service-attach opportunity where subscription direct-to-consumer platforms and clinical nutrition consultation layers expand faster than commodity powder volumes, rewarding players who capture recurring patient and athlete relationships beyond transactional product sales.
For Market Incumbents: Harden formulation moats by acquiring enzymatic hydrolysis capabilities from distressed mid-cap soy processors in Hyogo prefecture, while securing PMDA Foods with Function Claims pre-approvals ahead of labeling standard tightening. Threat of precision fermentation entrants with novel protein claims demands backward integration into captive bioreactor construction partnerships with Nagoya precision engineering clusters.
For New Entrants and Emerging Players: Pursue Kansai metropolitan whitespace through regional distribution partnerships with Osaka-based drugstore chains underserved by Tokyo-centric incumbents, targeting fitness enthusiasts migrating from conventional retail to subscription platforms. Marine protein valorization in Kyushu coastal prefectures offers lowest competitive density for collagen and fish protein concentrate production. Go-to-market angle should emphasize METI-compliant allergen-free positioning for soy-sensitive consumers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical research capabilities over commodity scale, as PMDA evidentiary requirements for functional claims filter out undercapitalized ingredient suppliers. Long-term viability over the next decade hinges on vertical integration into pharmaceutical-grade manufacturing infrastructure. Signal to watch is fermentation-derived novel protein approval velocity from PMDA, indicating which production technologies achieve commercial scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capability Acquisition | Secures higher bioavailability scores for clinical nutrition segment differentiation against commodity competitors. |
| PMDA Foods with Function Claims Pathway Navigation | Unlocks premium channel access for muscle maintenance claims with controlled human study investment. |
| Marine Protein Valorization Partnership | Converts Kyushu fish processing waste into collagen and concentrate supply with regional subsidy support. |
| Subscription Direct-to-Consumer Platform Launch | Captures recurring revenue from Tokyo fitness enthusiasts displacing drugstore purchases with same-day delivery. |
| Precision Fermentation Bioreactor Construction | Builds domestic novel protein production capacity despite limited Japanese chemical engineering contractor experience. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, PMDA Foods with Function Claims registrations, and customs import data for whey and pea protein feedstock. Primary interviews engaged formulation scientists at diversified food conglomerates, procurement directors at Kanto-region fitness club chains, regulatory affairs specialists navigating PMDA submission requirements, and distribution managers at Osaka-based drugstore networks. Secondary validation drew from JIS standards documentation, Ministry of Agriculture trade statistics, and pharmaceutical-grade manufacturing facility disclosure reports. Bottom-up protein volume estimates by product type and form were triangulated against top-down market value reconstructions.
Forecast inputs include historical consumption patterns by prefecture, PMDA approval pipeline status for novel protein ingredients, and METI labeling standard implementation timelines across the analysis window. Segmentation dimensions modeled encompass product type, form, end user, and application with geographic consumption cluster overlays. CAGRs were derived from regression analysis of protein volume growth against fitness club membership expansion and clinical nutrition demographic trends. Industry-specific forecast inputs include enzymatic hydrolysis adoption rates and precision fermentation facility commissioning schedules.
Sensitivities concentrate around currency fluctuation on imported whey feedstock, PMDA evidentiary requirement tightening for functional claims, and fermentation scale-up delays from bioprocess talent scarcity. Forecasts reflect assumptions on regulatory approval velocity and consumer channel migration patterns without guaranteeing outcome realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Milk Powder for Pregnant Women Market