
 South America Whey Protein Market | 2026-2036
South America Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Whey Protein Market Analytics
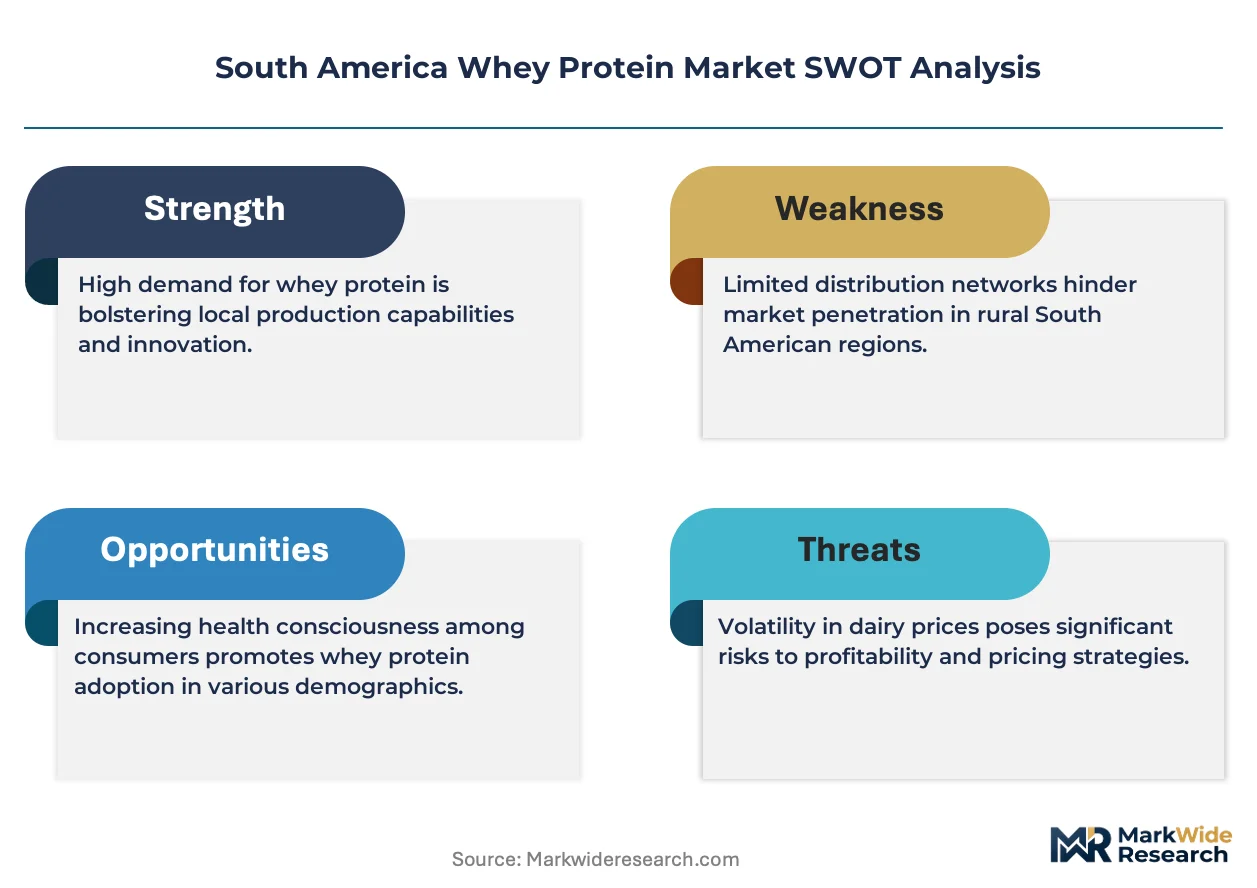
Direct-to-consumer online retail is narrowing as the dominant growth channel across South America. Fonterra Co-Operative Group leverages its New Zealand dairy heritage to anchor premium whey positioning in Brazilian e-commerce. Carbery Group competes through specialized whey isolate formulations targeting performance nutrition segments. Glanbia PLC extends its distribution reach via partnerships with regional health food store networks in Argentina and Chile.
Whey protein comprises the soluble protein fraction separated during cheese manufacture, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing grade. The ingredient serves primarily as a functional food additive and nutritional supplement base for muscle protein synthesis applications. Whey Protein Isolate commands the highest margin pool due to its superior purity profile and lower lactose content, while Sports Nutrition application volumes lead absolute consumption across the region. Hydrolyzed Whey Protein represents the fastest-growing product type as pre-digested formulations gain traction among consumers with digestive sensitivities.
Brazil's ANVISA maintains stringent dairy protein purity standards that govern import approvals and domestic manufacturing compliance. Argentina's national food safety authority enforces CODEX-aligned labeling requirements that shape product positioning claims across the Mercosur trade zone. Stakeholders must monitor evolving regulatory harmonization between Mercosur members and potential divergence in protein content certification protocols.
Market Dynamics
ANVISA's escalating dairy protein purity enforcement is compressing import timelines and forcing domestic manufacturers toward backward integration into whey fractionation capacity. This regulatory pressure concentrates competitive advantage among operators with certified in-house processing infrastructure.
Growth Catalysts
- Performance Nutrition Expansion:Brazil's southeastern metropolitan corridor spanning São Paulo and Rio de Janeiro anchors concentrated demand from amateur and professional athletes seeking muscle protein synthesis support.
- CODEX-Aligned Labeling Standards:Argentina's national food safety authority mandates transparent ingredient sourcing that rewards whey isolate formulations with superior purity profiles across the Mercosur trade zone.
- Hydrolyzed Formulation Adoption:Pre-digested whey protein gains traction among consumers with lactose intolerance and digestive sensitivities, expanding addressable population beyond traditional sports nutrition users.
Market Restraints
- Input Cost Volatility:Fluid milk supply fluctuations in Argentina's Pampas dairy belt transmit directly to whey concentrate pricing, compressing processor margins during drought cycles.
- Supply Concentration Risk:New Zealand-origin whey protein isolate dominates premium import channels into Brazil, creating foreign exchange exposure and tariff vulnerability.
- Technical Limitation:Lactose removal efficiency in microfiltration systems caps isolate yields at approximately 90% protein content, constraining ultra-premium product development.
Strategic Opportunities
- Chilean Market Underpenetration:Santiago's health food retail channel remains fragmented relative to Brazil, presenting first-mover positioning for specialized whey isolate distribution partnerships.
- Medical Nutrition Applications:Clinical whey protein prescriptions for sarcopenia and post-surgical recovery represent an emerging application with reimbursement pathway development underway.
- Direct-to-Consumer Channel Innovation:Subscription-based personalized protein dosing platforms bypass traditional pharmacy and gym retail intermediaries, capturing recurring revenue streams.
Industry Challenges
- Specialized Technician Scarcity:Cross-flow membrane operation and chromatographic separation expertise remains concentrated among a limited pool of dairy process engineers in the Southern Cone.
- Certification Timeline Compression:ANVISA's extended import approval cycles for novel whey protein hydrolysates delay product launches by 18-24 months versus domestic manufacturing pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Whey Protein Market |
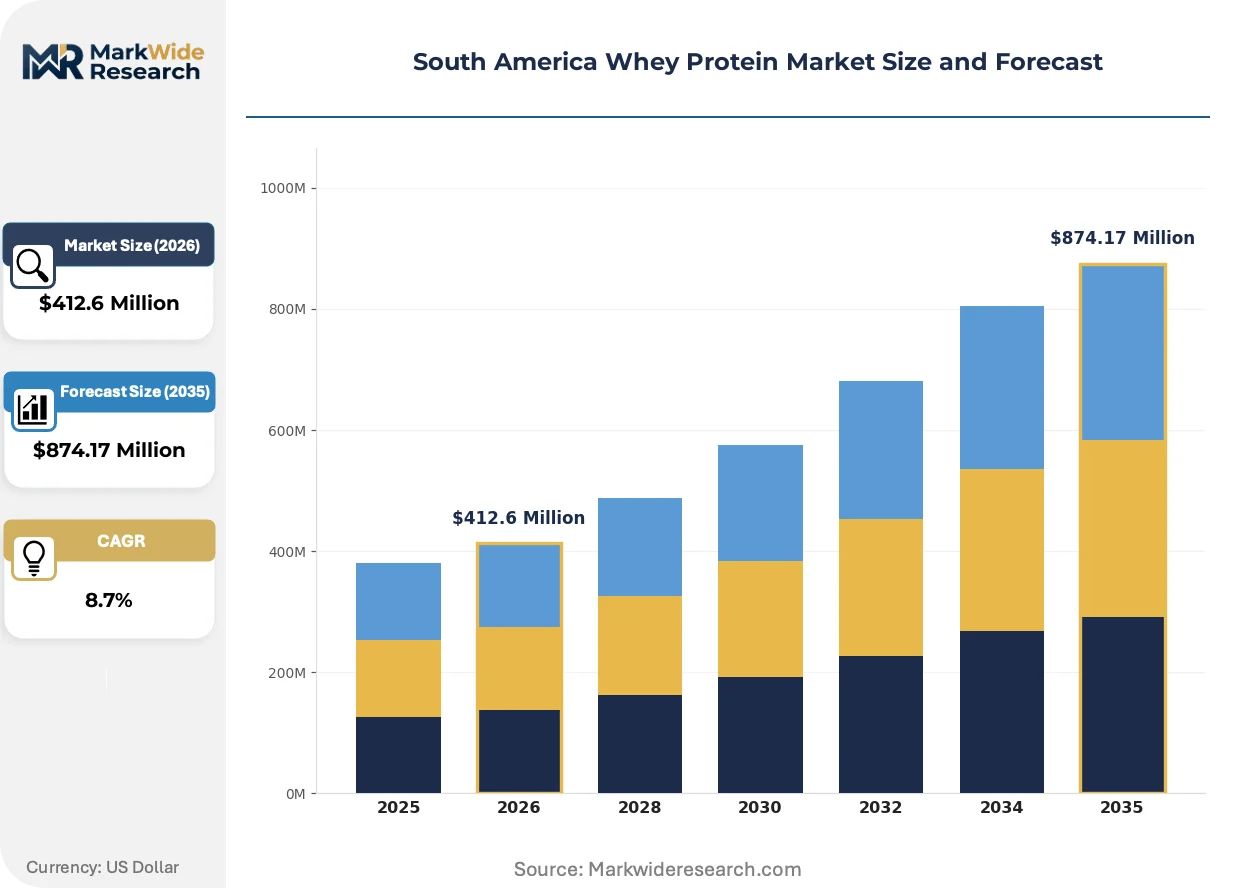
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein Application: Sports Nutrition, Functional Foods, Infant Formula, Dietary Supplements Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Pharmacies End User: Athletes, Bodybuilders, Fitness Enthusiasts, General Consumers |
| Companies Covered | Arla Foods Ingredients, Carbery Group, Fonterra Co-Operative Group, Hilmar Ingredients, FrieslandCampina, Glanbia PLC, Saputo Inc, Agropur Cooperative, Lactalis Ingredients, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Whey Protein Market Evolving Landscape
Digital supply chain orchestration and precision fermentation alternatives are actively restructuring whey protein sourcing economics across the Southern Cone. These forces compress traditional dairy-dependent production models while opening novel ingredient pathways.
Membrane filtration technology is virtualizing whey protein separation workflows by replacing batch-based thermal processing with continuous cross-flow systems. Brazilian dairy cooperatives adopt these systems at accelerating pace to meet ANVISA purity thresholds. The technology is virtualizing capital deployment patterns, enabling mid-scale processors to achieve isolate-grade output without integrated cheese manufacturing infrastructure.
Argentina's CODEX-aligned labeling mandate is tightening protein content verification requirements across Mercosur, forcing reformulation of blended products and retirement of ambiguous "protein matrix" descriptors. Sports nutrition brands face the steepest compliance burden as legacy positioning claims require substantiation through third-party assay. Chilean importers are responding by pre-certifying isolate formulations through Santiago-based analytical laboratories before customs clearance.
Consumer purchasing patterns are gravitating toward transparent supply chain visibility, with QR-code traceability from dairy farm to finished product becoming a baseline expectation rather than premium differentiator. Brazil's e-commerce health platforms are displacing gym-based retail as the primary education and transaction channel for first-time whey protein buyers. This behavioral shift concentrates most visibly among São Paulo's digitally native demographic aged 25-34.
South America Whey Protein Market Segmentation
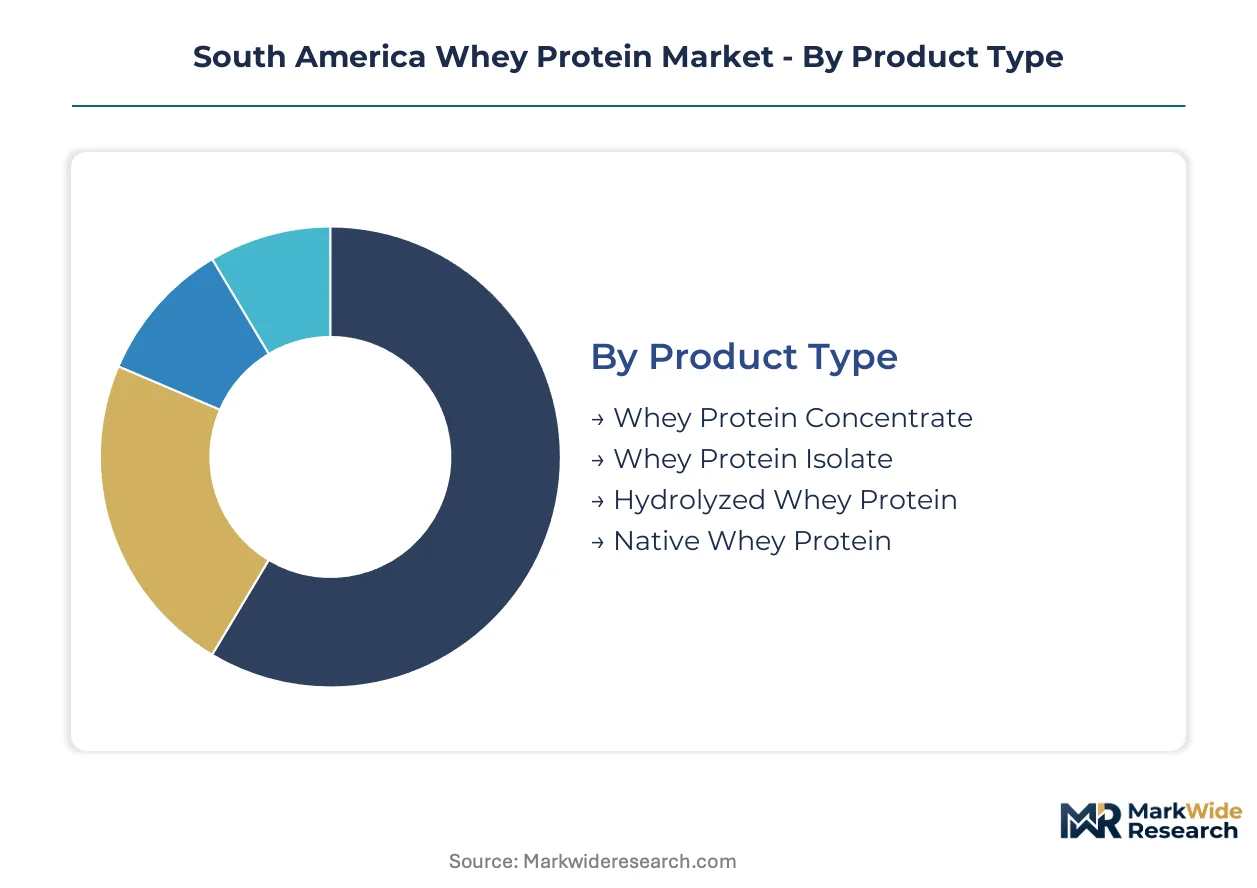
Whey protein segmentation in South America reflects divergent purity grades, application intensities, and channel economics. Manufacturers configure production assets around isolate-grade membrane capacity while distributors optimize for São Paulo's digital-native fitness demographic.
Product Type:
Mature concentrate formulations anchor volume throughput while emerging hydrolyzed variants capture digestive-sensitive niches.
- Whey Protein Concentrate:Contains 34-80% protein by weight with retained lactose and milk lipids, serving cost-sensitive formulations across Brazil's mass-market sports nutrition sector. São Paulo's private-label manufacturers rely on concentrate feedstock for economy-tier positioning.
- Whey Protein Isolate:Achieves 90%+ protein concentration through cross-flow microfiltration and ion exchange chromatography, commanding premium positioning in Rio de Janeiro's specialized athletic retail. ANVISA's escalating purity enforcement favors isolate-grade domestic processing infrastructure.
- Hydrolyzed Whey Protein:Pre-digested enzymatic fragments reduce allergenic potential for lactose-intolerant consumers in Argentina's metropolitan corridor.
- Native Whey Protein:Cold-processed separation from skim milk rather than cheese whey retains underatured immunoglobulin fractions for Chile's emerging medical nutrition applications.
Whey Protein Concentrate retains volume leadership; Hydrolyzed Whey Protein holds the steepest expansion curve.
Application:
Performance-driven consumption dominates absolute tonnage while clinical nutrition applications build reimbursement infrastructure.
- Sports Nutrition:Powder and ready-to-drink formulations targeting muscle protein synthesis dominate Brazilian gym retail and direct-to-consumer subscription platforms. Amateur athlete penetration in São Paulo's southeastern corridor drives repeat purchase velocity.
- Functional Foods:Protein-fortified dairy beverages, bakery, and snack applications leverage whey for texture modification and nutritional enhancement. Argentina's CODEX-aligned labeling mandates transparent protein content declaration across Mercosur trade zones.
- Infant Formula:Demineralized whey fractions serve as lactose-adjusted protein bases for specialized pediatric nutrition.
- Dietary Supplements:Capsule and tablet formats target aging populations with sarcopenia-prevention positioning in Chile's pharmacy channel.
Sports Nutrition commands absolute consumption; Medical nutrition applications gain reimbursement traction slowest.
Distribution Channel:
Digital intermediation is compressing traditional pharmacy and supermarket margins while health food retail retains education-intensive transactions.
- Supermarkets:Mass-market concentrate SKUs reach general consumers through Brazil's southeastern retail chains with limited staff consultation. Price transparency pressures margin retention.
- Health Food Stores:Staff-trained environments in Buenos Aires and Santiago support isolate-grade product education and loyalty program enrollment. Personalized dosing guidance justifies premium pricing.
- Online Retail:Direct-to-consumer platforms bypass intermediaries with subscription-based replenishment and QR-code supply chain traceability.
- Pharmacies:Clinical whey prescriptions for post-surgical recovery and sarcopenia management require physician endorsement and reimbursement pathway development.
Online Retail captures share fastest; Health Food Stores defend margin through consultation value.
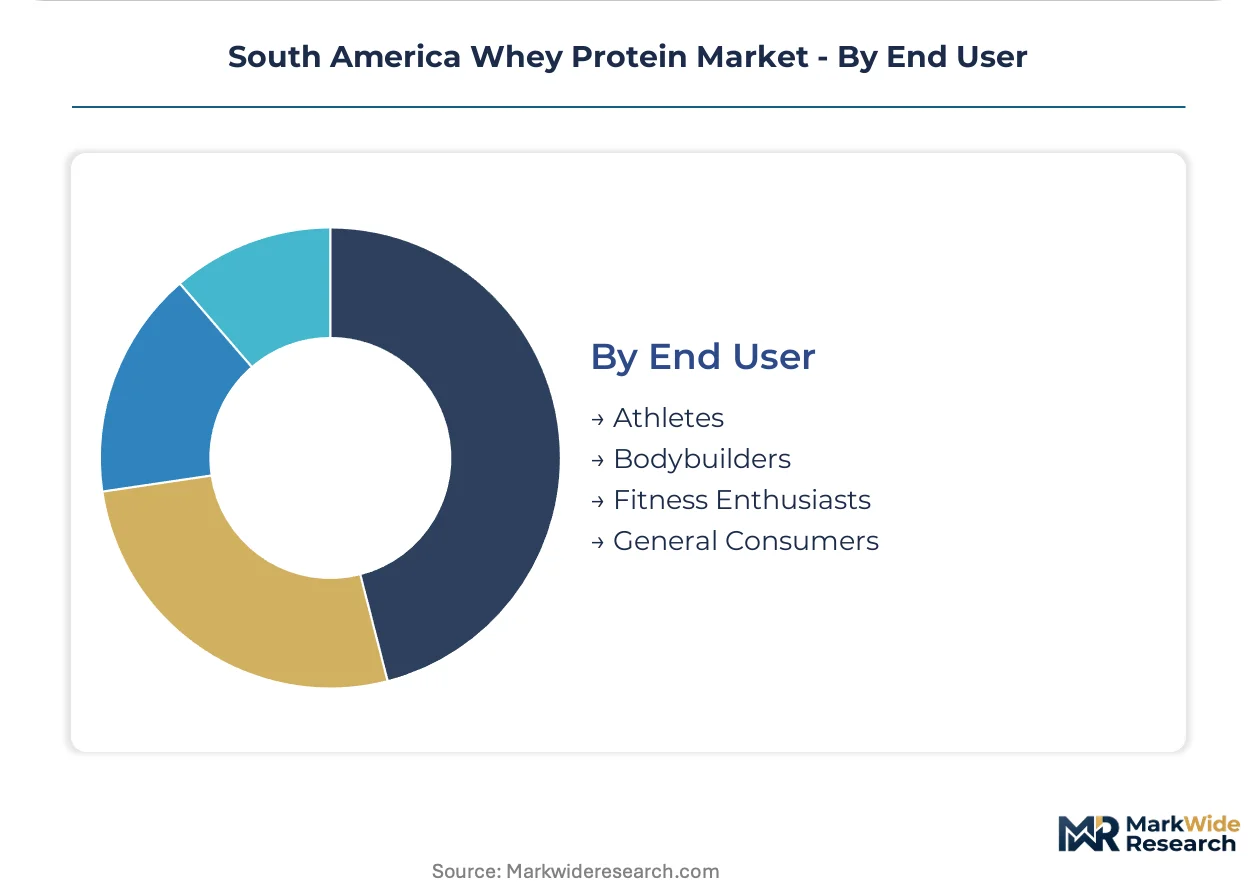
End User:
Professional-grade demand concentrates in coastal metropolitan zones while general wellness adoption diffuses inland.
- Athletes:Competitive and amateur competitors in Brazil's organized sports leagues prioritize isolate and hydrolyzed formulations for rapid absorption timing. Rio de Janeiro's triathlon and CrossFit communities drive premium SKU velocity.
- Bodybuilders:High-frequency resistance trainers consume 2-3g protein per kg bodyweight daily, concentrating demand for bulk concentrate and isolate formats. São Paulo's specialized gym retail caters to this segment with personalized stacking recommendations.
- Fitness Enthusiasts:Recreational exercisers seek convenient protein supplementation without competitive dosing protocols.
- General Consumers:Aging demographics and wellness-oriented buyers adopt whey for meal replacement and immune support positioning.
Bodybuilders drive per-capita consumption intensity; General Consumers represent the largest addressable population expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos handles the bulk of whey protein imports into Brazil, anchoring South American distribution networks that radiate through Mercosur trade corridors. This maritime infrastructure underwrites regional supply security while exposing landed costs to foreign exchange volatility.
Brazil
São Paulo's metropolitan corridor drives concentrated demand from amateur athletes and CrossFit practitioners seeking isolate-grade formulations. ANVISA enforces escalating dairy protein purity standards that compress import timelines and favor domestic membrane filtration capacity. Rio de Janeiro's specialized athletic retail clusters anchor premium SKU velocity among triathlon and bodybuilding communities.
Argentina
Buenos Aires anchors Mercosur's most sophisticated health food retail channel, where staff-trained environments support isolate-grade product education. The national food safety authority mandates CODEX-aligned labeling requirements that reward transparent protein sourcing claims. Córdoba's dairy processing belt transmits fluid milk supply fluctuations directly to whey concentrate pricing during Pampas drought cycles.
Chile
Santiago's fragmented health food retail landscape presents first-mover positioning for specialized whey isolate distribution partnerships. The country's pharmacy channel develops reimbursement pathways for clinical whey prescriptions targeting sarcopenia and post-surgical recovery. Valparaíso's analytical laboratories pre-certify isolate formulations before customs clearance, accelerating import velocity.
Colombia
Bogotá's emerging fitness demographic drives nascent demand for economy-tier concentrate formulations through supermarket channels. The national food and drug surveillance institute maintains import registration requirements that lag ANVISA stringency, creating regulatory arbitrage opportunities. Medellín's gym retail networks expand whey protein education among first-time supplement buyers.
South America Whey Protein Market Competitive Landscape
On the supply side, the industry is consolidating around operators with certified in-house whey fractionation infrastructure capable of meeting ANVISA purity thresholds. New Zealand-origin processors dominate premium import channels into Brazil, while European dairy cooperatives compete through specialized isolate formulations. Two strategic archetypes define competitive positioning: integrated dairy processors with captive whey streams, and specialized ingredient manufacturers focused on hydrolyzed and native protein variants. Dominant competitive moves include backward integration into membrane filtration capacity and geographic expansion through regional health food store partnerships.
Among New Zealand-based dairy cooperatives, Fonterra Co-Operative Group exemplifies the heritage-premium archetype, leveraging origin positioning in Brazilian e-commerce channels. European specialists including Carbery Group and Glanbia PLC occupy positions defined by formulation expertise and distribution reach across Argentina and Chile. These three anchors represent divergent competitive vectors: origin-based brand equity, technical specialization in isolate and hydrolyzed grades, and partnership-driven channel access.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Carbery Group |
| Fonterra Co-Operative Group |
| Hilmar Ingredients |
| FrieslandCampina |
| Glanbia PLC |
| Saputo Inc |
| Agropur Cooperative |
| Lactalis Ingredients |
| Others |
Value Network & Pricing Analysis
New Zealand-origin whey protein isolate dominates premium import channels into Brazil, anchoring margin pools in Rio de Janeiro's specialized athletic retail and São Paulo's direct-to-consumer platforms. ANVISA's escalating dairy protein purity enforcement compresses import timelines and concentrates pricing power among operators with certified in-house membrane filtration capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolate formulations from concentrate SKUs and hydrolyzed variants. Price differentiation rests on protein concentration certification and lactose removal efficiency, with ANVISA compliance tiers acting as gatekeepers. Cost compression in economy-tier concentrate is intensifying because São Paulo's private-label manufacturers compete on fluid milk feedstock arbitrage. General consumers through supermarket channels exhibit highest price sensitivity; bodybuilders purchasing through specialized gym retail show lowest.
Supply Chain Analysis
Tariff exposure between New Zealand and Brazil dominates supply chain risk calculations for premium isolate imports. Geographic supply concentrates in New Zealand, Argentina's Pampas dairy belt, and domestic Brazilian membrane filtration operations. Raw material dependencies draw from fluid milk supply, cheese whey streams, and enzymatic hydrolysis inputs. Single-source vulnerability runs through New Zealand-origin isolate for premium positioning. Distribution runs through Port of Santos maritime infrastructure radiating across Mercosur corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified membrane filtration engineers remain scarce across the Southern Cone, constraining domestic capacity expansion and compressing timelines for ANVISA compliance. This capability gap favors early movers with captive technical talent.
For Market Incumbents: Pre-empt precision fermentation alternatives by securing long-term whey stream offtake from Argentina's Pampas cooperatives and accelerating backward integration into chromatographic separation capacity. Defend against emerging native whey entrants through immunoglobulin fraction patent filings. Certification investment in ANVISA pre-approved hydrolysate formulations is the critical defensive lever. For New Entrants and Emerging Players: Chile's fragmented health food retail in Santiago offers first-mover positioning for isolate-grade distribution partnerships before incumbent network lock-in solidifies. Target medical nutrition applications in pharmacy channels where reimbursement pathway development lags and clinical whey prescriptions for sarcopenia remain underdeveloped. Deploy subscription-based personalized dosing platforms as the primary go-to-market angle to bypass traditional retail intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian dairy cooperatives lacking isolate-grade membrane infrastructure but holding ANVISA import licenses. Five-to-ten year viability hinges on regulatory harmonization execution and technical talent retention. Acquisition candidates include mid-scale processors with certified cross-flow systems and established health food store partnerships. Watch for ANVISA approval timeline compression as the inflection signal for domestic manufacturing preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Filtration | Captures ANVISA compliance premiums by converting cheese whey streams to isolate-grade output in-house. |
| Direct-to-Consumer Platform Launch | Bypasses São Paulo's gym retail intermediaries with subscription replenishment and QR-code traceability. |
| Medical Nutrition Reimbursement Strategy | Develops clinical whey prescription pathways through Chile's pharmacy channel for sarcopenia applications. |
| Health Food Store Partnership Expansion | Secures staff-trained environments in Buenos Aires and Santiago for isolate-grade product education. |
| Hydrolyzed Formulation Pre-Certification | Accelerates ANVISA approval timelines by submitting through Santiago-based analytical laboratories. |
Research Methodology
Cross-validation between primary interviews with dairy processing executives and secondary validation through ANVISA regulatory filings anchors the qualitative findings. Stakeholder engagement included membrane filtration engineers, health food store buyers, sports nutrition brand managers, and pharmacy procurement officers. Secondary sources drew from customs import records, CODEX alimentarius standards, dairy cooperative annual disclosures, and Mercosur trade documentation. Bottom-up volume modeling triangulated against top-down expenditure estimates across the projection horizon.
Calibration against historical isolate and concentrate price spreads informed the analytical framework throughout the modeling period. Segmentation dimensions included protein grade tier, application intensity, distribution channel economics, and metropolitan demand clustering. CAGRs were derived from trend extrapolation moderated by regulatory enforcement trajectory and technical adoption curves. Forecast inputs incorporated membrane filtration capacity buildout schedules and precision fermentation competitive threat assessment.
Practitioners should monitor ANVISA enforcement intensity, Pampas drought cycles, and New Zealand exchange rate volatility for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Chaga Mushroom Extract Market