
 South Africa Nutraceuticals Market | 2026-2036
South Africa Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Nutraceuticals Market Analytics
The South African nutraceuticals sector is consolidating around a sharp split between premium clinically validated formulations and commodity-grade supplements sold through mass retail. Vital Health Foods anchors the premium tier through its specialized focus on science-backed formulations and pharmacy channel control. Ascendis Health competes across multiple price points, leveraging its broad manufacturing scale to serve both private label and branded segments. Clicks Group Limited dominates retail distribution, extending its pharmacy footprint to capture recurring consumer purchases.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, herbal extracts, and functional food ingredients formulated to deliver physiological benefits beyond basic nutrition, typically manufactured through cold-press extraction, microencapsulation, or fermentation processes to preserve bioavailability. The product type dimension shows vitamins and functional foods commanding the largest revenue pools, while herbal supplements generate the fastest growth as traditional African botanicals gain commercial traction. Distribution channel dynamics reveal online retail eroding pharmacy dominance among younger demographics, though health stores sustain margin strength through personalized consultation services.
South Africa's Medicines Control Council under the Department of Health enforces registration requirements for health claims, while the National Regulator for Compulsory Specifications and SABS maintain quality benchmarks for functional food safety. These frameworks elevate compliance costs for entrants but protect established players with documented clinical substantiation. Stakeholders must monitor pending amendments to complementary medicine regulations that could redefine the boundary between food supplements and scheduled medicines.
Market Dynamics
South Africa's Medicines Control Council registration requirements under the Medicines and Related Substances Act are compressing market entry timelines and elevating compliance thresholds for functional food and supplement manufacturers.
Growth Catalysts
- Urban Health Consciousness:Johannesburg and Cape Town consumers are prioritizing preventive wellness formulations over reactive healthcare, creating sustained pull for condition-specific nutritional products.
- SABS Quality Benchmarking:The South African Bureau of Standards maintains functional food safety protocols that reward documented clinical substantiation, insulating compliant manufacturers from commodity price erosion.
- Elderly Demographic Concentration:South Africa's aging population segments in Gauteng and Western Cape provinces generate concentrated demand for bone health, cardiovascular support, and cognitive function supplements.
Market Restraints
- Import Dependency for Active Ingredients:Cold-press extraction equipment and specialized probiotic strains concentrate supply with European and North American suppliers, exposing local formulators to currency volatility and extended lead times.
- Regulatory Friction from Pending Amendments:The Department of Health's pending complementary medicine regulation amendments threaten to reclassify certain herbal supplements as scheduled medicines, forcing costly clinical trial investments.
- Technical Limitation in Bioavailability Preservation:Microencapsulation expertise remains concentrated with multinational contract manufacturers, constraining local producers from delivering extended-release formulations competitive with imported alternatives.
Strategic Opportunities
- Traditional African Botanical Commercialization:Rooibos, buchu, and devil's claw extracts command premium positioning in export markets as European and North American consumers seek novel adaptogenic ingredients with traceable indigenous sourcing.
- Online Channel Penetration:Direct-to-consumer platforms are capturing younger demographics in Durban and Pretoria who bypass pharmacy intermediaries for subscription-based personalized nutrition protocols.
- Pharmacy-Private Label Convergence:Clicks Group Limited's controlled pharmacy network creates captive distribution for clinically validated house brands, compressing marketing expenditure requirements for emerging formulators.
Industry Challenges
- Formulation Chemistry Talent Scarcity:South African universities produce insufficient graduates with combined expertise in pharmacognosy and food science, forcing manufacturers to recruit from European technical institutes at premium compensation.
- Clinical Substantiation Timeline Compression:The Medicines Control Council's evolving evidentiary standards for health claims require bioequivalence studies that extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Nutraceuticals Market |
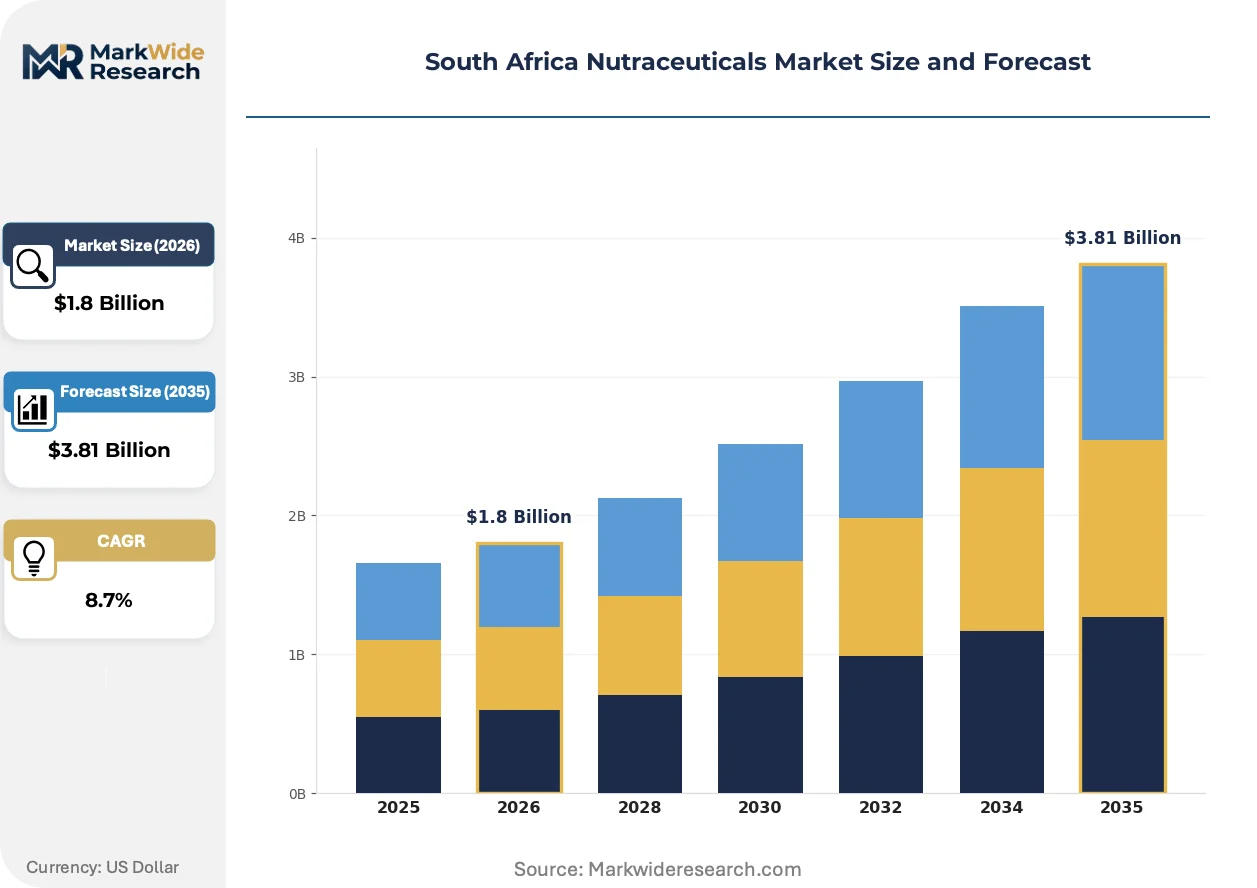
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Functional Foods End User: Health-conscious Consumers, Athletes, Elderly, Patients Form: Capsules, Powders, Liquids, Gummies Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Solal Technologies (Pty) Ltd., Vital Health Foods (Pty) Ltd., Herbalife Nutrition Ltd., USN (United States Nutrition), Ascendis Health, Amway South Africa (Pty) Ltd., Biogen (Pty) Ltd., Clicks Group Limited, Nutrilite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Nutraceuticals Market Evolving Landscape
Cold-press extraction and fermentation-based manufacturing are displacing conventional heat-processing methods across South African nutraceutical production, preserving thermolabile compounds in functional foods and herbal concentrates.
Fermentation-derived bioactive manufacturing is overtaking solvent-based extraction for probiotic and enzyme production in Cape Town's specialized manufacturing zones. Local contract manufacturers serving pharmacy chains are adopting this biotechnology to reduce dependency on imported active pharmaceutical ingredients. The shift is compressing cost structures for mid-tier supplement brands while elevating quality differentiation against commodity imports.
The Department of Health's pending amendments to complementary medicine regulations are forcing manufacturers to pre-position clinical trial data ahead of potential reclassification thresholds. This regulatory pressure is accelerating consolidation among smaller herbal supplement producers lacking documentation infrastructure. Established players with existing pharmacovigilance systems in Johannesburg are capturing market share from compliant importers.
Subscription-based personalized nutrition is disrupting traditional pharmacy replenishment patterns among millennials in urban centers. Digital health platforms integrating biomarker testing with automated supplement dispensing are replacing discretionary retail purchases. This behavioral shift concentrates most visibly in Gauteng's tech-savvy professional segments, where convenience premiums override brand loyalty to legacy multivitamin formulations.
South Africa Nutraceuticals Market Segmentation
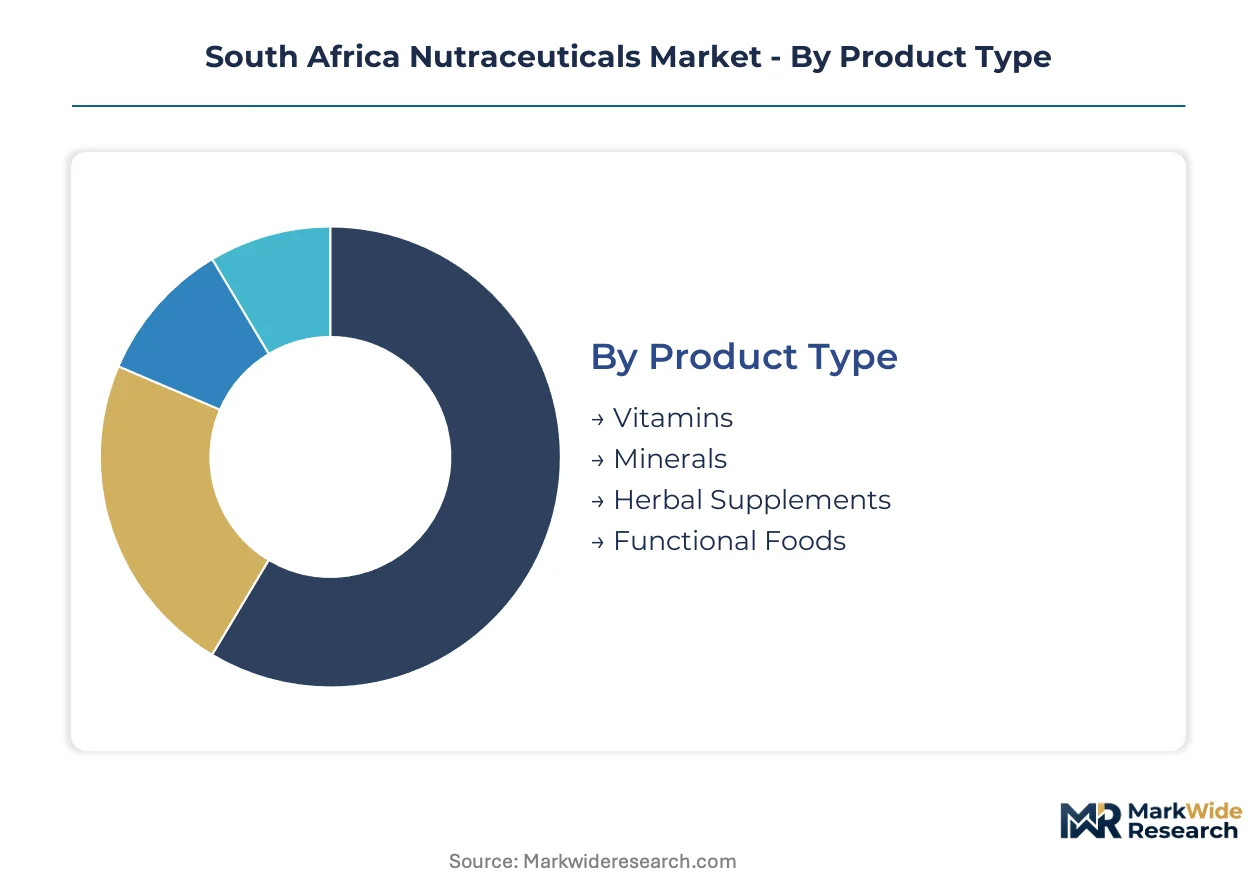
South Africa's nutraceuticals market fragments along four critical dimensions that determine pricing power, channel access, and regulatory burden. Understanding these splits reveals where formulation investments concentrate versus where commoditization pressures dominate.
Product Type:
Vitamins and functional foods anchor volume throughput, while herbal supplements command premium positioning through traceable indigenous sourcing.
- Vitamins:Synthetic and natural vitamin complexes constitute the largest revenue pool, with demand concentrating among elderly consumers in Gauteng seeking condition-specific nutritional support. Multivitamin formulations face margin compression from private-label pharmacy alternatives.
- Functional Foods:Probiotic yogurts, fortified cereals, and omega-3 enriched products generate recurring purchase frequency through supermarket distribution in Cape Town and Johannesburg. SABS quality benchmarking rewards clinically substantiated health claims with shelf placement priority.
- Herbal Supplements:Rooibos, buchu, and devil's claw extracts with documented traditional use histories.
- Minerals:Calcium, magnesium, and zinc formulations targeting bone health and immune function.
Today's leader: Vitamins. Tomorrow's challenger: Herbal Supplements.
End User:
Demographic targeting determines whether brands pursue pharmacy credibility or mass-market accessibility.
- Elderly:South Africa's aging population in Western Cape and Gauteng provinces drives concentrated demand for bone health, cardiovascular support, and cognitive function products. Pharmacy channel loyalty remains highest among this segment.
- Patients:Condition-specific nutritional support prescribed alongside pharmaceutical regimens requires Medicines Control Council registration compliance.
- Health-conscious Consumers:Urban professionals in Johannesburg and Cape Town prioritizing preventive wellness over reactive healthcare.
- Athletes:Protein supplements, electrolyte replacements, and recovery formulations targeting fitness enthusiasts in Durban and Pretoria.
The elderly segment commands pricing premiums; health-conscious consumers are expanding most quickly through direct-to-consumer channels.
Form:
Manufacturing complexity and bioavailability preservation differentiate delivery formats.
- Capsules:Hard-shell and soft-gel formats dominate pharmacy shelves, with microencapsulation expertise concentrated among multinational contract manufacturers. Cold-press extraction preserves thermolabile compounds in oil-based formulations.
- Powders:Bulk protein and meal replacement products serving athlete and weight management segments through specialized retail.
- Liquids:Pediatric and geriatric formulations where swallowing difficulty limits solid dosage adoption.
- Gummies:Palatability-driven formats gaining traction among younger demographics bypassing traditional supplement aversion.
Capsules retain manufacturing scale advantages; gummies are climbing the fastest as format innovation targets compliance improvement.
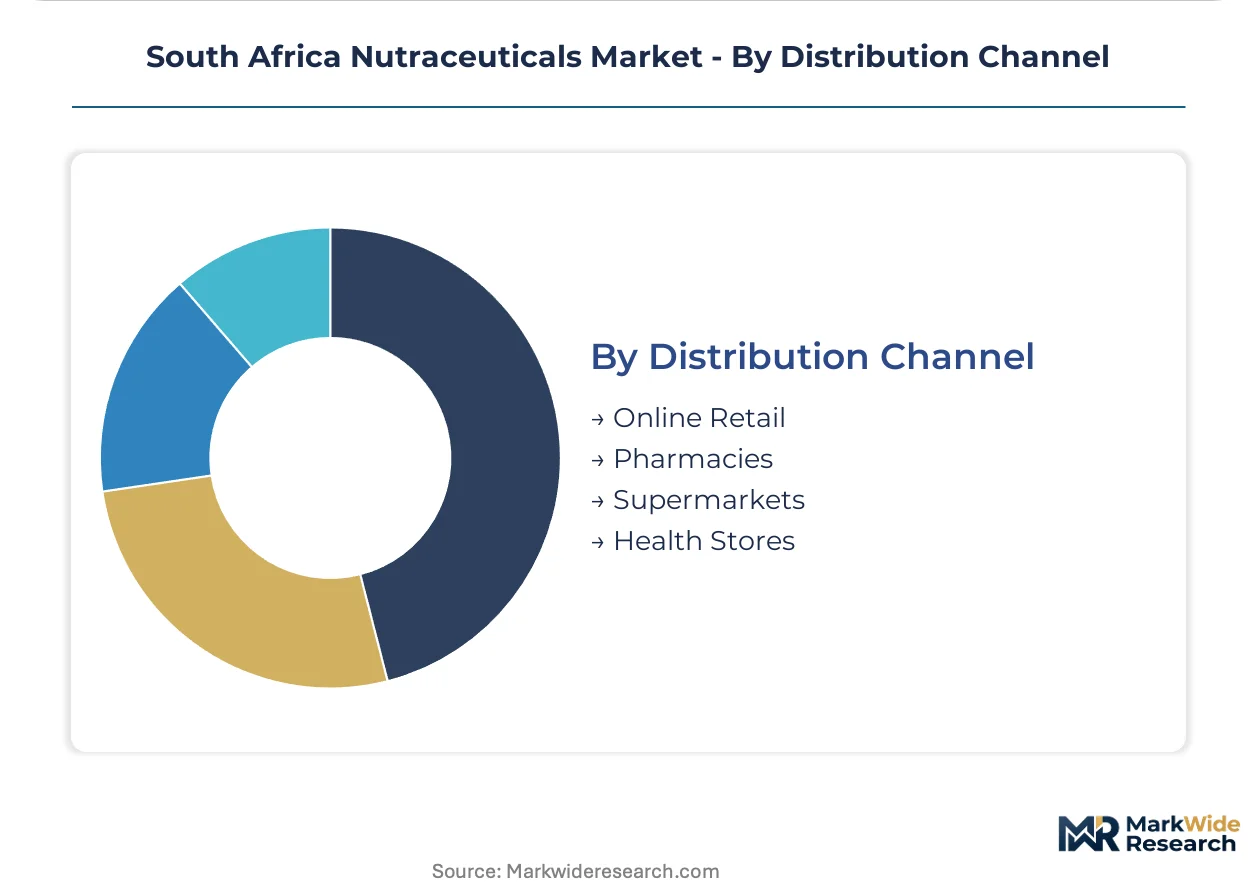
Distribution Channel:
Channel selection determines margin structure and consumer relationship depth.
- Pharmacies:Clicks Group Limited's controlled network creates captive distribution for clinically validated brands, with personalized consultation services sustaining margin strength. The Medicines Control Council's health claim registration requirements reinforce pharmacy credibility.
- Online Retail:Direct-to-consumer platforms capture millennials in Durban and Pretoria through subscription-based personalized nutrition protocols, eroding traditional pharmacy replenishment patterns.
- Supermarkets:Mass-market functional foods and commodity supplements competing on price and shelf visibility.
- Health Stores:Specialized retailers in urban centers providing botanical expertise and premium positioning for traditional African ingredients.
Pharmacies currently dominate value capture; online retail presents the steepest expansion trajectory among younger urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulation chemists and food science graduates from Stellenbosch University and University of Cape Town anchor Gauteng and Western Cape's nutraceutical manufacturing base, concentrating technical expertise in Johannesburg and Cape Town metropolitan corridors.
Gauteng
Johannesburg and Pretoria generate concentrated demand for condition-specific supplements among elderly consumers seeking bone health and cardiovascular support. The Medicines Control Council under the Department of Health enforces registration requirements for health claims that elevate compliance thresholds for local formulators. Manufacturing clusters in Midrand and Centurion host cold-press extraction facilities serving pharmacy distribution networks.
Western Cape
Cape Town's health-conscious urban professionals drive preventive wellness adoption through direct-to-consumer subscription platforms. The South African Bureau of Standards maintains functional food safety protocols that reward documented clinical substantiation with retail shelf placement priority. Fermentation-based manufacturing zones in Paarl and Stellenbosch specialize in probiotic and enzyme production for pharmacy chains.
KwaZulu-Natal
Durban's fitness enthusiast population sustains demand for protein supplements and electrolyte replacement formulations targeting athlete segments. The National Regulator for Compulsory Specifications oversees quality benchmarks for sports nutrition products entering mass retail channels. Specialized health stores in Umhlanga and Ballito provide botanical expertise for traditional African ingredient commercialization.
Eastern Cape
Port Elizabeth and East London manufacturing nodes serve emerging middle-class consumers through supermarket distribution of fortified cereals and omega-3 enriched functional foods. Pending amendments to complementary medicine regulations from the Department of Health threaten reclassification timelines for herbal supplement producers in the region. Industrial development zones near Coega attract contract manufacturers seeking port access for imported active ingredient supply chains.
South Africa Nutraceuticals Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Africa's nutraceutical sector, creating a tiered structure where manufacturing scale separates premium clinically validated formulations from commodity-grade alternatives. The market consolidates around three strategic archetypes: science-backed specialty formulators, diversified health conglomerates spanning multiple price points, and retail-controlled private label operators. M&A activity concentrates among mid-tier brands lacking pharmacovigilance infrastructure, while strategic partnerships between local formulators and multinational ingredient suppliers accelerate technology licensing for bioavailability preservation.
Within the premium specialty tier, Vital Health Foods exemplifies pharmacy channel control through science-backed positioning, while Ascendis Health occupies a diversified manufacturing role across branded and private label segments. Clicks Group Limited anchors retail-captive distribution, leveraging its controlled pharmacy network to compress marketing expenditure requirements for clinically validated house brands. These three players represent distinct competitive vectors—formulation credibility, manufacturing breadth, and channel dominance—that define strategic positioning in the South African market.
| Leading Market Players |
|---|
| Solal Technologies (Pty) Ltd. |
| Vital Health Foods (Pty) Ltd. |
| Herbalife Nutrition Ltd. |
| USN (United States Nutrition) |
| Ascendis Health |
| Amway South Africa (Pty) Ltd. |
| Biogen (Pty) Ltd. |
| Clicks Group Limited |
| Nutrilite |
| Others |
Value Network & Pricing Analysis
Cold-press extraction and microencapsulation technology adoption is compressing production costs for premium formulations while simultaneously concentrating manufacturing capability among contract manufacturers with European technical licensing. This dual effect creates pricing power asymmetry between pharmacy-distributed clinically validated brands and mass-market commodity alternatives.
Pricing Analysis
Pharmacy consultation bundling versus unbundled direct-to-consumer sales defines the dominant pricing split. Three-tier pricing structure across premium clinically validated, standard pharmacy private-label, and economy mass-market levels captures value differentiation. Price differentiation rests on Medicines Control Council registration status and SABS quality certification tier. Cost compression in the economy tier is intensifying because Clicks Group Limited's private-label expansion erodes branded multivitamin margins. Health-conscious millennials in Durban and Pretoria exhibit lowest price sensitivity through subscription convenience premiums, while supermarket functional food buyers in Eastern Cape remain most price-elastic.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-sensitive probiotic returns remains underdeveloped, forcing pharmacy chains to absorb spoilage costs rather than recirculate inventory. Active ingredient supply concentrates in Germany, Switzerland, and the United States for specialized cold-press extraction equipment and probiotic strain libraries. Raw material dependencies include rooibos leaf from Western Cape cultivation zones, imported omega-3 fish oil concentrates, and pharmaceutical-grade excipients from Indian API manufacturers. Single-source vulnerability for microencapsulation technology exposes local formulators to extended lead time volatility. Distribution runs through Clicks Group Limited's controlled pharmacy network for premium tiers, with supermarket mass retail capturing volume functional foods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
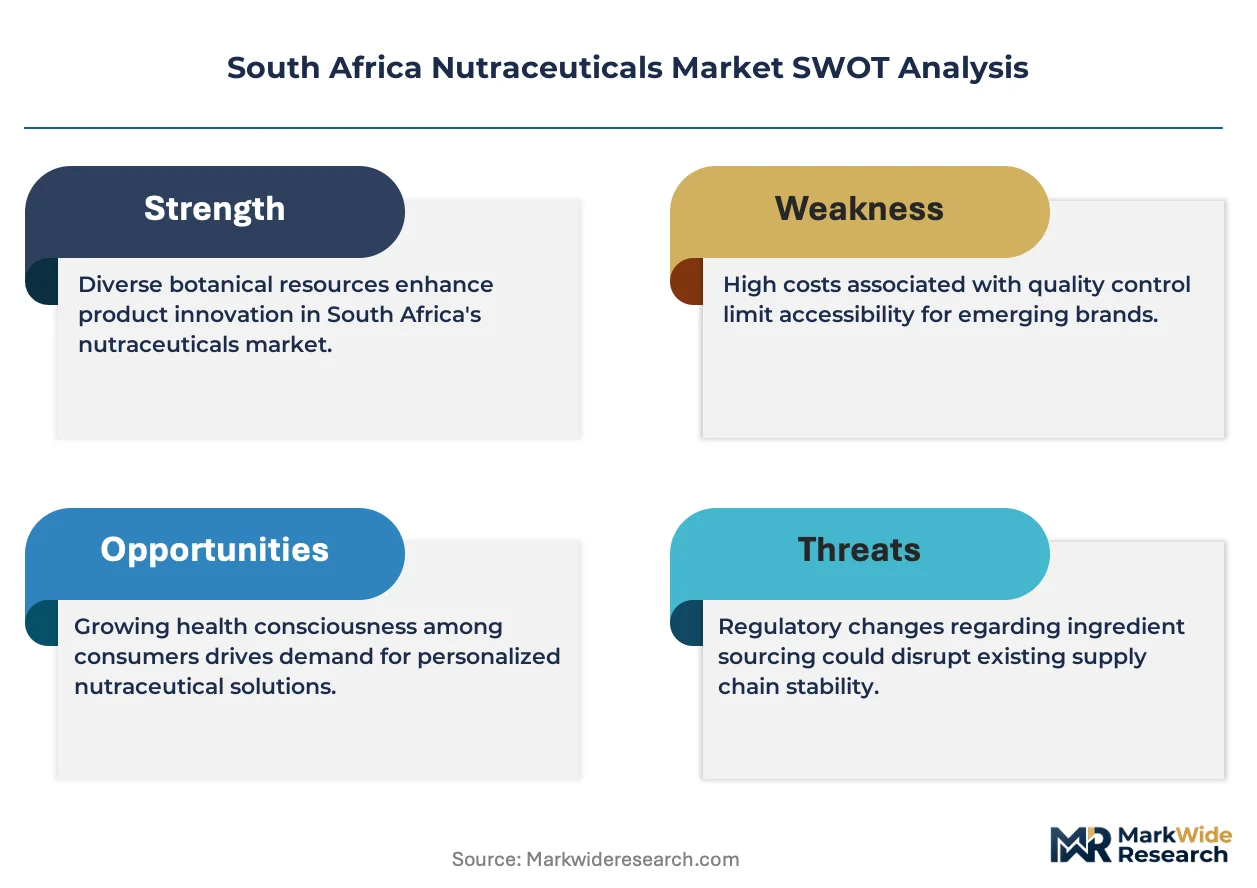
South Africa's nutraceutical sector functions as a geographic-arbitrage play where European-quality clinical substantiation standards meet lower local manufacturing overhead, creating margin expansion potential for compliant exporters serving EU and North American adaptogenic botanical demand.
For Market Incumbents: Deepen vertical integration into rooibos and buchu cultivation through Western Cape agricultural partnerships to secure traceable indigenous sourcing credentials against emerging Ethiopian and Kenyan botanical competitors. Expand Midrand cold-press extraction capacity to reduce dependency on European contract manufacturing for extended-release formulations. Medicines Control Council registration compliance creates defendable moats as pending complementary medicine amendments force costly clinical investments upon smaller rivals.
For New Entrants and Emerging Players: Rural elderly consumers in Eastern Cape and KwaZulu-Natal provinces represent an underserved buyer archetype bypassed by urban-focused direct-to-consumer platforms. Target this segment through mobile health worker partnerships delivering condition-specific nutritional support to township clinics and retirement communities. Pharmacy-private label convergence with Clicks Group Limited offers the most penetrable go-to-market angle for clinically validated house brand development.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier herbal supplement producers lacking pharmacovigilance documentation infrastructure yet possessing established traditional African botanical supply relationships. Long-term viability over the five-to-ten year window hinges on successful navigation of Department of Health regulatory amendments and export market access for indigenous ingredients. Monitor Medicines Control Council enforcement intensity and EU Novel Food approval timelines for rooibos-derived adaptogenic claims as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | Medicines Control Council registration compliance creates pharmacy channel access and pricing premium capture. |
| Indigenous Botanical Supply Integration | Western Cape cultivation partnerships secure rooibos and buchu traceability for EU export market positioning. |
| Direct-to-Consumer Platform Launch | Subscription-based personalized nutrition disrupts traditional pharmacy replenishment among Gauteng millennials. |
| Microencapsulation Technology Licensing | European contract manufacturer partnerships enable extended-release formulation competitiveness against imports. |
| Private Label Pharmacy Convergence | Clicks Group Limited captive distribution compresses marketing expenditure for clinically validated house brands. |
Research Methodology
Bottom-up patient and consumer demand modeling reconciled against top-down manufacturing capacity and import volume tracking forms the analytical core of this study. Primary interviews with pharmacy procurement managers, supplement brand marketing directors, Medicines Control Council regulatory affairs specialists, and Stellenbosch University food science faculty were validated against secondary sources including SABS quality certification databases, Department of Health complementary medicine regulation filings, and South African customs import records for active pharmaceutical ingredients. Triangulation between demand-side prescription patterns and supply-side production volumes ensures consistency across estimation approaches.
Historical trendline analysis of vitamin, functional food, herbal supplement, and mineral category growth rates established baseline momentum parameters. Segmentation modeling across product type, end-user demographic, delivery form, and distribution channel dimensions generated discrete growth trajectories across the projection horizon. CAGRs were derived from regression analysis against population aging curves, urban health consciousness indices, and regulatory compliance cost escalations. Forecast inputs include Gauteng and Western Cape elderly demographic concentration patterns and online retail penetration rates among millennial consumers.
Underlying measurement precision varies by segment; pharmacy-distributed vitamins with established prescription histories carry tighter precision than emerging direct-to-consumer personalized nutrition protocols. Forecasts reflect assumptions regarding Department of Health regulatory amendment timing and EU Novel Food approval pathways for traditional African botanicals. Practitioners should monitor Medicines Control Council enforcement intensity, rand-euro exchange rate volatility for imported active ingredients, and subscription platform customer acquisition cost trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
North America Whey Protein Market