
 US and Canada Beta Glucan Market | 2026-2036
US and Canada Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Beta Glucan Market Analytics
US heartland grain processing corridors are rewriting beta glucan supply dynamics as domestic oat milling capacity expands. Tate & Lyle PLC leverages its specialty ingredient distribution network to anchor North American food manufacturer relationships. Kerry Group sustains competitive positioning through integrated extraction capabilities and clean-label formulation expertise. Ceapro Inc. specializes in high-purity beta glucan isolates for pharmaceutical-grade applications, differentiating on bioactivity consistency.
US and Canada beta glucan comprises glucose polysaccharides extracted primarily from yeast cell walls, oat bran, and mushroom mycelia, with beta-(1,3/1,6)-D-glucan linkages conferring immunomodulatory and cholesterol-reduction properties; extraction methods span aqueous alkaline processing, acid precipitation, and enzymatic hydrolysis yielding molecular weights from 10 to 2,000 kDa. Powder formulations dominate ingredient manufacturing channels due to shelf stability and blending flexibility, while yeast-derived sources lead immunotherapy applications with higher branching ratios. Supplement applications are expanding fastest as consumer familiarity with immune health positioning deepens.
FDA qualified health claims for oat beta glucan and coronary heart disease risk reduction establish baseline product standards, while Health Canada's Natural Health Product Directorate governs dosage and labeling for supplement positioning. USDA organic certification and Non-GMO Project verification increasingly filter market access for premium-positioned ingredients. Stakeholders must monitor evolving fiber definition debates and immunotherapy clinical trial pipelines to align R&D allocation with regulatory-validated claim pathways.
Market Dynamics
FDA qualified health claims for oat beta glucan and coronary heart disease risk reduction have compressed the competitive window, forcing manufacturers to align extraction protocols with validated bioactivity thresholds or exit premium positioning entirely.
Growth Catalysts
- Heart Health Labeling:FDA's authorized health claim for beta glucan and reduced coronary heart disease risk drives reformulation across breakfast cereal and nutrition bar portfolios.
- Immunotherapy Pipeline Expansion:Yeast-derived beta-(1,3/1,6)-D-glucan isolates gain traction in oncology adjuvant applications, pulling pharmaceutical-grade demand upward.
- Midwest Processing Infrastructure:Concentrated oat milling capacity across Minnesota, Iowa, and Manitoba reduces inbound logistics costs for ingredient manufacturers.
Market Restraints
- Raw Material Volatility:Oat futures price swings and mycelium cultivation cycle variability compress margin predictability for extraction operators.
- Extraction Technology Concentration:Aqueous alkaline processing equipment suppliers cluster in Germany and Switzerland, creating import dependency for North American scale-up projects.
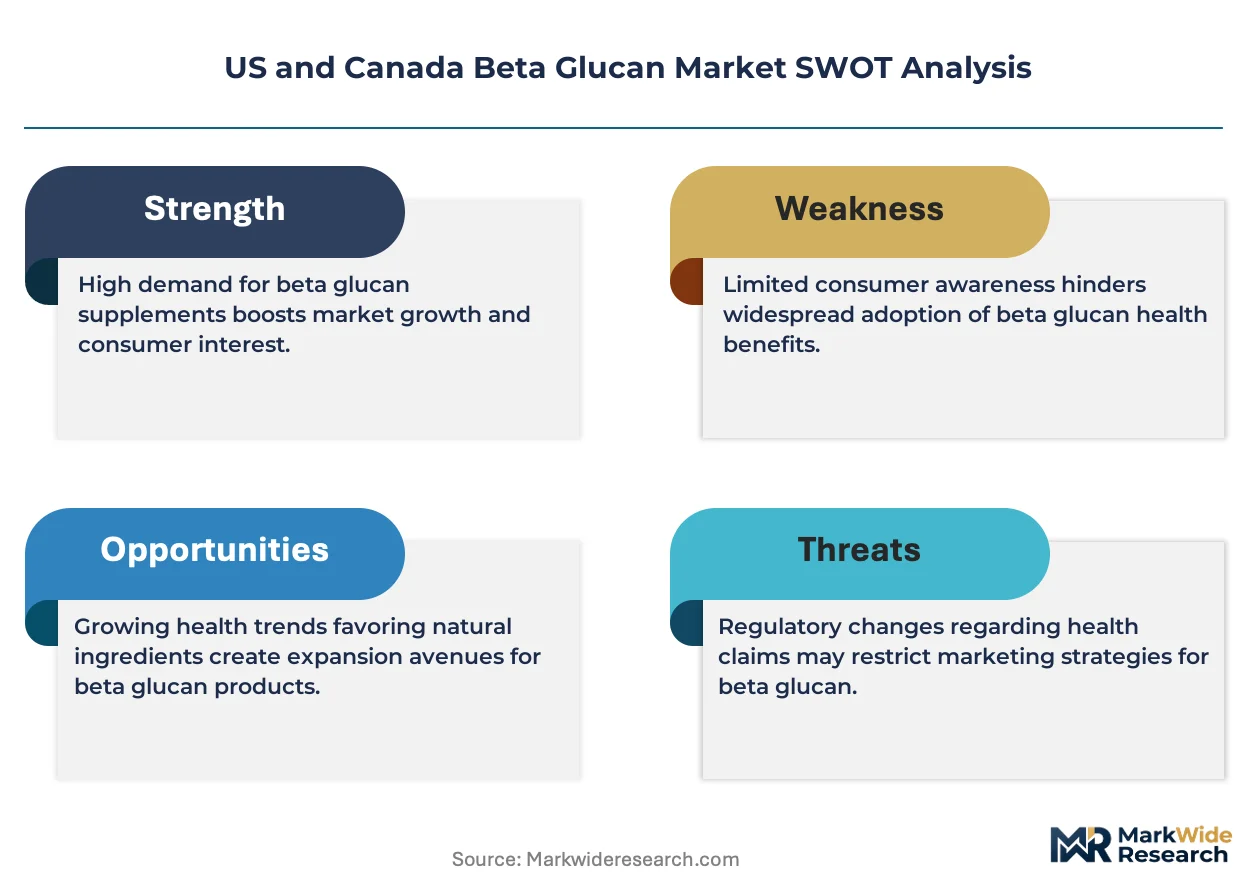
- Functional Ingredient Substitution:Psyllium husk and resistant starch compete for soluble fiber positioning in digestive health applications.
Strategic Opportunities
- Underpenetrated Western Canada:Prairie provinces lack dedicated beta glucan extraction facilities despite regional oat production density, creating greenfield entry potential.
- Personalized Nutrition Platforms:Direct-to-consumer microbiome testing services open channel partnerships for condition-specific beta glucan dosing protocols.
- USDA Organic Certification Tailwind:Premium organic oat beta glucan commands price multiples in infant formula and clinical nutrition segments.
Industry Challenges
- Chromatographic Purity Talent Gap:High-performance liquid chromatography specialists with polysaccharide characterization experience command premium compensation in biopharma-competing labor markets.
- Dual Jurisdiction Compliance Burden:Simultaneous FDA food additive and Health Canada Natural Health Product Directorate approvals extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Beta Glucan Market |
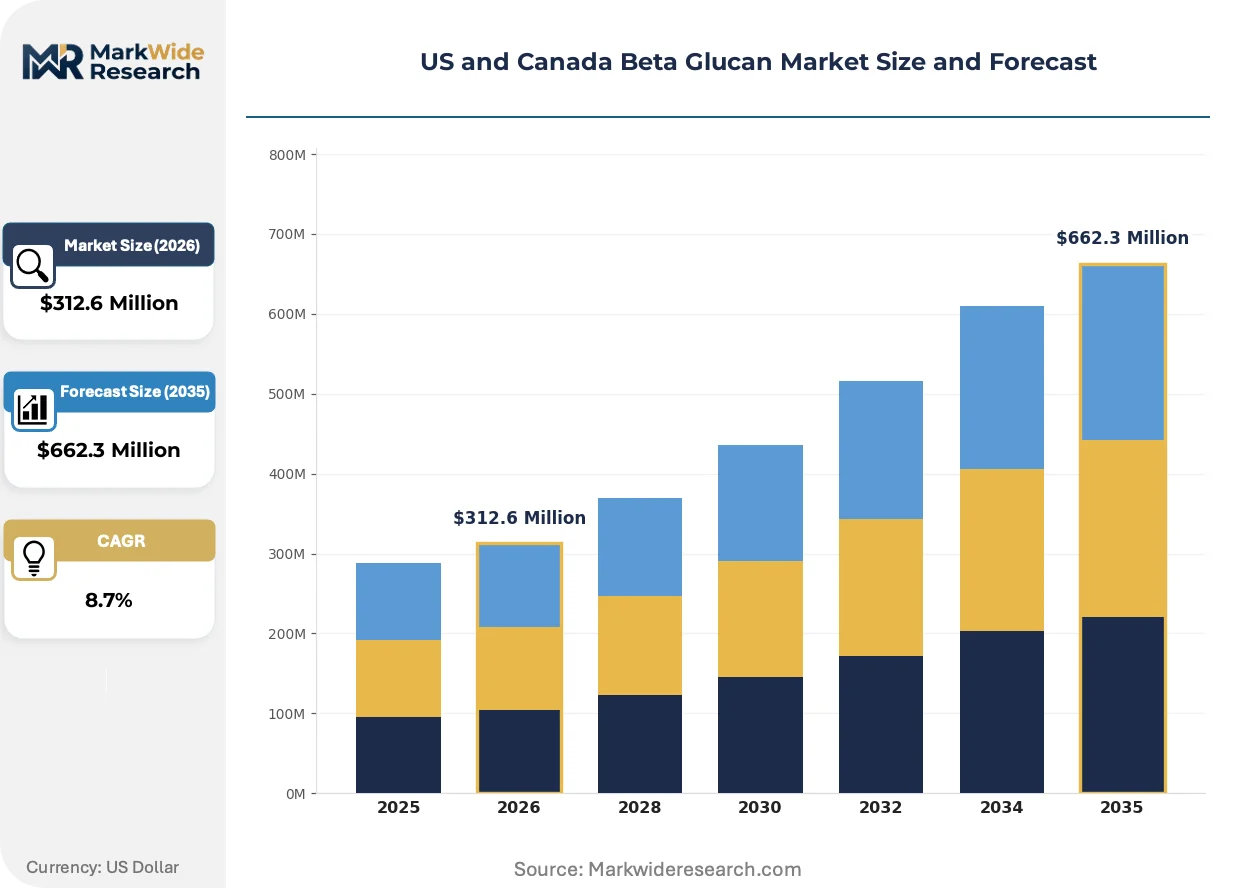
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Capsules Application: Food & Beverages, Supplements, Pharmaceuticals, Cosmetics Source: Yeast, Mushroom, Cereal, Others Delivery Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | Super Beta Glucan, Angel Yeast, Tate & Lyle PLC, Lesaffre, Ceapro Inc., Kerry Group, Biorigin S.A., Kemin Industries, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Beta Glucan Market Evolving Landscape
Enzymatic extraction protocols and precision fermentation are compressing traditional batch processing economics while regulatory agencies on both sides of the border tighten bioactivity validation standards for immune health positioning.
Enzymatic hydrolysis using specific endo-beta-glucanases is collapsing the cost differential between laboratory-grade and food-grade beta glucan purity tiers. Contract manufacturers in Wisconsin and Ontario are retrofitting existing starch processing lines to accommodate enzymatic cell wall disruption. This technology convergence enables mid-scale ingredient suppliers to enter pharmaceutical adjuvant markets previously reserved for dedicated extraction specialists.
Health Canada's Natural Health Product Directorate has tightened monograph requirements for yeast-derived beta glucan immune claims, requiring quantitative (1,3/1,6)-linkage ratio disclosure on all supplement labels. Canadian formulators are restructuring supply agreements to secure certificates of analysis specifying branching patterns. US manufacturers anticipating similar FDA enforcement are voluntarily adopting Health Canada standards to preempt compliance disruption.
Ingredient procurement from functional food brands is consolidating toward vertically integrated oat processors with captive analytical laboratories. CPG buyers in the US Northeast and Pacific Northwest are bypassing traditional ingredient distributors for direct tolling arrangements with prairie grain handlers. This disintermediation concentrates volume with operators controlling both varietal selection and extraction yield optimization.
US and Canada Beta Glucan Market Segmentation
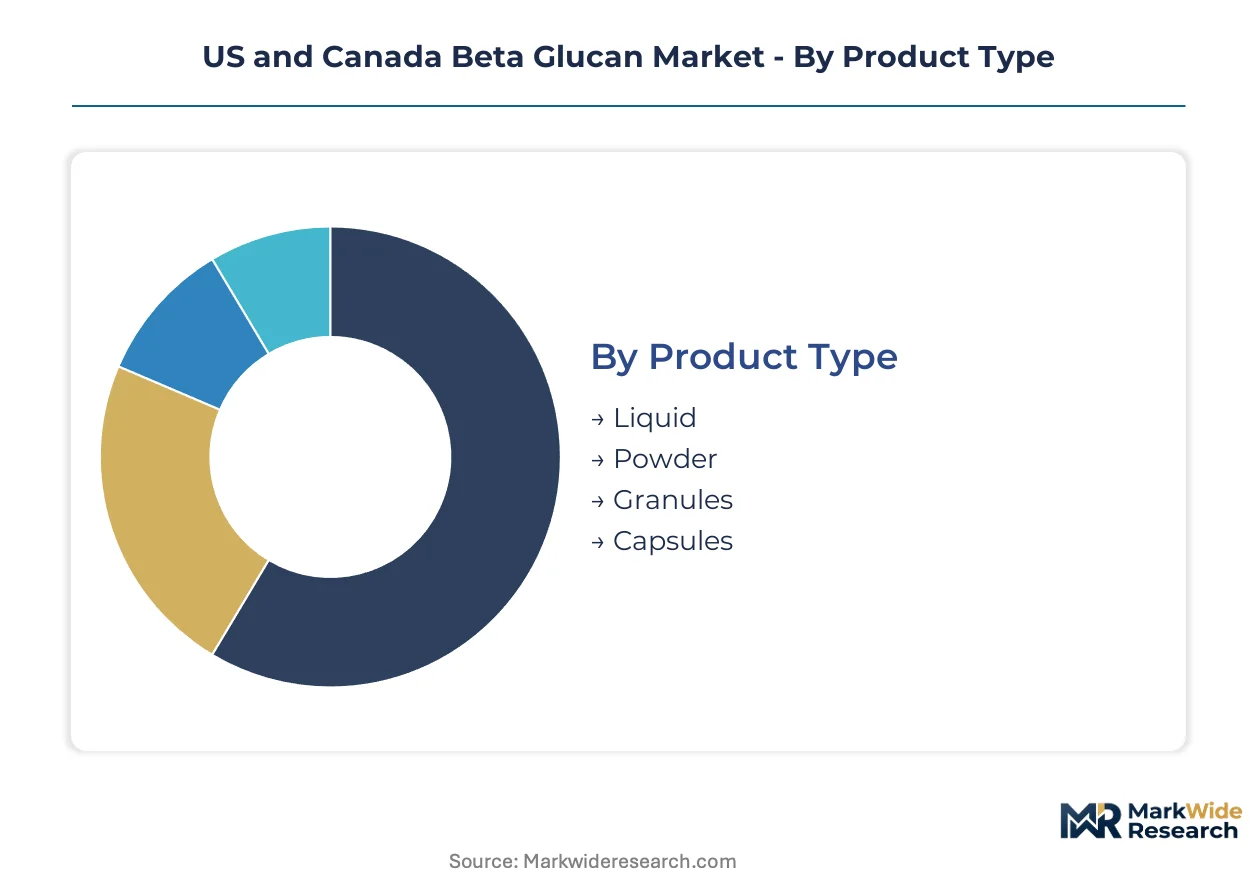
Beta glucan formulations demand distinct technical support protocols across product formats, with powder and liquid variants requiring specialized stability consulting while pharmaceutical-grade isolates necessitate batch-specific bioactivity documentation. Segmentation reveals how extraction purity tiers and delivery complexity reshape manufacturer-customer relationships across the value chain.
Product Type:
After-sales intensity escalates with formulation complexity, as liquid concentrates demand cold-chain validation support and granule formats require blending compatibility testing that powder standards rarely trigger.
- Powder:Shelf-stable polysaccharide concentrates with standardized particle size distributions dominate ingredient manufacturing channels. Food and beverage formulators in Minnesota and Iowa specify powder grades for seamless integration into dry-mix applications, with enzymatic hydrolysis advances collapsing purity-tier cost differentials.
- Liquid:Aqueous suspensions with preserved bioactive integrity serve functional beverage manufacturers requiring rapid dissolution profiles. Pacific Northwest kombucha and oat milk producers concentrate procurement here, though cold-chain logistics constrain distribution radius and elevate technical service demands.
- Granules:Agglomerated formats bridge powder flowability and liquid dispersibility for tablet compression lines.
- Capsules:Pre-metered unit doses target direct-to-consumer supplement brands with simplified quality assurance protocols.
By volume, Powder leads. By growth pace, Liquid is ahead.
Application:
Application segmentation tracks how regulatory validation burdens concentrate in pharmaceutical channels while food positioning leverages established FDA health claim pathways.
- Supplements:Immune health positioning drives yeast-derived beta glucan demand with Health Canada NHP Directorate monograph compliance requirements. Direct-to-consumer brands in Ontario and California structure supply agreements around quantitative (1,3/1,6)-linkage ratio certificates, with microbiome testing partnerships opening condition-specific dosing protocols.
- Food & Beverages:Oat beta glucan fortification leverages FDA qualified health claims for coronary heart disease risk reduction. Breakfast cereal and nutrition bar portfolios across the US Midwest reformulate around soluble fiber thresholds, with organic certification commanding price multiples in infant formula segments.
- Pharmaceuticals:Oncology adjuvant applications require pharmaceutical-grade isolates with documented endotoxin limits and chromatographic purity profiles.
- Cosmetics:Topical formulations exploit moisture-retention properties of lower molecular weight fractions in dermal care products.
Supplements generate the steepest expansion trajectory as consumer familiarity with immune health positioning deepens.
Source:
Source segmentation reflects extraction infrastructure concentration, with prairie oat processing corridors competing against fermentation-based yeast production for supply dominance.
- Yeast:Saccharomyces cerevisiae cell walls yield beta-(1,3/1,6)-D-glucan with immunomodulatory branching ratios optimized for therapeutic applications. Wisconsin and Ontario contract manufacturers retrofit starch processing lines for enzymatic cell wall disruption, enabling mid-scale suppliers to enter pharmaceutical adjuvant markets.
- Cereal:Oat bran concentrates deliver cholesterol-reduction bioactivity with established FDA health claim validation. Manitoba and Minnesota milling clusters reduce inbound logistics costs for North American ingredient manufacturers, though organic certification gaps limit premium segment access.
- Mushroom:Mycelium cultivation cycles generate beta-glucan fractions with distinct molecular weight profiles for specialized therapeutic positioning.
- Others:Algae and bacterial fermentation sources occupy nascent supply positions with unstandardized extraction protocols.
Cereal sources anchor volume throughput. Yeast sources are climbing the fastest on immunotherapy pipeline pull.
Delivery Mode:
Delivery segmentation maps regulatory jurisdiction complexity, with oral formats navigating food-additive pathways while injectable routes require biologic licensing.
- Oral:Gastrointestinal absorption of soluble fiber fractions supports digestive health and cardiovascular positioning with established safety profiles. Health Canada and FDA labeling guidelines for soluble fiber claims shape product development pipelines across functional food and supplement channels.
- Topical:Dermal penetration of lower molecular weight beta glucan serves wound healing and cosmetic moisture-retention applications with localized regulatory requirements.
- Injectable:Parenteral formulations demand pharmaceutical-grade purity with endotoxin limits and sterility validation for oncology adjuvant protocols.
- Intravenous:Hospital-administered immunotherapy applications require batch-specific bioactivity documentation and adverse event monitoring infrastructure.
Oral delivery commands volume dominance. Injectable formats are gaining share fastest on clinical trial pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US and Canada Beta Glucan consumption patterns diverge sharply across the border. American demand concentrates in cardiovascular-positioned food fortification, while Canadian procurement tilts toward immunotherapy-grade isolates governed by stricter natural health product regulations.
Midwest United States
Minnesota and Iowa oat milling corridors anchor North American supply infrastructure. FDA qualified health claims for coronary heart disease risk reduction drive breakfast cereal and nutrition bar reformulation across the region. Twin Cities processing clusters reduce inbound logistics costs for ingredient manufacturers sourcing prairie-grown oats.
Pacific Northwest United States
Oregon and Washington functional beverage manufacturers concentrate procurement in liquid beta glucan suspensions for kombucha and oat milk applications. USDA organic certification requirements filter supplier access for premium-positioned brands. Seattle-area formulation labs provide technical support for cold-chain validation protocols.
Ontario
Toronto and Waterloo supplement brands structure supply agreements around Health Canada Natural Health Product Directorate monograph compliance. Quantitative (1,3/1,6)-linkage ratio certificates have become mandatory for yeast-derived immune health positioning. Contract manufacturers retrofit starch processing lines for enzymatic extraction protocols.
Prairie Provinces
Manitoba and Saskatchewan oat production density exceeds regional extraction capacity, creating greenfield entry potential for dedicated facilities. Health Canada labeling guidelines for soluble fiber claims shape product development pipelines. Winnipeg grain handlers increasingly bypass traditional distributors for direct tolling arrangements with CPG buyers.
US and Canada Beta Glucan Market Competitive Landscape
Capability concentration sits with pharmaceutical-grade specialists; scale advantage sits with integrated grain processors. The market structures around three tiers: multinational ingredient distributors with established food manufacturer relationships, regional extraction operators with captive analytical capabilities, and contract manufacturers retrofitting existing starch lines. Dominant competitive moves include backward integration into oat varietal selection and strategic partnerships with microbiome testing platforms for personalized nutrition protocols.
Within the specialty extraction tier, Ceapro Inc. and Super Beta Glucan exemplify high-purity isolate capabilities for therapeutic applications. Tate & Lyle PLC and Kerry Group occupy positions bridging food-grade distribution networks with pharmaceutical-adjacent technical service. Angel Yeast represents the fermentation-derived supply vector with integrated yeast cell wall processing capabilities.
| Leading Market Players |
|---|
| Super Beta Glucan |
| Angel Yeast |
| Tate & Lyle PLC |
| Lesaffre |
| Ceapro Inc. |
| Kerry Group |
| Biorigin S.A. |
| Kemin Industries |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
German and Swiss aqueous alkaline processing equipment suppliers anchor upstream cost structures for North American extraction scale-up projects, concentrating margin pools with tolling operators in Minnesota and Iowa who control captive oat varietal selection. This upstream dependency compresses procurement flexibility for mid-scale ingredient manufacturers seeking pharmaceutical-grade purity tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between prairie oat processors and CPG manufacturers, though spot purchasing persists for organic-certified grades where supply intermittency elevates premiums. Price differentiation hinges on Health Canada NHP Directorate compliance documentation and USDA organic certification status, with the former commanding substantial premiums in supplement channels. Cost compression in standard-grade yeast-derived isolates is intensifying because enzymatic hydrolysis retrofits collapse purity-tier cost differentials. Nutrition bar and breakfast cereal manufacturers exhibit highest price sensitivity, while oncology adjuvant pharmaceutical buyers prioritize bioactivity consistency over unit economics.
Supply Chain Analysis
Extended payment terms from prairie grain handlers to Wisconsin and Ontario contract manufacturers are restructuring working capital requirements across enzymatic extraction retrofit projects. Geographic supply concentration centers on the United States, Canada, and Germany, with the latter anchoring equipment fabrication dependencies. Raw material sourcing draws from prairie oat cultivation, Saccharomyces cerevisiae fermentation facilities, and mycelium cultivation operations in British Columbia. Single-source vulnerability in chromatographic purity characterization equipment creates bottlenecks for pharmaceutical-grade batch validation. Distribution runs through direct tolling arrangements that disintermediate traditional ingredient distributors for CPG buyers in the US Northeast and Pacific Northwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from psyllium husk and resistant starch in digestive health applications, requiring defensive repositioning around validated immunomodulatory bioactivity that fiber alternatives cannot replicate.
For Market Incumbents: Entrench FDA qualified health claim positioning through backward integration into oat varietal breeding programs that optimize beta-glucan yield per acre. Secure Health Canada NHP Directorate monograph compliance documentation ahead of anticipated FDA enforcement convergence. Pharmaceutical-grade specialists must defend against enzymatic hydrolysis retrofit competitors by locking in chromatographic purity talent through long-term compensation structures.
For New Entrants and Emerging Players: Build out dedicated extraction capacity in Manitoba and Saskatchewan where prairie oat production density exceeds regional processing infrastructure. Target underpenetrated Western Canada through direct tolling arrangements with Winnipeg grain handlers bypassing distributor markups. Enter through USDA organic certification pathways that command price multiples in infant formula and clinical nutrition segments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers in Wisconsin and Ontario that have completed enzymatic extraction retrofits but lack pharmaceutical-grade validation infrastructure. Long-term viability over the coming decade rests on immunotherapy pipeline expansion sustaining yeast-derived isolate demand. Watch Health Canada and FDA regulatory convergence on quantitative (1,3/1,6)-linkage ratio disclosure requirements as the signal for premium-tier pricing compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Retrofit | Wisconsin and Ontario contract manufacturers collapse cost differentials between laboratory-grade and food-grade purity tiers. |
| Health Canada NHP Monograph Compliance | Canadian formulators restructure supply agreements around quantitative linkage ratio certificates ahead of FDA convergence. |
| USDA Organic Certification Investment | Premium organic oat beta glucan commands price multiples in infant formula and clinical nutrition channels. |
| Direct Tolling Arrangement Expansion | Prairie grain handlers bypass traditional distributors for CPG buyers in the US Northeast and Pacific Northwest. |
| Chromatographic Purity Talent Acquisition | High-performance liquid chromatography specialists command premium compensation in biopharma-competing labor markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, Health Canada NHP Directorate monographs, and USDA organic certification databases. Primary interviews engaged extraction technology directors at prairie oat processors, regulatory affairs leads at supplement manufacturers, procurement managers at functional food CPGs, and analytical laboratory directors at contract manufacturers. Secondary validation drew from SEC 10-K filings of publicly traded ingredient distributors, trade customs data for oat bran concentrate imports, and clinical trial registrations for oncology adjuvant applications. Bottom-up volume modeling from extraction capacity utilization triangulates against top-down demand aggregation across application segments.
Forecast inputs incorporate extraction yield optimization trajectories, enzymatic hydrolysis adoption curves, and regulatory validation timeline assumptions across the projection horizon. Segmentation dimensions modeled include product type, application, source, and delivery mode, with additional stratification by certification tier and purity grade. CAGRs derive from regression analysis of historical volume trajectories against projected capacity additions and demand elasticity parameters. Industry-specific inputs include oat futures price volatility assumptions and immunotherapy clinical trial pipeline progression rates.
Practitioners should monitor oat futures price swings, Health Canada and FDA regulatory convergence timing, and immunotherapy clinical trial readouts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Global Nutraceutical Market