
 L-Leucine Market | 2026-2036
L-Leucine Market Size, Share, and Industry Trends Forecast 2026-2036
L-Leucine Market Foresight
The L-leucine supply landscape is rebalancing between pharmaceutical-grade fermentation output and commodity-grade protein hydrolysate streams. Ajinomoto Co., Inc. leverages decades of microbial fermentation expertise to sustain premium positioning in amino acid purity. Fufeng Group Company Limited anchors volume production through integrated corn-processing infrastructure in Shandong Province. Evonik Industries AG differentiates via biotechnology leadership in precision fermentation for pharmaceutical applications.
L-leucine is an essential branched-chain amino acid with the molecular formula C₆H₁₃NO₂, synthesized industrially through microbial fermentation of glucose-derived substrates or protein hydrolysis, and serves primarily as a nutritional supplement and pharmaceutical intermediate for protein synthesis modulation. Powder formulations dominate commercial volumes due to lower production costs and broader formulation flexibility in sports nutrition blends. Muscle recovery applications within the application dimension attract premium pricing from endurance athletes and aging populations seeking sarcopenia mitigation. Online retail channels now capture the fastest-growing share of distribution, displacing traditional pharmacy and specialty store routes as direct-to-consumer brands proliferate.
FDA dietary supplement regulations under 21 CFR 111 govern manufacturing practices for L-leucine sold in the United States, while EFSA novel food assessments shape market access for fermented variants in European Union member states. China's NMPA and national food safety standards enforce purity thresholds for amino acid additives in domestic nutritional products. Stakeholders must monitor evolving fermentation substrate costs and regulatory divergence between pharmaceutical and food-grade specifications when allocating capacity investments.
Market Dynamics
Fermentation technology is consolidating L-leucine production around glucose-derived microbial platforms, squeezing out protein hydrolysate methods and concentrating supply among biotech-capable manufacturers with integrated substrate access.
Growth Catalysts
- Sports Nutrition Formulation Demand:Branched-chain amino acid blends for bodybuilders and endurance athletes pull pharmaceutical-grade L-leucine into powder and capsule formats. Supplement brands specify minimum 98.5% purity thresholds.
- 21 CFR 111 Compliance:FDA current good manufacturing practice mandates for dietary supplements force quality upgrades across US-bound production, filtering out sub-scale hydrolysate operations.
- Sarcopenia Research Momentum:Clinical trials on muscle protein synthesis in aging populations expand prescription-grade applications beyond athletics into medical nutrition.
Market Restraints
- Corn Price Volatility:Fermentation substrate costs swing with Shandong Province grain markets, compressing margin predictability for glucose-dependent producers.
- Shandong Supply Concentration:Three integrated corn processors control bulk fermentation capacity, creating single-geography disruption risk for global amino acid flows.
- Protein Hydrolysate Residuals:Lower-purity acid-hydrolyzed streams from soy and feather meal compete on price in feed-grade applications, capping premiumization in commodity segments.
Strategic Opportunities
- Precision Fermentation Convergence:Synthetic biology tools combined with continuous bioprocessing enable strain optimization for pharmaceutical-grade titers previously unattainable with batch methods.
- Direct-to-Consumer Channel Expansion:Subscription-based supplement platforms bypass pharmacy and specialty retail intermediaries, capturing full margin stack from formulation to doorstep delivery.
- EFSA Novel Food Pathways:Fermented amino acid variants without animal-source history qualify for streamlined safety assessments, accelerating European market access for microbial-derived products.
Industry Challenges
- Pharmaceutical-Grade Validation Timelines:USP and EP certification for injectable-grade L-leucine requires 18-24 month stability studies, delaying capacity monetization.
- Continuous Bioprocessing Talent Scarcity:Fermentation engineers with perfusion bioreactor expertise command premium compensation, constraining scale-up velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Leucine Market |
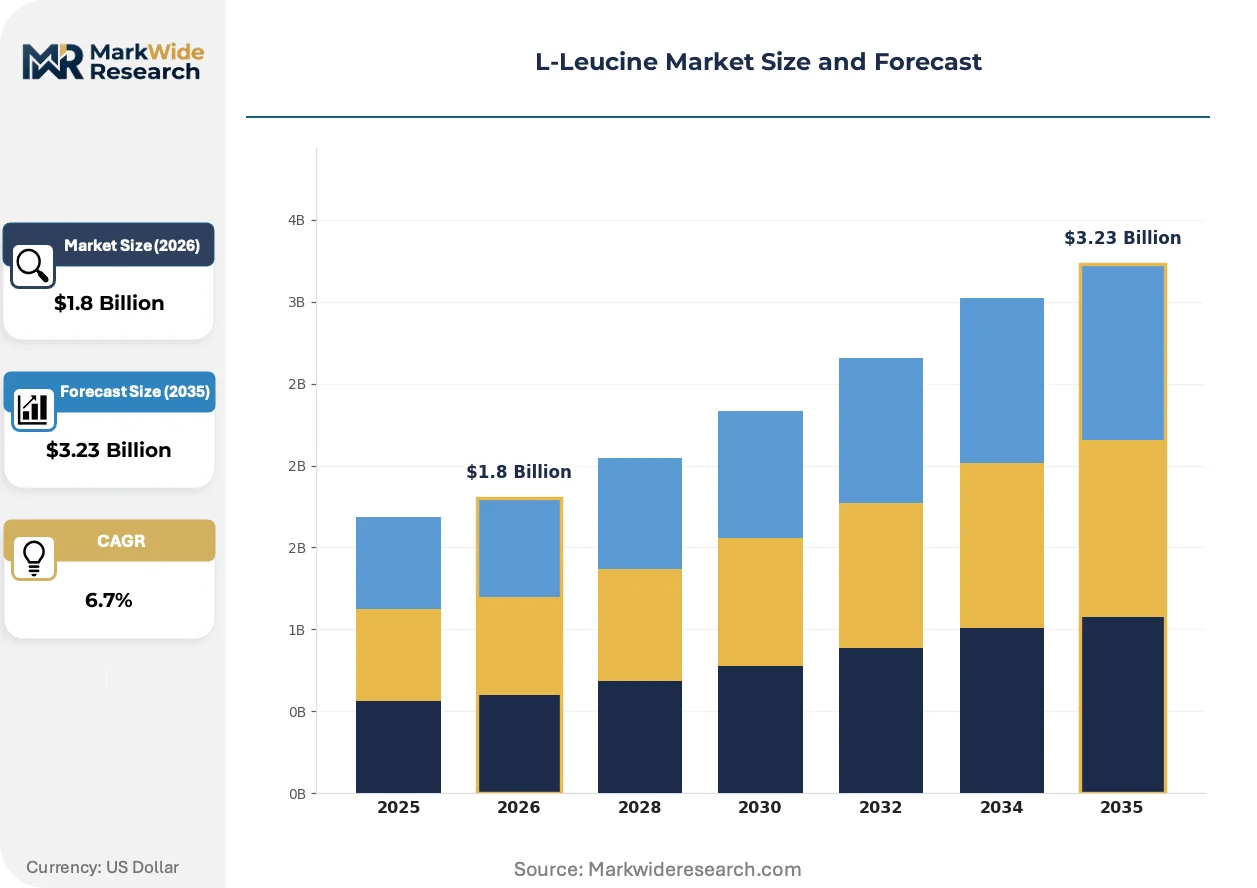
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid End User: Bodybuilders, Athletes, Nutritional Supplement Consumers, Health Enthusiasts Application: Muscle Growth, Weight Loss, Muscle Recovery, General Health Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Meihua Holdings Group Co., Ltd., Wuxi Jinghai Amino Acid Co., Ltd., Ajinomoto Co., Inc., Amino GmbH, Fufeng Group Company Limited, Evonik Industries AG, CJ CheilJedang Corporation, Daesang Corporation, Kyowa Hakko Bio Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Leucine Market Shifts & Advancements
Bioprocessing automation and regulatory differentiation are fragmenting the competitive landscape between commodity feed-grade suppliers and precision fermentation specialists targeting pharmaceutical applications.
Continuous perfusion fermentation is electrifying L-leucine manufacturing economics by maintaining cells in exponential growth phase indefinitely. Contract development and manufacturing organizations adopt these systems to serve peptide API producers requiring consistent isotopic labeling. The technology is compressing batch-to-batch variability and enabling real-time quality release.
EFSA novel food assessments under Regulation 2015/2283 are reshaping market access rules for microbial-derived amino acids in European Union member states. Fermentation substrates must demonstrate absence of allergenic protein residues, forcing substrate supply chain documentation upgrades. Sports nutrition brands reformulating for EU compliance now specify non-animal derived certificates of origin.
Ingredient sourcing decisions increasingly hinge on blockchain-verified chain-of-custody documentation rather than traditional supplier audits. Direct-to-consumer brands displace legacy wholesale relationships by marketing fermentation provenance and carbon intensity scores to end-users. This behavioral shift concentrates in North American and Western European premium supplement segments where clean-label claims command shelf price premiums.
L-Leucine Market Segmentation
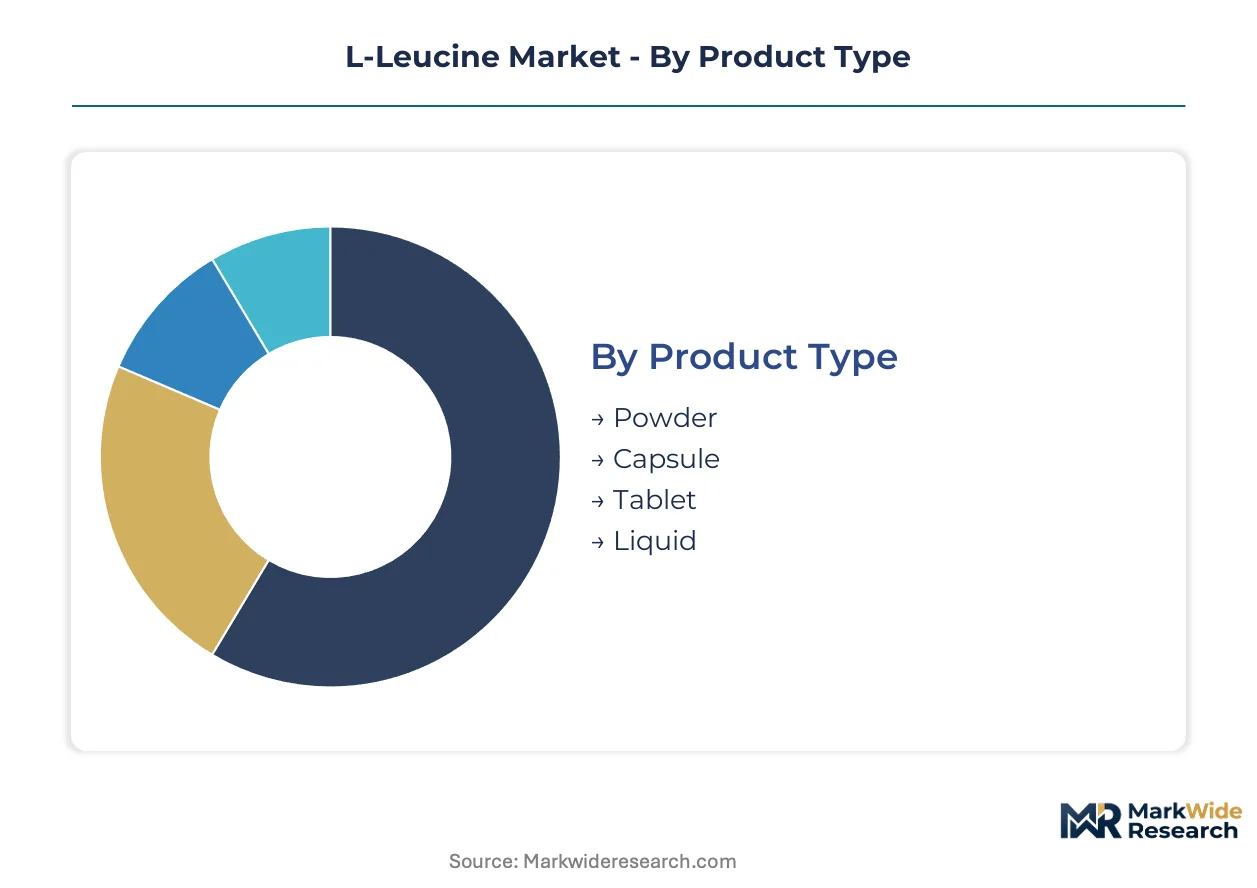
Segmentation in the L-leucine market separates pharmaceutical-grade fermentation output from commodity-grade streams, with purity thresholds and formulation flexibility determining pricing power across each category. Buyers in sports nutrition prioritize dissolution rates and blend compatibility, while medical nutrition customers demand USP-certified batches with full chain-of-custody documentation.
Product Type:
Powder formulations attract cost-sensitive bulk buyers in sports nutrition, while capsules and tablets command premiums from convenience-focused consumers seeking pre-measured dosing.
- Powder:Crystalline L-leucine with particle sizes optimized for beverage solubility dominates commercial volumes due to lower unit production costs and broader formulation flexibility in pre-workout blends. Demand concentrates among bodybuilders in China and the United States who mix custom branched-chain amino acid ratios, though caking issues during humid storage create quality complaints in Southeast Asian distribution.
- Capsule:Hard-shell gelatin and vegetable-derived encapsulation delivers precise 500-1000mg dosing for endurance athletes requiring portability during training blocks. German and Japanese buyers specify delayed-release polymer coatings to bypass gastric degradation and maximize plasma leucine spike timing.
- Tablet:Compressed formulations with binders and lubricants suit pharmacy-channel distribution where pill-count packaging aligns with prescription medical nutrition protocols. Aging populations in Italy and Spain seeking sarcopenia mitigation drive steady demand despite slower disintegration rates compared to powders.
- Liquid:Ready-to-drink suspensions with flavor masking systems target CrossFit and functional fitness segments in Australia and Canada where immediate consumption post-workout is prioritized over cost efficiency.
Powder leads volumes today; liquid is gaining share fastest.
End User:
Performance requirements and purchasing sophistication create distinct buyer tiers, from competitive athletes demanding batch-tested purity to casual wellness consumers responding to influencer marketing.
- Bodybuilders:Competitive physique athletes in the United States and United Kingdom specify minimum 98.5% purity with third-party banned substance certification, driving pharmaceutical-grade fermentation demand. These buyers purchase through direct-to-consumer subscription platforms that bypass traditional retail markups.
- Athletes:Endurance competitors in cycling, triathlon, and team sports prioritize leucine-enriched recovery formulations with rapid gastric emptying properties. Japanese Olympic training centers and Australian Institute of Sport procurement contracts set quality benchmarks that filter down to amateur segments.
- Nutritional Supplement Consumers:Daily users stacking L-leucine with creatine and protein powders represent the volume base, with purchasing decisions driven by price-per-serving calculations and flavor compatibility. Chinese e-commerce festivals trigger bulk purchasing patterns that strain fermentation capacity.
- Health Enthusiasts:Wellness-focused buyers without specific athletic goals respond to longevity and metabolic health messaging, particularly in California and Nordic markets where biohacking culture intersects with supplement use.
Nutritional supplement consumers anchor current demand; athletes are expanding most quickly.
Application:
Clinical validation levels and dosing precision requirements separate medical-grade muscle preservation from lifestyle-oriented fitness applications.
- Muscle Growth:Resistance training protocols leveraging leucine's mTOR activation pathway require 2.5-3g acute doses, with powdered formulations preferred for stacking flexibility. Young male demographics in Brazil and Mexico drive volume through gym-affiliated retail channels.
- Weight Loss:Leucine's role in preserving lean mass during caloric deficit is marketed to intermittent fasting and ketogenic diet adherents, with capsule formats preferred for compliance in portion-controlled regimens. French and German consumers show strongest response to metabolic health positioning.
- Muscle Recovery:Post-exercise soreness reduction claims attract premium pricing from masters athletes and aging populations, with clinical trial backing from institutions like McMaster University strengthening positioning. Hospital discharge protocols in Japan now include leucine supplementation for post-surgical recovery.
- General Health:Broad wellness positioning without specific performance claims competes on price with other amino acids and protein sources, capturing price-sensitive buyers in emerging markets where supplement penetration is deepening.
Muscle growth commands the largest share; muscle recovery shows the steepest expansion trajectory.
Distribution Channel:
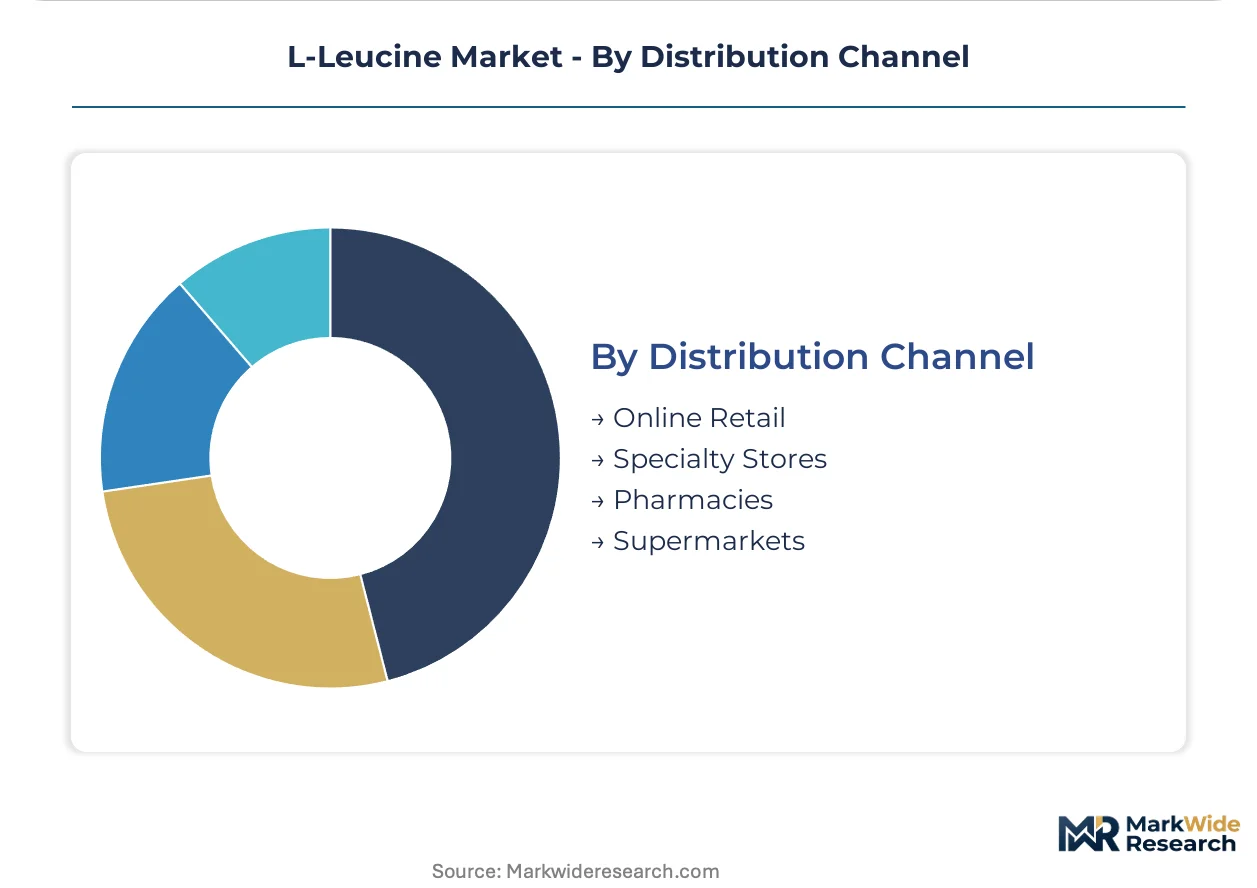
Margin capture and customer relationship control determine channel strategy, with direct-to-consumer platforms disrupting traditional pharmacy and specialty retail intermediaries.
- Online Retail:Brand-owned websites and marketplace platforms now capture the fastest-growing share, enabled by subscription models and influencer-affiliate marketing. California-based direct-to-consumer brands leverage fermentation provenance storytelling to justify 40-60% price premiums over commodity alternatives.
- Specialty Stores:Vitamin Shoppe, GNC, and independent supplement retailers in the United States provide physical sampling and staff consultation that converts first-time buyers. These channels face margin compression as brands shift inventory to higher-margin direct channels.
- Pharmacies:CVS, Walgreens, and Boots locations in the United States and United Kingdom stock L-leucine adjacent to protein powders and joint health products, with pharmacist recommendation driving trust among older consumers. Regulatory scrutiny of structure-function claims limits marketing flexibility compared to online channels.
- Supermarkets:Mass-market placement in Walmart, Tesco, and Carrefour exposes L-leucine to casual wellness shoppers, typically in smaller trial sizes with lower purity specifications. Private label expansion by retailers is squeezing branded supplier margins.
Online retail is climbing the fastest; specialty stores retain the highest customer lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fermentation infrastructure commands volume leadership while Germany's pharmaceutical-grade specialization captures margin premiums across European medical nutrition channels.
China
Shandong Province's integrated corn-processing clusters supply glucose substrates for bulk fermentation, with domestic supplement manufacturers consuming over half of national L-leucine output. NMPA purity thresholds for amino acid additives enforce quality documentation across nutritional product registrations. Qingdao and Weifang host concentrated amino acid production parks where three major processors coordinate substrate logistics and wastewater treatment.
United States
FDA 21 CFR 111 compliance mandates filter sub-scale hydrolysate operations, consolidating supply relationships among fermentation-capable manufacturers serving sports nutrition brands. Direct-to-consumer subscription platforms headquartered in California and Texas now capture the fastest-growing distribution share. Utah's supplement manufacturing corridor and New Jersey's pharmaceutical ingredient hubs anchor contrasting purity-grade supply chains.
Germany
EFSA novel food assessments under Regulation 2015/2283 shape market access for microbial-derived amino acids, with German buyers demanding non-animal origin certificates. Precision fermentation specialists near Frankfurt and Hamburg serve peptide API producers requiring isotopic labeling consistency. Bavaria's industrial biotechnology parks host continuous bioprocessing pilot facilities advancing perfusion fermentation economics.
Japan
Meticulous purity specifications from Olympic training centers and hospital discharge protocols drive pharmaceutical-grade demand, with METI industrial standards guiding amino acid additive classifications. Kyowa Hakko's legacy fermentation expertise in Tokyo and Yamaguchi prefectures anchors domestic supply. Aging demographics in Osaka and Nagoya metropolitan areas expand medical nutrition applications beyond traditional athletics.
Brazil
Bodybuilding culture in São Paulo and Rio de Janeiro drives powder formulation demand, with ANVISA supplement registration requirements creating compliance barriers for imported hydrolysate streams. Local distributors increasingly specify fermentation-derived certificates to satisfy gym-affiliated retail channels. The Southeast region's logistics infrastructure concentrates import flows through Santos port.
L-Leucine Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade fermentation output, while commodity-grade protein hydrolysate processors compete on price in feed-grade applications. The competitive landscape stratifies between integrated corn-processing conglomerates with captive substrate access and biotechnology specialists leveraging precision fermentation for premium segments. Three strategic archetypes dominate: volume-driven fermentation platforms, pharmaceutical-grade purity specialists, and diversified amino acid portfolios. Capacity expansion in Shandong Province and strategic partnerships for continuous bioprocessing technology represent the dominant competitive moves reshaping supply relationships.
Among Asia-Pacific fermentation leaders, Ajinomoto Co., Inc., Fufeng Group Company Limited, and Meihua Holdings Group Co., Ltd. occupy positions spanning the premium-to-volume spectrum. Ajinomoto exemplifies decades-long microbial fermentation expertise sustaining pharmaceutical-grade positioning. Fufeng Group represents integrated corn-processing scale with Shandong Province infrastructure advantages. Meihua Holdings anchors the volume-tier with amino acid diversification across feed and food applications. European biotechnology differentiation is represented by Evonik Industries AG, whose precision fermentation capabilities serve pharmaceutical API requirements. CJ CheilJedang Corporation and Daesang Corporation from South Korea, alongside Kyowa Hakko Bio Co., Ltd. from Japan, complete the Northeast Asian competitive cluster with heritage fermentation platforms.
| Leading Market Players |
|---|
| Meihua Holdings Group Co., Ltd. |
| Wuxi Jinghai Amino Acid Co., Ltd. |
| Ajinomoto Co., Inc. |
| Amino GmbH |
| Fufeng Group Company Limited |
| Evonik Industries AG |
| CJ CheilJedang Corporation |
| Daesang Corporation |
| Kyowa Hakko Bio Co., Ltd. |
| Others |
Supply & Pricing Matrix
Fermentation engineers with perfusion bioreactor expertise cluster in Bavaria's industrial biotechnology parks and Tokyo's Yamaguchi prefectures, commanding compensation premiums that widen spreads between pharmaceutical-grade and commodity-grade L-leucine pricing tiers.
Pricing Analysis
Bundle-unbundle splits separate fermentation-provenanced certificates from stripped commodity offerings. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels tracks purity thresholds and documentation depth. Cost compression in feed-grade tiers intensifies because protein hydrolysate residuals undercut fermentation output on price. Nutritional supplement consumers show highest price sensitivity, while peptide API producers demonstrate lowest.
Supply Chain Analysis
Glucose substrate supply rests on Shandong Province corn processors, German precision fermentation specialists, and Japanese heritage manufacturers. Corn grain markets, microbial strain banks, and pharmaceutical-grade filtration equipment constitute critical input dependencies. Single-geography concentration in Shandong creates disruption vulnerability for global amino acid flows. Distribution runs through direct-to-consumer platforms, specialty supplement retailers, and hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing adoption is compressing unit production costs while expanding pharmaceutical-grade margin capture, creating a margin-expansion story anchored in manufacturing technology shifts.
For Market Incumbents: Anticipate precision fermentation specialists encroaching on premium segments by accelerating USP certification timelines and locking multi-year substrate offtake agreements with Shandong glucose suppliers. Continuous bioprocessing talent scarcity demands retention premiums and university partnership pipelines. For New Entrants and Emerging Players: Aging populations seeking sarcopenia mitigation represent the most penetrable buyer archetype, with medical nutrition protocols in Japanese and Italian hospital discharge systems offering validated entry points. Direct-to-consumer subscription platforms bypass incumbent channel control. For Investors and Strategic Acquirers: Pharmaceutical CDMOs are the most active acquirer in this space, targeting fermentation assets with isotopic labeling capabilities and EU novel food dossiers. Five-to-ten year viability hinges on regulatory divergence between pharmaceutical and food-grade specifications. Watch EFSA novel food approval velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Perfusion Fermentation Scale-Up | Bavaria's pilot facilities demonstrate 40% yield improvement over batch methods. |
| USP Certification Investment | Eighteen-month stability studies unlock injectable-grade pricing premiums from peptide API producers. |
| Direct-to-Consumer Channel Buildout | California-based brands capture full margin stack via subscription platforms displacing GNC and Vitamin Shoppe. |
| Backward Integration into Corn Processing | Shandong's integrated clusters secure glucose substrate cost predictability against grain volatility. |
| EFSA Novel Food Dossier Filing | Streamlined Regulation 2015/2283 pathways accelerate European market access for microbial-derived variants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with fermentation plant managers, sports nutrition brand formulators, pharmaceutical procurement leads, and regulatory affairs specialists at NMPA and FDA complemented secondary validation through customs trade databases, SEC filings from listed amino acid producers, EFSA novel food registers, and ClinicalTrials.gov sarcopenia intervention records. Bottom-up capacity modeling and top-down demand estimation were triangulated.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions included product formulation type, end-user sophistication tier, application clinical validation level, and distribution channel control intensity. CAGRs derived from trend extrapolation moderated by capacity expansion announcements and substrate cost assumptions. Fermentation yield curves and regulatory approval timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade production volumes carry tighter precision than commodity-grade hydrolysate estimates. Forecasts reflect documented assumptions about continuous bioprocessing adoption rates and corn price trajectories. Supply concentration risk, regulatory divergence, and talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Global Soluble Dietary Fibers Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Diet Market