
 Rapid-Set Gelatin Market | 2026-2036
Rapid-Set Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid-Set Gelatin Market Analytics
Pharmaceutical capsule manufacturers are unwinding legacy reliance on standard-set gelatin as food manufacturers and home consumers gain share in rapid-set procurement. Gelita AG leverages backward integration into porcine and bovine raw material streams across European abattoir networks. Rousselot sustains R&D intensity in enzymatic hydrolysis patents that shorten bloom development cycles. Nitta Gelatin Inc. anchors geographic dominance in East Asian supply chains through dedicated facilities in Japan.
Rapid-set gelatin denotes a collagen-derived hydrocolloid engineered to achieve gelation within 5–15 minutes at ambient or chilled temperatures, typically exhibiting bloom strengths of 150–250 g and isoelectric points between pH 4.7 and 5.4 depending on extraction method. The substance serves primarily as a functional gelling agent in time-sensitive manufacturing environments where thermal exposure must be minimized. Powdered gelatin occupies the dominant volume position due to shelf stability and dosing precision in automated bakery lines, while pharmaceutical applications represent the fastest-expanding margin pool as capsule manufacturers prioritize cold-fill compatibility. Flavored gelatin competes mainly in home consumer channels where convenience positioning commands premium pricing over unflavored base grades.
FDA food additive regulations and EFSA purity standards govern residual heavy metal limits and BSE/TSE compliance documentation for collagen-derived ingredients entering pharmaceutical and food channels. The European Union's REACH framework and emerging CSRD disclosure requirements further compel gelatin processors to map supply chain environmental footprints across rendering operations. Stakeholders must monitor evolving pharmaceutical excipient monographs and sustainability disclosure mandates to secure formulation approvals and procurement contracts.
Market Dynamics
Clean-label ingredient mandates from EFSA and FDA are compressing formulation timelines for gelatin processors, forcing simultaneous compliance with pharmaceutical excipient monographs and food-grade purity thresholds.
Growth Catalysts
- Pharmaceutical capsule cold-fill compatibility:Manufacturers prioritize rapid-set grades that eliminate thermal exposure during encapsulation, reducing cycle times in high-volume production lines.
- REACH and CSRD disclosure mandates:European sustainability frameworks reward processors with mapped supply chain footprints, creating procurement advantages in regulated channels.
- East Asian bakery automation:Powdered rapid-set formats integrate into dosing systems across Japanese and South Korean industrial baking facilities.
Market Restraints
- Porcine and bovine raw material volatility:Rendering output fluctuations in European abattoir networks create input cost instability for bloom-grade production.
- BSE/TSE compliance documentation burden:FDA and EMA requirements for collagen-derived pharmaceutical ingredients extend qualification timelines for new suppliers.
- Pectin and modified starch substitution:Plant-based hydrocolloids capture share in food applications where religious dietary restrictions limit animal-derived options.
Strategic Opportunities
- Home consumer convenience channels:Flavored rapid-set formats command premium positioning in direct-to-retail and e-commerce distribution.
- Enzymatic hydrolysis patent portfolios:Processors with protected shortening technologies for bloom development cycles capture licensing revenue.
- Indian pharmaceutical manufacturing expansion:CDSCO-aligned capsule producers represent underpenetrated demand for high-bloom pharmaceutical grades.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in collagen biochemistry and regulatory dossier preparation command premium compensation.
- Legacy ERP integration with batch traceability systems:Processors face capex demands for real-time supply chain mapping required by CSRD and downstream pharmaceutical audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid-Set Gelatin Market |
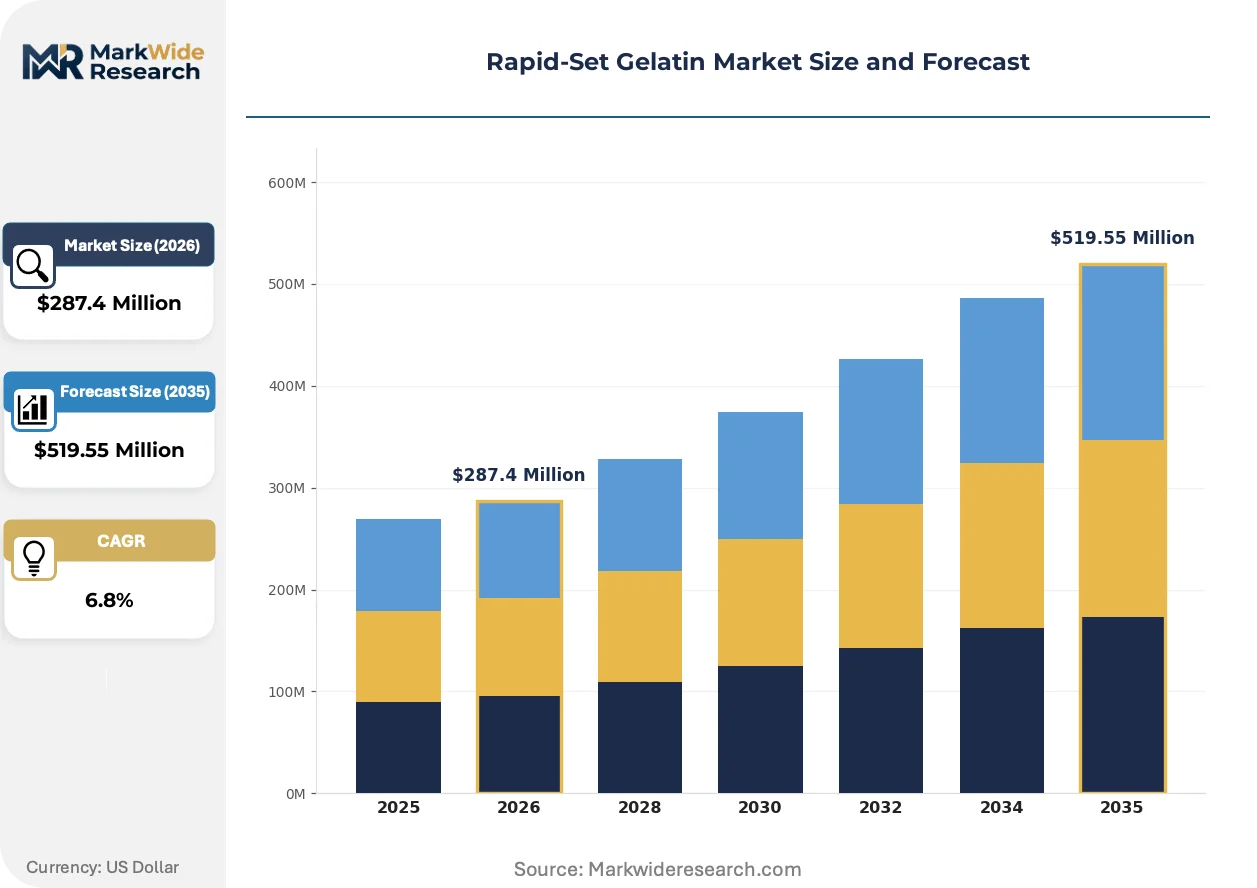
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $519.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Gelatin, Sheet Gelatin, Granulated Gelatin, Flavored Gelatin Application: Baking, Confectionery, Pharmaceuticals, Dairy End User: Food Manufacturers, Pharmaceutical Companies, Bakeries, Home Consumers Form: Semi-Solid, Liquid, Solid, Miscible |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin Inc., PB Gelatins, Weishardt Group, Junca Gelatines S.L., Sterling Gelatin, Trobas Gelatine B.V., Sanfame Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid-Set Gelatin Market Evolving Landscape
Enzymatic processing technologies and sustainability disclosure mandates are rewriting competitive requirements for gelatin processors, compressing the window between raw material sourcing and certified product release.
Enzymatic hydrolysis protocols for collagen extraction are fragmenting traditional acid-alkali processing dominance. Pharmaceutical capsule manufacturers adopt these methods to achieve sub-15-minute gelation without thermal degradation of active pharmaceutical ingredients. The technology is fragmenting equipment vendor hierarchies as specialized bioprocessing firms displace conventional rendering technology suppliers.
EFSA's evolving purity standards for residual heavy metals in collagen-derived ingredients are tightening batch-release protocols. Processors must now maintain dual documentation trails for food additive and pharmaceutical excipient channels simultaneously. German and French manufacturing clusters invest most heavily in in-house analytical capabilities to preempt regulatory rejection.
Buyers in pharmaceutical and food channels are consolidating supplier relationships around processors with pre-mapped environmental footprints. Long-term contracting with verified rendering sources is displacing spot-market raw material procurement. This pattern concentrates most visibly in German and Japanese supply chains where downstream customers face imminent CSRD and METI disclosure deadlines.
Rapid-Set Gelatin Market Segmentation
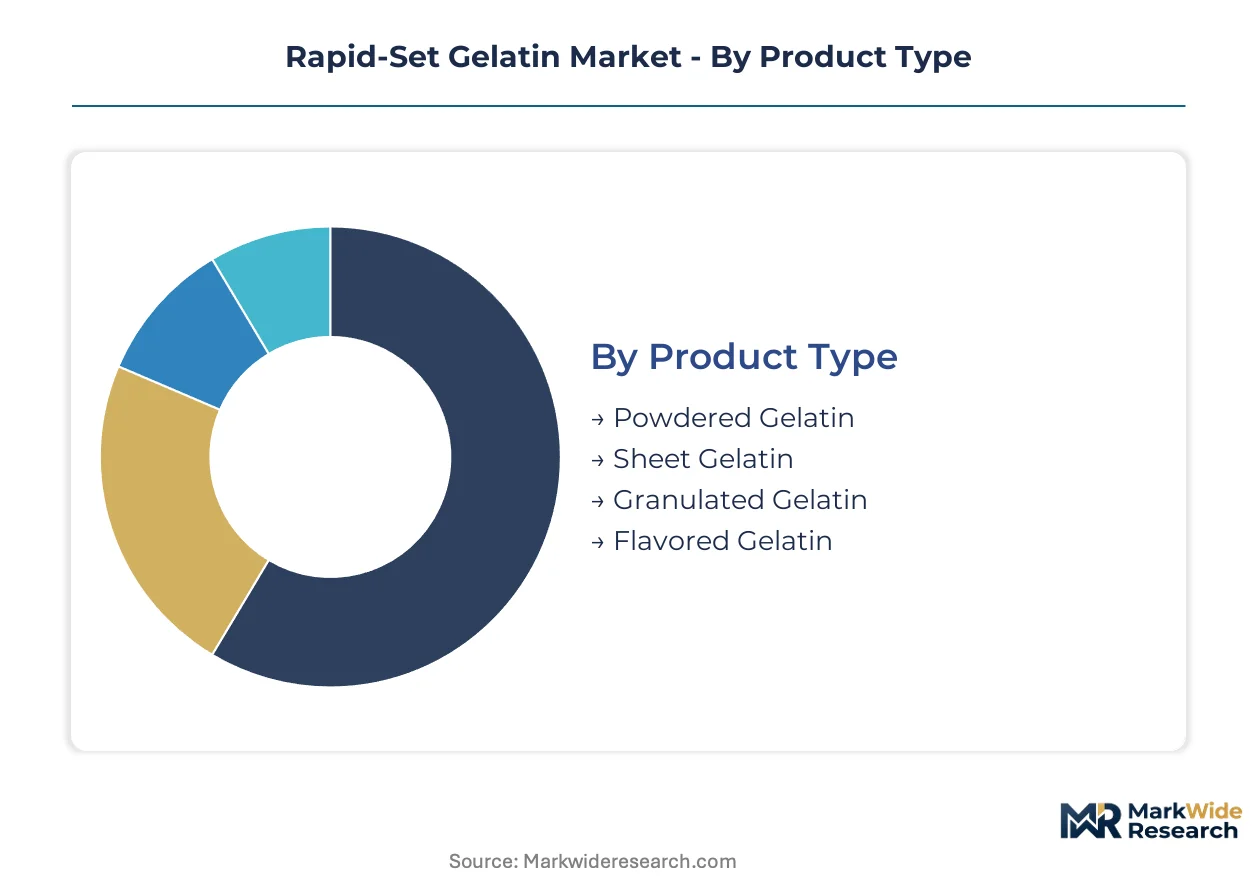
Segmentation in rapid-set gelatin reflects divergent regulatory pathways. Pharmaceutical excipient grades face EMA and FDA monograph compliance, while food-grade variants navigate EFSA additive thresholds and clean-label certification demands.
Product Type:
Regulatory differentiation separates pharmaceutical-grade bloom specifications from food additive purity tiers, with each product format carrying distinct documentation burdens for BSE/TSE traceability and heavy metal residuals.
- Powdered Gelatin:Dehydrated collagen hydrolysate with standardized particle size distribution enables precise automated dosing in high-throughput bakery and encapsulation lines. Demand concentrates in German pharmaceutical manufacturing clusters where cold-fill compatibility eliminates thermal degradation of active ingredients. Bloom strength standardization at 150–250 g aligns with USP-NF excipient monographs.
- Sheet Gelatin:Pre-portioned leaf format delivers consistent gel strength per unit without weighing equipment, prized in artisan confectionery and premium dessert applications. French and Italian patisserie channels sustain procurement despite higher unit costs, driven by formulation tradition and visual clarity requirements in molded preparations. EFSA food additive labeling distinguishes sheet grades from powdered alternatives in retail channels.
- Granulated Gelatin:Intermediate particle size offers faster hydration kinetics than sheets without the dust control requirements of fine powders. Industrial soup and sauce manufacturers in Japan favor this format for reconstitution efficiency.
- Flavored Gelatin:Pre-sweetened and acidified variants target home consumer convenience with reduced preparation steps. Direct-to-retail distribution in North American and European supermarkets commands premium positioning over unflavored base grades.
Powdered gelatin handles the majority of throughput; flavored gelatin is the fastest mover on share.
Application:
Cost tier differentiation separates commodity food applications from premium pharmaceutical excipient contracts, with documentation intensity and analytical testing burdens driving margin stratification.
- Pharmaceuticals:Hard and soft capsule manufacturing demands rapid-set grades achieving gelation below 20°C to protect thermolabile APIs. CDSCO-aligned producers in India represent expanding procurement volume as domestic pharmaceutical manufacturing scales. Dual compliance with USP-NF and Ph.Eur. monographs extends qualification timelines but locks in multi-year supply agreements.
- Baking:Industrial bread and pastry operations prioritize powdered formats with consistent hydration rates for automated sponge and mousse production. South Korean and Japanese bakery automation lines integrate rapid-set dosing for chiffon and entremet applications where thermal setting would collapse delicate structures.
- Confectionery:Gummy and marshmallow applications balance bloom strength against elasticity requirements, with EFSA additive thresholds governing residual sulfur dioxide from processing.
- Dairy:Yogurt stabilizers and dessert bases utilize low-bloom variants for texture modification without gel formation, competing with pectin and modified starch in clean-label formulations.
Baking handles the majority of throughput; pharmaceuticals is expanding most quickly.
End User:
Customer type determines procurement scale and specification intensity, from pharmaceutical quality agreements with batch traceability to spot-market food ingredient purchasing.
- Food Manufacturers:Industrial scale buyers negotiate annual contracts with specified bloom ranges and microbial limits, leveraging volume for price stability. German and French processing clusters concentrate demand for high-bloom variants in premium dessert applications.
- Pharmaceutical Companies:Capsule and tablet manufacturers impose excipient qualification protocols requiring supplier audits, stability data, and regulatory dossier support. Long-term contracting with pre-mapped supply chain footprints is displacing spot procurement under CSRD disclosure mandates.
- Bakeries:Artisan and industrial operators prioritize format convenience over bloom precision, with sheet gelatin sustaining share in European craft channels despite cost premiums.
- Home Consumers:Convenience positioning drives flavored and instant-format procurement through retail and e-commerce channels, with premium pricing over industrial grades reflecting packaging and marketing investments.
Food manufacturers handle the majority of throughput; pharmaceutical companies are gaining share fastest.
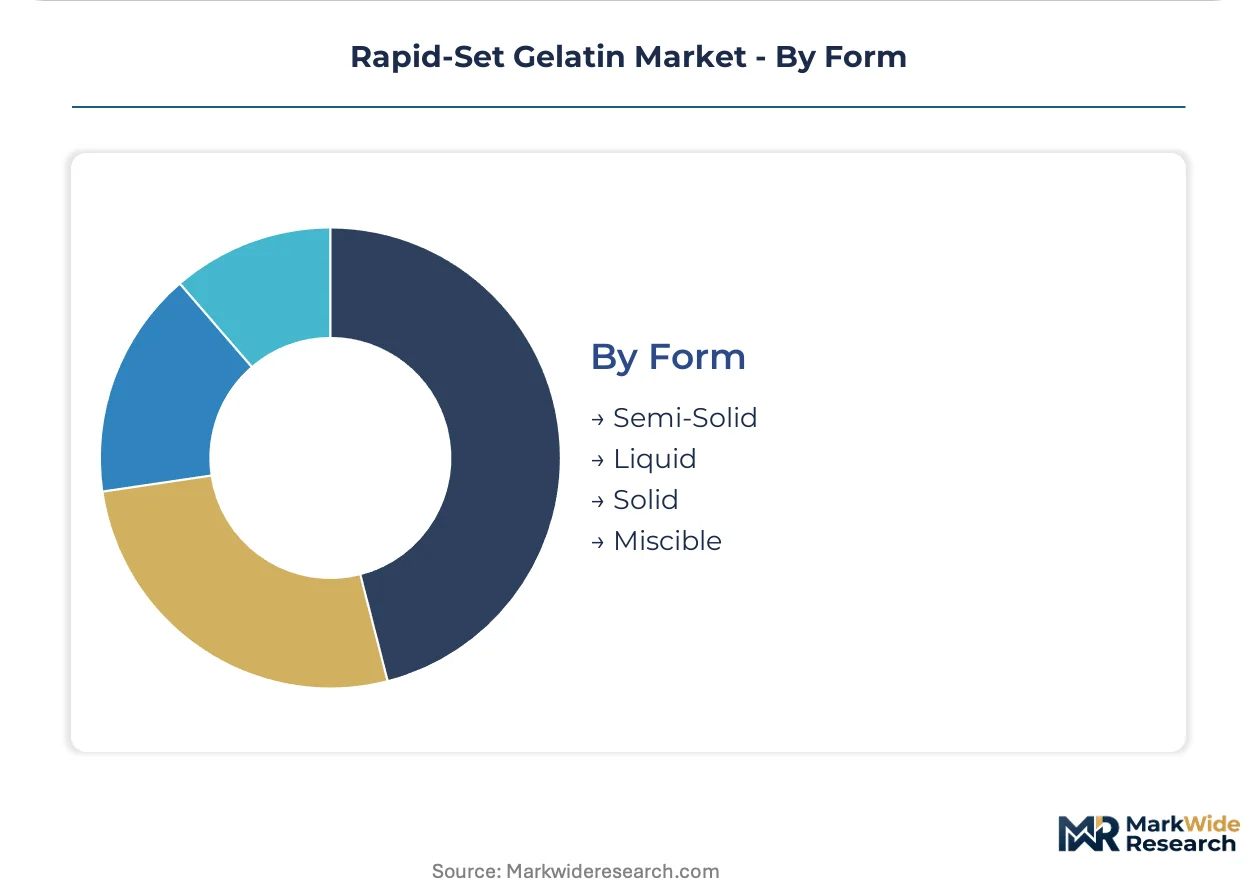
Form:
Supply concentration in solid and semi-solid formats reflects shelf stability advantages, while liquid and miscible variants serve niche process integration requirements.
- Solid:Powdered and granulated variants dominate inventory positions due to extended shelf life and reduced cold chain dependency. Japanese and German distribution networks prioritize solid formats for just-in-time pharmaceutical manufacturing.
- Semi-Solid:Hydrated gel bases and concentrated solutions eliminate dissolution steps in high-speed production lines, carrying higher logistics costs and shorter use windows.
- Liquid:Pre-hydrolyzed collagen solutions enable direct incorporation into temperature-sensitive formulations without heating, limited by microbial stability constraints.
- Miscible:Alcohol-compatible and oil-dispersible variants serve specialized confectionery and nutraceutical applications where standard aqueous gelation fails.
Solid handles the majority of throughput; semi-solid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German gelatin processors command export corridors into pharmaceutical manufacturing clusters across Switzerland and the Netherlands, while Japanese suppliers anchor East Asian trade flows into South Korean bakery automation lines.
Germany
Pharmaceutical capsule manufacturers in Baden-Württemberg and North Rhine-Westphalia drive procurement of high-bloom grades for cold-fill compatibility. ECHA REACH documentation requirements and emerging CSRD disclosure mandates compel processors to map rendering supply chains across European abattoir networks. Gelita AG maintains specialized production capacity in Eberbach for pharmaceutical-grade rapid-set formulations.
United States
FDA-regulated nutraceutical and softgel manufacturers in New Jersey and California represent expanding demand for rapid-set excipient grades. The agency's food additive regulations and BSE/TSE compliance documentation requirements extend supplier qualification timelines. Chicago-area distribution hubs consolidate inbound shipments from European rendering sources for just-in-time pharmaceutical manufacturing.
Japan
Industrial bakery automation in Osaka and Nagoya integrates powdered rapid-set formats into high-throughput sponge and mousse production lines. METI disclosure deadlines for supply chain environmental footprints drive long-term contracting with verified rendering sources. Nitta Gelatin Inc. operates dedicated facilities in Shimonoseki serving East Asian pharmaceutical and food channels.
India
CDSCO-aligned capsule producers in Maharashtra and Gujarat scale domestic pharmaceutical manufacturing, generating underpenetrated demand for high-bloom pharmaceutical grades. FSSAI clean-label mandates and dual compliance with USP-NF and Ph.Eur. monographs shape procurement specifications. Hyderabad and Mumbai clusters attract multinational excipient suppliers establishing local technical service capabilities.
South Korea
Automated chiffon and entremet production lines in Seoul and Busan prioritize rapid-set gelatin dosing where thermal setting would collapse delicate structures. MFDS pharmaceutical excipient regulations and bakery industry automation investments concentrate demand in the Seoul Capital Area. Local distributors maintain inventory positions for just-in-time supply to industrial baking facilities.
Rapid-Set Gelatin Market Competitive Landscape
Player mix skews toward integrated collagen processors with captive rendering operations and specialized pharmaceutical excipient suppliers with deep regulatory dossier capabilities. Market structure concentrates around three strategic archetypes: backward-integrated European majors controlling porcine and bovine raw material streams, East Asian specialists leveraging geographic proximity to bakery automation demand, and regional processors serving food-grade applications with lower documentation burdens. Dominant competitive moves include enzymatic hydrolysis technology licensing and long-term supply agreements with pre-mapped environmental footprints under CSRD and METI disclosure mandates.
Among European integrated processors, Gelita AG and Rousselot exemplify archetypes combining rendering network control with pharmaceutical-grade certification depth. Nitta Gelatin Inc. occupies a position representing East Asian supply chain dominance through dedicated production facilities and proximity to Japanese and South Korean industrial bakery automation. These three entities anchor competitive positioning across the premium pharmaceutical excipient tier where dual USP-NF and Ph.Eur. compliance creates qualification barriers for aspirant entrants.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin Inc. |
| PB Gelatins |
| Weishardt Group |
| Junca Gelatines S.L. |
| Sterling Gelatin |
| Trobas Gelatine B.V. |
| Sanfame Group |
| Others |
Value Network & Pricing Analysis
EMA and FDA dual-compliance documentation gates supply qualification and price differentiation simultaneously, forcing processors to carry certification costs that stratify tier positioning. Buyers in pharmaceutical channels absorb premium pricing for pre-mapped supply chain footprints under CSRD disclosure mandates, while food-grade procurement negotiates on spot-market volatility in rendering inputs.
Pricing Analysis
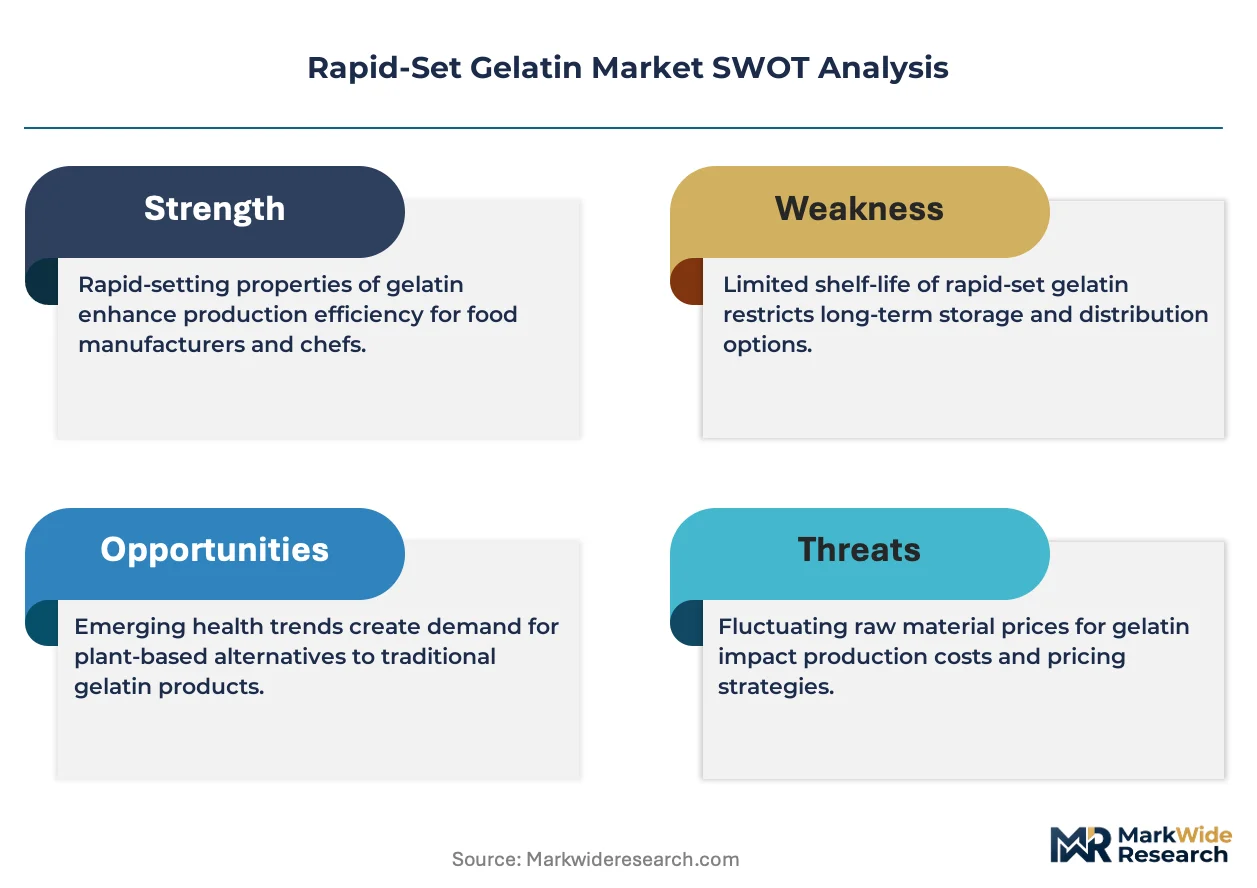
Enzymatic hydrolysis protocols command premium positioning against legacy acid-alkali processing, with next-generation cold-fill grades extracting 15-25% uplifts over standard pharmaceutical tiers. Three-tier pricing structure across premium enzymatic, standard acid-processed, and economy food-grade levels reflects certification depth and bloom precision. Cost compression in standard acid-processed tiers is intensifying because pectin and modified starch substitution erodes volume leverage. Pharmaceutical capsule manufacturers show lowest price sensitivity due to API protection requirements, while industrial bakeries negotiate aggressively on volume contracts.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical manufacturing clusters in Germany and the United States, while strategic stockpiling persists in Japanese bakery automation channels facing raw material volatility. Supply concentrates in Germany, Japan, and the United States for high-bloom pharmaceutical grades, with India emerging for CDSCO-aligned capsule production. Raw material streams draw from European porcine rendering networks, South American bovine collagen sources, and East Asian abattoir partnerships. Single-source vulnerability in German pharmaceutical-grade processing creates concentration risk for cold-fill compatible supply. Distribution runs through regional excipient distributors with regulatory dossier capabilities and direct processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid-set gelatin sits in early-cycle expansion as pharmaceutical cold-fill adoption accelerates capsule manufacturer procurement of enzymatic hydrolysis grades. Penetration remains shallow in Indian CDSCO-aligned production and South Korean automated bakery lines.
For Market Incumbents: Fortify backward integration into verified European rendering networks to preempt CSRD disclosure penalties and secure multi-year pharmaceutical contracts. Invest in in-house analytical capabilities at German and French manufacturing clusters to preempt EFSA heavy metal rejection. Capacity expansion in Eberbach and Shimonoseki anchors supply security against emerging Indian demand. For New Entrants and Emerging Players: Lead with enzymatic hydrolysis licensing to pharmaceutical capsule manufacturers seeking sub-15-minute gelation without thermal degradation. Target Indian CDSCO-aligned capsule producers in Maharashtra and Gujarat as the most penetrable geography. Pursue technical service partnerships with Hyderabad and Mumbai clusters to overcome dual USP-NF and Ph.Eur. qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic processing equipment and real-time batch traceability systems. Long-term viability favors processors with pre-mapped environmental footprints and captive rendering supply. Acquire mid-cap specialists with CDSCO technical service capabilities and existing pharmaceutical dossier libraries. Watch for enzymatic hydrolysis patent portfolio licensing revenue inflection as a signal of sustainable margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Patent Licensing | Rousselot and specialized bioprocessing firms capture recurring revenue from capsule manufacturers. |
| Backward Integration into Rendering Networks | Gelita AG secures supply chain footprint mapping required by ECHA REACH and emerging CSRD mandates. |
| CDSCO Technical Service Expansion | Multinational excipient suppliers establish Hyderabad capabilities to qualify Indian capsule producers. |
| Real-Time Batch Traceability System Deployment | Processors face capex demands for ERP integration supporting pharmaceutical audit requirements. |
| Long-Term Supply Agreement Structuring | Pre-mapped environmental footprints displace spot procurement under METI and CSRD disclosure deadlines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA submission databases, FDA food additive filings, and customs trade records for collagen-derived ingredients. Interviews with pharmaceutical excipient procurement managers, gelatin plant operations directors, and CDSCO regulatory consultants informed supply chain and qualification dynamics. Secondary validation drew from USP-NF monograph updates, EFSA additive threshold revisions, and SEC 10-K disclosures from publicly traded processors. Bottom-up volume modeling triangulated against top-down pharmaceutical capsule production estimates.
Segmentation dimensions modeled include product format, application channel, end-user archetype, and physical form state across the projection horizon. CAGRs were derived from growth driver elasticity analysis against pharmaceutical manufacturing expansion and bakery automation penetration. Industry-specific forecast inputs incorporated enzymatic hydrolysis adoption curves and EFSA heavy metal standard revision timelines.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical cold-fill adoption or EFSA purity standard stability would require recalibration. Forecasts reflect documented assumptions regarding rendering output availability and regulatory dossier preparation timelines. Revision becomes warranted when pectin substitution rates in food applications or BSE/TSE documentation burdens cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Tomato Powder Market
Ingredients
United States Gelatin Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Global Egg White Peptide Market
Ingredients
Textured Soy Flour Market
Ingredients
Specialty Starch Market
Ingredients
Banana Flour Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
High Oleic Oil Market
Ingredients
Fruit Concentrate Market
Ingredients
Pea Fiber Market