
 Drum to Hopper Blends Market | 2026-2036
Drum to Hopper Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Drum to Hopper Blends Market Foresight
Pharmaceutical-grade blend specifications are redrawing competitive boundaries in drum-to-hopper processing. BASF SE leverages its integrated chemical manufacturing base to supply high-purity excipient blends directly to pharmaceutical formulators. Koninklijke DSM N.V. anchors its position through intensive R&D in nutrient premix stability during pneumatic transfer. Cargill competes by controlling agricultural raw material sourcing for food-grade powder blends destined for industrial bakeries.
Drum to hopper blends are homogeneous mixtures engineered for direct pneumatic or mechanical transfer from bulk shipping containers into processing equipment, typically requiring particle size distributions below 500 microns and moisture content specifications under 5% to prevent bridging or segregation during conveyance. Powder blends dominate pharmaceutical manufacturing applications where batch consistency determines tablet weight uniformity, while liquid blends serve coatings operations requiring precise viscosity control during automated dispensing. Granular blends occupy a mature niche in chemical processing where free-flowing properties reduce feeder calibration frequency.
FDA Current Good Manufacturing Practice regulations and EMA quality guidelines govern excipient traceability and contamination limits, compelling blend suppliers to validate cleaning protocols between product changeovers. OSHA combustible dust standards and ATEX directives in Europe mandate explosion protection systems in drum-to-hopper transfer equipment, elevating capital requirements for processing line installations. Stakeholders must monitor evolving pharmacopeial standards for blend uniformity testing as regulatory agencies tighten acceptance criteria for transferred materials.
Market Dynamics
Pharmaceutical manufacturers are consolidating powder blend procurement around suppliers capable of integrated drum-to-hopper validation documentation, compressing vendor lists and elevating technical service requirements above commodity pricing.
Growth Catalysts
- EMA Quality Guidelines:Tightened excipient traceability mandates in Europe are compelling pharmaceutical formulators to source pre-validated blend packages with complete batch documentation.
- Continuous Manufacturing:Adoption of continuous direct compression tablet lines by generic drug producers is accelerating demand for drum-to-hopper feed systems with real-time uniformity monitoring.
- German CMO Expansion:Contract manufacturing organizations in Germany are adding dedicated drum-to-hopper processing suites for high-potency API handling, creating concentrated demand pull.
Market Restraints
- Specialty Excipient Concentration:Supply of pharmaceutical-grade microcrystalline cellulose and croscarmellose sodium concentrates among three chemical manufacturers, creating single-source vulnerability.
- ATEX Compliance Burden:Explosion protection system requirements for pneumatic transfer equipment add 15-25% capital cost premiums to processing line installations in Europe.
- Moisture Sensitivity Thresholds:Hygroscopic API blends below 3% moisture specification require climate-controlled drum storage, limiting distribution radius and inventory flexibility.
Strategic Opportunities
- Indian Generic API Sector:Formulators in India lack validated drum-to-hopper infrastructure for high-shear blends, creating white space for technical service partnerships.
- Biologics Lyophilization:Excipient blends for freeze-dried biologic formulations represent an emerging application with purity requirements exceeding standard pharmaceutical grades.
- US IRA Manufacturing Credits:Domestic production incentives under the Inflation Reduction Act are reshoring blend manufacturing capacity for Medicare-covered drug categories.
Industry Challenges
- Pneumatic Conveying Expertise:Shortage of process engineers capable of modeling dense-phase transfer for cohesive powder blends is extending commissioning timelines.
- Cleaning Validation Documentation:FDA expectations for residue detection below 10 ppm between product changeovers demand specialized analytical chemistry capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum to Hopper Blends Market |
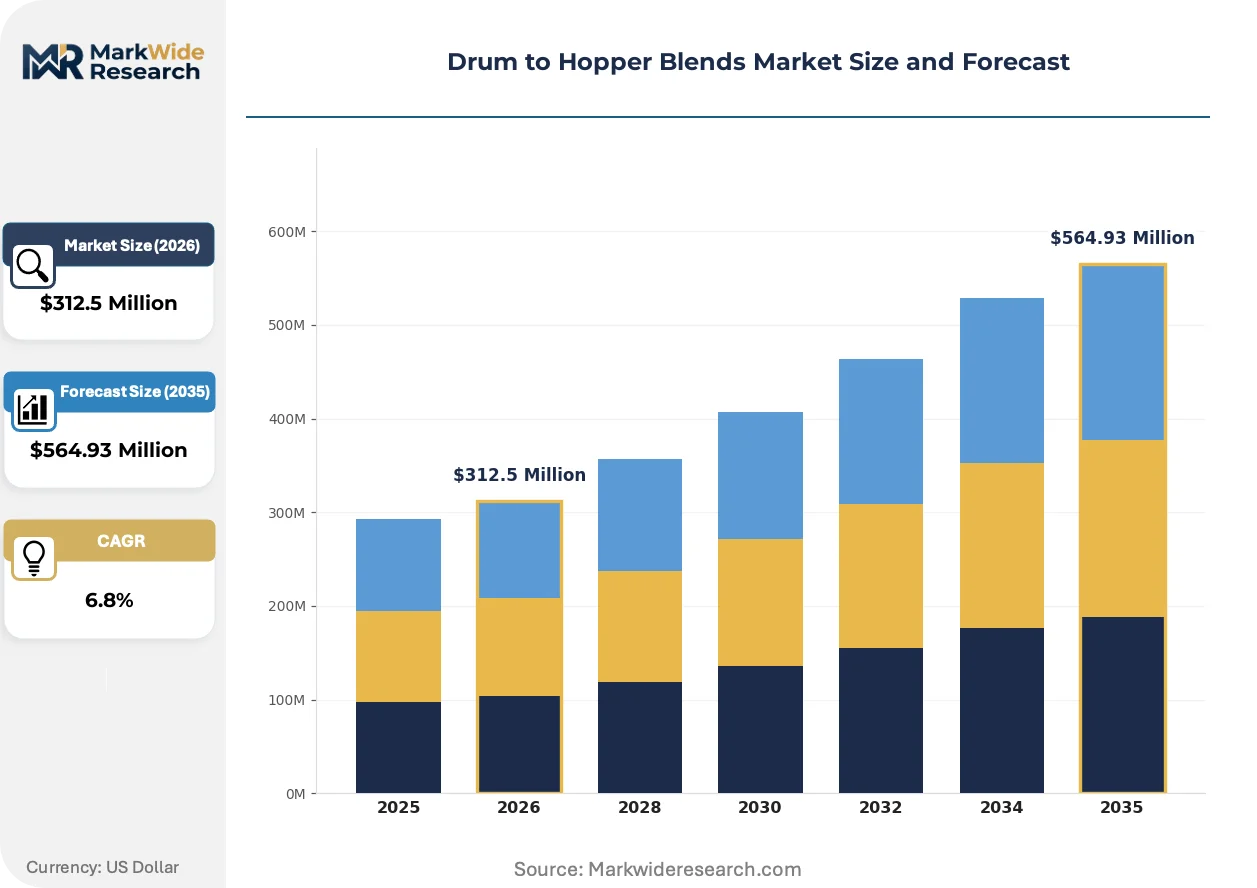
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Blends, Liquid Blends, Granular Blends, Paste Blends End User: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Application: Baking, Coatings, Pharmaceuticals Manufacturing, Personal Care Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Glanbia Plc, Archer Daniels Midland Company, Koninklijke DSM N.V., BASF SE, Jubilant Life Sciences, Farbest Brands, Fenchem Biotek Ltd, Cargill, Prinova Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum to Hopper Blends Market Shifts & Advancements
Near-infrared spectroscopy integration and closed-loop process control are converging to transform drum-to-hopper transfers from mechanical handling into quality-assured manufacturing steps with full parametric release capability.
Continuous blending systems with inline NIR sensors are supplanting traditional batch tumbling operations in solid-dose manufacturing. Large pharmaceutical formulators in North America are retrofitting existing suites at a measured pace. This technology is compressing blend uniformity testing from offline laboratory analysis to real-time release decisions.
REACH authorization requirements for titanium dioxide in pharmaceutical applications are forcing reformulation of white pigment-containing excipient blends. The industrial consequence is accelerated qualification of alternative opacifiers including calcium carbonate and starch-based systems. Tablet coating operations in Europe are most affected, with manufacturers stockpiling grandfathered TiO2-containing materials while validating replacements.
Consolidated supplier agreements are displacing spot purchasing for critical excipient blends among mid-sized generic manufacturers. Direct commercial relationships with blend houses are replacing distributor intermediaries in procurement channels. This pattern is most visible in Germany and Switzerland, where formulators seek single-source accountability for blend uniformity failures.
Drum to Hopper Blends Market Segmentation
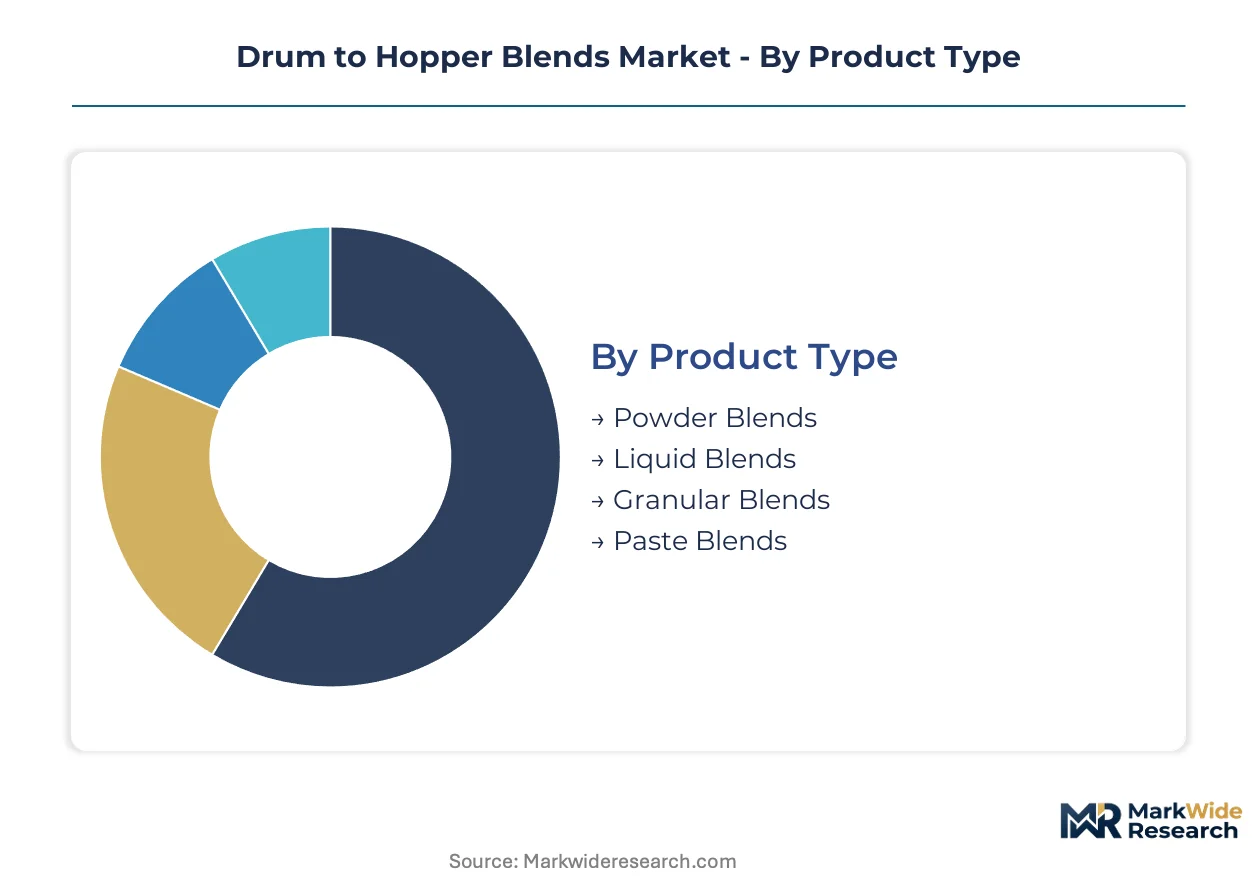
Segmentation in drum-to-hopper blends reveals distinct technical requirements across physical states and end-use applications. Each category carries unique regulatory burdens and substitution pressures that reshape supplier positioning.
Product Type:
Substitution pressure intensifies where pneumatic conveying technology advances, threatening traditional blend formats with process redesign.
- Powder Blends:Homogeneous dry mixtures with particle size distributions below 500 microns and moisture specifications under 5% prevent bridging during pneumatic transfer. Pharmaceutical manufacturers in Germany concentrate procurement around suppliers offering integrated drum-to-hopper validation documentation for tablet weight uniformity compliance.
- Liquid Blends:Viscosity-controlled formulations engineered for automated dispensing systems in coatings operations. Demand concentrates among industrial bakeries seeking precise viscosity control for spray applications, though shelf stability constraints limit distribution radius compared to dry formats.
- Granular Blends:Free-flowing particulate systems reducing feeder calibration frequency in chemical processing applications.
- Paste Blends:Semi-solid formulations requiring heated drum discharge systems for transfer integrity.
Powder blends anchor the volume base while liquid blends gain share at the steepest rate.
End User:
Cost tier stratification separates premium-validated supply from commodity-grade procurement channels.
- Pharmaceuticals:Excipient blends governed by FDA Current Good Manufacturing Practice and EMA quality guidelines with residue detection thresholds below 10 ppm between product changeovers. Contract manufacturing organizations in Germany are expanding dedicated drum-to-hopper processing suites for high-potency API handling.
- Food & Beverage:Industrial bakery applications requiring agricultural raw material traceability and FSSAI or FDA food-grade certification.
- Chemicals:Process intermediates where OSHA combustible dust standards and ATEX directives mandate explosion protection systems.
- Cosmetics:Personal care formulations with REACH compliance requirements tightening purity benchmarks for titanium dioxide and alternative opacifiers.
Pharmaceuticals anchors the volume base while cosmetics gains share at the steepest expansion trajectory.
Application:
Application maturity varies sharply between established industrial processes and emerging biologics requirements.
- Pharmaceuticals Manufacturing:Solid-dose production where continuous direct compression tablet lines demand real-time uniformity monitoring through inline NIR sensors. Generic drug producers in North America are retrofitting existing suites at a measured pace.
- Coatings:Tablet coating operations in Europe most affected by REACH authorization requirements for titanium dioxide, forcing accelerated qualification of calcium carbonate and starch-based opacifier alternatives.
- Baking:Industrial bakery lines requiring consistent dosing accuracy for premix stability during pneumatic transfer.
- Personal Care:Freeze-dried biologic formulations representing an emerging application with purity requirements exceeding standard pharmaceutical grades.
Pharmaceuticals manufacturing anchors the volume base while personal care gains share most quickly.
Distribution Channel:
Customer type fragmentation separates integrated formulators seeking single-source accountability from spot purchasers.
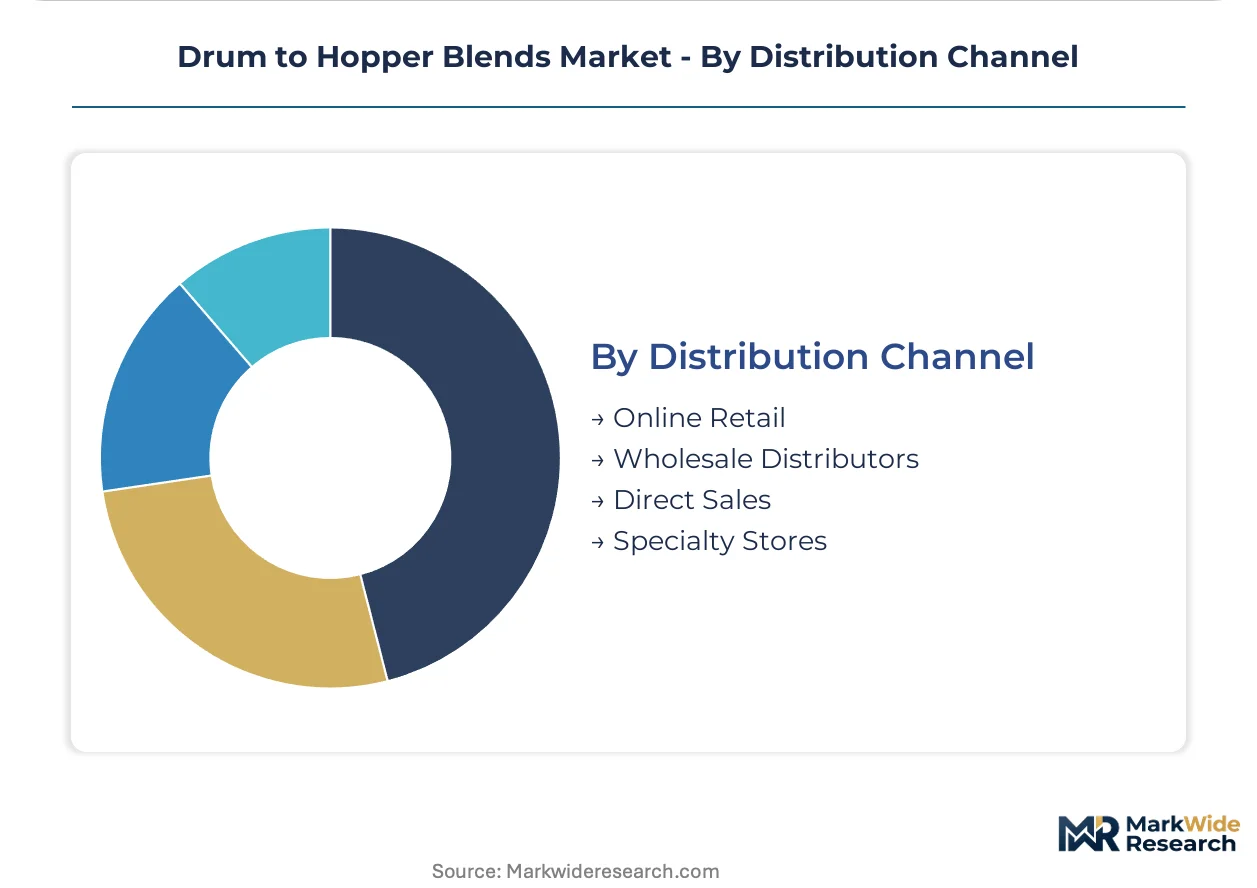
- Direct Sales:Consolidated supplier agreements displacing distributor intermediaries among mid-sized generic manufacturers in Germany and Switzerland. Direct commercial relationships provide single-source accountability for blend uniformity failures.
- Wholesale Distributors:Traditional procurement channels losing share as formulators seek technical service partnerships for validated drum-to-hopper infrastructure.
- Online Retail:Digital procurement platforms serving smaller volume accounts with standardized product specifications.
- Specialty Stores:Niche channels for customized small-batch formulations with extended lead times.
Wholesale distributors anchors the volume base while direct sales gains share climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in drum-to-hopper blends tilt toward import dependency in high-regulation markets while export-oriented manufacturing clusters concentrate in supply chain hubs with validated infrastructure. Germany runs a structural surplus in pharmaceutical-grade blends, whereas India and Brazil rely on imported excipient formulations for domestic formulation.
Germany
Contract manufacturing organizations in Baden-Württemberg and North Rhine-Westphalia are commissioning dedicated drum-to-hopper suites for high-potency API handling. REACH authorization timelines for titanium dioxide compel formulators to pre-validate alternative opacifiers through ECHA consultation channels. The Rhine-Main cluster around Frankfurt anchors continental Europe's largest concentration of pre-validated blend storage and pneumatic transfer infrastructure.
United States
Generic drug producers in North Carolina and New Jersey are retrofitting continuous direct compression lines with inline NIR monitoring for real-time blend uniformity verification. IRA manufacturing credits are reshoring excipient blending capacity for Medicare-covered therapeutic categories under FDA Current Good Manufacturing Practice. The Philadelphia-Camden corridor maintains the densest agglomeration of drum-to-hopper validation specialists serving branded and generic formulators.
India
Formulators in Maharashtra and Gujarat lack validated drum-to-hopper infrastructure for high-shear cohesive powder blends, creating technical service partnership opportunities with European equipment vendors. CDSCO import licensing requirements for pharmaceutical excipients extend lead times for critical raw materials. The Hyderabad-Visakhapatnam corridor is emerging as a domestic hub for contract blend manufacturing serving Southeast Asian export markets.
Switzerland
Swissmedic's tightened excipient traceability mandates are compressing approved supplier lists around integrated documentation providers. Basel's pharmaceutical cluster demands drum-to-hopper systems with parametric release capability for continuous manufacturing lines. The country's contract manufacturing sector is consolidating procurement through direct commercial relationships that displace distributor intermediaries.
China
NMPA alignment with ICH Q3D elemental impurity guidelines is forcing domestic blend manufacturers to upgrade purification and detection capabilities for export-grade pharmaceutical excipients. The Yangtze River Delta pharmaceutical corridor is absorbing capacity expansion for freeze-dried biologic excipient formulations. Shanghai's free-trade zone infrastructure supports bonded storage of climate-sensitive hygroscopic blends requiring sub-3% moisture specifications.
Drum to Hopper Blends Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized nutrition ingredient houses that control backward integration into raw material sourcing. Three strategic archetypes define competitive positioning: integrated chemical manufacturers with captive excipient supply, nutrient premix specialists with pneumatic transfer expertise, and agricultural processors with food-grade powder capabilities. Dominant competitive moves include capacity expansion in high-regulation jurisdictions and strategic partnerships for continuous manufacturing validation documentation.
Among European chemical conglomerates, BASF SE and Koninklijke DSM N.V. exemplify the integrated manufacturer archetype with in-house production of high-purity excipient systems. Cargill occupies a position within the agricultural-processor tier, leveraging upstream control over commodity raw materials for industrial food-grade applications. These three entities represent distinct competitive vectors: chemical synthesis depth, nutrient stability science, and supply chain scale respectively.
| Leading Market Players |
|---|
| Glanbia Plc |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| BASF SE |
| Jubilant Life Sciences |
| Farbest Brands |
| Fenchem Biotek Ltd |
| Cargill |
| Prinova Group LLC |
| Others |
Supply & Pricing Matrix
Calcium carbonate and starch-based opacifier alternatives replacing REACH-restricted titanium dioxide simultaneously shift raw material sourcing toward agricultural processors and compress pricing premiums for white pigment-containing excipient blends in European tablet coating operations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in drum-to-hopper blends. Price differentiation rests on FDA certification grade and volume scale, with pharmaceutical-grade validated blends commanding substantial premiums over food-grade commodity formulations. Cost compression in standard-tier powder blends is intensifying because German contract manufacturing organizations are consolidating procurement around integrated documentation providers. Generic drug manufacturers in India exhibit the highest price sensitivity due to thin formulation margins, while branded pharmaceutical formulators in Switzerland demonstrate the least.
Supply Chain Analysis
Germany and India anchor pharmaceutical-grade excipient blend production, with China expanding capacity for freeze-dried biologic formulations. Raw material supply draws from agricultural processors for starch-based systems, chemical manufacturers for microcrystalline cellulose, and mining operations for calcium carbonate. Single-source vulnerability concentrates in pharmaceutical-grade croscarmellose sodium supply among three chemical manufacturers. Distribution runs through direct commercial relationships displacing wholesale distributor intermediaries among mid-sized generic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as continuous manufacturing adoption splits demand between validated real-time release systems and legacy batch processing infrastructure, creating distinct service tiers for equipment vendors and blend suppliers.
For Market Incumbents: Consolidate procurement relationships through captive supply of high-purity excipient systems and backward integration into climate-controlled drum storage infrastructure. BASF SE and Koninklijke DSM N.V. face substitution pressure from agricultural processors qualifying starch-based opacifiers. Capacity addition in the Rhine-Main cluster around Frankfurt secures geographic proximity to German contract manufacturing organization expansion. For New Entrants and Emerging Players: Anchor in technical service partnerships for pneumatic conveying system validation serving Indian generic API formulators in Maharashtra and Gujarat. The most penetrable segment comprises high-shear cohesive powder blends lacking validated drum-to-hopper infrastructure. A go-to-market angle pairing European equipment vendor alliances with localized blend uniformity testing capabilities addresses CDSCO import licensing bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations in Baden-Württemberg and North Rhine-Westphalia expanding drum-to-hopper processing suites. Long-term viability over a five-to-ten year window hinges on continuous manufacturing validation documentation capabilities rather than commodity excipient production. The signal to watch is NIR sensor integration adoption rates among generic drug producers retrofitting direct compression lines.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Validation Partnership | Inline NIR sensor integration with drum-to-hopper systems enables real-time blend uniformity release for FDA-regulated tablet lines. |
| Backward Integration into Agricultural Raw Materials | Cargill's upstream control over commodity starch secures supply chain resilience for titanium dioxide replacement formulations. |
| Climate-Controlled Drum Storage Infrastructure | Sub-3% moisture specification compliance expands distribution radius for hygroscopic API blends in Shanghai's free-trade zone. |
| Technical Service Alliance with Equipment Vendors | European pneumatic conveying expertise addresses process engineer shortages extending commissioning timelines in Indian formulator facilities. |
| Alternative Opacifier Qualification Program | Calcium carbonate and starch-based system validation through ECHA consultation channels mitigates REACH authorization risk for titanium dioxide. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Current Good Manufacturing Practice guidance documents, EMA quality guideline publications, and REACH authorization timelines for titanium dioxide. Interviews with pharmaceutical plant managers, procurement leads at contract manufacturing organizations, distribution channel partners, and technical R&D directors in excipient formulation were cross-checked against customs and trade data, SEC 10-K filings, and ECHA consultation records. Bottom-up demand modeling from end-use application volumes was triangulated against top-down supply capacity assessments.
Segmentation dimensions modeled span physical state, end-use industry, application maturity, and distribution channel structure across the projection horizon. CAGRs were derived through growth driver elasticity analysis applied to base-year market sizing. Forecast inputs incorporated continuous manufacturing adoption curves, REACH regulatory phase-out schedules, and IRA manufacturing credit allocation patterns for domestic pharmaceutical production.
Underlying assumptions cover EMA guideline enforcement consistency, ATEX directive implementation timelines, and pneumatic conveying technology diffusion rates, with deviation risk concentrated in regulatory acceleration or delay for titanium dioxide alternatives. Recalibration cycles align with material shifts in pharmacopeial blend uniformity testing standards and continuous manufacturing validation guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bean Flour Market
Ingredients
South America Phytosterols Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Hen Egg White Protein Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Plant-Based API Market
Ingredients
Mirepoix Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Vegetable Powder Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Kairomones Market
Ingredients
Fonio Flour Market
Ingredients
United Kingdom Protein Market