
 Brewing Enzymes Market | 2026-2036
Brewing Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Enzymes Market Analysis
Food-grade enzyme certification at the pharmaceutical purity tier is reorganizing competitive dynamics in brewing inputs. Novozymes A/S leverages its microbial platform leadership to dominate high-performance amylase supply for large-scale lager operations. DSM-Firmenich anchors its position through integrated biotechnology pipelines that sustain consistent glucoamylase output across European malt houses. Kerry Group plc differentiates via application-specific technical service teams that navigate formulation complexity for craft brewery clients.
Brewing enzymes are biocatalysts—typically proteins derived from microbial fermentation or plant extraction—that accelerate specific biochemical reactions during malting, mashing, and fermentation, operating optimally at defined temperature and pH ranges such as alpha-amylase activity near 70°C at pH 5.7. Their primary commercial purpose is to improve extract yield, accelerate wort filtration, ensure attenuation control, and stabilize finished beer clarity. Amylase and glucoamylase command the largest volume positions due to their essential role in starch saccharification, while beta-glucanase generates premium pricing in high-adjunct and high-oat brewing where viscosity reduction becomes critical. Liquid formulations lead industrial procurement because of dosing precision and handler familiarity, though powder and granular forms are gaining traction in smaller facilities seeking extended shelf stability and reduced cold-chain dependency.
The FDA's GRAS notification framework and EFSA's food enzyme evaluation process shape market access by mandating toxicological dossiers and production strain disclosures that filter out unqualified suppliers. Germany's BfR and the Brewing and Malting Barley Research Institute publish technical guidelines that influence enzyme performance benchmarking across Central European brewing clusters. Stakeholders must monitor evolving purity thresholds and strain transparency requirements as regulatory convergence between North American and European assessment protocols accelerates supplier consolidation pressures.
Market Dynamics
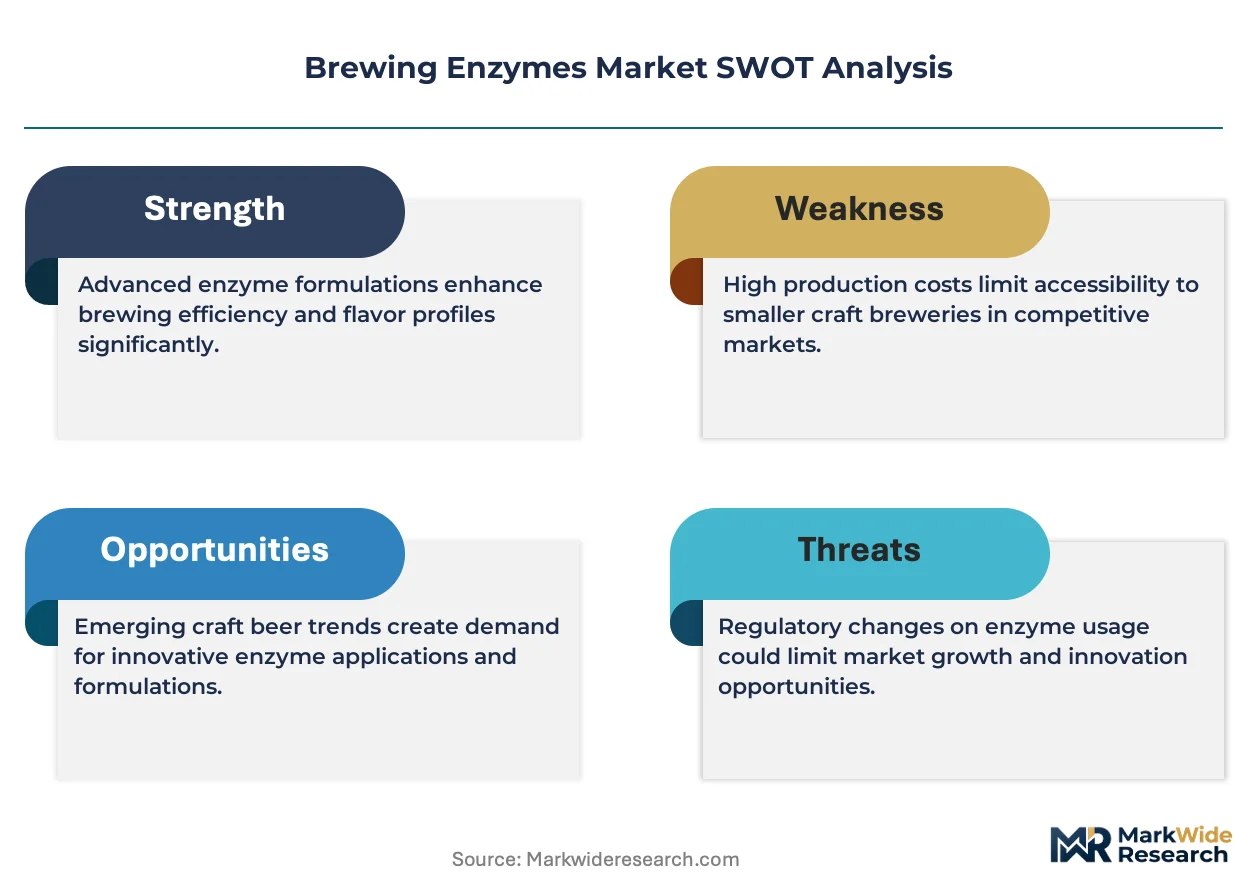
Enzyme supplier consolidation around pharmaceutical-grade purity certification is compressing procurement options for mid-sized malt houses and forcing reformulation investments across the brewing value chain.
Growth Catalysts
- EFSA Food Enzyme Evaluation:The harmonized safety assessment framework accelerates cross-border enzyme approvals, reducing regulatory lag for suppliers seeking multi-country market access.
- High-adjunct brewing:Brewers in Germany and the United States deploy beta-glucanase to process unmalted oats and rice, extracting fermentable sugars without traditional malt infrastructure.
- Liquid formulation precision:Automated dosing systems enable real-time mash adjustment, cutting variability losses in large-scale lager production.
Market Restraints
- Fermentation substrate volatility:Barley and wheat price swings squeeze enzyme cost absorption margins, particularly for craft breweries lacking long-term grain contracts.
- Supplier concentration in Denmark:Microbial platform dominance by two Nordic biotechnology groups limits price negotiation leverage for regional malt processors.
- Thermostability ceilings:Current alpha-amylase variants lose efficacy above 75°C, constraining high-temperature mashing protocols that accelerate throughput.
Strategic Opportunities
- India craft segment:Emerging microbreweries in Bangalore and Mumbai seek technical service partnerships to navigate enzyme selection without in-house biochemistry capacity.
- Cell-free enzyme synthesis:Converging synthetic biology and continuous processing technologies promise batch-to-batch consistency without live fermentation risks.
- US bioengineered disclosure rules:The USDA's National Bioengineered Food Disclosure Standard creates first-mover advantage for suppliers with transparent strain documentation.
Industry Challenges
- Enzymologist talent scarcity:Brewing science programs produce fewer specialists capable of bridging biochemistry and production engineering, extending troubleshooting timelines.
- GRAS notification delays:FDA toxicological review backlogs stretch novel enzyme approvals to 24-36 months, freezing product pipeline investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Enzymes Market |
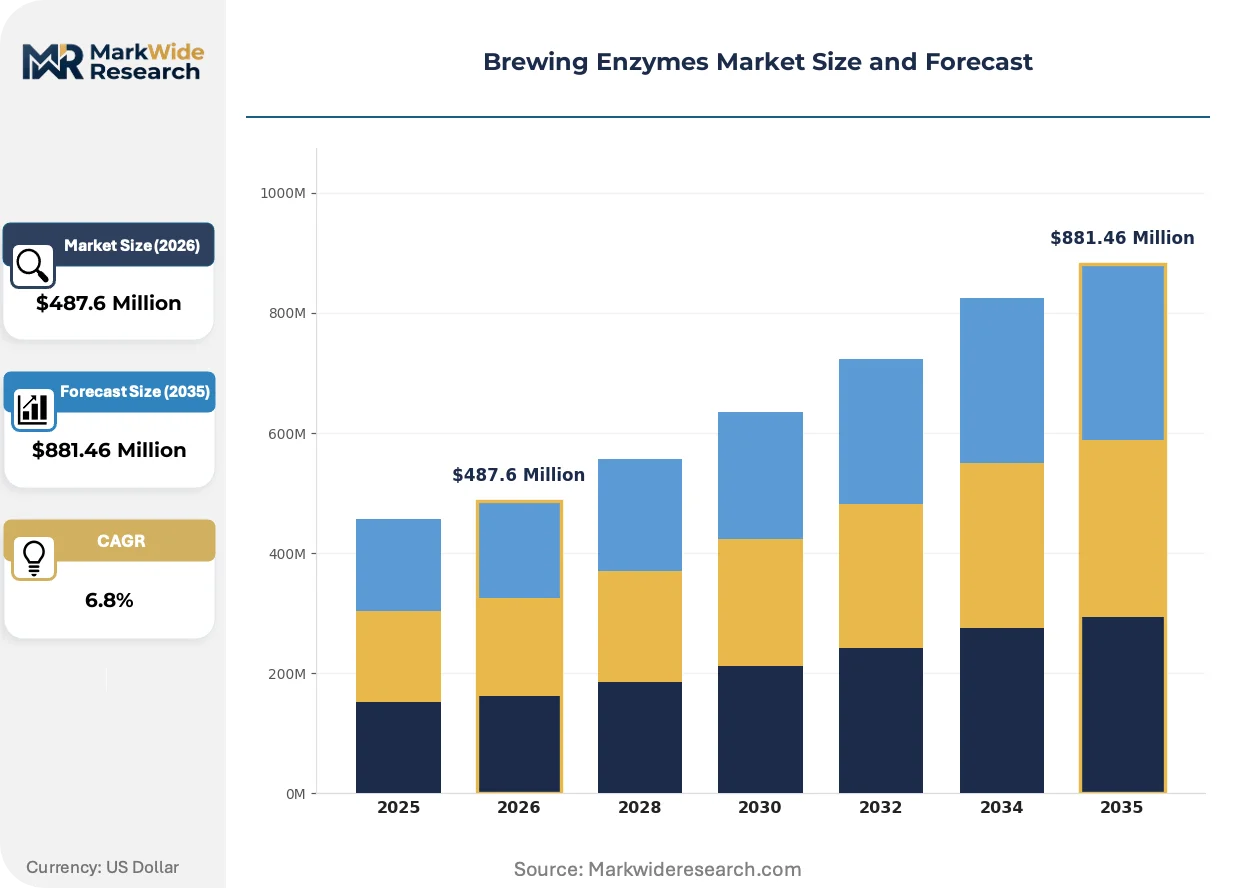
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Glucoamylase, Beta-Glucanase, Protease Application: Lager Production, Ale Production, Specialty Beers, Malt Beverage End User: Craft Breweries, Large Breweries, Microbreweries, Home Brewers Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Novozymes A/S, DSM-Firmenich, DuPont de Nemours, Inc., Amano Enzyme Inc., Associated British Foods plc, BASF SE, Kerry Group plc, Advanced Enzyme Technologies, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Enzymes Market Emerging Trajectories
Biotechnology platforms and regulatory disclosure mandates are reconfiguring how enzymes are developed, validated, and procured across brewing operations of varying scale.
Continuous bioprocessing is decomposing the batch fermentation paradigm that has dominated enzyme manufacturing for decades. Contract manufacturers in the Netherlands and Singapore install perfusion bioreactors that maintain microbial cultures in steady-state production, collapsing cycle times from weeks to days. This operational shift enables just-in-time enzyme supply contracts that reduce cold-chain inventory burdens for distant brewing facilities.
REACH substance registration requirements in Europe now capture fermentation-derived proteins previously exempt under generic bulk chemical classifications. The European Chemicals Agency's expanded dossier demands force enzyme suppliers to disclose production strain lineages and residual DNA thresholds. German malt houses face the steepest compliance costs, as their centralized procurement models concentrate exposure to registration renewal deadlines.
Direct supplier relationships are displacing distributor intermediaries in craft brewery enzyme sourcing. Smaller brewers in Colorado and Oregon now contract technical service agreements straight with biotechnology firms, accessing application support previously reserved for industrial lager accounts. This channel compression rewards suppliers with regional technical staff density over those relying on generalized distribution networks.
Brewing Enzymes Market Segmentation
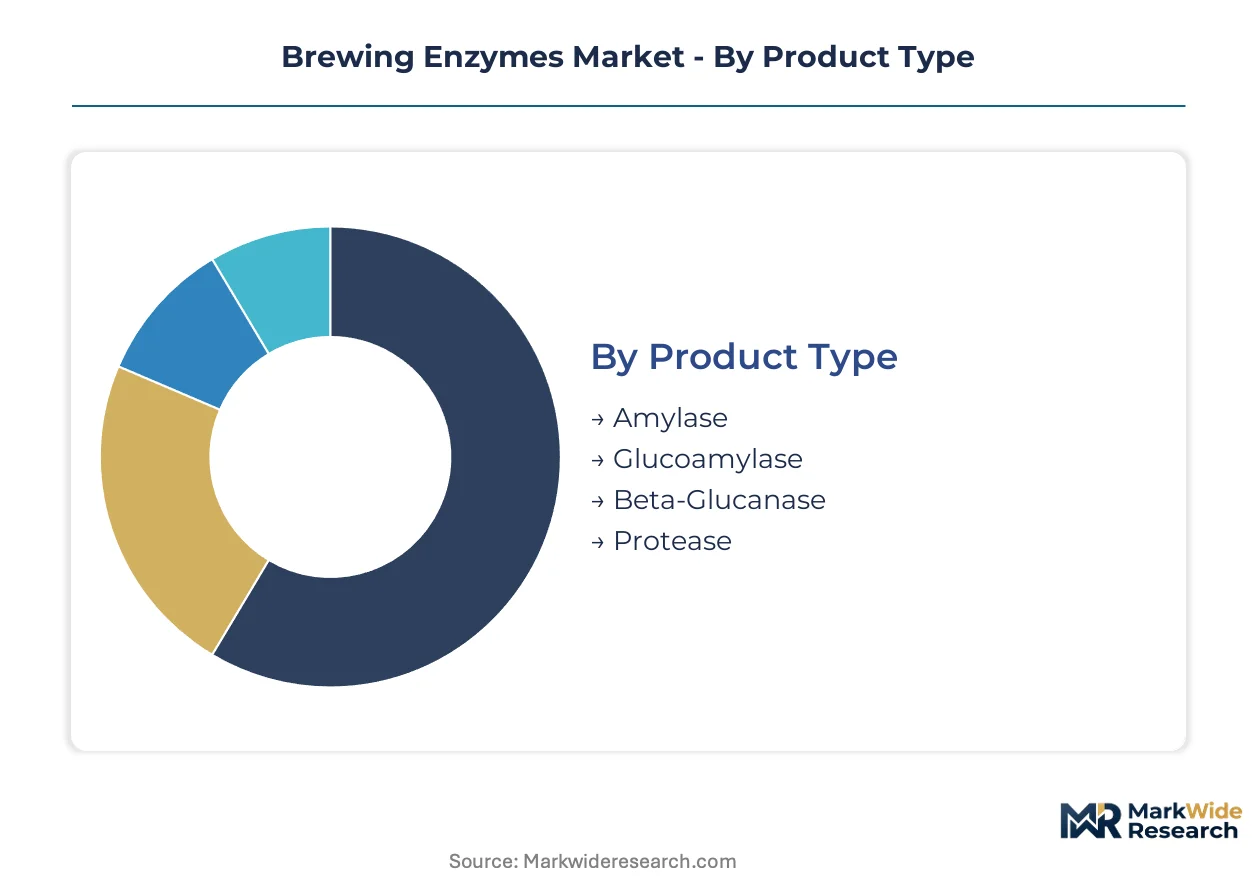
Brewing enzyme procurement splits across technical specifications, operational scale, and regulatory compliance tiers. Distinct performance requirements across lager versus specialty beer production create divergent supplier qualification pathways. Formulation choices—liquid versus dry—further stratify based on cold-chain infrastructure and dosing automation maturity.
Product Type:
Amylase and glucoamylase face the weakest substitution pressure due to irreplaceable starch saccharification functions, while protease encounters rising competition from alternative protein stabilization methods.
- Amylase:Alpha-amylase variants hydrolyze internal alpha-1,4-glycosidic bonds in starch polymers, producing dextrins and maltose during mashing at 60-70°C. German lager breweries in Bavaria and Baden-Württemberg concentrate procurement for decoction mash protocols where precise dextrinization controls final attenuation.
- Glucoamylase:Exo-acting enzymes cleave terminal glucose units from starch chains, enabling complete saccharification for high-attenuation beers. United States craft breweries in Colorado deploy glucoamylase to achieve sub-1.010 finishing gravities in brut IPA and light lager formulations.
- Beta-Glucanase:Hydrolyzes beta-1,3 and beta-1,4 linkages in barley and oat cell walls, reducing wort viscosity for high-adjunct brewing.
- Protease:Cleaves peptide bonds to reduce haze-forming proteins, though silica gel and PVPP alternatives constrain enzyme adoption in clarity-focused operations.
Amylase anchors the volume base while beta-glucanase gains share at the steepest rate.
Application:
Cost tier stratification separates commodity lager production from premium specialty brewing, with enzyme spend per hectoliter varying threefold across the spectrum.
- Lager Production:Industrial-scale facilities prioritize thermostable amylase variants that withstand 72°C mashing temperatures without denaturation. Automated dosing systems at Anheuser-Busch InBev and Heineken plants enable real-time enzyme adjustment based on malt variability.
- Specialty Beers:Barrel-aged and sour beer producers deploy enzyme cocktails for complex carbohydrate profiles. Belgian lambic breweries in Brussels and Pajottenland rely on beta-glucanase to process unmalted wheat without traditional turbid mash infrastructure.
- Ale Production:Warmer fermentation temperatures reduce enzyme dependency, though diastaticus strain contamination risks drive glucoamylase monitoring.
- Malt Beverage:Adjunct-heavy formulations in Latin American markets require enhanced enzymatic conversion for rice and corn substrates.
Lager production commands the procurement volume while specialty beers deliver the highest enzyme spend per hectoliter.
End User:
Customer type determines technical service intensity, with microbreweries requiring hands-on formulation support that large breweries source internally.
- Large Breweries:Integrated quality control laboratories validate enzyme performance against EBC and ASBC standards. Carlsberg and Molson Coors negotiate multi-year supply agreements with tiered pricing tied to pharmaceutical-grade purity certification.
- Craft Breweries:Smaller scale demands application-specific guidance on mash pH adjustment and enzyme dosage optimization. Portland and San Diego craft clusters contract direct with Novozymes technical service teams, bypassing traditional distribution.
- Microbreweries:Limited biochemistry capacity drives preference for pre-formulated enzyme blends over single-activity products.
- Home Brewers:Consumer-packaged enzyme tablets and powder sachets target 5-20 liter batch sizes with simplified instruction protocols.
Large breweries anchor the volume base while craft breweries expand procurement most quickly.
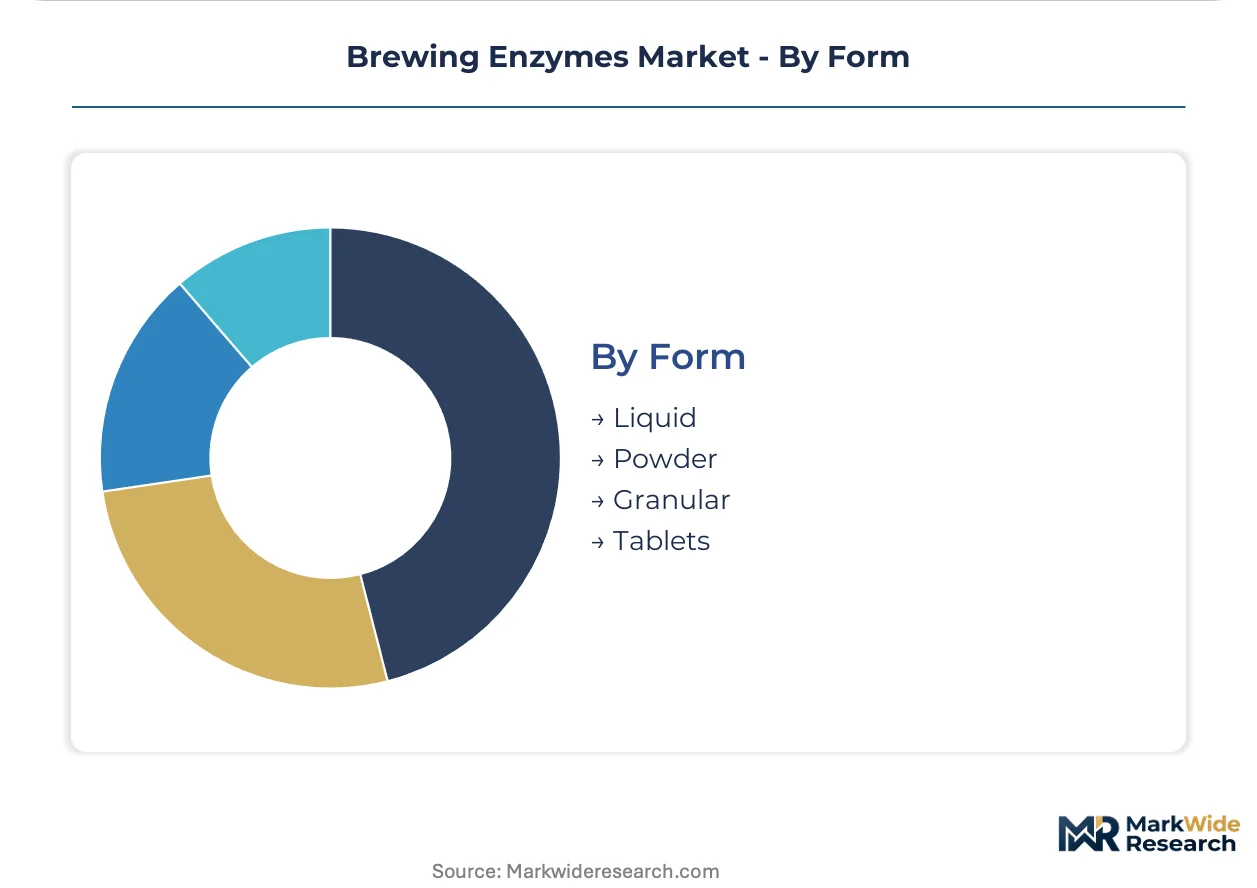
Form:
Supply concentration in liquid formulation manufacturing creates procurement rigidity for facilities lacking cold storage infrastructure.
- Liquid:Aqueous enzyme solutions enable precise volumetric dosing through automated injection systems. Dutch and Danish contract fermentation facilities supply liquid glucoamylase to Heineken's Zoeterwoude brewery under just-in-time logistics contracts.
- Powder:Spray-dried formulations extend shelf stability to 24 months at ambient temperature, reducing inventory risk for seasonal breweries. German farmhouse breweries in Franconia stock powder amylase for autumn bock production campaigns.
- Granular:Dust-free handling characteristics suit smaller facilities without enclosed dosing equipment.
- Tablets:Pre-measured unit doses eliminate weighing errors for microbrewery and homebrewing segments.
Liquid form dominates industrial procurement while powder gains traction among seasonal and remote brewing operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme manufacturing clusters concentrate in Denmark and the Netherlands, where microbial fermentation infrastructure serves brewing clients across three continents. Regulatory divergence between FDA and EFSA approval pathways shapes supplier market access strategies. Demand patterns split between industrial lager strongholds and craft brewery expansion zones.
United States
Colorado and Oregon craft brewery clusters drive beta-glucanase procurement for oat-heavy hazy IPA formulations. The FDA's GRAS notification framework mandates toxicological dossiers that filter out unqualified enzyme suppliers. Pacific Northwest malt houses negotiate direct technical service contracts with biotechnology firms, bypassing traditional distribution layers.
Germany
Bavarian lager breweries anchor alpha-amylase demand for decoction mash protocols requiring precise dextrinization control. The BfR publishes purity benchmarks that reshape supplier qualification requirements across Central European brewing clusters. Franconian farmhouse breweries stock powder enzyme formulations for seasonal bock production campaigns.
Denmark
Nordic biotechnology groups dominate microbial platform supply for large-scale lager operations worldwide. EFSA's food enzyme evaluation process accelerates cross-border approvals for Danish fermentation-derived products. Copenhagen-area contract manufacturers supply liquid glucoamylase to Heineken under just-in-time logistics contracts.
India
Bangalore and Mumbai microbreweries seek technical partnerships to navigate enzyme selection without in-house biochemistry capacity. FSSAI food safety standards create compliance entry barriers for imported fermentation inputs. Maharashtra-based craft producers deploy amylase cocktails for adjunct-heavy formulations using local rice substrates.
Netherlands
Zoeterwoude brewing facilities integrate automated enzyme dosing systems for real-time mash adjustment. REACH substance registration requirements now capture fermentation-derived proteins previously exempt under bulk chemical classifications. Dutch perfusion bioreactor installations enable continuous enzyme production, collapsing cycle times from weeks to days.
Brewing Enzymes Market Vendor Landscape
Concentration sits with Nordic microbial platform specialists and integrated biotechnology conglomerates that control pharmaceutical-grade purity certification pathways. The supplier base organizes around three archetypes: fermentation technology leaders, diversified nutrition-science groups, and application-specific technical service providers. Competitive dynamics revolve around strain transparency documentation and direct channel relationships with craft brewery clusters. M&A activity targets regional technical service capabilities, while capacity investments focus on continuous bioprocessing infrastructure.
Among Nordic biotechnology leaders, Novozymes A/S and Chr. Hansen Holding A/S exemplify the microbial platform archetype that dominates high-performance enzyme supply. DSM-Firmenich represents the integrated nutrition-science model, anchoring position through biotechnology pipelines serving European malt houses. Kerry Group plc occupies the technical service tier, differentiating via application-specific support teams that navigate formulation complexity for smaller brewing clients. These three patterns illustrate how competitive positioning splits between scale-driven fermentation, integrated supply chains, and hands-on customer engineering.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM-Firmenich |
| DuPont de Nemours, Inc. |
| Amano Enzyme Inc. |
| Associated British Foods plc |
| BASF SE |
| Kerry Group plc |
| Advanced Enzyme Technologies |
| Chr. Hansen Holding A/S |
| Others |
Supply Flow & Price Mechanics
Microbial fermentation capacity utilization above 85 percent in Danish and Dutch manufacturing clusters compresses unit economics for pharmaceutical-grade enzymes, concentrating supply-side pricing power among Nordic biotechnology groups while forcing regional malt processors to absorb premium tier qualification costs.
Pricing Analysis
EFSA's food enzyme evaluation process dictates the pricing tier structure across European procurement, separating pharmaceutical-grade purity certification from standard food-grade supply. Three-tier pricing structure across premium, standard, and economy levels reflects toxicological dossier completeness and production strain documentation transparency. Cost compression in the standard tier is intensifying because REACH registration deadlines concentrate compliance investment among German malt houses. Craft breweries in Colorado and Oregon exhibit highest price sensitivity due to limited volume scale and absence of long-term supply agreements, while integrated lager operations at Heineken and Carlsberg negotiate least-sensitive contract positions tied to multi-year offtake guarantees.
Supply Chain Analysis
Just-in-time liquid enzyme delivery from Copenhagen-area contract manufacturers to Zoeterwoude brewing facilities operates on 48-72 hour lead-time windows, constraining inventory buffers against fermentation batch variability. Supply concentrates in Denmark, the Netherlands, and Germany, with microbial platform infrastructure anchored in Nordic biotechnology clusters. Raw material dependencies center on pharmaceutical-grade nutrient media, specialized fermentation vessel alloys, and cold-chain logistics capacity. Single-source vulnerability runs through the two dominant Nordic microbial platform suppliers, limiting buyer negotiation leverage. Distribution runs through direct technical service agreements for craft brewery segments and consolidated distributor networks for industrial lager accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing technology and synthetic biology convergence are accelerating disruption, with cell-free enzyme synthesis threatening batch fermentation economics and EFSA strain transparency mandates filtering supplier qualification tiers.
For Market Incumbents: Secure pharmaceutical-grade purity certification pathways before REACH registration renewal deadlines consolidate supplier tiers, and anchor capacity expansion in perfusion bioreactor installations that collapse production cycle times. Cell-free synthesis platforms from synthetic biology entrants threaten batch fermentation cost structures, requiring backward integration into continuous processing infrastructure to defend unit economics. For New Entrants and Emerging Players: Technical service gaps in India's craft brewery segment offer white-space entry where Bangalore and Mumbai microbreweries lack in-house biochemistry capacity for enzyme selection. Direct supplier relationships displacing distributor intermediaries in Colorado and Oregon craft clusters present the most penetrable channel structure. Deploy application-specific support teams that navigate mash pH adjustment and dosage optimization without requiring client-side enzymology expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical service-tier suppliers with regional staff density and direct craft brewery contracts, offering superior cash-flow predictability compared to commodity fermentation plays. Long-term viability through the projection horizon favors acquisition targets with transparent strain documentation aligned to USDA bioengineered disclosure rules and EFSA evaluation protocols. Watch for FDA GRAS notification backlog clearance as inflection signal for novel enzyme pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion bioreactor installations collapse cycle times from weeks to days for Danish contract manufacturers. |
| Pharmaceutical-Grade Certification Investment | Toxicological dossier completeness filters supplier tiers under EFSA's harmonized safety assessment framework. |
| Direct Technical Service Expansion | Regional staff density in Portland and San Diego bypasses distributor layers for craft brewery accounts. |
| Cell-Free Enzyme Synthesis Development | Synthetic biology convergence promises batch-to-batch consistency without live fermentation contamination risks. |
| Strain Transparency Documentation | Production strain lineage disclosure aligns with USDA National Bioengineered Food Disclosure Standard requirements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brewing science directors at Bavarian lager houses, procurement leads at Colorado craft brewery clusters, enzymology specialists at Dutch contract fermentation facilities, and technical service managers at Nordic biotechnology groups. Secondary validation drew from EFSA food enzyme evaluation dossiers, FDA GRAS notification registers, BfR purity benchmark publications, and Brewing and Malting Barley Research Institute technical guidelines. Bottom-up enzyme volume modeling triangulated against top-down brewing production statistics across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by enzyme type, application protocol, end-user scale tier, and formulation state, with additional dimensioning for regulatory compliance tier. CAGRs were derived from trend extrapolation of craft brewery expansion rates and industrial lager automation investment cycles, cross-referenced against EFSA approval velocity and FDA toxicological review throughput. Industry-specific inputs included decoction mash protocol prevalence in German brewing clusters and oat-heavy hazy IPA formulation adoption in Pacific Northwest craft segments.
Underlying assumptions cover sustained EFSA-REACH regulatory convergence and stable barley price volatility bands, with deviation risk concentrated in FDA GRAS notification backlog duration and synthetic biology platform commercialization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Alcoholic Drinks Market