
 Cooking Wine Market | 2026-2036
Cooking Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Wine Market Intelligence
Demand from home cooks seeking premium ingredients for complex recipes is bifurcating the market away from its traditional food service base. Mizkan America Inc. leverages its brand recognition within retail channels to capture this shift. The Kroger Co. competes by offering accessible private-label cooking wines. Meanwhile, Roland Foods, LLC specializes in supplying high-quality, specialty cooking wines to both retail and professional kitchens, anchoring its position in the premium segment.
Cooking wine is a grape wine modified for culinary use, typically containing added salt to prevent its consumption as a beverage and to act as a preservative. Its primary purpose is to add flavor, acidity, and moisture to dishes without the high alcohol content of traditional table wine. White wine variants hold a significant share due to their versatility in sauces and poultry dishes. The market's value is increasingly found in premium and organic quality levels, which offer higher margins compared to standard cooking grade products.
Food safety and labeling standards set by the US FDA and the European EFSA dictate permissible preservatives and sodium levels, shaping product formulations. In countries like Australia, regulations from the TGA can also influence import requirements for products containing alcohol. The central strategic decision for producers involves balancing investment between the high-volume food service segment and the brand-intensive premium retail channel.
Market Dynamics
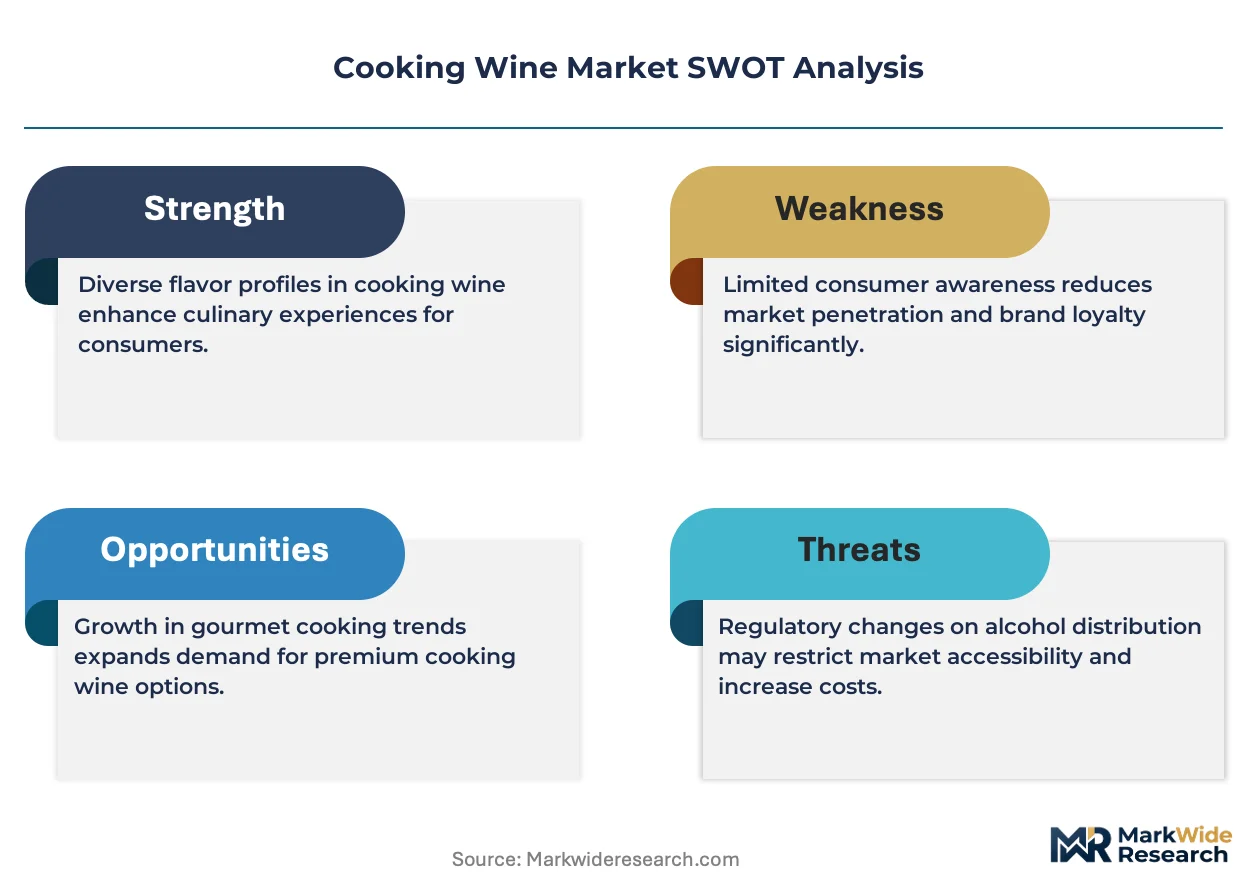
The market's structure is defined by a fundamental tension between the high-volume, cost-sensitive food service channel and the burgeoning premium retail segment. This divergence forces producers to navigate conflicting demands for shelf stability versus craft-oriented, clean-label attributes, directly influencing product formulation and go-to-market strategies.
Growth Catalysts
- Clean-Label Formulations:Consumer demand for transparency, reinforced by retail-specific quality standards, pushes development of cooking wines with natural preservatives and lower sodium, aligning with wellness trends in home cooking.
- Professional Catering Expansion:Growth in the global professional catering and institutional food service sectors creates consistent demand for shelf-stable, standardized flavor solutions that deliver consistent results in large-scale food preparation.
- Culinary Tourism and Media:The popularization of complex international cuisines through digital media inspires home cooks in markets like the United States and the UK to experiment with authentic, premium-grade ingredients.
Market Restraints
- Ingredient Substitution:In cost-sensitive applications, chefs may substitute cooking wine with vinegar, citrus juices, or wine reductions made from lower-cost table wines, limiting penetration in certain culinary segments.
- Regulatory Sodium Limits:Stringent sodium content regulations, such as those guided by the US FDA and Europe's EFSA, complicate formulation and can impact the product's shelf life and flavor profile, adding development costs.
- Grape Price Volatility:The price and quality of base wine, the primary input, are subject to agricultural volatility from climate events, directly impacting production costs and margin stability for manufacturers.
Strategic Opportunities
- Organic and Fortified Variants:There is significant white space in certified organic cooking wines and fortified versions like sherry or marsala cooking wines, catering to niche, high-margin premium retail and fine dining segments.
- Asia-Pacific Market Entry:Rising disposable incomes and adoption of Western culinary practices in urban centers across countries like South Korea and Australia present an underpenetrated market for premium cooking wine products.
- Direct-to-Consumer Channels:E-commerce platforms and subscription box models offer a new channel to reach home cooks directly, bypassing traditional retail and enabling brand storytelling around sourcing and quality.
Industry Challenges
- Dual-Channel Logistics:Managing divergent supply chain requirements for bulk food service packaging versus brand-intensive, shelf-ready retail formats creates significant operational complexity and inventory management challenges for producers.
- Complex International Compliance:Exporting products requires navigating a patchwork of alcohol-related regulations, from Europe's EFSA food additive rules to Australia's TGA import standards, increasing compliance overhead and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Wine Market |
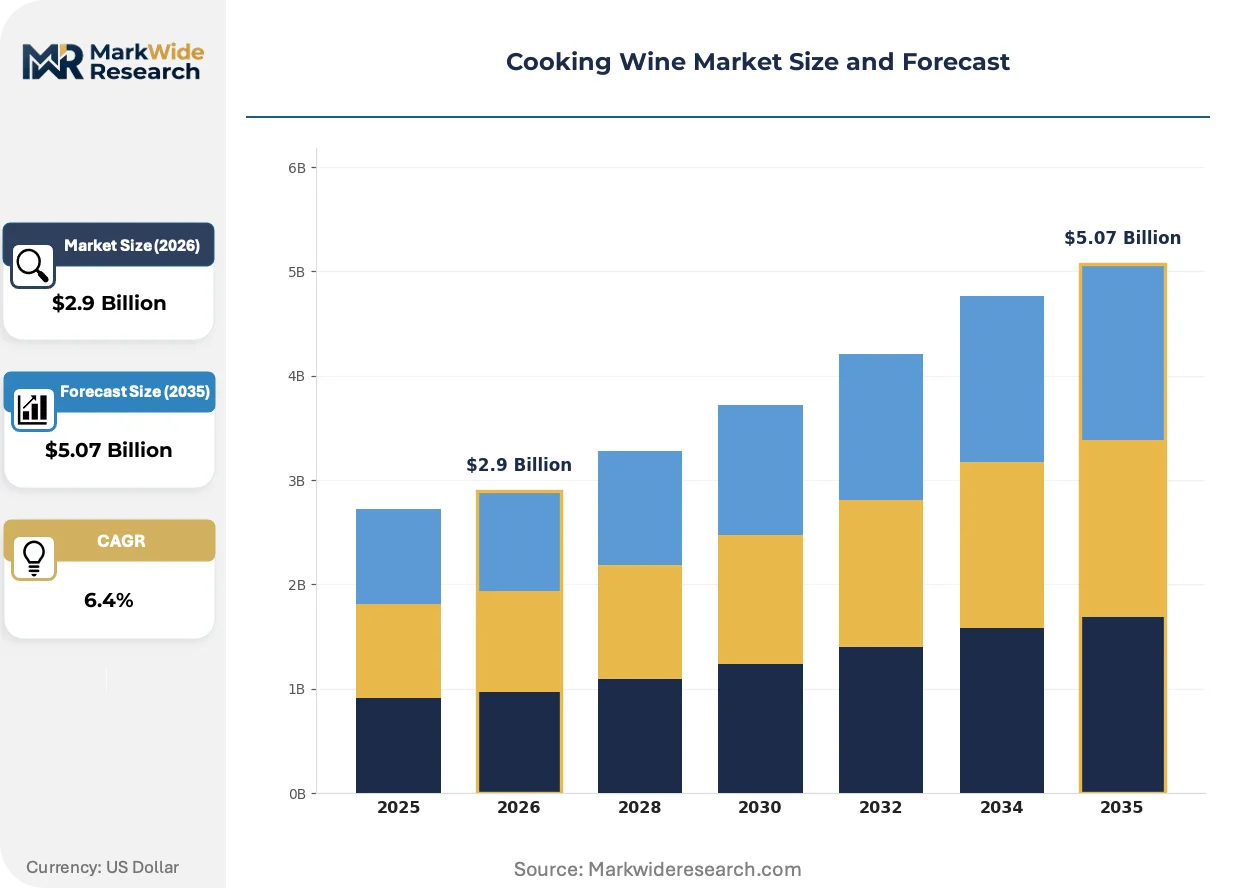
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red, White, Sherry, Marsala End User: Restaurants, Home Cooks, Catering Services, Culinary Schools Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Quality Level: Premium, Standard, Cooking Grade, Organic |
| Companies Covered | Roland Foods, LLC, PALMETTO CANNING, Batory Foods, Marina Foods, Inc., ECOVINAL, S.L.U., Stratas Foods, The Kroger Co., Iberica Export, Mizkan America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Wine Market Strategic Shifts & Innovations
Product development is pivoting from industrial-scale utility toward craft and premiumization. This shift reflects a broader food culture change where even functional ingredients like cooking wine are scrutinized for origin, purity, and flavor complexity by end-users.
Advanced flavor concentration technology, using methods like reverse osmosis, creates potent wine extracts that preserve delicate aromatics. Professional chefs and industrial food processors are adopting these concentrates for precise, repeatable flavor dosing in sauces and marinades. This innovation is miniaturizing the required product volume for a given flavor impact, enabling more efficient and cost-effective formulations.
Heightened regulatory scrutiny over food labeling is driving formulation changes across the industry. Mandates from the US FDA on sodium disclosure and the European EFSA on sulphite and allergen declarations are forcing producers to seek cleaner, more transparent ingredient lists. The premium segment is most affected, actively reformulating products to meet "natural" or "organic" certifications.
A pronounced shift in purchasing behavior sees home cooks moving away from generic supermarket options toward specialty food stores and online channels for premium ingredients. This trend disrupts the traditional grocery channel's dominance for retail cooking wine sales, favoring brands that can build a direct connection with consumers. This pattern is most visible in North American and European culinary hubs.
Cooking Wine Market Segmentation
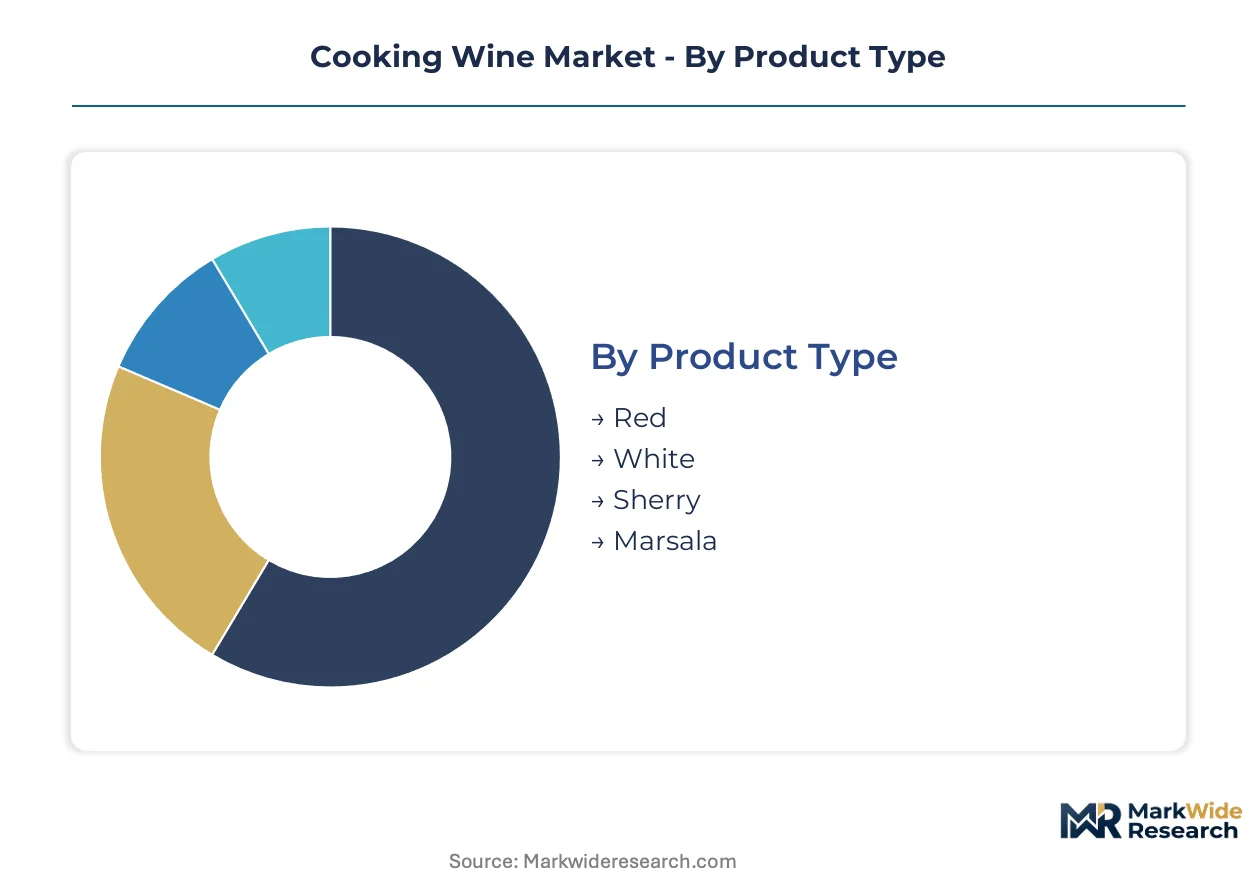
Market segmentation provides a granular view of the cooking wine industry, highlighting the diverse product offerings and consumer demands that shape its competitive landscape. Understanding these distinct segments allows producers to tailor product formulations, marketing strategies, and distribution networks effectively. This segmentation also reveals evolving preferences across both professional and retail channels.
Product Type:
Product type segmentation highlights how different wine variants are channeled to distinct culinary applications and consumer preferences.
- White:This variant is typically light-bodied, with high acidity and citrus notes, making it versatile for deglazing, sauces, and poultry dishes. Demand concentrates in European and North American kitchens for its ability to brighten flavors without overpowering.
- Sherry:A fortified wine known for its nutty, savory, or sweet profiles, sherry cooking wine adds depth to soups, stews, and reductions. Demand is significant in fine dining establishments and premium retail channels across Spain and the United Kingdom.
- Red:These robust, often tannic, wines are suitable for red meats, hearty stews, and rich sauces, contributing color and a complex flavor profile.
- Marsala:A fortified wine, available in dry or sweet forms, marsala is a staple in Italian cuisine, frequently used in savory dishes like chicken marsala and various desserts.
By volume, White cooking wine leads the market. By growth pace, Sherry variants are expanding most quickly.
End User:
End user segmentation reveals distinct procurement patterns and usage occasions across professional and home-based culinary environments.
- Home Cooks:These consumers seek premium ingredients for complex recipes, often purchasing through brand-intensive retail channels and specialty stores. Demand from home cooks is strong in North America and Europe, driven by culinary media and a desire for authentic flavors.
- Catering Services:This segment demands consistent, shelf-stable flavor enhancers for large-scale food preparation, prioritizing reliability and cost-effectiveness. Growth in the global professional catering sector creates continuous demand for these standardized solutions.
- Restaurants:Restaurants utilize cooking wine for diverse menu items, prioritizing consistent quality, bulk supply, and flavor integrity for their culinary creations.
- Culinary Schools:These institutions procure cooking wine for educational purposes, emphasizing product versatility and instructional value in teaching various cooking techniques.
Home Cooks represent a high-margin segment for premium products. Catering Services drive significant volume through consistent procurement.
Distribution Channel:
Distribution channel analysis illustrates the varied pathways products take from producers to end consumers, reflecting evolving purchasing behaviors.
- Online:E-commerce platforms and subscription box models offer a direct-to-consumer channel, enabling brand storytelling around sourcing and quality. This channel is gaining traction among home cooks in North American and European culinary hubs.
- Wholesale:This channel supplies bulk quantities to professional kitchens, catering services, and institutional buyers, prioritizing cost-effectiveness and volume. The global foodservice sector relies heavily on wholesale distribution for consistent product access.
- Supermarkets:Supermarkets serve as a traditional retail channel for mass-market cooking wines, offering accessibility and convenience to a broad base of home cooks.
- Specialty Stores:These stores cater to the premium segment, offering curated selections and expert advice for discerning consumers seeking unique or high-quality ingredients.
Online channels offer efficient direct-to-consumer reach. Wholesale channels provide broad penetration into the professional sector.
Quality Level:
Quality level segmentation delineates product differentiation based on ingredient sourcing, processing, and perceived value, impacting pricing and market positioning.
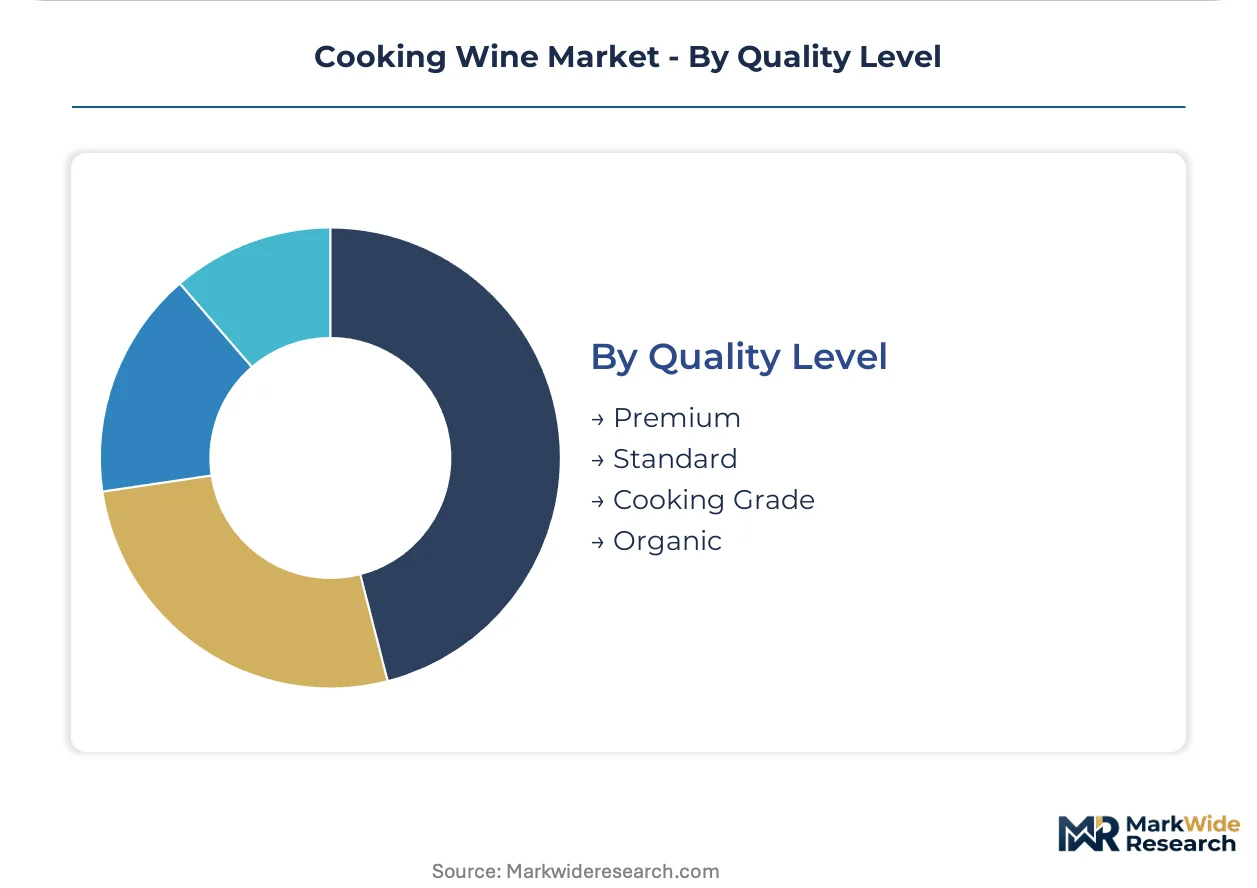
- Premium:This segment features higher-quality base wines, often with specific varietal characteristics and minimal additives, targeting discerning consumers and fine dining establishments. Demand for premium cooking wines is concentrated in culinary hubs within France, Italy, and the United States.
- Organic:Certified organic cooking wines adhere to stringent organic farming standards, appealing to health-conscious consumers and meeting specific retail quality benchmarks. This segment sees strong demand in Europe and North America, driven by wellness trends and transparency mandates.
- Standard:Standard cooking wines offer a balance of quality and affordability, serving as general-purpose options for everyday culinary use across various applications.
- Cooking Grade:These basic formulations, often with added salt for preservation, are designed for high-volume foodservice applications where cost and functional utility are primary considerations.
Premium and Organic quality levels capture higher market value. Cooking Grade products appeal primarily to cost-sensitive bulk purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cooking wine producers frequently export specialized variants to North American retail channels, meeting a growing demand for authentic international flavors. This trade flow supports the expansion of premium and organic product lines. Such cross-continental commerce shapes regional market dynamics.
United States
United States consumers, particularly home cooks, drive demand for premium ingredients to create complex international recipes. US FDA sodium disclosure mandates influence product formulation, pushing for cleaner labels. Culinary hubs like New York City and Los Angeles foster innovation in specialty food stores, showcasing diverse cooking wine options.
France
French professional catering services and fine dining establishments consistently demand high-quality, reliable cooking wine solutions. Europe's EFSA dictates food additive rules, ensuring product safety and transparency for French producers. Parisian culinary schools and Michelin-starred restaurants influence the adoption of premium and organic cooking wine products.
Italy
Italian home cooks and restaurants prioritize authentic flavors, creating sustained demand for traditional cooking wine variants like Marsala. EFSA standards impact local producers, especially those exporting their products to other European markets. Sicilian producers specialize in Marsala cooking wines, catering to both domestic culinary traditions and international exports.
Australia
Australian urban centers show increasing interest in Western culinary practices, stimulating demand for premium imported cooking wines. Australia's TGA influences import requirements for alcohol-containing food products, ensuring compliance for foreign suppliers. Cities like Sydney and Melbourne are emerging as key markets for specialty cooking wine distribution.
South Korea
South Korean consumers, with rising disposable incomes, are adopting Western culinary practices, expanding the market for diverse cooking wine products. The MFDS (Ministry of Food and Drug Safety) sets food safety standards for imported products, impacting market entry. Seoul's vibrant food scene and growing e-commerce platforms facilitate premium cooking wine distribution.
Cooking Wine Market Key Industry Players
Listed leaders compete with private specialists across product formulation, distribution reach, and market share. The market exhibits a tiered structure, with global food conglomerates operating alongside niche ingredient providers and dedicated private-label manufacturers. Strategic archetypes include high-volume industrial suppliers, brand-intensive retail players, and premium specialty distributors serving fine dining. Companies pursue portfolio diversification into organic and fortified variants, alongside geographic expansion into underpenetrated markets, and strategic partnerships for technology transfer.
Specialists in retail channel penetration, Mizkan America Inc. and The Kroger Co. exemplify distinct approaches to consumer engagement. Mizkan America Inc. leverages established brand recognition to capture home cook demand, while The Kroger Co. provides accessible private-label options through its extensive supermarket network. Roland Foods, LLC, a US-based LLC, anchors the premium segment by supplying high-quality, specialty cooking wines to both retail and professional kitchens, representing a focus on curated product offerings.
| Leading Market Players |
|---|
| Roland Foods, LLC |
| PALMETTO CANNING |
| Batory Foods |
| Marina Foods, Inc. |
| ECOVINAL, S.L.U. |
| Stratas Foods |
| The Kroger Co. |
| Iberica Export |
| Mizkan America Inc. |
| Others |
Cost & Logistics Intelligence
US FDA and Europe's EFSA regulatory regimes gate product qualification and simultaneously drive price differentiation for cooking wine. This influences sourcing and formulation choices across all market segments.
Pricing Analysis
Formulation-generation pricing gaps exist between standard cooking wines, clean-label options, and organic variants. The market operates with a three-tier pricing structure across premium, standard, and economy levels. Quality grade, particularly organic certification, and brand premium are key price differentiation drivers. Pricing pressure stems from ingredient substitution in cost-sensitive applications, where chefs may use lower-cost alternatives. Catering Services represent the most price-sensitive buyer segment, while fine dining establishments show the least sensitivity.
Supply Chain Analysis
France and Italy anchor the supply of high-quality base wines for European cooking wine production. The supply chain draws from grape harvests, salt, and permitted preservatives as primary inputs. Grape price volatility, driven by climate events, represents a significant structural risk for manufacturers. Distribution runs through a dual model, with wholesale channels serving the professional food service sector and retail/online platforms reaching home cooks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooking wine market faces a capability gap in balancing high-volume food service demands with brand-intensive premium retail requirements. This operational tension requires specialized expertise.
For Market Incumbents: Fortify core market positions by investing in advanced clean-label formulation R&D. Optimize dual-channel logistics to mitigate the threat of new entrants in the premium segment and ingredient substitution in cost-sensitive applications. Pursue organic certification investments and expand e-commerce channel control to capture direct-to-consumer sales.
For New Entrants and Emerging Players: Service-layer gaps exist in providing highly curated, transparently sourced premium cooking wines. Target the premium home cook segment in North American and European culinary hubs. Introduce organic and fortified variants, leveraging direct-to-consumer platforms for brand storytelling around origin and quality. This approach allows efficient market penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the premium retail segment due to efficient e-commerce reach. The long-term viability of the cooking wine market is stable, supported by consistent foodservice demand and growing premiumization. Target niche specialty producers or brands with strong retail penetration and established organic certifications. Watch for sustained growth in organic product certifications as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Clean-Label Formulations | Enhances brand appeal and meets evolving regulatory standards for transparency. |
| Optimize Dual-Channel Logistics | Reduces operational complexity and improves cost-efficiency for diverse market segments. |
| Expand Direct-to-Consumer Channels | Builds brand loyalty and captures higher margins from premium home cooks. |
| Develop Organic and Fortified Variants | Addresses niche demand and unlocks higher-margin opportunities in fine dining. |
| Geographic Expansion into Asia-Pacific | Captures new consumer bases with rising disposable incomes and Western culinary adoption. |
Research Approach
A spread of perspectives from food service operators, retail buyers, product formulators, and culinary experts converged on the working assumptions for this study. The analysis combined primary interviews with industry stakeholders and secondary validation through regulatory filings from US FDA and Europe's EFSA, trade association reports, and culinary publications. Bottom-up and top-down triangulation ensured data accuracy and consistency.
Product type, end-user, distribution channel, quality level, and regional demand were the segmentation dimensions modeled. The analytical framework projected market trends across the analysis window, with CAGRs derived from historical trends and future projections. Consumer spending on premium food and catering sector growth rates served as critical industry-specific forecast inputs.
Material uncertainties — agricultural volatility, sudden regulatory shifts, and evolving consumer dietary preferences — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Specialty Beer Market