
 North America Beer Market | 2026-2036
North America Beer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beer Market Intelligence
Independent brewery taprooms and brewpub direct-to-consumer channels are fragmenting as legacy distributors lose exclusivity in key metropolitan markets. Anheuser-Busch InBev leverages its vertically integrated brewing and logistics network to maintain cost discipline across mass-market lager production. Molson Coors Beverage Company anchors its position through concentrated investments in above-premium and craft-adjacent portfolios. Boston Beer Company differentiates through hard seltzer and flavored malt beverage extensions that compete beyond traditional beer occasions.
Beer comprises a fermented alcoholic beverage brewed from malted cereal grains, typically barley, with hops added for bitterness, aroma, and preservation, undergoing mashing, boiling, fermentation, and conditioning before packaging for commercial distribution. Lager remains the volume foundation across North America due to its crisp profile and mainstream accessibility, while ale production expands fastest among regional craft operators experimenting with indigenous yeast strains and local malt sourcing. Supermarkets and convenience stores still control the bulk of off-premise volume, though online direct shipping now captures disproportionate growth in specialty and limited-release segments where margin pools run deepest.
The Alcohol and Tobacco Tax and Trade Bureau enforces federal labeling, formula approval, and excise tax compliance that directly shapes product formulation and market entry timelines for new entrants. State-level three-tier distribution laws, administered variably across US jurisdictions, constrain vertical channel control and mandate licensed intermediary participation. Canada’s Health Canada and provincial liquor boards impose parallel packaging standards and advertising restrictions that filter cross-border portfolio standardization. Stakeholders must monitor evolving cannabis-alcohol crossover regulations and state-level direct-shipping liberalization to anticipate where next-generation distribution investments will yield sustainable access advantages.
Market Dynamics
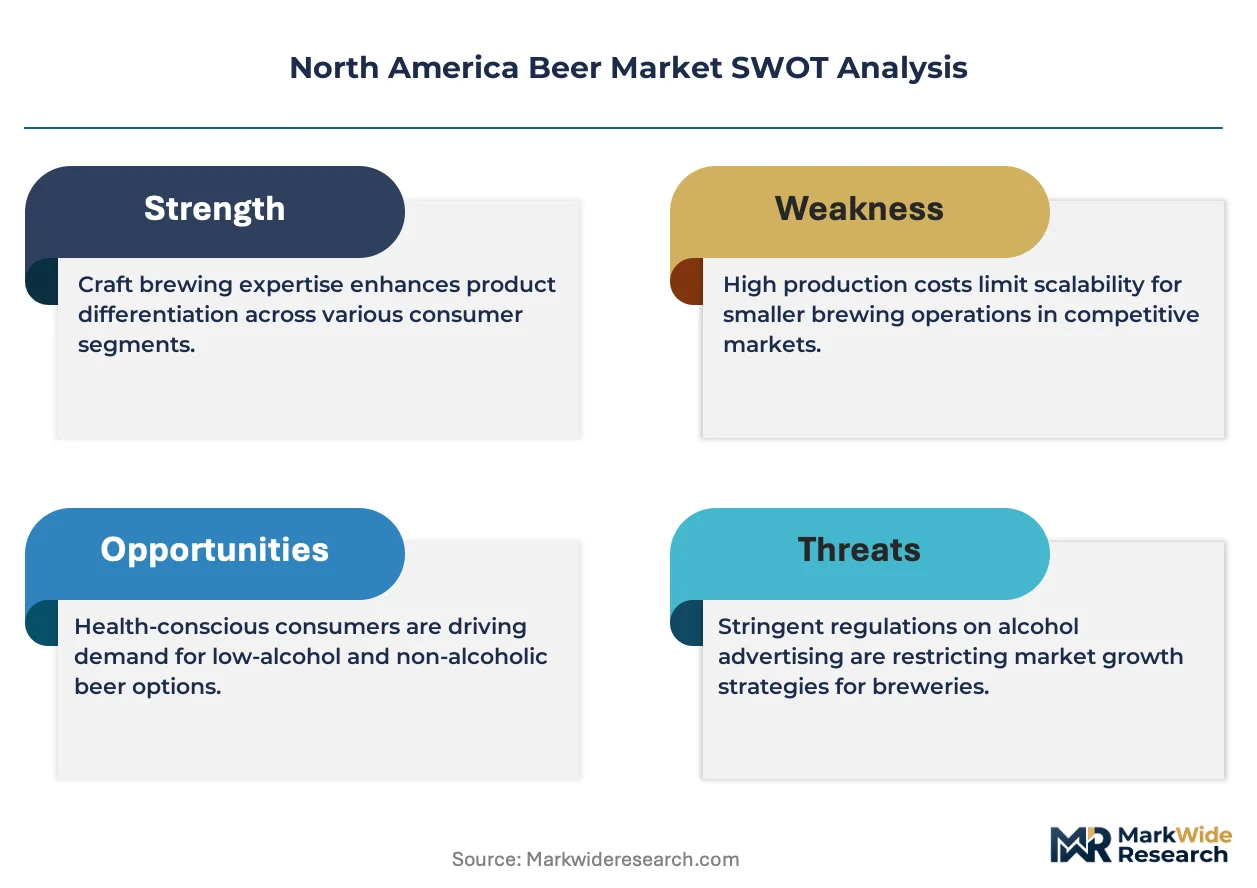
Independent brewery taprooms and brewpub direct-to-consumer channels are fragmenting legacy distributor exclusivity in key metropolitan markets, while the Alcohol and Tobacco Tax and Trade Bureau tightens ingredient disclosure standards that reshape formulation timelines.
Growth Catalysts
- Direct-to-consumer liberalization:State-level shipping law reforms in Texas and California enable brewery-owned e-commerce channels to capture margin pools previously surrendered to licensed distributors.
- TTB formula modernization:Streamlined approval pathways for flavored malt beverages accelerate innovation cycles and reduce time-to-market for seasonal and limited-release portfolios.
- Indigenous ingredient sourcing:Regional craft operators leveraging heritage barley varieties and locally cultivated hops differentiate through terroir-driven positioning that commands price premiums.
Market Restraints
- Three-tier distribution mandate:State-level laws requiring licensed intermediary participation constrain vertical channel control and inflate go-to-market costs for emerging producers.
- Malt supply concentration:North American barley production clusters in the northern Great Plains, exposing brewers to weather-driven input volatility and single-origin risk.
- Cannabis-alcohol substitution:Normalized recreational cannabis consumption in Canada and select US states diverts discretionary spending from traditional beer occasions among younger demographics.
Strategic Opportunities
- Hard seltzer adjacencies:Flavored malt beverage extensions beyond traditional beer occasions capture incremental consumption moments previously owned by spirits and wine.
- Cross-border portfolio optimization:Harmonized production between US and Canadian facilities reduces tariff exposure and enables efficient capacity allocation across North American demand clusters.
- Taproom experience monetization:Brewery-owned hospitality venues generate higher per-visit revenue through food service integration and merchandise capture.
Industry Challenges
- Brewmaster talent scarcity:Specialized fermentation science expertise concentrates among established craft operators, constraining quality consistency for scaling regional entrants.
- Legacy system integration:ERP and inventory management platforms designed for mass-market lager production require costly reconfiguration to accommodate small-batch variability and seasonal SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beer Market |
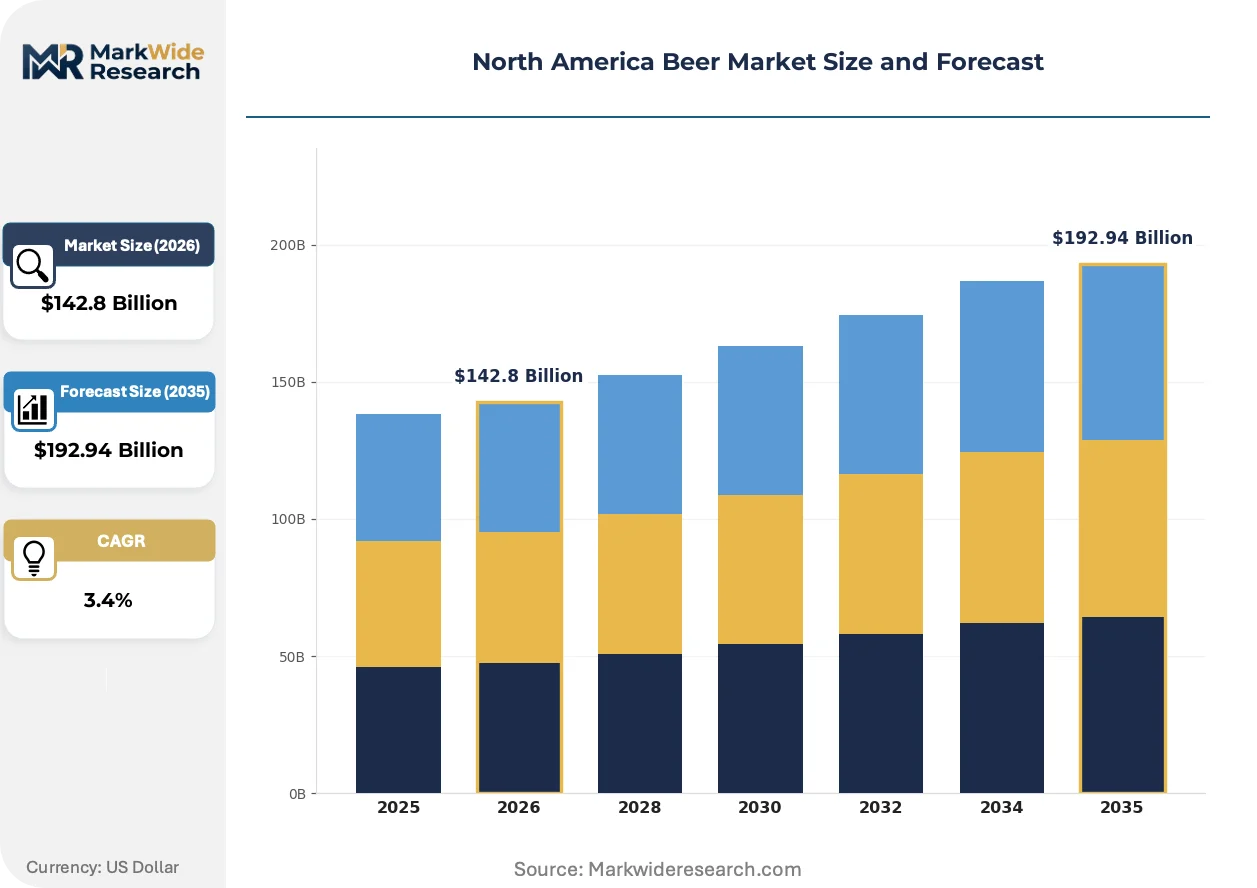
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $192.94 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Distribution Channel: Supermarkets, Convenience Stores, Bars, Online Customer Type: Young Adults, Professionals, Sports Fans, Casual Drinkers Flavor Profile: Hoppy, Floral, Fruity, Malty |
| Companies Covered | Boston Beer Company, Carlsberg Group, Anheuser-Busch InBev, Asahi Group Holdings, Diageo Plc, Molson Coors Beverage Company, Heineken Holding N.V., D.G. Yuengling & Son, Constellation Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beer Market Strategic Shifts & Innovations
Technology convergence and regulatory recalibration are compressing traditional production timelines while reshaping how producers engage directly with end consumers outside conventional three-tier structures.
Precision fermentation is collapsing the cost structure of specialty enzyme and yeast strain development. Regional craft breweries adopting biosynthesized hop extracts and designer yeast cultures reduce raw material dependence while accelerating flavor profile experimentation. This biotechnology adoption is collapsing the historical advantage of scale economies in aroma compound production, enabling smaller operators to rival multinational portfolios in sensory complexity.
The Alcohol and Tobacco Tax and Trade Bureau's updated allergen and ingredient disclosure mandates are forcing reformulation investments across flavored malt beverage lines. Producers must now submit expanded formula documentation and revised label artwork that extends approval timelines. Above-premium and craft-adjacent portfolios face disproportionate compliance burden given their higher ingredient complexity and seasonal rotation frequency.
Consumer procurement patterns favoring experiential consumption over packaged goods are redirecting volume toward on-premise brewery hospitality. Taproom visitation and membership subscription models displace supermarket and convenience store purchasing among high-value demographic segments. This channel rotation is most pronounced in California and Texas metropolitan clusters where brewery density supports destination visitation behavior.
North America Beer Market Segmentation
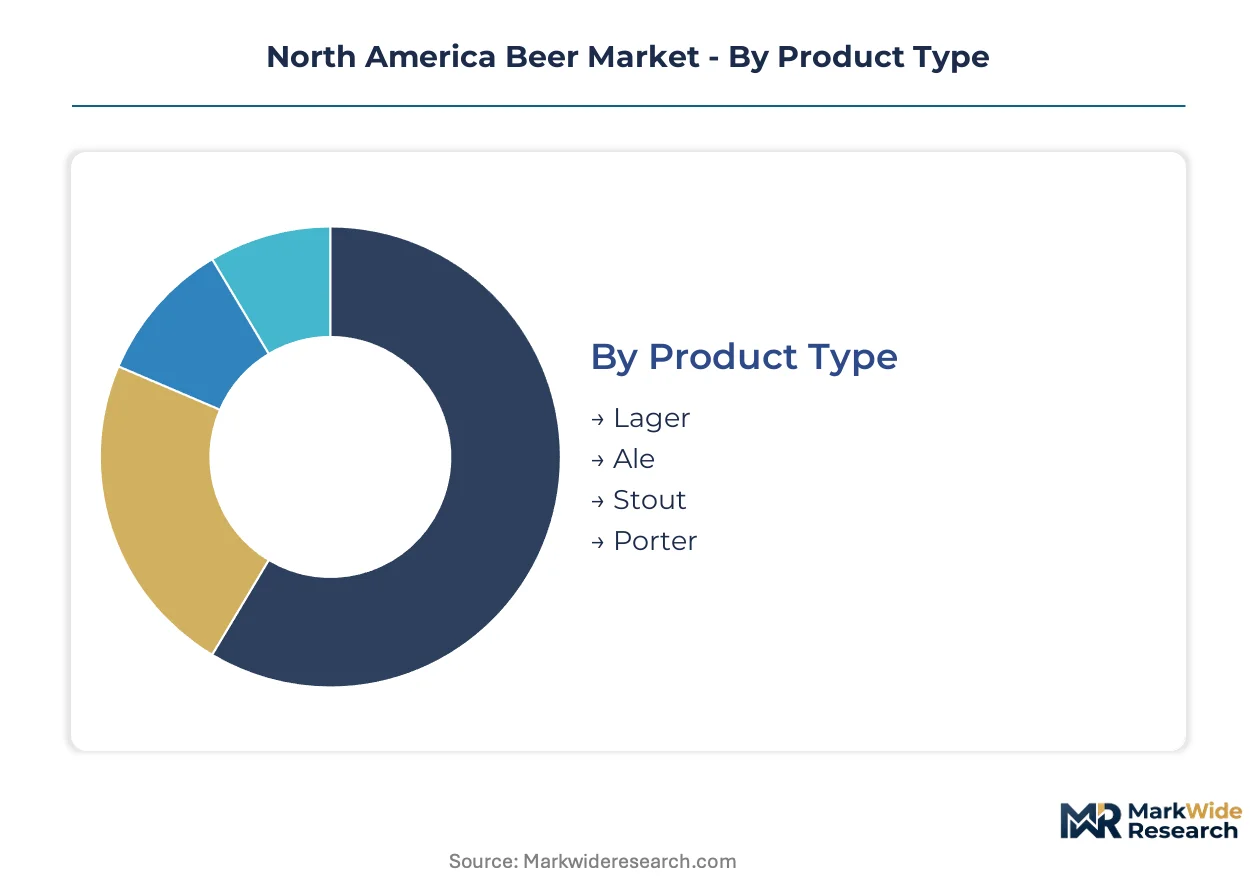
Segmentation in the North America Beer Market reveals how consumption occasions, channel economics, and demographic targeting fragment what appears as a homogeneous commodity category. Understanding these divisions exposes where margin pools concentrate and which innovation vectors command disproportionate investment returns.
Product Type:
Lager cycles through inventory fastest due to mainstream volume and refrigerated shelf-life constraints, while ale and specialty styles turn more slowly but yield higher per-unit economics.
- Lager:Bottom-fermented at cooler temperatures producing crisp, clean flavor profiles with extended shelf stability. Demand concentrates in Texas and California metropolitan clusters where mainstream accessibility drives repeat purchase velocity, though TTB labeling modernization is compressing formulation timelines for flavored lager extensions.
- Ale:Top-fermented at warmer temperatures enabling complex ester production and indigenous yeast experimentation. Regional craft operators in the Pacific Northwest and New England leverage heritage barley varieties and locally cultivated hops to command terroir-driven price premiums, though brewmaster talent scarcity constrains scaling consistency.
- Stout:Dark roasted malt character with higher alcohol tolerance and extended aging potential. Seasonal rotation frequency accelerates in winter months across Great Lakes and Northeast markets.
- Porter:Historical English style with chocolate and coffee notes from crystal and black malt additions. Limited-release portfolios in Colorado and Oregon drive niche demand among enthusiast segments.
Lager anchors the volume base while ale gains share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply between high-velocity mass retail and experience-driven on-premise venues where per-visit revenue multipliers justify capital intensity.
- Supermarkets:Temperature-controlled retail space commanding slotting fees and promotional calendar coordination. California and Texas three-tier distribution mandates inflate go-to-market costs for emerging producers seeking shelf placement.
- Convenience Stores:Impulse-driven cold-box purchasing with limited SKU breadth and rapid inventory turns. Single-serve can formats dominate in highway-adjacent locations.
- Bars:Draft systems and line-cleaning protocols create switching costs that entrench established distributors. Taproom visitation in Austin and San Diego displaces packaged goods purchasing among high-value demographics.
- Online:Direct-to-consumer shipping platforms capturing margin pools previously surrendered to licensed intermediaries. State-level law reforms enable brewery-owned e-commerce channels to accelerate growth.
Supermarkets and convenience stores control the volume foundation while online channels expand most quickly.
Customer Type:
Demographic targeting determines formulation complexity, with professionals and enthusiasts driving premium-migration while casual segments sustain mass-market lager economics.
- Young Adults:Flavor-forward preferences and social occasion orientation. Hard seltzer adjacencies and flavored malt beverage extensions capture consumption moments previously owned by spirits.
- Professionals:Premium craft beer consumption gaining momentum with above-premium portfolio concentration. Membership subscription models and limited-release access programs deepen engagement.
- Sports Fans:Stadium and arena concession economics favor high-volume, low-complexity offerings with rapid pour speeds.
- Casual Drinkers:Price-sensitive repeat purchase behavior anchored by brand recognition and distribution ubiquity.
Casual drinkers sustain the volume base while professionals drive the steepest premium-migration trajectory.
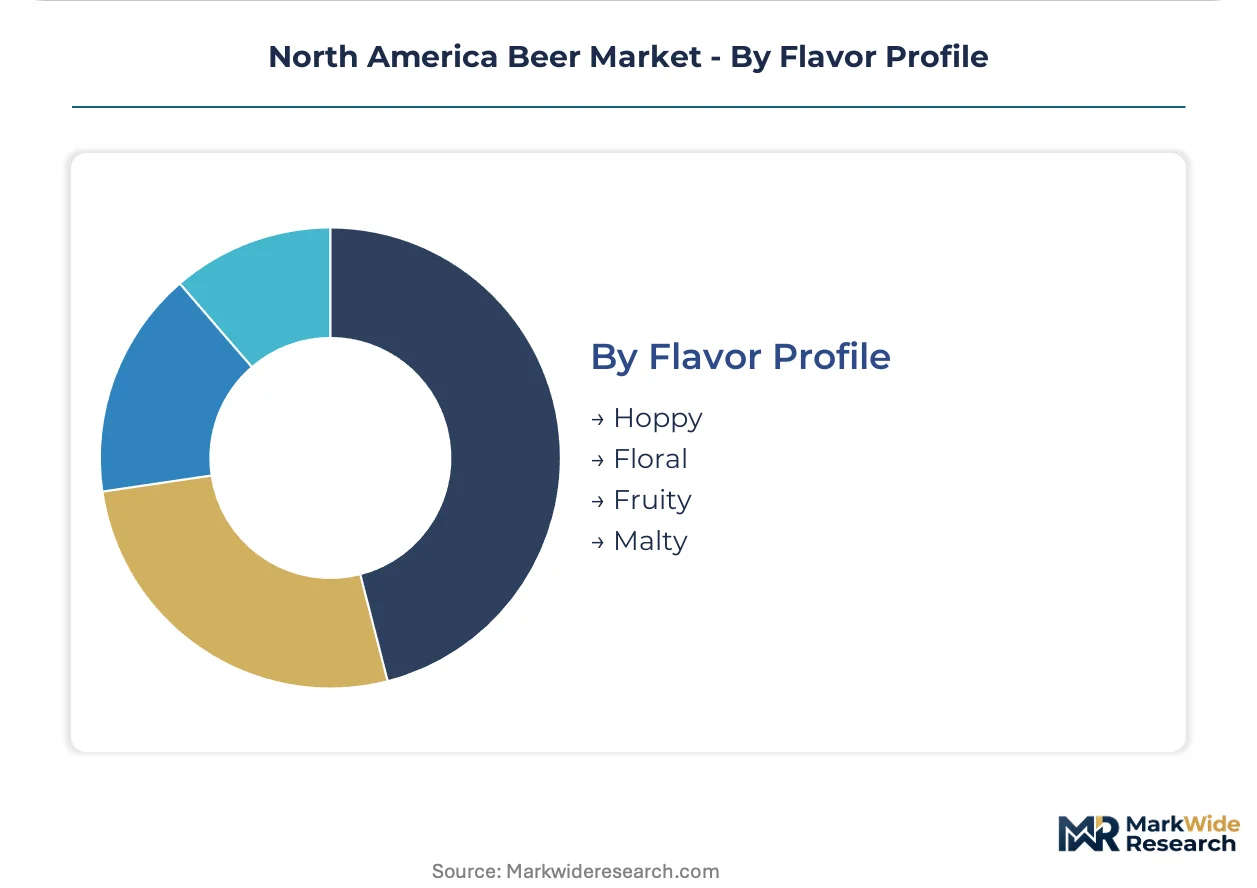
Flavor Profile:
Ingredient complexity stratifies production economics, with hop-forward formulations requiring specialized sourcing and extended TTB approval timelines.
- Hoppy:Elevated IBU levels from multiple hop additions demanding cold-chain integrity and rapid consumption windows. Pacific Northwest hop farms supply concentrated aroma compounds.
- Floral:Noble hop varieties and botanical adjuncts requiring precise fermentation control. European import dependency creates tariff exposure.
- Fruity:Yeast-derived esters or adjunct additions triggering expanded allergen disclosure mandates. Reformulation investments extend approval timelines under updated TTB standards.
- Malty:Caramel and toasted grain character from specialty malt bills. Northern Great Plains barley concentration exposes brewers to weather-driven input volatility.
Malty profiles anchor traditional volume while hoppy formulations climb the fastest among craft-adjacent portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas metropolitan clusters while Canadian provincial liquor boards enforce tighter margin compression through centralized procurement mandates.
United States
Professional demographic premium-migration and craft taproom density drive demand concentration in Austin, San Diego, and Portland metro areas. The Alcohol and Tobacco Tax and Trade Bureau enforces updated allergen disclosure standards that extend formulation approval timelines. California's three-tier distribution reforms enable direct-to-consumer shipping channels that capture margin pools previously surrendered to licensed intermediaries.
Canada
Provincial liquor board monopsony purchasing and cannabis-alcohol substitution patterns reshape consumption occasions in Toronto and Vancouver. Health Canada mandates parallel packaging standards and advertising restrictions that filter cross-border portfolio standardization. Quebec's SAQ centralized procurement constrains pricing autonomy for above-premium imports while Ontario's LCBO expansion into experiential retail redirects volume toward hospitality-integrated venues.
Mexico
Tourism corridor demand and cross-border supply chain integration anchor production decisions in Baja California and Mexico City metro clusters. Federal economic competition authority monitors concentration levels among brewing assets while state-level excise structures vary across jurisdictions. Nuevo León's industrial brewing infrastructure supports efficient capacity allocation for North American export commitments.
North America Beer Market Key Industry Players
Vertically integrated multinationals and regional craft specialists split the market between mass-market scale economies and terroir-driven premium positioning. Consolidation pressure intensifies as distributor exclusivity fragments in key metropolitan markets. Two archetypes dominate: cost-disciplined volume producers leveraging captive logistics networks, and experience-focused taproom operators monetizing direct consumer relationships. Competitive moves concentrate on cross-border portfolio optimization and brewery-owned hospitality venue expansion.
Within the multinational tier, Anheuser-Busch InBev and Molson Coors Beverage Company exemplify cost-disciplined scale positioning through integrated brewing and distribution infrastructure. Boston Beer Company occupies a craft-adjacent position representing flavored malt beverage innovation beyond traditional beer occasions. These three entities anchor the competitive structure while D.G. Yuengling & Son represents regional heritage positioning that commands loyalty in Eastern US markets.
| Leading Market Players |
|---|
| Boston Beer Company |
| Carlsberg Group |
| Anheuser-Busch InBev |
| Asahi Group Holdings |
| Diageo Plc |
| Molson Coors Beverage Company |
| Heineken Holding N.V. |
| D.G. Yuengling & Son |
| Constellation Brands |
| Others |
Cost & Logistics Intelligence
Commodity barley volatility in the northern Great Plains determines both the premium-mass pricing spread and supply chain configuration across North American brewing. Weather-driven input shocks compress margins on standard lager while amplifying terroir-driven price premiums for heritage grain formulations.
Pricing Analysis
The customization-premium spread between limited-release craft portfolios and mass-market lager anchors pricing architecture across the North America Beer Market. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient complexity, with hop-forward formulations commanding spreads based on Pacific Northwest aroma compound sourcing. Pricing pressure stems from cannabis-alcohol substitution diverting discretionary spending among younger demographics. Casual drinkers exhibit highest price sensitivity, while professionals purchasing through membership subscription models show lowest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration among legacy multinationals with captive malting facilities and independent craft operators with third-party canning lines shapes production flexibility. Barley sourcing draws from the northern Great Plains, hop cultivation clusters in Washington and Idaho, and malt processing in Wisconsin and Colorado. Single-source vulnerability concentrates in heritage barley varieties with limited seed stock. Distribution runs through licensed three-tier intermediaries in most US jurisdictions, though direct-to-consumer shipping reforms in California and Texas fragment this structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as brewery-owned taproom ecosystems displace traditional distributor-controlled access, with interoperability between hospitality software and e-commerce channels enabling direct consumer relationship monetization.
For Market Incumbents: Entrench distributor relationships in Texas and California metropolitan clusters where three-tier fragmentation threatens exclusivity. Invest in backward integration into heritage barley seed programs to secure terroir-driven supply differentiation against craft entrants. Prioritize ERP reconfiguration to accommodate small-batch SKU proliferation without sacrificing cost discipline on mass-market lager lines.
For New Entrants and Emerging Players: Build out direct-to-consumer shipping capabilities in states with liberalized brewery-owned e-commerce channels, particularly Texas and California. Target the above-premium flavored malt beverage segment where TTB formula modernization accelerates approval timelines relative to traditional beer. Pursue taproom-first go-to-market strategies that capture per-visit revenue multipliers through food service integration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors craft-adjacent portfolios with established taproom footprints and scalable brewing infrastructure. Long-term viability hinges on access to licensed distribution in three-tier constrained jurisdictions and proprietary yeast strain libraries. Monitor state-level direct-shipping liberalization as the primary inflection signal for next-generation distribution investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Taproom Experience Expansion | Brewery-owned hospitality venues in Austin and San Diego capture margin pools previously surrendered to bars. |
| Heritage Ingredient Sourcing | Proprietary barley variety contracts with northern Great Plains growers command terroir-driven price premiums. |
| Direct-to-Consumer Platform Launch | E-commerce channels in California and Texas bypass three-tier intermediaries to deepen consumer relationships. |
| Flavored Malt Beverage Innovation | Hard seltzer extensions beyond traditional beer occasions compete with spirits for younger demographic occasions. |
| Cross-Border Production Harmonization | Integrated US-Canadian brewing capacity reduces tariff exposure and optimizes allocation across demand clusters. |
Research Approach
A spread of perspectives from brewing operations directors, three-tier distributor principals, TTB regulatory affairs specialists, and craft brewery founders converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of publicly traded beverage companies, Alcohol and Tobacco Tax and Trade Bureau formula approval databases, and state-level liquor board procurement records. Bottom-up volume modeling from individual brewery capacity and top-down category spend analysis triangulated on segment-level estimates.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with consumption occasion shifts and channel rotation dynamics modeled explicitly. Segmentation dimensions included product type, distribution channel, customer archetype, and flavor profile complexity. CAGRs were derived from iterative reconciliation of historical volume trends and forward-looking capacity announcements. Industry-specific inputs incorporated barley harvest forecasts from USDA crop reports and hop acreage data from the Hop Growers of America.
Stress conditions across input commodity volatility, regulatory approval timeline extensions, and cannabis-alcohol substitution intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding state-level shipping law trajectories and three-tier structural persistence. Quarterly review of TTB formula approval backlogs, provincial liquor board procurement policy shifts, and craft brewery taproom visitation indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Wine Chocolate Market