
 Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market | 2026-2036
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market Outlook
Mixology-trained production labor is rotating from on-premise bartending into contract manufacturing facilities as canning lines scale across North America and Europe. Diageo plc leverages its captive spirits supply to control ingredient costs across multiple RTD brands. Bacardi Limited anchors its portfolio in rum-based premixes with established Caribbean sourcing networks. Brown-Forman competes through whiskey-flavored RTD extensions that draw on aged stock reserves.
Alcoholic ready-to-drink beverages and high-strength premixes are pre-formulated, shelf-stable blends of distilled spirits or fermented bases with carbonated or still mixers, typically packaged in aluminum cans with alcohol-by-volume ranging from four percent to twelve percent depending on jurisdiction. These products serve commercial and retail channels seeking portion-controlled, consistent-quality alternatives to freshly mixed cocktails. Hard seltzers dominate volume throughput in North America while cocktails capture premium shelf positioning in European grocery retail. Citrus flavor profiles sustain the broadest demographic appeal, though herbal formulations are gaining traction in on-trade placements seeking differentiation.
The FDA governs ingredient safety and labeling accuracy for alcohol-adjacent products in the United States, while TTB permitting controls interstate commerce and formula approval for malt-based and distilled-spirit RTDs. EMA-adjacent national regulators across Europe enforce varying maximum ABV thresholds and marketing restrictions that fragment product portability across borders. Stakeholders must monitor evolving excise tax structures and single-use packaging mandates that threaten aluminum can economics while evaluating localized formulation adjustments for compliance.
Market Dynamics
Aluminum can supply concentration and TTB formula approval bottlenecks are compressing production timelines for new RTD entrants, forcing brands to secure multi-year canning contracts before securing distribution.
Growth Catalysts
- Music festival channel expansion:Young adult consumers at live events in the United States and United Kingdom are normalizing canned cocktails as default beverage choices, creating habitual purchase patterns that transfer to retail.
- TTB streamlined malt-base pathways:The Alcohol and Tobacco Tax and Trade Bureau's expedited review process for malt-derived RTDs is accelerating product-to-shelf cycles versus distilled-spirit equivalents.
- Carbonation technology maturation:Precision in-line carbonation systems are enabling consistent mouthfeel across production batches, reducing quality variance that previously limited geographic expansion.
Market Restraints
- Aluminum input cost volatility:Primary aluminum smelter capacity concentration in China and Russia exposes can manufacturers to tariff-driven price swings that compress RTD margin structures.
- EMA ABV threshold fragmentation:European Medicines Agency-adjacent national regulators enforce divergent maximum alcohol-by-volume limits that prevent standardized European formulations.
- Fresh cocktail substitution threat:On-premise venues with mixology-trained labor can undercut canned premium positioning through customizable ingredient combinations.
Strategic Opportunities
- India urban convenience retail:FSSAI regulatory modernization and organized retail expansion in Mumbai and Bangalore create first-mover positioning for imported RTD portfolios.
- CBD-spirit convergence:Cannabidiol infusion technologies are opening functional beverage positioning where local regulations permit, differentiating from conventional intoxication-only products.
- DTC subscription channels:Direct-to-consumer platforms bypass three-tier distribution constraints in the United States, enabling flavor experimentation without slotting fee burdens.
Industry Challenges
- Canning line technician scarcity:Mixology-trained labor migration into manufacturing has not kept pace with line automation complexity, creating maintenance bottleneck risks.
- TTB formula resubmission cycles:Ingredient sourcing changes trigger mandatory re-approval processes that delay reformulation responses to consumer preference shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market |
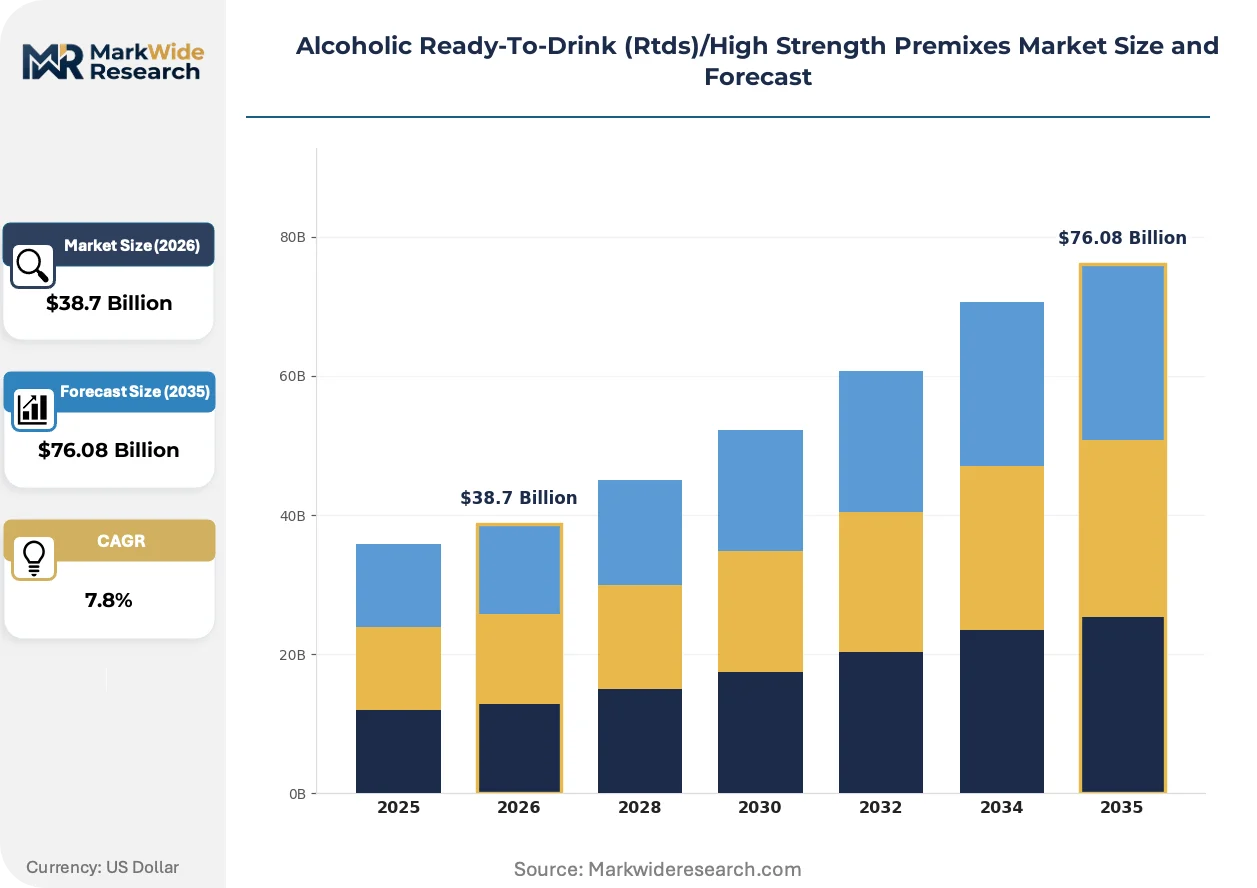
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocktails, Hard Seltzers, Spritzers, Highballs Flavor Profile: Citrus, Berry, Herbal, Spicy Packaging Type: Can, Bottle, Tetra Pak, Keg Alcohol Content: Low, Moderate, High, Very High |
| Companies Covered | Diageo plc, Bacardi Limited, Brown-Forman, Anheuser-Busch InBev, Molson Coors Beverage Company, Campari Group, Asahi Group Holdings, Pernod Ricard, Constellation Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market Strategic Shifts
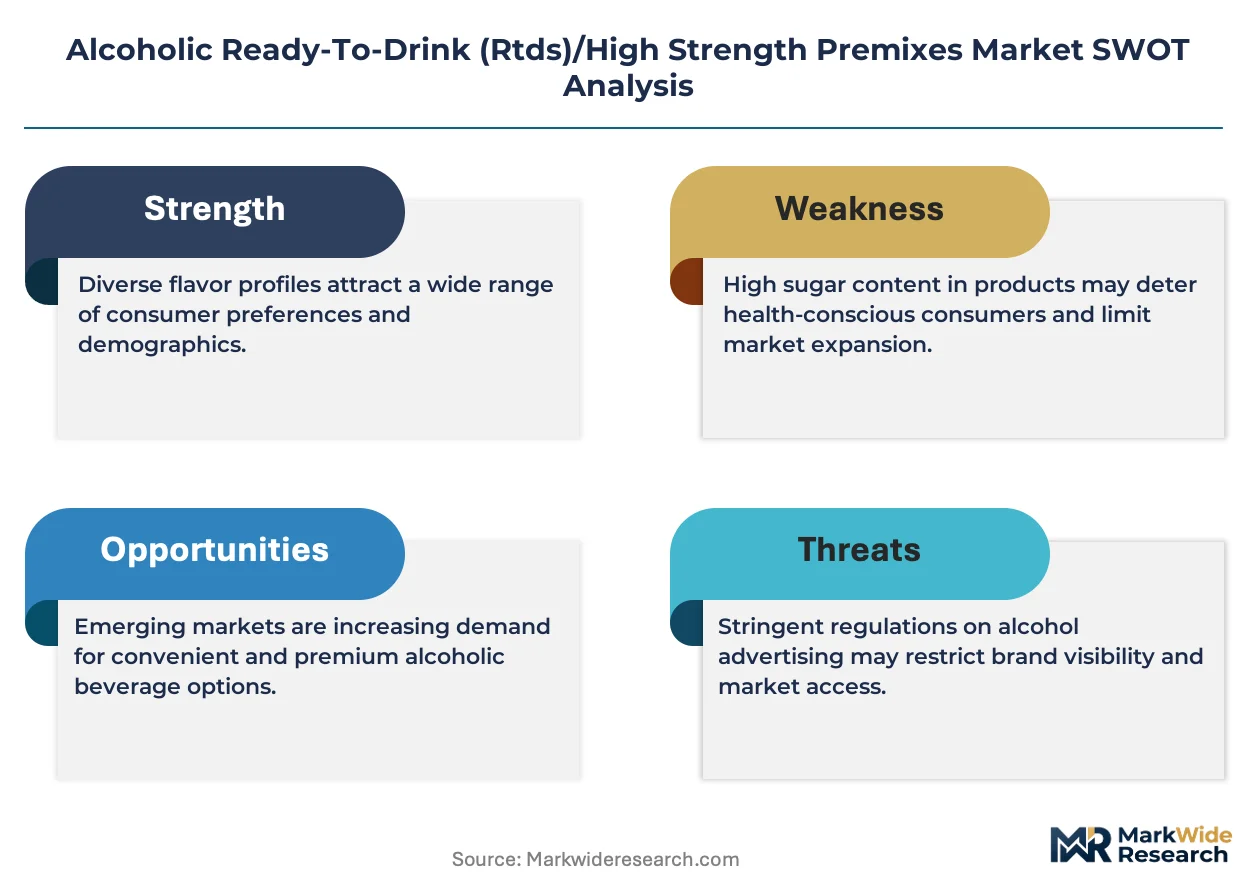
Reformulation around lower-sugar profiles and functional ingredients is displacing legacy flavor systems, while packaging sustainability mandates and channel-specific ABV optimization are reshaping production priorities across the category.
Precision fermentation-derived flavor compounds are fragmenting traditional citrus and berry sourcing models. Contract manufacturers in the United States and Germany are adopting biosynthetic terpene production to reduce agricultural supply dependency. This biotechnology is fragmenting established flavor house relationships and enabling rapid seasonal rotation without procurement lead times.
The FDA's updated Nutrition Facts labeling requirements for alcohol-adjacent products are forcing ingredient disclosure granularity that exposes proprietary formulations. TTB parallel mandates on allergen cross-contamination are requiring production line segregation investments. Malt-based RTDs face the steepest compliance cost escalation due to shared facility requirements with traditional beer production.
Festival-goers and sporting venue attendees are consolidating purchase decisions around single-serve portability and consistent ABV predictability. Convenience stores in the United States are responding with refrigerated RTD-dedicated sections that displace traditional beer cooler space. This behavioral pivot is most pronounced in Texas and Florida, where extended outdoor event seasons sustain year-round category visibility.
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market Segmentation
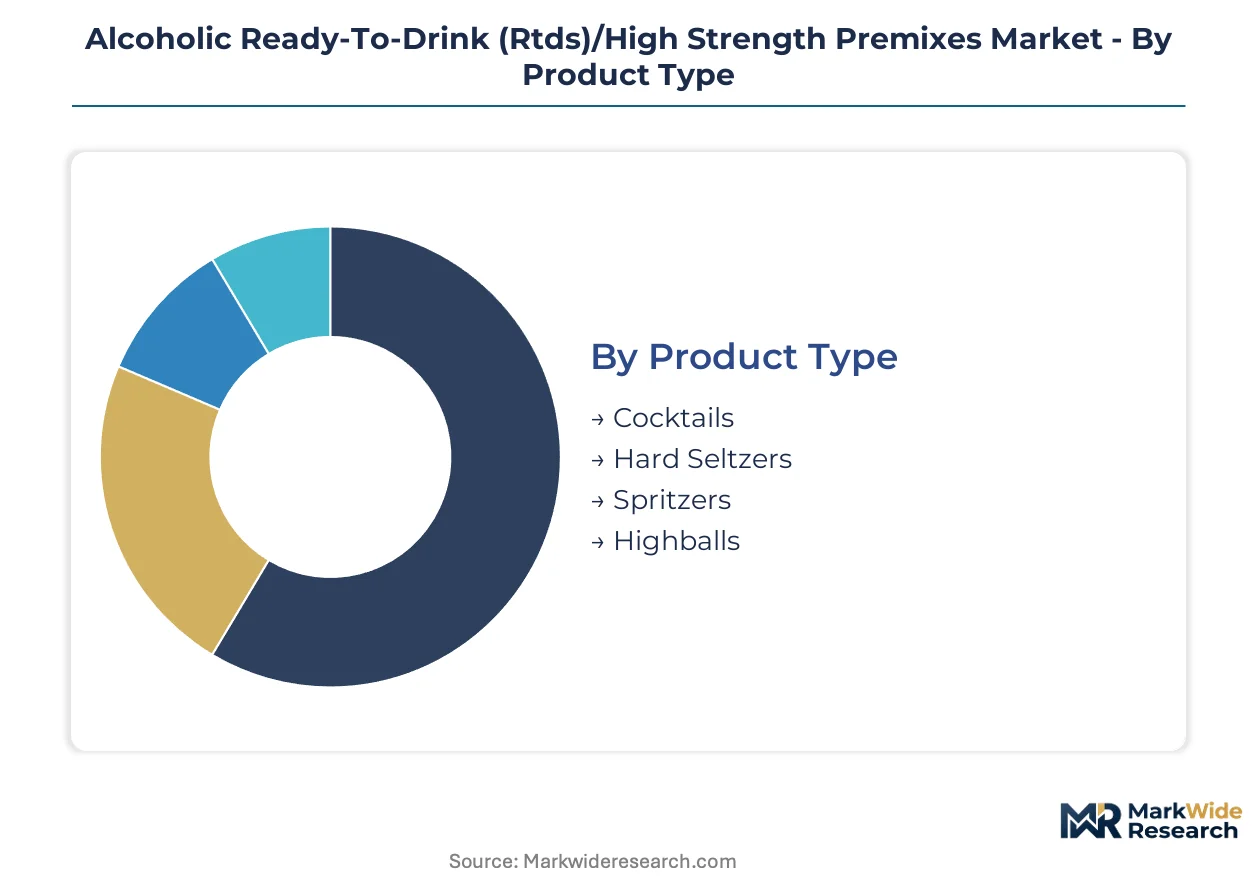
RTD manufacturers face divergent substitution threats across product architectures. Flavor systems and packaging formats determine channel access and margin capture in ways that reshape competitive boundaries.
Product Type:
Hard seltzers and cocktails face the sharpest fresh-mix substitution pressure from on-premise venues with trained bartending labor.
- Cocktails:Pre-formulated spirit-mixer blends with ABV precision matching hand-mixed equivalents. Demand concentrates in European grocery retail where premium shelf positioning offsets per-unit cost premiums versus bar service.
- Hard Seltzers:Fermented sugar bases with fruit flavoring and aggressive carbonation. United States convenience-store channel expansion drives volume throughput as refrigerated dedicated sections displace traditional beer cooler space.
- Spritzers:Wine-based carbonated blends targeting daytime consumption occasions.
- Highballs:Whiskey or rum with soda water emphasizing simplicity over complexity.
Hard seltzers anchor the volume base while cocktails gain share at the steepest rate.
Flavor Profile:
Citrus and berry formulations concentrate procurement spend on agricultural supply chains vulnerable to climate volatility.
- Citrus:Lemon, lime, and grapefruit terpene formulations sustaining the broadest demographic appeal across age cohorts. Texas and Florida outdoor event seasons normalize habitual purchase patterns that transfer to retail.
- Berry:Raspberry, blackberry, and mixed berry profiles capturing seasonal rotation cycles. Biosynthetic terpene production in United States and German contract manufacturing facilities reduces procurement lead times.
- Herbal:Botanical infusions targeting differentiation in on-trade placements.
- Spicy:Chili and ginger formulations appealing to experimental consumer segments.
Citrus anchors the volume base while herbal gains share most quickly through on-trade differentiation.
Packaging Type:
Can and bottle formats diverge sharply in aluminum input cost exposure and TTB labeling compliance burden.
- Can:Aluminum single-serve containers with superior portability for festival and sporting venue channels. Supply concentration in Chinese and Russian primary smelter capacity exposes manufacturers to tariff-driven price swings.
- Bottle:Glass containers with established recycling infrastructure. European grocery retail maintains preference for premium cocktail presentation in transparent packaging.
- Tetra Pak:Aseptic cartons for ambient distribution in emerging market retail.
- Keg:Stainless steel returnable vessels for on-premise draft service.
Can anchors the volume base while Tetra Pak climbs the fastest in ambient distribution expansion.
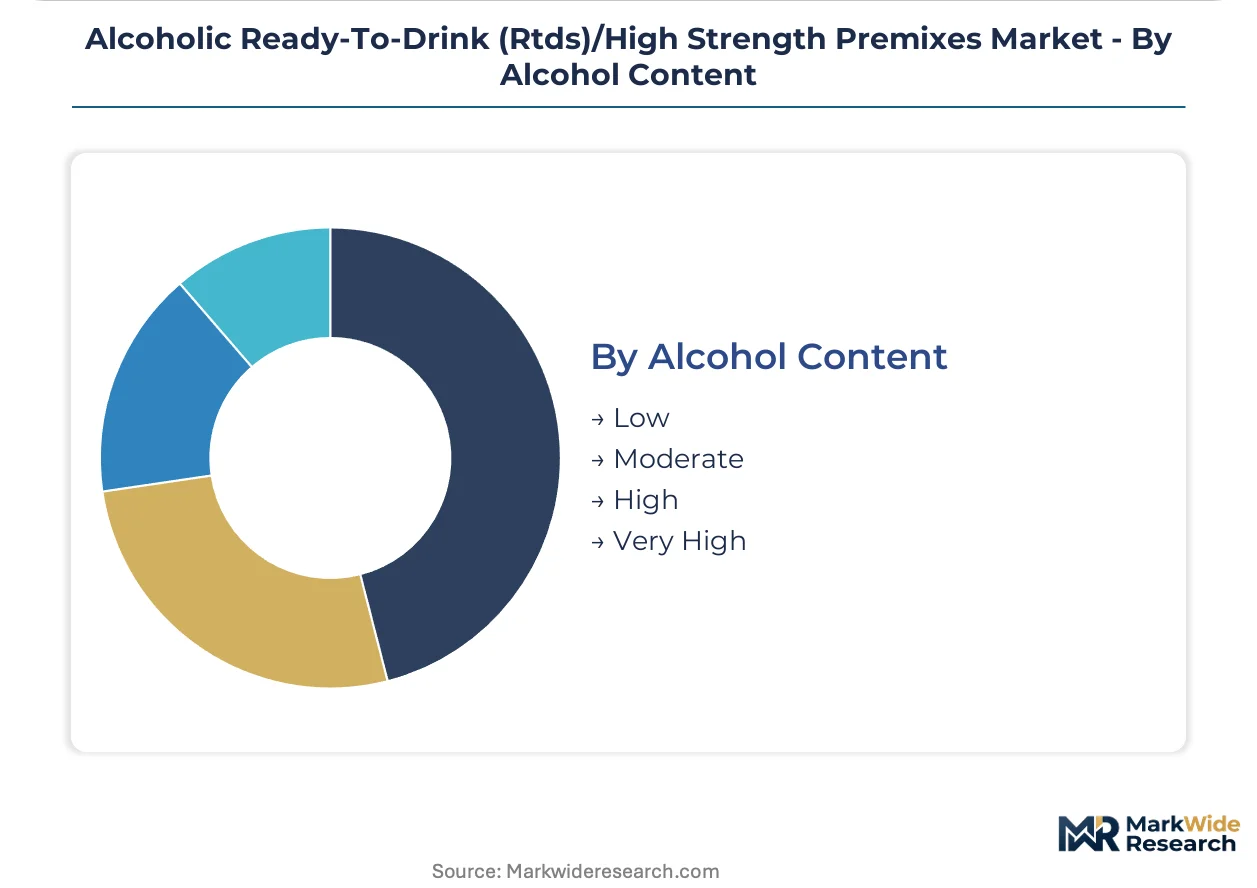
Alcohol Content:
Moderate and high ABV tiers fragment across EMA-adjacent national regulators enforcing divergent maximum thresholds.
- Moderate:Four to eight percent ABV formulations optimizing for malt-base TTB streamlined approval pathways. Malt-derived RTDs accelerate product-to-shelf cycles versus distilled-spirit equivalents in United States interstate commerce.
- High:Eight to twelve percent ABV capturing premium positioning. European Medicines Agency-adjacent national regulators prevent standardized formulations across borders.
- Low:Below four percent ABV targeting session drinking occasions.
- Very High:Above twelve percent ABV facing distribution restrictions in multiple jurisdictions.
Moderate ABV anchors the volume base while high ABV expands most quickly in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns fragment sharply across geographies. United States buyers prioritize convenience-store portability and festival accessibility. European purchasers favor premium grocery positioning with transparent ingredient disclosure. Emerging market adoption concentrates in urban convenience retail with localized flavor adaptation.
United States
Music festival channel expansion and sporting venue penetration drive habitual purchase formation among young adult demographics. TTB streamlined malt-base approval pathways accelerate product-to-shelf cycles versus distilled-spirit equivalents. Texas and Florida sustain year-round category visibility through extended outdoor event seasons with refrigerated RTD-dedicated cooler sections displacing traditional beer space.
Germany
Precision fermentation-derived flavor compound adoption reduces agricultural supply dependency for contract manufacturing facilities. EMA-adjacent national ABV threshold enforcement prevents standardized European formulations across borders. Bavarian production clusters integrate biosynthetic terpene systems enabling rapid seasonal rotation without procurement lead times.
United Kingdom
Live event normalization of canned cocktails transfers habitual purchase patterns into grocery retail channels. National marketing restrictions on alcohol advertising constrain brand building through traditional media. London metropolitan convenience retail expansion creates premium shelf positioning opportunities for imported cocktail portfolios.
India
FSSAI regulatory modernization and organized retail expansion in Mumbai and Bangalore enable first-mover positioning for imported RTD portfolios. Central excise structures and state-level distribution licensing create compliance complexity for interstate commerce. Maharashtra and Karnataka urban clusters concentrate organized modern trade development with ambient distribution infrastructure scaling.
Japan
Highball culture sustains whiskey-soda premix demand through convenience store and izakaya channels. METI packaging sustainability mandates pressure aluminum can economics while driving material innovation. Tokyo-Osaka metropolitan corridors concentrate premium positioning experimentation with lower-ABV session formulations.
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier with divergent sourcing and channel strategies. The upper tier controls captive spirits supply and canning line capacity through multi-year contracts. Specialist competitors concentrate on flavor innovation velocity and regional distribution partnerships. Dominant competitive moves include securing aluminum supply agreements ahead of tariff-driven price swings and acquiring regional flavor houses to accelerate formulation pipelines.
Among integrated multinational beverage corporations, Diageo plc, Bacardi Limited, and Brown-Forman occupy distinct archetype positions. Diageo exemplifies the captive supply model with spirits integration spanning multiple RTD brand architectures. Bacardi anchors rum-based premix specialization with Caribbean sourcing network leverage. Brown-Forman represents whiskey-flavored extension strategies drawing on aged stock reserves for premium positioning.
| Leading Market Players |
|---|
| Diageo plc |
| Bacardi Limited |
| Brown-Forman |
| Anheuser-Busch InBev |
| Molson Coors Beverage Company |
| Campari Group |
| Asahi Group Holdings |
| Pernod Ricard |
| Constellation Brands |
| Others |
Value Chain & Pricing Dynamics
Multi-year canning contracts with take-or-pay provisions lock in aluminum supply access and price visibility for RTD manufacturers navigating tariff exposure on Chinese and Russian primary smelter output. These arrangements compress margin flexibility while insulating brands from spot-market volatility in container input costs.
Pricing Analysis
Long-term offtake agreements dominate pricing structure for aluminum can inputs, with three-tier pricing separating premium cocktail formulations from standard malt-base RTDs and economy hard seltzer tiers. Price differentiation rests on ABV precision, flavor complexity, and brand heritage rather than commodity positioning. Pricing pressure stems from aluminum tariff exposure and TTB formula resubmission costs that delay reformulation responses. Convenience-store channel buyers exhibit highest price sensitivity, while festival and sporting venue purchasers prioritize portability over per-unit cost.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for aluminum sheet and can-end components sourced from Chinese and Russian primary smelters. Supply concentrates in China, Russia, and domestic North American rolling mills for aluminum inputs, while precision fermentation-derived flavor compounds draw from German and United States biotechnology facilities. Raw material dependencies span agricultural citrus terpenes, biosynthetic flavor compounds, and malt-derived alcohol bases. Single-source vulnerability in Chinese smelter capacity exposes manufacturers to tariff-driven price swings. Distribution runs through three-tier wholesale networks in the United States and direct-to-retail arrangements in European grocery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across flavor innovation velocity and channel-specific ABV optimization as consumer occasions splinter beyond traditional beer and wine occasions. Demand-side shift toward music festival and sporting venue consumption creates niche positioning for single-serve portability specialists.
For Market Incumbents: Consolidate aluminum supply agreements ahead of tariff escalation cycles and acquire regional flavor houses to accelerate biosynthetic terpene pipelines. Captive spirits integration defends against contract manufacturing margin compression. Channel control through refrigerated cooler space allocation in Texas and Florida convenience stores reinforces habitual purchase formation. For New Entrants and Emerging Players: Anchor in India urban convenience retail in Mumbai and Bangalore where FSSAI regulatory modernization enables first-mover positioning for imported portfolios. White-space targets include CBD-spirit convergence where local regulations permit functional differentiation, and direct-to-consumer subscription channels that bypass three-tier distribution constraints. Go-to-market angle should emphasize flavor experimentation velocity without slotting fee burdens. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing specialists with precision fermentation capabilities and multi-year canning line contracts. Long-term viability across the projection horizon favors biotechnology-enabled flavor houses over agricultural-dependent sourcing models. Signal to watch: TTB approval cycle times for malt-base versus distilled-spirit pathways as indicator of competitive access speed.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Supply Agreement Securement | Multi-year contracts with Chinese and Russian smelter exposure mitigation insulate margin structures from tariff volatility. |
| Precision Fermentation Capability Acquisition | Biosynthetic terpene production in German and United States facilities reduces agricultural supply dependency and procurement lead times. |
| Direct-to-Consumer Channel Launch | Bypassing three-tier distribution constraints enables flavor experimentation without slotting fee burdens in United States interstate commerce. |
| CBD-Spirit Convergence Product Development | Functional beverage positioning differentiates from intoxication-only products where local regulations permit cannabidiol infusion. |
| India Market Entry Partnership | FSSAI regulatory modernization and organized retail expansion in Mumbai and Bangalore create first-mover positioning for imported portfolios. |
Study Parameters
Desk research of TTB formula approval databases, FDA labeling guidance documents, and aluminum trade flow customs data preceded structured interviews with contract manufacturing facility managers, flavor house R&D directors, convenience store category buyers, and festival venue beverage procurement leads. Primary fieldwork combined with secondary validation across Nielsen retail audit data, SEC beverage company filings, and EMA-adjacent national regulatory filings. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, flavor profile, packaging format, alcohol content tier, and distribution channel dimensions structured the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate synthesis weighted by base-year volume contributions. Industry-specific forecast inputs included TTB approval cycle time projections and aluminum tariff scenario modeling.
Decision-makers should treat outputs as directional under assumptions of continued TTB malt-base pathway streamlining and stable aluminum tariff structures; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include EMA ABV threshold harmonization failure, single-use packaging mandate escalation, and fresh cocktail substitution acceleration in on-premise channels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Vermouth Market