
 Asia Pacific Wine Coolers Market | 2026-2036
Asia Pacific Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wine Coolers Market Insights
A capital-intensity divergence between high-volume OEMs and precision-engineering specialists is reorganizing competitive dynamics across the Asia Pacific wine coolers landscape. Haier Group Corporation leverages its integrated compressor manufacturing base in Qingdao to control input costs across freestanding and built-in lines. Midea Group anchors its position through mass-market thermoelectric units distributed through e-commerce channels in Southeast Asia. Electrolux competes on design-led premium positioning, sustaining margin pools in dual-zone and countertop segments targeted at affluent households in Singapore and Hong Kong.
Asia Pacific wine coolers are climate-controlled appliances engineered to maintain precise temperature bands between 5°C and 18°C, utilizing vapor-compression, thermoelectric, or absorption cooling systems with UV-resistant glass doors and vibration-dampened shelving to preserve wine integrity during short-to-medium-term storage. Freestanding units dominate volume shipments due to lower installation barriers and portability suited to rental-dense urban markets across the region, while built-in configurations command premium pricing from renovation-driven demand in Australia's luxury residential sector. Compressor-based cooling technology leads in reliability and capacity for larger collections, whereas thermoelectric systems are gaining traction in compact countertop formats where noise reduction and energy efficiency outweigh absolute cooling power.
China's SAMR enforces mandatory energy efficiency labeling under GB standards that directly shape compressor selection and insulation specifications for wine coolers sold domestically. Australia's Equipment Energy Efficiency program imposes Minimum Energy Performance Standards that filter out low-efficiency imports, while Japan's METI administers Top Runner standards that progressively tighten allowable power consumption for appliance categories including precision climate-control devices. Stakeholders must monitor how diverging national efficiency trajectories affect platform standardization and whether hybrid cooling architectures can bridge compliance gaps across multiple regulatory regimes.
Market Dynamics
China's SAMR is enforcing updated GB energy efficiency standards that compel manufacturers to redesign compressor architectures and insulation systems, compressing legacy product lines while accelerating modular platform development.
Growth Catalysts
- Dual-zone temperature control:Japan's metropolitan restaurant districts demand precise climate separation for red and white wine service, driving specification upgrades across commercial installations.
- GB 12021.2 efficiency mandates:China's appliance labeling requirements filter low-efficiency imports, creating procurement preference for redesigned compressor systems with variable-speed drives.
- Built-in renovation cycles:Australia's luxury residential sector in Sydney and Melbourne integrates wine storage into kitchen fit-outs, expanding premium configuration demand.
Market Restraints
- Copper and aluminum input volatility:Compressor coil and heat exchanger materials face commodity price swings that compress OEM margin pools.
- Thermoelectric cooling limitations:Peltier systems cannot achieve sub-10°C performance in ambient temperatures above 35°C, restricting deployment in Southeast Asian climates without climate-controlled environments.
- Australia's MEPS compliance costs:Equipment Energy Efficiency program testing and certification requirements raise fixed costs for imported units, filtering smaller manufacturers from market entry.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:E-commerce channel development for compact countertop units targets urban middle-class households with limited legacy appliance ownership.
- Hybrid cooling convergence:Vapor-compression and thermoelectric system integration enables dual-mode operation optimized for ambient temperature variation.
- Japan's METI Top Runner incentives:Premium efficiency ratings unlock preferential procurement positioning within commercial foodservice chains.
Industry Challenges
- Refrigeration engineer scarcity:Vapor-compression system design expertise concentrates in Qingdao and Guangzhou manufacturing clusters, constraining regional R&D expansion.
- Multi-jurisdiction certification timelines:Parallel GB, MEPS, and JIS compliance testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wine Coolers Market |
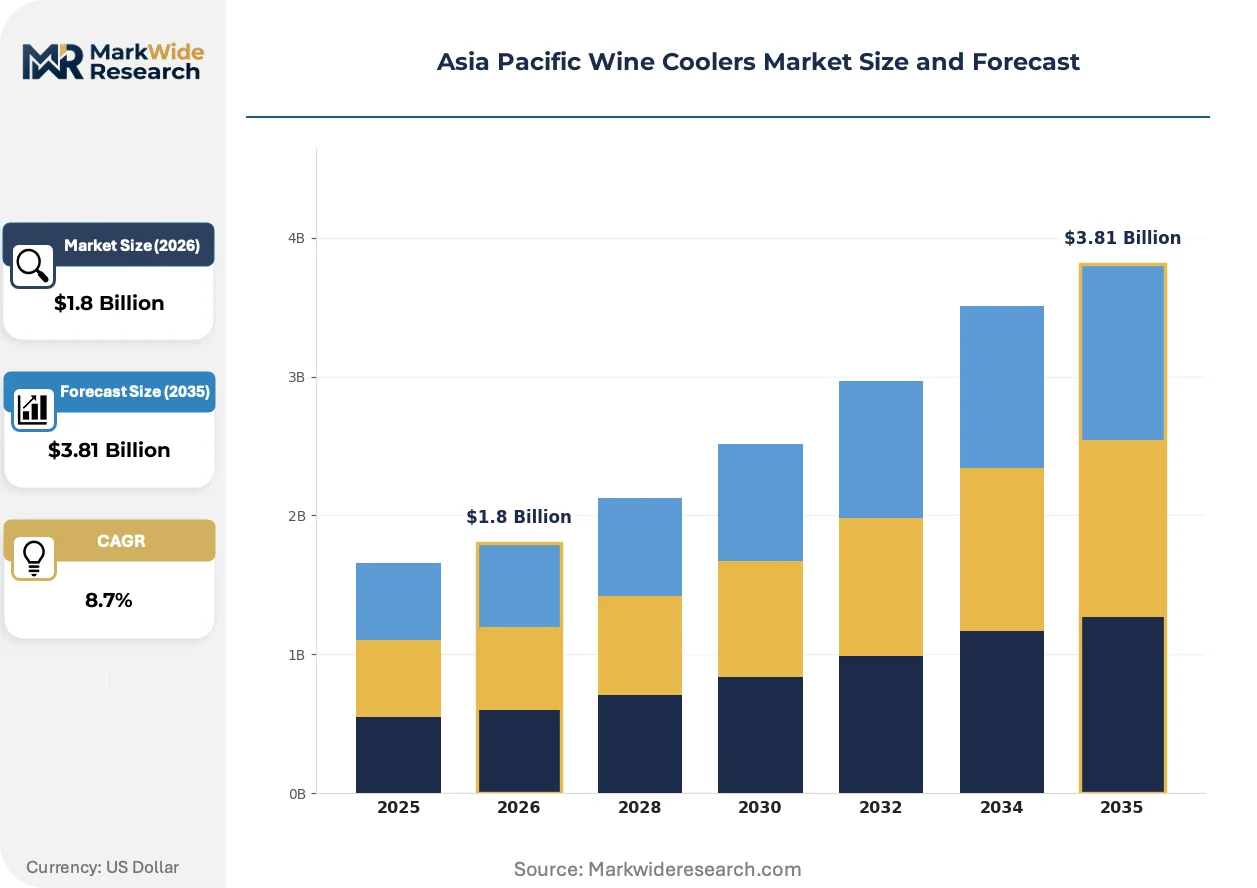
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-In, Countertop, Dual-Zone End User: Households, Restaurants, Hotels, Wine Retailers Cooling Technology: Thermoelectric, Compressor, Absorption, Hybrid Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Haier Group Corporation, Whirlpool Corporation, Midea Group, Panasonic Corporation, Samsung Electronics Co., Ltd., LG Corporation, Bosch Group, Electrolux, Arcelik A.Ş., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wine Coolers Market Trends and Innovations
Technology trajectories across the Asia Pacific wine coolers market center on thermal management precision, regulatory compliance automation, and channel-specific product configuration. These forces are compressing legacy single-zone formats while elevating connected and modular systems.
Variable-speed compressor technology is decomposing the traditional fixed-speed architecture that dominated mid-capacity residential units. Japanese commercial buyers in Tokyo and Osaka specify inverter-driven systems for vibration reduction and temperature stability. The shift is compressing price premiums between entry-level and precision-engineered product tiers.
China's SAMR GB standards revision mandates real-time energy consumption monitoring and standardized efficiency labeling, forcing platform redesigns across domestic and export-oriented manufacturers. Compressor suppliers must recalibrate displacement and refrigerant charge specifications to meet tightened coefficient of performance thresholds. Australian importers are prioritizing pre-certified platforms to avoid MEPS testing bottlenecks at port of entry.
Direct-to-installer procurement via specialized kitchen and interior design channels is displacing traditional retail distribution for built-in configurations. Singaporean and Hong Kong renovation contractors specify wine storage during early-stage project planning, bypassing appliance retail entirely. This pattern concentrates in high-rise residential developments where space optimization demands integrated solutions.
Asia Pacific Wine Coolers Market Segmentation
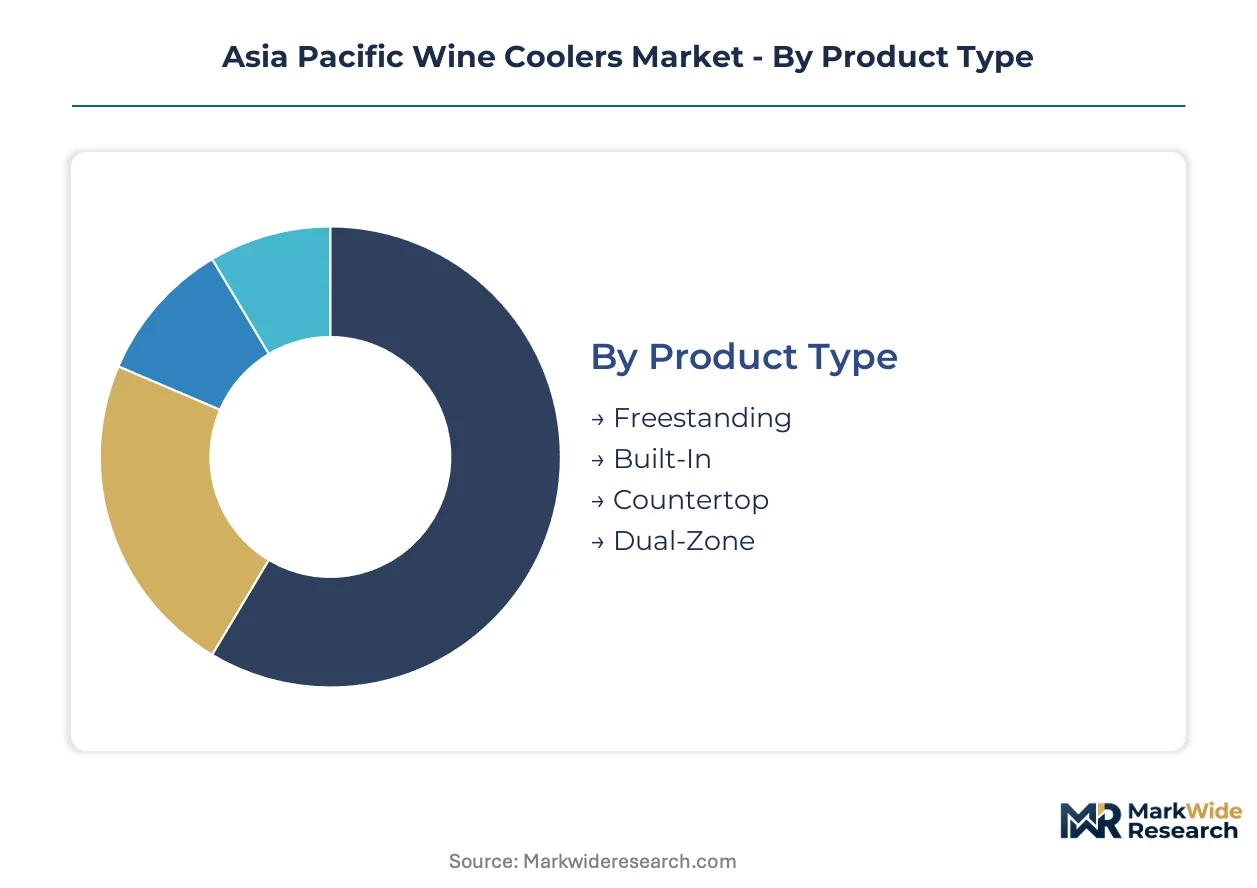
Wine cooler segmentation in the Asia Pacific region reflects divergent consumer priorities across climate zones, housing stock, and beverage consumption patterns. Product configuration and cooling architecture choices directly determine addressable market scope and margin capture potential.
Product Type:
Freestanding units face substitution pressure from multi-purpose beverage refrigerators in price-sensitive Southeast Asian markets, while built-in configurations defend their position through renovation-integrated specification.
- Freestanding:Portable floor-standing cabinets with finished exteriors designed for flexible placement in rental apartments and temporary residences. Volume concentrates in China's tier-2 cities where young professionals prioritize mobility over permanent installation, though thermoelectric limitations in humid climates constrain penetration.
- Built-In:Front-venting undercounter units engineered for seamless kitchen cabinetry integration with standardized dimensions. Australia's Sydney and Melbourne luxury residential sectors specify these during renovation cycles, with procurement shifting to direct-to-installer channels that bypass traditional retail.
- Countertop:Compact thermoelectric units occupying under 50 liters capacity for limited collection storage.
- Dual-Zone:Separated temperature compartments enabling simultaneous red and white wine service.
Freestanding anchors the volume base while dual-zone gains share at the steepest rate.
End User:
Commercial buyers command pricing power through volume procurement, while household segments fragment across income tiers and collection sophistication levels.
- Restaurants:Metropolitan dining establishments in Tokyo's Ginza and Osaka's Dotonbori districts require precise dual-zone climate separation for sommelier-driven beverage programs. Specification upgrades center on vibration-dampened shelving and UV-resistant glass to protect investment-grade inventory.
- Households:Residential consumers spanning compact urban apartments to suburban estates with dedicated cellar space. Australia's urban centers show strongest premium residential installation growth as consumers invest in dedicated wine storage solutions.
- Hotels:In-room minibars and lobby service stations with standardized procurement protocols.
- Wine Retailers:Display and storage systems for inventory management and customer tasting environments.
Restaurants anchor the volume base while households expand most quickly.
Cooling Technology:
Regulatory efficiency mandates are compressing legacy fixed-speed compressor architectures while elevating variable-speed and hybrid alternatives.
- Compressor:Vapor-compression systems utilizing refrigerant cycles with displacement-controlled cooling capacity. China's SAMR GB standards compel redesigns toward variable-speed drives, with Japanese commercial buyers in Tokyo and Osaka specifying inverter-driven systems for vibration reduction.
- Thermoelectric:Solid-state Peltier devices converting electrical current directly to temperature differential without moving parts. Compact countertop formats in noise-sensitive environments favor these systems, though ambient temperatures above 35°C in Southeast Asian climates restrict deployment without climate-controlled environments.
- Absorption:Heat-driven cooling cycles utilizing ammonia-water solutions for silent operation.
- Hybrid:Integrated vapor-compression and thermoelectric architectures enabling dual-mode operation optimized for ambient temperature variation.
Compressor anchors the volume base while hybrid climbs the fastest.
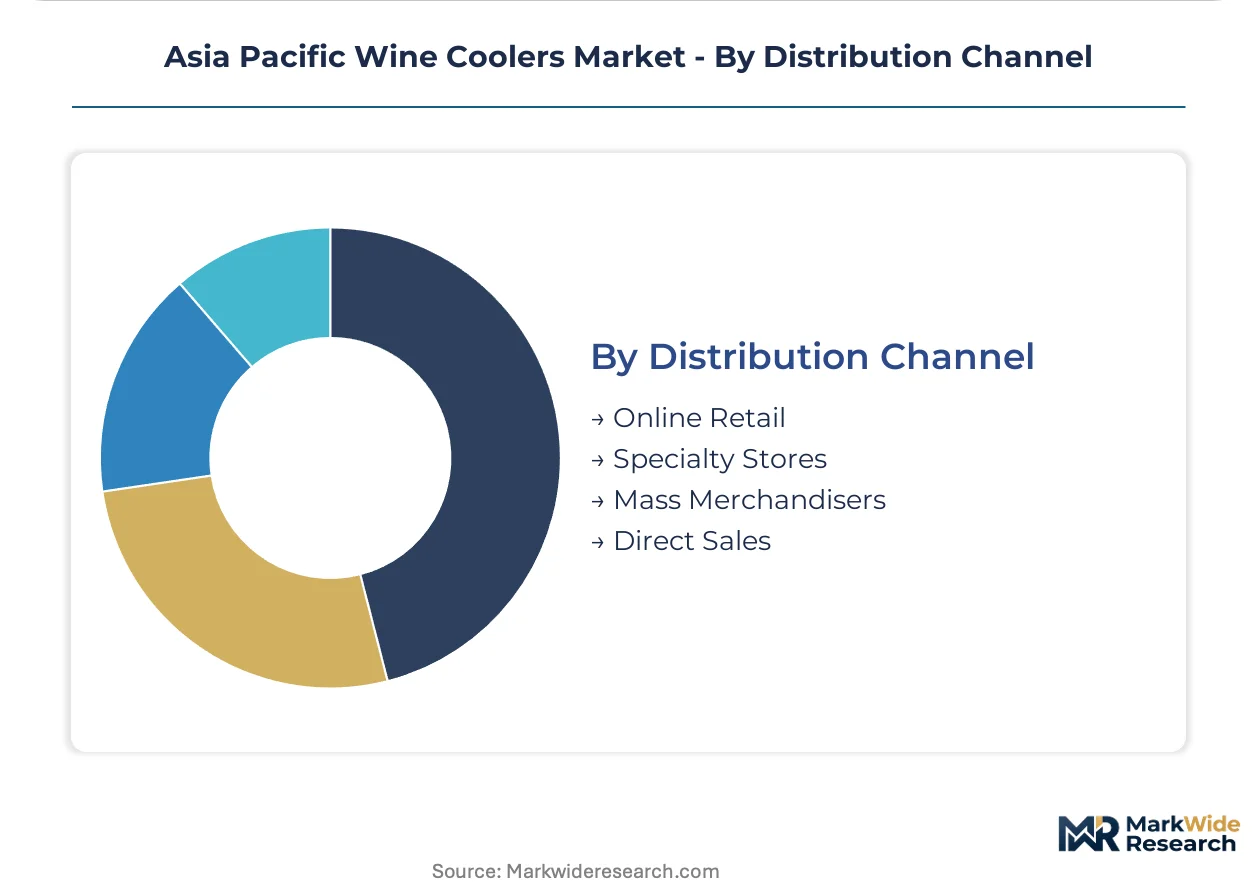
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct procurement displacing traditional retail for premium configurations.
- Online Retail:E-commerce platforms enabling mass-market thermoelectric distribution across Southeast Asia with lower customer acquisition costs. Midea Group anchors position through these channels in Indonesia and Vietnam.
- Direct Sales:Procurement relationships with kitchen designers, interior contractors, and renovation specialists. Singaporean and Hong Kong high-rise residential developments specify wine storage during early-stage project planning, bypassing appliance retail entirely.
- Specialty Stores:Wine-focused retailers and appliance boutiques with consultative selling environments.
- Mass Merchandisers:Big-box retailers with standardized inventory and price-competitive positioning.
Online retail anchors the volume base while direct sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's metropolitan restaurant districts while cost-sensitive procurement dominates Southeast Asian e-commerce channels, creating a two-tier regional structure that shapes manufacturer platform strategies.
China
Urban middle-class households in Shanghai and Beijing drive freestanding unit demand as rental-dense housing favors portable appliances. SAMR's GB 12021.2 efficiency mandates compel compressor redesigns with variable-speed drives, filtering low-efficiency imports from port entry. Qingdao's integrated manufacturing clusters supply compressor systems to domestic OEMs seeking compliance cost control.
Japan
Tokyo's Ginza and Osaka's Dotonbori restaurant districts require precise dual-zone climate separation for sommelier-driven beverage programs. METI's Top Runner standards progressively tighten allowable power consumption for precision climate-control devices, unlocking preferential procurement positioning for premium efficiency ratings. Nagoya's industrial corridor hosts compressor engineering specialists serving commercial specification upgrades.
Australia
Sydney and Melbourne's luxury residential renovation cycles integrate built-in wine storage into kitchen fit-outs, expanding premium configuration demand. The Equipment Energy Efficiency program imposes Minimum Energy Performance Standards that raise fixed costs for imported units, filtering smaller manufacturers from market entry. Melbourne's design-led procurement channels bypass traditional retail through direct-to-installer relationships.
South Korea
Seoul's high-rise residential developments specify compact countertop units for space-optimized urban living. The country's national appliance efficiency regulator enforces labeling requirements that shape import procurement criteria. Busan-Ulsan's manufacturing base supplies thermoelectric components for noise-sensitive residential applications.
Vietnam
Ho Chi Minh City's emerging middle-class households adopt compact thermoelectric units through e-commerce channels with limited legacy appliance ownership. Ambient temperatures above 35°C restrict Peltier system deployment without climate-controlled environments, constraining penetration in non-air-conditioned housing stock. Local distributors prioritize low-cost Chinese OEM platforms to match price-sensitive demand.
Asia Pacific Wine Coolers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific wine coolers landscape. The market structure fragments between high-volume OEMs with captive compressor manufacturing and precision-engineering specialists serving premium commercial specifications. Three archetypes dominate: integrated appliance conglomerates controlling upstream component costs, mass-market distributors leveraging e-commerce scale, and design-led European specialists capturing renovation-integrated procurement. Competitive moves center on modular platform development for multi-jurisdiction compliance and direct-to-installer channel bypass of traditional retail.
Within the integrated conglomerate tier, Haier Group Corporation and Midea Group exemplify divergent scale strategies. Haier's Qingdao-based manufacturing structure represents upstream control over compressor production, while Midea anchors mass-market positioning through Southeast Asian e-commerce penetration. Electrolux occupies a position exemplifying design-led premium specialization for affluent households in Singapore and Hong Kong.
| Leading Market Players |
|---|
| Haier Group Corporation |
| Whirlpool Corporation |
| Midea Group |
| Panasonic Corporation |
| Samsung Electronics Co., Ltd. |
| LG Corporation |
| Bosch Group |
| Electrolux |
| Arcelik A.Ş. |
| Others |
Pricing and Supply Chain Analysis
Qingdao's integrated compressor manufacturing clusters achieve 40-50% capacity utilization advantages over fragmented Southeast Asian assembly operations, compressing cost floors for freestanding units while elevating premium pricing power for built-in configurations specified through Australia's direct-to-installer channels. This scale asymmetry between captive component production and import-dependent assembly defines margin capture potential across the Asia Pacific wine coolers landscape.
Pricing Analysis
Customization-premium spreads separate built-in configurations specified during Sydney and Melbourne renovation cycles from mass-market freestanding units distributed through Southeast Asian e-commerce. Three-tier pricing structure across premium, standard, and economy levels stratifies by cooling architecture, with variable-speed compressor systems commanding 25-35% premiums over fixed-speed alternatives due to METI Top Runner compliance and vibration-dampened shelving specifications. Price differentiation hinges on certification grade and geographic delivery cost, with Australia's MEPS testing requirements filtering low-cost imports and compressing margins at the economy tier. Household segments in Vietnam and Indonesia exhibit highest price sensitivity, while Japan's metropolitan restaurant districts demonstrate lowest sensitivity due to sommelier-driven specification requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites compressor component flows from Qingdao and Guangzhou manufacturing clusters to Southeast Asian assembly operations, exposing lead times to seasonal congestion. Geographic supply concentration centers on China for compressor systems and thermoelectric modules, South Korea for electronic control assemblies, and Japan for precision temperature sensors. Raw material dependencies encompass copper coil stock for vapor-compression heat exchangers, aluminum extrusions for cabinet framing, and refrigerant gases subject to phasedown regulations. Supply chain risk manifests through single-source vulnerability in variable-speed drive controllers sourced from Nagoya industrial corridor specialists. Distribution runs through direct-to-installer procurement for built-in configurations and platform e-commerce for compact countertop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cooling technology architectures and jurisdiction-specific compliance requirements creates multiple niche entry points, as renovation-integrated specification in Australia's luxury residential sector diverges from mass-market e-commerce penetration in Southeast Asia.
For Market Incumbents: Fortify position through captive compressor manufacturing scale in Qingdao and modular platform development spanning GB, MEPS, and JIS compliance requirements. Invest in direct-to-installer channel control to bypass retail margin compression in Singapore and Hong Kong renovation markets. Address thermoelectric cooling limitations in Southeast Asian climates through hybrid architecture R&D before emerging specialists capture white-space positioning. For New Entrants and Emerging Players: After-sales service networks for dual-zone commercial installations represent an incumbent under-serve where specialized technicians command premium pricing in Tokyo and Osaka restaurant districts. Target Vietnam's e-commerce channel with compact thermoelectric units priced below Midea Group's mass-market positioning, leveraging local distributor relationships to circumvent MEPS-equivalent testing burdens. Pursue go-to-market partnerships with kitchen design studios in Australian renovation markets to capture built-in specification before incumbent direct sales relationships solidify. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineering specialists with inverter-driven compressor expertise over high-volume OEMs facing commodity input volatility. Long-term viability rests on regulatory compliance automation capabilities as efficiency standards tighten across multiple jurisdictions. Acquisition targets should demonstrate established relationships with Japan's METI certification bodies and Australia's Equipment Energy Efficiency program administrators. Watch hybrid cooling architecture patent filings as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Enables single-SKU compliance across China's SAMR GB standards, Australia's MEPS, and Japan's METI Top Runner requirements. |
| Direct-to-Installer Channel Expansion | Bypasses retail margin compression in Singapore and Hong Kong high-rise residential renovation markets. |
| Hybrid Cooling Architecture Investment | Bridges thermoelectric noise advantages with vapor-compression capacity for Southeast Asian climate adaptation. |
| Captive Compressor Manufacturing Scale-Up | Secures input cost control against copper and aluminum commodity volatility affecting coil and heat exchanger materials. |
| Commercial Service Network Buildout | Captures recurring revenue from Tokyo and Osaka restaurant district dual-zone installation maintenance contracts. |
Research Methodology
The analysis maps freestanding, built-in, countertop, and dual-zone product configurations, each validated through appliance procurement managers at commercial foodservice chains, residential renovation contractors, e-commerce platform category leads, and compressor manufacturing engineers. Primary interviews with Haier Group Corporation and Midea Group supply chain executives, Electrolux specification designers, and METI standards administrators combined with secondary validation through SAMR GB standard filings, Australia's Equipment Energy Efficiency program registration databases, Japan's Top Runner product lists, and customs trade data for compressor component flows. Bottom-up shipment estimates by product type and cooling technology triangulated against top-down market value reconstructions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning product configuration, cooling architecture, end-user category, and distribution channel dimensions. CAGRs derived from fitted growth curves incorporating regulatory compliance cost trajectories, renovation cycle timing in Australian metropolitan markets, and e-commerce penetration rates in Southeast Asian middle-class households. Industry-specific forecast inputs encompass variable-speed compressor adoption curves in Japanese commercial installations and thermoelectric system performance constraints in ambient temperatures above 35°C.
Material uncertainties — commodity price swings in copper and aluminum, divergence in national efficiency standard trajectories, and climate adaptation failures in non-air-conditioned Southeast Asian housing stock — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and renovation cycle continuity. Practitioners should keep alternative scenarios live as hybrid cooling technology maturation and multi-jurisdiction certification streamlining evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Middle East and Africa Beer Market