
 Europe Mass Spectrometry Market | 2026-2036
Europe Mass Spectrometry Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mass Spectrometry Market Foresight
The capability gap between high-end research-grade platforms and routine analytical systems is collapsing as mid-range instruments incorporate resolution and speed features once reserved for elite configurations. Thermo Fisher Scientific leverages its Orbitrap technology portfolio to anchor premium positioning across European pharmaceutical hubs. Waters Corporation sustains dominance in liquid chromatography-mass spectrometry integration through disciplined channel control in regulated laboratories. Bruker Corporation specializes in time-of-flight architectures for academic and industrial research segments.
Mass spectrometry measures the mass-to-charge ratio of ions using electromagnetic fields, with modern systems achieving resolution exceeding 100,000 full-width at half-maximum and mass accuracy below 2 parts per million for molecular identification and quantification. Triple quadrupole platforms occupy the core of pharmaceutical quality control and clinical diagnostics workflows due to proven regulatory compliance and method transferability. Hybrid systems, combining quadrupole and time-of-flight or Orbitrap analyzers, are capturing expanding proteomics and metabolomics application budgets as multi-omics research intensifies across European biotechnology institutes.
EMA bioanalytical method validation guidelines and REACH chemical substance registration requirements shape instrument specification standards and drive replacement cycles in contract research organizations and environmental testing laboratories. The EU AI Act and MDR frameworks increasingly influence software-enabled mass spectrometry systems with automated data interpretation and diagnostic reporting capabilities. Stakeholders must monitor evolving CE marking obligations for in-vitro diagnostic mass spectrometry platforms and assess how ECHA substance restriction proposals redirect environmental testing demand toward higher-sensitivity detection modalities.
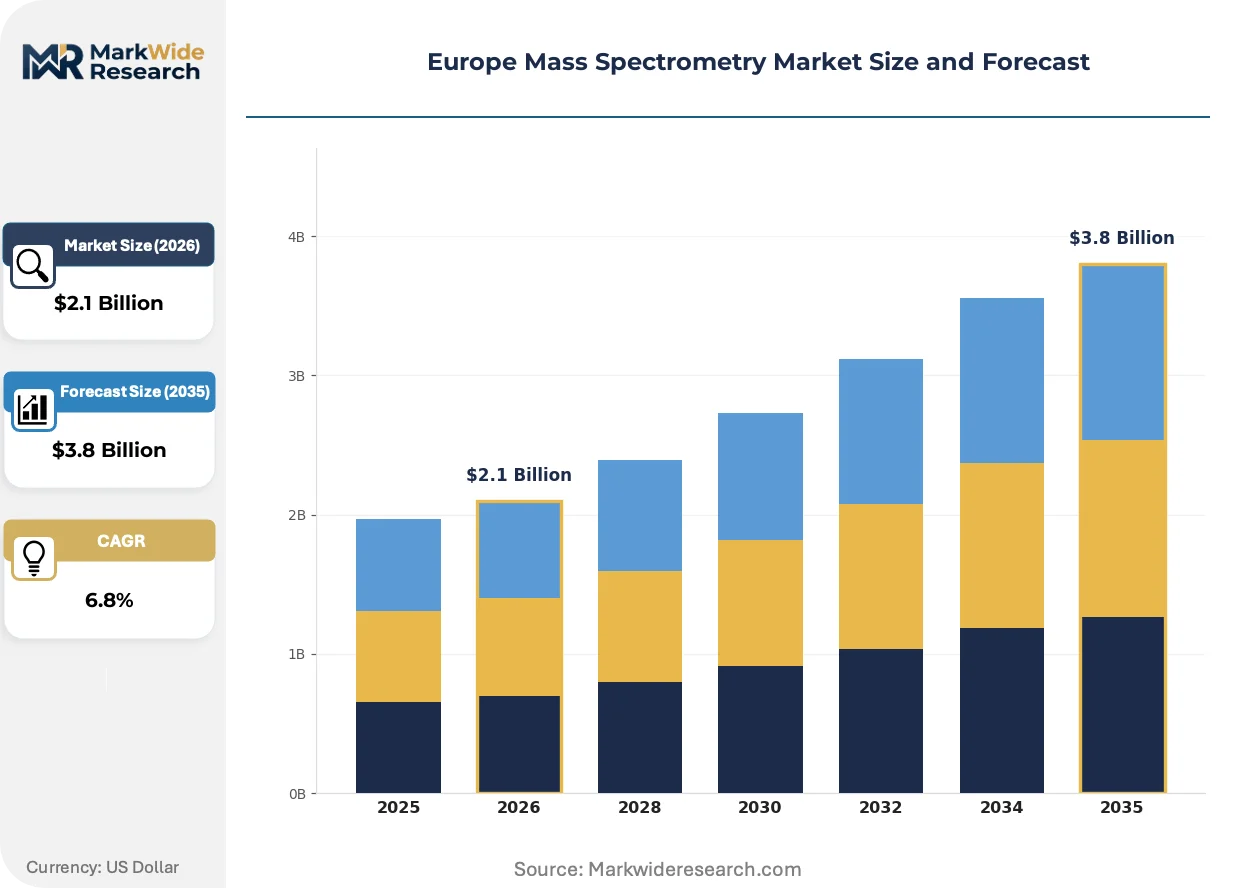
Market Dynamics
The convergence of EMA bioanalytical method validation requirements with REACH substance registration mandates is compressing replacement cycles and elevating minimum performance specifications across pharmaceutical and environmental testing laboratories.
Growth Catalysts
- EMA bioanalytical guidelines:Pharmaceutical laboratories in Germany and France are upgrading to high-resolution accurate mass systems to meet stringent method validation standards for biologics development.
- Multi-omics research expansion:European biotechnology institutes are channeling funding into hybrid quadrupole-Orbitrap platforms for integrated proteomics and metabolomics workflows.
- Environmental testing modernization:ECHA substance restriction proposals are redirecting contract laboratories toward higher-sensitivity detection modalities for emerging contaminant surveillance.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry operations face input cost pressure from concentrated noble gas sourcing and geopolitical supply disruptions.
- Instrument capital intensity:Academic and mid-sized CRO budgets constrain adoption of research-grade platforms despite performance advantages over routine systems.
- CE marking complexity:The EU MDR framework extends certification timelines for in-vitro diagnostic mass spectrometry platforms, delaying commercialization of automated diagnostic systems.
Strategic Opportunities
- Spain and Italy biopharma clusters:Underpenetrated analytical instrument fleets in southern European manufacturing hubs present expansion targets for mid-range hybrid systems.
- AI-enabled data interpretation:Convergence of machine learning algorithms with spectral libraries is creating new value layers in high-throughput screening applications.
- EU Green Deal alignment:Sustainability-linked procurement criteria favor vendors offering energy-efficient ion source technologies and reduced solvent consumption workflows.
Industry Challenges
- Spectroscopist talent scarcity:Specialized expertise in high-resolution mass spectrometry method development remains concentrated in elite pharmaceutical hubs, constraining CRO scaling.
- Legacy LIMS integration:Laboratory information management systems in regulated environments require costly customization to accommodate modern instrument data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mass Spectrometry Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triple Quadrupole, Time-of-Flight, Ion Trap, Hybrid End User: Pharmaceuticals, Biotechnology, Environmental Testing, Academic Research Application: Proteomics, Metabolomics, Drug Testing, Food Safety Technology: Gas Chromatography, Liquid Chromatography, Mass Detectors, Ionization Techniques |
| Companies Covered | Thermo Fisher Scientific, Waters Corporation, Agilent Technologies, Bruker Corporation, Danaher Corporation, Shimadzu Corporation, PerkinElmer, LECO Corporation, Dani Instruments, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mass Spectrometry Market Shifts & Advancements
Instrument architectures are collapsing traditional capability tiers while regulatory frameworks accelerate software-enabled automation. Three developments are reconfiguring competitive positioning across the European landscape.
High-resolution accurate mass detection is supplanting nominal mass systems in routine pharmaceutical quality control. Mid-tier manufacturing sites in the Netherlands and Switzerland are adopting Orbitrap-based platforms previously reserved for elite research institutions. This capability democratization is compressing the premium segment and forcing vendors to differentiate through workflow integration rather than raw specifications alone.
REACH chemical substance registration deadlines are tightening detection threshold requirements for environmental testing laboratories. The ECHA restriction roadmap is accelerating demand for tandem quadrupole and time-of-flight systems capable of sub-parts-per-billion quantification. Contract research organizations in Germany and the United Kingdom are prioritizing instrument procurement that satisfies both current compliance needs and anticipated regulatory escalation.
Service unbundling is fragmenting traditional capital-equipment purchasing patterns. Pharmaceutical quality control departments in France and Belgium are separating hardware acquisition from method development and validation support, creating openings for specialized analytical service providers. This shift favors vendors with flexible financing structures and modular software licensing over bundled full-service contracts.
Europe Mass Spectrometry Market Segmentation
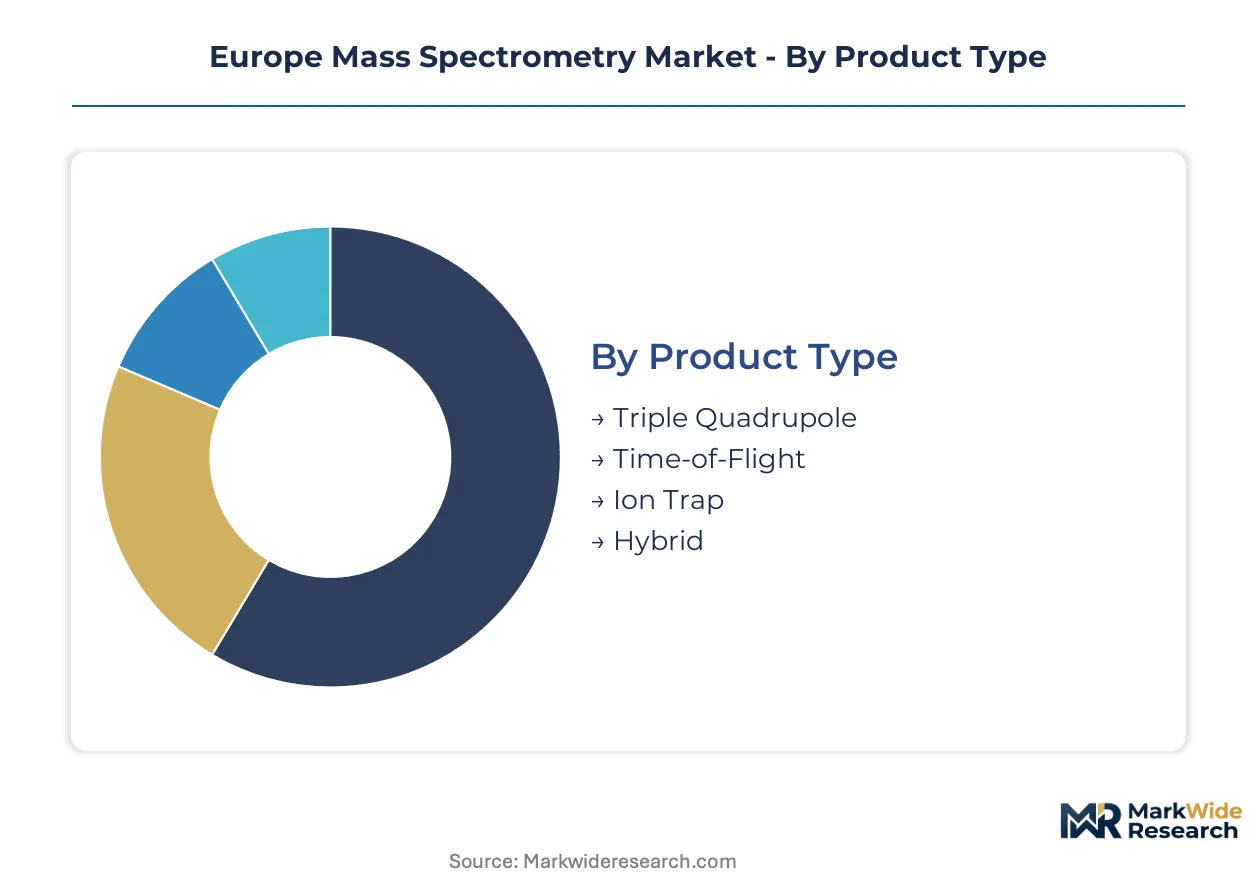
Mass spectrometry segmentation in Europe reflects divergent technology maturity curves and regulatory compliance pressures across pharmaceutical manufacturing, environmental surveillance, and academic research ecosystems. Procurement patterns fragment across performance tiers, with high-resolution platforms commanding premium positioning in biologics development while routine quadrupole systems dominate quality control workflows.
Product Type:
Margin pools concentrate in hybrid architectures where quadrupole-Orbitrap and quadrupole-time-of-flight configurations command pricing premiums through multi-analyzer versatility.
- Triple Quadrupole:These tandem mass analyzers deliver selective reaction monitoring with proven regulatory compliance for quantitative bioanalysis. Pharmaceutical quality control laboratories in Germany and France deploy these platforms for EMA method validation workflows, constrained by helium supply volatility in gas chromatography-coupled configurations.
- Hybrid:Quadrupole-Orbitrap and quadrupole-time-of-flight systems combine precursor ion selection with high-resolution accurate mass detection. Biotechnology institutes across Switzerland and the Netherlands are channeling capital toward these platforms as multi-omics research intensifies, displacing standalone time-of-flight systems in proteomics budgets.
- Time-of-Flight:Single-stage analyzers excel in rapid full-scan acquisition for untargeted screening applications.
- Ion Trap:These three-dimensional or linear quadrupole traps enable multi-stage fragmentation for structural elucidation in academic research settings.
The dominant share belongs to Triple Quadrupole, while Hybrid is closing the gap fastest.
End User:
Customer procurement authority concentrates in pharmaceutical manufacturing hubs where EMA bioanalytical guidelines mandate instrument performance thresholds.
- Pharmaceuticals:Large molecule development and small molecule quality control drive capital allocation toward compliant platforms. German and French biopharma clusters are upgrading analytical instrument fleets to satisfy EMA bioanalytical method validation requirements for biologics characterization.
- Biotechnology:European biotechnology institutes prioritize hybrid quadrupole-Orbitrap systems for integrated proteomics and metabolomics workflows. Funding concentration in multi-omics research is accelerating replacement cycles beyond traditional depreciation schedules.
- Environmental Testing:Contract research organizations face tightening detection thresholds from ECHA substance restriction proposals.
- Academic Research:University laboratories balance performance specifications against constrained capital budgets, favoring mid-range configurations.
Pharmaceuticals captures the largest revenue pool, though Biotechnology is expanding most quickly as multi-omics funding intensifies.
Application:
Workflow complexity and regulatory stringency determine platform selection across quantitative and qualitative analytical demands.
- Proteomics:High-resolution accurate mass detection enables protein identification and post-translational modification mapping. European biotechnology institutes are deploying hybrid quadrupole-Orbitrap systems for large-scale protein quantification studies, with method development expertise concentrated in elite pharmaceutical hubs.
- Metabolomics:Untargeted metabolic profiling requires broad dynamic range and mass accuracy for unknown compound identification. Research consortia across the Netherlands and Belgium are integrating these workflows with AI-enabled spectral interpretation tools.
- Drug Testing:Forensic and clinical toxicology laboratories rely on triple quadrupole platforms for regulated bioanalysis.
- Food Safety:Veterinary residue and contaminant screening drives demand for multi-residue methods in regulatory laboratories.
Proteomics maintains the leading position, while Metabolomics is gaining share fastest through convergence with systems biology research.
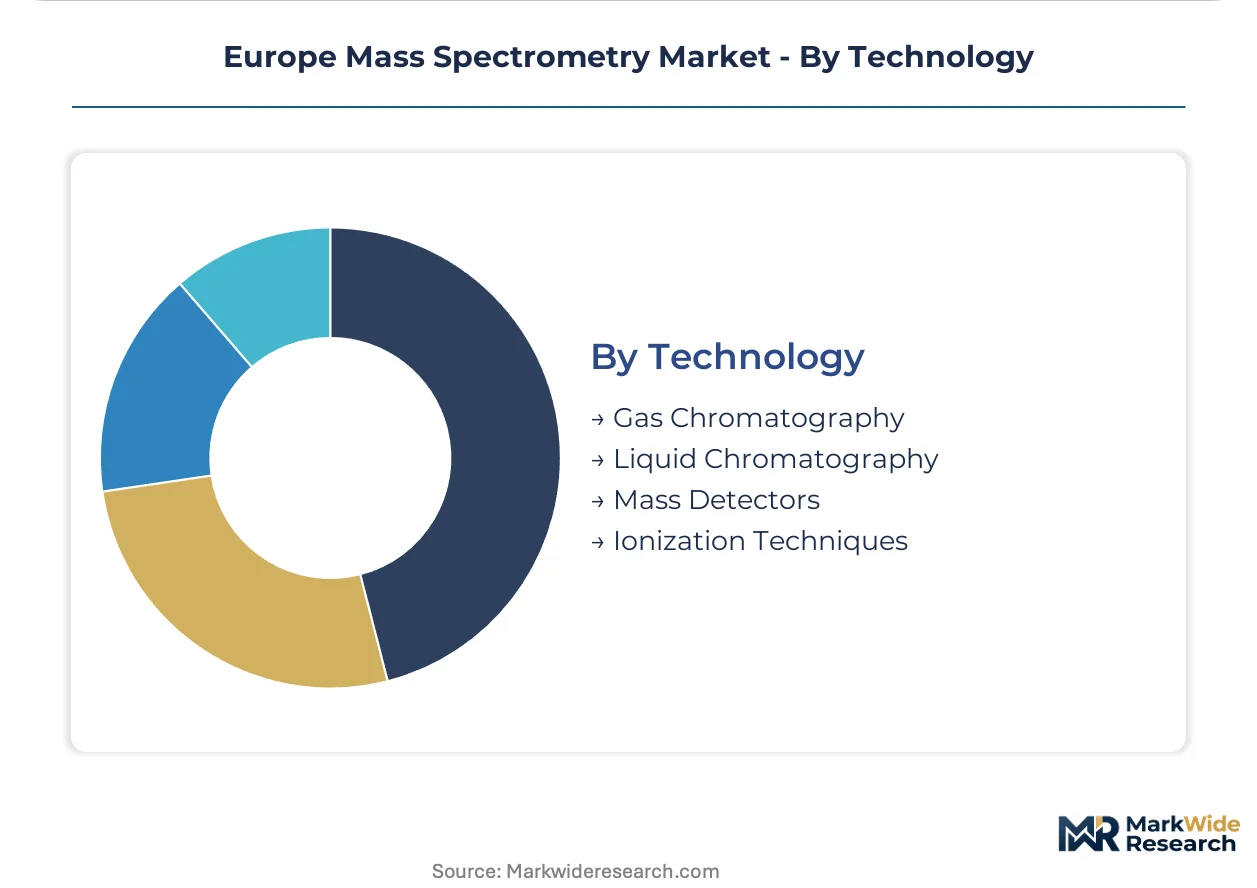
Technology:
Chromatographic integration and ionization flexibility separate routine analytical systems from research-grade configurations.
- Liquid Chromatography:LC-MS dominates biopharma analytical workflows for polar and thermally labile compounds. Waters Corporation sustains channel control in regulated European laboratories through disciplined distribution partnerships for ultra-high-pressure systems.
- Gas Chromatography:GC-MS retains dominance in volatile and semi-volatile compound analysis for environmental testing. Helium supply volatility from concentrated noble gas sourcing is redirecting some procurement toward hydrogen carrier gas alternatives.
- Mass Detectors:Detector architecture selection—electron multiplier, array detector, or orbitrap—determines sensitivity and resolution specifications.
- Ionization Techniques:Electrospray and atmospheric pressure chemical ionization interfaces enable diverse compound class coverage.
Liquid Chromatography holds the dominant technology position, while advanced Ionization Techniques are climbing fastest through application-specific customization demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical manufacturing clusters while Italian and Spanish laboratories operate under tighter capital constraints. This asymmetry shapes procurement patterns across the continent. Northern European biopharma hubs command premium instrument specifications that southern European facilities cannot replicate.
Germany
Bavarian and North Rhine-Westphalian pharmaceutical clusters drive demand for EMA-compliant high-resolution systems. The country's national pharmaceutical regulator enforces stringent bioanalytical method validation standards that accelerate replacement cycles in contract research organizations. Frankfurt and Munich host dense concentrations of analytical service providers upgrading hybrid quadrupole-Orbitrap platforms.
Switzerland
Basel and Zurich biotechnology institutes channel funding toward integrated proteomics workflows. Swissmedic maintains rigorous device approval pathways that favor established instrument vendors with proven regulatory track records. The country's pharmaceutical manufacturing corridor concentrates procurement authority for research-grade mass spectrometry configurations.
France
Paris-Saclay research consortia and Lyon biopharma clusters expand metabolomics capabilities. ANSM oversight of in-vitro diagnostic platforms extends certification timelines for automated mass spectrometry systems. Île-de-France laboratories are separating hardware acquisition from method development support, creating openings for specialized service providers.
Netherlands
Amsterdam and Rotterdam contract laboratories face tightening REACH detection thresholds for environmental contaminant surveillance. The country's environmental regulator aligns with ECHA substance restriction proposals that redirect demand toward higher-sensitivity detection modalities. Randstad analytical service providers are modernizing tandem quadrupole fleets for emerging pollutant monitoring.
United Kingdom
Cambridge and Oxford academic-industrial partnerships drive multi-omics research instrumentation budgets. The Medicines and Healthcare products Regulatory Agency maintains post-Brexit alignment with EMA bioanalytical guidelines for pharmaceutical quality control. Southeast England biotechnology institutes are deploying AI-enabled spectral interpretation tools alongside hybrid mass spectrometry platforms.
Europe Mass Spectrometry Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium positioning depends on regulatory compliance depth rather than raw specifications alone. The vendor base spans consolidated multinationals with full workflow portfolios and specialized firms dominating narrow application niches. Two strategic archetypes predominate: integrated platform providers leveraging chromatography-mass spectrometry bundling, and resolution-focused specialists anchoring high-end research segments. Competitive moves concentrate on strategic partnerships for AI-enabled data interpretation and geographic expansion into underpenetrated southern European manufacturing hubs.
Among US-based diversified technology conglomerates, Thermo Fisher Scientific and Waters Corporation exemplify contrasting positioning strategies. Thermo Fisher Scientific anchors the premium tier through Orbitrap technology ownership and pharmaceutical hub penetration. Waters Corporation occupies a disciplined position in regulated liquid chromatography-mass spectrometry integration. Danaher Corporation represents the life sciences tools consolidation archetype, assembling analytical instrument portfolios through serial acquisition strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Waters Corporation |
| Agilent Technologies |
| Bruker Corporation |
| Danaher Corporation |
| Shimadzu Corporation |
| PerkinElmer |
| LECO Corporation |
| Dani Instruments |
| Others |
Supply & Pricing Matrix
Manufacturing scale economies in German and Swiss precision engineering clusters concentrate high-end mass spectrometer production, compressing price floors for mid-range configurations while elevating premium-tier entry barriers through regulatory certification complexity. This supply concentration amplifies vendor pricing power in pharmaceutical hubs while squeezing margins for southern European distributors serving budget-constrained academic laboratories.
Pricing Analysis
The customization-premium spread spans configured-to-order hybrid quadrupole-Orbitrap systems against standard triple quadrupole platforms, with pricing stratifying across premium, standard, and economy tiers based on resolution specifications and EMA validation documentation depth. Price differentiation hinges on CE marking tier and after-sales method development bundling. Cost compression in mid-range configurations is intensifying because helium supply volatility elevates gas chromatography-coupled system operating expenses. Academic laboratories exhibit highest price sensitivity, while German pharmaceutical quality control departments prioritize regulatory compliance over capital expenditure optimization.
Supply Chain Analysis
Germany and Switzerland anchor precision mass analyzer manufacturing, with Massachusetts and California housing specialized ion source component production. Vacuum systems draw from German pump engineering, detection electronics rest on Japanese semiconductor fabrication, and rare earth magnet assemblies source from Chinese rare earth processing. Single-source vulnerability concentrates in helium isotope separation for gas chromatography-mass spectrometry carrier gas applications. Distribution runs through authorized distributor networks with factory-trained service engineer certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in high-resolution mass spectrometry method development remains concentrated in Bavarian and Basel pharmaceutical corridors, constraining contract research organization scaling and creating acquisition premiums for talent-dense analytical service providers.
For Market Incumbents: Shield installed base retention through captive supply of replacement ion source consumables and embedded LIMS integration customization. Deepen regulatory compliance documentation depth to extend EMA bioanalytical validation service contracts. Prioritize channel control in French and Belgian laboratories where service unbundling fragments traditional bundled purchasing patterns. For New Entrants and Emerging Players: Lead with AI-enabled spectral interpretation software licensing as a low-capital entry vector into high-throughput screening applications. Target Spanish and Italian biopharma manufacturing clusters where analytical instrument fleet penetration lags northern European hubs. Deploy flexible financing structures to capture method development support contracts separated from hardware acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid platform vendors with embedded software subscription tiers and consumables lock-in. Long-term viability centers on regulatory compliance depth rather than raw specification advantages. Target acquisition archetypes include specialized analytical service providers with EMA validation track records in underpenetrated southern European markets. Watch helium supply substitution progress as an inflection indicator for gas chromatography-mass spectrometry competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Spectral Interpretation Development | Machine learning convergence with Orbitrap data streams creates differentiation in high-throughput proteomics workflows. |
| Helium Substitution Technology Investment | Hydrogen carrier gas validation expands addressable market amid noble gas supply disruption risks. |
| Southern European Geographic Expansion | Spanish and Italian biopharma cluster penetration captures mid-range hybrid system demand outside saturated northern hubs. |
| Regulatory Compliance Documentation Depth | EMA bioanalytical method validation expertise extends service contract duration and reduces competitive displacement risk. |
| Consumables and Service Revenue Conversion | Embedded ion source and detector replacement contracts stabilize recurring revenue against capital equipment cyclicality. |
Research Methodology
Desk research of EMA bioanalytical guidance documents, ECHA substance restriction proposals, and Swissmedic device approval pathways preceded structured interviews with pharmaceutical analytical laboratory directors, contract research organization procurement leads, biotechnology institute facility managers, and environmental testing laboratory technical directors. Secondary validation drew from REACH registration databases, EU MDR certification records, and academic multi-omics research funding disclosures. Bottom-up instrument shipment modeling triangulated against top-down pharmaceutical R&D expenditure allocation estimates.
Variance decomposition across product type, end user, application, and technology segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression analysis and multi-omics funding trajectory assessment. Modeled inputs incorporated EMA bioanalytical guideline revision timelines and ECHA substance restriction proposal implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EMA guideline enforcement or helium supply stabilization would require recalibration. Forecasts reflect assumptions regarding biotechnology funding continuity and REACH detection threshold escalation. Recalibration cycles align with material shifts in regulatory compliance deadlines and noble gas sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Breath Biopsy Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Mycological Testing Market
Testing Services
Cholesterol Test Market
Testing Services
D-Dimer Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Addison Disease Testing Market
Testing Services
Americas Sterility Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Dengue Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market