
 Staphylococcus Aureus Testing Market | 2026-2036
Staphylococcus Aureus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Staphylococcus Aureus Testing Market Analytics
Hospital laboratories is bifurcating from smaller outpatient clinics as the dominant buyer archetype in Staphylococcus aureus testing, with large integrated delivery networks consolidating procurement volume. Thermo Fisher Scientific dominates molecular diagnostics platforms through extensive R&D infrastructure and direct hospital contracts. bioMérieux SA differentiates via automated blood culture systems that reduce time-to-result for bloodstream infection protocols. Abbott Laboratories anchors point-of-care testing with cartridge-based platforms designed for emergency department triage.
Staphylococcus aureus testing encompasses laboratory and near-patient diagnostic methods designed to detect, identify, and characterize this Gram-positive bacterium, including methicillin-resistant strains (MRSA), through phenotypic or genotypic analysis. PCR-based molecular diagnostics detect mecA or mecC gene sequences within hours, replacing traditional overnight culture confirmation in critical care settings. Immunoassays occupy the high-throughput screening tier in hospital core laboratories, while NGS-based surveillance applications represent the fastest-growing technology segment for outbreak investigation and resistance profiling. Rapid tests command premium pricing in emergency and surgical pre-admission workflows where turnaround time directly affects isolation bed management.
The FDA regulates in vitro diagnostic devices through premarket notification and clearance pathways, while the Clinical Laboratory Improvement Amendments (CLIA) establish proficiency standards for laboratories performing S. aureus identification. The European Union's In Vitro Diagnostic Regulation (IVDR) imposes stricter clinical evidence requirements on molecular diagnostic kits, reshaping market access timelines for manufacturers. Stakeholders must monitor how antimicrobial stewardship mandates from the Centers for Medicare & Medicaid Services increasingly tie reimbursement to rapid pathogen identification capabilities.
Market Dynamics
Hospital laboratory consolidation is compressing vendor margins while simultaneously accelerating molecular platform standardization across integrated delivery networks, forcing manufacturers to restructure commercial terms around multi-year enterprise agreements rather than transactional instrument sales.
Growth Catalysts
- CLIA-waived rapid tests:Emergency departments in the United States deploy FDA-cleared cartridge platforms to isolate MRSA-positive patients within one hour, reducing transmission risk and bed-blocking costs.
- Antimicrobial stewardship mandates:CMS reimbursement conditions now require documented rapid pathogen identification for sepsis bundles, directly linking payment to molecular diagnostic capability in acute care settings.
- Next-generation sequencing surveillance:Public health laboratories in the United Kingdom deploy whole-genome typing for outbreak tracing, creating demand for bioinformatics-integrated testing workflows.
Market Restraints
- Capital intensity of molecular platforms:Real-time PCR systems require $150,000-$400,000 upfront investment, excluding smaller independent laboratories from automated testing tiers.
- IVDR clinical evidence requirements:The European Union's 2022 regulation imposes prospective performance studies on novel resistance gene assays, extending time-to-market by 18-24 months.
- Specialized technician scarcity:Molecular diagnostics demands dual competency in microbiology and nucleic acid amplification, constraining laboratory expansion in rural and community hospital settings.
Strategic Opportunities
- Decentralized testing in India:Tier-2 and Tier-3 cities lack reference laboratory density, creating white space for point-of-care MRSA screening in surgical pre-admission clinics.
- AI-assisted resistance prediction:Machine learning algorithms analyzing phenotypic growth patterns combined with genomic markers enable same-day susceptibility reporting without overnight culture.
- Direct-to-consumer screening channels:Occupational health programs for healthcare workers and food processing staff represent an underdeveloped revenue stream outside traditional hospital procurement.
Industry Challenges
- Legacy LIS integration complexity:Hospital information systems built on 1990s architectures resist seamless data flow from modern molecular instruments, requiring costly middleware development.
- Proficiency testing standardization gaps:External quality assessment programs for mecC gene detection remain inconsistent across accreditation bodies, complicating laboratory compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Staphylococcus Aureus Testing Market |
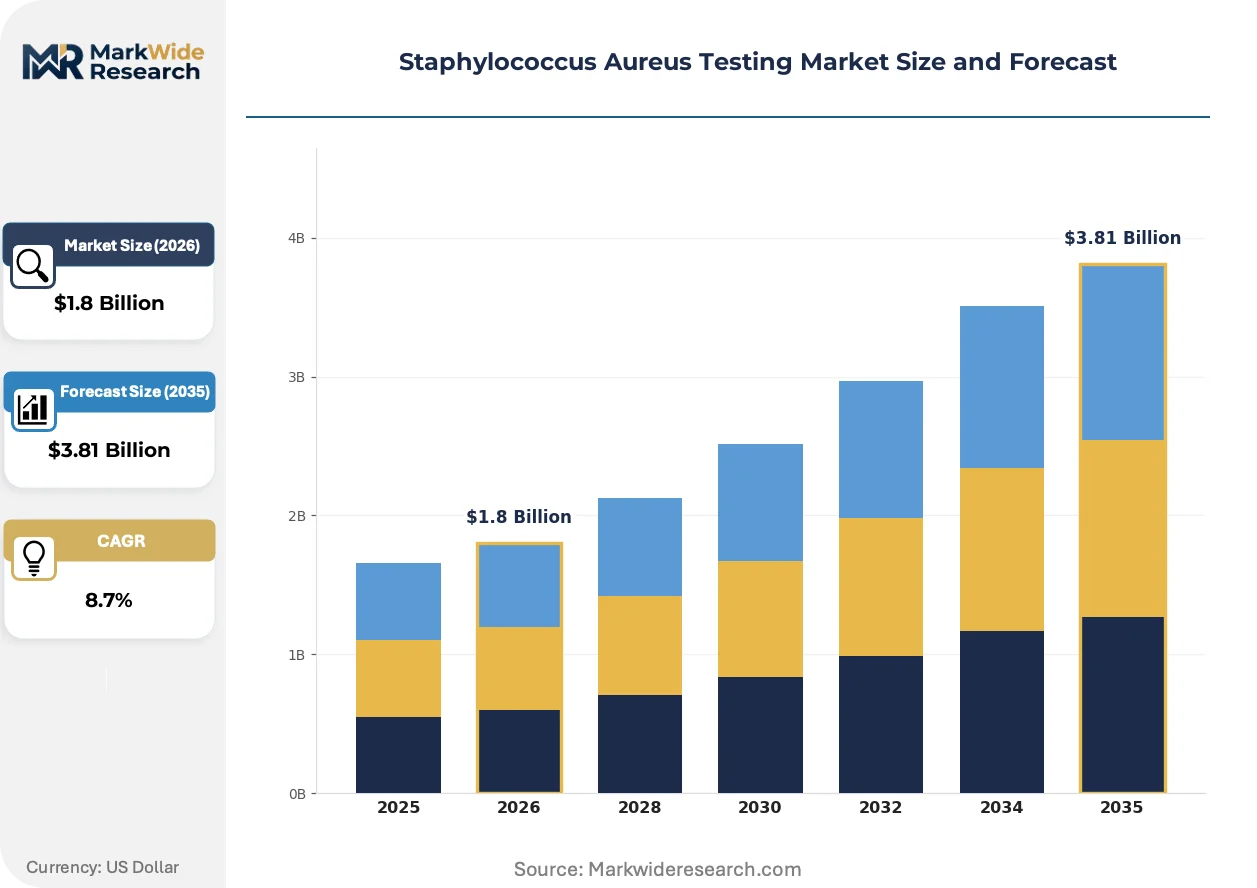
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, Culture Media, Immunoassays, Rapid Tests End User: Hospitals, Diagnostic Laboratories, Research Facilities, Home Care Technology: Microbiological Methods, Molecular Diagnostics, Serological Tests, NGS Application: Clinical Diagnostics, Food Safety, Environmental Testing, Veterinary Care |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Grifols S.A., QIAGEN N.V., bioMérieux SA, Cepheid, 3M Company, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Staphylococcus Aureus Testing Market Evolving Landscape
Diagnostic workflows are bifurcating between centralized high-throughput molecular hubs and distributed rapid testing nodes, with technology choices increasingly dictated by turnaround requirements rather than analytical sensitivity alone.
CRISPR-based detection platforms are fragmenting the nucleic acid testing landscape by enabling instrument-free resistance gene identification at ambient temperature. Community hospitals and long-term care facilities lacking capital budgets adopt these lateral flow formats for same-shift results. The technology is fragmenting the traditional hospital-core-laboratory monopoly on definitive MRSA diagnosis, shifting diagnostic authority toward infection control nurses and bedside clinicians.
The FDA's 2023 updated antimicrobial susceptibility testing guidance now requires device manufacturers to demonstrate clinical outcomes impact beyond analytical accuracy. This reshapes product development roadmaps toward integrated diagnostic-therapeutic decision support. Bloodstream infection assay developers face expanded clinical trial obligations before 510(k) clearance, particularly for novel resistance mechanism detection claims.
Integrated delivery networks now mandate enterprise-wide testing standardization through sole-source contracts spanning dozens of affiliated sites. This procurement consolidation displaces best-of-breed instrument selection with unified vendor relationships. The shift is most visible in the United States, where health systems exceeding $5 billion annual revenue increasingly centralize laboratory governance under single diagnostic platform agreements.
Staphylococcus Aureus Testing Market Segmentation
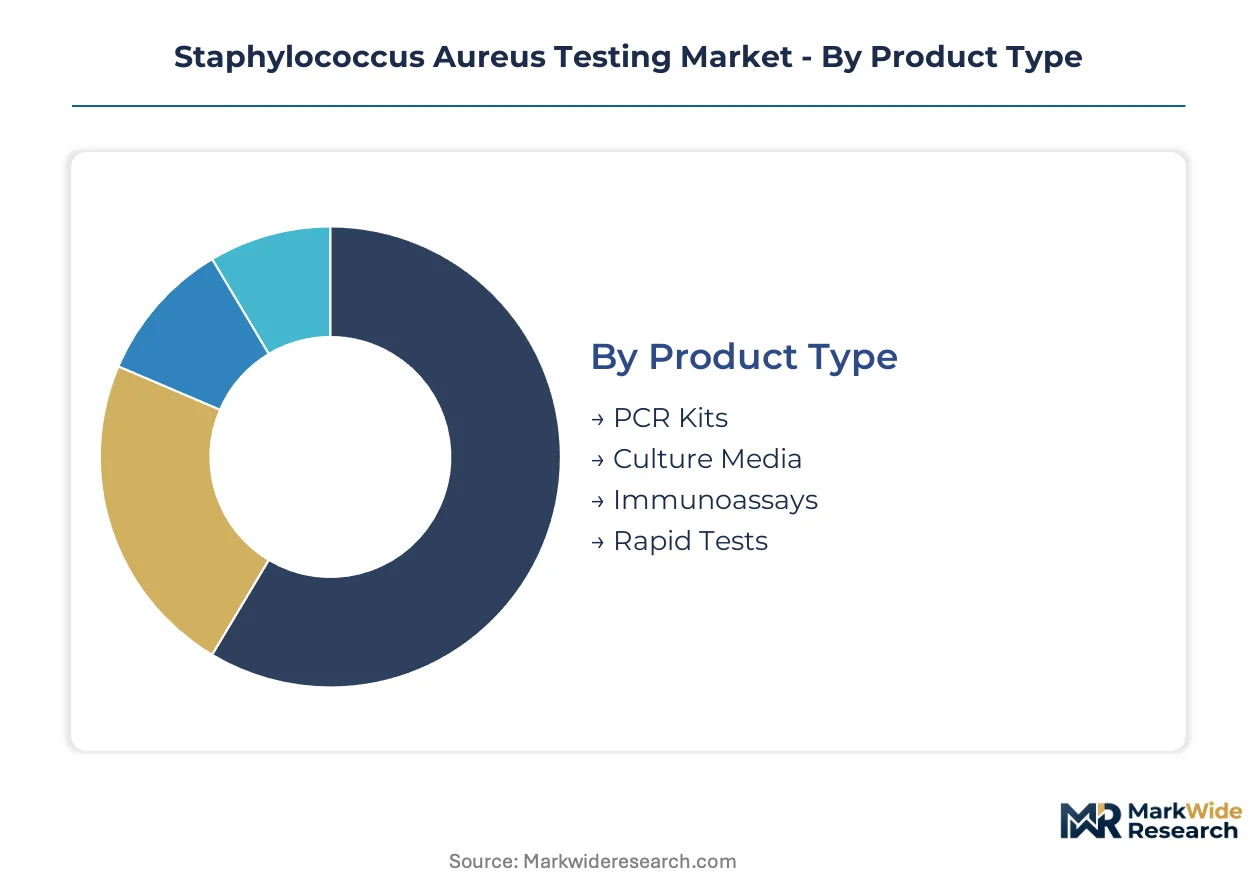
Staphylococcus aureus testing segments fracture along capability-cost tradeoffs, with molecular platforms displacing legacy methods in high-acuity settings while rapid lateral flow formats capture decentralized demand. Procurement consolidation across integrated delivery networks increasingly favors vendors offering cross-segment platform compatibility.
Product Type:
PCR Kits face the most acute substitution pressure from CRISPR-based detection formats that eliminate thermal cycler capital requirements, while Culture Media resists displacement through reimbursement anchoring in routine surveillance protocols.
- PCR Kits:Real-time amplification systems detect mecA/mecC resistance genes within 2-4 hours. Demand concentrates in United States tertiary care centers where CMS sepsis bundle mandates require documented rapid pathogen identification.
- Rapid Tests:Lateral flow immunochromatographic cartridges deliver results at point-of-care without laboratory infrastructure. United States emergency departments deploy FDA-cleared platforms for same-shift MRSA isolation decisions, reducing transmission risk and bed-blocking costs.
- Culture Media:Chromogenic agar formulations enable phenotypic MRSA identification through selective colony coloration. Remains standard for susceptibility testing reference methods.
- Immunoassays:Enzyme-linked formats process high sample volumes in hospital core laboratories for screening asymptomatic carriers.
Culture Media anchors the volume base through sustained reference laboratory demand while Rapid Tests gain share at the steepest rate via CLIA-waived emergency department adoption.
End User:
Cost tier stratification separates capital-intensive molecular platform adopters from budget-constrained settings reliant on manual methods, with procurement scale determining access to automated tiers.
- Hospitals:Integrated delivery networks consolidate molecular diagnostics procurement across dozens of affiliated sites. United States health systems exceeding $5 billion annual revenue centralize laboratory governance under sole-source platform agreements, compressing vendor margins while accelerating standardization.
- Diagnostic Laboratories:Independent reference laboratories face exclusion from automated molecular tiers due to $150,000-$400,000 upfront PCR system investments. Concentrate on high-throughput immunoassay screening for outpatient surgical pre-admission protocols.
- Research Facilities:Academic medical centers deploy NGS-based surveillance for outbreak investigation and novel resistance mechanism discovery.
- Home Care:Nasal screening for healthcare worker occupational health programs represents nascent direct-to-consumer channel development outside traditional hospital procurement.
Hospitals dominate absolute spending while Diagnostic Laboratories face the steepest competitive pressure from integrated network consolidation.
Technology:
Application urgency dictates technology selection, with turnaround requirements superseding analytical sensitivity in emergency workflows while surveillance applications prioritize genomic resolution.
- Molecular Diagnostics:Nucleic acid amplification platforms detect resistance gene sequences directly from clinical specimens. United Kingdom public health laboratories deploy whole-genome typing for outbreak tracing, creating demand for bioinformatics-integrated workflows.
- NGS:Whole-genome sequencing enables single-nucleotide resolution for transmission mapping and resistance profiling. Represents the technology segment expanding most quickly for epidemiological surveillance applications.
- Microbiological Methods:Traditional culture-based identification and susceptibility testing retains regulatory reference status despite 24-48 hour turnaround limitations.
- Serological Tests:Antibody detection formats occupy niche applications for retrospective infection confirmation and epidemiological seroprevalence studies.
Microbiological Methods retain the largest installed base while NGS climbs the fastest through public health infrastructure investment.
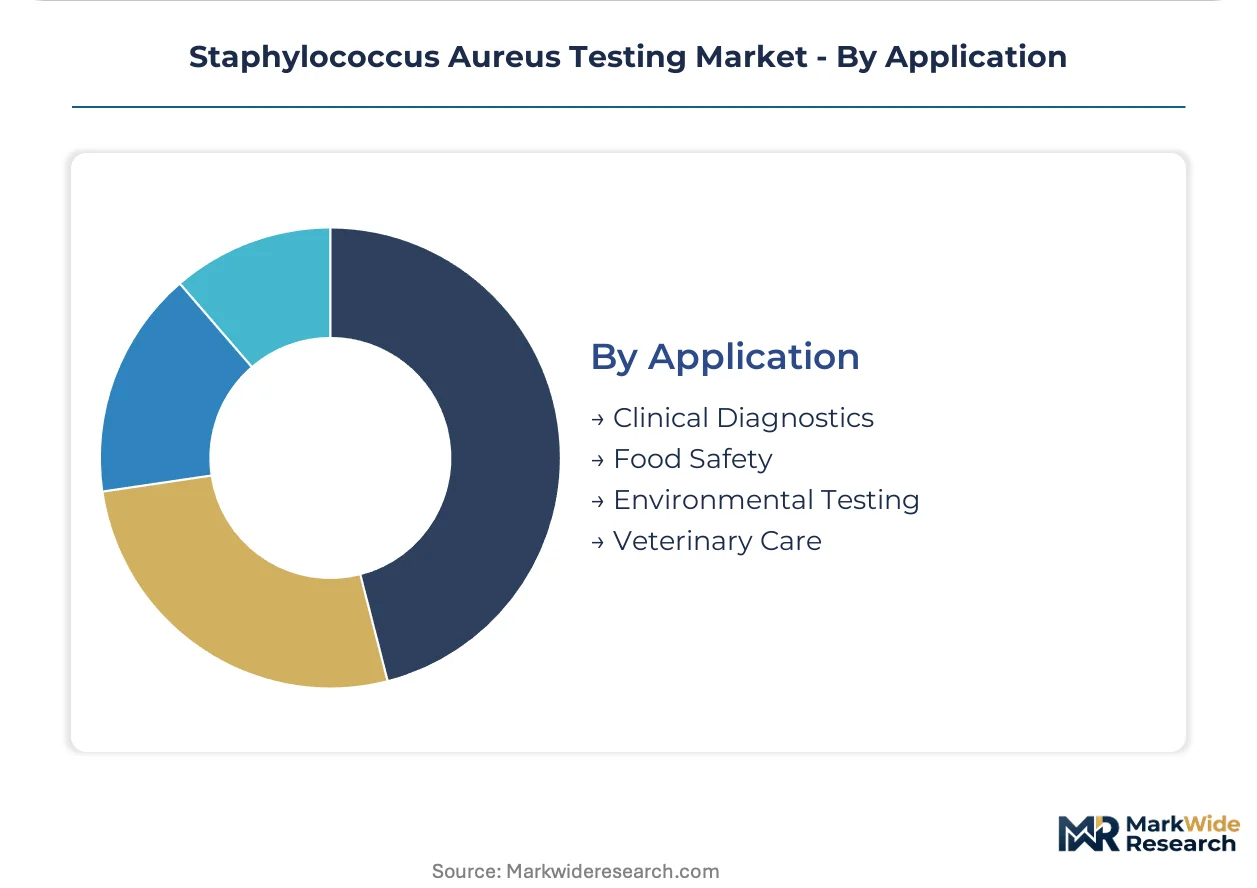
Application:
Customer type fragmentation separates regulated clinical diagnostics from industrial quality control applications, with certification requirements determining vendor market access.
- Clinical Diagnostics:Bloodstream infection protocols drive the most time-sensitive demand, with antimicrobial stewardship programs mandating rapid identification for reimbursement eligibility. FDA 510(k) clearance requirements shape product development roadmaps toward integrated diagnostic-therapeutic decision support.
- Food Safety:Processing facilities test for S. aureus enterotoxin production in ready-to-eat products. United States USDA-FSIS regulations mandate environmental monitoring in high-risk production environments.
- Environmental Testing:Surface sampling in healthcare facilities supports infection control accreditation compliance.
- Veterinary Care:Livestock and companion animal screening addresses zoonotic transmission concerns and agricultural biosecurity protocols.
Clinical Diagnostics commands premium pricing through reimbursement anchoring while Food Safety demonstrates the steepest volume expansion through regulatory testing mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratory consolidation concentrates procurement authority within large integrated delivery networks across major healthcare markets. Buyer archetypes bifurcate sharply between capital-rich tertiary systems and resource-constrained community facilities. Regulatory mandates for rapid pathogen identification reshape investment priorities in acute care settings.
United States
CMS antimicrobial stewardship mandates tie sepsis bundle reimbursement to documented rapid pathogen identification, accelerating molecular platform adoption in acute care settings. The FDA's 2023 updated antimicrobial susceptibility testing guidance imposes expanded clinical trial obligations for novel resistance mechanism detection claims. Integrated delivery networks exceeding $5 billion annual revenue in Texas and California centralize laboratory governance under sole-source diagnostic platform agreements.
Germany
Hospital laboratory consolidation across Baden-Württemberg and Bavaria compresses vendor margins while accelerating automated blood culture system standardization. The EU In Vitro Diagnostic Regulation imposes prospective performance studies on novel resistance gene assays, extending time-to-market for molecular diagnostic kits. The Rhine-Ruhr metropolitan cluster anchors reference laboratory density for high-throughput screening protocols.
United Kingdom
Public health laboratories deploy whole-genome sequencing for outbreak tracing and transmission mapping, creating demand for bioinformatics-integrated testing workflows. NHS antimicrobial stewardship programs mandate rapid identification for bloodstream infection protocols in acute trusts. The Cambridge-Oxford-London golden triangle concentrates NGS surveillance infrastructure and academic medical center research capacity.
China
Tier-2 and Tier-3 cities lack reference laboratory density, creating white space for point-of-care MRSA screening in surgical pre-admission clinics. The National Medical Products Administration strengthens clinical evidence requirements for molecular diagnostic device registration. The Yangtze River Delta cluster around Shanghai anchors high-throughput hospital laboratory investment and diagnostics manufacturing scale.
India
Diagnostic laboratory fragmentation across Maharashtra and Karnataka constrains automated molecular platform penetration outside major metropolitan tertiary centers. The Central Drugs Standard Control Organization implements phased strengthening of in vitro diagnostic quality standards for imported and domestic kits. The Delhi-NCR corridor concentrates corporate hospital chain laboratory networks pursuing enterprise-wide testing standardization.
Staphylococcus Aureus Testing Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with extensive R&D infrastructure and direct hospital contracting capabilities. Market structure exhibits tiered consolidation with molecular diagnostics platforms commanding premium positioning through regulatory clearance depth and integrated workflow design. Strategic archetypes separate into capital-intensive platform developers, automated blood culture specialists, and point-of-care rapid test innovators. Competitive dynamics center on multi-year enterprise agreements displacing transactional instrument sales, alongside middleware development for legacy laboratory information system integration.
Among diversified diagnostics conglomerates, Abbott Laboratories, Thermo Fisher Scientific Inc., and bioMérieux SA occupy positions exemplifying contrasting strategic vectors. Abbott represents the point-of-care testing archetype with cartridge-based platforms designed for emergency department triage workflows. Thermo Fisher exemplifies the molecular diagnostics platform developer with extensive R&D infrastructure and direct hospital contracting scale. bioMérieux sits within the automated blood culture systems tier, differentiating through time-to-result reduction for bloodstream infection protocols. Each anchors a distinct competitive position without direct product overlap, enabling sustained premium positioning across separate hospital laboratory budget lines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Grifols S.A. |
| QIAGEN N.V. |
| bioMérieux SA |
| Cepheid |
| 3M Company |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Capital utilization rates above 80% in automated molecular platform manufacturing anchor price floors across the Staphylococcus aureus testing supply base, concentrating production scale in United States and German facilities while compressing margins for smaller cartridge assemblers serving point-of-care segments.
Pricing Analysis
Multi-year enterprise agreements with cost-plus indexation to raw material baskets dominate procurement between integrated delivery networks and molecular diagnostics vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared PCR platforms from CLIA-waived rapid cartridges and unregulated research-use-only kits. Pricing pressure stems from hospital laboratory consolidation forcing sole-source negotiations across dozens of affiliated sites. Community hospitals and long-term care facilities exhibit highest price sensitivity, while tertiary academic medical centers prioritize turnaround time over per-test cost.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach has elevated inbound logistics costs for thermocycler components and optical detection modules sourced from Chinese contract manufacturers. Final assembly concentrates in the United States, Germany, and China, with specialized reagent production drawing from Singapore and Switzerland. Critical dependencies include Taq polymerase enzymes, fluorescence resonance energy transfer probes, and medical-grade plastics. Single-source vulnerability in CRISPR guide RNA synthesis creates chokepoint exposure. Distribution runs through direct hospital contracting and group purchasing organizations, bypassing traditional distributor markups for high-value platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic workflow fragmentation between centralized molecular hubs and distributed rapid testing nodes creates multiple entry points for specialized players, as turnaround requirements splinter procurement authority between laboratory directors and infection control nurses.
For Market Incumbents: Secure multi-year enterprise agreements with integrated delivery networks before procurement consolidation locks out secondary vendors. Deepen backward integration into reagent manufacturing to offset margin compression from sole-source contracting. Invest in middleware development for legacy laboratory information system integration, as hospital IT fragmentation creates switching costs that defend installed base positions against CRISPR-based point-of-care substitutes. For New Entrants and Emerging Players: Anchor in India's Tier-2 and Tier-3 cities where reference laboratory density remains insufficient for automated molecular platform deployment. Target surgical pre-admission clinics with instrument-free lateral flow formats that bypass capital budget constraints. Pursue occupational health direct-to-consumer channels for healthcare worker screening programs, leveraging CLIA-waived regulatory pathways to circumvent hospital procurement gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform developers with locked-in reagent annuity streams, positioning these archetypes for premium valuation multiples. Prioritize acquisition targets with established FDA 510(k) clearances for resistance gene detection claims, as expanded clinical trial obligations under 2023 guidance raise regulatory barriers for de novo entrants. Watch for inflection in NHS England whole-genome sequencing procurement as signal for NGS surveillance infrastructure buildout acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Sole-source agreements with integrated delivery networks lock out competitors across dozens of affiliated sites. |
| FDA Submission Pathway | 510(k) clearance for novel resistance mechanism claims requires expanded clinical outcome studies under 2023 guidance. |
| Software Companion Development | Bioinformatics-integrated workflows for whole-genome typing address NHS outbreak tracing mandates. |
| CE Marking Pathway | IVDR prospective performance studies extend time-to-market for molecular diagnostic kits entering European Union. |
| Reimbursement Strategy | CMS sepsis bundle documentation requirements tie payment to rapid pathogen identification capability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, infection control officers, biomedical engineers, and group purchasing organization contract managers. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement records, and EU IVDR technical documentation requirements. Bottom-up instrument placement and reagent consumption estimates were triangulated against top-down healthcare expenditure flows.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, end user, technology platform, and application, with geographic granularity to country level. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Key inputs included antimicrobial stewardship mandate implementation timelines, hospital laboratory consolidation patterns, and regulatory clearance pipeline status for novel resistance detection assays.
Material uncertainties — IVDR enforcement variability, CRISPR platform clinical validation outcomes, and integrated delivery network procurement centralization pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement continuity and regulatory pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Global Bioburden Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Blood Borne Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
ATP Assays Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Cholesterol Testing Services Market