
 Drug Testing Market | 2026-2036
Drug Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Testing Market Intelligence
Oral fluid is decoupling drug testing economics from centralized laboratory infrastructure. Quest Diagnostics leverages its national collection network to sustain dominance in federally regulated workplace panels. Abbott Laboratories anchors point-of-care positioning with rapid immunoassay platforms cleared for forensic use.
Drug testing encompasses analytical methods that detect controlled substances, prescription medications, and their metabolites in biological matrices using cutoff concentrations measured in nanograms per milliliter; its primary purpose spans employment compliance, clinical toxicology, and forensic investigation. Immunoassay screens and confirmatory mass spectrometry form a two-tier architecture where rapid tests capture volume and liquid chromatography-mass spectrometry commands premium pricing for legally defensible results. Employers and rehabilitation centers represent structurally different demand pools, with the former prioritizing cost-per-test and turnaround speed while the latter requires comprehensive panels supporting treatment monitoring.
FDA oversees premarket notification for diagnostic devices, while OSHA workplace safety standards and SAMHSA federal guidelines shape employer testing protocols and laboratory certification requirements. The Department of Transportation maintains separate substance abuse professional mandates that create specialized compliance segments distinct from general workplace screening. Stakeholders must monitor how state cannabis legalization cascades into policy fragmentation between zero-tolerance federal contractors and permissive state frameworks.
Market Dynamics
Oral fluid testing is decoupling drug screening economics from centralized laboratory infrastructure, compressing turnaround times from days to minutes while fragmenting procurement authority between HR departments and occupational health clinics.
Growth Catalysts
- DOT Mandate Expansion:The Department of Transportation's 2023 oral fluid testing authorization for federally regulated employers is redirecting volume toward rapid point-of-care platforms in trucking and aviation sectors.
- Synthetic Opioid Surveillance:Fentanyl analog detection requirements in workplace panels are forcing panel expansion across logistics and manufacturing employers seeking insurance premium reductions.
- Clinical Toxicology Integration:Hospital emergency departments are adopting bedside immunoassay readers to accelerate overdose triage decisions, creating dual-use demand pools.
Market Restraints
- Confirmatory Bottleneck:Liquid chromatography-mass spectrometry capacity concentrates in three national laboratory networks, creating 48-72 hour delays for legally defensible results.
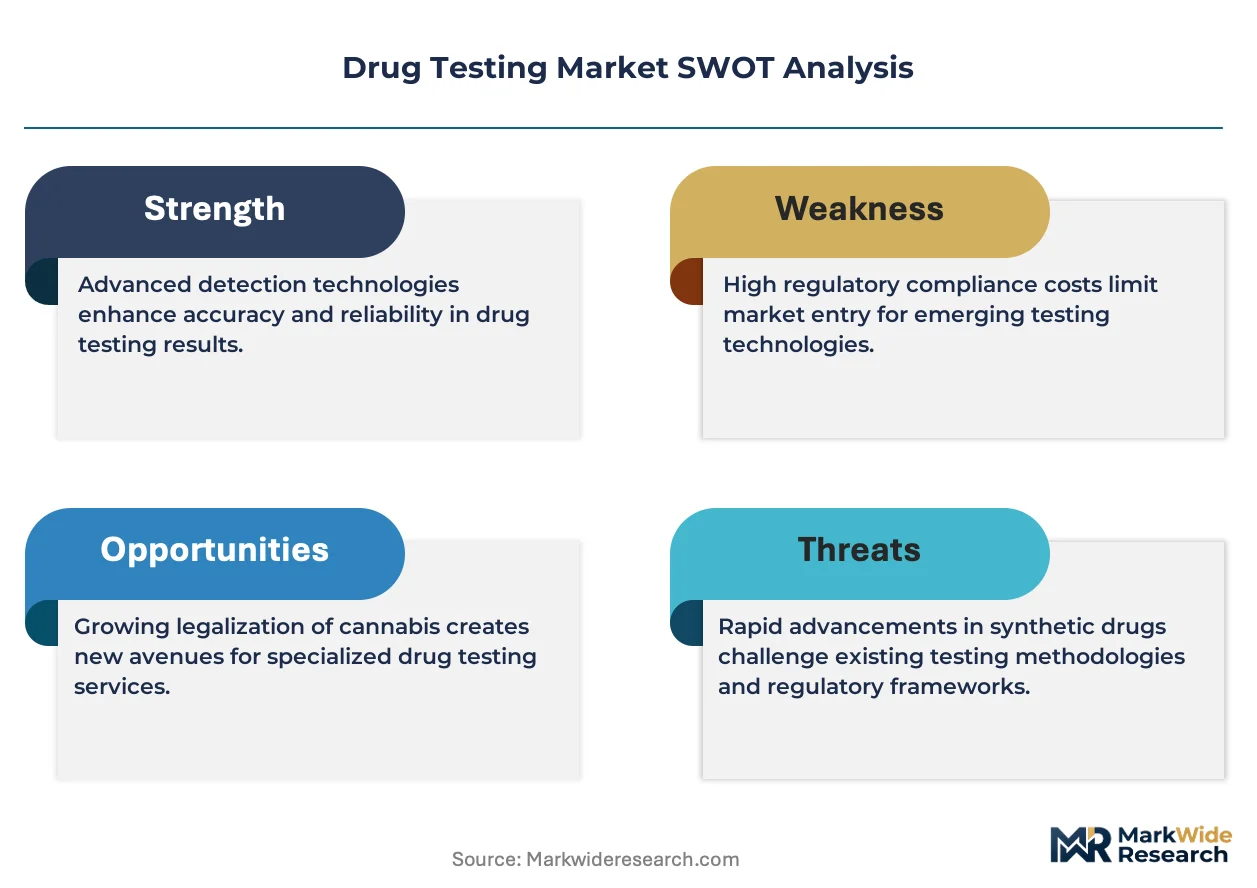
- State Policy Friction:Divergent cannabis testing thresholds between zero-tolerance federal contractors and permissive state frameworks generate compliance fragmentation for multi-state employers.
- Reagent Supply Concentration:Monoclonal antibody production for amphetamine and benzodiazepine assays clusters in single-source bioreactor facilities, exposing immunoassay manufacturers to batch variability risks.
Strategic Opportunities
- Remote Workforce Monitoring:At-home oral fluid collection kits with video-witnessed chain-of-custody protocols are penetrating professional services sectors with distributed employee bases.
- Rehabilitation Panel Expansion:Medication-assisted treatment programs require comprehensive metabolic monitoring, opening recurring revenue streams distinct from one-time employment screens.
- ISO 15189 Accreditation Arbitrage:Laboratories achieving international quality standards are capturing forensic contract work from court systems upgrading evidentiary requirements.
Industry Challenges
- Cross-Reactivity Engineering:Immunoassay developers struggle to eliminate false positives from hemp-derived CBD products, eroding employer confidence in rapid screening results.
- SAMHSA Certification Backlogs:Laboratory accreditation queues for federal workplace testing extend 14-18 months, freezing new entrant participation in regulated panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Testing Market |
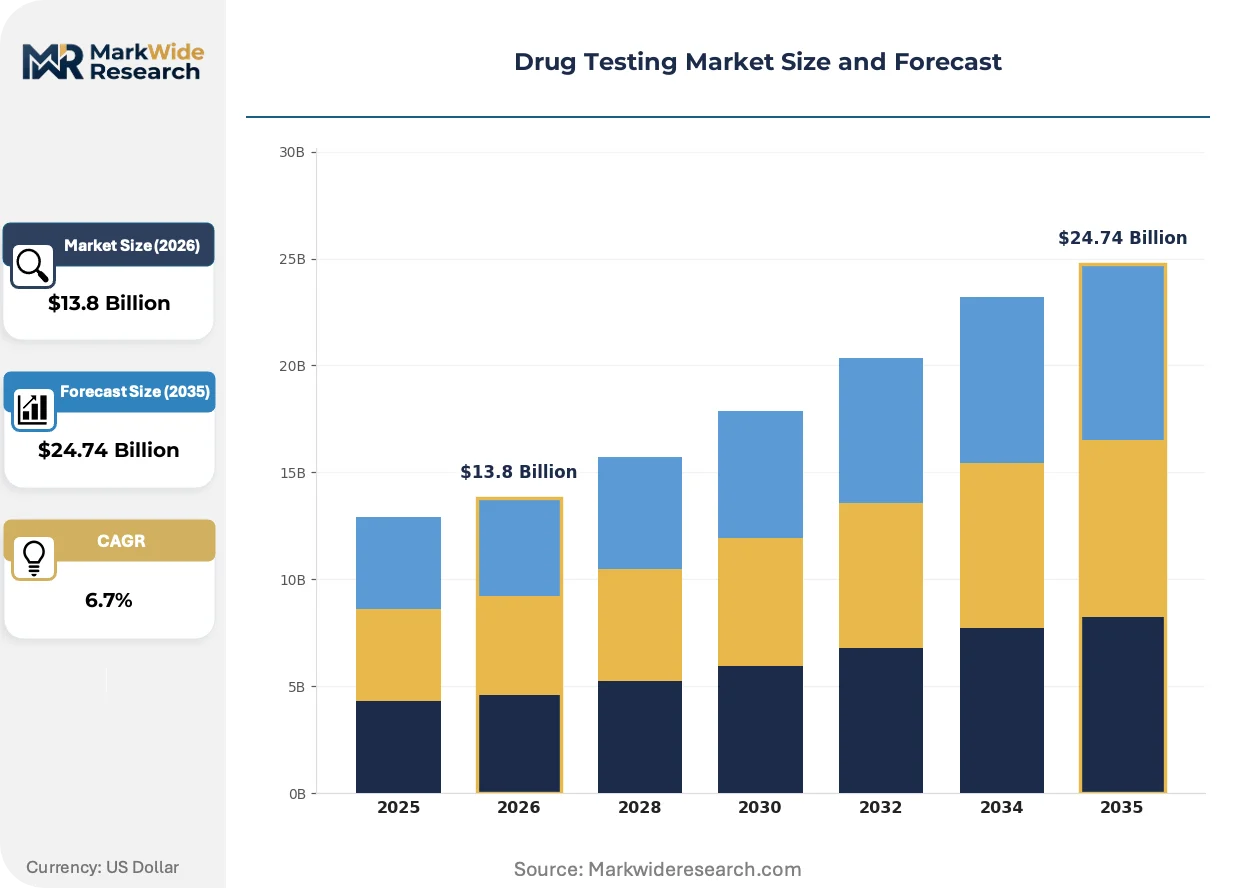
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay, Gas Chromatography, Liquid Chromatography, Mass Spectrometry End User: Hospitals, Laboratories, Rehabilitation Centers, Employers Technology: Rapid Testing, Lab-Based Testing, Oral Fluid Testing, Breathalyzer Sample Type: Urine, Blood, Hair, Saliva |
| Companies Covered | Quest Diagnostics, LabCorp, Abbott Laboratories, Thermo Fisher Scientific, Danaher Corporation, Drägerwerk, Siemens Healthineers, F. Hoffmann-La Roche, Cordant Health Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Testing Market Strategic Shifts & Innovations
Digital chain-of-custody platforms are replacing paper documentation, biometric identity verification is hardening sample integrity protocols, and artificial intelligence is penetrating result interpretation workflows.
Microfluidic cartridge technology is electrifying point-of-care drug testing by integrating sample preparation, reaction chemistry, and optical detection into single-use cassettes. Occupational health clinics and on-site employer testing stations are adopting these platforms to eliminate phlebotomist staffing requirements. The technology is electrifying competitive positioning by collapsing the cost gap between rapid screens and laboratory-based confirmation.
EMA's 2023 In Vitro Diagnostic Medical Devices Regulation (IVDR) reclassification is elevating clinical toxicology assay documentation requirements for CE-marked products entering European markets. Manufacturers face expanded clinical evidence obligations and notified body involvement that were previously waived for professional-use devices. Clinical laboratories in Germany and France are responding by consolidating procurement around IVDR-compliant platforms, accelerating supplier attrition among legacy assay producers.
Subscription-based testing programs are displacing transactional per-test purchasing among mid-sized employers with 500-5,000 employees. Third-party administrators are bundling policy development, collection logistics, and medical review officer services into annual contracts with predictable budgeting. This shift is most visible in United States construction and energy sectors where seasonal hiring volatility complicates traditional volume forecasting.
Drug Testing Market Segmentation
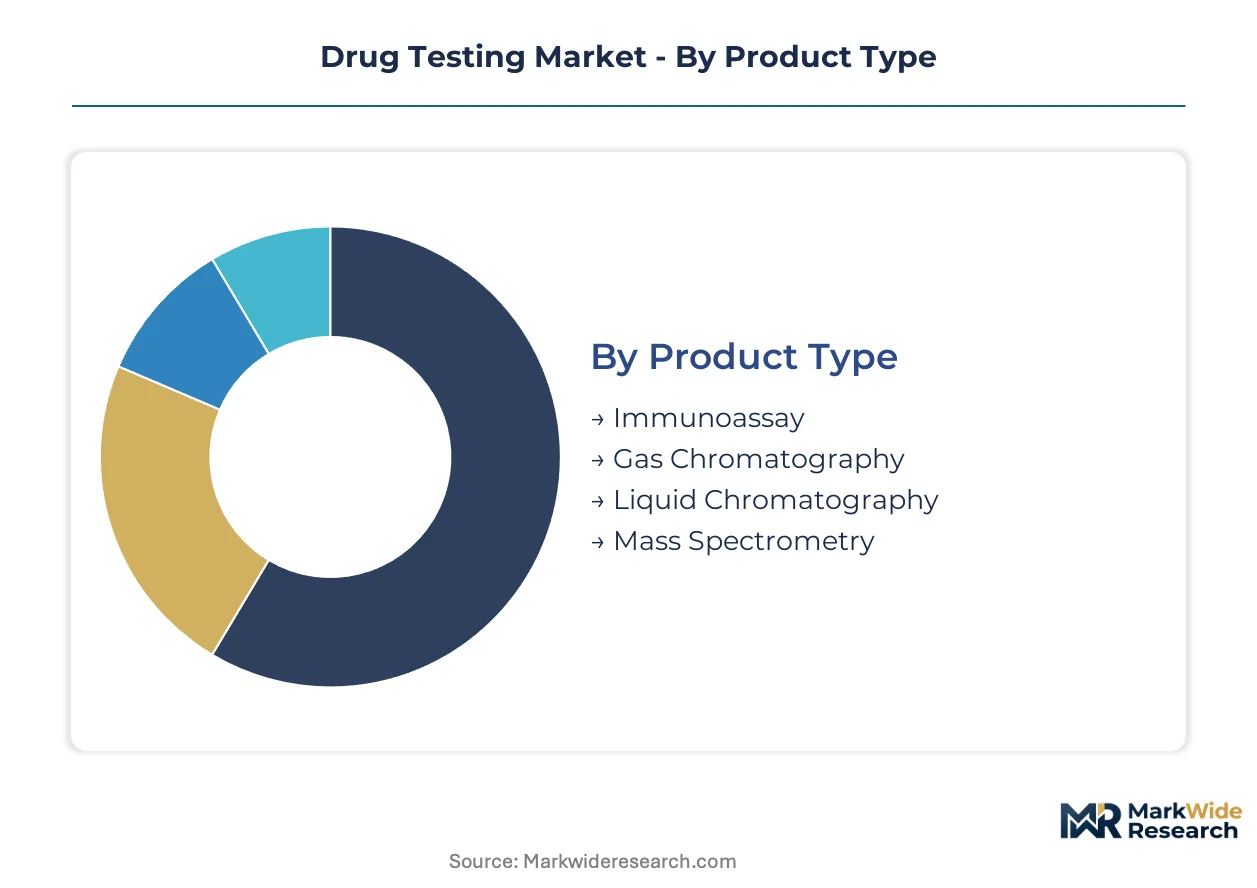
Drug testing segmentation reveals divergent capital requirements across analytical platforms, with mass spectrometry infrastructure demanding multimillion-dollar laboratory investments while rapid immunoassay devices enable distributed point-of-care deployment. Understanding these structural cost tiers helps stakeholders align procurement strategies with testing volume, regulatory stringency, and turnaround requirements.
Product Type:
Capital intensity peaks in chromatography-mass spectrometry systems, where laboratory infrastructure, specialized ventilation, and certified operator training create steep barriers to entry. Immunoassay platforms require comparatively modest upfront investment but incur higher per-test consumable costs at scale.
- Immunoassay:Antibody-based competitive binding assays detect drug classes through colorimetric or chemiluminescent signals. Point-of-care demand concentrates in occupational health clinics serving logistics employers facing DOT-mandated screening obligations. The format dominates volume due to sub-fifteen-minute turnaround and minimal operator training.
- Mass Spectrometry:Tandem quadrupole and time-of-flight systems deliver definitive molecular identification with quantification precision. Forensic laboratories and workplace testing programs requiring legally defensible confirmation drive demand, though instrument costs exceeding $300,000 restrict deployment to centralized reference facilities.
- Liquid Chromatography:Separation technology paired with UV or fluorescence detection supports therapeutic drug monitoring in hospital settings.
- Gas Chromatography:Volatile compound analysis remains concentrated in forensic toxicology for ethanol and inhalant detection.
Most installed capacity flows through Immunoassay. Expansion is steepest in Mass Spectrometry.
End User:
Customer archetypes impose fundamentally different technical specifications, with employers prioritizing cost-per-test minimization and rehabilitation centers demanding comprehensive metabolic panels for treatment compliance monitoring.
- Employers:Corporate wellness and safety departments administer pre-employment, random, and post-incident screening programs. Manufacturing and transportation sectors generate the highest testing frequency, with federal contractor status mandating SAMHSA-certified laboratory partnerships for regulated panels.
- Laboratories:Independent diagnostic facilities and hospital-based toxicology units process samples under CLIA and CAP accreditation frameworks. Capacity constraints in liquid chromatography-mass spectrometry confirmation create 48-72 hour backlogs during volume surges.
- Hospitals:Emergency departments deploy bedside immunoassay readers for overdose triage acceleration.
- Rehabilitation Centers:Medication-assisted treatment programs require recurring metabolic monitoring for compliance verification.
Volume concentrates in Laboratories. Rehabilitation Centers are gaining share fastest.
Technology:
Testing modality selection hinges on the tension between immediacy and evidentiary rigor, with rapid formats sacrificing legal defensibility for speed while laboratory protocols preserve chain-of-custody integrity for contested results.
- Rapid Testing:Lateral flow cassettes and digital readers deliver qualitative results without laboratory infrastructure. On-site employer testing stations and occupational health clinics drive adoption, particularly where same-day hiring decisions compress screening timelines.
- Oral Fluid Testing:Saliva-based collection eliminates privacy concerns and adulteration risks inherent in observed urine collection. The DOT's authorization of oral fluid for federally regulated employers is redirecting trucking and aviation sector volume toward point-of-care platforms.
- Lab-Based Testing:Centralized processing with documented chain-of-custody remains mandatory for forensic and employment litigation contexts.
- Breathalyzer:Exhaled breath analysis for ethanol detection concentrates in law enforcement and transportation safety applications.
Procurement is shifting toward Oral Fluid Testing. Lab-Based Testing retains the largest installed base.
Sample Type:
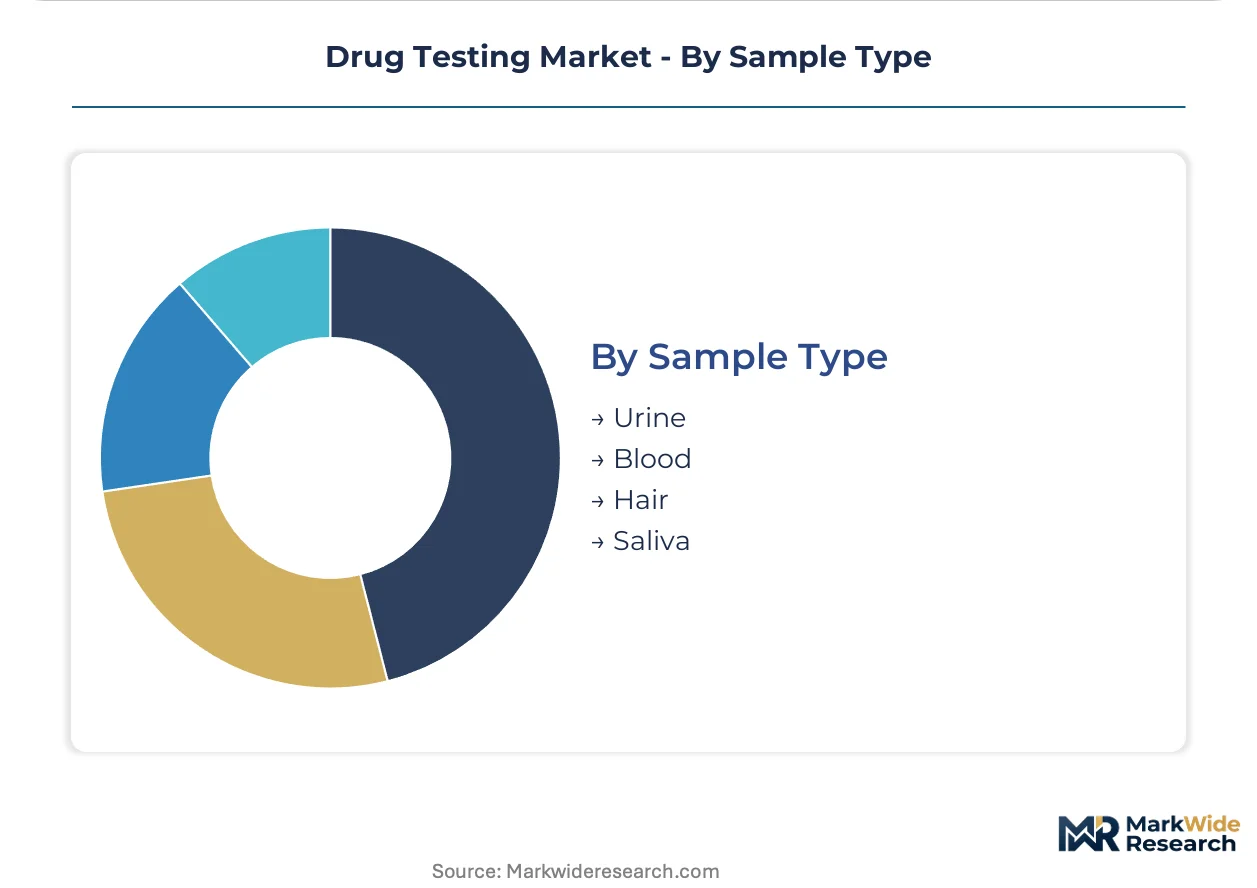
Biological matrix selection determines detection windows, collection logistics, and donor acceptability, with each specimen type presenting distinct adulteration vulnerabilities and analytical interference profiles.
- Urine:The standard matrix for workplace and forensic testing offers extended detection windows for most drug classes. Collection requires observed protocols to prevent substitution, driving privacy litigation and donor reluctance in professional services sectors.
- Saliva:Oral fluid captures parent drug compounds rather than metabolites, narrowing detection windows to recent use. Manufacturing employers with safety-critical positions favor the matrix for identifying impairment rather than historical consumption.
- Blood:Invasive collection limits deployment to clinical toxicology and legal proceedings requiring precise quantification.
- Hair:Keratin analysis provides retrospective detection windows spanning months, serving forensic and child custody investigations.
Sample volume concentrates in Urine. Saliva is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics corridors in the United States generate the highest drug testing procurement volumes worldwide, with federal contractor rules and state-level cannabis legalization creating dual compliance pressures that reshape procurement patterns across transportation, energy, and professional services sectors.
United States
Trucking fleets and aviation maintenance operations drive demand for rapid oral fluid platforms following DOT authorization in 2023. OSHA workplace safety standards and SAMHSA federal guidelines shape employer testing protocols, while state cannabis legalization fragments compliance frameworks between zero-tolerance federal contractors and permissive state regimes. Houston's petrochemical corridor and Atlanta's distribution hub concentrate employer screening volume.
Germany
Industrial manufacturing employers in automotive and chemical sectors expand screening mandates under workplace safety regulations. EMA's 2023 IVDR reclassification elevates clinical toxicology assay documentation requirements, consolidating procurement around compliant platforms. The Rhine-Ruhr industrial belt and Bavaria's automotive clusters anchor laboratory service demand.
United Kingdom
Construction and logistics employers adopt subscription-based testing programs to manage seasonal hiring volatility. Health and Safety Executive guidelines influence workplace screening protocols, while NHS hospital emergency departments deploy bedside immunoassay readers for overdose triage. London's financial services sector and Manchester's logistics hub drive professional services screening adoption.
China
Manufacturing employers in electronics and automotive supply chains implement safety-critical position screening as production scales. NMPA oversight of diagnostic devices shapes product registration pathways for rapid testing platforms. The Yangtze River Delta and Pearl River Delta industrial zones concentrate occupational health clinic procurement.
Japan
Transportation and pharmaceutical employers maintain rigorous screening protocols under METI industrial safety frameworks. PMDA regulatory pathways for in vitro diagnostics influence platform selection for workplace and clinical applications. The Kanto region around Tokyo and Osaka's Kansai industrial zone anchor laboratory and point-of-care deployment.
Drug Testing Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers expand from single-modality offerings into integrated screening-to-confirmation workflows. The market structures around three tiers: national laboratory networks with federally certified capacity, diversified diagnostic conglomerates spanning rapid and laboratory platforms, and specialized point-of-care device manufacturers. Strategic archetypes include volume-driven collection network operators, technology-integrated platform providers, and compliance-focused certification specialists. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire chain-of-custody software capabilities and microfluidic cartridge engineering expertise.
Among United States-based diagnostic service providers, Quest Diagnostics and LabCorp occupy positions as volume-driven collection network operators with federally certified laboratory infrastructure. Abbott Laboratories exemplifies the technology-integrated platform provider archetype, anchoring point-of-care positioning through rapid immunoassay development. These three entities represent distinct strategic postures: service scale, laboratory certification depth, and device technology integration respectively.
| Leading Market Players |
|---|
| Quest Diagnostics |
| LabCorp |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Drägerwerk |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Cordant Health Solutions |
| Others |
Cost & Logistics Intelligence
Microfluidic cartridge electrification is collapsing the cost gap between rapid immunoassay screens and laboratory-based mass spectrometry confirmation, simultaneously fragmenting procurement authority toward occupational health clinics and compressing margins for centralized reference laboratories dependent on high-throughput volume.
Pricing Analysis
Input-cost pass-through from monoclonal antibody production concentrates pricing power among bioreactor operators in Germany and Switzerland. Subscription-based testing programs across mid-sized employers displace per-unit transactional purchasing, with price differentiation hinging on SAMHSA certification tier and medical review officer bundling. Pricing pressure stems from oral fluid point-of-care platforms eliminating phlebotomist staffing costs. Federal contractors exhibit lowest price sensitivity due to litigation-risk premiums; seasonal construction employers show highest sensitivity to per-test economics.
Supply Chain Analysis
Reverse-logistics flows for expired rapid test cassettes and reader calibration returns concentrate refurbishment costs in third-party logistics providers serving Quest Diagnostics and LabCorp networks. Monoclonal antibody production clusters in Germany, Switzerland, and the United States, with reagent supply drawing from single-source bioreactor facilities. Single-source vulnerability in benzodiazepine assay antibodies exposes batch variability risks. Distribution runs through occupational health clinics, third-party administrators, and direct employer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug testing market operates as a regulatory compounder where DOT oral fluid authorization redirects federally regulated employer volume toward point-of-care platforms, amplifying demand inflections from compliance mandate expansions.
For Market Incumbents: Anchor SAMHSA-certified laboratory capacity against oral fluid platform encroachment by deepening backward integration into microfluidic cartridge production. Defend collection network density in Houston's petrochemical corridor and Atlanta's distribution hub against occupational health clinic disintermediation. Certification investment in ISO 15189 accreditation captures forensic contract work from court systems upgrading evidentiary standards.
For New Entrants and Emerging Players: Launch via video-witnessed at-home oral fluid collection kits targeting professional services sectors with distributed remote workforces. White-space penetration concentrates in medication-assisted treatment programs requiring recurring metabolic panels for compliance verification, bypassing one-time employment screen competition. Go-to-market leverage rests on third-party administrator bundling partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among point-of-care device manufacturers lacking chain-of-custody software integration. Long-term viability over the medium-term projection horizon favors platforms spanning rapid screen-to-confirmation workflows. Acquisition target archetype: specialized microfluidic cartridge engineers with FDA 510(k) clearances. Monitor SAMHSA laboratory certification queue lengths as inflection indicator for new entrant participation freezes.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates product commercialization timelines for rapid diagnostic devices entering workplace screening. |
| DOT Oral Fluid Authorization | Redirects federally regulated employer volume toward point-of-care platforms in trucking and aviation. |
| ISO 15189 Accreditation Investment | Captures forensic contract work from court systems upgrading evidentiary requirements. |
| Chain-of-Custody Software Acquisition | Hardens sample integrity protocols against digital documentation substitution risks. |
| Microfluidic Cartridge Engineering | Collapses cost gap between rapid screens and laboratory confirmation for occupational health clinics. |
Research Approach
Bottom-up employer and rehabilitation center demand modeling reconciled against top-down laboratory capacity and reagent production tracking forms the analytical core. Primary interviews with occupational health clinic directors, third-party administrator procurement leads, SAMHSA-certified laboratory operations managers, and medical review officers combined with secondary validation against FDA 510(k) filings, DOT regulatory dockets, SAMHSA laboratory certification databases, and CLIA-accredited facility registries.
Historical trendline analysis of immunoassay and mass spectrometry platform deployment patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include analytical platform type, end-user archetype, testing modality, and biological matrix. CAGRs derived from volume-weighted average of segment-specific growth trajectories calibrated against federal contractor rule expansions and state cannabis policy fragmentation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMHSA certification backlog extensions and monoclonal antibody supply disruptions. Practitioners should monitor DOT oral fluid implementation rates and IVDR compliance timelines for European market entry signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Self-Testing Market
Testing Services
Blood Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Metabolic Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Drug Tester Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Radiographic Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Apoptosis Testing Market