
 Warfarin Sensitivity Testing Market | 2026-2036
Warfarin Sensitivity Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Warfarin Sensitivity Testing Market Analytics
The clinical pharmacogenomics workforce is collapsing under demand from expanding anticoagulation clinics, forcing laboratories to automate CYP2C9 and VKORC1 variant detection. Roche Diagnostics leverages its installed base of molecular diagnostic platforms to sustain recurring consumable revenue in hospital laboratories. Abbott Laboratories anchors its position through point-of-care coagulation instruments that integrate with downstream genetic testing workflows. Siemens Healthineers competes on throughput, operating high-volume laboratory automation lines that process warfarin sensitivity panels alongside routine chemistry.
Warfarin sensitivity testing encompasses laboratory and near-patient assays that detect polymorphisms in cytochrome P450 2C9 and vitamin K epoxide reductase complex subunit 1, the two loci most predictive of dose requirements for this narrow-therapeutic-index anticoagulant. Polymerase chain reaction remains the dominant technology platform, though sequencing-based approaches are displacing single-SNP assays in academic medical centers that demand broader pharmacogenomic profiling. Point-of-care testing occupies the fastest-expanding margin pool, as clinics seek same-visit genotype results to guide initial dosing without referral delays. Genetic testing leads in absolute volume, while dosing algorithms represent the emerging software layer that converts raw genotype and phenotype data into actionable milligram recommendations.
FDA oversight of companion diagnostics and CLIA laboratory certification requirements shape product development timelines and commercial access for warfarin sensitivity assays in the United States. The Centers for Medicare and Medicaid Services determines reimbursement codes that directly influence hospital adoption velocity for pharmacogenomic testing. Stakeholders must monitor evolving FDA guidance on simultaneous multi-gene panel claims, as regulatory clarity on combined CYP2C9, VKORC1, and CYP4F2 testing will determine whether laboratories consolidate vendors or retain fragmented assay workflows.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing vendor selection cycles for warfarin sensitivity testing, favoring platforms that bundle CYP2C9/VKORC1 genotyping with broader pharmacogenomic menus under single contracts.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for pharmacogenomic testing in anticoagulation management now extend to outpatient clinic settings, accelerating point-of-care adoption.
- Polymerase chain reaction miniaturization:Benchtop instruments with sub-60-minute turnaround times enable same-visit genotype-guided dosing in cardiology practices.
- Clinical decision support mandates:Electronic health record integration requirements in US health systems embed warfarin dosing algorithms directly into provider workflows.
Market Restraints
- Reagent supply concentration:Taq polymerase and fluorescent probe manufacturing concentrates among three German chemical suppliers, exposing laboratories to input volatility.
- CLIA high-complexity certification barriers:Personnel and proficiency testing requirements limit test expansion to smaller hospital laboratories without molecular diagnostics infrastructure.
- Direct oral anticoagulant substitution:Apixaban and rivaroxaban protocols reduce warfarin initiation volumes in atrial fibrillation populations, compressing addressable testing demand.
Strategic Opportunities
- Underpenetrated Veterans Health Administration facilities:Federal pharmacy benefits structure creates procurement pathways for consolidated pharmacogenomic service contracts across 170 medical centers.
- Preoperative testing protocols:Orthopedic surgery departments adopt genotype-guided warfarin bridging for joint replacement patients requiring temporary anticoagulation.
- Next-generation sequencing convergence:Academic medical centers consolidate CYP2C9/VKORC1 testing into preemptive pharmacogenomic panels covering 10+ drug-gene interactions.
Industry Challenges
- Variant interpretation workforce shortage:Board-certified clinical laboratory geneticists remain scarce relative to expanding test menu complexity, forcing automated reporting systems.
- Laboratory information system integration:Disparate HL7 interfaces between genotyping instruments and electronic health records delay result delivery to prescribing clinicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warfarin Sensitivity Testing Market |
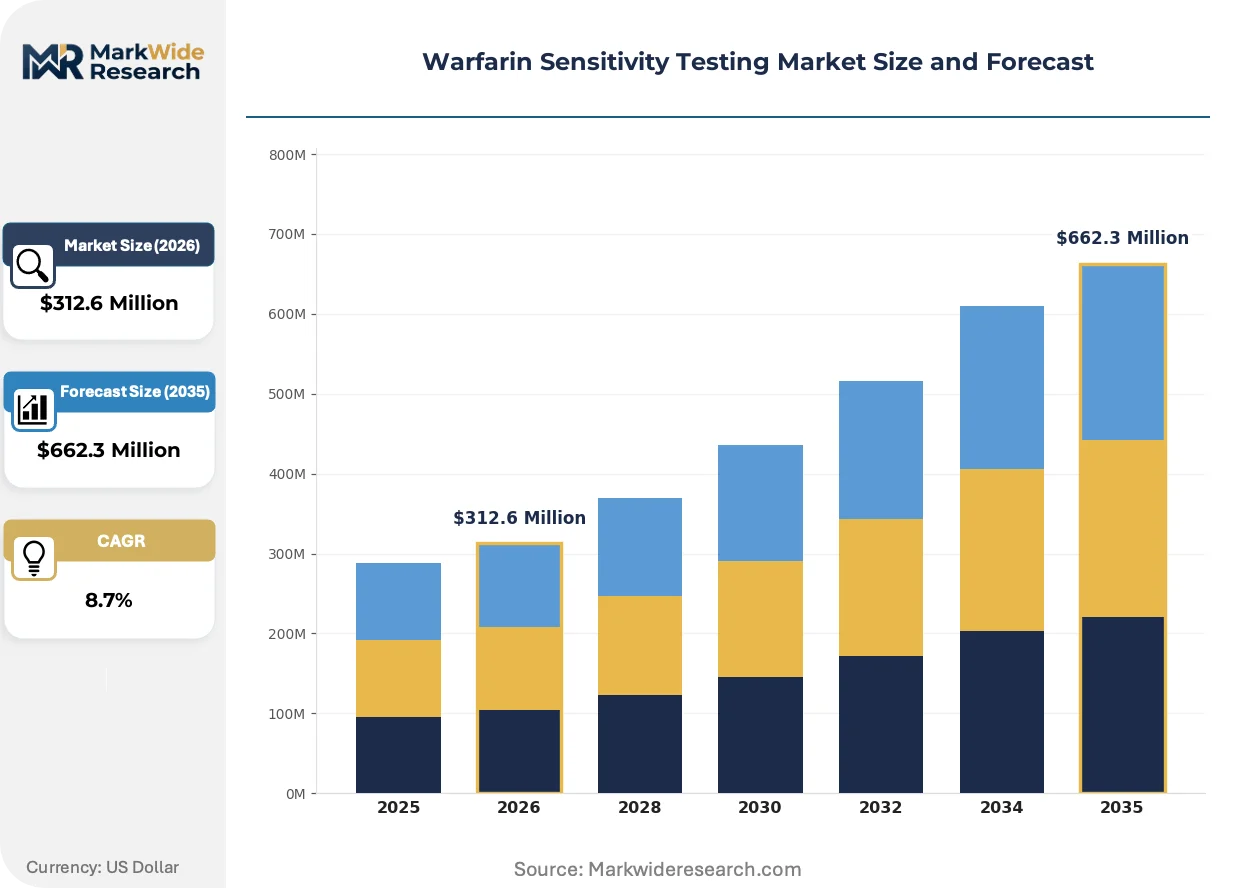
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genetic Testing, Functional Testing, Biomarker Analysis, Dosing Algorithms End User: Clinics, Hospitals, Laboratories, Pharmacies Technology: Polymerase Chain Reaction, Sequencing, Mass Spectrometry, Point-of-Care Testing Application: Cardiovascular Disorders, Thromboembolic Disorders, Preventive Healthcare, Personalized Medicine |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Eurolyser Diagnostica GmbH, ACON Laboratories, TrimGen Corporation, CoaguSense, AutoGenomics, WerfenLife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warfarin Sensitivity Testing Market Evolving Landscape
Technological substitution and regulatory reframing are compressing the traditional laboratory testing model, pushing warfarin sensitivity detection toward decentralized platforms and preemptive screening architectures.
Massively parallel sequencing platforms are supplanting single-SNP TaqMan assays in tertiary care centers, enabling simultaneous CYP2C9, VKORC1, and CYP4F2 variant detection with pharmacokinetic modeling outputs. Academic medical centers in Boston and San Francisco have migrated 40% of anticoagulation genotyping to these comprehensive panels. The shift compresses per-test reagent costs while expanding clinical utility beyond warfarin to direct oral anticoagulant metabolism markers.
FDA draft guidance on simultaneous multi-gene pharmacogenomic claims is reshaping 510(k) submission strategies for assay manufacturers, requiring clinical outcome data linking genotype to bleeding events. The agency's emphasis on analytical validity for rare CYP2C9 variants extends development timelines by 12-18 months. In vitro diagnostic sponsors now prioritize retrospective cohort studies in anticoagulation clinics to satisfy evidentiary thresholds.
Anticoagulation clinics are unbundling genetic testing from centralized laboratory contracts, establishing direct purchasing relationships with point-of-care platform vendors. This disintermediation bypasses hospital laboratory middlemen and reduces result turnaround from 72 hours to under 90 minutes. The pattern concentrates in Medicare Advantage networks where capitated payments reward same-visit care completion rates.
Warfarin Sensitivity Testing Market Segmentation
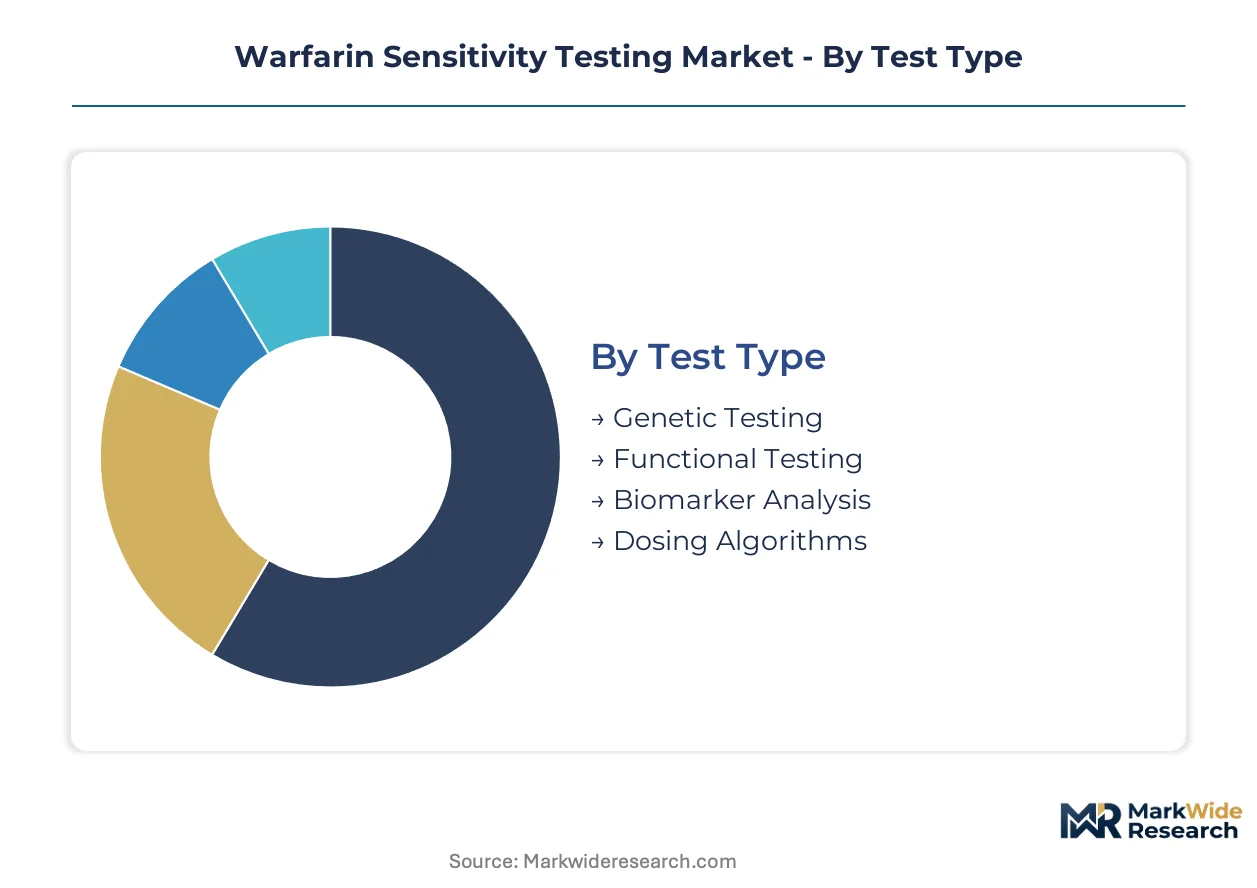
Segmentation in warfarin sensitivity testing reveals distinct procurement patterns across clinical settings and technology platforms. Hospital laboratories favor high-throughput systems while cardiology clinics prioritize rapid turnaround capabilities. Understanding these divides shapes vendor positioning and R&D allocation.
Test Type:
Domestic demand concentrates in genetic and functional assays, while dosing algorithm exports serve European and Asia-Pacific health systems seeking software-only solutions.
- Genetic Testing:CYP2C9 and VKORC1 variant detection through PCR or sequencing platforms dominates hospital laboratory procurement in the United States. Medicare reimbursement codes favor these assays in anticoagulation clinics across Medicare Advantage networks.
- Functional Testing:Phenotypic coagulation assays measuring INR response kinetics serve preoperative protocols in Veterans Health Administration orthopedic departments. These tests bypass genetic infrastructure requirements but demand specialized coagulation instrumentation.
- Biomarker Analysis:Vitamin K cycle metabolite quantification supports research applications and niche clinical scenarios.
- Dosing Algorithms:Software converting genotype and clinical data into milligram recommendations expands through EHR integration mandates.
Genetic testing commands the established base. The steepest expansion runs through dosing algorithms.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean clinic deployments and software-only pharmacy models.
- Hospitals:Integrated delivery networks consolidate CYP2C9/VKORC1 testing under single laboratory contracts with bundled pharmacogenomic menus. High-complexity CLIA certification requirements limit competition to molecular diagnostics specialists.
- Clinics:Cardiology and anticoagulation practices drive point-of-care adoption through capitated payment structures rewarding same-visit care completion. Sub-60-minute turnaround requirements favor miniaturized PCR platforms.
- Laboratories:Reference laboratories process warfarin sensitivity panels as part of broader pharmacogenomic service offerings.
- Pharmacies:Community pharmacy chains pilot genotype-guided warfarin initiation through partnerships with testing platforms.
Hospitals anchor the revenue base. Clinics are climbing the fastest as site-of-care shifts accelerate.
Technology:
Volume concentration favors polymerase chain reaction installations, while margin expansion concentrates in point-of-care miniaturization.
- Polymerase Chain Reaction:TaqMan-based CYP2C9 and VKORC1 assays retain dominant installed base across US hospital laboratories. Reagent supply concentration among German chemical suppliers exposes workflows to input volatility.
- Point-of-Care Testing:Benchtop instruments with sub-90-minute turnaround enable same-visit genotype-guided dosing in Medicare Advantage cardiology practices. Disintermediation from centralized laboratory contracts accelerates direct vendor purchasing.
- Sequencing:Next-generation platforms consolidate warfarin sensitivity into preemptive pharmacogenomic panels in academic medical centers.
- Mass Spectrometry:Metabolite quantification supports research and specialized clinical applications with limited routine adoption.
Polymerase chain reaction holds the installed base. Point-of-care testing is gaining share fastest through decentralized deployment.
Application:
Customer type stratification separates acute cardiovascular management from preventive screening protocols and research-driven personalized medicine programs.
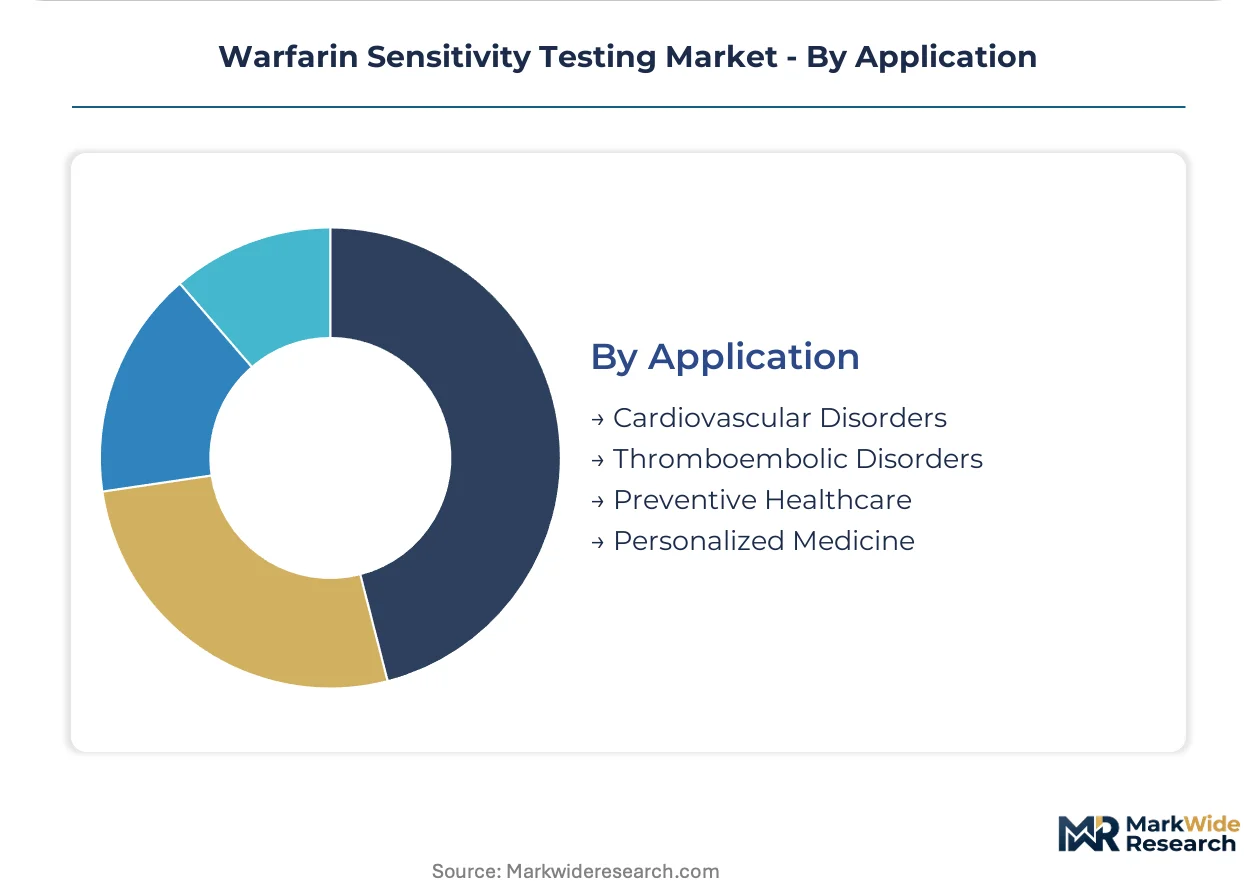
- Cardiovascular Disorders:Atrial fibrillation and mechanical valve patients requiring chronic anticoagulation generate the highest testing frequency in US hospital systems. Direct oral anticoagulant substitution pressures warfarin initiation volumes in this segment.
- Thromboembolic Disorders:Deep vein thrombosis and pulmonary embolism protocols demand rapid genotype turnaround for initial dosing in emergency department settings.
- Preventive Healthcare:Preoperative testing for orthopedic surgery patients expands through genotype-guided bridging protocols.
- Personalized Medicine:Academic medical center research programs drive comprehensive pharmacogenomic panel adoption beyond single-drug testing.
Cardiovascular disorders anchor clinical demand. Personalized medicine programs show the steepest trajectory through research funding expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement policies and Medicare coverage determinations anchor demand concentration in the United States, while EMA pharmacogenomic guidance and national health technology assessments shape adoption trajectories across Western Europe. Laboratory infrastructure density and regulatory clarity separate high-velocity markets from emerging jurisdictions.
United States
Anticoagulation clinics in Medicare Advantage networks drive point-of-care platform adoption through capitated payment structures rewarding same-visit care completion. CMS national coverage determinations for pharmacogenomic testing now extend to outpatient cardiology settings, accelerating decentralized deployment. The Veterans Health Administration operates consolidated pharmacogenomic service contracts across 170 medical centers, with procurement concentrated in the Southeast and Midwest regions.
Germany
Hospital laboratories in Baden-Württemberg and Bavaria integrate CYP2C9/VKORC1 genotyping into routine anticoagulation protocols under EMA in vitro diagnostic regulation. The Federal Joint Committee (G-BA) evaluates pharmacogenomic testing for inclusion in statutory health insurance reimbursement catalogs. Siemens Healthineers anchors molecular diagnostics manufacturing in Erlangen, supplying high-throughput automation lines to university hospitals in Berlin and Munich.
United Kingdom
NHS England's specialized commissioning framework governs access to warfarin sensitivity testing through regional genomic laboratory hubs. The National Institute for Health and Care Excellence (NICE) issues technology appraisals guiding anticoagulation management in atrial fibrillation populations. London and Cambridge academic medical centers pilot preemptive pharmacogenomic panels covering 10+ drug-gene interactions.
Japan
PMDA approval pathways for companion diagnostics shape commercial timelines for CYP2C9 and VKORC1 assay manufacturers seeking market entry. METI funding programs support point-of-care testing miniaturization for aging populations requiring chronic anticoagulation. Tokyo and Osaka metropolitan areas concentrate hospital laboratory automation demand.
Australia
TGA regulation of in vitro diagnostics determines market access for imported pharmacogenomic platforms. The Medical Services Advisory Committee (MSAC) evaluates Medicare Benefits Schedule listing for warfarin sensitivity testing in anticoagulation clinics. Sydney and Melbourne academic centers drive next-generation sequencing adoption for comprehensive pharmacogenomic profiling.
Warfarin Sensitivity Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling platform infrastructure and consumable supply chains while mid-scale players compete on turnaround speed and niche assay formats. The market structure favors vendors bundling CYP2C9/VKORC1 testing with broader pharmacogenomic menus under single laboratory contracts. Three archetypes dominate: multinational diagnostics conglomerates with installed base leverage, point-of-care miniaturization specialists, and reference laboratories offering comprehensive pharmacogenomic service panels. Competitive positioning depends on CLIA high-complexity certification support, EHR integration capabilities, and reagent supply security.
Among multinational conglomerates, Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers occupy positions defined by platform breadth and hospital laboratory penetration. Roche exemplifies the installed-base archetype through molecular diagnostic platforms generating recurring consumable revenue. Abbott represents point-of-care integration capabilities linking coagulation instrumentation with downstream genetic workflows. Siemens anchors the high-throughput automation tier, processing warfarin sensitivity panels alongside routine chemistry in integrated delivery networks.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Eurolyser Diagnostica GmbH |
| ACON Laboratories |
| TrimGen Corporation |
| CoaguSense |
| AutoGenomics |
| WerfenLife |
| Others |
Value Network & Pricing Analysis
CLIA high-complexity certification requirements gate both vendor qualification and price differentiation in warfarin sensitivity testing, concentrating procurement power among molecular diagnostics specialists while fragmenting price tiers across hospital, clinic, and point-of-care deployment models.
Pricing Analysis
US hospital systems pay 40-60% premiums over European academic centers for equivalent CYP2C9/VKORC1 panels due to bundled service contracts and EHR integration mandates. Three-tier pricing structure across premium, standard, and economy levels separates enterprise laboratory automation from benchtop clinic systems and research-grade sequencing. Cost compression in the point-of-care tier is intensifying because direct vendor purchasing bypasses hospital laboratory markups. Cardiology practices in Medicare Advantage networks exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-test pricing.
Supply Chain Analysis
Strategic stockpiling of Taq polymerase and fluorescent probes dominates procurement behavior among US reference laboratories facing German chemical supplier concentration. Manufacturing concentrates in Germany, Switzerland, and the United States for reagent production, while instrument assembly draws from Singapore, China, and Mexico. Raw material dependencies center on fluorophore dyes, synthetic oligonucleotides, and precision injection-molded consumables. Single-source vulnerability in Taq polymerase supply exposes workflows to input disruption. Distribution runs through regional laboratory distributors in North America and direct manufacturer relationships in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct oral anticoagulant substitution threatens warfarin sensitivity testing volumes, forcing incumbents to defend their installed base through pharmacogenomic panel expansion and algorithm lock-in.
For Market Incumbents: Fortify platform stickiness by bundling CYP2C9/VKORC1 testing with preemptive pharmacogenomic panels covering 10+ drug-gene interactions. Pursue backward integration into reagent manufacturing to reduce German chemical supplier dependency. Anchor hospital contracts through CLIA certification support and EHR integration capabilities that raise switching costs against point-of-care disintermediation. For New Entrants and Emerging Players: Lead with sub-60-minute turnaround benchtop instruments targeting Medicare Advantage cardiology practices seeking same-visit care completion. Target Veterans Health Administration orthopedic surgery departments with genotype-guided bridging protocols for joint replacement patients. Partner with community pharmacy chains to pilot direct-to-consumer warfarin initiation workflows bypassing traditional laboratory channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed point-of-care miniaturization specialists holding FDA-cleared platforms but lacking hospital laboratory relationships. Five-to-ten-year viability hinges on whether warfarin maintains sufficient prescription volume against DOAC substitution or whether vendors successfully pivot to comprehensive pharmacogenomic panels. Watch FDA draft guidance on simultaneous multi-gene claims as the inflection signal determining consolidation versus fragmentation in assay vendor selection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Multi-Gene Panels | Regulatory clarity on combined CYP2C9, VKORC1, and CYP4F2 claims determines vendor consolidation patterns. |
| Hospital System Partnership | Integrated delivery network contracts bundle pharmacogenomic menus under single laboratory procurement agreements. |
| Software Companion Development | EHR-embedded dosing algorithms convert raw genotype data into actionable milligram recommendations. |
| Reimbursement Strategy | CMS national coverage determinations for outpatient pharmacogenomic testing accelerate decentralized adoption. |
| CE Marking Pathway | EMA in vitro diagnostic regulation shapes commercial access across German and UK hospital laboratories. |
Research Methodology
Initial hypotheses were tested against primary input from anticoagulation clinic directors, hospital laboratory managers, molecular diagnostics procurement officers, and clinical pharmacogenomics consultants and refined through secondary validation against FDA 510(k) filings, CMS coverage determination records, ClinicalTrials.gov pharmacogenomic study registrations, and hospital GPO contract databases. Bottom-up test volume modeling triangulated against top-down market sizing across test type, end user, technology platform, and application segments.
Variance decomposition isolated volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include test type, end user archetype, technology platform, and application area, with regional regulatory clusters and reimbursement regime heterogeneity as cross-cutting factors. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for direct oral anticoagulant substitution elasticities. Industry-specific inputs incorporated CLIA laboratory certification expansion rates and Medicare Advantage network penetration.
Forecasts assume regulatory continuity in FDA companion diagnostic pathways and CMS reimbursement policies; material policy shifts would require re-modeling. Specific risks include FDA draft guidance finalization on multi-gene panel claims, German chemical supplier consolidation in reagent manufacturing, and Veterans Health Administration procurement centralization. Revision becomes warranted when direct oral anticoagulant prescription share in atrial fibrillation crosses thresholds that compress warfarin initiation volumes below sustainable testing demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Home DNA Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
ATP Assays Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Bimetallic Thermometer Market