
 Global Legionella Testing Market | 2026-2036
Global Legionella Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Legionella Testing Market Foresight
ISO-certified assay precision is rotating toward the center of procurement decisions for large-scale water safety programs. Thermo Fisher Scientific leverages its PCR platform breadth to dominate reference laboratory contracts across North America. bioMérieux sustains competitive positioning through specialized culture media formulations that meet European pharmacopeia standards. Abbott anchors hospital-based testing workflows with integrated immunoassay systems designed for rapid turnaround.
Legionella testing encompasses laboratory and point-of-use diagnostic methods for detecting viable and non-viable cells of Legionella pneumophila and related species in environmental water samples, respiratory specimens, and biofilm matrices, typically employing nucleic acid amplification with detection thresholds below ten colony-forming units per milliliter or selective culture on buffered charcoal yeast extract agar with cysteine supplementation. PCR Technology leads the technology segment due to its specificity for serogroup differentiation and compatibility with high-throughput laboratory automation. Environmental Testing Labs occupy the deepest margin pools within the end-user landscape, as regulatory compliance mandates generate recurring specimen volumes from cooling towers and potable water distribution networks.
The EPA's Safe Drinking Water Act guidance, the EU Drinking Water Directive, and ISO 11731 culture standards collectively shape product validation requirements and market access pathways for assay manufacturers. FDA-cleared in vitro diagnostic platforms face additional clinical validation hurdles when laboratories seek to extend environmental test kits to respiratory specimen applications. Stakeholders must monitor evolving harmonization between environmental monitoring protocols and clinical diagnostic regulations to anticipate portfolio repositioning requirements.
Market Dynamics
EPA's Safe Drinking Water Act guidance revision is compelling building operators to replace culture-based methods with molecular detection platforms, fundamentally restructuring assay procurement criteria across water safety programs.
Growth Catalysts
- Cooling tower regulatory mandates:The EPA's revised Legionella guidance under the Safe Drinking Water Act now requires routine screening in healthcare facilities, generating recurring specimen volumes from potable water distribution networks.
- PCR platform automation:High-throughput laboratory automation compatibility is driving reference laboratories to consolidate testing contracts onto nucleic acid amplification systems capable of serogroup differentiation.
- Aging infrastructure colonization risks:United States municipal water systems with deteriorating pipe networks create persistent biofilm habitats that sustain environmental surveillance demand.
Market Restraints
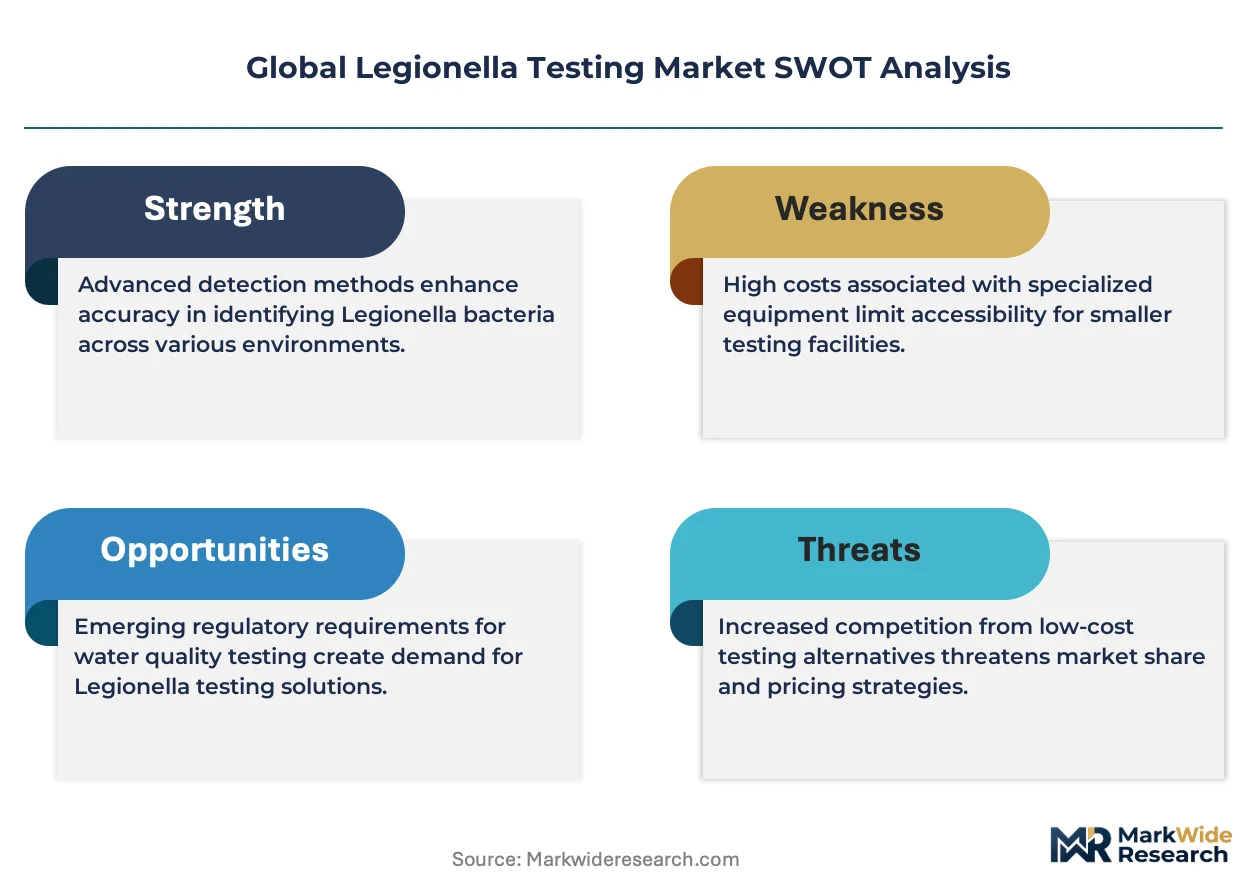
- ISO 11731 culture standard compliance costs:Buffered charcoal yeast extract agar with cysteine supplementation requires specialized laboratory infrastructure and trained microbiologists, elevating operational fixed costs for smaller environmental testing facilities.
- FDA clinical-environmental assay harmonization friction:In vitro diagnostic platforms cleared for respiratory specimens face additional validation hurdles when laboratories seek to extend kits to environmental water applications, fragmenting product development roadmaps.
- Culture method substitution pressure:Selective culture on specialized media retains regulatory acceptance for viability confirmation, slowing complete displacement by rapid molecular methods despite longer turnaround times.
Strategic Opportunities
- Point-of-use detection integration:Building management systems in United States hospitals are embedding continuous monitoring sensors into cooling tower infrastructure, creating demand for automated alert protocols.
- EU Drinking Water Directive expansion:European pharmacopeia standards for specialized culture media are opening procurement pathways for assay manufacturers with existing CE-marked platforms.
- Digital PCR serogroup quantification:Absolute quantification technology convergence with cloud-based laboratory information systems is enabling remote result verification for distributed water safety networks.
Industry Challenges
- Dual-competency workforce scarcity:Environmental microbiologists with simultaneous expertise in molecular assay validation and traditional culture techniques command premium compensation, constraining laboratory expansion timelines.
- Clinical-environmental protocol reconciliation:Laboratories must maintain parallel quality systems for FDA-cleared respiratory applications and EPA-guided environmental monitoring, duplicating documentation and audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Legionella Testing Market |
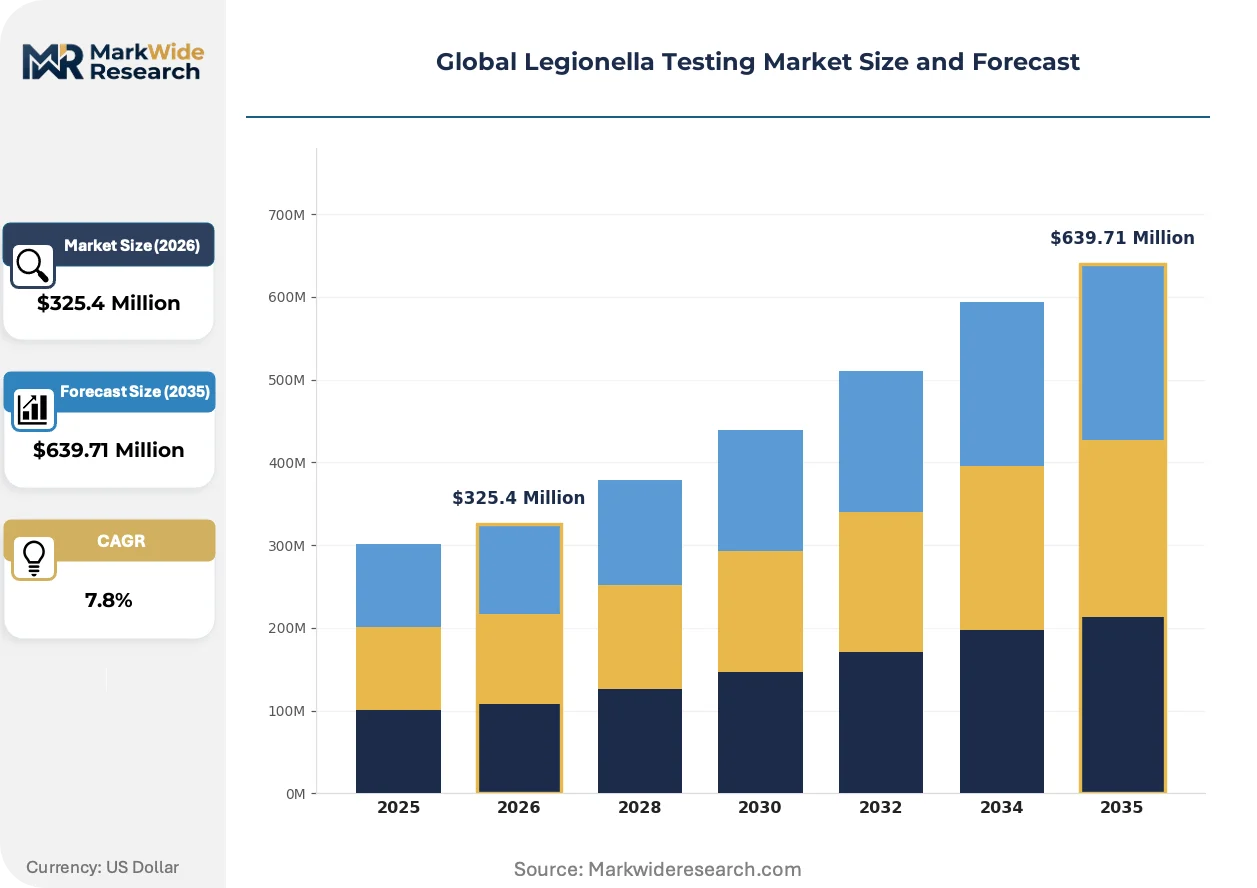
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $639.71 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction Kits, Culture Media, Immunoassay Kits, Rapid Test Strips, DNA Sequencing Tools Technology: PCR Technology, Immunofluorescence, ELISA, Dot Blot, Biosensors Application: Water Treatment Facilities, Cooling Towers, HVAC Systems, Public Fountains, Commercial Buildings End User: Environmental Testing Labs, Municipal Water Authorities, Hospitality Operators, Facility Management Companies, Research Institutes |
| Companies Covered | Thermo Fisher Scientific, Abbott, Merck KGaA, bioMérieux, Becton Dickinson and Company, Bio-Rad Laboratories, IDEXX Laboratories, Eurofins Scientific, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Legionella Testing Market Shifts & Advancements
Detection methodology is fragmenting across viability-confirmation and rapid-screening pathways, with regulatory acceptance lagging technological capability. This divergence is reshaping capital allocation priorities among assay developers and testing service providers.
Digital PCR platforms with absolute quantification capability are bifurcating the reference laboratory segment. Large hospital networks in the United States are adopting these systems for cooling tower surveillance programs. The technology is bifurcating procurement decisions between high-throughput centralized laboratories and distributed point-of-need configurations.
The EU Drinking Water Directive's updated microbiological parameters are mandating Legionella surveillance in public buildings across member states. This regulatory expansion is compelling assay manufacturers to recalibrate product validation roadmaps for CE-marked environmental kits. Germany and France are accelerating implementation timelines, forcing portfolio prioritization shifts away from clinical-only platforms.
Building operators are consolidating testing contracts with environmental laboratories offering integrated sampling logistics and digital reporting portals. This channel compression is displacing smaller regional providers lacking nationwide sampling networks. The United States healthcare facility sector exhibits the most pronounced contract consolidation, with multi-site hospital systems negotiating enterprise-level water safety agreements.
Global Legionella Testing Market Segmentation
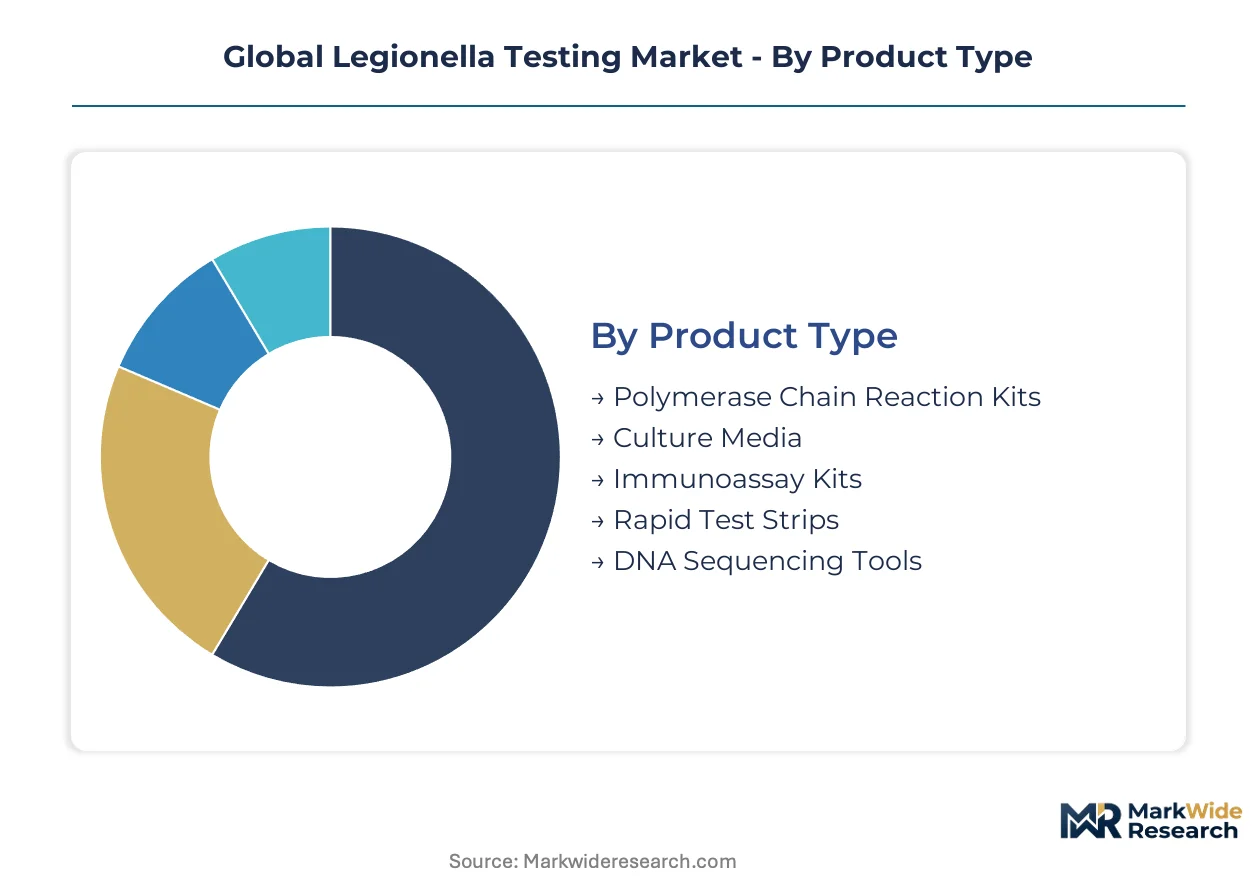
Legionella testing procurement varies sharply across product formats and user workflows. Segment boundaries determine margin capture, with environmental compliance mandates concentrating demand in specific technology and end-user configurations.
Product Type:
PCR kits and culture media dominate export flows to regulated markets, while rapid test strips serve domestic maintenance programs in cost-sensitive regions.
- Polymerase Chain Reaction Kits:Nucleic acid amplification systems detect serogroup-specific DNA sequences with thresholds below ten colony-forming units per milliliter. Reference laboratories in Germany and France are consolidating procurement onto automated PCR platforms for cooling tower surveillance programs.
- Culture Media:Buffered charcoal yeast extract agar with cysteine supplementation remains the ISO 11731 viability confirmation standard. United States hospital systems maintain parallel culture capacity despite molecular method adoption, sustaining demand for European pharmacopeia-certified formulations.
- Immunoassay Kits:Antigen detection systems serve point-of-need screening in facility management workflows.
- Rapid Test Strips:Lateral flow devices enable field technicians without laboratory infrastructure to execute preliminary assessments.
- DNA Sequencing Tools:Whole-genome platforms support outbreak investigation and strain comparison in public health reference centers.
PCR kits hold the largest share; momentum sits with rapid test strips.
Technology:
Cost tiers separate centralized laboratory automation from portable field applications, with capital intensity determining geographic penetration patterns.
- PCR Technology:Thermal cycling platforms with fluorescent probe detection enable serogroup differentiation and high-throughput batch processing. United States multi-site hospital networks are embedding PCR-based surveillance into enterprise water safety agreements.
- Immunofluorescence:Direct fluorescent antibody staining requires specialized microscopy infrastructure and trained technologists.
- ELISA:Enzyme-linked immunosorbent assays offer quantitative antigen detection for environmental monitoring laboratories.
- Dot Blot:Membrane-based antibody detection serves resource-constrained settings with minimal equipment requirements.
- Biosensors:Electrochemical and optical transducer systems are gaining share fastest for continuous cooling tower monitoring applications.
PCR technology commands premium positioning; biosensors are climbing the fastest.
Application:
Customer type fragmentation splits the market between regulatory-mandated infrastructure and voluntary preventive maintenance programs.
- Water Treatment Facilities:Municipal disinfection plants require incoming and outgoing stream monitoring to verify Legionella inactivation. Japan's METI guidelines are accelerating automated sampler deployment at treatment works serving healthcare districts.
- Cooling Towers:Evaporative heat rejection systems create optimal aerosolization conditions for Legionella transmission. United States healthcare facility managers face EPA Safe Drinking Water Act screening obligations that generate recurring specimen volumes.
- HVAC Systems:Air handling units with humidification components require seasonal testing protocols.
- Public Fountains:Decorative water features in urban spaces present intermittent exposure risks requiring event-driven assessment.
- Commercial Buildings:Office and retail properties implement voluntary testing beyond regulatory minimums for liability mitigation.
Cooling towers hold the largest share; momentum sits with HVAC systems.
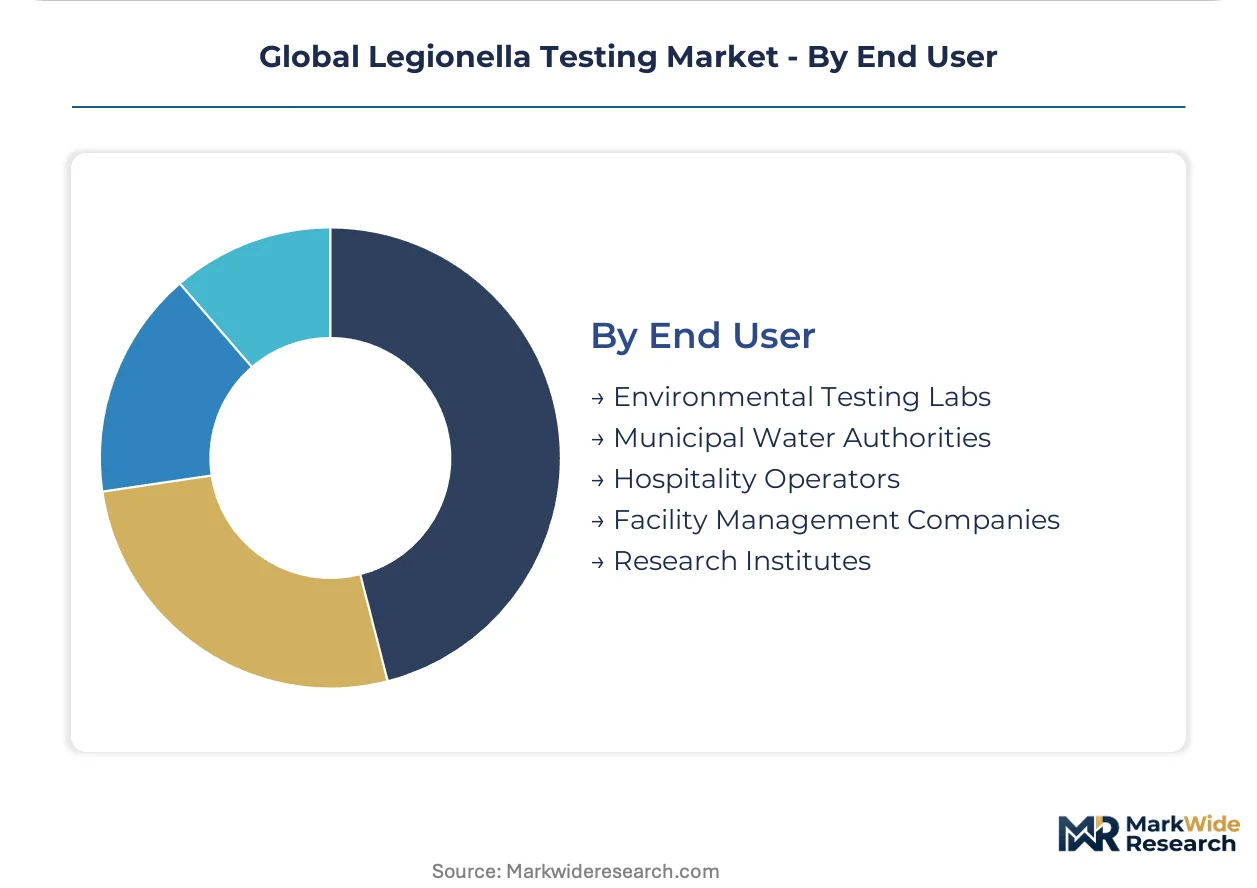
End User:
Maturity gradients separate established compliance-driven laboratories from emerging facility management service providers.
- Environmental Testing Labs:ISO 17025-accredited facilities execute EPA and EU Drinking Water Directive protocols with documented chain-of-custody procedures. Germany and France are accelerating contract consolidation with providers offering integrated sampling logistics and digital reporting portals.
- Municipal Water Authorities:Public utility operators monitor distribution network integrity and treatment efficacy.
- Hospitality Operators:Hotels and resorts implement guest protection protocols beyond jurisdictional minimums.
- Facility Management Companies:Multi-site service providers are integrating water safety into bundled maintenance contracts.
- Research Institutes:Academic and government laboratories advance detection methodology and virulence factor characterization.
Environmental testing labs hold the largest share; facility management companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States healthcare systems absorb premium pricing for rapid molecular platforms, while municipal operators in Southern Europe and Southeast Asia prioritize cost-per-test economics over automation features.
United States
EPA Safe Drinking Water Act screening mandates drive recurring specimen volumes from hospital cooling towers and potable water networks. The agency's revised Legionella guidance compels building operators to adopt molecular detection methods or face enforcement action. Texas and Florida healthcare clusters exhibit the steepest contract consolidation, with multi-site hospital systems negotiating enterprise-level water safety agreements that bundle sampling logistics with digital reporting.
Germany
EU Drinking Water Directive implementation timelines are accelerating demand for CE-marked environmental assay kits in public buildings. The Federal Environment Agency enforces ISO 11731 culture standards for viability confirmation alongside molecular screening protocols. Bavaria and North Rhine-Westphalia dominate procurement volumes, where municipal utilities integrate automated PCR surveillance into district heating and cooling infrastructure serving healthcare districts.
France
ANSM pharmacovigilance requirements intersect with environmental monitoring obligations for healthcare facility accreditation. The country's national health agency mandates Legionella surveillance in retirement homes and thermal spa establishments under reinforced hygiene protocols. The Lyon-Grenoble corridor concentrates specialized environmental testing capacity, with ISO 17025-accredited laboratories offering integrated chain-of-custody services for hospital network clients.
Japan
METI guidelines for building maintenance standards are accelerating automated sampler deployment at water treatment works serving dense healthcare districts. The Ministry of Health, Labour and Welfare maintains strict culture-based confirmation requirements that sustain parallel demand for specialized media formulations. The Kanto region around Tokyo exhibits the densest cooling tower surveillance activity, where facility management companies bundle Legionella testing into comprehensive building hygiene contracts.
Australia
State-level public health regulations in New South Wales and Victoria mandate routine testing for cooling towers in commercial and healthcare properties. The country's national water quality guidelines reference ISO standards for both culture and molecular methods without prescribing hierarchy. Sydney and Melbourne environmental testing markets show pronounced contract consolidation, with multi-state laboratory networks displacing regional providers through integrated digital reporting platforms.
Global Legionella Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Legionella testing landscape. Multinational life science conglomerates with PCR platform breadth dominate reference laboratory contracts through automated high-throughput systems, while specialized culture media manufacturers sustain margin pools in European pharmacopeia-compliant formulations. The market structure separates into three strategic archetypes: diversified diagnostics platforms, specialized environmental assay developers, and integrated testing service providers. Competitive moves concentrate on geographic licensing partnerships for regulatory pathway acceleration and vertical integration into sampling logistics to capture recurring revenue streams.
Among diversified diagnostics platforms, Thermo Fisher Scientific and Abbott occupy positions exemplifying contrasting strategic vectors—one anchored in laboratory automation breadth, the other in hospital-based rapid turnaround workflows. bioMérieux represents the specialized environmental assay archetype, with its European S.A. structure signaling pharmacopeia-focused validation priorities. These three companies illustrate how regulatory geography shapes competitive positioning, with North American conglomerates prioritizing FDA-cleared platform extensions and European specialists emphasizing CE-marked environmental kit portfolios.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott |
| Merck KGaA |
| bioMérieux |
| Becton Dickinson and Company |
| Bio-Rad Laboratories |
| IDEXX Laboratories |
| Eurofins Scientific |
| QIAGEN |
| Others |
Supply & Pricing Matrix
ISO 11731 certification requirements simultaneously gate supplier qualification and stratify price tiers, forcing assay manufacturers to absorb specialized media formulation costs while passing premium positioning to accredited laboratories. This dual-gating mechanism concentrates margin capture among European pharmacopeia-compliant producers and fragments procurement access for cost-optimized entrants.
Pricing Analysis
Consumables and extended service contracts drive lifetime value capture, with reagent rental models dominating reference laboratory procurement. Three-tier pricing structure across premium, standard, and economy levels separates automated PCR platforms from manual culture kits and rapid field strips. Cost compression in rapid test strips is intensifying because of biosensor substitution in cooling tower monitoring. Environmental testing labs exhibit highest price sensitivity; hospital systems absorb premium pricing for FDA-cleared respiratory platforms.
Supply Chain Analysis
Strategic stockpiling of specialized culture media dominates inventory strategy, with cysteine-supplemented formulations requiring temperature-controlled logistics chains. Manufacturing concentrates in Germany, France, and the United States, with raw material dependencies on activated charcoal, yeast extract, and fluorescent probe chemistries. Single-source vulnerability runs through European pharmacopeia-certified media suppliers. Distribution runs through integrated laboratory service networks with digital chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across point-of-use detection integration, as building management system procurement creates service-layer niches beyond traditional laboratory contracts. Regulatory divergence between EPA environmental protocols and FDA clinical pathways sustains multiple viable positioning strategies.
For Market Incumbents: Fortify reference laboratory relationships through automated platform upgrades and embedded reagent supply contracts. Thermo Fisher Scientific's PCR dominance faces displacement pressure from digital PCR quantification; backward integration into fluorescent probe chemistry secures cost position. CE-marked environmental kit portfolios require expansion to capture EU Drinking Water Directive implementation.
For New Entrants and Emerging Players: Continuous monitoring sensor deployment represents the service-layer gap where incumbents under-serve facility management procurement. Target United States hospital systems with enterprise water safety agreements bundling sampling logistics and digital reporting. Biosensor hardware with cloud-integrated alert protocols offers the most penetrable entry vector against established PCR incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-need detection platforms, reducing barrier thresholds for specialized entrants. Five-to-ten year viability favors assay developers with dual environmental-clinical regulatory pathways and captive distribution networks. Acquisition targets should demonstrate ISO 17025 accreditation and integrated sampling logistics capabilities. The signal to watch is EPA enforcement action frequency against non-compliant healthcare facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | EU Drinking Water Directive mandates create procurement access for environmental kit manufacturers. |
| Automated Sampler Integration | Building management systems in United States hospitals embed continuous Legionella monitoring infrastructure. |
| Digital PCR Platform Launch | Absolute quantification technology enables remote result verification for distributed water safety networks. |
| Integrated Sampling Logistics | Environmental testing labs capture recurring revenue through chain-of-custody service bundling. |
| Dual-Use Assay Development | FDA-cleared respiratory platforms extended to environmental applications fragment product development roadmaps. |
Research Methodology
The analysis maps PCR platform configurations, culture media formulations, immunoassay systems, and biosensor technologies, each validated through laboratory directors, environmental testing facility managers, hospital procurement committees, and regulatory affairs specialists at assay manufacturers. Primary interviews with these stakeholders combined with secondary validation from EPA guidance documents, EU Drinking Water Directive implementation records, ISO standard certification databases, and hospital GPO contract filings. Bottom-up and top-down triangulation reconciles equipment installation data with reagent consumption patterns.
Consistency checks validated volume and value outputs against external benchmarks including regulatory enforcement databases and accredited laboratory capacity surveys. Segmentation modeling incorporated technology type, application setting, end-user category, and regional regulatory framework across the projection horizon. CAGRs were derived from equipment replacement cycles and reagent consumption trajectories, with cooling tower surveillance mandates and HVAC system testing protocols serving as industry-specific demand inputs.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement and EU Drinking Water Directive implementation timelines; material policy shifts would require re-modeling. Specific risks include FDA-EPA assay harmonization acceleration, digital PCR platform cost deflation, and biosensor technology performance validation. Revision becomes warranted when point-of-use detection accuracy crosses clinical correlation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Specimen Validity Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Bimetallic Thermometer Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Drug Testing Systems Market
Testing Services
Osmometer Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Global Electronystagmography Testing Market