
 Greece Facility Management Market | 2026-2036
Greece Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Facility Management Market Foresight
Service procurement channels across Greek commercial real estate are reshaping as landlords consolidate vendor panels under longer outsourced contracts. AKTOR FM leverages its construction heritage to anchor bundled hard and soft service offerings across Attica. Cowa Hellas Facility Management AE competes through specialized healthcare maintenance protocols that sustain recurring revenue from Athens hospital clusters. Globe Williams International extends its international playbook to dominate security and cleaning contracts at Piraeus port logistics facilities.
Facility management encompasses the integrated coordination of building operations, maintenance, and support services to ensure functional, safe, and cost-effective environments, typically governed by service-level agreements specifying response times, uptime thresholds, and energy performance benchmarks. Its primary commercial purpose centers on extending asset lifecycles while reducing total occupancy costs for building owners and tenants. Cleaning and maintenance services claim the largest revenue share within the service type dimension, reflecting the labor-intensive reality of Greece's aging building stock. Smart building systems within the technology segment represent the fastest-expanding margin pool, as CMMS and IoT Solutions deployments accelerate under pressure from EU decarbonization mandates and rising utility costs.
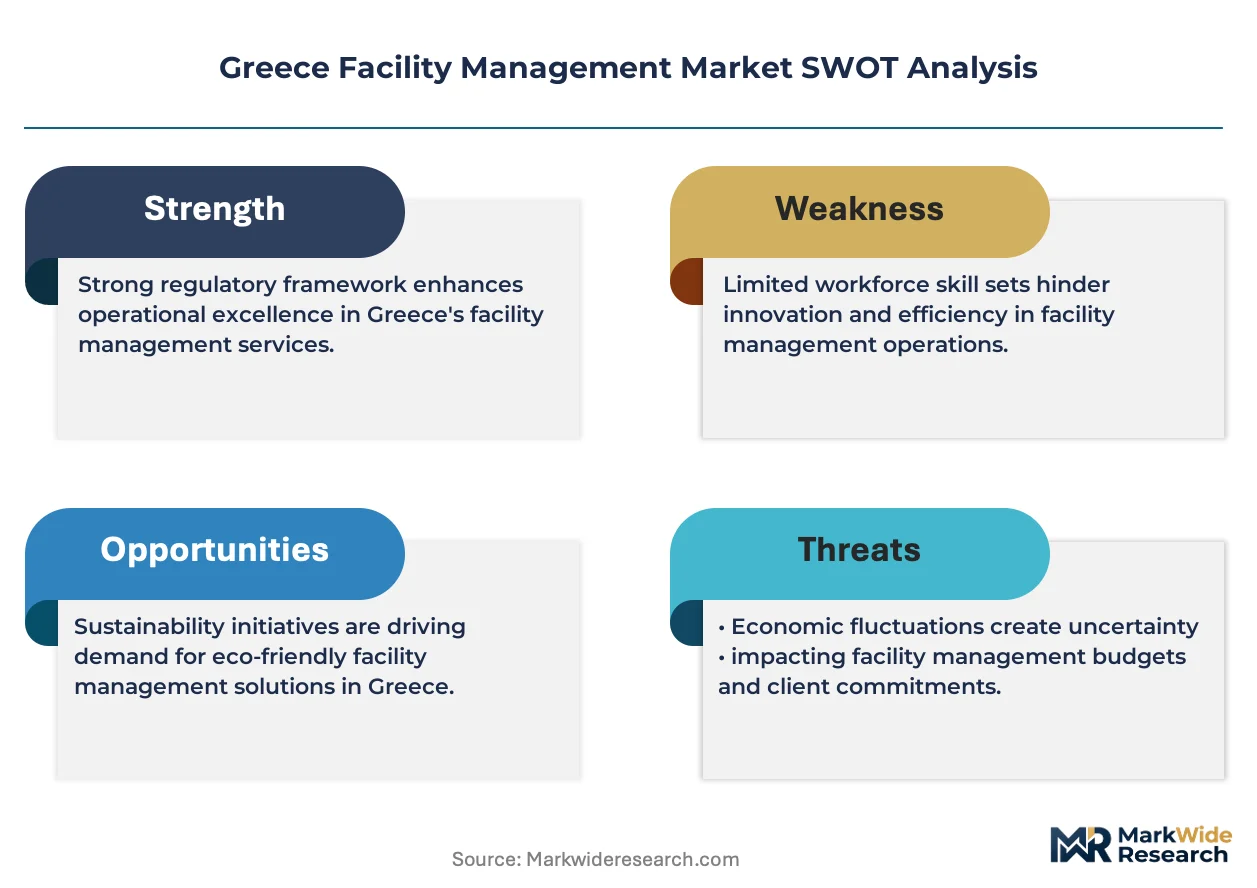
Greek facility operators navigate oversight from the Ministry of Environment and Energy on building efficiency standards, alongside Ministry of Labour mandates on workplace safety and subcontractor classification. The EU Energy Performance of Buildings Directive and national implementation frameworks shape demand by compelling energy audits and retrofit roadmaps across public and large private buildings. Stakeholders must monitor how forthcoming EU taxonomy alignment requirements will filter contract specifications and vendor qualification criteria.
Market Dynamics
The EU Energy Performance of Buildings Directive compels Greek facility operators to retrofit aging commercial stock with integrated energy management systems, accelerating vendor consolidation around full-service providers capable of delivering audit-to-execution retrofit roadmaps under single-contract accountability.
Growth Catalysts
- Healthcare outsourcing expansion:Athens hospital clusters are transferring non-clinical estate management to specialized operators, creating recurring revenue streams for maintenance protocols that comply with Ministry of Labour workplace safety mandates.
- EU decarbonization pressure:The Energy Performance of Buildings Directive mandates energy audits across public buildings, forcing capital allocation toward smart building retrofits and CMMS deployments that reduce utility expenditure.
- Port logistics modernization:Piraeus container terminal expansion drives demand for integrated security, cleaning, and mechanical maintenance services at scale, favoring operators with maritime sector expertise.
Market Restraints
- Labor cost inflation:Cleaning and maintenance services remain labor-intensive, with wage pressure from Ministry of Labour classification rules compressing margins on fixed-price contracts.
- Construction sector volatility:AKTOR FM and similar construction-heritage providers face revenue cyclicality tied to Attica building permit issuance rates, creating cash flow unpredictability.
- Technology integration gaps:Legacy building automation protocols in Thessaloniki commercial stock resist seamless IoT sensor deployment, delaying smart retrofit timelines and inflating project costs.
Strategic Opportunities
- Crete hospitality estates:Underserved resort properties across Heraklion and Chania present white space for bundled facility services as tourism operators seek operational cost predictability.
- Photovoltaic integration:Rooftop solar mandates under national energy efficiency frameworks create demand for facility operators capable of coordinating PV installation with building envelope upgrades.
- Public-private partnership models:Municipal building energy performance contracting in Patras and Larissa opens long-term concession structures that transfer retrofit risk to private operators.
Industry Challenges
- Certified energy auditor scarcity:The pool of professionals qualified to execute EU-mandated building energy certification remains thin, bottlenecking retrofit project initiation across Attica and Central Macedonia.
- Subcontractor coordination complexity:Multi-trade project delivery requires harmonizing electrical, HVAC, and envelope specialists under unified SLAs, with payment disputes and quality variance eroding client retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Facility Management Market |
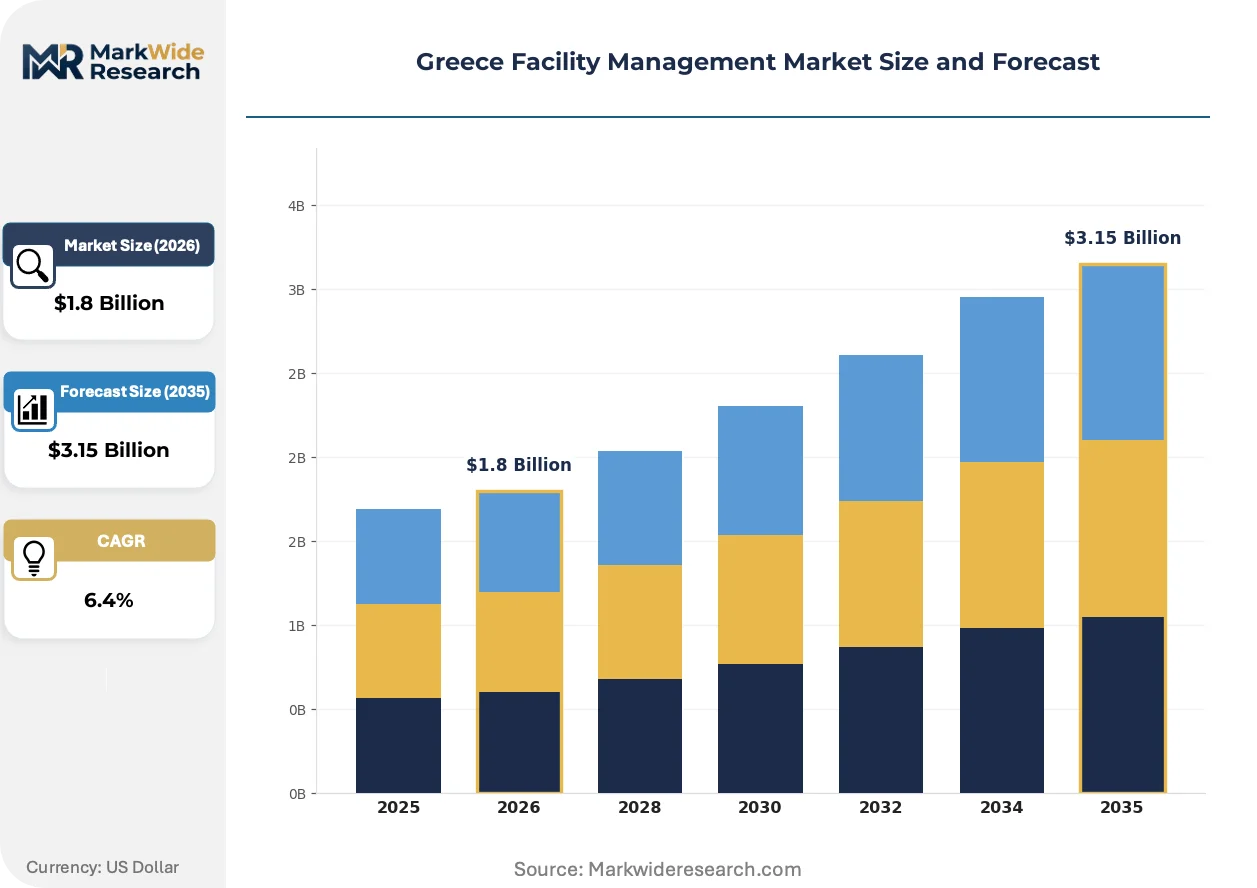
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Corporate Offices, Educational Institutions, Hospitals, Retail Stores Technology: CMMS, IoT Solutions, Smart Building Systems, Energy Management Contract Type: Outsourced, Joint Venture, In-House, Full-Service |
| Companies Covered | Cowa Hellas Facility Management AE, MELKAT, Globe Williams International, IDMON Property Advisors & Technical Experts, IMAGIN Facility Management SA, Manifest Services SA, AKTOR FM, Controline, CORDIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Facility Management Market Shifts & Advancements
Digital infrastructure is penetrating Greek facility operations at uneven rates, with Athens commercial landlords leading adoption while provincial assets lag. Three distinct vectors are restructuring competitive requirements and investment priorities.
Computerized maintenance management systems (CMMS) are migrating from reactive work-order tracking toward predictive analytics platforms that integrate IoT sensor streams with asset lifecycle modeling. Large Attica office landlords are piloting these systems to compress mean-time-to-repair metrics and negotiate insurance premium reductions. The structural consequence is margin pressure on pure-play cleaning contractors unable to bundle digital asset management into service offerings.
The EU Energy Performance of Buildings Directive is tightening audit frequency and disclosure requirements for buildings exceeding specified floor areas, compelling owners to document retrofit roadmaps or face occupancy restrictions. Industrial consequence flows through to contract specifications, with RFPs now mandating vendor capability to execute energy audits, install monitoring hardware, and guarantee consumption reductions. Thessaloniki logistics facilities are responding fastest, driven by multinational tenant ESG reporting obligations.
Consolidated vendor panels are displacing fragmented multi-contractor arrangements as Greek commercial landlords seek single-accountability structures for hard and soft services. Property management firms are compressing supplier rosters from twelve to three preferred partners, with selection criteria weighting energy performance guarantees and digital reporting capability above unit-rate competitiveness. This concentration is most visible in Athens CBD office towers, where lease structures increasingly pass facility cost volatility to operators through indexed management fees.
Greece Facility Management Market Segmentation
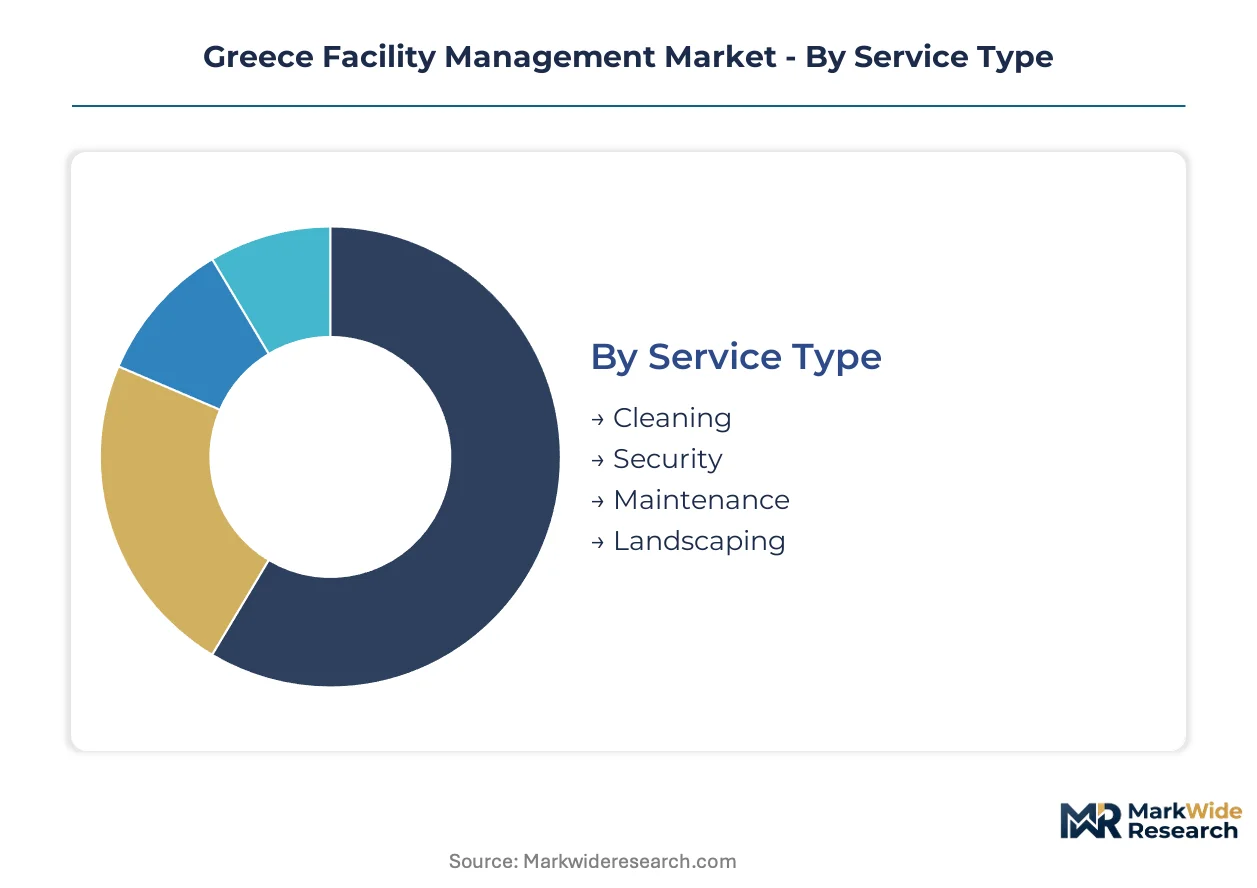
Facility management segmentation in Greece reveals how service bundling, technology adoption, and contract structures align with distinct client risk appetites and asset classes. Understanding these divisions exposes where vendor consolidation concentrates and where specialized operators defend niche positions.
Service Type:
Mature segments dominate revenue capture while emerging categories reshape margin structures across Attica and Thessaloniki commercial portfolios.
- Cleaning:Labor-intensive surface sanitation and waste removal protocols constitute the largest employment base within Greek facility operations. Athens CBD office towers and Piraeus logistics terminals drive sustained demand for daily janitorial crews, though Ministry of Labour classification rules compress contract profitability.
- Security:Personnel-based access control and surveillance operations serve high-value assets including maritime facilities and healthcare estates. Piraeus port expansion generates concentrated demand for integrated security-cleaning bundles that reduce vendor management overhead for terminal operators.
- Maintenance:Mechanical and electrical asset upkeep spanning HVAC, plumbing, and building envelope systems.
- Landscaping:Exterior grounds management and seasonal vegetation services for corporate campuses and hospitality estates.
Cleaning retains volume leadership; Smart building-integrated maintenance holds the steepest expansion curve.
End User:
Cost tier differentiation separates premium-grade estate operators from budget-constrained public sector clients.
- Corporate Offices:Athens CBD towers and Thessaloniki business parks demand integrated hard and soft service bundles with digital reporting capabilities. Lease structures increasingly pass facility cost volatility to operators through indexed management fees, favoring vendors with capital reserves.
- Hospitals:Athens hospital clusters transfer non-clinical estate management to specialized operators under strict Ministry of Labour workplace safety compliance. Recurring revenue streams from maintenance protocols sustain vendor relationships across multi-year contracts.
- Educational Institutions:Public and private campus facilities with seasonal occupancy patterns and constrained capital budgets.
- Retail Stores:High-traffic commercial premises requiring rapid-response cleaning and security protocols.
Corporate offices command premium pricing; hospitals demonstrate the most resilient contract renewal rates.
Technology:
Application maturity varies sharply between predictive platforms and legacy reactive systems across Greek building stock.
- Smart Building Systems:Integrated sensor networks and automation controls that optimize HVAC, lighting, and security operations. EU Energy Performance of Buildings Directive mandates accelerate deployment in Thessaloniki logistics facilities responding to multinational tenant ESG reporting obligations.
- CMMS:Computerized maintenance management systems migrating from work-order tracking toward predictive analytics platforms. Large Attica office landlords pilot these systems to compress mean-time-to-repair metrics and negotiate insurance premium reductions.
- IoT Solutions:Distributed sensor networks enabling real-time asset monitoring and energy consumption tracking.
- Energy Management:Audit-to-execution platforms documenting retrofit roadmaps and guaranteeing consumption reductions.
CMMS retains installed base leadership; Smart building systems are climbing the fastest as retrofit mandates tighten.
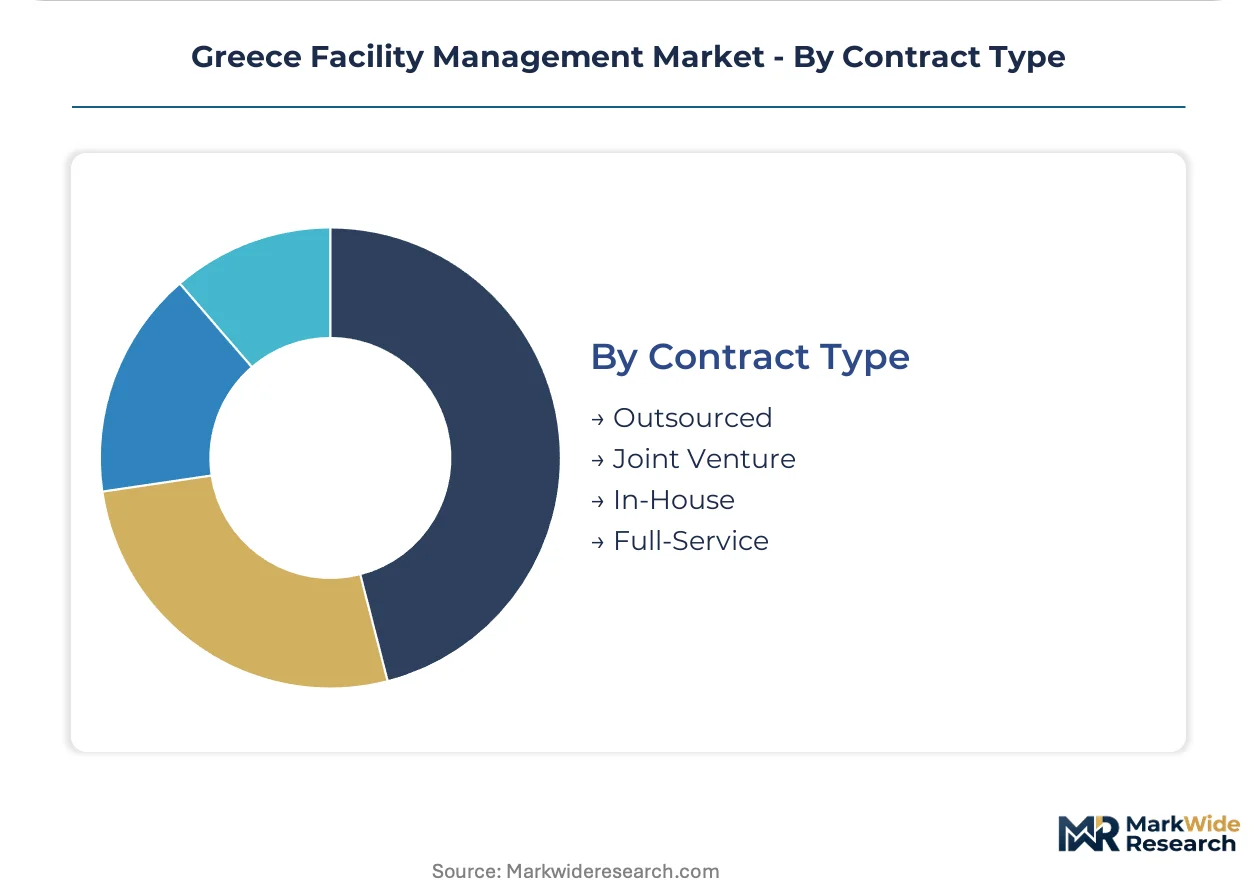
Contract Type:
Customer type preferences diverge between risk-averse institutional clients and operationally integrated corporate operators.
- Outsourced:Third-party facility management where external vendors assume operational responsibility under service-level agreements. Greek commercial landlords consolidate vendor panels from twelve to three preferred partners, with selection criteria weighting energy performance guarantees above unit-rate competitiveness.
- Full-Service:Single-accountability structures bundling hard services, soft services, and technology platforms under unified management. AKTOR FM leverages construction heritage to anchor these offerings across Attica, capturing retrofit-to-operations continuity.
- In-House:Direct employment of facility staff retained by asset owners seeking operational control.
- Joint Venture:Shared-risk structures between property owners and service specialists.
Outsourced contracts retain transaction volume leadership; Full-service structures gain share fastest as landlord consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Energy Performance of Buildings Directive channels capital toward smart building retrofits across Greek metropolitan centers, with facility service demand concentrating where commercial stock modernization accelerates fastest under national implementation frameworks.
Attica
Athens CBD office towers drive consolidated vendor panel adoption as landlords compress supplier rosters from twelve to three preferred partners. The Ministry of Environment and Energy enforces building efficiency standards that compel energy audits across public buildings. Piraeus port logistics facilities generate concentrated demand for integrated security and mechanical maintenance bundles.
Central Macedonia
Thessaloniki business parks and logistics terminals respond fastest to multinational tenant ESG reporting obligations through smart building system deployment. EU decarbonization mandates shape contract specifications requiring vendor capability to execute audit-to-execution retrofit roadmaps. Legacy building automation protocols in commercial stock resist seamless IoT sensor integration, inflating project timelines.
Crete
Heraklion and Chania resort properties present underserved white space for bundled facility services as tourism operators seek operational cost predictability. National energy efficiency frameworks create demand for photovoltaic integration alongside building envelope upgrades. Hospitality estates remain fragmented across multiple small-scale contractors without single-accountability structures.
Western Greece
Patras municipal buildings open long-term concession structures through public-private partnership models that transfer retrofit risk to private operators. The Ministry of Labour mandates on workplace safety and subcontractor classification shape service procurement channels. University and hospital clusters generate recurring revenue streams for specialized maintenance protocols.
Thessaly
Larissa municipal energy performance contracting creates demand for facility operators capable of coordinating multi-trade project delivery under unified service-level agreements. Certified energy auditor scarcity bottlenecks retrofit project initiation across the region. Industrial and logistics facilities concentrate maintenance demand around seasonal agricultural processing cycles.
Greece Facility Management Market Competitive Landscape
On the supply side, the industry is consolidating around construction-heritage providers and specialized healthcare operators capable of delivering bundled hard and soft service offerings. Three strategic archetypes dominate competitive positioning: full-service integrated providers leveraging retrofit-to-operations continuity, healthcare-focused specialists commanding recurring revenue through compliance-driven maintenance protocols, and maritime-logistics operators capturing port facility security and cleaning contracts. Dominant competitive moves include vendor panel consolidation under longer outsourced contracts and technology platform integration to satisfy EU-mandated energy audit and digital reporting requirements.
Within the construction-heritage tier, AKTOR FM anchors full-service bundled offerings across Attica, exemplifying providers that capture retrofit-to-operations continuity. Cowa Hellas Facility Management AE occupies a position among healthcare-focused specialists, representing the archetype that sustains recurring revenue through Athens hospital cluster relationships. Globe Williams International sits within the maritime-logistics specialist category, reflecting operators that extend international playbooks to dominate security and cleaning contracts at Piraeus port facilities.
| Leading Market Players |
|---|
| Cowa Hellas Facility Management AE |
| MELKAT |
| Globe Williams International |
| IDMON Property Advisors & Technical Experts |
| IMAGIN Facility Management SA |
| Manifest Services SA |
| AKTOR FM |
| Controline |
| CORDIA |
| Others |
Supply & Pricing Matrix
Piraeus port freight corridors anchor cost dynamics across Greek facility management, with maritime logistics expenses feeding directly into service pricing tiers and vendor consolidation patterns across Attica commercial portfolios. Supply concentration among construction-heritage providers amplifies pricing power for bundled retrofit-to-operations contracts, while downstream buyers face differentiated rate structures based on energy compliance requirements and digital reporting capabilities.
Pricing Analysis
Certification level under EU Energy Performance of Buildings Directive standards creates the primary spread between premium audit-to-execution vendors and commodity maintenance contractors. Contract-based long-term outsourcing dominates, with price differentiation hinging on energy auditor qualification scarcity and CMMS platform bundling. Pricing pressure intensifies in labor-intensive cleaning segments as Ministry of Labour classification rules compress fixed-contract margins. Public sector municipal clients exhibit highest price sensitivity; Athens CBD corporate towers with ESG-mandated tenants show lowest.
Supply Chain Analysis
Tariff exposure between EU member states and third-country equipment suppliers dominates supply chain risk assessment for smart building retrofit components. Component sourcing concentrates in Germany, Italy, and China for HVAC automation systems, IoT sensors, and energy management hardware. Raw material dependencies span copper wiring, aluminum envelope systems, and lithium-ion storage units. Single-source vulnerability persists for certified energy audit software platforms. Distribution runs through Attica-based master contractors coordinating multi-trade subcontractor networks across regional project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek facility management is cycling through post-construction volatility toward steady-state outsourcing expansion, with EU decarbonization mandates providing durable demand tailwinds across the forecast horizon.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive maintenance platforms into existing Athens hospital cluster contracts before specialized healthcare competitors capture upgrade cycles. Secure backward integration into energy auditor certification pipelines to bottleneck competitor access to EU-mandated audit capabilities. Threat vector: construction-heritage rivals leveraging Attica retrofit-to-operations continuity to displace pure-play service vendors. For New Entrants and Emerging Players: Establish a beachhead in Crete hospitality estates where bundled facility services remain fragmented across small-scale contractors without single-accountability structures. Target Heraklion and Chania resort properties seeking operational cost predictability through indexed management fee structures. Go-to-market angle: photovoltaic integration capabilities aligned with national rooftop solar mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from construction conglomerates seeking to monetize captive facility management divisions amid cyclical building permit downturns. Long-term viability frames around 5-10 year concession structures transferring municipal retrofit risk to private operators under EU taxonomy alignment. Signal to monitor: public-private partnership award velocity in Patras and Larissa municipal energy performance contracting.| Strategic Initiative | Industry Significance |
|---|---|
| CMMS Platform Integration | Compresses mean-time-to-repair metrics for Attica office landlords negotiating insurance reductions. |
| Energy Auditor Certification Investment | Bottlenecks competitor pipeline access under EU Energy Performance of Buildings Directive mandates. |
| Photovoltaic Coordination Capability | Captures rooftop solar mandate demand alongside building envelope upgrade contracts. |
| Healthcare Compliance Specialization | Sustains recurring revenue through Ministry of Labour workplace safety protocol adherence. |
| Maritime-Logistics Bundle Expansion | Dominates Piraeus port security and cleaning contracts through integrated service offerings. |
Research Methodology
Operator-level perspectives from facility management executives, property portfolio directors, energy auditors, municipal procurement officers, and subcontractor trade specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EU Energy Performance of Buildings Directive implementation frameworks, Ministry of Environment and Energy efficiency standard disclosures, and Attica commercial real estate transaction records. Bottom-up service segmentation data triangulated against top-down construction sector output indicators.
Scenario-bracketing framed projections across conservative, baseline, and accelerated outsourcing adoption paths throughout the forecast period. Segmentation dimensions modeled encompass service type bundling intensity, technology platform maturity, contract structure risk allocation, and regional regulatory enforcement variance. CAGRs derived from historical outsourcing penetration rates projected against EU mandate compliance timelines and healthcare estate expansion patterns.
Sensitivities concentrate around certified energy auditor supply expansion, construction permit cyclicality, and EU taxonomy alignment acceleration. Forecasts reflect documented assumptions on vendor consolidation velocity and digital platform adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Romania Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
North America Facilities Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Denmark Facility Management Market