
 Middle East and Africa Soft Facility Management Market | 2026-2036
Middle East and Africa Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Soft Facility Management Market Foresight
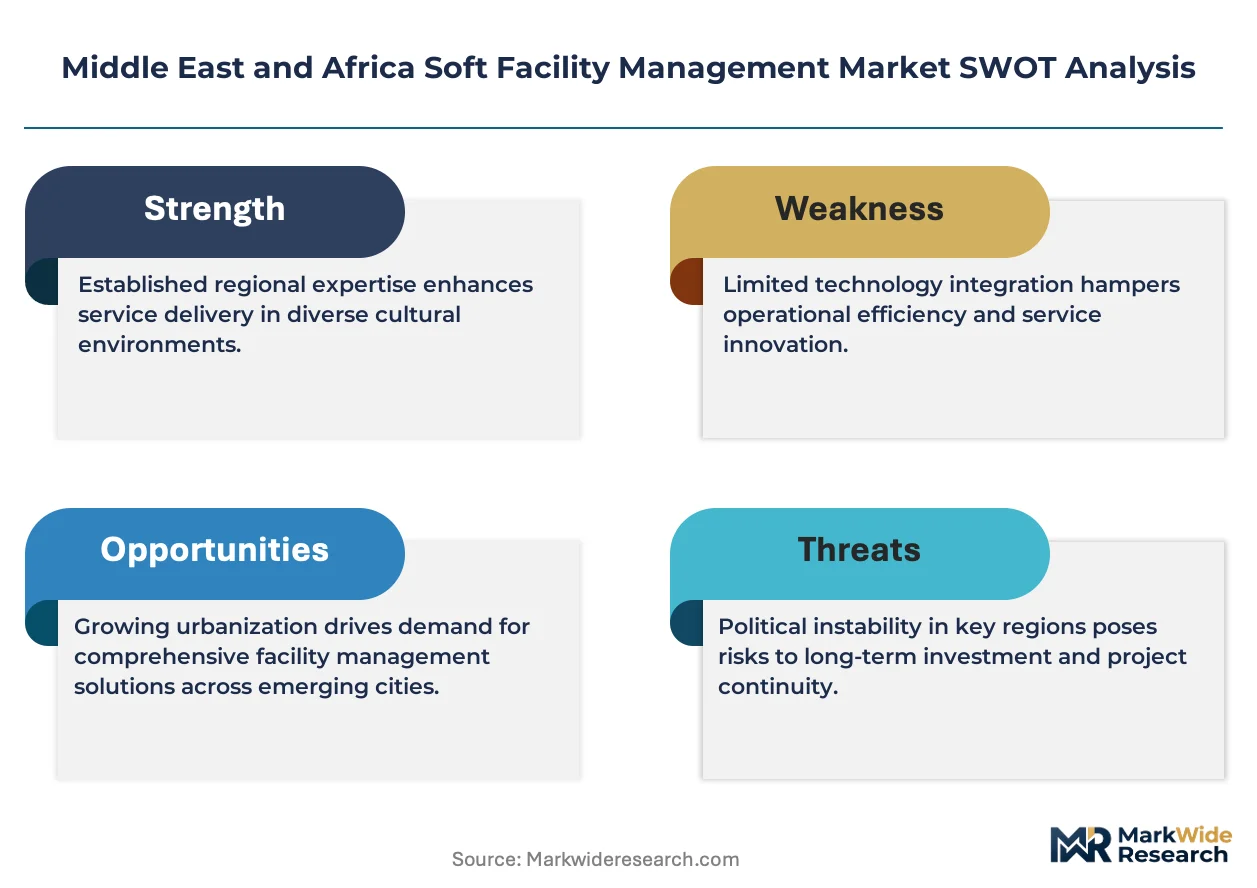
ISO 41001 certification for facility management systems is redrawing competitive boundaries across the Middle East and Africa. Serco Group PLC leverages its British standards heritage to sustain premium positioning in government and aviation contracts. EFS Facilities Services Group anchors its expansion through in-house training academies that produce locally certified technicians. Farnek Services LLC differentiates via IoT-integrated cleaning audits that reduce resource waste for Dubai commercial towers.
Soft facility management encompasses non-structural building services including cleaning, security, landscaping, and waste handling, typically delivered through labor-intensive operations with increasing sensor-based performance verification. Its primary commercial purpose is sustaining occupant productivity, health compliance, and asset lifecycle value without capital-intensive infrastructure modification. Cleaning Services generates the largest revenue pool across the region, while IoT Solutions within the Technology segment records the fastest uptake as Saudi and Emirati clients mandate real-time service verification. Outsourced Services dominates the Delivery Model dimension, though Hybrid Services is gaining traction as clients seek retained oversight with specialist execution.
The UAE's Ministry of Energy and Infrastructure enforces green building codes that mandate waste diversion targets and indoor air quality thresholds, directly shaping service specifications and vendor qualification requirements. Saudi Arabia's Saudi Building Code and Giga-project procurement frameworks impose standardized facility management clauses that accelerate market formalization. Egypt's Housing and Building National Research Center is developing localized FM standards that will reshape vendor eligibility. Stakeholders must monitor how carbon disclosure requirements and local content mandates alter contract structures and technology investment priorities.
Market Dynamics
Giga-project construction across Saudi Arabia and the UAE is compressing procurement timelines and forcing facility management vendors to pre-qualify for decade-long service contracts before concrete is poured. This demand concentration is restructuring competitive entry barriers across the Middle East and Africa.
Growth Catalysts
- Estidama Pearl Rating System:The UAE's mandatory green building framework mandates waste diversion and indoor air quality thresholds, forcing commercial developers to contract technology-enabled soft services that verify compliance through sensor networks.
- Saudi Giga-project Procurement:NEOM, Red Sea Global, and Qiddiya embed standardized facility management clauses into construction contracts, creating predictable revenue pipelines for qualified service providers.
- IoT-Integrated Performance Verification:Real-time cleaning audit platforms and occupancy-based service scheduling are displacing manual inspection regimes in Dubai and Riyadh commercial towers.
Market Restraints
- Labor Cost Volatility:South Asian expatriate worker remittance fluctuations and visa processing delays in the UAE and Saudi Arabia create unpredictable wage pressure for labor-intensive cleaning and security operations.
- Supplier Concentration in Equipment:European and East Asian manufacturers dominate commercial cleaning robotics and sensor hardware, exposing regional operators to currency risk and extended lead times.
- Technical Skills Mismatch:Local training infrastructure produces technicians certified to legacy standards while giga-projects demand competency in building automation system integration and data analytics.
Strategic Opportunities
- Egypt Formalization Wave:The Housing and Building National Research Center's draft facility management standards will disqualify informal operators from government and commercial contracts, creating vendor replacement demand in Cairo and Alexandria.
- Hybrid Service Models:Clients in Abu Dhabi and Jeddah are retaining strategic oversight functions in-house while outsourcing execution to specialists, enabling new contract structures that blend fixed fees with performance bonuses.
- Carbon Disclosure Mandates:Saudi Arabia's Green Building Forum and UAE corporate sustainability reporting requirements are creating demand for waste tracking and energy-efficient cleaning protocols that reduce scope three emissions.
Industry Challenges
- ISO 41001 Certification Backlog:Accredited bodies in the region lack capacity to process facility management system certifications at the pace required by government and aviation procurement deadlines.
- Integration Complexity:Legacy building management systems in older Dubai and Manama commercial stock lack API compatibility with modern IoT service verification platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Soft Facility Management Market |
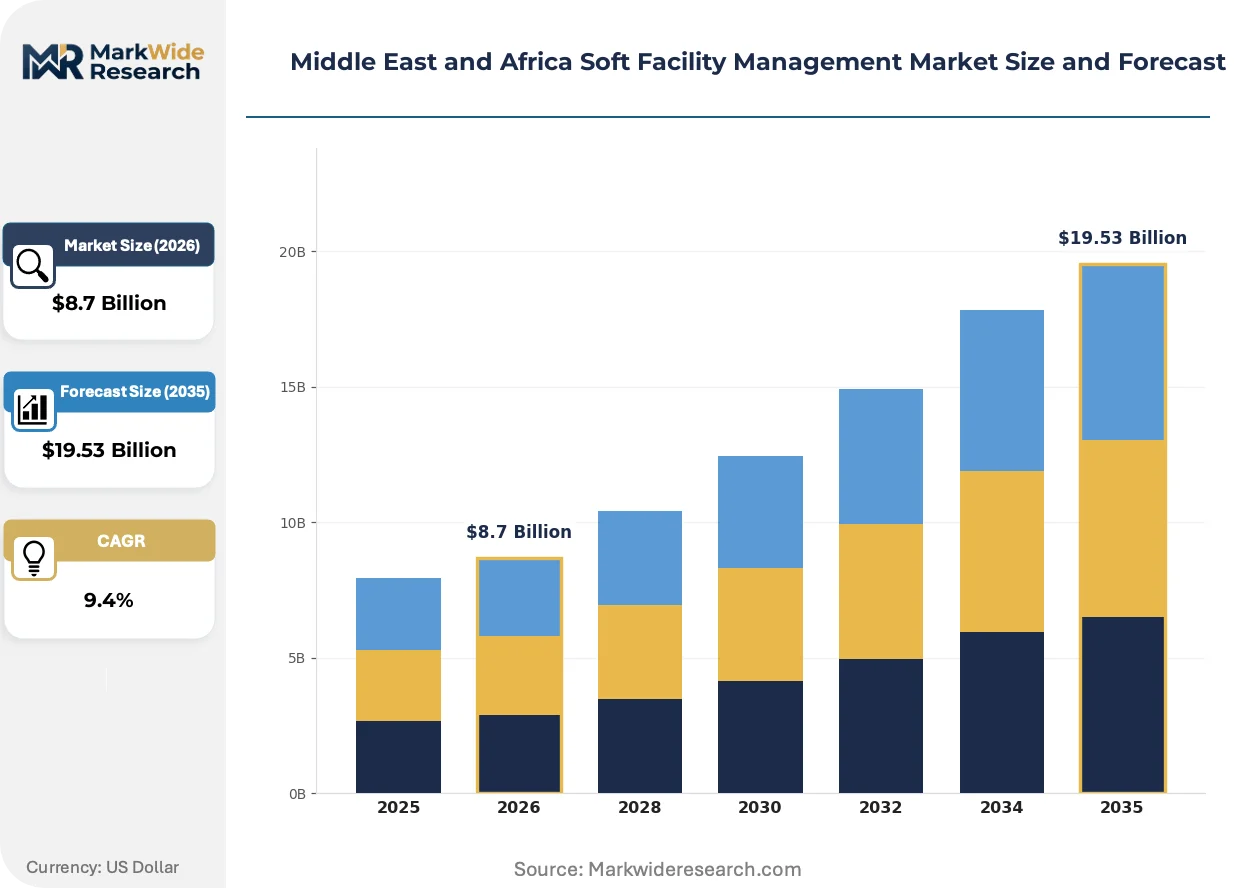
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Landscaping Services, Waste Management End User: Office Buildings, Residential Complexes, Retail Stores, Educational Institutions Delivery Model: Onsite Services, Outsourced Services, Hybrid Services, Contractual Services Technology: IoT Solutions, Software Platforms, Automation Tools, Maintenance Management |
| Companies Covered | Emrill Services LLC, Serco Group PLC, EFS Facilities Services Group, Initial Saudi Arabia Company Limited, Ecolab Inc., Sodexo Inc., Ejadah Asset Management Group, Kharafi National for Infrastructure Projects Developments Construction and Services SAE, Farnek Services LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Soft Facility Management Market Shifts & Advancements
Technology-enabled performance verification is displacing manual supervision models across the Middle East and Africa soft facility management landscape. Vendors are racing to embed sensor networks and automated reporting into service delivery before regulatory mandates harden competitive positioning.
Autonomous cleaning robotics is fragmenting the traditional labor-dominant service model. These machines perform overnight floor maintenance and window cleaning in Riyadh and Dubai commercial towers. Large developers are piloting mixed fleets of robotic units and human supervisors. The technology is fragmenting contract pricing structures by separating equipment capital costs from labor service fees.
Saudi Arabia's Saudi Building Code and Giga-project procurement frameworks are mandating standardized facility management clauses across all new construction. These requirements specify minimum service levels, reporting frequencies, and technology integration standards. International contractors entering NEOM and Red Sea Global developments must demonstrate compliance with these frameworks or face disqualification from consortium bids.
Performance-based contracting is replacing fixed-fee arrangements in Abu Dhabi and Jeddah commercial property portfolios. Property managers are retaining outcome verification rights and linking vendor payments to measurable metrics including occupant satisfaction scores and energy-adjusted cleaning efficacy. This pattern is most visible in sovereign wealth fund-backed developments where asset lifecycle value takes priority over short-term opex minimization.
Middle East and Africa Soft Facility Management Market Segmentation
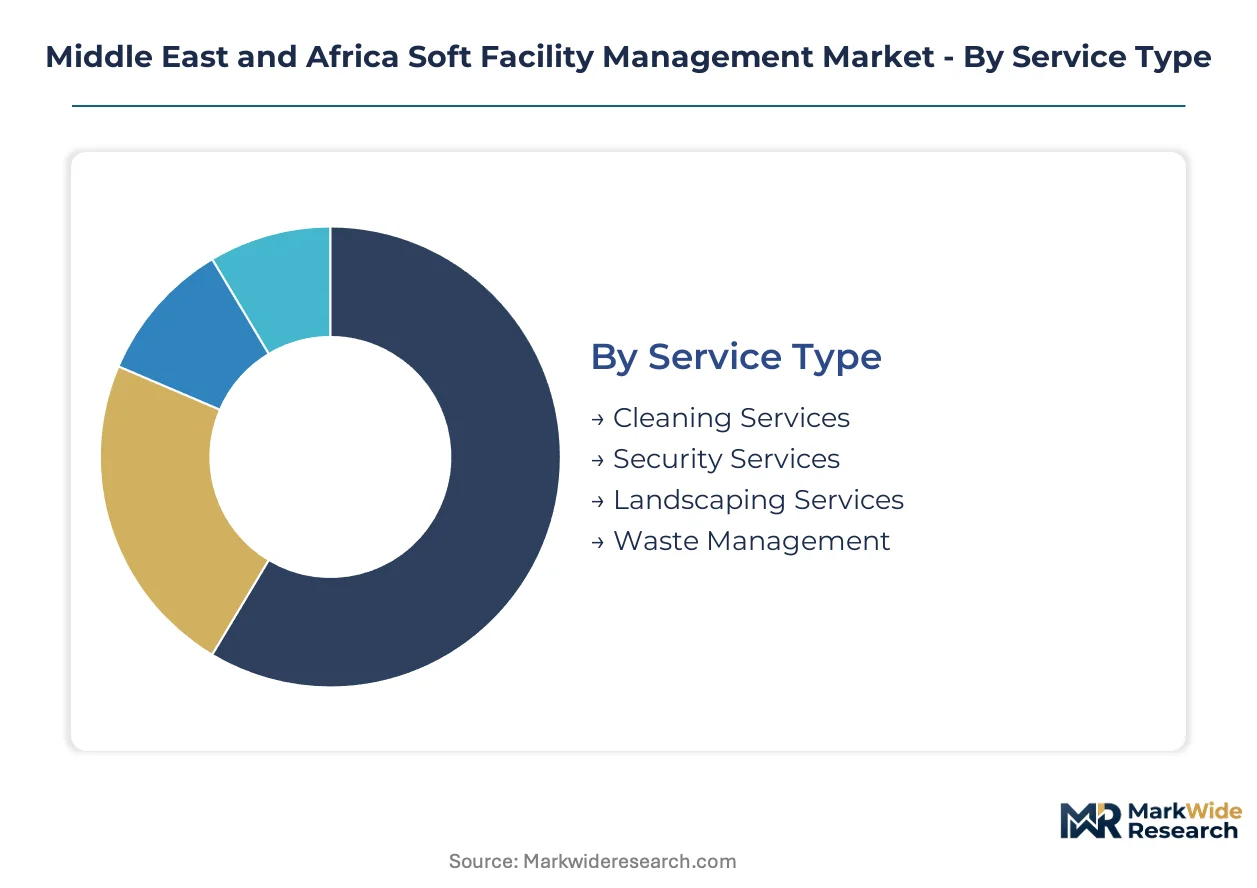
Soft facility management procurement across the Middle East and Africa fragments across service delivery modes, technology integration levels, and asset-class requirements. Each segmentation dimension carries distinct margin structures and vendor qualification thresholds that reshape competitive positioning.
Service Type:
Margin pools concentrate in technology-augmented service lines where compliance verification commands premium pricing, while commoditized labor-intensive segments face persistent cost pressure.
- Cleaning Services:Labor-intensive operations encompassing janitorial, specialized surface treatment, and infection control protocols for healthcare and commercial assets. Demand clusters in Saudi Arabia's giga-project corridors where Estidama Pearl Rating mandates drive sensor-verified cleaning audits and waste diversion documentation.
- Security Services:Personnel-based access control, surveillance monitoring, and emergency response coordination. Abu Dhabi sovereign wealth fund developments are embedding security services into integrated facility management contracts with decade-long tenures and performance-linked fee structures.
- Landscaping Services:Exterior maintenance, irrigation management, and xeriscaping for water-scarce environments. UAE municipalities specify native species quotas and smart irrigation mandates.
- Waste Management:Collection, segregation, and diversion tracking for circular economy compliance. Saudi Building Code amendments impose landfill diversion minimums on commercial developments.
Cleaning Services holds installed capacity. Waste Management is rotating up the share rankings.
End User:
Application intensity varies sharply by asset lifecycle stage and regulatory exposure, with new construction commanding integrated service packages while legacy stock demands retrofit compliance.
- Office Buildings:Multi-tenant commercial towers requiring flexible service scheduling, occupancy-based cleaning protocols, and tenant satisfaction benchmarking. Dubai International Financial Centre properties mandate ISO 41001-certified vendors with real-time performance dashboards.
- Residential Complexes:Gated communities and high-rise apartments with amenity maintenance and concierge-integrated security. Jeddah's Corniche developments specify soft service standards in strata title regulations.
- Retail Stores:High-traffic environments with rapid response cleaning and loss prevention security. Mall operators in Riyadh and Cairo prioritize vendor flexibility for seasonal demand spikes.
- Educational Institutions:Schools and universities with specialized hygiene protocols and campus-wide security perimeters. UAE Ministry of Education procurement frameworks standardize facility management specifications across public campuses.
Office Buildings anchor current contract value. Residential Complexes are climbing the fastest as giga-project housing stock delivers.
Delivery Model:
Customer type determines contract structure preference, with institutional owners favoring retained control and private developers seeking full risk transfer.
- Onsite Services:Captive workforce models with direct employer liability and asset-specific training investment. Saudi Aramco residential compounds maintain proprietary facility management cadres with decades of institutional knowledge.
- Outsourced Services:Third-party contract execution with defined service level agreements and penalty structures. Dominant across UAE commercial property where REIT structures prohibit operational employment.
- Hybrid Services:Strategic oversight retained in-house with specialist execution subcontracted. Gaining traction in Abu Dhabi and Jeddah where asset managers retain compliance verification functions.
- Contractual Services:Project-based arrangements for event support, seasonal peaks, or turnaround maintenance. Common in Red Sea Global tourism developments with variable occupancy patterns.
Outsourced Services commands volume leadership. Hybrid Services is expanding most quickly as owner sophistication increases.
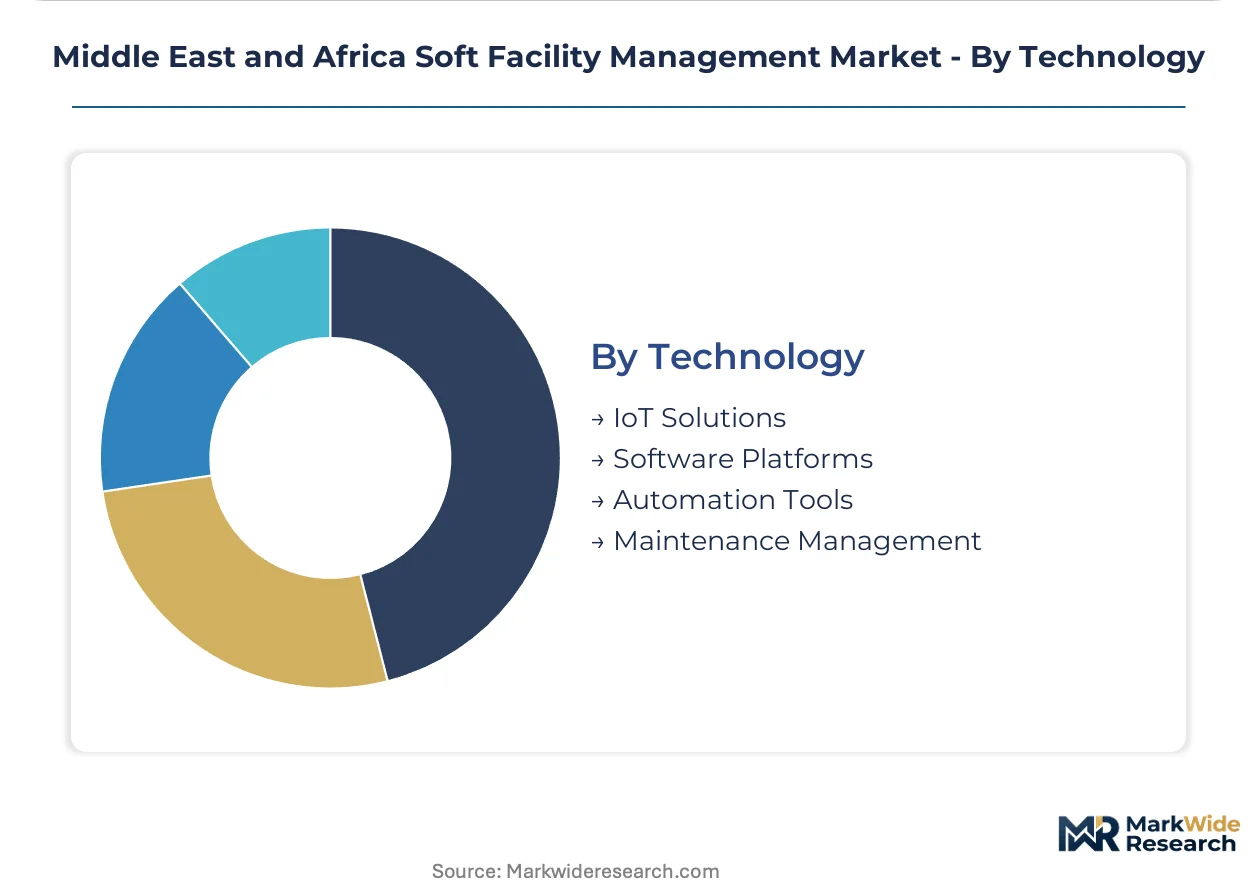
Technology:
Supply concentration in European and East Asian hardware vendors shapes regional operator technology choices and capital deployment timing.
- IoT Solutions:Sensor networks for occupancy detection, air quality monitoring, and automated service dispatch. NEOM procurement mandates require IoT-integrated soft service verification from contract inception.
- Software Platforms:Computerized maintenance management systems with mobile workforce interfaces and client reporting portals. Dubai-based vendors are developing Arabic-localized platforms for regional compliance documentation.
- Automation Tools:Robotic floor cleaners, window washing drones, and autonomous security patrol units. Riyadh commercial towers pilot mixed human-robot fleets for overnight operations.
- Maintenance Management:Preventive scheduling systems and asset lifecycle tracking for building fabric and MEP coordination. Egypt's draft FM standards will mandate digital maintenance logging for government contracts.
Software Platforms holds current deployment scale. IoT Solutions is gaining share fastest as green building verification requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway anchors Bahrain's logistics corridor, while Saudi Arabia's Riyadh-Jeddah rail spine and the UAE's Jebel Ali port complex structure regional facility management demand across the Middle East and Africa.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya giga-projects generate decade-long soft service procurement pipelines. The Saudi Building Code mandates standardized facility management clauses with minimum service levels and technology integration requirements. Riyadh's King Abdullah Financial District concentrates demand for ISO 41001-certified vendors with real-time performance dashboards.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market properties command premium technology-enabled cleaning and security services. Estidama Pearl Rating and Al Sa'fat green building regulations enforce waste diversion targets and indoor air quality thresholds through sensor-verified compliance. Dubai's commercial tower stock drives IoT-integrated cleaning audit adoption.
Egypt
Government and commercial contract formalization accelerates as the Housing and Building National Research Center develops localized facility management standards. Cairo's New Administrative Capital construction embeds soft service specifications into sovereign development frameworks. Alexandria's industrial zones generate demand for hybrid service delivery models.
South Africa
Commercial property portfolios in Johannesburg and Cape Town adopt performance-based contracting with outcome verification rights. The country's national building regulator enforces energy efficiency standards that reshape cleaning protocol specifications. Gauteng province concentrates vendor activity around REIT-structured developments.
Qatar
Post-World Cup hospitality and commercial assets sustain facility management procurement at elevated service levels. Lusail City's smart city infrastructure mandates IoT-integrated soft service verification from inception. Doha's sovereign wealth fund-backed developments prioritize asset lifecycle value over short-term operational expenditure minimization.
Middle East and Africa Soft Facility Management Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and technology integration depth. The vendor base fragments across British-heritage standards adherents, Gulf-based training academy operators, and IoT-integrated service innovators. Three archetypes dominate: premium-positioned certification holders, scale-driven integrated facility managers, and technology-augmented audit specialists. Consolidation pressure intensifies through pre-qualification requirements for giga-project contracts and ISO 41001 certification backlogs at accredited bodies.
Among British-heritage operators, Serco Group PLC occupies a position exemplifying premium government and aviation contract positioning. EFS Facilities Services Group and Farnek Services LLC represent the Gulf-based specialist tier, with the former anchoring expansion through in-house training infrastructure and the latter exemplifying IoT-integrated performance verification capabilities. These three entities illustrate competitive positioning strategies across certification depth, workforce development investment, and technology deployment intensity.
| Leading Market Players |
|---|
| Emrill Services LLC |
| Serco Group PLC |
| EFS Facilities Services Group |
| Initial Saudi Arabia Company Limited |
| Ecolab Inc. |
| Sodexo Inc. |
| Ejadah Asset Management Group |
| Kharafi National for Infrastructure Projects Developments Construction and Services SAE |
| Farnek Services LLC |
| Others |
Supply & Pricing Matrix
Fourteen-week lead times for commercial cleaning robotics from East Asian manufacturers compress vendor margins and concentrate pricing power with equipment suppliers who serve Saudi giga-project procurement cycles. This inventory-to-delivery gap forces regional operators to pre-position capital in sensor hardware before contract awards, linking supply chain rigidity directly to bid competitiveness.
Pricing Analysis
Volume-discount tiering separates ISO 41001-certified operators from uncertified competitors and informal labor brokers across the Middle East and Africa. Premium pricing attaches to real-time performance verification capabilities mandated by Estidama Pearl Rating and Saudi Building Code compliance, while economy tiers compete on headcount density for legacy commercial stock. Cost compression in the labor-intensive cleaning segment intensifies as South Asian expatriate wage volatility feeds through to contract renegotiation cycles. Government and aviation procurement shows lowest price sensitivity due to decade-long tenure structures, whereas retail mall operators in Cairo and Riyadh demonstrate highest elasticity to unit-rate bidding.
Supply Chain Analysis
Germany and Switzerland anchor commercial cleaning robotics manufacturing, while South Korea and Japan produce sensor hardware and building automation components serving regional facility management operators. European equipment draws from precision-machined drivetrains, lithium-ion battery packs, and machine-vision navigation systems. Single-source vulnerability concentrates in firmware-locked maintenance contracts that tie regional operators to original manufacturer service networks. Distribution runs through Dubai-based trading houses that hold regional inventory positions for rapid deployment to Saudi giga-project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 41001 certification capacity at accredited bodies trails procurement demand from Saudi giga-projects and UAE green building mandates, creating a credential bottleneck that reshapes competitive access. This scarcity dynamic favors operators who secured early-mover certification positions.
For Market Incumbents: Secure decade-long service pre-qualifications with NEOM and Red Sea Global before construction completion locks vendor rosters. Invest in captive training academies that produce technicians certified to Saudi Building Code integration standards, defending against emerging entrants who lack workforce development infrastructure. Backward integration into Arabic-localized software platforms reduces dependency on European CMMS vendors. For New Entrants and Emerging Players: Anchor in Egypt's formalization wave as Housing and Building National Research Center standards disqualify informal operators from Cairo and Alexandria government contracts. Target hybrid service delivery models in Abu Dhabi and Jeddah where asset managers retain compliance verification in-house and subcontract execution to specialists. Lead with IoT-integrated cleaning audit capabilities that satisfy real-time performance mandates without legacy cost structures. For Investors and Strategic Acquirers: Carve-out targets emerge from European facility management conglomerates divesting non-core Middle East operations to focus on domestic sustainability compliance. Long-term viability hinges on technology-augmented service verification capabilities that align with tightening green building regulations across the Gulf Cooperation Council. Monitor Saudi Building Code amendment cycles as inflection indicators for vendor qualification threshold shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Investment | Unlocks pre-qualification for NEOM and Red Sea Global procurement frameworks. |
| In-House Training Academy Development | Produces Saudi Building Code-certified technicians faster than regional accredited bodies. |
| IoT Platform Localization | Captures compliance documentation requirements under Estidama Pearl Rating mandates. |
| Hybrid Service Model Deployment | Matches Abu Dhabi sovereign wealth fund asset managers' retained oversight preferences. |
| Robotics Fleet Integration | Addresses labor cost volatility through overnight autonomous cleaning operations in Dubai towers. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with facility management executives, procurement officers at Saudi giga-project developers, and UAE green building compliance consultants; and secondary validation through Saudi Building Code amendments, Estidama Pearl Rating technical guides, and ISO 41001 certification body capacity disclosures. Bottom-up triangulation against top-down market sizing cross-checked contractor bid patterns and service contract tenures.
Across the analysis window, forecasts model service type segmentation, delivery model preferences, technology integration tiers, and end-user asset class requirements. CAGRs derive from contract pipeline visibility at NEOM and Red Sea Global, green building code enforcement timelines, and IoT solution adoption curves in Dubai commercial towers. Labor cost volatility indices and equipment import lead times feed sensitivity scenarios.
Material uncertainties — regulatory amendment cycles, expatriate visa policy shifts, and currency fluctuation exposure — sit outside the modeled envelope. Forecasts reflect assumptions about certification body capacity expansion and giga-project construction schedules. Recalibration cycles align with material shifts in Saudi Building Code enforcement and UAE green building mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Netherlands Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Croatia Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Egypt Facility Management Market