
 Global Unified Facility Management Market | 2026-2036
Global Unified Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unified Facility Management Market Foresight
Aftermarket service revenue from predictive maintenance contracts is reshaping how facility operators capture lifetime value from building portfolios. Sodexo S.A. leverages its food services heritage to bundle workplace experience offerings with traditional hard services. CBRE Group anchors its competitive stance through proprietary technology platforms that integrate vendor management with real-time asset tracking. ISS A/S specializes in labor-intensive cleaning and security operations across Nordic and Continental European accounts.
Unified facility management coordinates hard services, soft services, and building systems through a single accountability layer, typically governed by service level agreements spanning energy consumption, occupant satisfaction, and regulatory compliance. IoT Integration enables continuous monitoring of HVAC performance, lighting loads, and occupancy patterns to trigger automated work orders before equipment failure. Cloud Computing deployment models dominate new contract structures because real estate investment trusts and multinational corporations require centralized visibility across geographically dispersed properties. Artificial Intelligence applications in fault detection and energy optimization represent the fastest-expanding technology segment as owners seek to reduce utility spend without capital-intensive equipment replacement.
The EPA enforces refrigerant management rules that compel facility managers to track HVAC maintenance cycles, while the EU Green Deal mandates progressive carbon reduction targets for commercial buildings. OSHA workplace safety standards shape janitorial and security staffing protocols across US federal and state properties. Facility directors must evaluate whether cloud-based or hybrid deployment architectures align with cybersecurity requirements and data sovereignty constraints across their property portfolios.
Market Dynamics
Cloud-native deployment architectures are compressing contract cycles as real estate investment trusts demand centralized visibility across dispersed property portfolios without on-premise infrastructure overhead.
Growth Catalysts
- EU Green Deal carbon mandates:Commercial building owners across Germany and France face binding decarbonization timelines, accelerating technology upgrades to integrated energy management platforms.
- Smart building IoT convergence:HVAC, lighting, and access control systems now share unified data layers, enabling predictive maintenance contracts that extend service revenue streams.
- China's commercial real estate consolidation:State-owned enterprises and private developers in Shanghai and Beijing are bundling hard and soft services under single accountability structures.
Market Restraints
- Technical skill scarcity:Facility operators struggle to recruit technicians proficient in both legacy mechanical systems and cloud-based analytics platforms.
- Data sovereignty fragmentation:Multinational corporations face conflicting requirements between China's Cybersecurity Law and EU GDPR when deploying centralized facility management software.
- Cyber insurance cost inflation:Premiums for operational technology coverage have risen sharply, eroding margins on connected building contracts.
Strategic Opportunities
- India's commercial office expansion:Bengaluru and Hyderabad campuses present greenfield deployment opportunities for integrated facility services without legacy system displacement costs.
- AI-driven fault detection:Machine learning algorithms analyzing HVAC vibration and thermal patterns enable utility cost reduction without capital-intensive equipment replacement.
- US Inflation Reduction Act incentives:Tax credits for building energy efficiency retrofits create funded pathways for technology upgrade contracts.
Industry Challenges
- Interoperability protocol gaps:BACnet, Modbus, and proprietary IoT standards create integration friction when consolidating multi-vendor building systems.
- Workforce credentialing complexity:OSHA safety certifications, EPA refrigerant handling licenses, and state-level security clearances multiply compliance overhead for cross-functional service teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unified Facility Management Market |
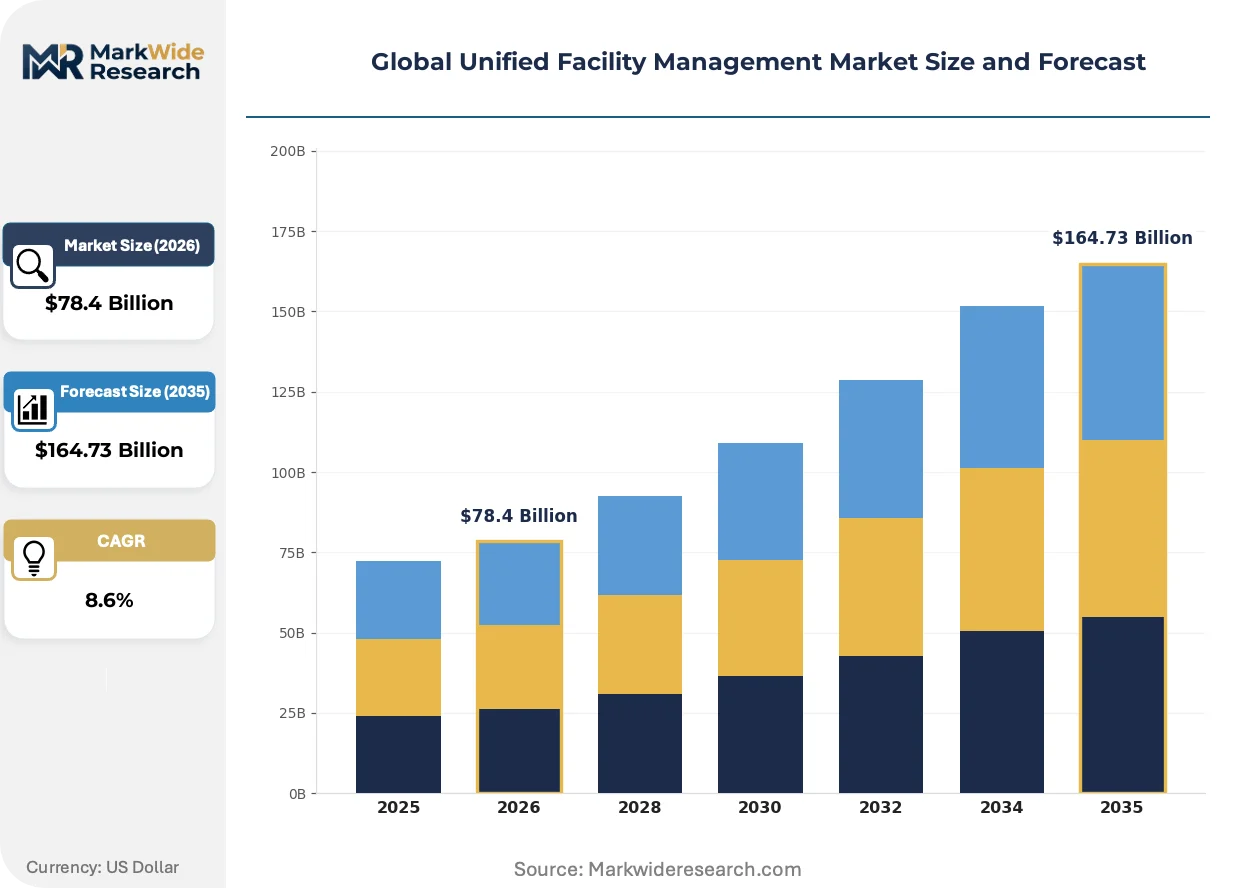
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Janitorial, Security, Landscaping, HVAC, Waste Management Technology: IoT Integration, Cloud Computing, Mobile Applications, BIM, Artificial Intelligence, Automation End User: Commercial Properties, Educational Institutions, Data Centers, Government Buildings, Retail Outlets, Hospitality Venues Deployment: On-Premise, Cloud-Based, SaaS, Hybrid, Managed Services |
| Companies Covered | ABM Industries Incorporated, Sodexo S.A., CBRE Group, Mitie Group plc, Cushman & Wakefield plc, Jones Lang LaSalle Incorporated, ISS A/S, Aramark Corporation, Emcor Group Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unified Facility Management Market Shifts & Advancements
Facility management is transitioning from reactive maintenance schedules to continuous performance optimization, with technology vendors embedding intelligence directly into service delivery workflows rather than treating software as a separate procurement category.
Digital twin technology is digitizing physical building assets into dynamic simulation models that mirror real-time HVAC, electrical, and occupancy conditions. Large corporate campuses in the United States are deploying these virtual replicas to test energy optimization scenarios before implementing physical changes. This capability is digitizing how facility directors justify capital investments and negotiate performance guarantees with service providers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with aggressive quota reductions through 2030. Facility managers must track equipment containing these gases through mandatory leak detection and reporting protocols. Cold storage and data center operators across Germany and the Netherlands are accelerating HVAC replacement cycles to avoid stranded asset risk from compliance penalties.
Corporate real estate buyers are consolidating vendor relationships from fragmented point solutions to integrated service platforms. Multinational technology firms with campuses in Ireland, Singapore, and Texas now issue single-source contracts spanning cleaning, security, and building systems maintenance. This concentration is most visible among pharmaceutical and financial services tenants with stringent regulatory audit requirements across their property footprints.
Global Unified Facility Management Market Segmentation
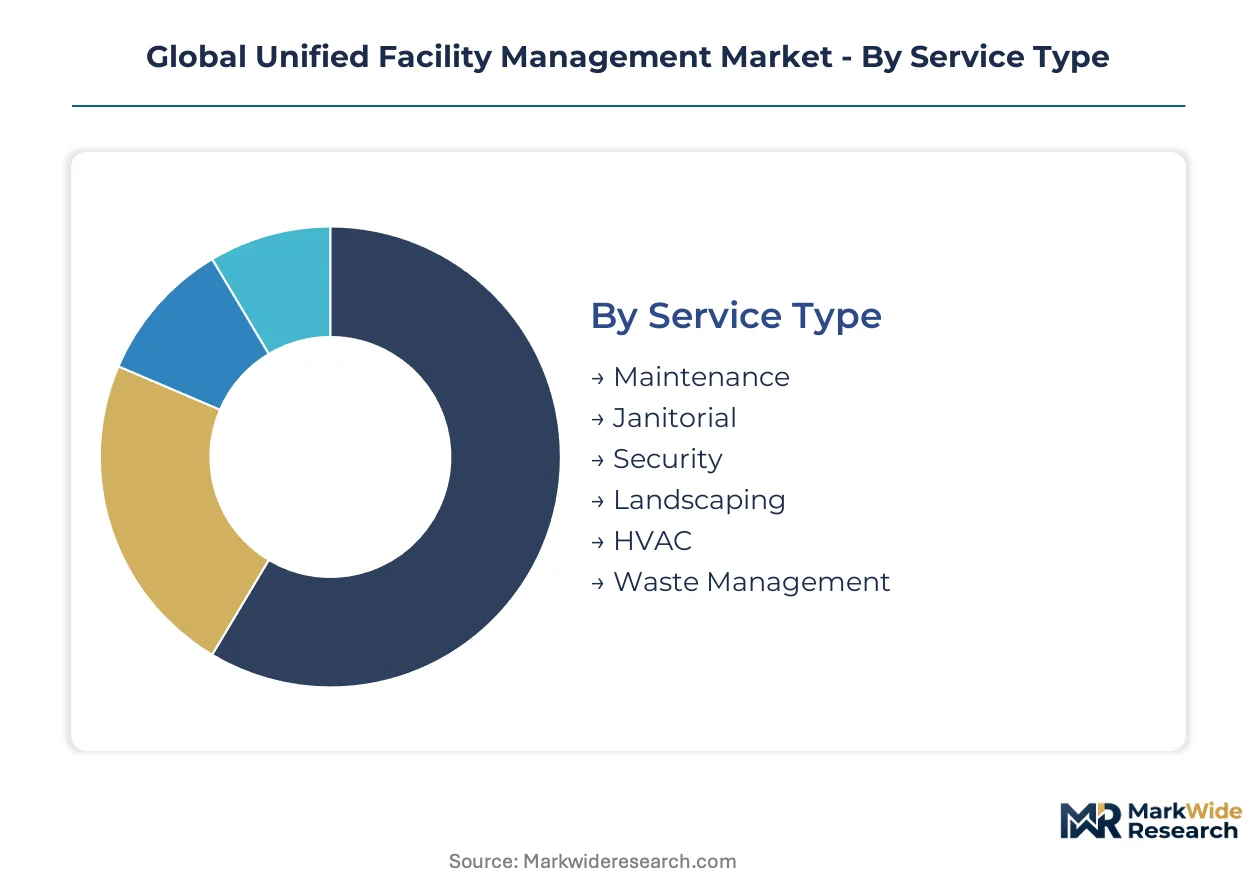
Unified facility management vendors structure their service portfolios around distinct operational layers that determine contract pricing, technology integration depth, and customer retention economics. Segmentation reveals where capital deployment concentrates and which service bundles command premium positioning.
Service Type:
Facility directors select service combinations based on asset criticality, regulatory exposure, and labor arbitrage potential across their building portfolios.
- Maintenance:Scheduled and corrective upkeep of mechanical, electrical, and plumbing systems. Demand concentrates among data center operators in Northern Virginia and Frankfurt seeking to minimize unplanned downtime under ISO 55000 asset management protocols.
- HVAC:Climate control system operation, refrigerant management, and energy optimization. Pharmaceutical campuses in Basel and Boston drive specification intensity due to FDA and EMA validation requirements for controlled environments.
- Security:Access control, surveillance, and personnel guarding services. Financial services towers in London and Singapore prioritize integrated physical-cyber security frameworks under national critical infrastructure regulations.
- Janitorial:Cleaning, sanitization, and waste removal operations. Healthcare-adjacent facilities in Melbourne and Toronto specify antimicrobial protocols exceeding baseline commercial standards.
- Landscaping:Exterior grounds maintenance and irrigation management. Corporate campuses in California and the UAE deploy drought-resistant design under municipal water restriction mandates.
- Waste Management:Collection, sorting, and regulatory-compliant disposal streams. EU Green Deal circular economy targets in France and Germany mandate separation and tracking of construction debris from commercial properties.
The dominant share belongs to Maintenance, while HVAC is closing the gap fastest.
Technology:
Technology selection determines whether facility operators achieve predictive capabilities or remain tethered to reactive service models.
- IoT Integration:Sensor networks capturing real-time occupancy, temperature, and equipment vibration data. Smart office complexes in Shanghai and Stockholm deploy these layers to automate work order generation before asset failure.
- Artificial Intelligence:Machine learning models for fault detection and energy load forecasting. REITs across Texas and Bavaria prioritize this segment to reduce utility spend without capital-intensive equipment replacement.
- Cloud Computing:Centralized data architecture enabling multi-property portfolio visibility. Multinational corporations with dispersed assets favor this deployment to satisfy GDPR and China's Cybersecurity Law through regional data residency.
- Automation:Robotic process execution for repetitive inspection and cleaning tasks. Airports in Dubai and Amsterdam trial autonomous floor cleaning to offset labor cost inflation.
- Mobile Applications:Field technician interfaces for work order management and asset documentation. Service providers in India and Brazil deploy these to bridge skill gaps in remote facility locations.
- BIM:Building Information Modeling for digital asset repositories and space planning. Healthcare construction projects in Sydney and Copenhagen mandate BIM handover for operational readiness.
Cloud Computing commands the largest installed base, though Artificial Intelligence is expanding most quickly.
End User:
End-user verticals impose distinct compliance, uptime, and experience requirements that reshape service provider capabilities.
- Commercial Properties:Office towers and mixed-use developments seeking operational consolidation. Demand clusters in Manhattan and Mumbai where landlords compete for tenant retention through workplace experience differentiation.
- Data Centers:Critical facilities demanding continuous cooling and power reliability. Hyperscale operators in Ashburn and Amsterdam specify redundant maintenance protocols under Uptime Institute tier certifications.
- Government Buildings:Federal, state, and municipal properties with security clearance and procurement rigor. US GSA and UK Crown Commercial Service frameworks dictate vendor qualification standards.
- Educational Institutions:Universities and K-12 districts with seasonal occupancy patterns. Campus operators in California and Ontario prioritize deferred maintenance backlogs during summer shutdown windows.
- Hospitality Venues:Hotels and conference facilities where guest experience drives brand equity. Luxury properties in Paris and Maldives specify white-glove service integration with building systems.
- Retail Outlets:Store networks requiring standardized service delivery across dispersed locations. Fast-fashion chains in Spain and Japan centralize vendor management for portfolio consistency.
Commercial Properties retain the deepest vendor relationships, yet Data Centers are gaining share fastest.
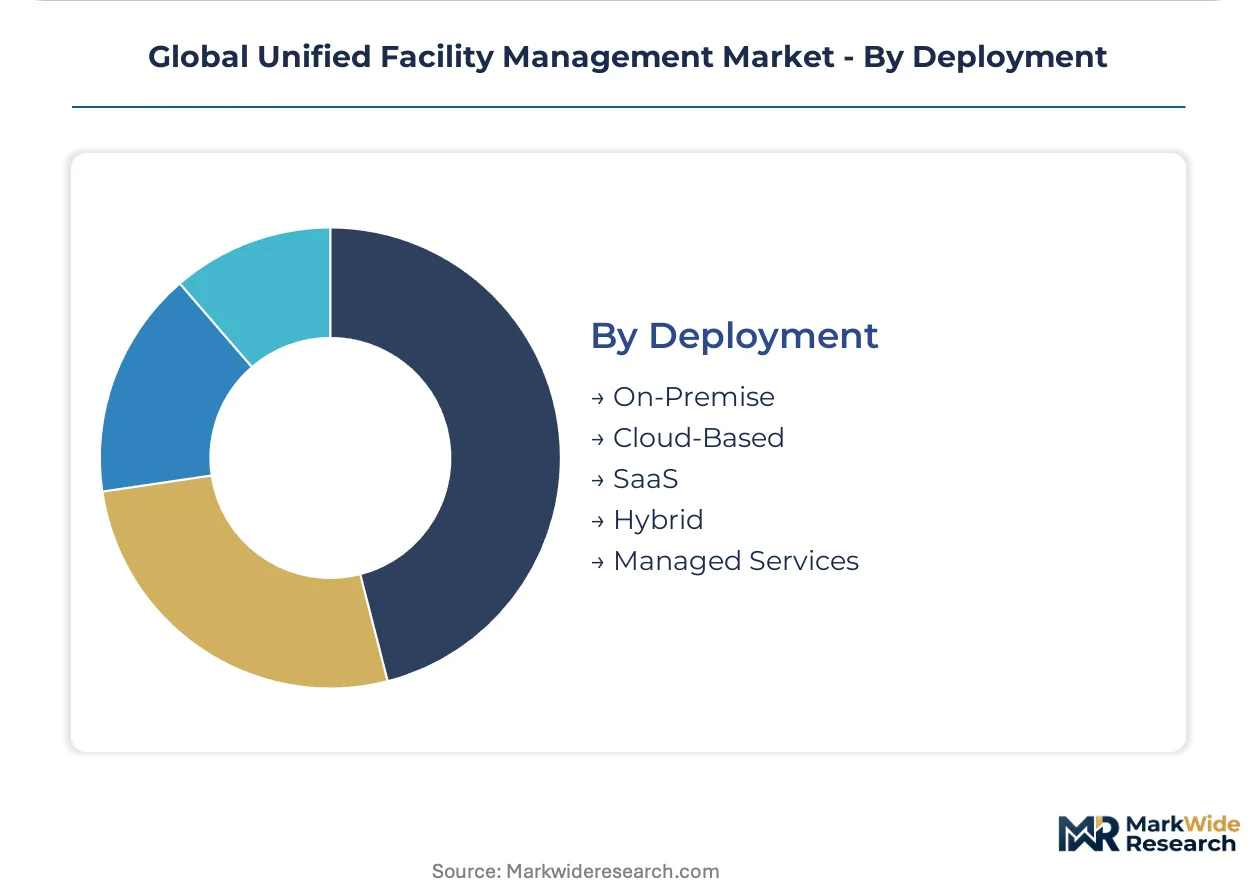
Deployment:
Deployment architecture selection reflects cybersecurity posture, data sovereignty constraints, and IT infrastructure maturity.
- Cloud-Based:Fully hosted software with browser or mobile client access. REITs and multinational corporations in Ireland and Singapore prefer this model to eliminate on-premise infrastructure overhead.
- Hybrid:Split architecture keeping sensitive operational data local while leveraging cloud analytics. German and Swiss facility operators favor this approach under national data residency requirements.
- SaaS:Subscription-licensed applications with vendor-managed updates. Mid-market property managers in Australia and Canada adopt this to convert capital expenditure to operational expenditure.
- Managed Services:Outsourced IT operations including hosting, security, and support. Owners with limited internal technology staff in Brazil and South Africa select this to access enterprise-grade capabilities.
- On-Premise:Self-hosted software within customer data centers. Defense contractors and classified facilities in the US and Israel mandate this for air-gapped security compliance.
Cloud-Based deployment leads current contract structures, while Hybrid architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement patterns diverge sharply across geographies. US real estate investment trusts prioritize predictive maintenance contracts with technology integration. European portfolios emphasize carbon compliance and energy performance contracting. Chinese state-owned enterprises favor bundled hard-soft service packages under single accountability structures.
United States
Data center clusters in Northern Virginia and hyperscale campuses in Texas drive demand for redundant HVAC maintenance under Uptime Institute certifications. The EPA enforces refrigerant management rules compelling facility managers to track HVAC maintenance cycles through mandatory reporting protocols. Corporate campuses in Manhattan compete for tenant retention through workplace experience differentiation bundled with building systems.
Germany
Pharmaceutical facilities in Basel-adjacent Baden-Württemberg and cold storage operators in the Netherlands border region specify intensive climate control validation. The EU F-Gas Regulation mandates aggressive hydrofluorocarbon quota reductions through 2030 with leak detection protocols. Industrial properties across Bavaria accelerate HVAC replacement cycles to avoid stranded asset risk from compliance penalties.
China
State-owned enterprises and private developers in Shanghai and Beijing consolidate hard and soft services under single-source accountability structures. The Cybersecurity Law imposes data residency requirements complicating centralized software deployment for multinational portfolios. Smart office complexes in Shenzhen deploy IoT sensor networks to automate work order generation before equipment failure.
India
Commercial office expansion in Bengaluru and Hyderabad presents greenfield deployment opportunities without legacy system displacement costs. The country's national building energy codes progressively mandate efficiency standards for new construction. IT parks across Karnataka specify integrated facility services to attract multinational technology tenants seeking operational consistency.
United Kingdom
Financial services towers in London prioritize integrated physical-cyber security frameworks under national critical infrastructure regulations. The Crown Commercial Service framework dictates vendor qualification standards for government property contracts. Mixed-use developments across the Southeast compete through workplace experience differentiation tied to building performance guarantees.
Global Unified Facility Management Market Competitive Landscape
Capability concentration sits with specialized technology integrators; scale advantage sits with diversified service conglomerates. The vendor base organizes around three tiers: global integrated providers with cross-border delivery infrastructure, regional specialists with deep regulatory expertise, and technology-native platforms disrupting traditional contract structures. Dominant competitive moves include portfolio diversification into adjacent workplace services and strategic partnerships with IoT platform vendors.
Within the diversified service tier, Sodexo S.A. and ISS A/S exemplify contrasting geographic specializations. Sodexo leverages its food services heritage to bundle workplace experience offerings with traditional hard services across multinational accounts. ISS anchors labor-intensive cleaning and security operations across Nordic and Continental European portfolios. CBRE Group occupies a position among technology-forward providers, anchoring competitive stance through proprietary platforms that integrate vendor management with real-time asset tracking.
| Leading Market Players |
|---|
| ABM Industries Incorporated |
| Sodexo S.A. |
| CBRE Group |
| Mitie Group plc |
| Cushman & Wakefield plc |
| Jones Lang LaSalle Incorporated |
| ISS A/S |
| Aramark Corporation |
| Emcor Group Inc |
| Others |
Supply & Pricing Matrix
Shanghai and Beijing service delivery clusters anchor capacity for integrated facility management platforms across Asia-Pacific, with their scale dynamics translating directly into pricing leverage for multinational contract renewals. Labor arbitrage from these hubs feeds downstream margin structures in Singapore and Sydney, while data residency requirements under China's Cybersecurity Law fragment pricing power for cloud-native deployments.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with REITs and pharmaceutical campuses locking in five-to-ten year service agreements to hedge against technician wage inflation. Three-tier pricing structure across premium, standard, and economy levels separates Tier 1 data center operators seeking Uptime Institute certification from mid-market commercial properties and government facilities with baseline compliance needs. Cost compression in standard-tier janitorial and security bundles is intensifying because ISS A/S and regional specialists compete on headcount efficiency. Government buyers under GSA and Crown Commercial Service frameworks exhibit highest price sensitivity due to rigid procurement scoring, while hyperscale data center operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for IoT sensor hardware and HVAC control systems deployed across multinational portfolios. Component manufacturing concentrates in China, Germany, and the United States, with facility operators drawing from these hubs for building automation controllers, refrigerant monitoring equipment, and cloud infrastructure. Raw material dependencies span copper for electrical systems, lithium for backup power, and specialized refrigerants subject to EU F-Gas Regulation quota restrictions. Single-source vulnerability persists for AI-enabled fault detection software from Silicon Valley and Nordic vendors. Distribution runs through direct vendor relationships for enterprise accounts and regional service integrators for mid-market properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent facility management conglomerates face substitution pressure from technology-native platforms embedding AI directly into service delivery workflows rather than treating software as a separate procurement layer.
For Market Incumbents: Insulate core maintenance revenue by acquiring specialized IoT platform vendors in Germany and the United States to close the predictive maintenance capability gap. Deepen backward integration into refrigerant management and HVAC controls to capture margin from EPA and EU F-Gas Regulation compliance cycles. Vertical integration into workplace experience services, following Sodexo's bundled model, defends against pure-play technology entrants. For New Entrants and Emerging Players: India's commercial office expansion in Bengaluru and Hyderabad presents the most penetrable geography for greenfield integrated service deployment without legacy system displacement costs. Target mid-market data center operators in Northern Virginia seeking alternatives to incumbent pricing for redundant HVAC maintenance. Lead with AI-driven energy optimization as the go-to-market wedge, offering utility cost reduction guarantees without capital-intensive equipment replacement. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because facility management vendor bases fragment across regional specialists with deep regulatory expertise and technology integrators with proprietary platforms. Acquisition target archetype: mid-cap European specialists with EU Green Deal carbon compliance capabilities and established pharmaceutical campus relationships. Watch for inflection signals in cyber insurance pricing for operational technology coverage, as premium stabilization indicates risk-model maturity for connected building contracts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Platform Integration | Machine learning fault detection reduces utility spend for REITs across Texas and Bavaria without equipment replacement. |
| Backward Integration into HVAC Controls | In-house production of refrigerant monitoring systems captures margin from EPA enforcement and EU F-Gas Regulation compliance. |
| Geographic Expansion into India | Bengaluru and Hyderabad campuses offer greenfield deployment without legacy displacement costs for integrated services. |
| Strategic Partnership with IoT Vendors | Sensor network alliances enable predictive maintenance contracts extending service revenue for smart office complexes. |
| Workplace Experience Bundling | Food services and building systems integration differentiates tenant retention for Manhattan corporate campuses. |
Research Methodology
A spread of perspectives from facility directors, procurement officers at REITs, HVAC maintenance technicians, IoT platform engineers, and regulatory compliance leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from ABM Industries and Emcor Group, EPA refrigerant enforcement databases, EU ETS carbon market registries, and commercial real estate transaction records. Bottom-up service revenue estimates triangulated against top-down building stock and energy consumption data.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeled across service type, technology deployment, end-user vertical, and regional regulatory cluster. CAGRs derived from historical contract value trajectories and projected technology adoption curves, incorporating HVAC equipment replacement cycles, IoT sensor penetration rates, and cloud migration timelines for property management software.
Practitioners should monitor EPA refrigerant rule enforcement intensity, EU Green Deal carbon mandate acceleration, and cyber insurance premium trajectories for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
UK Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
North America Soft Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Warehouse Management Service Market