
 Experimental Amateur-Built (E-AB) Aircraft Market | 2026-2036
Experimental Amateur-Built (E-AB) Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Experimental Amateur-Built (E-AB) Aircraft Market Insights
Carbon fiber is pivoting from racing applications into mainstream E-AB airframes as builders seek lighter, stronger alternatives to riveted aluminum. Van's Aircraft leverages its RV-series ecosystem to sustain a dominant position in the North American kit market. CubCrafters anchors the backcountry segment with specialized STOL designs that command premium positioning. Zenith Aircraft differentiates through all-metal designs that appeal to traditionalist builders seeking predictable fabrication.
Experimental amateur-built aircraft are non-type-certified flying machines constructed by individuals from prefabricated kits or raw materials, typically seating one to four occupants and operating under visual flight rules with empty weights ranging from 600 to 2,500 pounds depending on configuration. Fixed-wing configurations retain the largest share of active registrations due to simpler construction protocols and broader powerplant compatibility, though rotary-wing kits are gaining traction among technically advanced builders. Composite materials attract margin-focused suppliers because resin-infused layups reduce parts count and enable aerodynamic refinements impossible with sheet metal, while aluminum construction maintains volume leadership among first-time builders prioritizing repairability and proven fatigue characteristics.
The FAA governs E-AB certification through 14 CFR Part 21 and the accompanying 51-percent builder rule, which mandates that the amateur constructor perform the majority of fabrication and assembly to qualify for experimental airworthiness. EASA's lighter regulatory touch on microlight and amateur-built categories in member states such as Germany and France creates parallel demand corridors with divergent compliance burdens. ASTM standards for light sport aircraft indirectly influence E-AB powerplant selection as engine manufacturers design for overlapping certification spaces. Stakeholders must monitor whether FAA reauthorization debates alter the 51-percent threshold, as any relaxation would reshape competitive dynamics between kit manufacturers and factory-assisted build centers.
Market Dynamics
Composite airframe fabrication is compressing build timelines from years to months, expanding the addressable builder base beyond traditional metalworking craftsmen into digitally-native hobbyists seeking lower-skill entry points.
Growth Catalysts
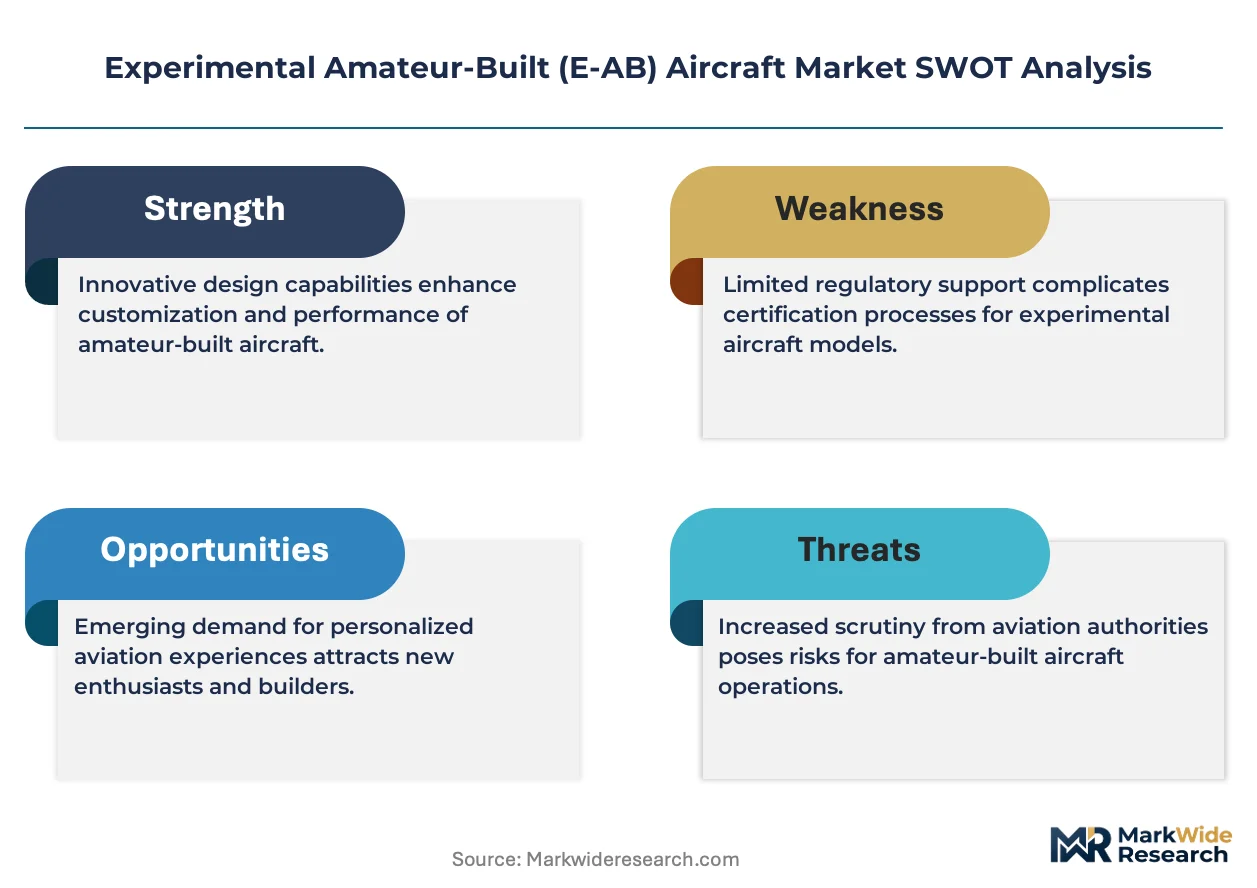
- FAA Part 23 Reforms:Streamlined certification pathways reduce regulatory friction for amateur constructors, accelerating kit registrations across the United States.
- Carbon Fiber Infusion:Resin transfer molding techniques cut parts count by two-thirds versus riveted aluminum, enabling complex aerodynamic shapes previously requiring factory tooling.
- Recreational Flyer Surge:Post-pandemic aviation interest draws new entrants seeking ownership economics below certified aircraft price points.
Market Restraints
- Aerospace-Grade Resin Volatility:Epoxy and pre-preg material costs fluctuate with petrochemical feedstock markets, squeezing margin for composite-focused kit suppliers.
- Powerplant Supply Concentration:Lycoming and Continental dominate piston engine supply for E-AB installations, creating bottleneck risk for builders awaiting factory-overhauled units.
- 51-Percent Rule Friction:FAA's amateur-built certification threshold blocks factory-assisted build centers from capturing time-constrained professional buyers.
Strategic Opportunities
- Australian Microlight Corridor:Civil Aviation Safety Authority's lighter regulatory framework permits commercial training in amateur-built aircraft, expanding revenue models beyond pure kit sales.
- Electric Propulsion Convergence:Battery-electric and hybrid-electric powertrains intersect with E-AB weight allowances, opening airframe-integrated energy storage designs.
- Digital Build Assist Channels:Remote expert guidance via augmented reality overlays reduces on-site mentor dependency for geographically isolated constructors.
Industry Challenges
- Composite Repair Skill Scarcity:Damage tolerance assessment and scarf repair techniques require specialized training absent from traditional A&P curricula.
- Flight Test Protocol Variability:Phase I operating limitations differ across FAA field offices, creating compliance uncertainty for builders relocating during construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Experimental Amateur-Built (E-AB) Aircraft Market |
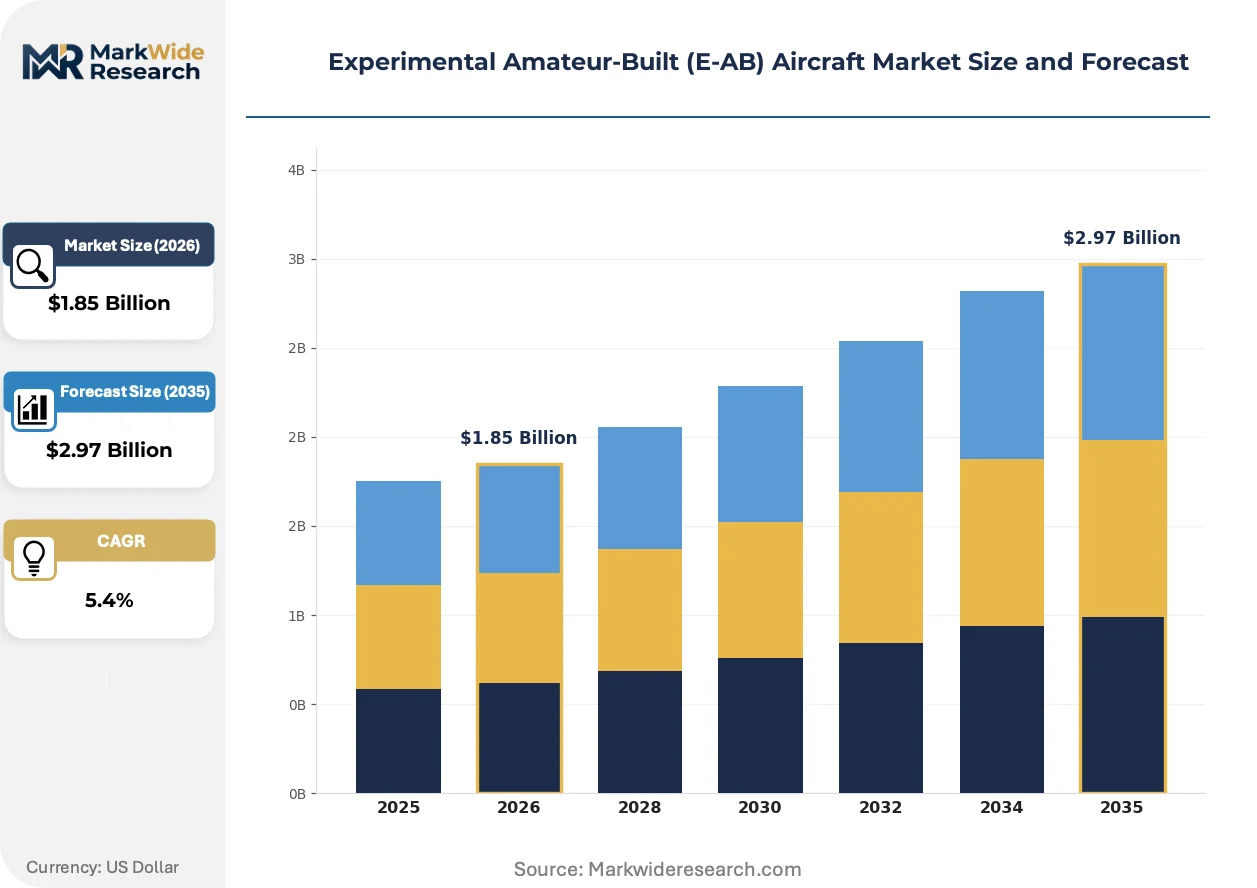
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotary-Wing, Gliders, Ultralight, Powered Parachutes Construction Material: Aluminum, Composite Materials, Wood, Fabric, Steel Tubing Engine Type: Piston, Turboprop, Electric, Rotary, Diesel End User: Private Pilots, Flight Schools, Aeroclubs, Recreational Flyers, Aviation Enthusiasts |
| Companies Covered | CubCrafters, Van's Aircraft, Zenith Aircraft, Kitfox Aircraft, Sonex Aircraft, Tecnam, Lancair International, Rans Designs, Czech Sport Aircraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Experimental Amateur-Built (E-AB) Aircraft Market Trends and Innovations
Digital fabrication workflows and regulatory modernization are converging to reshape how amateur aircraft move from kit boxes to flight-ready machines, compressing traditional build timelines while elevating safety expectations.
Pre-impregnated carbon fiber is decentralizing airframe production from centralized factories to individual workshops. First-time builders lacking metalworking backgrounds now complete composite layups with vacuum-bagging equipment costing under five thousand dollars. This capability diffusion is fragmenting the traditional skill hierarchy that once gated market entry.
EASA's lighter touch on microlight and amateur-built categories in Germany and France creates regulatory arbitrage opportunities absent from FAA jurisdiction. Builders in these member states access simplified operational approvals and reduced flight test hour minimums. The divergence pressures kit manufacturers to maintain dual compliance documentation streams.
Builder assistance models are unbundling from geographic proximity constraints. Factory-sponsored build centers now supplement physical presence with video-guided fabrication sequences and real-time quality verification through mobile imaging. Australia and Germany lead this hybrid support adoption, where remote mentorship sustains construction momentum through weather-bound winter months.
Experimental Amateur-Built (E-AB) Aircraft Market Segmentation
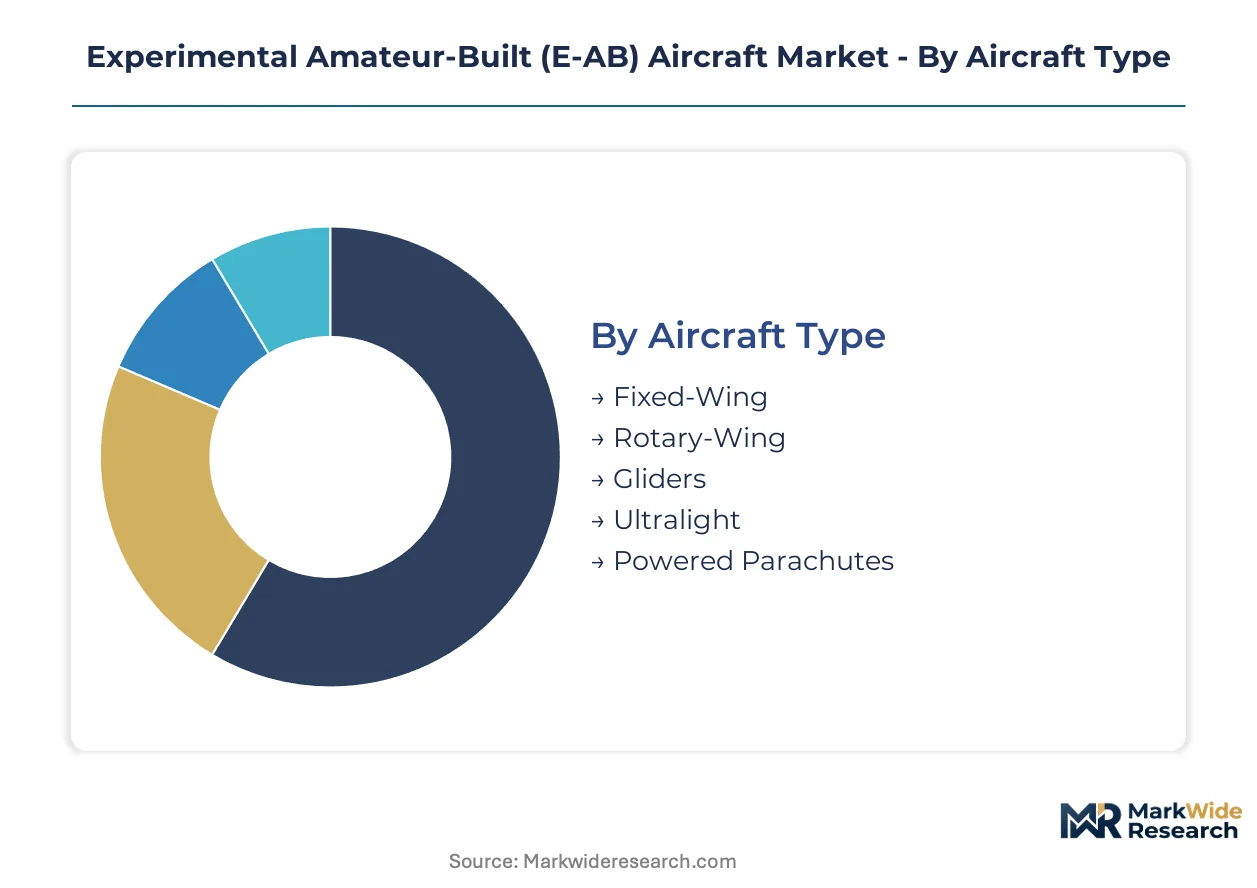
Segmentation in the E-AB market reveals how builder preferences fragment across fabrication philosophy, performance requirements, and regulatory pathways. Each category exposes distinct supply chain configurations and margin structures that kit manufacturers must navigate.
Aircraft Type:
Customization intensity varies sharply across this category, from standardized plans-built designs to bespoke aerobatic configurations demanding extensive engineering judgment.
- Fixed-Wing:Dominant configuration spanning low-wing sport planes to high-wing bush aircraft. Demand concentrates among first-time builders in the United States and Australia seeking predictable flight characteristics and broad engine compatibility. The RV-series ecosystem from Van's Aircraft anchors volume here.
- Rotary-Wing:Helicopter and gyroplane kits demand advanced metallurgical and rotor dynamics expertise. Builders cluster in Germany and France where EASA microlight frameworks reduce certification friction for technically sophisticated amateurs.
- Gliders:Self-launching motor-gliders and pure sailplanes attract performance-focused constructors prioritizing glide ratio over cruise speed. German aeroclubs sustain concentrated demand.
- Ultralight:Weight-restricted designs operating under Part 103 exemptions in the United States. Australian Civil Aviation Safety Authority permits commercial training in this category, expanding revenue models.
- Powered Parachutes:Minimal airframe complexity with fabric wing deployment. Entry-level builders in recreational aviation clusters favor these for sub-50-hour build timelines.
Leading the category by volume: Fixed-Wing. Growing fastest: Rotary-Wing.
Construction Material:
Cost tiers stratify sharply here, from commodity aluminum sheet to aerospace-grade pre-preg carbon fiber systems commanding 4-5x material cost multiples.
- Aluminum:Riveted sheet metal construction remains the default for first-time builders prioritizing repairability and predictable fatigue characteristics. Volume leadership persists among traditionalist constructors in the United States and Germany.
- Composite Materials:Resin-infused carbon fiber and fiberglass enable complex aerodynamic shapes impossible with metal. Australian builders adopt these methods fastest as vacuum-bagging equipment costs drop below five thousand dollars.
- Wood:Traditional spruce-and-plywood methods survive in vintage reproduction and cost-sensitive segments. European heritage aircraft restoration sustains niche demand.
- Fabric:Dacron or polyester covering over steel or wood frames dominates ultralight and backcountry STOL designs. CubCrafters specializes here with premium positioning.
- Steel Tubing:Welded 4130 chromoly frames provide crashworthiness and repairability for aerobatic and bush aircraft. American builders favor this for welded fuselage structures.
Volume concentration: Aluminum. Steepest expansion trajectory: Composite Materials.
Engine Type:
Application requirements drive segmentation here, from economy-focused piston installations to experimental electric powertrains redefining weight-and-balance calculations.
- Piston:Lycoming and Continental four- and six-cylinder engines dominate E-AB installations. Supply bottlenecks for factory-overhauled units constrain build completion timelines across all major markets.
- Turboprop:Pratt & Whitney PT6 derivatives and smaller Garrett units power high-performance homebuilts. German and French builders lead adoption for pressurized cabin designs.
- Electric:Battery-electric powertrains intersect with E-AB weight allowances, enabling airframe-integrated energy storage. Australian regulatory flexibility accelerates flight testing here.
- Rotary:Mazda and Mazda-derived Wankel engines offer power-to-weight advantages for pusher configurations. Niche adoption among performance-focused builders.
- Diesel:Thielert and Continental CD-100 series provide Jet-A compatibility for international travel. European builders prioritize this for fuel availability across borders.
Market share leader: Piston. Gaining share fastest: Electric.
End User:
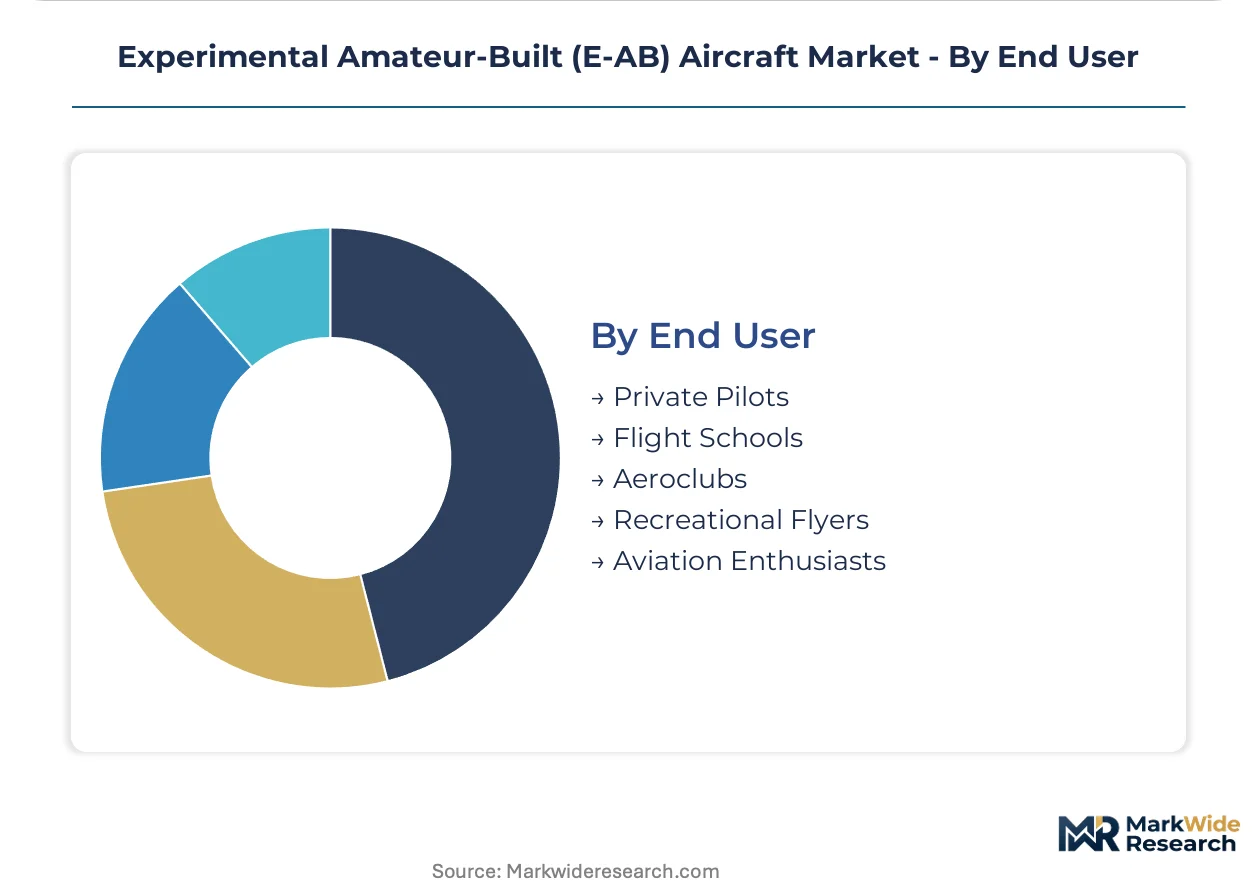
Customer type determines build assistance requirements, from solo garage projects to aeroclub collective fabrication with shared tooling.
- Recreational Flyers:Post-pandemic aviation interest draws new entrants seeking ownership economics below certified aircraft price points. This cohort expands fastest across the United States and Australia.
- Private Pilots:Certificated pilots building for personal transportation or proficiency maintenance. FAA Part 23 reforms streamline their certification pathways.
- Flight Schools:Australian CASA permits commercial training in amateur-built aircraft, creating fleet acquisition demand absent from FAA jurisdiction.
- Aeroclubs:Collective build programs spread capital costs and fabrication expertise across member bases. German clubs sustain strong tradition here.
- Aviation Enthusiasts:Builders prioritizing fabrication process over flight hours, often completing multiple projects. Zenith Aircraft's all-metal designs attract this traditionalist segment.
Dominant by volume: Private Pilots. Expanding most quickly: Recreational Flyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational flyers concentrate in the United States, Australia, and Germany, where regulatory frameworks and aeroclub infrastructure sustain the highest kit registration densities. FAA Part 23 reforms and EASA microlight pathways create divergent compliance corridors that manufacturers must navigate simultaneously.
United States
Recreational flyers and certificated private pilots drive kit demand through Van's Aircraft RV-series ecosystems and CubCrafters backcountry designs. FAA's 14 CFR Part 21 and the 51-percent builder rule govern certification, though reauthorization debates threaten threshold relaxation. Oregon and Washington host concentrated builder communities with factory-sponsored assistance centers.
Australia
CASA's lighter regulatory touch permits commercial training in amateur-built aircraft, expanding revenue models beyond pure kit sales. Composite material adoption accelerates fastest here as vacuum-bagging equipment costs drop below five thousand dollars. Queensland and New South Wales sustain aeroclub collective build programs with shared tooling infrastructure.
Germany
EASA microlight frameworks reduce certification friction for technically sophisticated amateurs constructing rotary-wing and glider configurations. German aeroclubs maintain strong collective build traditions spreading capital costs across member bases. Bavaria and Baden-Württemberg concentrate heritage aircraft restoration and spruce-and-plywood construction expertise.
France
EASA's streamlined operational approvals and reduced flight test hour minimums attract builders seeking simplified compliance pathways. Diesel powertrain adoption concentrates here for Jet-A compatibility across European borders. The Provence-Alpes-Côte d'Azur region sustains performance-focused motor-glider constructors prioritizing glide ratio optimization.
United Kingdom
Post-Brexit regulatory divergence from EASA creates uncertainty for kit manufacturers maintaining dual compliance documentation streams. Traditionalist builders favor all-metal designs with predictable fatigue characteristics and repairability. The Southeast and Midlands host concentrated aviation enthusiast communities completing multiple sequential projects.
Experimental Amateur-Built (E-AB) Aircraft Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with kit producers commanding premium positioning through ecosystem lock-in while component suppliers compete on material cost efficiency. The vendor base organizes around fabrication philosophy rather than scale, creating tiered competition between composite-centric innovators and metal-traditionalist incumbents. Three archetypes dominate: ecosystem-anchored full-kit providers, material-specialist airframe fabricators, and powerplant-integrated system integrators. Capacity expansion through factory-assisted build centers and technology licensing for resin transfer molding represent the dominant competitive moves.
Among North American kit manufacturers, Van's Aircraft, CubCrafters, and Zenith Aircraft exemplify divergent strategic positioning. Van's Aircraft occupies the ecosystem-anchored archetype through RV-series platform dominance. CubCrafters represents the specialization vector with premium backcountry STOL positioning. Zenith Aircraft sits within the traditionalist tier, appealing to builders seeking predictable all-metal fabrication protocols. These three companies collectively illustrate how fabrication philosophy segmentation creates defensible competitive territory without direct price confrontation.
| Leading Market Players |
|---|
| CubCrafters |
| Van's Aircraft |
| Zenith Aircraft |
| Kitfox Aircraft |
| Sonex Aircraft |
| Tecnam |
| Lancair International |
| Rans Designs |
| Czech Sport Aircraft |
| Others |
Pricing and Supply Chain Analysis
Kit-to-fly pricing bifurcation separates factory-complete ecosystems from plans-only entry points, compressing margins for aluminum-focused incumbents while carbon-fiber specialists capture premium positioning through resin transfer molding capabilities. This tier divergence maps directly onto supply chain configurations, where aerospace-grade epoxy and pre-preg feedstock tether composite manufacturers to petrochemical volatility while riveted-aluminum builders source from distributed commodity metals distributors.
Pricing Analysis
Volume leadership concentrates in sub-fifty-thousand-dollar all-metal kits where Zenith Aircraft and Van's Aircraft compete on builder support ecosystem breadth, while margin accretion flows to carbon-fiber backcountry designs commanding seventy-percent premiums through STOL performance differentiation. Price differentiation hinges on fabrication complexity tier and FAA certification assistance bundling, with factory-assisted build centers capturing time-constrained professionals despite 51-percent rule friction. Pricing pressure stems from Lycoming and Continental engine supply bottlenecks extending completion timelines and inflating powerplant procurement costs. Recreational flyers exhibit highest price sensitivity, deferring purchases when kit-plus-engine packages exceed certified used-aircraft alternatives; aviation enthusiasts demonstrate lowest sensitivity, prioritizing fabrication process over total cost of ownership.
Supply Chain Analysis
Aerospace-grade resin supply rests on German and Japanese specialty chemical producers, with carbon-fiber pre-preg drawing from Toray and Hexcel manufacturing concentrated in the United States and France. Raw material dependencies span petrochemical-derived epoxy systems, PAN-based carbon fiber tow, and 6061-T6 aluminum sheet from Chinese and Russian smelters. Single-source vulnerability concentrates in Lycoming and Continental piston engine supply, where factory-overhauled unit backlogs create eighteen-month completion delays. Distribution runs through direct-to-builder kit shipments from Oregon and Washington factory centers, supplemented by Australian and German regional warehousing for aeroclub collective procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as kit manufacturers pursue captive carbon-fiber preform production to insulate margins from aerospace resin volatility and secure supply continuity for resin transfer molding expansion.
For Market Incumbents: Anticipate regulatory arbitrage pressure from EASA microlight frameworks in Germany and France by maintaining dual compliance documentation streams, while deepening backward integration into carbon-fiber preform manufacturing to offset petrochemical feedstock volatility. Factory-assisted build centers represent a channel control lever blocked by FAA 51-percent thresholds; monitor reauthorization debates for threshold relaxation that would unlock time-constrained professional buyer segments. For New Entrants and Emerging Players: Capture the Australian commercial-training revenue model enabled by CASA's lighter regulatory touch on amateur-built aircraft operations, where flight schools seek fleet economics below certified aircraft price points. The rotary-wing segment offers lowest competitive density among technically sophisticated builders in Germany and France; pursue gyroplane kit development with EASA microlight pathway optimization as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in ecosystem-anchored full-kit providers with recurring component revenue streams and builder community lock-in. Long-term viability favors manufacturers with carbon-fiber fabrication capabilities and factory-assisted build center networks spanning multiple regulatory jurisdictions. Watch FAA reauthorization outcomes as the primary inflection signal; 51-percent rule relaxation would reshape competitive dynamics between kit manufacturers and factory-assisted build centers overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Transfer Molding Capacity Expansion | Enables complex aerodynamic shapes while cutting parts count by two-thirds versus riveted aluminum construction methods. |
| Factory-Assisted Build Center Network | Captures time-constrained professional buyers blocked by FAA 51-percent amateur-builder certification thresholds. |
| Dual Compliance Documentation Investment | Maintains market access across FAA Part 21 and EASA microlight regulatory corridors in Germany and France. |
| Electric Propulsion Integration Program | Positions airframe designs for battery-electric powertrains intersecting with E-AB weight allowances in Australia. |
| Remote Digital Build Assistance Platform | Reduces geographic dependency through augmented reality overlays sustaining construction momentum through weather-bound months. |
Research Methodology
FAA registration databases, EASA microlight certification records, and kit manufacturer shipment disclosures formed the secondary backbone, triangulated with primary interviews of kit manufacturer product managers, aeroclub fleet acquisition officers, and A&P mechanic instructors. Builder community forums and flight school procurement directors provided demand-side validation, while customs data on carbon-fiber pre-preg and aluminum sheet imports anchored supply-side estimation. Bottom-up kit shipment aggregation and top-down addressable builder population analysis were cross-referenced for convergence.
Historical trendline analysis of active registrations and kit deliveries established baseline growth patterns across the projection horizon. Segmentation modeling incorporated aircraft type, construction material, engine configuration, end-user archetype, and regulatory jurisdiction dimensions. CAGRs were derived from regression analysis of kit shipment volumes against driver variables including FAA Part 23 reform implementation timelines, composite material cost trajectories, and recreational aviation interest indices. Forecast inputs included powerplant supply bottleneck duration assumptions and electric propulsion technology readiness assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAA reauthorization debates, aerospace resin price volatility, and electric propulsion certification pathway evolution. Forecasts reflect documented assumptions on builder demographic shift rates and regulatory threshold stability. A small set of named triggers—FAA 51-percent rule modification, EASA microlight framework harmonization, and battery-electric powertrain weight-breakthrough announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Door Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Air Deflector Market
Aircraft
France Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Active Air Deflector Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
GCC Business Jet Market