
 Aircraft Cabin Windows, Shades & Blinds Market | 2026-2036
Aircraft Cabin Windows, Shades & Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cabin Windows, Shades & Blinds Market Insights
Multi-source procurement for transparencies and dimmable systems is recalibrating how tier-one aerostructures contractors manage their supply bases. PPG Aerospace leverages its vertically integrated optical coatings operation to secure long-term OEM contracts for cockpit and cabin windows. GKN Aerospace sustains competitive position through advanced thermoplastic processing capabilities that reduce frame weight versus traditional acrylic constructions. Gentex Corporation dominates the electrochromic segment with proprietary SPD film deposition technology that commands premium positioning in business jet retrofits.
Aircraft cabin windows, shades and blinds encompass transparent or dimmable apertures and their associated light-management coverings, typically fabricated from stretched acrylic, polycarbonate laminates, or glass composites with conductive oxide layers, engineered to maintain pressurization integrity while controlling solar heat gain and passenger comfort. The primary commercial purpose centers on regulating cabin illumination and thermal load without compromising structural performance at altitude. Electrochromic windows and smart glass panels lead product-type value generation due to their elimination of mechanical shade mechanisms and associated maintenance burden. Among applications, commercial airliners anchor volume demand while business jets concentrate margin pools through customized dimmable installations. Aircraft manufacturers as end users control specification authority, though aircraft retrofitters represent the fastest-growing channel as aging fleets undergo cabin modernization programs.
FAA Part 25 airworthiness standards govern flammability, impact resistance, and optical properties for U.S.-certified installations, while EASA CS-25 imposes parallel requirements across European jurisdictions that OEMs must satisfy for dual-type certification. The EU Green Deal's trajectory for aviation emissions reduction is pressuring suppliers to develop lighter-weight window assemblies that contribute to fleet fuel efficiency targets. Stakeholders must monitor evolving certification timelines for next-generation photochromic and polymer-dispersed liquid crystal technologies that promise to merge dimming performance with simplified regulatory compliance.
Market Dynamics
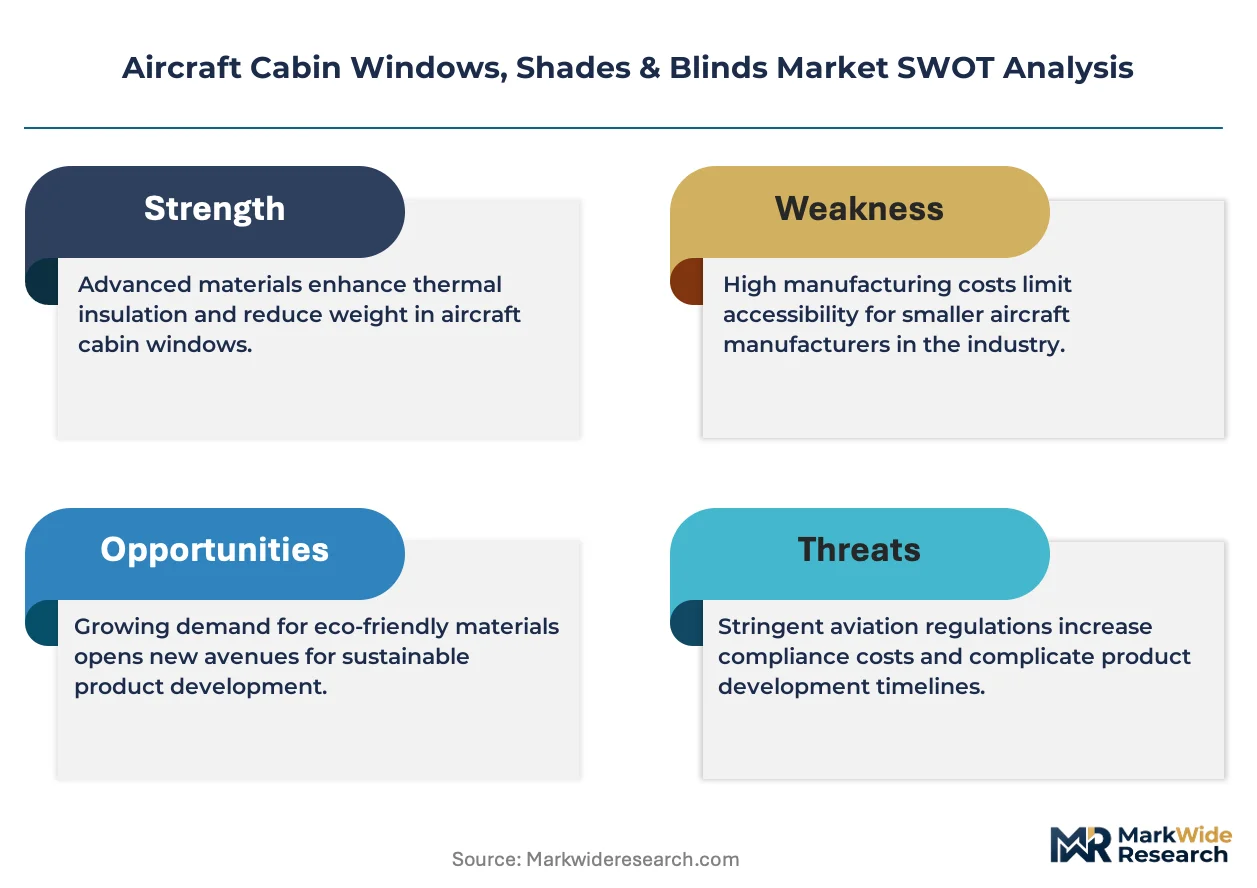
Fleet modernization cycles and regulatory pressure on aircraft weight are compressing procurement timelines for integrated window and shade systems, forcing tier-one suppliers to consolidate optical coating and frame manufacturing capabilities.
Growth Catalysts
- FAA Part 25 Certification Alignment:Harmonized flammability and impact standards between Washington and Brussels are reducing dual-certification costs for transparency manufacturers, accelerating new product introductions.
- Narrow-Body Fleet Renewal:Airlines replacing aging single-aisle aircraft with fuel-efficient platforms are specifying factory-installed electrochromic systems rather than aftermarket mechanical shades.
- SPD Film Deposition Advances:Proprietary manufacturing processes for suspended particle device layers are lowering unit costs and expanding retrofit applicability across business aviation.
Market Restraints
- Acrylic Monomer Supply Concentration:Stretched acrylic substrate production clusters in Gulf Coast petrochemical corridors, exposing window fabricators to hurricane-related supply interruptions.
- EASA CS-25 Optical Clarity Requirements:Stringent haze and light-transmission specifications for pressurized cabin installations are extending qualification timelines for experimental polymer formulations.
- Mechanical Shade Substitution:Low-cost manual blind systems retain dominant share in regional turboprop and cargo conversions where capital constraints override passenger experience investments.
Strategic Opportunities
- India Civil Aviation Expansion:IndiGo and Air India's narrow-body order backlogs create captive demand for line-fit window assemblies at emerging MRO clusters in Hyderabad and Bengaluru.
- EU Green Deal Weight Mandates:Emissions reduction frameworks incentivize kilogram-level savings from thermoplastic window frames versus legacy acrylic constructions.
- Photochromic-Liquid Crystal Convergence:Hybrid dimming technologies combining UV-responsive and electric-field modulation promise simplified wiring architectures for retrofit installations.
Industry Challenges
- Optical Coating Technician Scarcity:Vacuum deposition and conductive oxide application skills concentrate at PPG Aerospace's Huntsville and Sylmar facilities, constraining workforce mobility.
- Dual Certification Timeline Compression:Simultaneous FAA and EASA validation for novel transparency designs demands parallel test programs that strain engineering bandwidth at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cabin Windows, Shades & Blinds Market |
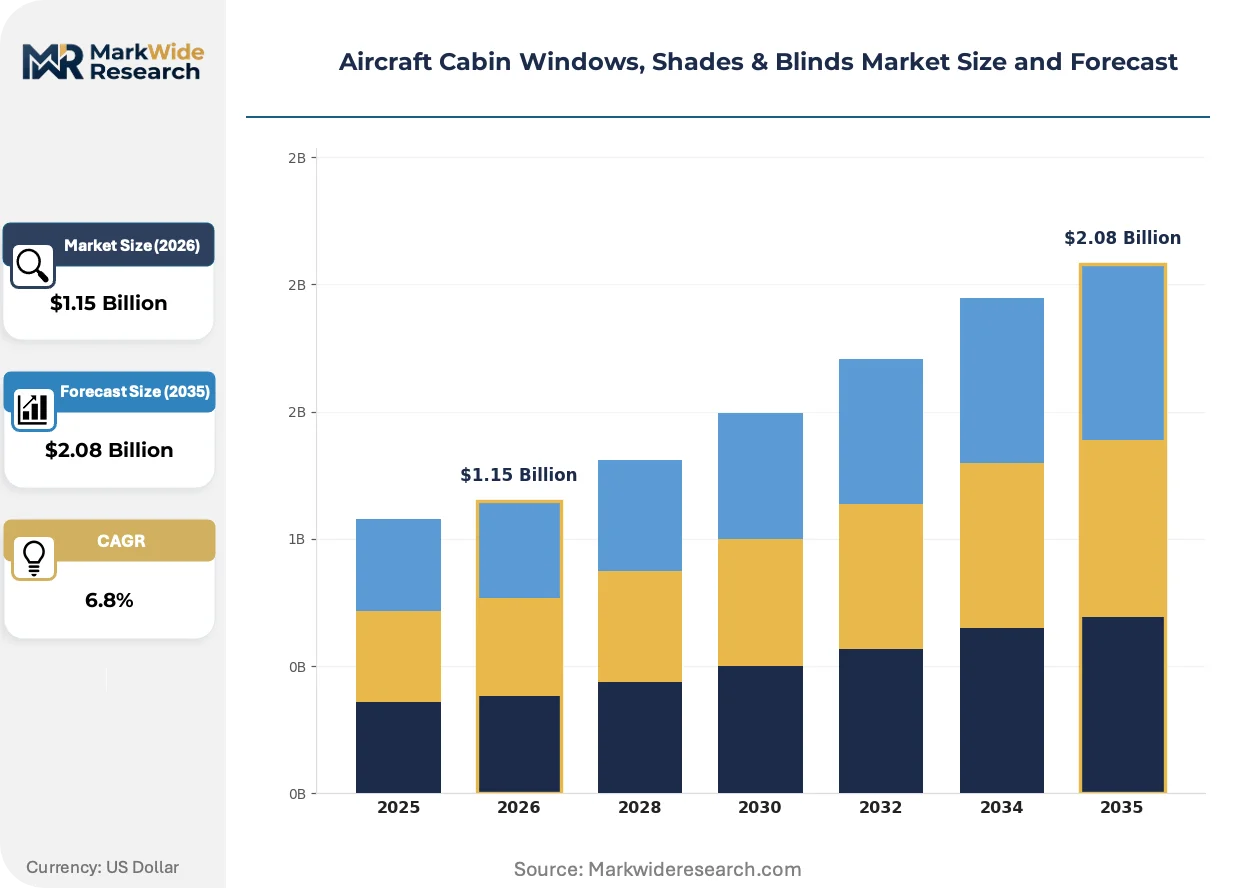
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic Windows, Mechanical Shades, Hybrid Blinds, Manual Shades, Smart Glass Panels Technology: Liquid Crystal Display, Polymer Dispersed Liquid Crystal, Suspended Particle Devices, OLED, Photochromic Films Application: Commercial Airliners, Business Jets, Military Aircraft, Cargo Planes, Amphibious Aircraft End User: Aircraft Manufacturers, Aircraft Maintenance Providers, Airline Operators, Aircraft Retrofitters |
| Companies Covered | PPG Aerospace, GKN Aerospace, Gentex Corporation, Saint-Gobain Aerospace, Nordam, Lee Aerospace, Perkins Aircraft Windows, Gal Aerospace, ATG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cabin Windows, Shades & Blinds Market Trends and Innovations
Material science breakthroughs and regulatory harmonization are collapsing the traditional separation between structural transparency and active dimming functionality, reshaping how OEMs specify integrated cabin apertures.
Electrochromic window systems employing tungsten oxide and nickel oxide intercalation layers are converging with structural polycarbonate substrates to eliminate separate shade mechanisms entirely. Boeing and Airbus are specifying these integrated assemblies for next-generation narrow-body programs, compressing supplier tiering from three layers to two. This convergence is forcing acrylic specialists to acquire coating capabilities or exit the dimmable segment entirely.
EASA's tightening CS-25 Amendment 25-157 requirements for emergency egress visibility are mandating redundant power supplies for all electrically dimmable installations. European carriers operating mixed fleets must now retrofit older electrochromic windows or restrict them to daytime operations, creating aftermarket service demand. The regulation is accelerating development of fail-clear modes that default to transparent state upon electrical failure.
Airline technical procurement teams are consolidating window and shade specifications under single-source contracts rather than fragmenting transparency and mechanism awards. This behavioral shift favors suppliers with captive optical coating and frame extrusion capabilities, disadvantaging pure-play shade manufacturers. The pattern is most pronounced among US network carriers modernizing domestic narrow-body fleets at Seattle and Charleston assembly points.
Aircraft Cabin Windows, Shades & Blinds Market Segmentation
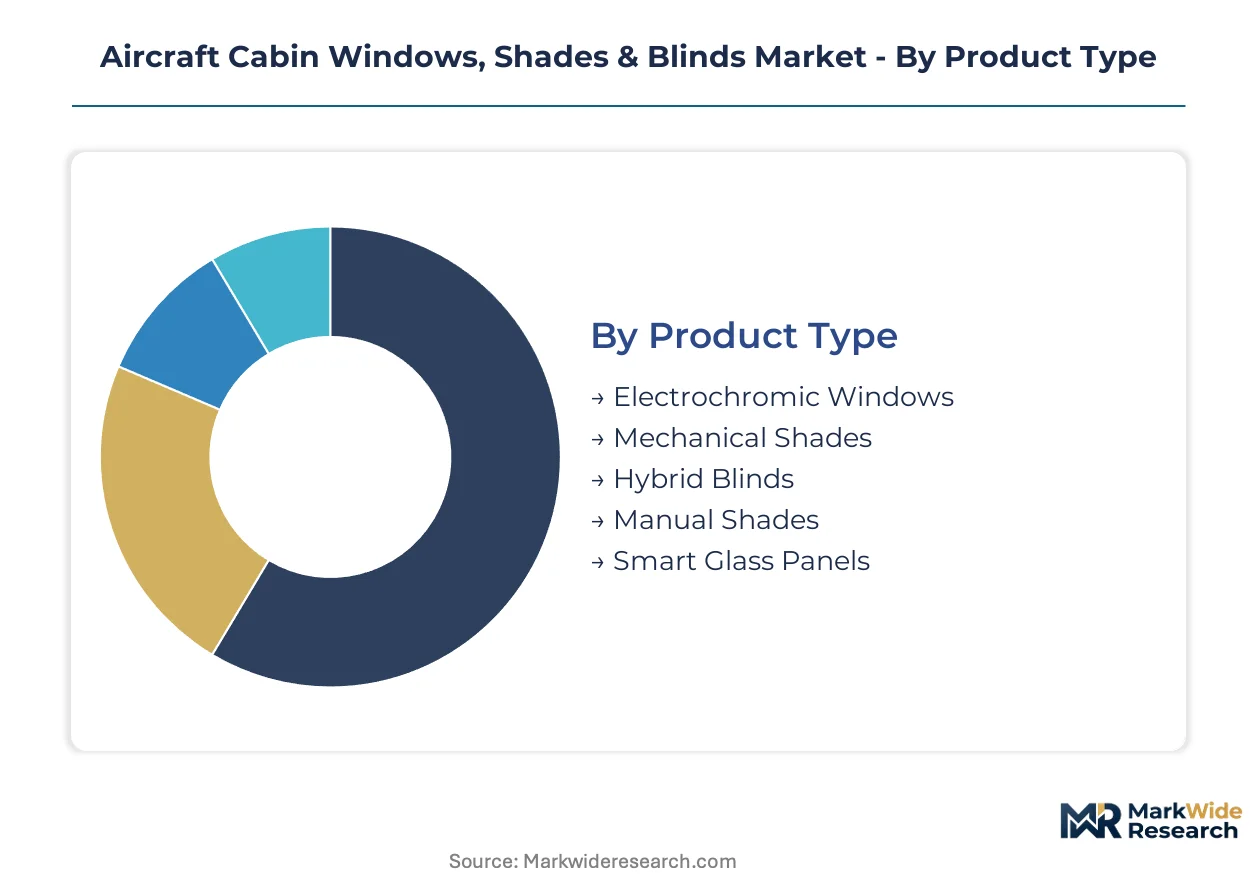
Aircraft cabin window systems fragment across four distinct taxonomies that determine procurement authority and margin capture. Product type and technology classifications dominate engineering specifications, while application and end-user dimensions govern contract structures and aftermarket service economics.
Product Type:
Supply concentration for active dimming systems clusters around electrochromic specialists with captive coating capabilities, while mechanical shade production disperses across commodity fabricators.
- Electrochromic Windows:Tungsten oxide and nickel oxide intercalation layers deposited on polycarbonate substrates enable voltage-controlled tint modulation without moving parts. Boeing's 787 and Airbus A350 programs at Charleston and Toulouse anchor OEM demand for line-fit installations, though EASA CS-25 Amendment 25-157 mandates redundant power supplies that extend qualification timelines.
- Smart Glass Panels:Polymer-dispersed liquid crystal and suspended particle device films laminated between conductive oxide layers deliver instant dimming response for premium cabin zones. Gulfstream and Dassault Falcon programs at Savannah and Little Rock concentrate retrofit demand as business jet operators replace mechanical assemblies.
- Mechanical Shades:Woven polyester or aluminum slat systems with manual or motorised actuation retain dominance in regional turboprop conversions where acquisition cost constraints override passenger experience specifications.
- Hybrid Blinds:Combined electro-mechanical architectures pair motorized roller mechanisms with integrated tint films for redundant light control in VIP configurations.
- Manual Shades:Simple spring-loaded or track-mounted fabric panels persist in cargo conversions and aging narrow-body fleets undergoing minimal cabin modernization.
Today's leader: Electrochromic Windows. Tomorrow's challenger: Smart Glass Panels.
Technology:
Cost tier stratification separates mature deposition processes from emerging film technologies still navigating dual-certification pathways.
- Suspended Particle Devices:Rod-shaped nanoparticles suspended in polymer matrix align under electric field to block light transmission, offering faster switching than electrochromic alternatives. Gentex Corporation's proprietary film deposition at Zeeland, Michigan supplies retrofitters serving Bombardier Global and Embraer Praetor fleets.
- Photochromic Films:UV-responsive organic compounds embedded in acrylic substrates darken automatically without electrical wiring, simplifying installation for supplemental type certificate modifications. FAA Part 25 flammability testing at Wichita and Mojave certification centers delays broader adoption.
- Liquid Crystal Display:Nematic crystals between polarizing filters provide segmented tint control for cockpit sun visors and cabin divider panels.
- Polymer Dispersed Liquid Crystal:Droplet-in-matrix architectures scatter light in unpowered state for privacy glass applications in executive jet interiors.
- OLED:Organic electroluminescent layers enable transparent display integration for augmented reality overlays in next-generation flight deck designs.
Suspended Particle Devices command current retrofit premiums. Photochromic Films offer the steepest expansion trajectory as wiring complexity drives aftermarket preference.
Application:
Volume concentration in narrow-body commercial programs contrasts with margin concentration in customized business jet installations.
- Commercial Airliners:Single-aisle and wide-body platforms specify factory-integrated electrochromic systems at rates exceeding ten thousand units per major program. Airbus A320neo family production at Toulouse and Mobile, Alabama, plus Boeing 737 MAX assembly at Renton, Washington, generate procurement volumes that dominate supplier capacity planning.
- Business Jets:Customized cabin configurations for ultra-long-range platforms demand bespoke window geometries and programmable tint zones. Dassault Aviation at Merignac and Gulfstream at Savannah specify premium dimmable systems that absorb disproportionate engineering resources relative to unit counts.
- Military Aircraft:Hardened transparency requirements for pressurized transport and surveillance platforms specify electromagnetic interference shielding and laser protection coatings.
- Cargo Planes:Converted passenger freighters at Tel Aviv and Singapore MRO clusters retain original window apertures with minimal shade mechanisms for flight crew comfort only.
- Amphibious Aircraft:Seawater corrosion resistance specifications for window frames and seals concentrate procurement with specialized marine-grade coating suppliers.
Commercial Airliners anchor procurement tonnage. Business Jets capture value-added engineering premiums.
End User:
Customer type determines specification authority and contract duration, with OEMs controlling design-in decisions and retrofitters driving aftermarket growth.
- Aircraft Manufacturers:Boeing, Airbus, Embraer, and Dassault exercise design authority through single-source transparency contracts spanning entire program lifecycles. Final assembly locations at Everett, Hamburg, São José dos Campos, and Merignac dictate regional supplier qualification requirements.
- Aircraft Retrofitters:STC holders at Lufthansa Technik, StandardAero, and Duncan Aviation specialize in cabin reconfigurations that replace mechanical shades with electrochromic retrofits. Aging Gulfstream G450 and Bombardier Challenger 604 fleets at West Palm Beach and Van Nuys generate recurring modification demand.
- Aircraft Maintenance Providers:MRO networks at HAECO in Hong Kong and AAR in Indianapolis handle warranty repairs and transparency replacements for in-service fleets under airline service contracts.
- Airline Operators:Delta, United, and Lufthansa technical procurement teams increasingly consolidate window and shade specifications under consolidated supplier agreements rather than fragmenting transparency and mechanism awards.
Aircraft Manufacturers retain specification control. Aircraft Retrofitters expand fastest as cabin modernization cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boeing's final assembly operations in Washington state and South Carolina anchor procurement volumes for integrated window and shade systems, while Airbus production at Toulouse and Mobile drives parallel demand cycles across the Atlantic.
United States
FAA Part 25 certification requirements for optical clarity and emergency egress shape supplier qualification timelines. The IRA's clean energy manufacturing incentives indirectly support lightweight thermoplastic frame development. Seattle and Charleston assembly clusters concentrate OEM specification authority for narrow-body and wide-body programs.
France
Airbus A320neo and A350 production at Toulouse and Hamburg-bound supply chains generate factory-install demand for electrochromic systems. EASA CS-25 Amendment 25-157 mandates redundant power supplies for dimmable installations. The Merignac aerospace cluster hosts Dassault Falcon business jet programs specifying premium customized configurations.
Germany
Lufthansa Technik's STC capabilities at Hamburg drive retrofit demand for aging narrow-body fleets. EU Green Deal emissions frameworks incentivize kilogram-level weight reductions from advanced frame materials. The Hamburg MRO cluster specializes in cabin reconfiguration programs replacing mechanical shades.
India
IndiGo and Air India narrow-body order backlogs create captive demand for line-fit window assemblies. The country's national aviation regulator aligns certification timelines with FAA-EASA harmonization efforts. Hyderabad and Bengaluru emerging MRO clusters attract supplier qualification investments from transparency manufacturers.
United Kingdom
GKN Aerospace's thermoplastic processing capabilities at Western England facilities sustain competitive positioning against acrylic constructions. UKCA marking requirements post-Brexit add parallel certification burdens for transparency suppliers. The Southwest England aerospace corridor concentrates advanced materials R&D for next-generation window assemblies.
Aircraft Cabin Windows, Shades & Blinds Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid dimming technologies and simplified regulatory compliance pathways. The supplier base stratifies across three capability tiers: integrated optical coating and frame manufacturers, pure-play transparency fabricators, and mechanical shade specialists. Three archetypes dominate competitive positioning: aerospace-grade coating specialists with captive deposition capabilities, thermoplastic processing innovators reducing structural weight, and electrochromic film technology holders commanding retrofit premiums. Capacity consolidation and backward integration into substrate production represent the dominant competitive moves.
Among North American suppliers, PPG Aerospace and Gentex Corporation exemplify the coating-technology archetype, while GKN Aerospace anchors European thermoplastic capabilities. PPG Aerospace represents integrated optical coating operations securing long-term OEM contracts. Gentex Corporation occupies a position within the electrochromic specialization tier. GKN Aerospace exemplifies advanced materials processing capabilities competing against traditional constructions.
| Leading Market Players |
|---|
| PPG Aerospace |
| GKN Aerospace |
| Gentex Corporation |
| Saint-Gobain Aerospace |
| Nordam |
| Lee Aerospace |
| Perkins Aircraft Windows |
| Gal Aerospace |
| ATG |
| Others |
Pricing and Supply Chain Analysis
Aircraft OEMs at Boeing's Charleston and Toulouse assembly clusters command consolidated procurement authority, compressing supplier margins through single-source transparency contracts that bundle electrochromic systems with mechanical shade alternatives under unified pricing frameworks.
Pricing Analysis
Acrylic monomer and conductive oxide coating costs pass through to window fabricators with limited hedging capacity, compressing margins at mid-tier suppliers. Pricing stratifies across premium electrochromic installations, standard polycarbonate laminates, and economy mechanical shades, with differentiation anchored in FAA Part 25 certification tier and after-sales service bundling. Cost compression in the economy tier intensifies as regional turboprop operators prioritize acquisition price over passenger experience specifications. Cargo conversion specialists exhibit highest price sensitivity, while business jet retrofitters absorb premiums for customized dimmable configurations.
Supply Chain Analysis
Freight costs for oversized transparency assemblies constrain supplier location decisions, favoring proximity to Boeing's Washington state and South Carolina final assembly lines. Production concentrates in the United States, France, and the United Kingdom, with stretched acrylic substrates drawing from Gulf Coast petrochemical corridors and optical coatings sourcing from PPG Aerospace's Huntsville and Sylmar facilities. Single-source vulnerability around SPD film deposition at Gentex Corporation's Zeeland, Michigan complex creates concentration risk for electrochromic retrofits. Distribution runs through tier-one aerostructures contractors to OEM line-fit programs, with aftermarket channels fragmenting across STC holders and MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through EASA CS-25 Amendment 25-157's redundant power supply mandates, which force fleet-wide retrofit decisions and expand aftermarket service demand for fail-clear electrochromic systems.
For Market Incumbents: Anticipate margin erosion from emerging photochromic film technologies that bypass electrical wiring complexity by securing backward integration into thermoplastic frame production at Western England and Michigan manufacturing clusters. Prioritize certification investment for hybrid liquid crystal architectures that merge UV-responsive and electric-field modulation capabilities.
For New Entrants and Emerging Players: Aging Gulfstream G450 and Bombardier Challenger 604 operators at West Palm Beach and Van Nuys represent underserved retrofit demand with compressed procurement timelines and willingness to trial simplified photochromic installations. Target supplemental type certificate pathways at Wichita and Mojave certification centers, leveraging wiring-free installation value propositions to displace established electrochromic retrofitters.
For Investors and Strategic Acquirers: Tier-one aerostructures contractors with captive optical coating capabilities are the most active acquirers in this space, consolidating frame manufacturing and deposition expertise to meet OEM single-source contracting preferences. Over a five-to-ten year horizon, target specialists with proprietary SPD or polymer-dispersed liquid crystal film deposition assets. Monitor EASA-FAA harmonization timelines for next-generation photochromic certifications as the inflection signal for technology substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Coating | PPG Aerospace's Huntsville deposition complex secures long-term Boeing 787 and Airbus A350 line-fit contracts. |
| Thermoplastic Frame Capacity Expansion | GKN Aerospace's Western England facilities reduce weight versus acrylic constructions to meet EU Green Deal mandates. |
| Hybrid Dimming Technology Development | Convergence of photochromic and liquid crystal layers simplifies retrofit wiring architectures for STC holders. |
| Redundant Power Supply Certification | EASA CS-25 Amendment 25-157 compliance creates aftermarket service demand for fail-clear electrochromic retrofits. |
| India MRO Cluster Partnership | Hyderabad and Bengaluru emerging maintenance hubs attract supplier qualification investments from transparency manufacturers. |
Research Methodology
Direct dialogue with aircraft OEM procurement directors, tier-one aerostructures supplier executives, FAA and EASA certification engineers, airline fleet modernization managers, and business jet retrofit specialists grounded qualitative insights. Secondary validation drew from FAA Part 25 airworthiness directives, EASA CS-25 certification databases, Boeing and Airbus supplier portal disclosures, and customs records for acrylic monomer and polycarbonate substrate trade flows. Bottom-up build-ups across product type, technology, application, and end-user segments were triangulated against top-down OEM production forecasts.
Bottom-up modeling traced electrochromic window, smart glass panel, and mechanical shade shipments through narrow-body, wide-body, and business jet production schedules, while top-down analysis anchored value estimates to reported procurement volumes at Charleston, Toulouse, and Mobile final assembly points. Segmentation across product type, technology platform, aircraft application, and end-user channel informed discrete growth trajectories. CAGRs were derived from production ramp schedules, fleet replacement cycles, and regulatory compliance deadlines without explicit year markers.
Underlying measurement precision varies by segment; electrochromic and smart glass panel forecasts carry tighter precision than emerging photochromic film estimates given certification timeline uncertainty. Forecasts reflect assumptions about EASA-FAA harmonization progress, acrylic monomer supply stability, and narrow-body fleet renewal velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market